
 Aragonite Market | 2026-2036
Aragonite Market Size, Share, and Industry Trends Forecast 2026-2036
Aragonite Market Analysis
Single-source reliance on Bahamian marine deposits is restructuring procurement patterns across the aragonite value chain. Omya AG leverages its vertically integrated grinding and classification network to sustain supply security for European pharmaceutical customers. CARMEUSE anchors its position through captive control over calcination and slaking assets that feed synthetic aragonite production. Imerys competes via specialized particle-size engineering for water treatment membrane pre-treatment applications.
Aragonite is a metastable polymorph of calcium carbonate (CaCO₃), crystallizing in the orthorhombic system with a specific gravity of 2.93 and Mohs hardness of 3.5 to 4.0, distinguishing it from the more common calcite polymorph through higher specific gravity and distinct cleavage patterns. Manufacturers precipitate synthetic grades from calcium chloride and sodium carbonate solutions, or harvest natural deposits from oolitic shoals in warm, shallow marine environments, with material serving primarily as a bioavailable calcium source, soil neutralizer, and filtration substrate. Natural aragonite dominates volume flows into aquaculture pH stabilization, where its higher solubility versus calcite accelerates buffering kinetics in recirculating systems. Synthetic aragonite captures premium pricing in pharmaceutical-grade applications, where batch consistency and heavy-metal traceability override raw material cost considerations. Industrial-grade powder for construction mortar additive use sits in a mature, cost-competitive segment with thinner margin pools.
EPA effluent guidelines and FDA food contact substance notifications shape product purity specifications for US-sourced material, while REACH registration dossiers govern import eligibility into European Union member states. EMA quality standards for excipient-grade calcium carbonates extend testing protocols to polymorph identification, forcing suppliers to certify crystalline phase content beyond elemental assays. Stakeholders must monitor how evolving marine protected area designations in the Bahamas and Turks and Caicos constrain natural harvest quotas relative to synthetic capacity expansion timelines.
Market Dynamics
Single-source dependence on Bahamian marine deposits is forcing buyers to restructure supply chains, while synthetic precipitation capacity expansion in Europe and Asia creates parallel sourcing channels that fragment procurement power.
Growth Catalysts
- REACH purity thresholds:ECHA's tightening calcium carbonate specifications for food and pharmaceutical channels is pulling synthetic aragonite demand as manufacturers seek batch-traceable alternatives to natural harvests.
- Aquaculture pH buffering:Shrimp and shellfish hatcheries across Vietnam's Mekong Delta favor aragonite's superior solubility kinetics over calcite for larval survival optimization in recirculating systems.
- Soil neutralization:Agricultural lime programs in Brazil's Cerrado region are incorporating aragonite for faster acid neutralization response versus dolomitic limestone in no-till farming systems.
Market Restraints
- Marine deposit concentration:Over 80 percent of natural aragonite originates from oolitic shoals in the Bahamas and Turks and Caicos, creating geographic supply vulnerability to protected area designations.
- Calcite substitution:Lower-cost calcite polymorphs satisfy industrial-grade construction and water treatment applications where solubility kinetics are not performance-critical.
- Energy input volatility:Synthetic aragonite precipitation requires controlled thermal regimes and reagent-grade calcium chloride, exposing margins to natural gas and chlor-alkali feedstock swings.
Strategic Opportunities
- EMA excipient-grade certification:Polymorph identification requirements in European pharmaceutical standards create premium positioning for suppliers with crystalline-phase analytics capabilities.
- Membrane pre-treatment engineering:Specialized particle-size distributions for reverse osmosis scale inhibition represent an underdeveloped specification tier between commodity powder and pharmaceutical grades.
- Carbon capture integration:Synthetic production facilities co-located with industrial CO₂ emitters can mineralize waste gas into aragonite precipitate, qualifying for EU Green Deal carbon border adjustment offsets.
Industry Challenges
- Polymorph analytics talent:X-ray diffraction and Raman spectroscopy expertise for crystalline-phase certification remains scarce in quality control laboratories serving mid-tier suppliers.
- Heavy-metal traceability documentation:FDA food contact substance notifications and EMA excipient dossiers require multi-element ICP-MS testing protocols that extend batch release timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aragonite Market |
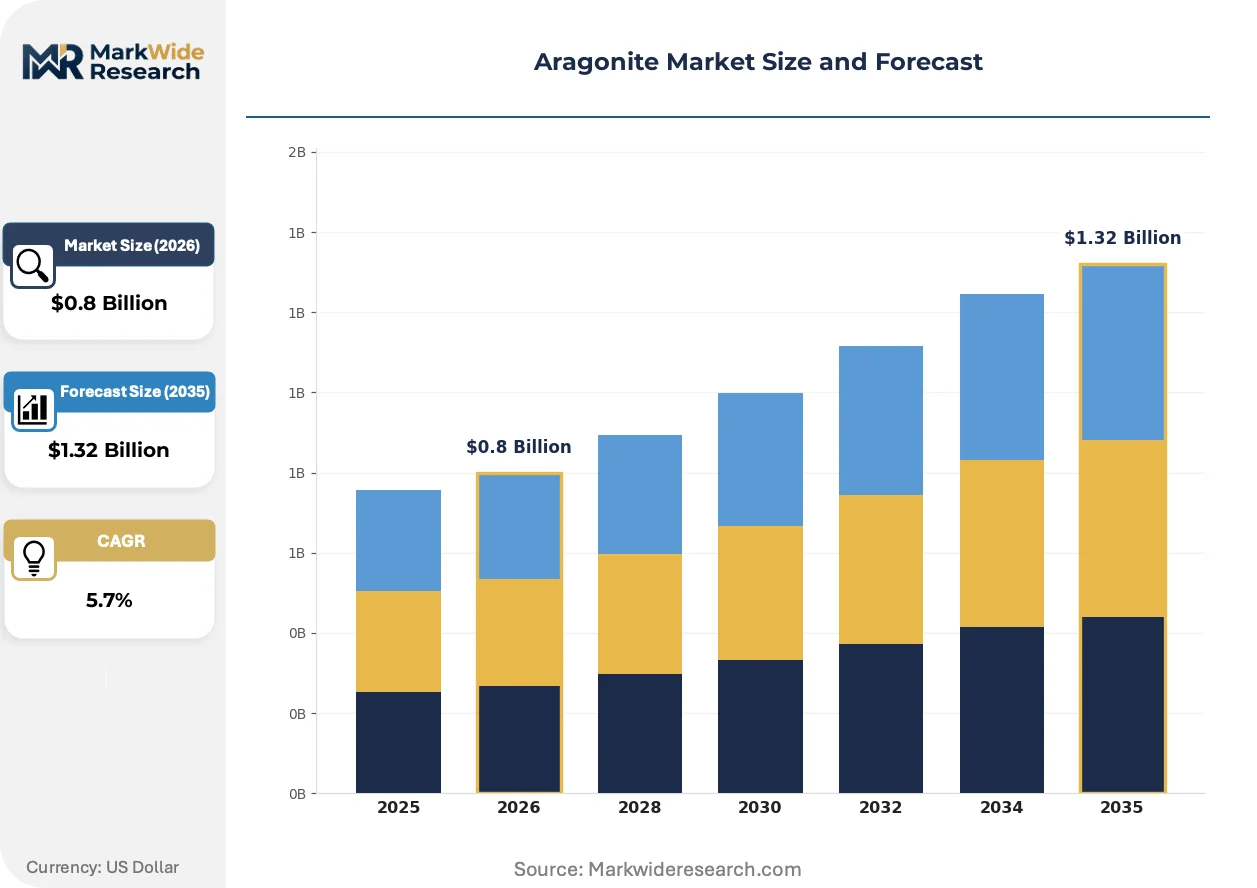
| Market Size in 2026 | $0.8 Billion |
| Market Size in 2035 | $1.32 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Aragonite, Synthetic Aragonite, Aragonite Powder, Aragonite Granules Application: Aquaculture, Construction, Agriculture, Water Treatment Grade: Standard Grade, Food Grade, Industrial Grade, Pharmaceutical Grade End User: Aquaculturists, Builders, Farmers, Water Treatment Facilities |
| Companies Covered | CARMEUSE, Omya AG, Minerals Technologies Inc., Lhoist Group, Mississippi Lime Company, Longcliffe Quarries Ltd., Nordkalk Corporation, Esseco Group, Imerys, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aragonite Market Emerging Trajectories
Aragonite value chains are bifurcating between natural marine harvests serving cost-sensitive volume applications and synthetic precipitates capturing specification-driven premium segments, with processing technology and regulatory compliance as the primary axes of differentiation.
Continuous precipitation reactor designs with real-time particle-size monitoring are overtaking batch crystallization in pharmaceutical-grade synthetic production. European calcium carbonate specialists are retrofitting existing calcite lines with orthorhombic-phase control systems to serve EMA polymorph specifications. This equipment transition is compressing batch-to-batch variability premiums and forcing natural harvesters to certify provenance traceability beyond elemental purity.
REACH registration dossiers for calcium carbonate derivatives now mandate crystalline-phase disclosure alongside standard compositional data. ECHA's 2023 updated guidance on nanoform identification extends to engineered aragonite particles below 100 nanometers, affecting filtration membrane coating applications. Suppliers are responding by segregating synthetic production lines to isolate sub-micron grades from standard precipitate flows.
Hatchery operators in Southeast Asia are consolidating purchase volumes through cooperative procurement platforms that bypass traditional mineral traders. Vietnam's Mekong Delta aquaculture belt now sources directly from Bahamian deposit holders under annual offtake agreements, displacing spot-market transactions. This channel compression is visible most acutely in shrimp larval production facilities with >50 ton annual aragonite consumption.
Aragonite Market Segmentation
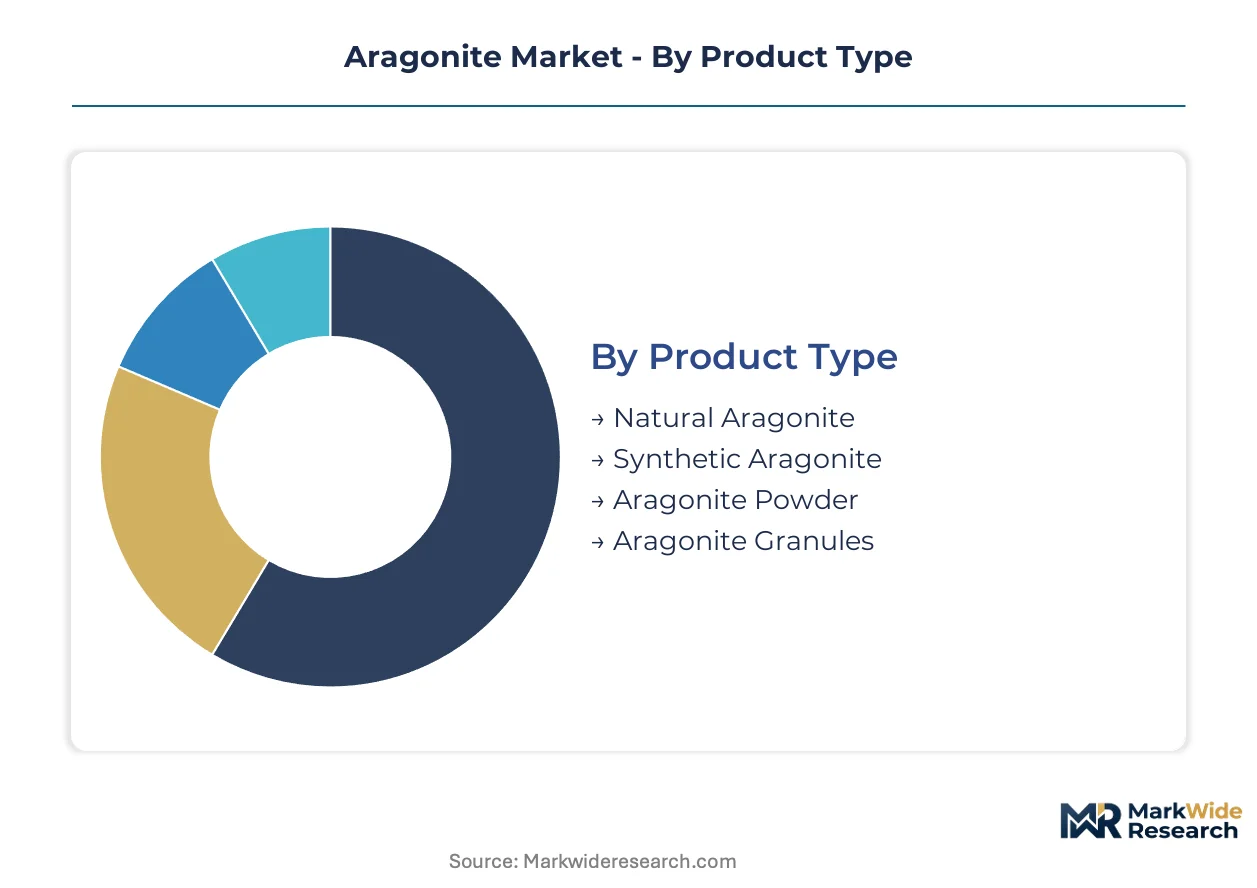
Aragonite procurement patterns diverge sharply between natural harvests from Bahamian marine deposits and synthetic precipitates engineered for regulatory compliance. Buyers segment primarily by solubility kinetics and traceability requirements rather than elemental calcium content alone.
Product Type:
Supply concentration in Bahamian oolitic shoals forces buyers to balance geographic risk against solubility performance.
- Natural Aragonite:Harvested from warm shallow marine environments with orthorhombic crystalline structure and specific gravity of 2.93. Vietnam's Mekong Delta aquaculture belt sources directly from Bahamian deposit holders under annual offtake agreements, bypassing spot markets to secure larval survival-critical buffering kinetics.
- Synthetic Aragonite:Precipitated from calcium chloride and sodium carbonate solutions under controlled thermal regimes. EMA polymorph identification requirements and REACH purity thresholds pull demand toward batch-traceable synthetic grades for European pharmaceutical channels despite higher reagent and energy input costs.
- Aragonite Powder:Milled to sub-100 micron specifications for rapid dissolution in recirculating aquaculture systems.
- Aragonite Granules:Sized for controlled-release soil neutralization in Brazil's Cerrado no-till farming systems.
Today's leader: Natural Aragonite. Tomorrow's challenger: Synthetic Aragonite.
Application:
End-use economics separate specification-driven premiums from commodity volume plays.
- Aquaculture:pH buffering in shrimp and shellfish hatcheries exploits aragonite's superior solubility versus calcite polymorphs. Southeast Asian operators favor the material for larval survival optimization in intensive recirculating systems where buffering speed determines mortality rates.
- Construction:Industrial-grade powder serves as mortar additive where cost competitiveness with calcite and dolomitic limestone constrains margin pools. Performance specifications rarely mandate polymorph identification in this mature segment.
- Agriculture:Soil neutralization programs leverage faster acid neutralization response versus dolomitic limestone in no-till farming systems.
- Water Treatment:Specialized particle-size distributions enable reverse osmosis scale inhibition and membrane pre-treatment applications.
Aquaculture commands the steepest expansion trajectory as intensive hatchery capacity multiplies across Southeast Asia.
Grade:
Regulatory tiering creates pricing stratification across certification levels rather than performance alone.
- Pharmaceutical Grade:EMA quality standards extend testing protocols to polymorph identification, requiring X-ray diffraction and Raman spectroscopy certification of crystalline-phase content beyond elemental assays. Heavy-metal traceability via multi-element ICP-MS protocols extends batch release timelines and captures premium positioning.
- Food Grade:FDA food contact substance notifications and REACH registration dossiers govern import eligibility with tightening purity thresholds for calcium carbonate derivatives entering food channels.
- Industrial Grade:Construction mortar and water treatment applications accept broader compositional tolerances where calcite substitution pressure is strongest.
- Standard Grade:Agricultural lime programs prioritize cost per unit neutralizing capacity over polymorph certification.
Pharmaceutical Grade extracts the widest margin spread. Food Grade is climbing the fastest as REACH compliance tightens.
End User:
Customer consolidation patterns reshape channel economics across the value chain.
- Aquaculturists:Cooperative procurement platforms in Vietnam's Mekong Delta consolidate purchase volumes and displace traditional mineral traders. Hatcheries exceeding 50 ton annual consumption negotiate direct with Bahamian deposit holders.
- Water Treatment Facilities:Engineering specifications for membrane pre-treatment create demand for specialized particle-size distributions between commodity powder and pharmaceutical grades.
- Farmers:Brazil's Cerrado region incorporates aragonite for faster acid neutralization response in no-till systems.
- Builders:Construction mortar additive use competes directly with lower-cost calcite polymorphs where solubility kinetics are not performance-critical.
Aquaculturists anchor current procurement volume. Water Treatment Facilities represent the most underdeveloped specification tier with expansion potential.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting aragonite procurement toward jurisdictions with lower compliance burdens for natural harvests, while synthetic capacity migrates to regions with stranded industrial CO₂ and favorable chlor-alkali feedstock economics.
United States
EPA effluent guidelines and FDA food contact substance notifications shape purity specifications for aquaculture and pharmaceutical applications. Mississippi Lime Company anchors domestic supply from the Ozark Plateau, serving water treatment facilities across the Gulf Coast. Construction mortar additive demand concentrates in Texas and Florida where calcite substitution pressure is strongest.
Germany
REACH registration dossiers and EMA polymorph identification requirements pull demand toward synthetic grades with batch-traceable heavy-metal documentation. Nordkalk Corporation leverages captive calcination assets in the Lahn-Dill mining district to serve pharmaceutical channels. The country's central position enables re-export distribution into Eastern European aquaculture markets.
Vietnam
The Mekong Delta aquaculture belt sources directly from Bahamian deposit holders under annual offtake agreements, bypassing spot markets to secure larval survival-critical buffering kinetics. Cooperative procurement platforms consolidate hatchery purchase volumes exceeding 50 tons annually. Ho Chi Minh City logistics hubs handle transshipment for regional shellfish farming operations.
Brazil
Agricultural lime programs in the Cerrado region incorporate aragonite for faster acid neutralization response in no-till farming systems. ANVISA governs import eligibility for food-grade calcium carbonate derivatives. São Paulo-based distributors coordinate supply from both Caribbean marine deposits and European synthetic precipitate sources.
United Kingdom
Longcliffe Quarries Ltd. occupies a position within the industrial-grade powder segment, serving construction mortar additive applications where calcite competition constrains margin pools. The country's pharmaceutical excipient demand increasingly sources from EMA-certified synthetic suppliers on the European continent. Brexit-related customs documentation extends batch release timelines for cross-channel material.
Aragonite Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue carbon capture integration and pharmaceutical-grade certification as differentiation vectors. The vendor base arranges around three strategic archetypes: vertically integrated mineral processors with captive quarry networks, synthetic precipitation specialists with analytical laboratory capabilities, and regional distributors with hatchery direct relationships. Capacity expansion and polymorph analytics licensing represent the dominant competitive moves as regulatory compliance costs reshape procurement patterns.
Within the vertically integrated tier, CARMEUSE and Omya AG exemplify divergent strategic positioning. CARMEUSE anchors its market presence through captive control over calcination and slaking assets feeding synthetic production lines. Omya AG occupies a position defined by grinding and classification network density serving European pharmaceutical customers with batch-traceable supply security. Imerys represents the specialized engineering archetype, with particle-size distribution capabilities targeting water treatment membrane pre-treatment specifications between commodity and pharmaceutical grades.
| Leading Market Players |
|---|
| CARMEUSE |
| Omya AG |
| Minerals Technologies Inc. |
| Lhoist Group |
| Mississippi Lime Company |
| Longcliffe Quarries Ltd. |
| Nordkalk Corporation |
| Esseco Group |
| Imerys |
| Others |
Supply Flow & Price Mechanics
Continuous precipitation reactor designs with real-time particle-size monitoring are displacing batch crystallization across pharmaceutical-grade synthetic production, simultaneously compressing unit processing costs and fragmenting procurement power away from Bahamian natural harvesters toward European and Asian manufacturing hubs.
Pricing Analysis
Distributor margins in the aragonite trade have compressed as Vietnam's Mekong Delta hatcheries consolidate volumes through cooperative procurement platforms that negotiate direct annual offtake agreements with Bahamian deposit holders. Pricing stratifies across pharmaceutical-grade synthetic precipitates, food-grade natural harvests with REACH documentation, and industrial-grade powder where calcite substitution exerts persistent cost pressure. Price differentiation hinges on polymorph certification via X-ray diffraction and heavy-metal traceability through multi-element ICP-MS protocols. Margins are tightening in the industrial-grade tier as Brazilian agricultural lime programs prioritize cost per unit neutralizing capacity over crystalline-phase verification. Aquaculture operators demonstrate the lowest price sensitivity, accepting premium positioning for larval survival-critical buffering kinetics.
Supply Chain Analysis
Domestic-content requirements in pharmaceutical procurement across European Union member states are redirecting synthetic aragonite sourcing toward regional precipitation capacity with EMA-certified quality systems. Geographic supply concentration centers on Bahamian oolitic shoals for natural grades, Germany and Belgium for synthetic pharmaceutical grades, and Vietnam for aquaculture distribution hubs. Raw material dependencies include reagent-grade calcium chloride from chlor-alkali operations, sodium carbonate feedstock, and natural gas for thermal regime control. Single-source vulnerability to marine protected area designations in the Bahamas and Turks and Caicos threatens natural harvest quotas. Distribution runs through Ho Chi Minh City logistics clusters for Southeast Asian aquaculture, Rotterdam and Antwerp for European pharmaceutical channels, and São Paulo for Brazilian agricultural markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The aragonite market functions as a stable compounder anchored by non-discretionary aquaculture pH buffering demand in Southeast Asian intensive hatchery systems, where larval mortality economics override substitution to lower-cost calcite polymorphs.
For Market Incumbents: Acquire X-ray diffraction and Raman spectroscopy laboratory assets to certify crystalline-phase content for EMA polymorph identification requirements, defending against synthetic precipitation specialists with native analytical capabilities. Secure backward integration into Bahamian marine deposit offtake agreements before cooperative procurement platforms displace traditional mineral traders entirely. Capacity addition in Vietnam's Mekong Delta logistics corridor captures channel compression benefits as hatcheries exceed 50 ton annual consumption thresholds.
For New Entrants and Emerging Players: Begin with carbon capture integration at synthetic precipitation facilities co-located with industrial CO₂ emitters, qualifying for EU Green Deal carbon border adjustment offsets while serving pharmaceutical-grade demand with batch-traceable heavy-metal documentation. Target water treatment membrane pre-treatment specifications between commodity powder and pharmaceutical grades, where specialized particle-size distribution capabilities remain underdeveloped. A direct technical sales model to reverse osmosis engineering firms bypasses entrenched mineral trader relationships.
For Investors and Strategic Acquirers: Valuations sit cheapest among industrial-grade construction mortar additive suppliers facing calcite substitution pressure, while pharmaceutical-grade synthetic specialists with EMA certification command scarcity premiums. The five-to-ten year viability window favors producers with captive control over calcination and slaking assets feeding synthetic lines. Acquisition target archetypes include regional distributors with hatchery direct relationships in Vietnam and analytical laboratory operators with polymorph identification capabilities. The signal to watch is ECHA nanoform guidance extension below 100 nanometers, which would force production line segregation investments and strand non-compliant capacity.
| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Capture Integration | Co-location with industrial CO₂ emitters mineralizes waste gas into aragonite precipitate qualifying for EU Green Deal offsets. |
| Polymorph Analytics Licensing | X-ray diffraction and Raman spectroscopy capabilities enable EMA excipient-grade certification capturing premium positioning. |
| Long-term Supply Agreement | Annual offtake contracts with Bahamian deposit holders secure larval survival-critical buffering kinetics for Mekong Delta hatcheries. |
| Backward Integration | Captive control over calcination and slaking assets feeds synthetic production lines with reagent-grade calcium carbonate feedstock. |
| Geographic Expansion | Vietnam logistics hub capacity captures cooperative procurement platform consolidation in Southeast Asian aquaculture markets. |
Methodological Framework
Multiple input streams — structured interviews with aquaculture hatchery operators and procurement managers, technical discussions with calcium carbonate plant managers and quality control directors, and validation with distribution channel partners — were reconciled against trade data from customs filings and REACH registration dossiers. Secondary sources included SEC 10-K filings from listed chemical producers, ECHA substance registration databases, and aquaculture industry association production statistics. Bottom-up hatchery consumption estimates and top-down calcium carbonate trade flow analysis were triangulated to constrain volume ranges.
Data-stream reconciliation across natural harvest production volumes, synthetic precipitation capacity announcements, and end-use consumption surveys informed the analytical framework across the projection horizon. Segmentation dimensions modeled encompassed product type, application grade, end-user industry, and regional regulatory cluster. CAGRs were derived from trend extrapolation of aquaculture intensification rates, REACH compliance cost trajectories, and carbon capture integration adoption curves. Industry-specific forecast inputs included larval survival optimization economics in recirculating systems and EMA polymorph identification requirement implementation timelines.
Caveats apply where marine protected area designation expansions in the Bahamas and Turks and Caicos, chlor-alkali feedstock cost volatility, or ECHA nanoform guidance revisions could materially shift the outlook. Forecasts reflect assumptions regarding synthetic precipitation capacity expansion timelines and aquaculture hatchery consolidation patterns. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Heat-Resistant Ceramic Tableware Market
Ceramics
Global Zirconia Oxygen Sensors Market
Ceramics
Ceramics Market
Ceramics
North America Ceramic Coatings Market
Ceramics
Active Calcium Silicate Market
Ceramics
Ceramic Ware Market
Ceramics
Ceramic Sanitary Ware Market
Ceramics
Nano Ceramic Coatings Market
Ceramics
Kaolin Market
Ceramics
Traditional Ceramic Market
Ceramics
Cement Castables Market
Ceramics
Glazed Bricks Market
Ceramics
Advanced Ceramics Market
Ceramics
Japan Ceramic Tiles Market
Ceramics
Europe Ceramic Tiles Market
Ceramics
Feldspar and Nepheline Syenite Market