
 Magnesia Carbon Bricks Market | 2026-2036
Magnesia Carbon Bricks Market Size, Share, and Industry Trends Forecast 2026-2036
Magnesia Carbon Bricks Market Analysis
REACH compliance in Europe is recalibrating the cost-of-entry calculus for carbon-bonded refractory producers serving export markets. RHI Magnesita leverages its vertically integrated raw material base to sustain margin stability under tightening chemical disclosure rules. Shinagawa Refractories anchors its position through deep technical specialization in high-purity magnesia sourcing for premium steel ladle applications.
Magnesia carbon bricks are composite refractory materials combining sintered or fused magnesia with carbonaceous binders, typically graphite, at carbon contents ranging from 10% to 20% by weight; they function primarily as erosion-resistant linings in the slag zones of basic oxygen furnaces and steel ladles. Dense bricks dominate volume shipments for steelmaking slag lines where thermal shock resistance and corrosion protection prove critical, while insulating bricks command premium positioning in secondary refining vessels where heat retention directly reduces energy intensity. Refractory bricks tailored for non-ferrous metallurgy represent the fastest-growing application segment as copper and nickel smelters adopt higher operating temperatures.
The EPA enforces particulate emission thresholds that limit graphite processing methods in U.S. manufacturing zones, while China's MEE imposes carbon intensity benchmarks on refractory production clusters in Liaoning and Shandong provinces. India's BIS certification requirements for steel plant consumables are tightening dimensional tolerances and chemical purity standards for imported brick shipments. Stakeholders must monitor how evolving carbon border adjustment mechanisms in multiple jurisdictions reshape the competitiveness of regional supply bases against import-dependent markets.
Market Dynamics
China's MEE carbon intensity benchmarks are forcing refractory manufacturers in Liaoning and Shandong provinces to retool kilns and reformulate binder chemistries, compressing margins for graphite-dependent brick grades while advantaging producers with captive magnesia calcination capacity.
Growth Catalysts
- Electric Arc Furnace Expansion:India's Ministry of Steel production targets are accelerating EAF capacity builds in Gujarat and Odisha, directly lifting consumption of high-erosion magnesia carbon linings for slag zones.
- REACH Chemical Disclosure:ECHA's tightening SVHC candidate list requirements are filtering out small refractory exporters from European steel mill supply chains, consolidating procurement toward compliant producers.
- Graphite-Resin Hybrid Binders:Advanced carbon bonding systems with controlled oxidation profiles are extending brick service life in basic oxygen furnace slag lines, reducing relining frequency for integrated mills.
Market Restraints
- Flake Graphite Supply Concentration:Over 70% of battery-grade and refractory-grade graphite feedstock originates from Heilongjiang province mines, creating single-source vulnerability for carbon-bonded brick manufacturers.
- Fused Magnesia Energy Intensity:Electrofused magnesia production requires 3,000-3,500 kWh per tonne, exposing cost structures to power tariff volatility in China's industrial zones.
- Ceramic Bond Substitution:Alumina-magnesia spinel castables with zero carbon content are capturing secondary ladle positions where ultra-low carbon steel grades are specified.
Strategic Opportunities
- Indonesian Nickel Smelter Buildout:Sulawesi and Halmahera island ferronickel complexes are adopting magnesia carbon linings for high-temperature rotary kiln discharge zones, creating new non-ferrous demand outside traditional steel channels.
- EU Carbon Border Adjustment:CBAM phase-in on imported aluminum and steel is incentivizing European refractory buyers to source from low-carbon production clusters, rewarding kiln electrification investments.
- Predictive Relining Analytics:Integration of thermal imaging sensors with brick wear algorithms is enabling condition-based maintenance contracts that bundle material supply with performance guarantees.
Industry Challenges
- Refractory Engineer Shortage:Steel mill technical services departments face acute scarcity of specialists capable of optimizing magnesia carbon lining designs for dual-slag chemistries.
- BIS Certification Timelines:India's Bureau of Indian Standards approval processes for imported brick batches now extend 16-24 weeks, compressing inventory turns for distributors serving Mumbai-Pune steel corridors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Magnesia Carbon Bricks Market |
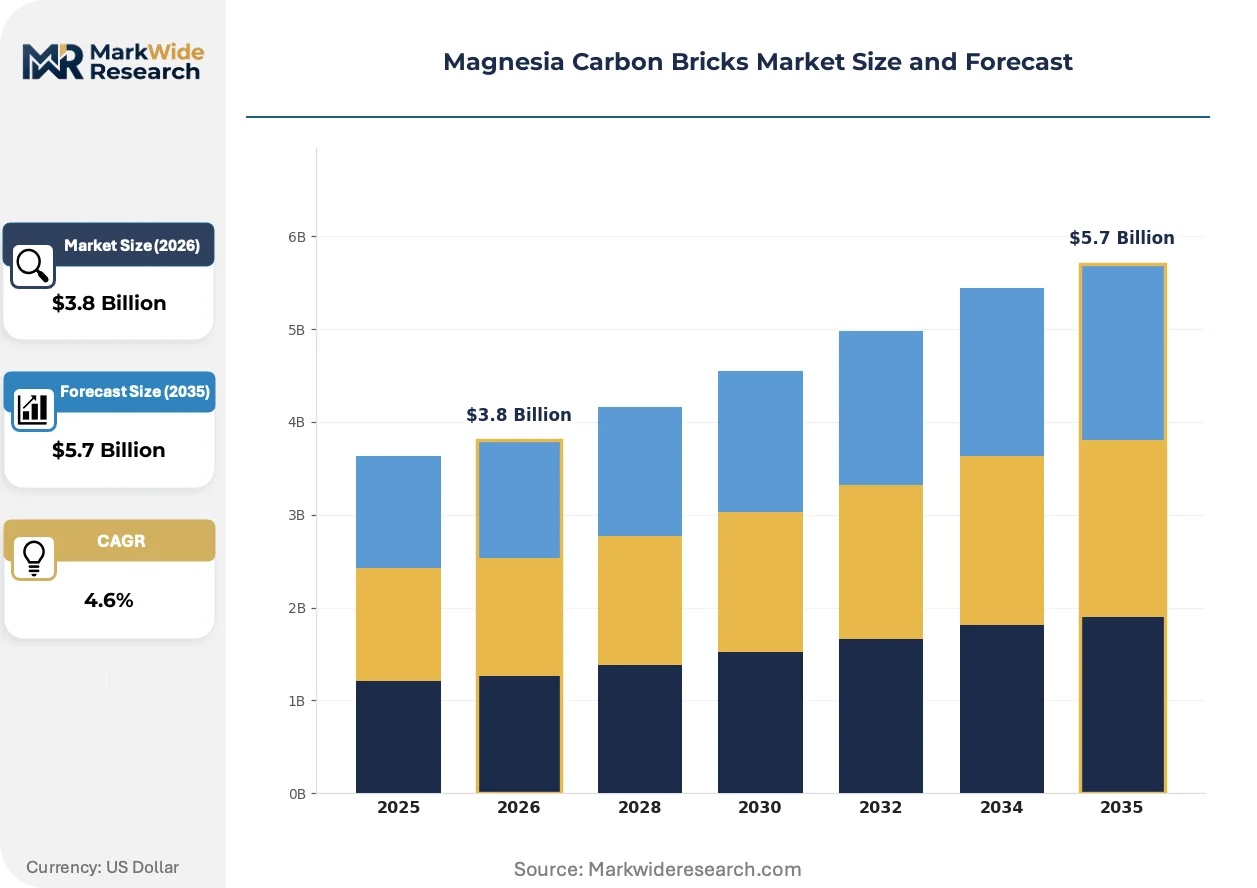
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dense Bricks, Insulating Bricks, Refractory Bricks, Shaped Bricks Application: Steelmaking, Glass Manufacturing, Cement Production, Non-Ferrous Metallurgy End User: Steel Plants, Foundries, Cement Manufacturers, Glass Producers Installation Type: On-site Installation, Pre-cast Structures, Modular Solutions, Custom Fabrication |
| Companies Covered | Shinagawa Refractories, Chosun Refractories, RHI Magnesita, Maithan Ceramics Limited, Trent Refractories, HarbisonWalker International, Puyang Refractories Group, Kerui Refractory, Vesuvius, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Magnesia Carbon Bricks Market Emerging Trajectories
Refractory technology is pivoting toward carbon footprint traceability and service-life extension, with digital monitoring systems and low-carbon binder chemistries converging to redefine value propositions in steel mill procurement.
Antioxidant-infused graphite matrices with metallic silicon and aluminum powder additions are absorbing thermal shock loads in ultra-high-power electric arc furnaces operating above 160 tonnes per heat. European stainless steel producers in Belgium and Finland are piloting these formulations to push campaign lengths beyond 700 heats. The technology is absorbing market share from conventional resin-bonded grades by eliminating premature spalling failures in delta sections.
China's dual carbon policy framework is mandating 30% renewable power integration for refractory production clusters by 2030, with Shandong provincial authorities enforcing coal-to-gas kiln conversions on accelerated timelines. Liaoning-based magnesia processors are responding by relocating calcination capacity to Inner Mongolia wind power zones. Dense brick grades with electrofused grain are most affected, as energy cost premiums now exceed 12% of production value.
Steel mill technical procurement teams are consolidating vendor panels from 8-12 suppliers to 3-4 strategic partners capable of delivering integrated lining packages. German automotive steel specialists in Bavaria and Baden-Württemberg are leading this consolidation, bundling magnesia carbon slag line materials with gunning repair services under multi-year performance contracts. This pattern is most visible in flat-rolled product mills where unplanned downtime costs exceed €50,000 per hour.
Magnesia Carbon Bricks Market Segmentation
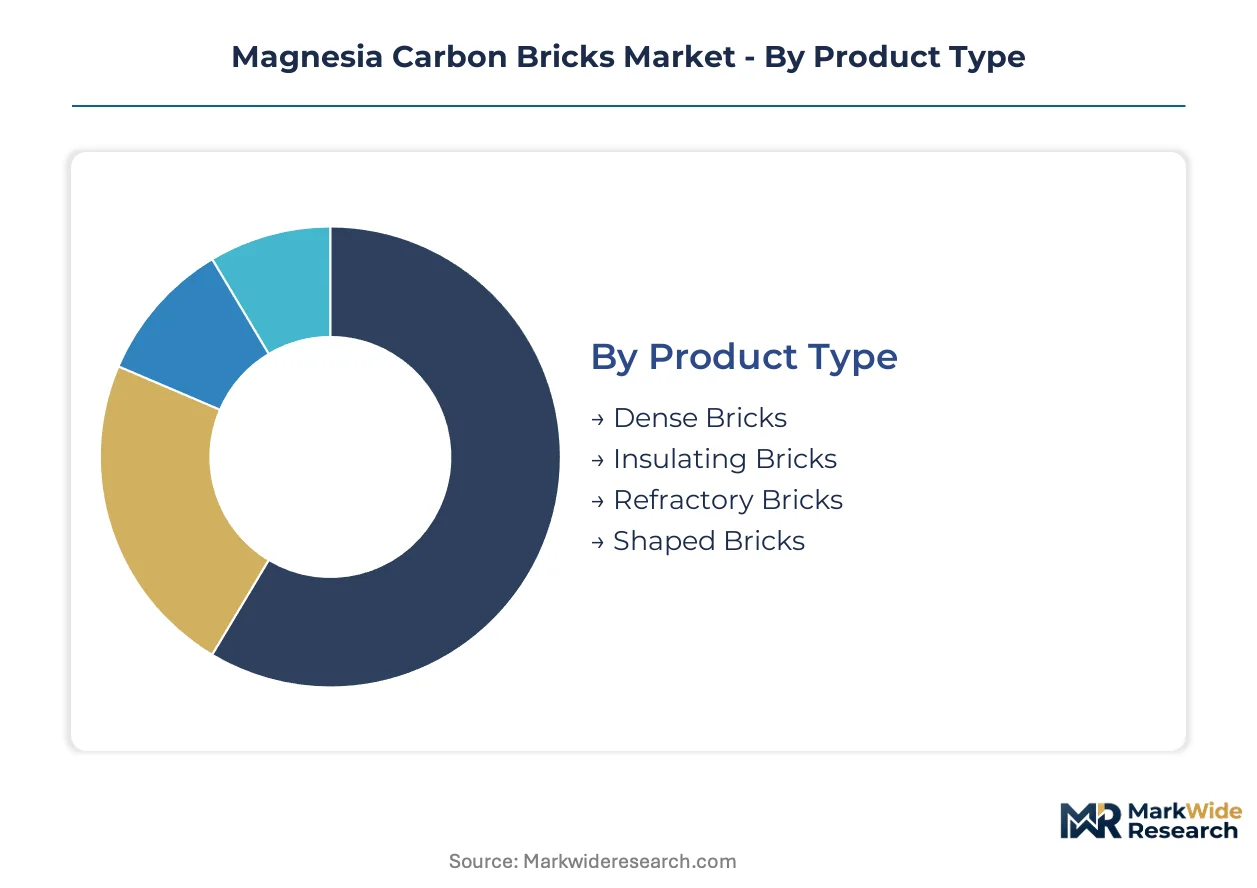
Magnesia carbon bricks serve distinct thermal and chemical protection roles across metallurgical processes. Product specifications diverge sharply between high-erosion steelmaking slag zones and heat-retention applications in secondary refining. Understanding these segment boundaries clarifies where formulation investments concentrate and where substitution pressures mount.
Product Type:
Supply concentration for electrofused magnesia feedstock favors producers with captive calcination capacity in Liaoning and Shandong provinces, tilting competitive advantage toward integrated manufacturers of dense refractory grades.
- Dense Bricks:These materials combine sintered or fused magnesia grains with 10-20% graphite content in resin-bonded matrices engineered for extreme slag line exposure. Steelmaking operations in India's Gujarat and Odisha corridors specify these grades for basic oxygen furnace and electric arc furnace slag zones where thermal shock resistance determines campaign life. China's MEE carbon intensity benchmarks are compressing margins for graphite-dependent formulations while rewarding producers with renewable-powered calcination assets.
- Insulating Bricks:Lower bulk density formulations prioritize heat retention over erosion resistance through controlled porosity and reduced carbon content. Secondary ladle refining vessels in European stainless steel mills deploy these materials to cut energy intensity per heat, particularly in Belgium and Finland where ultra-low carbon steel grades are standard. REACH chemical disclosure requirements are filtering non-compliant suppliers from procurement panels.
- Refractory Bricks:General-purpose magnesia carbon grades balance cost and performance for non-critical furnace zones.
- Shaped Bricks:Custom-contoured preforms reduce on-site cutting and installation labor in complex vessel geometries.
Dense bricks absorb the bulk of installed capacity; insulating bricks are expanding most quickly.
Application:
Cost tier differentiation separates commodity steelmaking consumption from premium non-ferrous applications where specialized slag chemistries command higher formulation prices.
- Steelmaking:Basic oxygen furnaces, electric arc furnaces, and steel ladles consume the majority of magnesia carbon volume worldwide. India's Ministry of Steel production targets are accelerating EAF capacity builds that directly lift demand for high-erosion slag line linings. EPA particulate emission thresholds in U.S. manufacturing zones constrain graphite processing methods for producers serving integrated mill supply chains.
- Non-Ferrous Metallurgy:Copper and nickel smelters operating above 1,500°C are adopting magnesia carbon linings for rotary kiln discharge zones and converter vessels. Indonesian nickel smelter buildouts on Sulawesi and Halmahera islands are creating new demand channels outside traditional steel procurement, with ferronickel complexes specifying these materials for high-temperature process zones.
- Glass Manufacturing:Regenerator checkerwork and furnace crowns employ lower-carbon magnesia grades for alkali vapor resistance.
- Cement Production:Rotary kiln burning zones represent a declining application as alternative alkaline refractories capture share.
Steelmaking absorbs the bulk of installed capacity; non-ferrous metallurgy is climbing the fastest.
End User:
Volume concentration among integrated steel producers creates procurement consolidation toward strategic partners capable of delivering integrated lining packages with performance guarantees.
- Steel Plants:Flat-rolled product mills and long product producers represent the dominant consumption base for magnesia carbon materials. German automotive steel specialists in Bavaria and Baden-Württemberg are consolidating vendor panels from 8-12 suppliers to 3-4 strategic partners under multi-year performance contracts bundling materials with gunning repair services.
- Foundries:Smaller-scale ferrous and non-ferrous casting operations purchase standard grades through distributor channels with less technical service integration.
- Cement Manufacturers:Clinker production facilities represent a shrinking end-use segment as alternative refractory systems displace magnesia carbon in kiln burning zones.
- Glass Producers:Container and flat glass manufacturers specify lower-carbon magnesia formulations for regenerative furnace applications.
Steel plants command the bulk of procurement volume; foundries are gaining share fastest as EAF-based minimill capacity expands.
Installation Type:
Customer type segmentation separates integrated mill technical procurement teams from project-based engineering contractors with diverging specifications for pre-fabrication and on-site customization.
- On-site Installation:Traditional bricklaying by refractory contractor crews remains standard for furnace rebuilds and emergency repairs. India's BIS certification timelines extending 16-24 weeks for imported brick batches are compressing inventory turns for distributors serving Mumbai-Pune steel corridors.
- Pre-cast Structures:Factory-cured shapes with optimized binder development and controlled curing reduce installation time and variability for critical vessel zones. European stainless steel producers are piloting these systems to push campaign lengths beyond 700 heats.
- Modular Solutions:Interchangeable lining segments enable rapid section replacement without full vessel shutdown.
- Custom Fabrication:Application-specific contouring serves non-standard vessel geometries in specialty metallurgical equipment.
On-site installation retains the bulk of deployment volume; pre-cast structures are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Liaoning province's refractory production clusters concentrate capacity under China's dual carbon policy framework, while India's Ministry of Steel targets reshape procurement geography.
China
Shandong and Liaoning provinces host electrofused magnesia calcination capacity serving domestic steel mills. MEE carbon intensity benchmarks force kiln conversions and renewable power integration by 2030. Inner Mongolia wind zones attract relocated calcination assets as energy cost premiums exceed 12% of production value for dense brick grades.
India
Gujarat and Odisha corridors expand electric arc furnace capacity under Ministry of Steel production targets. BIS certification timelines extend 16-24 weeks for imported brick batches. Mumbai-Pune steel distributors face compressed inventory turns as dimensional tolerance standards tighten for slag zone linings.
Germany
Bavaria and Baden-Württemberg automotive steel specialists consolidate vendor panels from 8-12 suppliers to 3-4 strategic partners. REACH chemical disclosure requirements filter non-compliant refractory exporters from procurement chains. Multi-year performance contracts bundle magnesia carbon materials with gunning repair services.
Indonesia
Sulawesi and Halmahera island ferronickel complexes adopt magnesia carbon linings for rotary kiln discharge zones. Nickel smelter buildouts create non-ferrous demand channels outside traditional steel procurement. High-temperature process specifications diverge from standard steelmaking slag chemistries.
United States
EPA particulate emission thresholds constrain graphite processing methods in manufacturing zones serving integrated mill supply chains. Unplanned downtime costs exceed €50,000 per hour at flat-rolled product mills, intensifying technical procurement scrutiny. Condition-based maintenance contracts with thermal imaging integration gain traction.
Magnesia Carbon Bricks Market Vendor Landscape
Chinese producers anchor the scale-driven tier; European and Japanese specialists hold premium positions through technical service integration. The vendor base splits between integrated refractory groups with captive magnesia assets and regional fabricators dependent on spot feedstock markets. Three archetypes dominate: vertically integrated raw material owners, application-specific technical specialists, and project-based installation contractors. Competitive moves concentrate on strategic partnerships bundling material supply with performance guarantees, and selective capacity relocation to low-carbon power zones.
Among Japanese technical specialists, Shinagawa Refractories occupies a position exemplifying deep specialization in high-purity magnesia sourcing. Austrian-registered RHI Magnesita represents the integrated archetype with backward control over raw material bases. Within the European premium tier, Belgium-based Vesuvius anchors refractory system integration capabilities. These three entities illustrate how geographic origin and corporate structure map to distinct competitive positioning in steel mill procurement consolidation.
| Leading Market Players |
|---|
| Shinagawa Refractories |
| Chosun Refractories |
| RHI Magnesita |
| Maithan Ceramics Limited |
| Trent Refractories |
| HarbisonWalker International |
| Puyang Refractories Group |
| Kerui Refractory |
| Vesuvius |
| Others |
Supply Flow & Price Mechanics
China's dual carbon policy framework gates both qualified supply and premium-tier pricing access for magnesia carbon brick producers, as renewable power integration mandates and coal-to-gas kiln conversions compress margins for graphite-dependent grades while rewarding operators with captive calcination assets in Inner Mongolia wind zones.
Pricing Analysis
Short lead-time premiums command substantial markups in India's Mumbai-Pune steel corridors where BIS certification timelines stretch 16-24 weeks, while spot inventory discounts attract price-sensitive foundry operators. Contract-based long-term offtake dominates procurement between integrated mills and strategic partners, with price differentiation hinging on REACH compliance tier and bundled technical service levels. Cost compression in dense brick grades is intensifying because electrofused magnesia production faces power tariff volatility. Steel plants prove least price-sensitive given unplanned downtime costs, whereas cement manufacturers exhibit acute price elasticity as alternative refractories displace magnesia carbon.
Supply Chain Analysis
India's tightening BIS dimensional tolerance standards and domestic-content preferences for steel plant consumables are reshaping sourcing patterns for imported brick shipments. Feedstock concentration centers on China for electrofused magnesia and flake graphite, with Indonesia emerging as nickel smelter demand pulls non-ferrous procurement. Raw material dependencies include Heilongjiang province graphite mines, Liaoning province magnesia calcination clusters, and resin binder chemistries. Single-source vulnerability pervades battery-grade and refractory-grade graphite origination. Distribution runs through technical procurement teams consolidating vendor panels from 8-12 suppliers toward 3-4 strategic partners capable of integrated lining packages.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The magnesia carbon bricks market functions as a cost-of-compliance arena where ECHA's tightening SVHC candidate list under REACH erects barrier-to-entry moats favoring producers with established chemical disclosure infrastructure and European regulatory affairs capabilities.
For Market Incumbents: Hedge against ceramic bond substitution in secondary ladle positions by accelerating antioxidant-infused graphite matrix development for ultra-high-power electric arc furnace applications above 160 tonnes per heat. Secure backward integration into captive magnesia calcination capacity in low-carbon power zones to defend margin stability under China's MEE carbon intensity benchmarks. Prioritize multi-year performance contracts bundling material supply with thermal imaging-enabled condition-based maintenance to lock in procurement consolidation trends.
For New Entrants and Emerging Players: Refractory engineering contractors represent the most accessible channel for bypassing consolidated steel mill vendor panels, particularly in India's Gujarat and Odisha EAF buildouts where technical service scarcity creates partnership openings. Target Indonesian nickel smelter buildouts on Sulawesi and Halmahera islands as the most penetrable geography, where ferronickel complexes adopt magnesia carbon linings outside entrenched steel procurement channels. Pursue go-to-market positioning through predictive relining analytics integration to differentiate from commodity suppliers.
For Investors and Strategic Acquirers: Relocation of calcination capacity to Inner Mongolia wind power zones is the leading indicator that low-carbon production assets will command sustained premium multiples in European procurement. Frame long-term viability around producers with renewable-powered electrofused magnesia operations and REACH-compliant formulation portfolios, as carbon border adjustment mechanisms phase in across steel and aluminum import channels. Watch for consolidation signals in India's distributor tier as BIS certification burdens compress inventory turns and force regional roll-ups.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Magnesia Calcination | Inner Mongolia wind zone relocation secures margin stability under China's MEE carbon benchmarks. |
| REACH Compliance Infrastructure Investment | ECHA SVHC disclosure capabilities filter non-compliant competitors from European steel mill supply chains. |
| Predictive Relining Analytics Development | Thermal imaging sensor integration enables condition-based maintenance contracts with performance guarantees. |
| Indonesian Nickel Smelter Channel Entry | Sulawesi and Halmahera ferronickel complexes create non-ferrous demand outside traditional steel procurement. |
| Multi-Year Performance Contract Structuring | Bundled material and gunning repair services align with German automotive steel vendor consolidation trends. |
Methodological Framework
Document review covered trade customs data, SEC filings from refractory producers, ECHA SVHC candidate list updates, and BIS certification timelines, complemented by interviews with steel mill technical procurement managers, refractory plant operations directors, EPC contractors serving metallurgical projects, and distributor channel heads in India and Europe. Primary fieldwork with maintenance directors at flat-rolled product mills and technical R&D leads at integrated refractory groups informed formulation and installation trend assessments. Secondary validation drew from EPA emission threshold documentation, China's MEE carbon intensity benchmark disclosures, and Ministry of Steel production target announcements. Bottom-up shipment analysis and top-down steel production correlation established volume baselines.
Segmented outputs across product type, application, end user, and installation type dimensions combined with regional production cluster mapping to generate consistent projections across the analysis window. CAGRs derived from steelmaking capacity expansion trajectories, EAF conversion rates in India, and nickel smelter buildout schedules in Indonesia. Forecast inputs incorporated power tariff volatility for electrofused magnesia production, graphite supply concentration risk premiums, and REACH compliance cost pass-through assumptions.
Several conditions sit outside the modeled scope, including abrupt trade policy shifts affecting magnesia or graphite feedstock flows, breakthrough ceramic bond technologies displacing carbon-bonded refractories in critical slag zones, and unanticipated relaxation of China's dual carbon policy enforcement. Forecasts reflect assumptions about sustained regulatory stringency and incremental rather than disruptive technology substitution. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Calcium Silicate Boards Market
Ceramics
Solid-Ion Conductors Market
Ceramics
Brazil Ceramic Tiles Market
Ceramics
Thermal Spray Powder Market
Ceramics
Glass Ceramics Market
Ceramics
Japan Ceramic Tiles Market
Ceramics
Global Pseudo Boehmite Market
Ceramics
Taiwan Ceramic Tiles Market
Ceramics
Asia-Pacific Kaolin Market
Ceramics
Global Thermal Ceramics Market
Ceramics
Ceramic Pigments Market
Ceramics
Tetra-N-Butyl Titanate Market
Ceramics
United States Ceramics Tableware Market
Ceramics
Nanoceramic Powder Market
Ceramics
Zirconium Dioxide Market
Ceramics
Asia-Pacific Ceramic Tiles Market