
 Refractory Material Market | 2026-2036
Refractory Material Market Size, Share, and Industry Trends Forecast 2026-2036
Refractory Material Market Analytics
Multi-source procurement for magnesia feedstock is recalibrating how refractory producers secure raw material stability. RHI Magnesita leverages captive magnesite mines across Austria and Turkey to buffer price volatility. Imerys anchors its alumina supply chain through bauxite refining partnerships in Brazil and Guinea. Krosaki Harima Corporation dominates technical ceramics-grade refractories for Japanese steelmakers, while Vesuvius competes through continuous casting flow control systems.
Refractory materials are non-metallic compounds engineered to withstand temperatures exceeding 1580°C, typically composed of oxides of silicon, aluminum, magnesium, or calcium bonded through ceramic firing or chemical setting. They function as thermal barriers, chemical containment walls, and structural supports in high-temperature process vessels across metallurgical and mineral processing industries. Alumina-based products command premium positioning due to superior slag resistance in basic oxygen furnaces, while monolithics represent the fastest-growing form category as steelmakers shift from brick-lining to gunnable and castable installations for faster turnaround. Fireclay maintains volume leadership in cement kiln preheater zones where thermal shock tolerance outweighs absolute temperature ratings.
EPA emission standards under the Clean Air Act constrain domestic refractory kiln operations, while REACH registration requirements in Europe restrict chromite-based formulations. China's MEE enforces dual carbon goals that pressure magnesia-carbon brick producers toward resin-binder alternatives. India's BIS certification mandates for steel plant refractories create compliance gateways for imported specialty grades. Stakeholders must monitor carbon border adjustment mechanisms and raw material export licensing shifts as these frameworks reshape competitive access across major steel-producing jurisdictions.
Market Dynamics
Blast furnace relining cycle compression is restructuring refractory demand patterns as steelmakers pursue maximum asset utilization. Indian steel producers now execute full vessel rebuilds at 12-to-14-year intervals versus historical 18-to-20-year cycles, intensifying consumption of magnesia-carbon and alumina-silicate grades.
Growth Catalysts
- India's BIS certification mandates:Mandatory quality standards for steel plant refractories create compliance gateways that favor specialty-grade imports over commodity domestic supply.
- Monolithic installation systems:Gunnable and castable refractories enable 40% faster turnaround times than traditional brick-lining, accelerating adoption among capacity-constrained steelmakers.
- China's dual carbon goals:MEE emission enforcement pressures magnesia-carbon producers toward phenolic resin alternatives, stimulating R&D investment in low-carbon binder chemistry.
Market Restraints
- Magnesite supply concentration:Chinese state-controlled mining operations control 70% of global dead-burned magnesia capacity, exposing Western refractory producers to export licensing volatility.
- Chromite substitution pressure:REACH registration requirements in Europe restrict hexavalent chromium formulations, forcing reformulation of direct-bonded magnesia-chromite bricks for AOD vessels.
- Alumina feedstock cost structure:Bauxite refining energy intensity ties refractory input costs to natural gas pricing in Guinean and Brazilian processing corridors.
Strategic Opportunities
- Technical ceramics-grade refractories:Japanese electric arc furnace operators demand ultra-low impurity alumina-zirconia-silica compositions for specialty steel production.
- Carbon border adjustment mechanisms:EU CBAM implementation creates competitive advantage for refractory producers with verified low-carbon supply chains and Scope 3 documentation.
- Continuous casting flow control:Submerged entry nozzle and shroud system upgrades present aftermarket penetration paths independent of new steelmaking capacity.
Industry Challenges
- Ceramic engineering talent scarcity:North American and European universities have reduced high-temperature materials science program enrollment by half since 2000, constraining R&D pipeline depth.
- ISO 9001:2015 recertification timelines:Steelmaker vendor qualification processes extend 18-to-24 months for new refractory suppliers, delaying market entry for innovative formulations.
- Legacy kiln asset integration:Refractory producers face stranded equipment risk as EPA Clean Air Act emission standards mandate pollution control retrofits costing $15-25 million per rotary kiln.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Refractory Material Market |
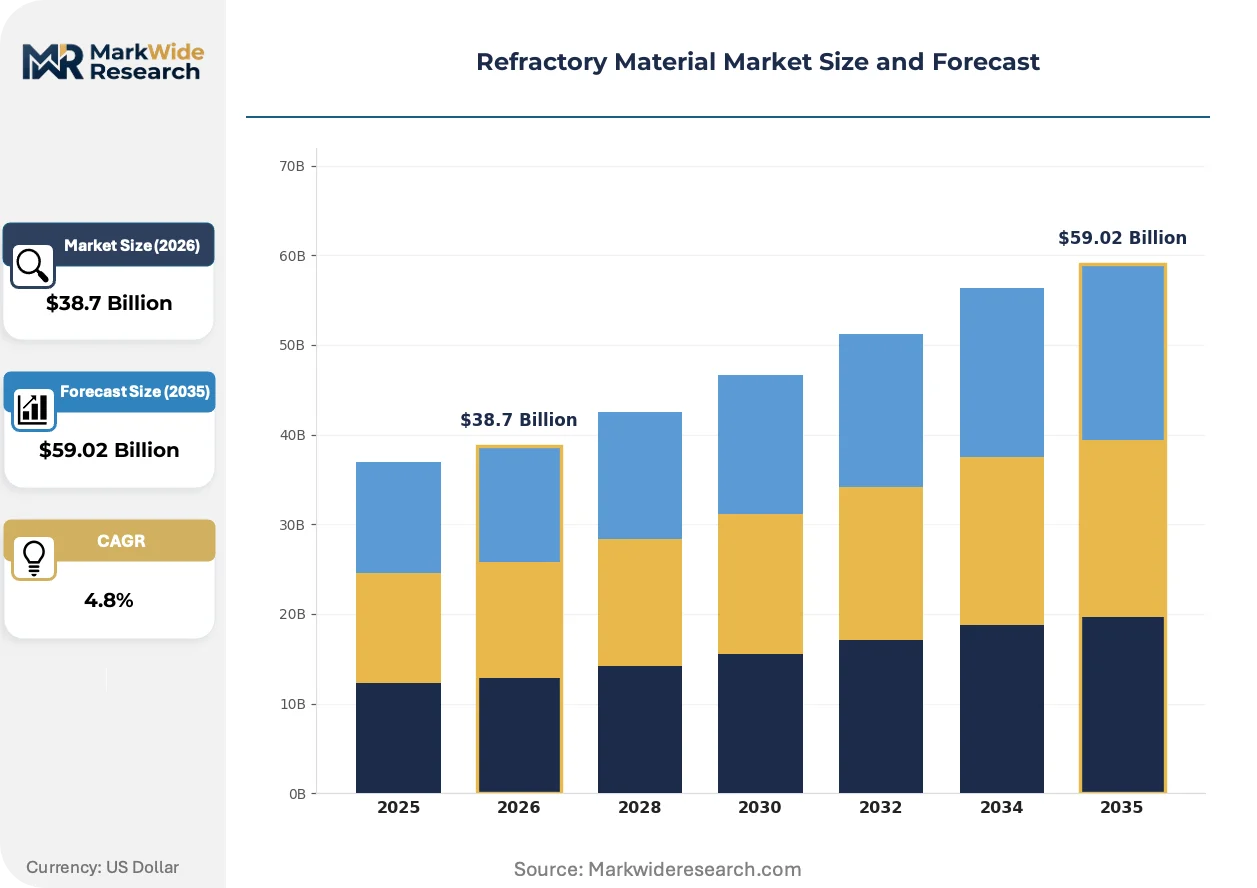
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $59.02 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silica, Alumina, Magnesia, Fireclay Form: Bricks, Castables, Blocks, Monolithics End User: Ceramics, Glass, Iron & Steel, Cement Application: Industrial Furnaces, Kilns, Reheating Furnaces, Boilers |
| Companies Covered | RHI Magnesita, Vesuvius, Saint-Gobain, Krosaki Harima Corporation, Imerys, Shinagawa Refractories Co., Ltd., Morgan Advanced Materials, Calderys, HarbisonWalker International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Refractory Material Market Evolving Landscape
Digitization of refractory performance monitoring is compressing maintenance decision cycles and enabling predictive replacement scheduling. Real-time thermal profiling and slag chemistry analysis now feed directly into procurement systems.
Sensor-embedded monolithic refractories are decentralizing condition monitoring away from centralized laboratory analysis. Steelmakers in South Korea and Germany embed fiber-optic thermocouple arrays directly into gunnable lining installations. These distributed sensing networks enable zone-specific wear tracking that extends campaign life by identifying localized hot spots before structural failure.
REACH authorization restrictions on chromium(VI) compounds are accelerating non-chromite refractory development for stainless steel refining. European AOD vessel operators now specify magnesia-spinel or doloma-based alternatives despite 15-20% thermal conductivity penalties. German steelmakers lead this transition through collaborative R&D with refractory suppliers under ECHA substitution roadmap timelines.
Buyer consolidation among steelmakers is consolidating refractory procurement through tiered supplier rationalization programs. ArcelorMittal and Tata Steel have reduced qualified refractory vendor pools from 40-plus suppliers to 12-15 strategic partners per region. India's eastern steel corridor from Rourkela to Jamshedpur exhibits this concentration most acutely, where integrated mills now demand single-source accountability for full furnace lining systems.
Refractory Material Market Segmentation
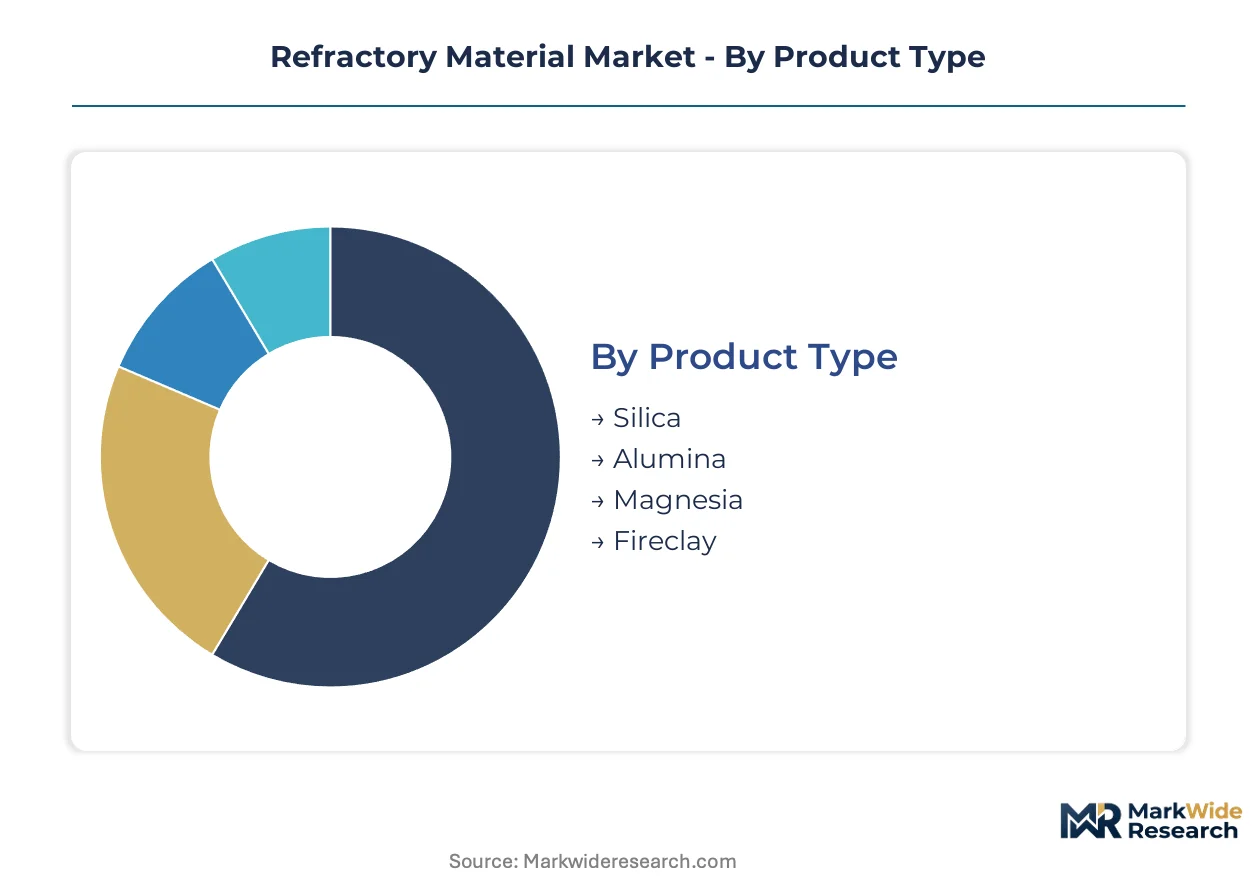
Refractory material segmentation reveals how thermal performance requirements, installation economics, and regulatory pressures fragment demand across distinct technical grades. Steelmakers and cement producers prioritize different property sets, forcing suppliers to maintain parallel product architectures rather than unified platforms.
Product Type:
Volume leadership sits with commodity grades serving cement and lower-temperature metallurgical applications, while premium chemistry commands pricing multiples in advanced steel refining.
- Silica:High-purity silicon dioxide compositions withstand thermal shock in coke oven battery walls and glass tank regenerators. Demand clusters in Pittsburgh's legacy steel corridor and Germany's Ruhr glassmaking basin, where EPA and REACH emission rules constrain alternative binder systems.
- Alumina:Synthetic corundum and bauxite-derived grades achieve 1850°C service temperatures with superior slag resistance in basic oxygen furnace hearths. Indian steelmakers along the Rourkela-Jamshedpur corridor specify 70-90% alumina content for extended campaign life under BIS certification mandates.
- Magnesia:Dead-burned and fused magnesia products anchor basic refractory chemistry for AOD vessels and cement kiln burning zones.
- Fireclay:Alumina-silicate blends balance cost against moderate temperature ratings in boiler settings and kiln preheater zones.
Today's leader: Alumina. Tomorrow's challenger: Magnesia.
Form:
Installation labor costs and turnaround time pressures are displacing traditional shaped products in favor of site-applied systems.
- Bricks:Pre-fired shaped units provide dimensional precision for critical wear zones in blast furnace stacks and glass tank crowns. German and Japanese steelmakers retain brick specifications for taphole surrounds where structural integrity failures carry catastrophic consequences.
- Castables:Hydraulically bonded dry mixes achieve 90% of fired brick strength after controlled curing, enabling complex geometries without mold constraints. South Korean EAF operators specify low-cement castables for delta sections to compress reline schedules.
- Blocks:Large prefabricated shapes reduce joint count in rotary kiln nose rings and ladle well blocks.
- Monolithics:Gunnable, ramming, and plastic compositions adapt to irregular surfaces while eliminating mortar joint vulnerabilities.
Installation speed advantages position monolithics as the steepest expansion trajectory, though bricks defend position in highest-stress zones.
End User:
Metallurgical intensity and thermal process sophistication determine specification grade and replacement frequency across consuming industries.
- Iron & Steel:Integrated mills and minimills consume magnesia-carbon, alumina-silicate, and basic oxygen furnace grades across vessel linings, ladles, and tundish systems. Chinese MIIT emission enforcement and India's BIS mandates reshape formulation requirements for producers in Tangshan and Odisha.
- Cement:Rotary kiln burning zones, preheater towers, and clinker coolers demand fireclay and alumina grades with alkali resistance. European producers under EU ETS carbon pricing prioritize thermal efficiency over absolute refractoriness.
- Glass:Tank furnaces and regenerators require silica and fused cast alumina-zirconia-silica for 1600°C continuous service.
- Ceramics:Kiln furniture and saggars utilize cordierite and mullite compositions for thermal cycling tolerance.
Iron & steel commands volume dominance. Cement offers replacement cycle predictability.
Application:
Process temperature profiles and chemical exposure severity dictate material selection across fixed industrial equipment categories.
- Industrial Furnaces:Heat treatment, forging, and melting furnaces deploy alumina and magnesia grades against oxidation and carburization atmospheres. US EPA Clean Air Act permitting constrains kiln rebuild schedules in Indiana and Ohio manufacturing clusters.
- Kilns:Cement and lime rotary kilns, plus ceramic tunnel kilns, require zone-specific lining strategies from inlet to discharge. Indian cement producers in Rajasthan and Madhya Pradesh drive dead-burned magnesia consumption for 1450°C burning zone stability.
- Reheating Furnaces:Steel slab and bloom reheating operations utilize dense fireclay and high-alumina products against scale buildup and thermal cycling.
- Boilers:Utility and industrial steam generators employ lower-duty fireclay and insulating refractories for combustion chamber containment.
Kilns anchor replacement demand through continuous duty cycles. Industrial furnaces concentrate premium grade consumption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rourkela-Jamshedpur steel corridor in eastern India anchors regional demand concentration for high-performance refractory grades, with blast furnace relining cycles compressing across multiple jurisdictions simultaneously.
India
Steelmakers along the Odisha-Jharkhand belt drive magnesia-carbon consumption as blast furnace campaigns shorten to 12-14 years. BIS certification mandates for steel plant refractories create compliance gateways favoring specialty-grade imports. The Rourkela-Jamshedpur corridor concentrates integrated mill procurement through vendor rationalization programs.
China
Tangshan and Hebei province steel clusters face MIIT emission enforcement pressuring refractory formulation shifts. The dual carbon goals framework from MEE accelerates phenolic resin binder alternatives in magnesia-carbon brick production. Shandong and Liaoning refractory manufacturing zones adapt to stricter kiln emission caps.
United States
Indiana and Ohio manufacturing clusters confront EPA Clean Air Act constraints on rotary kiln rebuild schedules. Steelmakers in the Pittsburgh legacy corridor specify silica grades for coke oven battery maintenance. The Great Lakes industrial belt maintains fireclay demand for boiler and reheating furnace applications.
Germany
Ruhr basin glassmakers and steel producers navigate REACH authorization restrictions on chromium(VI) compounds. ECHA substitution roadmaps drive magnesia-spinel alternatives for AOD vessel specifications. Collaborative R&D between refractory suppliers and ThyssenKrupp operations accelerates non-chromite formulation deployment.
Japan
Tokyo Bay and Chubu steel corridors demand technical ceramics-grade refractories for electric arc furnace specialty steel production. METI industrial standards reinforce ultra-low impurity requirements for alumina-zirconia-silica compositions. Krosaki Harima Corporation anchors domestic supply relationships across Kansai and Kyushu mill networks.
Refractory Material Market Competitive Landscape
Global majors compete with regional champions across raw material security and installation service capabilities. The vendor base organizes into three tiers: integrated miners-producers with captive magnesite reserves, formulation specialists with technical ceramics expertise, and regional fabricators serving single-country steel corridors. Consolidation pressure intensifies as steelmaker procurement rationalization reduces qualified vendor pools from 40-plus suppliers to 12-15 strategic partners per region. Dominant competitive moves include backward integration into bauxite refining corridors and geographic expansion through acquisition of local installation service providers.
Within the integrated miner-producer tier, RHI Magnesita and Imerys exemplify divergent raw material strategies. RHI Magnesita leverages captive magnesite mining operations across Austria and Turkey to buffer price volatility in dead-burned magnesia feedstock. Imerys anchors alumina supply security through bauxite refining partnerships in Brazil and Guinea. Krosaki Harima Corporation occupies a specialist position in technical ceramics-grade formulations for Japanese electric arc furnace operators. These three anchors illustrate how competitive positioning fragments across feedstock control, technical specification depth, and geographic service density rather than converging on unified scale advantages.
| Leading Market Players |
|---|
| RHI Magnesita |
| Vesuvius |
| Saint-Gobain |
| Krosaki Harima Corporation |
| Imerys |
| Shinagawa Refractories Co., Ltd. |
| Morgan Advanced Materials |
| Calderys |
| HarbisonWalker International |
| Others |
Value Network & Pricing Analysis
Dead-burned magnesia spot pricing in Liaoning province cascades through refractory supply chains into three distinct procurement tiers: technical ceramics-grade commands premium positioning against commodity fireclay and standardized alumina-silicate grades. Chinese state-controlled mining operations anchor global feedstock availability, while Indian BIS certification mandates and EU REACH compliance requirements stratify buyer willingness-to-pay across steelmaker segments.
Pricing Analysis
Input-cost pass-through from bauxite refining energy intensity and natural gas pricing in Guinean and Brazilian corridors compresses margins for alumina-based refractory producers. Three-tier pricing structure across premium, standard, and economy levels separates technical ceramics-grade formulations with ultra-low impurity specifications from commodity magnesia-carbon bricks. Pricing pressure stems from Chinese magnesite export licensing volatility and chromite substitution costs under ECHA timelines. Integrated steelmakers in India's eastern corridor exhibit lowest price sensitivity due to vendor rationalization programs, while cement producers prioritize thermal efficiency metrics over absolute refractoriness.
Supply Chain Analysis
India's BIS certification mandates and China's MIIT emission enforcement are reshaping sourcing patterns toward domestic-content-qualified suppliers. Geographic supply concentration centers on China for dead-burned magnesia, Brazil and Guinea for bauxite-derived alumina, and Austria and Turkey for captive magnesite reserves. Raw material dependencies include phenolic resin binders, fused alumina, and zirconia additives. Single-source vulnerability from Chinese state-controlled mining operations exposes Western producers to export licensing disruptions. Distribution runs through steelmaker-procurement rationalization programs that consolidate vendor pools to 12-15 strategic partners per region.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The refractory material market functions as a regulatory compounder where India's BIS certification mandates and China's dual carbon goals from MEE continuously reshape formulation requirements and procurement standards. These frameworks generate sustained demand for compliance-capable suppliers across steel-producing jurisdictions.
For Market Incumbents: Lock in raw material security through backward integration into bauxite refining corridors or captive magnesite mining operations. Secure BIS certification pathways for Indian steel corridor access before vendor rationalization programs close procurement gates. Prioritize low-carbon binder chemistry R&D to defend positioning against phenolic resin substitution pressures from China's MEE enforcement. For New Entrants and Emerging Players: Begin with sensor-embedded monolithic installation services for South Korean and German steelmakers seeking predictive maintenance capabilities. Target continuous casting flow control aftermarket upgrades as the most penetrable segment independent of new steelmaking capacity. Pursue geographic expansion through acquisition of local installation service providers in India's Rourkela-Jamshedpur corridor. For Investors and Strategic Acquirers: Consolidation pressure builds where steelmaker procurement rationalization reduces qualified vendor pools and stranded kiln assets face EPA Clean Air Act retrofit requirements. Long-term viability favors integrated miners-producers with captive magnesite reserves and technical ceramics formulation depth over regional fabricators dependent on single-country steel corridors. Watch for carbon border adjustment mechanism implementation as the signal indicating competitive advantage shift toward verified low-carbon supply chains.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bauxite Refining | Imerys anchors alumina supply security through Brazilian and Guinean partnerships. |
| Low-Carbon Binder Chemistry R&D | China's MEE dual carbon goals pressure magnesia-carbon producers toward phenolic resin alternatives. |
| Sensor-Embedded Monolithic Deployment | South Korean EAF operators embed fiber-optic arrays for zone-specific wear tracking. |
| Continuous Casting Flow Control Expansion | Vesuvius competes through submerged entry nozzle upgrades independent of new capacity. |
| Regional Installation Service Acquisition | Geographic expansion through local provider acquisition secures steel corridor access. |
Research Methodology
Multiple input streams — primary interviews with plant managers and procurement leads at integrated steelmakers, technical R&D directors at refractory formulators, and distribution channel partners — were reconciled against secondary validation from customs and trade data, SEC filings, and industry association reports. Bottom-up modeling of magnesia-carbon and alumina-silicate consumption by steelmaker vessel type triangulated with top-down market sizing across product type, form, and end-use segmentation dimensions.
Data-stream reconciliation anchored volume and value outputs across the projection horizon through analytical framework integration of blast furnace relining cycle compression, BIS certification mandate timelines, and MIIT emission enforcement trajectories. Segmentation modeling captured product type chemistry tiers, installation form preferences, and application-specific thermal performance requirements. CAGRs derived from steel production capacity expansion rates, cement kiln rebuild schedules, and glass tank regenerator replacement patterns.
Several conditions sit outside the modeled scope, including unannounced regulatory shifts in carbon border adjustment mechanisms, raw material export licensing disruptions, and breakthroughs in non-oxide refractory ceramics. Forecasts reflect documented assumptions regarding steelmaker asset utilization targets and EPA Clean Air Act enforcement consistency. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Methyl Silicate Market
Ceramics
Global Alumina Trihydrate Market
Ceramics
Ceramic Sanitary Ware Market
Ceramics
North America Barium Carbonate Market
Ceramics
Co-Fired Ceramic Market
Ceramics
Calcium Oxide Market
Ceramics
Asia-Pacific Ceramic Tiles Market
Ceramics
Lithium Silicate Market
Ceramics
Controlled Pore Metal Oxide Market
Ceramics
Glass Ceramics Market
Ceramics
Feldspar and Nepheline Syenite Market
Ceramics
Ceramics Packaging Market
Ceramics
Ceramic Binders Market
Ceramics
Global Wollastonite Powder Market
Ceramics
United States Ceramics Tableware Market
Ceramics
Global Ceramic Tube Market