
 Global Alumina Market | 2026-2036
Global Alumina Market Size, Share, and Industry Trends Forecast 2026-2036
Global Alumina Market Analysis
The EU Carbon Border Adjustment Mechanism is restructuring cost-of-entry calculus for alumina exporters to European aluminum smelters. Alcoa Corporation leverages its integrated bauxite-alumina-aluminum chain to sustain margin resilience against carbon tariffs. Rusal anchors its competitive position through low-carbon hydro-powered smelting assets in Siberia. Rio Tinto navigates dual exposure by controlling Australian bauxite mines while positioning European refineries for compliance-grade output.
Alumina, or aluminum oxide (Al₂O₃), is a white crystalline powder produced via the Bayer process from bauxite ore, typically refined to purity levels exceeding 99.5% for metallurgical applications and higher grades for specialty uses. Its primary industrial purpose centers on serving as the feedstock for primary aluminum production through electrolytic reduction in Hall-Héroult cells, while non-meturgical grades enable refractory, ceramic, and polishing applications. Smelter grade alumina dominates volume flows as the foundational input for aluminum ingot production, yet specialty alumina commands superior margin pools through tight specification control in electronic substrates and advanced ceramics. Refractory grade alumina competes on thermal stability metrics in steel and cement kiln linings, while calcined alumina extends into polishing compounds and catalyst supports where particle size distribution determines performance.
The EPA enforces emissions thresholds for U.S. refineries under the Clean Air Act, while China's MEE imposes dual carbon goals that constrain coal-powered calcination capacity expansion. REACH in Europe mandates registration and hazard disclosure for imported alumina-based materials, reshaping supplier documentation burdens. Stakeholders must monitor how carbon border mechanisms proliferate beyond Europe and whether low-carbon process certifications become mandatory market access conditions rather than voluntary premiums.
Market Dynamics
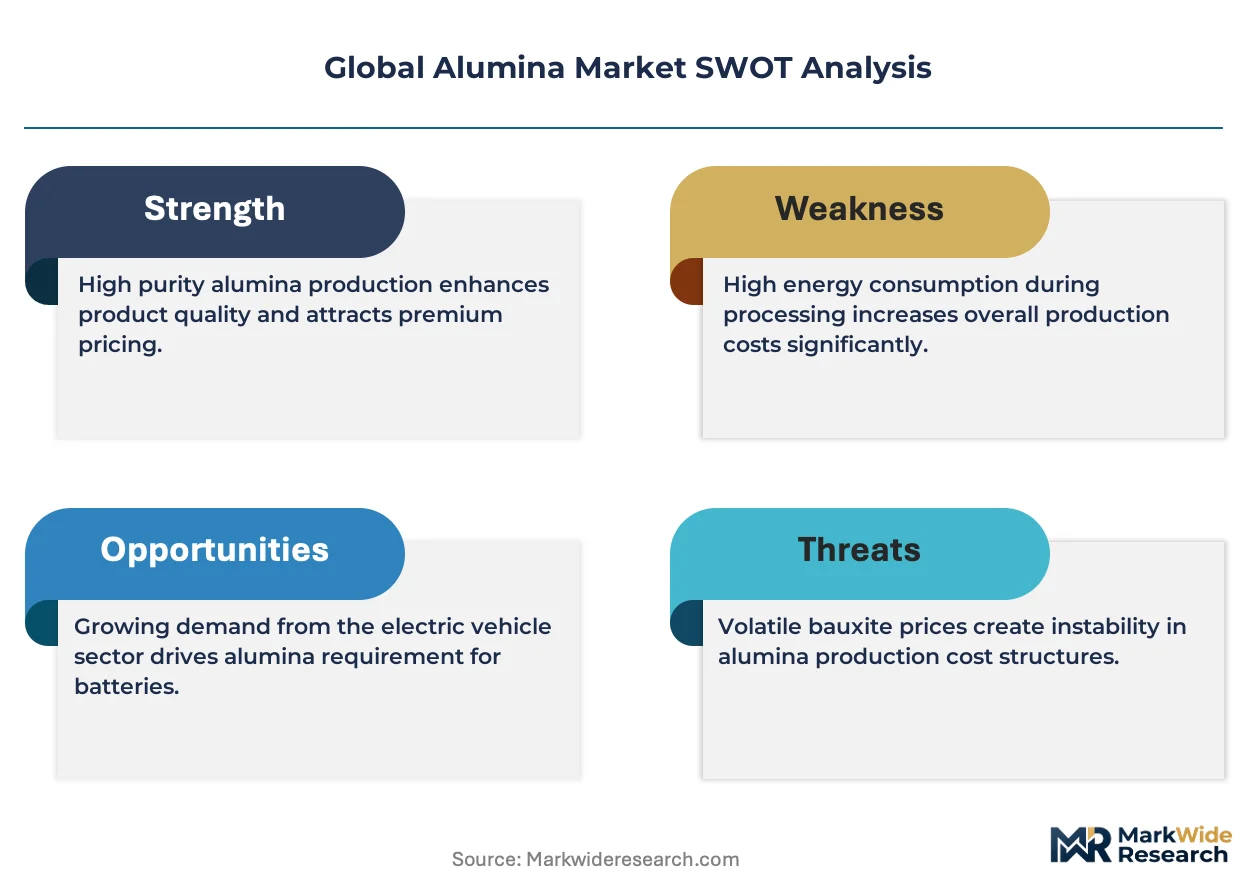
The EU Carbon Border Adjustment Mechanism is forcing a recalibration of refinery economics across the Atlantic-Pacific corridor, as carbon intensity now determines market access rather than mere cost efficiency. This mechanism privileges low-carbon hydro-powered production while penalizing coal-dependent calcination, splitting the competitive map between compliant and non-compliant supply basins.
Growth Catalysts
- China's MEE dual carbon goals:Environmental mandates are accelerating the retirement of outdated coal-fired calcination capacity, tightening global supply and lifting price floors for compliant producers.
- Aluminum smelter expansion:Capacity builds in Saudi Arabia and the UAE are pulling additional metallurgical alumina volumes through long-term offtake structures.
- Specialty ceramic substrates:Advanced packaging demand from semiconductor fabrication in Germany and Japan is creating premium-grade pull for high-purity calcined alumina.
Market Restraints
- Bauxite supply concentration:Australian and Guinean mine ownership concentrates among three major integrated miners, limiting independent refinery feedstock security.
- Natural gas price volatility:European refineries face input cost instability as gas-indexed calcination energy contracts reset quarterly.
- REACH documentation burdens:ECHA registration requirements for alumina-based imports impose fixed compliance costs that disadvantage smaller non-EU exporters.
Strategic Opportunities
- India's PLI scheme for specialty chemicals:Domestic production incentives are opening capacity-build opportunities for electronic-grade alumina serving display and substrate manufacturers.
- Low-carbon certification premiums:Hydro-powered production in Iceland and Norway commands voluntary price premiums from European automotive aluminum buyers.
- Refractory recycling integration:Steel mill spent refractory recovery programs in Japan are creating closed-loop alumina feedstock channels.
Industry Challenges
- Bayer process engineer scarcity:Specialized chemical engineering expertise for refinery optimization is concentrating among retiring workforce cohorts in Australia and Brazil.
- CSRD disclosure timelines:European corporate sustainability reporting requirements are compressing the window for supply chain carbon data collection from bauxite mine to smelter gate.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Alumina Market |
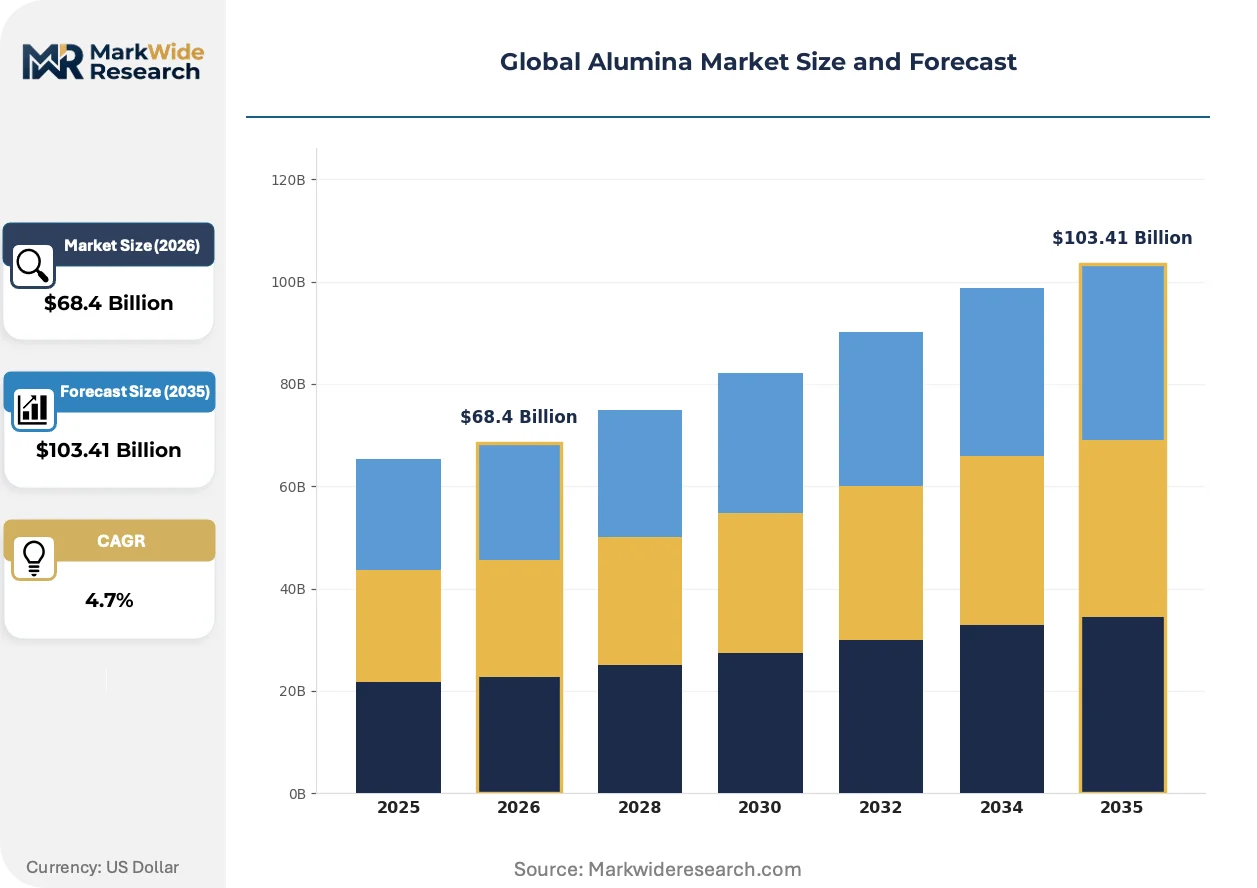
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $103.41 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Calcined Alumina, Smelter Grade Alumina, Refractory Grade Alumina, Specialty Alumina End Use Industry: Aerospace, Automotive Components, Building & Construction, Consumer Goods Form: Powder, Granules, Pellets, Crystals Sales Channel: Direct Sales, Distributors, Online Sales, Retailers |
| Companies Covered | Nabaltec AG, Hydro, Alcoa Corporation, Vedanta Resources, South32, Rio Tinto, Henan Zhongfu Industrial Co., Ltd, Rusal, Aluminium Corporation of China Limited (Chalco), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Alumina Market Emerging Trajectories
Process intensification and digital refinery control systems are compressing the gap between commodity metallurgical output and specialty-grade specifications. This convergence is dissolving traditional segment boundaries while raising the technical threshold for competitive participation.
Membrane filtration technology for Bayer liquor clarification is modularizing refinery upgrade pathways. Smelter-grade producers in Brazil and Indonesia are adopting ceramic membrane systems to bypass conventional thickener investments. This shift is enabling incremental capacity expansions without full greenfield commitments, compressing project timelines from five years to eighteen months.
REACH authorization requirements for aluminum oxide nanoparticles are tightening hazard communication obligations across European supply chains. Downstream ceramic and polishing compound formulators must now document substance volumes and exposure scenarios. Specialty alumina traders serving the Netherlands and Belgium are consolidating supplier bases to reduce registration duplication costs.
Long-term offtake contracting is displacing spot market liquidity for metallurgical grades. Chinese aluminum conglomerates are locking five-year supply agreements with Australian refineries, removing volume from open market circulation. This behavioral shift is most visible in the Pacific basin, where quarterly price negotiations are giving way to annual fixed-volume frameworks with inflation-linked adjustments.
Global Alumina Market Segmentation
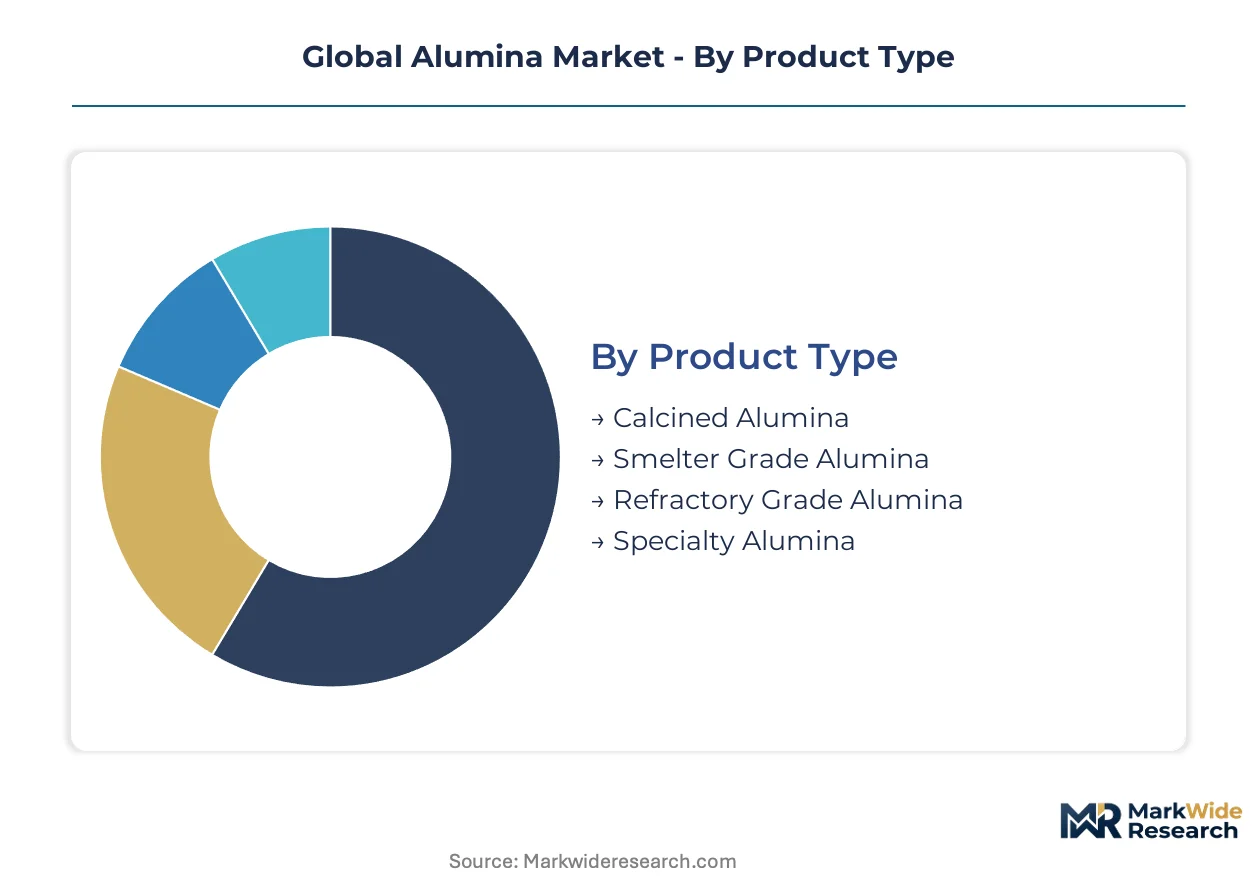
Alumina segmentation reflects divergent purity thresholds, thermal processing requirements, and customer specification rigor. Each category channels distinct margin structures and capital intensity profiles. Procurement patterns vary sharply between commodity metallurgical flows and precision-engineered specialty grades.
Product Type:
Customization intensity spans from standardized smelter feedstock to highly specified ceramic precursor grades, with purity levels and particle morphology determining value capture.
- Smelter Grade Alumina:Metallurgical purity exceeding 99.5% serves as the primary feedstock for Hall-Héroult electrolytic reduction. Chinese and Middle Eastern aluminum smelters are absorbing contracted volumes through long-term offtake structures, removing material from spot market circulation.
- Specialty Alumina:Ultra-high purity grades above 99.9% enable electronic substrate fabrication and advanced ceramic matrices. Demand concentrates in Germany and Japan where semiconductor packaging requirements command specification premiums.
- Calcined Alumina:Thermally processed alpha-alumina for polishing compounds and catalyst supports. Particle size distribution determines performance in precision surface finishing applications.
- Refractory Grade Alumina:Thermal stability-optimized grades for steel and cement kiln linings. Competes on creep resistance and corrosion performance metrics in high-temperature industrial environments.
Most installed capacity flows through Smelter Grade Alumina. Expansion is steepest in Specialty Alumina.
End Use Industry:
Application-driven specification requirements range from aerospace certification rigor to consumer goods cost sensitivity, reshaping supplier qualification protocols.
- Automotive Components:Lightweighting mandates from European and Chinese OEMs are pulling high-purity metallurgical alumina into cast and wrought aluminum alloys. EPA emissions thresholds and EU carbon border mechanisms are restructuring feedstock sourcing for North American and European automotive supply chains.
- Building & Construction:Architectural aluminum systems and cladding applications consume standard-grade alumina-derived primary metal. Saudi Arabian and UAE infrastructure builds are accelerating regional smelter capacity expansion.
- Aerospace:Airframe and engine component specifications demand traceable, low-impurity aluminum with documented thermal history. Certification requirements limit qualified supplier pools.
- Consumer Goods:Packaging, appliances, and electronics housings utilize commodity-grade aluminum with less stringent purity documentation. Price sensitivity dominates procurement decisions.
Volume concentration sits with Building & Construction. Value expansion is climbing the fastest in Automotive Components.
Form:
Physical presentation determines handling economics, dissolution kinetics, and downstream process compatibility across divergent industrial applications.
- Powder:Fine particulate alumina dominates ceramic processing and polishing compound formulation. Flowability and agglomeration control determine handling system design.
- Granules:Intermediate particle size enables controlled dissolution in chemical processing and refractory gunning applications. Dust generation reduction improves workplace safety compliance.
- Pellets:Compacted spherical forms optimize bulk density for transport efficiency and automated feeding systems. Preferred in large-scale smelter operations.
- Crystals:Single-crystal and coarse crystalline structures serve sapphire growth substrates and specialized abrasive applications. Defect-free morphology commands specification premiums.
Powder form carries the largest installed processing capacity. Pellet form is gaining share fastest in automated smelter feed systems.
Sales Channel:
Relationship intensity and technical service requirements vary from direct mill-to-smelter integration to fragmented retail distribution for small-lot specialty grades.
- Direct Sales:Integrated producers and major aluminum conglomerates transact metallurgical volumes through bilateral contracts. Chinese aluminum groups are locking five-year supply agreements with Australian refineries, compressing spot market liquidity.
- Distributors:Independent channel partners aggregate specialty and refractory grades for fragmented end-user bases. REACH documentation burdens are consolidating supplier bases among Netherlands and Belgium-based traders.
- Online Sales:Digital platforms emerging for standardized ceramic and polishing grade procurement. Limited penetration in high-volume metallurgical segments due to contract structure preferences.
- Retailers:Small-package sales for laboratory, artisan, and maintenance applications. Margins compressed by handling cost relative to unit value.
Direct Sales channels handle the majority of metallurgical volume. Distributor networks are expanding most quickly in specialty grade penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Bayer process for alumina refining achieved industrial scale in Germany during the 1890s before spreading to France and the United States. Today's production map reflects this European origin story while shifting toward bauxite-rich equatorial zones and low-carbon energy jurisdictions.
China
Shandong and Henan provinces host the densest concentration of metallurgical refineries serving domestic aluminum smelters. MEE dual carbon goals are forcing coal-fired calcination retirements faster than replacement capacity can come online. Zhengzhou-based engineering firms are exporting refinery technology to Indonesia and Guinea under Belt and Road financing structures.
Australia
Queensland and Western Australia bauxite mines feed refineries at Gladstone and Kwinana with integrated rail-to-port logistics. The country's national environmental regulator enforces strict tailings dam standards that elevate capital requirements for greenfield projects. Perth engineering consultancies dominate global Bayer process optimization contracts.
Brazil
Pará state bauxite deposits support hydro-powered refineries at São Luís with carbon intensity profiles attractive to European buyers. ANVISA registration requirements for specialty alumina imports are tightening documentation burdens for ceramic precursor shipments. Belém port infrastructure expansions are reducing Atlantic shipping costs to Rotterdam.
Germany
Specialty alumina demand concentrates in Saxony and Bavaria for ceramic substrate fabrication serving automotive electronics. REACH authorization requirements for nanoparticle grades are consolidating supplier qualification pools among Netherlands-based distributors. Hamburg traders are arbitraging hydro-powered Icelandic imports against gas-indexed domestic production.
Saudi Arabia
Ras Al-Khair industrial city anchors Gulf smelter expansion with integrated alumina refineries drawing on Guinean bauxite offtake agreements. SFDA chemical import regulations are harmonizing with Gulf Cooperation Council standards for refractory grade materials. Jubail petrochemical clusters are exploring calcined alumina integration for catalyst support manufacturing.
Global Alumina Market Vendor Landscape
The competitive structure tilts toward integrated miners with captive bauxite reserves and energy-positioned refiners with hydroelectric access. Three archetypes dominate: Australian-Brazilian integrated miners controlling mine-to-refinery chains, Chinese state-linked conglomerates securing vertical supply security, and European specialty producers commanding specification premiums. Capacity expansion and low-carbon certification partnerships constitute the primary competitive vectors as carbon border mechanisms proliferate.
Among integrated mining majors, Rio Tinto and Alcoa Corporation occupy positions defined by bauxite reserve control and refinery geographic diversification. Rusal exemplifies the low-carbon hydro-powered archetype through Siberian smelting assets. Chalco represents state-backed vertical integration securing Chinese domestic supply chains against import dependency.
| Leading Market Players |
|---|
| Nabaltec AG |
| Hydro |
| Alcoa Corporation |
| Vedanta Resources |
| South32 |
| Rio Tinto |
| Henan Zhongfu Industrial Co., Ltd |
| Rusal |
| Aluminium Corporation of China Limited (Chalco) |
| Others |
Supply Flow & Price Mechanics
Membrane filtration adoption for Bayer liquor clarification is compressing capital barriers and redrawing competitive boundaries between integrated majors and modular upstarts. This technology shift simultaneously erodes the scale advantages of legacy thickeners while concentrating margin capture among engineering licensors in Perth and Zhengzhou.
Pricing Analysis
Long-term offtake contracting dominates metallurgical grades while specialty alumina trades through distributor networks with certification premiums. Price differentiation hinges on carbon intensity documentation and REACH compliance grade, with hydro-powered Icelandic material commanding voluntary premiums from European automotive buyers. Cost compression in smelter-grade spot markets is intensifying as Chinese conglomerates lock five-year Australian supply agreements. Building and construction end-users exhibit highest price sensitivity; aerospace certification-grade buyers show least.
Supply Chain Analysis
Dual-sourcing mandates from European automotive OEMs are forcing qualification of secondary refineries beyond traditional Australian and Guinean supply basins. Bauxite feedstock draws from Australian, Guinean, and Brazilian mine operations, with calcination energy anchored in gas-indexed European contracts and hydro-powered Brazilian and Icelandic assets. Tariff exposure through the EU Carbon Border Adjustment Mechanism constitutes the dominant structural risk. Distribution runs through direct mill-to-smelter integration for metallurgical volumes and Netherlands-based distributor consolidation for specialty grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on carbon certification premiums displacing commodity pricing and process intensification collapsing grade-conversion costs.
For Market Incumbents: Extend low-carbon certification coverage to capture EU Carbon Border Adjustment Mechanism premiums before compliance becomes mandatory rather than voluntary. Secure captive bauxite reserves in Guinea and Australia against independent refinery feedstock competition. Invest in ceramic membrane systems to compress specialty-grade upgrade timelines from years to months. For New Entrants and Emerging Players: Launch via India's PLI scheme for specialty chemicals to access domestic electronic-grade alumina demand from display and substrate manufacturers. Target refractory recycling integration partnerships with Japanese steel mills as the most penetrable white-space channel. Pursue joint venture structures with Belt and Road engineering exporters to bypass proprietary Bayer process expertise scarcity. For Investors and Strategic Acquirers: Valuations sit cheapest among gas-dependent European refineries facing carbon border exposure and energy cost volatility. Long-term viability favors hydro-powered Brazilian and Icelandic assets with defensible low-carbon positioning. Watch for MEE dual carbon goal enforcement acceleration in Shandong and Henan as the inflection signal for Chinese capacity rationalization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bauxite Reserves | Secures feedstock autonomy against Australian and Guinean ownership concentration. |
| Green Manufacturing Transition | Positions refineries for EU Carbon Border Adjustment Mechanism compliance-grade market access. |
| Long-term Supply Agreement | Locks metallurgical volumes with Saudi and UAE smelter expansions at Ras Al-Khair. |
| Joint Venture | Combines Zhengzhou engineering expertise with Indonesian greenfield development financing. |
| Capacity Expansion | Adds specialty-grade output in Saxony and Bavaria for German automotive electronics demand. |
Methodological Framework
Coverage spans Australia, China, Brazil, Germany, and Saudi Arabia, with primary inputs from each production and demand cluster. Refinery operations directors, aluminum smelter procurement leads, ceramic substrate manufacturing engineers, and REACH compliance specialists contributed structured interviews. Secondary validation drew from customs trade databases, SEC 10-K filings, ECHA registration records, and IEA energy transition reports. Bottom-up capacity modeling and top-down demand segmentation were triangulated against bilateral trade flow data.
Rate-of-change decomposition separated volume growth from price evolution across the projection horizon. Segmentation dimensions modeled include product type tier, end-use industry, physical form, and sales channel structure. CAGRs were derived from iterative convergence between supply-side capacity build schedules and demand-pull indicators from semiconductor packaging and automotive lightweighting. Bayer process energy intensity curves and carbon border mechanism phase-in schedules served as industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under MEE enforcement acceleration or Gulf smelter expansion delays. Deviation in EU Carbon Border Adjustment Mechanism geographic extension beyond European borders would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Zirconia Ceramics Market
Ceramics
Potassium Silicate Market
Ceramics
Egypt Ceramic Tiles Market
Ceramics
Zeolite 4A Market
Ceramics
Solid-Ion Conductors Market
Ceramics
Magnesia Carbon Bricks Market
Ceramics
Tetra-N-Butyl Titanate Market
Ceramics
Ball Clay Market
Ceramics
Germany Ceramic Tiles Market
Ceramics
North America Activated Alumina Market
Ceramics
Taiwan Ceramic Tiles Market
Ceramics
Calcined Kaolin Market
Ceramics
Diatomite Market
Ceramics
Global Pseudo Boehmite Market
Ceramics
Pyrolytic Boron Nitride Market
Ceramics
China Ceramic Market