
 Kaolin Market | 2026-2036
Kaolin Market Size, Share, and Industry Trends Forecast 2026-2036
Kaolin Market Analysis
Modular product bundling is repositioning how ceramics manufacturers procure kaolin, with buyers now separating calcined grades from coating clays rather than accepting blended portfolios. Imerys S.A. leverages its vertical control over Brazilian and Georgian deposits to sustain long-term supply security. BASF SE anchors its competitiveness in European pharmaceutical-grade dispersions through specialized refining capabilities. Sibelco differentiates via its coastal logistics network, which controls bulk shipping lanes to Asian ceramics hubs.
Kaolin is a hydrated aluminum silicate clay mineral with a platy crystal structure and typical particle sizes ranging from 0.2 to 2 micrometers, valued for its brightness, chemical inertness, and low conductivity. Manufacturers refine raw ore through water washing, magnetic separation, and calcination to produce grades serving paper coating, ceramics forming, and polymer reinforcement. Calcined kaolin commands premium positioning in plastics and rubber applications where high opacity and electrical resistance justify elevated processing costs. Paper grade kaolin remains the volume anchor in mature Western markets, while coating clay faces substitution pressure from calcium carbonate in magazine and catalog papers. The pharmaceutical application segment shows accelerated interest as excipient-grade material meets tightened USP and EP monograph standards for oral solid dosage forms.
The EPA regulates mining runoff and air particulate emissions from kaolin extraction sites in Georgia and South Carolina, forcing producers to invest in closed-loop water systems and baghouse filtration. REACH registration requirements in Europe mandate full toxicological dossiers for kaolin imported in quantities above one tonne annually, raising compliance costs for non-EU suppliers. OSHA's permissible exposure limits for respirable crystalline silica directly shape workplace protocols at calcination facilities across the United States. Stakeholders must monitor evolving pharmaceutical excipient certification pathways and assess whether calcination capacity expansion or uncalcined specialty grades offer superior margin protection.
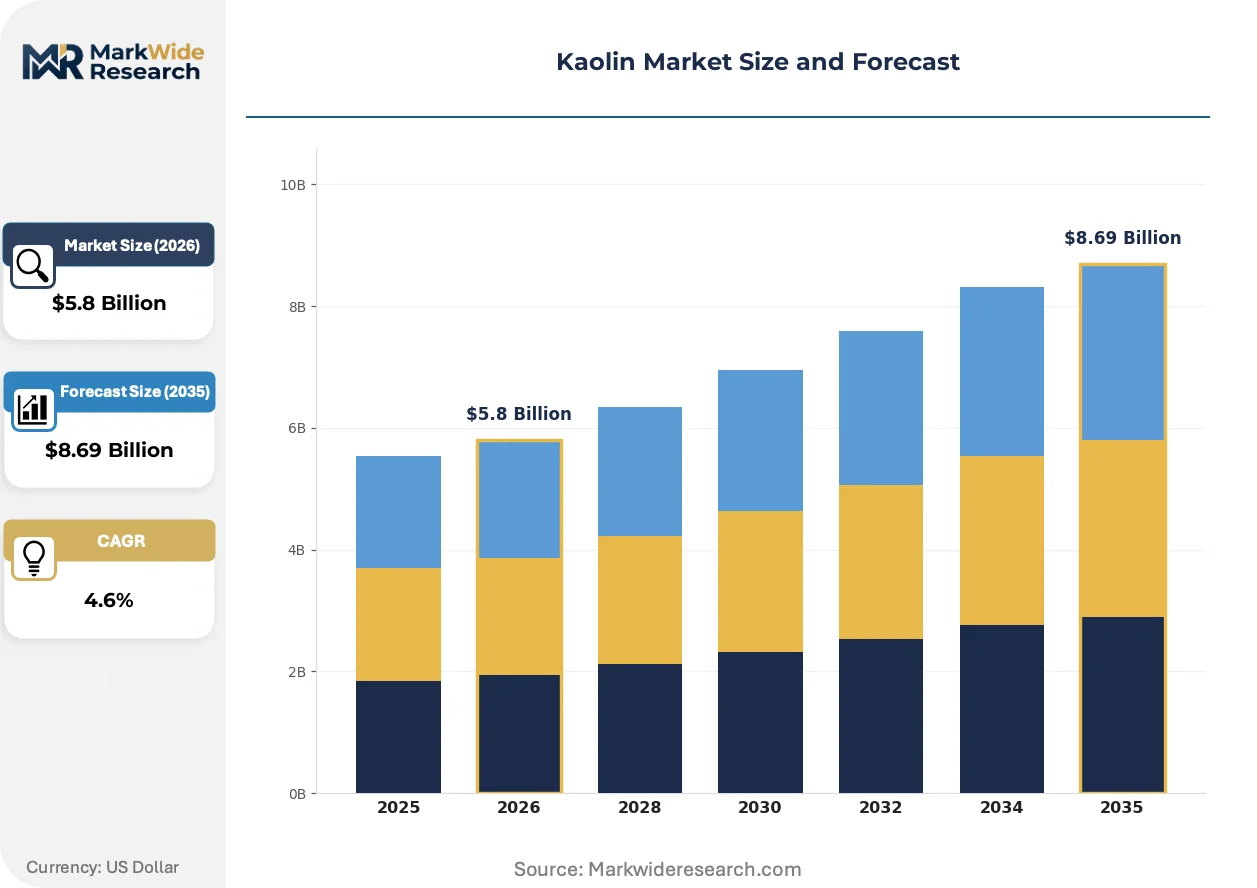
Market Dynamics
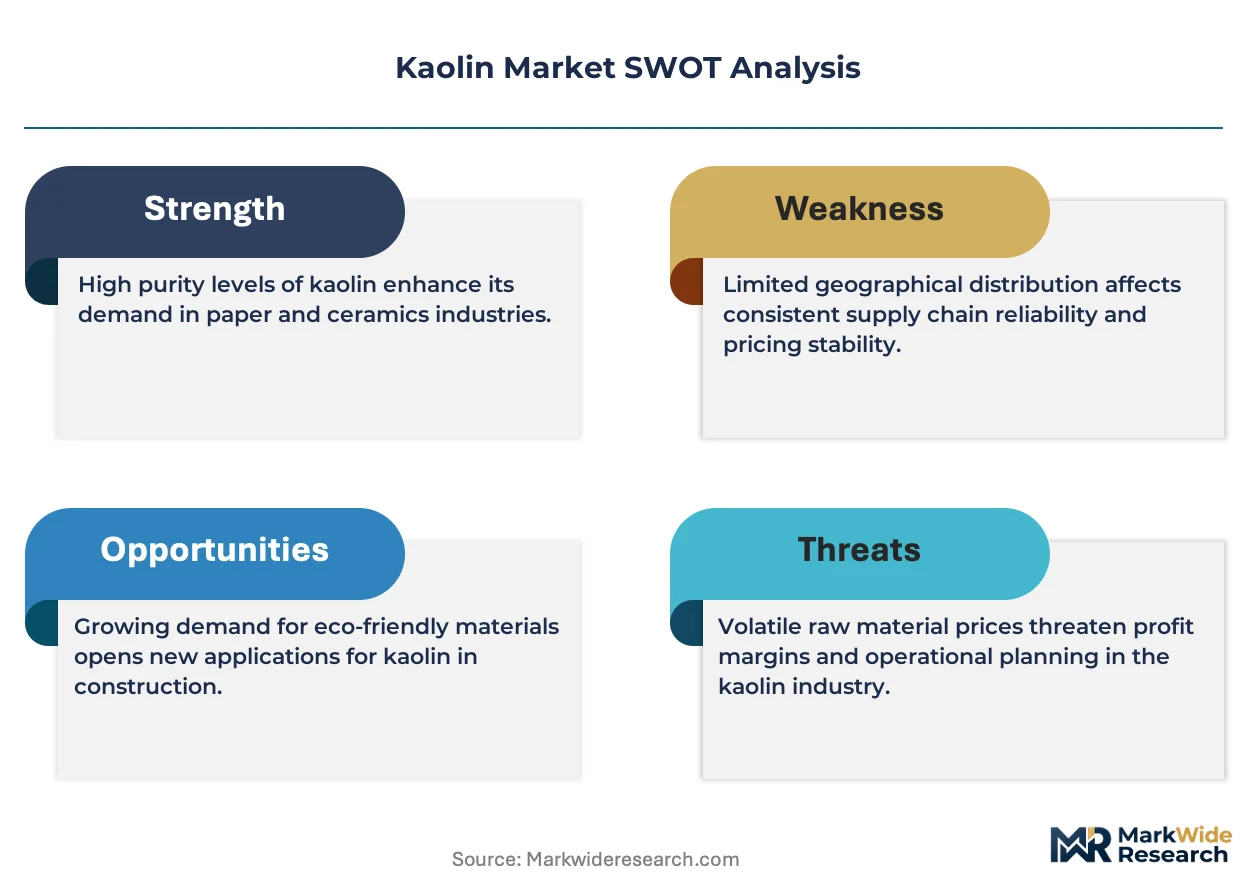
The kaolin market is restructuring around calcination capacity scarcity, as plastics and rubber formulators bid aggressively for high-brightness calcined grades while paper coating clay faces persistent substitution by ground calcium carbonate.
Growth Catalysts
- Sustainable packaging mandates:The EU Green Deal and extended producer responsibility frameworks in Germany and France compel brand owners to eliminate plastic laminates. Paperboard producers in these markets now specify coating clays with enhanced printability and barrier properties.
- Calcined kaolin in EV components:Wire and cable manufacturers serving electric vehicle platforms specify calcined grades for electrical insulation. NEV battery pack housings in China incorporate kaolin-filled polymers for thermal management.
- REACH pharmaceutical-grade compliance:Tightened monograph standards for oral solid dosage forms create certified supply scarcity. European formulators now secure long-term contracts with refiners meeting USP and EP purity thresholds.
Market Restraints
- Energy cost volatility in calcination:Natural gas and electricity account for 35-45% of calcined kaolin production costs. European producers face particular exposure to spot power markets.
- Deposit concentration in Georgia and Minas Gerais:High-purity sedimentary reserves concentrate in two geologic basins. Transportation costs to Asian ceramics hubs create landed price disadvantages versus regional competitors.
- Calcium carbonate substitution in coated paper:Precipitated calcium carbonate offers comparable brightness at lower cost for magazine and catalog grades. North American mills have accelerated this switch since 2020.
Strategic Opportunities
- Underpenetrated Southeast Asian ceramics:Vietnam and Indonesia lack domestic high-grade kaolin reserves. Import substitution strategies by regional tile manufacturers create openings for calcined grade suppliers with coastal logistics.
- Metakaolin in green cement:Partial Portland cement replacement using thermally activated kaolin reduces embodied carbon. European building codes under the EU Green Deal increasingly recognize this pathway.
- Specialty excipient certification:USP and EP compliance for direct compression tableting remains limited to a handful of refiners. First-mover certification in India and Brazil captures emerging generic pharmaceutical production.
Industry Challenges
- Calciner engineering talent scarcity:Rotary kiln operation and process control expertise concentrates with aging workforces in Georgia and Cornwall. Knowledge transfer to new production sites in Brazil and Vietnam lags capacity expansion timelines.
- Multi-year pharmaceutical qualification cycles:Excipient-grade certification requires 18-36 months of stability data and regulatory filing. Capital deployed today generates revenue only after significant delay.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kaolin Market |
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $8.69 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Calcined Kaolin, Paper Grade Kaolin, Rubber Grade Kaolin, Coating Clay Application: Paints, Ceramics, Plastics, Pharmaceuticals End User: Manufacturing, Construction, Automotive, Electronics Form: Powder, Granules, Dispersions, Pellets |
| Companies Covered | Imerys S.A., BASF SE, Sibelco, KaMin LLC, Thiele Kaolin Company, Ashapura Group, EICL Limited, Quarzwerke GmbH, 20 Microns Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kaolin Market Emerging Trajectories
Processing technology advances and regulatory tightening are compressing the viable supplier base while opening premium niches for material science innovators with certified refining capabilities.
Flash calcination systems are electrifying the efficiency frontier for high-brightness kaolin production. These units reduce residence time from hours to seconds, cutting energy intensity by 30-40% versus conventional rotary kilns. Wire and cable compounders in Germany and South Korea now specify flash-calcined grades for EV high-voltage insulation, electrifying margin structures for early adopters with installed capacity.
REACH registration requirements for kaolin imported above one tonne annually now mandate full toxicological dossiers including reproductive toxicity and carcinogenicity studies. The European Chemicals Agency enforcement has disqualified several non-EU suppliers from pharmaceutical and food-contact applications. German and French formulators have responded by consolidating supplier lists to three or four certified refiners with established dossier compliance.
Modular procurement contracts now separate calcined grades from hydrous coating clays rather than accepting blended portfolios. Brazilian ceramics manufacturers pioneered this unbundling, negotiating direct supply agreements with Minas Gerais calciners while sourcing hydrous grades through traders. This pattern has spread to Italian and Spanish tile producers, compressing margins for integrated suppliers unable to demonstrate discrete grade certification.
Kaolin Market Segmentation
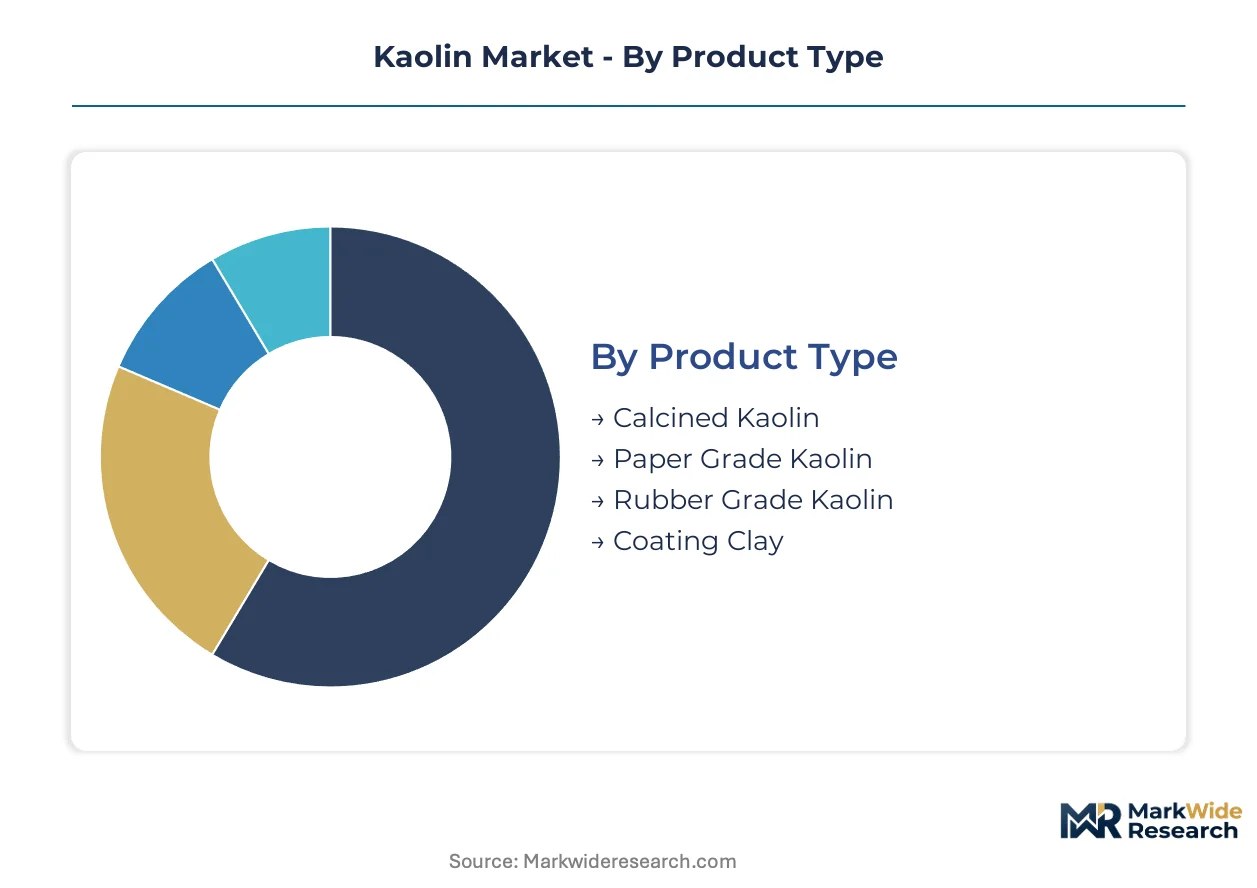
Kaolin buyers now separate procurement by functional grade rather than accepting bundled portfolios. Manufacturers track upgrade cycles across calcination intensity, pharmaceutical certification, and particle size distribution to align supply with evolving formulation requirements.
Product Type:
Calcination intensity separates premium grades from commodity positions, with energy cost exposure determining replacement economics for buyers.
- Calcined Kaolin:Thermally treated at 1,000-1,400°C to remove hydroxyl groups and create metakaolin or fully calcined structures. EV wire and cable manufacturers in Germany and South Korea specify flash-calcined grades for high-voltage insulation where electrical resistance and thermal stability justify 40% energy cost premiums.
- Paper Grade Kaolin:Hydrous, water-washed clay with controlled particle size distribution for coating and filling applications. EU packaging producers under extended producer responsibility frameworks now specify enhanced barrier properties to replace plastic laminates in food-contact board.
- Rubber Grade Kaolin:Surface-treated or untreated hydrous clay for tire and mechanical rubber reinforcement. Automotive sealant formulators favor low-grit, controlled-moisture grades from Georgia sedimentary deposits.
- Coating Clay:Fine-particle hydrous kaolin engineered for gloss, opacity, and printability in publication papers. North American mills accelerate substitution by precipitated calcium carbonate in magazine grades, compressing volume.
Paper grade kaolin sits at the top of the volume ranking, with calcined kaolin climbing the fastest.
Application:
End-use margins concentrate where regulatory certification creates supply scarcity and formulation lock-in.
- Paints:TiO2 extender and functional filler in architectural and industrial coatings. Waterborne systems in Western Europe specify delaminated, high-aspect-ratio grades for scrub resistance and sheen control.
- Ceramics:Body plasticizer and whiteness contributor in tile, sanitaryware, and tableware. Brazilian tile manufacturers in Minas Gerais source calcined grades locally while importing hydrous clays through coastal traders.
- Plastics:Nucleating agent, dimensional stabilizer, and electrical insulator in polyolefins and engineering resins. Chinese NEV battery pack housings incorporate kaolin-filled polymers for thermal management and flame retardancy.
- Pharmaceuticals:USP and EP-certified excipient for direct compression tableting and suspensions. REACH-registered supply concentrates with three to four European refiners with full toxicological dossiers, creating 18-36 month qualification barriers for new entrants.
Ceramics commands the largest application volume, with pharmaceuticals expanding most quickly.
End User:
Customer technical sophistication determines whether buyers specify discrete grades or accept blended supply.
- Manufacturing:Diverse industrial formulators across paper, rubber, and plastics with varying certification requirements. Modular procurement contracts now unbundle calcined from hydrous grades, compressing margins for integrated suppliers lacking discrete certification.
- Construction:Cement and concrete producers exploring metakaolin as supplementary cementitious material. European building codes under the EU Green Deal increasingly recognize thermally activated kaolin for embodied carbon reduction.
- Automotive:Wire, cable, and polymer compounders serving electrification platforms. German automotive suppliers specify flash-calcined grades for high-voltage harness insulation where dielectric performance is critical.
- Electronics:PCB substrate and encapsulant manufacturers requiring ultra-low trace metal content. Asian electronics hubs source high-purity dispersions from coastal logistics networks with bulk shipping control.
Manufacturing absorbs the highest end-user volume, with construction gaining share fastest.
Form:
Physical presentation shapes logistics economics and downstream processing integration.
- Powder:Standard milled product for dry compounding and direct addition. Bagged powder dominates ceramics body preparation where dust control and flowability determine handling costs.
- Granules:Agglomerated form for reduced dust and improved flow in automated feeding systems. Rubber compounders favor granules for masterbatch production to minimize airborne silica exposure under OSHA protocols.
- Dispersions:Aqueous slurries with controlled solids content and viscosity for paper coating and paint integration. Coastal logistics networks control bulk liquid shipping lanes to Asian ceramics hubs, creating differentiation for integrated suppliers.
- Pellets:Highly densified form for specialized polymer compounding and extrusion. Limited adoption concentrates in high-volume automotive polymer operations with dedicated feeding infrastructure.
Powder maintains the highest form volume, with dispersions climbing fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Kaolin extraction originated in Cornwall during the 18th century, where weathered granite deposits supplied England's burgeoning porcelain industry. Modern production has migrated to sedimentary basins in Georgia and Minas Gerais, where thick sequences of Cretaceous-age clay sustain industrial-scale operations.
United States
Georgia's sedimentary deposits between Augusta and Macon supply calcined and hydrous grades to domestic paper and plastics compounders. The EPA enforces mining runoff standards under the Clean Water Act, requiring closed-loop water systems at extraction sites. The Sandersville mining district anchors North American calcination capacity, with rotary kilns and flash calciners serving wire and cable manufacturers.
Brazil
Minas Gerais hosts Latin America's largest kaolin reserves, with calcined output feeding ceramics manufacturers across São Paulo and Rio de Janeiro. ANVISA regulates pharmaceutical-grade imports, creating compliance barriers for non-registered suppliers. The Rio Capim mining corridor concentrates high-brightness sedimentary clay for export to European tile producers.
Germany
Rhineland-Palatinate and Bavaria process imported kaolin into pharmaceutical dispersions and rubber compounds. REACH mandates full toxicological dossiers for kaolin imported above one tonne annually, disqualifying several non-EU suppliers. The Cologne chemical cluster specializes in excipient-grade refining for oral solid dosage forms.
China
Guangxi and Fujian provinces mine residual kaolin for domestic ceramics and paper coating, though high-purity sedimentary grades remain import-dependent. MIIT standards govern clay purity for electronics applications. The Foshan ceramics hub sources calcined material for porcelain tile production serving Southeast Asian export markets.
India
Gujarat and Rajasthan deposits supply domestic ceramics and paint manufacturers, with pharmaceutical-grade material imported from Europe. CDSCO certification requirements for excipient-grade kaolin create 24-36 month qualification cycles. The Morbi ceramics cluster in Gujarat consumes hydrous grades for vitrified tile production.
Kaolin Market Vendor Landscape
The competitive structure tilts toward integrated mineral processors with captive deposit control. Tier-one positions concentrate with French, German, and Belgian firms possessing multi-continental mining assets. Two strategic archetypes dominate: vertically integrated specialists controlling upstream reserves, and coastal logistics operators commanding bulk shipping lanes to Asian manufacturing hubs. Capacity expansion and pharmaceutical-grade certification represent the dominant competitive moves, with flash calcination technology creating differentiation in EV wire and cable supply.
Among European-based integrated processors, Imerys S.A. and BASF SE exemplify the reserve-control archetype, while Sibelco occupies a position as a coastal logistics specialist. Imerys S.A. represents vertical integration into Brazilian and Georgian sedimentary basins. BASF SE anchors pharmaceutical-grade dispersion capabilities in European regulatory compliance. Sibelco exemplifies bulk shipping network control to ceramics manufacturing clusters.
| Leading Market Players |
|---|
| Imerys S.A. |
| BASF SE |
| Sibelco |
| KaMin LLC |
| Thiele Kaolin Company |
| Ashapura Group |
| EICL Limited |
| Quarzwerke GmbH |
| 20 Microns Limited |
| Others |
Supply Flow & Price Mechanics
Backward integration into Brazilian and Georgian sedimentary basins anchors both supply security and pricing power for integrated refiners. Imerys S.A. and BASF SE leverage captive deposit control to buffer calcined grade premiums against energy cost volatility, while coastal logistics operators command distribution economics to Asian ceramics hubs.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates flash-calcined EV wire grades from hydrous coating clays and unprocessed mine-run material. Price differentiation rests on calcination intensity and REACH pharmaceutical certification, with German automotive suppliers paying steep premiums for high-voltage insulation grades. Cost compression in hydrous paper coating clays intensifies because calcium carbonate substitution accelerates in North American magazine papers. Rubber compounders in tire manufacturing show highest price sensitivity, while pharmaceutical formulators exhibit lowest sensitivity due to 18-36 month qualification lock-in.
Supply Chain Analysis
Direct-to-ceramics-manufacturer channels handle high-volume tile producer demand, while trader-mediated flows serve dispersed paint and rubber compounders. Geographic supply concentrates in Georgia, Minas Gerais, and Cornwall, with raw material dependencies on natural gas for calcination, water washing chemicals, and magnetic separation reagents. Single-source vulnerability runs through the Sandersville mining district, where rotary kiln capacity serves North American wire and cable insulation demand. Distribution runs through coastal bulk shipping networks controlled by integrated logistics specialists serving Foshan and Morbi ceramics clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as formulators substitute plastic laminates with barrier-enhanced paperboard specifications under EU Green Deal mandates.
For Market Incumbents: Cement calcination capacity leadership by expanding flash calciner installations ahead of EV wire and cable demand inflection. Secure pharmaceutical-grade certification moats through USP and EP dossier completion before generic production migrates to India and Brazil. Calcium carbonate substitution in coated paper threatens hydrous grade volumes, making calcined specialty pivot essential. For New Entrants and Emerging Players: The 40% energy cost premium gap between flash-calcined and rotary kiln grades creates entry space for electrified kiln innovators. Target Southeast Asian ceramics manufacturers in Vietnam and Indonesia lacking domestic high-purity reserves. Pursue coastal logistics partnerships rather than greenfield mining to bypass deposit concentration barriers. For Investors and Strategic Acquirers: Roll-up economics work for regional calciners with pharmaceutical certification pathways because regulatory barriers extend qualification cycles and consolidate buyer lists to three or four compliant suppliers. Five-to-ten year viability favors integrated processors with captive Brazilian or Georgian deposits. Monitor flash calcination patent filings as inflection signal for process technology leadership shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Flash Calcination Capacity Expansion | Electrified kiln installations capture EV wire insulation premiums from German automotive suppliers. |
| Pharmaceutical Excipient Certification | USP and EP compliance opens oral solid dosage form supply to European generic manufacturers. |
| Backward Integration into Brazilian Deposits | Captive Minas Gerais reserves secure calcined grade supply security for Latin American ceramics. |
| Coastal Logistics Network Control | Bulk shipping lane dominance reduces landed cost disadvantages to Asian tile manufacturing hubs. |
| Metakaolin Green Cement Partnerships | EU Green Deal building code recognition creates supplementary cementitious material demand from European producers. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged calciner operations managers, ceramics procurement leads at Brazilian tile manufacturers, pharmaceutical formulation scientists, and paper mill coating specialists. Secondary validation drew from EPA mining compliance filings, REACH registration databases, SEC 10-K disclosures by integrated processors, and customs trade flow records. Bottom-up grade-by-grade volume builds triangulated against top-down end-use consumption estimates.
Historical reference periods anchored the projection horizon through documented calcination capacity additions, pharmaceutical qualification cycle completions, and ceramics demand shifts. Segmentation modeling tracked calcination intensity tiers, application-grade certification levels, regional production hub economics, and buyer procurement sophistication. CAGRs derived from trend extrapolation of grade-specific volume trajectories, stress-tested against energy cost scenarios and regulatory compliance timelines. Forecast inputs incorporated EV platform wire and cable content assumptions, metakaolin cement substitution rates, and calcium carbonate coating clay displacement patterns.
Caveats apply where energy price volatility, REACH enforcement stringency, or pharmaceutical certification delays could materially shift the outlook. Forecasts reflect assumptions about calciner engineering talent availability and flash technology adoption curves. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Dielectric Ceramics Market
Ceramics
Global Industrial Clay Market
Ceramics
Europe Ceramic Tiles Market
Ceramics
Aragonite Market
Ceramics
Methyl Silicate Market
Ceramics
Germany Ceramic Tiles Market
Ceramics
United States Ceramic Tiles Market
Ceramics
Liquid Sodium Silicate Market
Ceramics
Global Metal and Ceramic Injection Molding Market
Ceramics
Europe Ceramic Coatings Market
Ceramics
UAE Ceramic Tiles Market
Ceramics
Calcite Market
Ceramics
Asia-Pacific Kaolin Market
Ceramics
Europe Aluminum Oxide Market
Ceramics
Cement Castables Market
Ceramics
Ceramic Armor Materials Market