
 HV Glass Insulator Market | 2026-2036
HV Glass Insulator Market Size, Share, and Industry Trends Forecast 2026-2036
HV Glass Insulator Market Foresight
Direct procurement channels between insulator manufacturers and national transmission utilities is reshaping traditional distribution economics in the HV glass insulator sector. Seves Group leverages its European manufacturing footprint to sustain long-term supply agreements with continental grid operators. NGK Insulators anchors its position through advanced toughened glass formulations and dominates high-voltage suspension product lines across Asian utility tenders.
HV glass insulators are toughened silicate-based dielectric components manufactured through thermal tempering, designed to mechanically support and electrically isolate energized conductors in overhead transmission and distribution networks. The tempering process creates compressive surface stresses that yield fragmentation patterns upon failure, enabling visual inspection and reducing catastrophic line-drop risks. Suspension insulators occupy the largest revenue share due to universal deployment on high-voltage transmission towers, while renewable energy applications represent the fastest-expanding end-use segment driven by offshore wind and solar farm interconnection projects. Extra high voltage and ultra high voltage ratings command premium positioning as grid operators upgrade corridors for long-distance power transfer.
IEC standards, India's CEA technical regulations, and Brazil's ANEEL grid reliability mandates collectively enforce mechanical load cycling and pollution withstand criteria that determine product qualification for public tenders. These frameworks compress market access for uncertified suppliers and elevate R&D thresholds for glass composition and coating technologies. Stakeholders must monitor evolving national grid codes and pollution severity mapping to align product portfolios with region-specific performance tiers.
Market Dynamics
Direct procurement channels between insulator manufacturers and national transmission utilities are compressing distributor margins and reshaping contract structures across the HV glass insulator sector. Long-term supply agreements now prioritize technical compliance over price competition.
Growth Catalysts
- CEA Technical Regulations:India's Central Electricity Authority mandates enhanced mechanical load and pollution withstand standards for transmission infrastructure, creating qualification barriers that favor established toughened glass suppliers.
- Offshore Wind Interconnection:European and Asian offshore wind farm developers require specialized suspension insulators rated for marine pollution environments, opening premium product tiers.
- Rural Electrification Programs:State-owned utilities in Brazil and India are executing massive grid extension projects that specify glass insulators for visual inspection advantages in remote maintenance contexts.
Market Restraints
- Soda Ash and Silica Volatility:Raw material cost swings for glass batch constituents compress margin predictability for manufacturers without backward integration into mineral processing.
- Chinese Supply Concentration:Over half of global toughened glass shell production concentrates in Shandong and Jiangsu provinces, creating geopolitical and logistics risk exposure for procurement officers.
- Composite Polymer Substitution:Silicone rubber insulators are displacing glass in medium-voltage distribution segments where weight reduction and vandalism resistance outweigh visual inspection benefits.
Strategic Opportunities
- Sub-Saharan Grid Buildout:Power transmission investments in Nigeria, Kenya, and Ethiopia remain underpenetrated by certified glass insulator suppliers, offering first-mover positioning for IEC 60383-compliant manufacturers.
- HVDC Converter Station Applications:Ultra high voltage direct current corridors require specialized insulator assemblies combining glass shells with composite hardware, converging material technologies.
- Brazil ANEEL Reliability Mandates:Grid reliability incentives reward utilities for reduced outage frequency, favoring glass insulators with predictable failure modes over alternatives with latent defect risks.
Industry Challenges
- Thermal Tempering Process Expertise:Qualified engineers capable of optimizing compressive stress profiles in glass shells remain scarce, constraining capacity expansion for new market entrants.
- IEC 60383 Certification Timelines:Mechanical load cycling and pollution flashover testing protocols require 18-24 month qualification periods, delaying revenue recognition for product line extensions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | HV Glass Insulator Market |
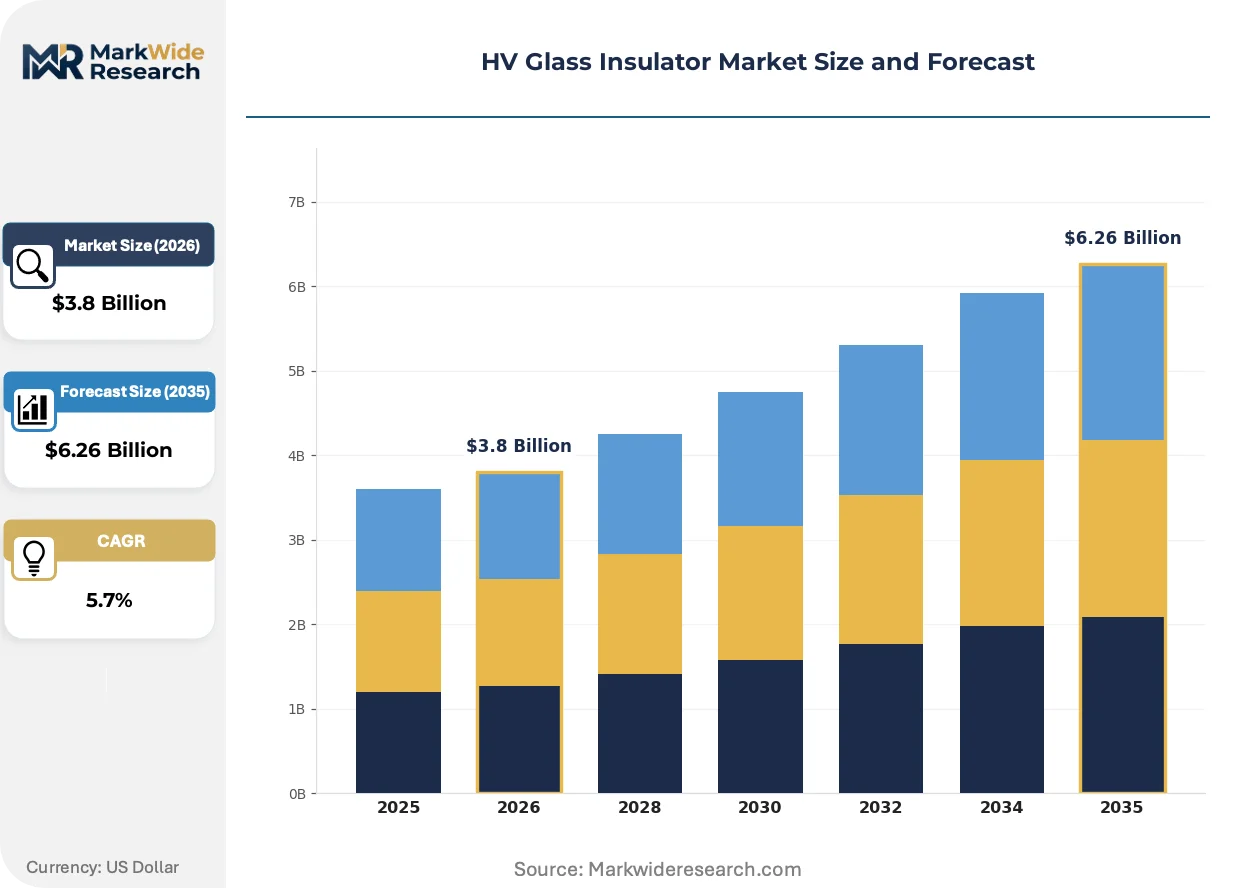
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Suspension Insulators, Shackle Insulators, Line Post Insulators, Cap and Pin Insulators End User: Utility Companies, OEMs, Industrial Users, Telecommunication Voltage Rating: High Voltage, Extra High Voltage, Ultra High Voltage, Medium Voltage Application: Power Transmission, Distribution Systems, Renewable Energy, Substations |
| Companies Covered | Seves Group, NGK Insulators, MacLean Power Systems, LAPP Insulators, INAEL Electrical Systems, Aditya Birla Insulators, PPC Insulators, Victor Insulators, Sediver, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
HV Glass Insulator Market Shifts & Advancements
Digital inspection technologies and toughened glass formulation advances are compressing maintenance cycles and enabling predictive asset management in transmission networks. Material science convergence with composite hardware is creating hybrid product architectures.
Embedded fiber optic sensors within glass insulator shells are digitizing condition monitoring capabilities for transmission operators. European utilities including RTE and TenneT are piloting these smart insulators on 400 kV corridors. Real-time mechanical load and temperature data streams are digitizing traditional visual inspection regimes and enabling predictive replacement scheduling.
EU F-Gas Regulation phase-down mandates are accelerating scrutiny of alternative insulation technologies in substation environments adjacent to overhead lines. Glass insulator manufacturers face indirect pressure to demonstrate lifecycle environmental superiority against gas-dependent alternatives. High-voltage suspension product lines are responding with enhanced recyclability certifications and carbon footprint disclosures.
Utility procurement officers are consolidating supplier panels and demanding integrated hardware-software-service packages. Direct manufacturer relationships are displacing traditional electrical distributor channels for transmission-class orders. This concentration is most visible in India's state transmission utilities and Brazil's regional grid operators, where tender specifications now require decade-long performance warranties.
HV Glass Insulator Market Segmentation
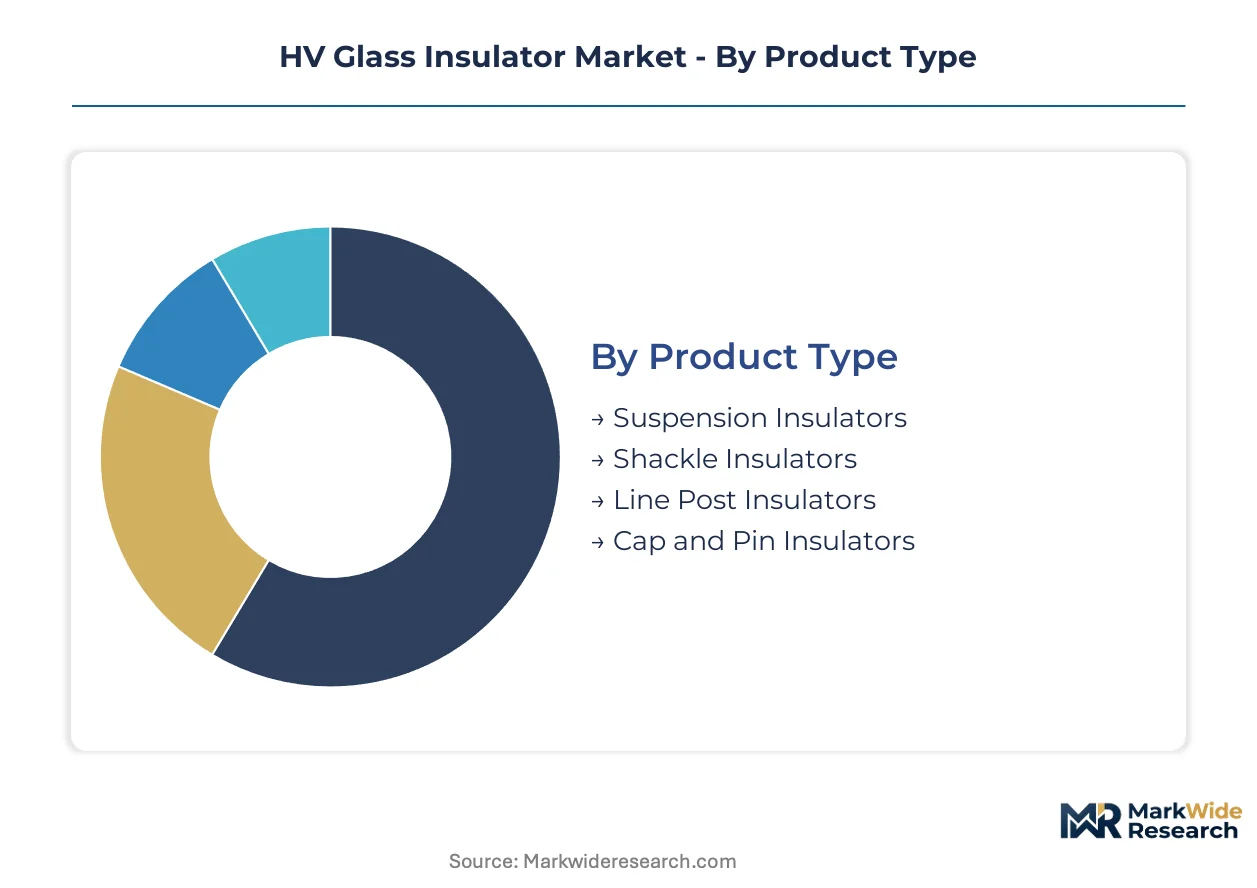
Segmentation in the HV glass insulator market reveals how technical specifications, procurement channels, and voltage requirements create distinct competitive arenas. Each dimension exposes different margin structures and qualification barriers that determine supplier positioning.
Product Type:
Use-case spectrum spans transmission towers, distribution poles, substation equipment, and specialized renewable interconnection hardware.
- Suspension Insulators:Toughened glass disc assemblies strung in vertical or horizontal strings to support energized conductors on transmission towers. Demand concentrates in China and India where state-owned utilities are executing massive rural electrification programs requiring visual inspection capabilities in remote maintenance contexts.
- Cap and Pin Insulators:Ball-and-socket coupling designs enabling modular string assembly for variable voltage ratings. European offshore wind developers specify these for marine pollution environments, opening premium product tiers with enhanced coating technologies.
- Shackle Insulators:Compact designs for low-voltage distribution dead-end applications.
- Line Post Insulators:Rigid support structures for distribution pole-top mounting.
The dominant share belongs to Suspension Insulators, while Cap and Pin Insulators is closing the gap fastest.
End User:
Customer type determines contract structure, with direct procurement displacing traditional distributor channels for transmission-class orders.
- Utility Companies:State-owned transmission operators and regional grid companies issuing multi-year supply tenders with decade-long performance warranties. India's state transmission utilities and Brazil's regional grid operators consolidate supplier panels and demand integrated hardware-service packages.
- OEMs:Original equipment manufacturers integrating insulators into complete transmission tower and substation packages. These customers prioritize IEC 60383 certification and technical compliance over price competition in contract negotiations.
- Industrial Users:Captive power plants and heavy manufacturing facilities with private transmission infrastructure.
- Telecommunication:Fiber optic and microwave tower operators requiring dielectric support hardware.
Utility Companies command the largest procurement volume, with OEMs expanding their share through bundled equipment contracts.
Voltage Rating:
Performance tier segmentation aligns with grid infrastructure investment cycles and long-distance power transfer requirements.
- High Voltage:Standard transmission ratings from 66 kV to 220 kV representing baseline utility procurement. This segment anchors volume for established toughened glass suppliers serving conventional overhead line projects across emerging economies.
- Ultra High Voltage:Ratings exceeding 800 kV for long-distance corridors and interregional grid interconnection. China and India are deploying UHVDC lines requiring specialized insulator assemblies combining glass shells with composite hardware.
- Extra High Voltage:330 kV to 765 kV ratings for regional transmission backbone reinforcement.
- Medium Voltage:Distribution-level ratings facing displacement pressure from silicone rubber alternatives.
High Voltage retains the largest installed base, though Ultra High Voltage is climbing the fastest as grid operators upgrade corridors.
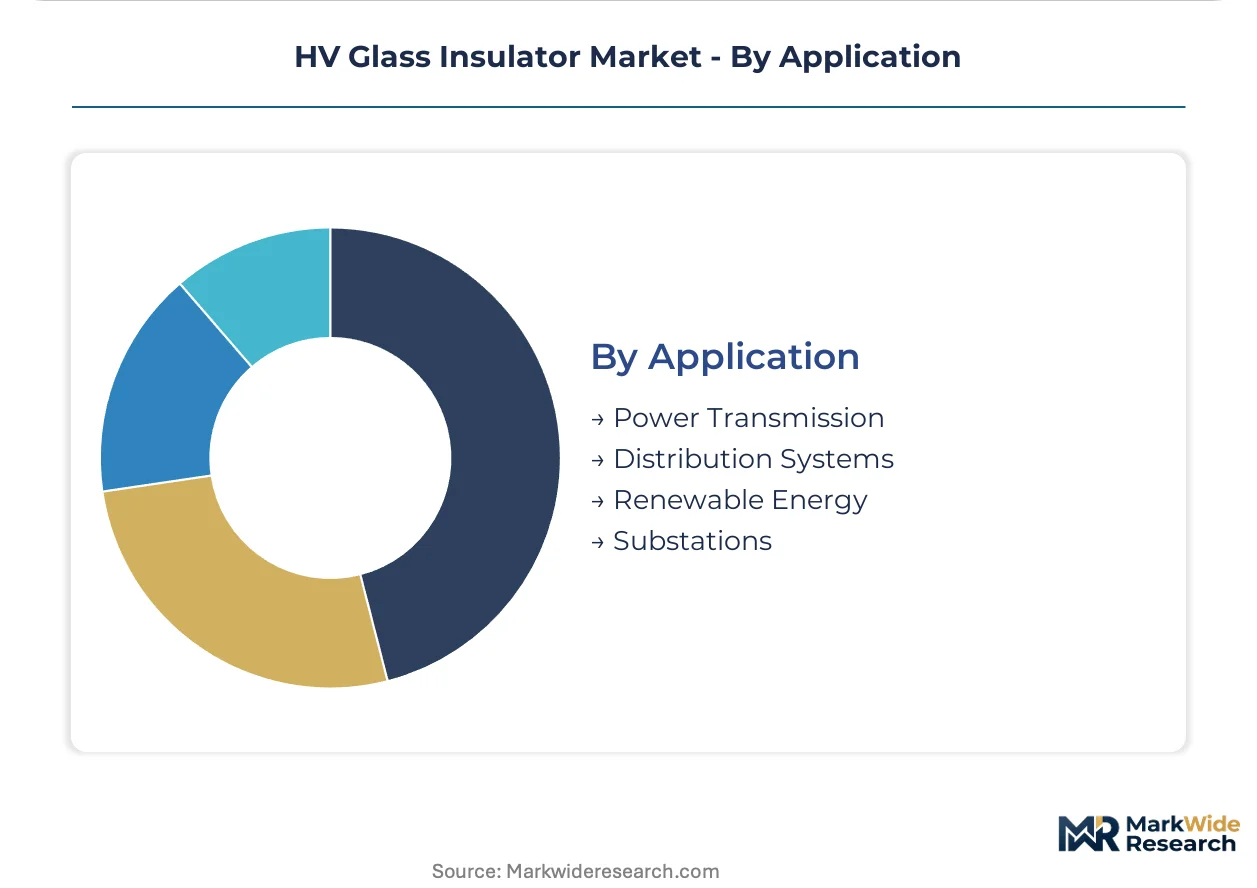
Application:
End-use context determines environmental exposure, failure mode tolerance, and maintenance regime specifications.
- Power Transmission:Long-distance overhead lines requiring suspension strings with predictable fragmentation failure modes. RTE and TenneT are piloting embedded fiber optic sensors on 400 kV corridors to digitize condition monitoring.
- Renewable Energy:Offshore wind and solar farm interconnection projects demanding marine pollution withstand and desert contamination resistance. This application is gaining share fastest as renewable capacity targets drive specialized procurement.
- Distribution Systems:Medium and low-voltage networks where glass competes with polymer alternatives.
- Substations:Equipment bushings and support structures adjacent to gas-insulated switchgear facing EU F-Gas Regulation scrutiny.
Power Transmission maintains the dominant revenue position, while Renewable Energy is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's CEA technical regulations and Brazil's ANEEL reliability mandates are accelerating procurement of IEC 60383-compliant toughened glass insulators across emerging grid infrastructure programs. State-owned utilities in both countries are consolidating supplier panels under decade-long performance warranties. China's UHVDC corridor buildout and European offshore wind interconnection projects are creating parallel demand centers for specialized suspension assemblies.
China
State Grid Corporation and China Southern Power Grid are deploying ultra high voltage direct current corridors exceeding 800 kV ratings for interregional power transfer. The national energy regulator enforces GB standards alignment with IEC 60383 for mechanical load cycling qualification. Manufacturing clusters in Shandong and Jiangsu provinces produce over half of global toughened glass shell output, concentrating supply-side capacity in eastern coastal regions.
India
Power Grid Corporation and state transmission utilities are executing rural electrification programs requiring visual inspection capabilities in remote maintenance contexts. The Central Electricity Authority mandates enhanced pollution withstand standards that compress market access for uncertified suppliers. Industrial corridors in Gujarat and Maharashtra host toughening furnace operations serving domestic tender specifications.
Brazil
Regional grid operators are extending transmission networks to accommodate renewable energy integration from northern hydroelectric and northeastern wind complexes. ANEEL reliability incentives reward utilities for reduced outage frequency, favoring glass insulators with predictable fragmentation failure modes. Manufacturing presence concentrates in São Paulo state for serving southeastern load centers.
Germany
TenneT and 50Hertz are piloting embedded fiber optic sensors on 400 kV corridors to digitize condition monitoring capabilities. The EU F-Gas Regulation phase-down mandates accelerate scrutiny of alternative insulation technologies in substation environments adjacent to overhead lines. Industrial clusters in North Rhine-Westphalia anchor European glass insulator R&D for offshore wind interconnection specifications.
United States
MacLean Power Systems and regional utilities are modernizing aging transmission infrastructure across the Eastern Interconnection and Texas ERCOT zone. FERC Order 1000 compliance requirements shape interregional transmission planning and associated insulator procurement specifications. Manufacturing and testing facilities in the Midwest and Southeast serve domestic utility direct procurement channels.
HV Glass Insulator Market Competitive Landscape
On the supply side, the industry is consolidating around vertically integrated specialists with captive tempering furnace capacity and IEC certification infrastructure. The vendor base separates into three strategic archetypes: European heritage manufacturers with long-term utility relationships, Asian scale producers serving price-sensitive tender markets, and regional specialists targeting niche pollution environments. Dominant competitive moves include backward integration into mineral processing and strategic partnerships for HVDC converter station assemblies.
Among European heritage manufacturers, Seves Group and Sediver exemplify the premium-tier positioning anchored by continental grid operator relationships. NGK Insulators occupies a central position within Asian-scale production archetypes, representing the toughened glass formulation specialization visible across utility tender documentation. MacLean Power Systems anchors North American regional supply capabilities, sitting within the utility-direct procurement channel structure reshaping distributor economics.
| Leading Market Players |
|---|
| Seves Group |
| NGK Insulators |
| MacLean Power Systems |
| LAPP Insulators |
| INAEL Electrical Systems |
| Aditya Birla Insulators |
| PPC Insulators |
| Victor Insulators |
| Sediver |
| Others |
Supply & Pricing Matrix
Shandong and Jiangsu provinces anchor over half of global toughened glass shell production, concentrating capacity in eastern China's coastal manufacturing belt. This geographic clustering grants established furnace operators disproportionate leverage in long-term supply negotiations with national transmission utilities across India and Brazil.
Pricing Analysis
IEC 60383 certification tier creates the primary spread between premium and commodity-grade offerings in this market. Three-tier pricing structure across premium, standard, and economy levels reflects differential compliance with mechanical load cycling and pollution withstand protocols. Cost compression in standard-grade segments is intensifying because Chinese manufacturers are expanding tempering furnace capacity faster than qualification timelines allow. State-owned utilities in emerging economies exhibit the highest price sensitivity, while European offshore wind developers prioritize technical compliance over unit economics.
Supply Chain Analysis
Export control regimes on advanced tempering furnace technology limit equipment flows to uncertified manufacturers in sub-Saharan Africa and Southeast Asia. Production gravity centers on China, India, and Germany for finished insulator assemblies. Soda ash, silica sand, and limestone feedstock draws from mineral processing operations concentrated in Shandong province and Gujarat state. Single-source vulnerability in specialized glass batch formulations creates procurement risk for manufacturers lacking backward integration. Distribution runs through direct manufacturer-utility procurement channels that are displacing traditional electrical distributor networks for transmission-class orders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
HV glass insulators sit in early-cycle expansion as renewable energy interconnection projects accelerate specialized suspension assembly procurement across offshore wind and solar farm corridors.
For Market Incumbents: Entrench market position through captive tempering furnace capacity additions in Gujarat and São Paulo industrial corridors. Composite polymer substitution in medium-voltage segments threatens volume anchors, making IEC 60383 certification maintenance the critical defensive lever for transmission-tier pricing power. For New Entrants and Emerging Players: Sub-Saharan grid buildout in Nigeria, Kenya, and Ethiopia represents the most penetrable entry point for IEC-compliant manufacturers facing saturated Asian tender markets. Target ANEEL reliability incentive programs in Brazil's northeastern wind complexes through partnership with regional EPC contractors lacking glass insulator supply relationships. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated specialists with captive mineral processing and decade-long utility warranty track records. Long-term viability hinges on HVDC converter station assembly capabilities converging glass and composite material technologies. Watch embedded fiber optic sensor adoption rates at RTE and TenneT as the inflection signal for predictive maintenance service revenue streams.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Mineral Processing | Captive soda ash and silica supply secures margin stability against raw material volatility. |
| IEC 60383 Certification Investment | Qualification for Indian CEA and Brazil ANEEL tenders compresses competitor market access. |
| HVDC Converter Station Partnership | Glass-composite hybrid assemblies open ultra high voltage direct current corridor opportunities. |
| Embedded Sensor Technology Licensing | Fiber optic integration with RTE and TenneT pilots digitizes condition monitoring revenue. |
| Sub-Saharan Distribution Partnership | First-mover positioning in Nigerian and Kenyan grid extensions builds tender track records. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with utility procurement officers at Power Grid Corporation and State Grid Corporation, tempering furnace operations managers in Shandong and Gujarat, and EPC contractors specializing in offshore wind interconnection. Secondary validation drew from IEC 60383 test protocol documentation, ANEEL reliability incentive filings, CEA technical regulation updates, and customs trade data on soda ash and silica sand movements. Bottom-up capacity estimates from individual furnace operations were triangulated against top-down transmission infrastructure investment forecasts across the analysis window.
Calibration against historical tender award volumes and actual installation rates anchored the projection framework. Segmentation modeling spanned product type, voltage rating, end-user archetype, and regional regulatory cluster throughout the forecast period. CAGRs were derived from regression analysis of infrastructure investment cycles correlated with renewable energy capacity targets. Industry-specific inputs included pollution severity mapping data and GB standards alignment timelines with IEC protocols.
Practitioners should monitor regulatory revision triggers including CEA pollution withstand standard updates and EU F-Gas Regulation phase-down acceleration for early signals of demand inflection. Forecasts reflect documented assumptions on tempering furnace capacity expansion rates and utility direct procurement channel penetration. Material shifts in Chinese export control enforcement on furnace technology or sub-Saharan grid financing availability would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
Industrial Strainers Market
Industrial Materials
Industrial Continuous Furnaces Market
Industrial Materials
Fiberglass Tanks Market
Industrial Materials
Industrial Pails and Drums Market
Industrial Materials
Noise Reduction Plastic Gear Market
Industrial Materials
Flat Enameled Wires Market
Industrial Materials
Middle-East and Africa Engineering Plastics Market
Industrial Materials
Asia Pacific Expanded Polyethylene (EPE) Foam Market
Industrial Materials
Injection Molding Market
Industrial Materials
Flat Scroll Spring Market
Industrial Materials
Saudi Arabia Industrial Insulation Market
Industrial Materials
Cork Material Market
Industrial Materials
2-in-1 Material Rack Correction Machine Market
Industrial Materials
North America Medical Plastics Extrusion Market
Industrial Materials
Ribbed Smoke Sheet Market
Industrial Materials
Injection Mold Hot Runners Market