
 Lithium Silicate Market | 2026-2036
Lithium Silicate Market Size, Share, and Industry Trends Forecast 2026-2036
Lithium Silicate Market Foresight
Maintenance contracts and performance-based service agreements is pivoting how lithium silicate suppliers capture recurring revenue beyond initial chemical sales. PQ Corporation leverages its North American distribution network to sustain bulk supply relationships with ready-mix concrete producers. Ganfeng Lithium anchors downstream demand through captive lithium carbonate supply that feeds directly into silicate manufacturing. Silmaco specializes in European formulations that navigate REACH registration requirements for industrial surface treatments.
Lithium silicate is an inorganic compound formed from lithium oxide and silicon dioxide, typically supplied as an aqueous solution with molar ratios between 4.8 and 7.5 that reacts with calcium hydroxide in concrete to form insoluble calcium silicate hydrate. Floor coatings applications dominate value capture due to premium pricing for polished concrete systems in retail and warehouse environments, while concrete sealers represent the volume base across infrastructure rehabilitation projects. Nano-coating technology leads growth trajectory as manufacturers integrate lithium silicate with colloidal silica dispersions to achieve sub-micron penetration depths that outperform conventional polymer-modified alternatives.
EPA regulates VOC emissions from architectural coatings under 40 CFR Part 59, while OSHA enforces permissible exposure limits for silica dust during concrete grinding operations that precede lithium silicate application. REACH registration requirements in Europe mandate full toxicological dossiers for lithium silicate imports above one tonne annually, creating compliance barriers for non-EU suppliers. Stakeholders must monitor evolving green building certification criteria from LEED and BREEAM that increasingly credit low-alkali densifiers for indoor air quality performance.
Market Dynamics
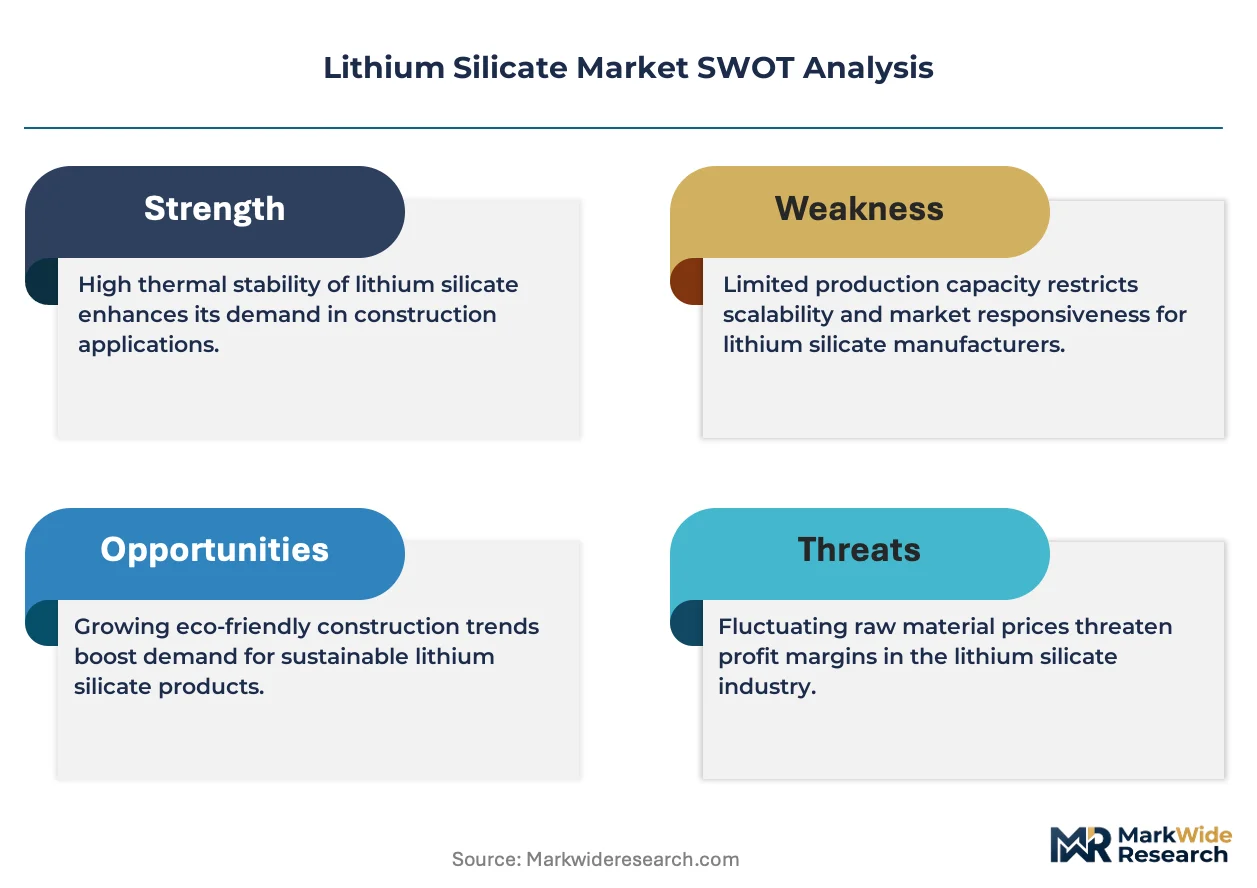
Floor coating specifications are hardening across commercial construction, forcing formulators to abandon sodium-based densifiers for lithium silicate systems that deliver measurable compressive strength gains and VOC compliance. This specification cascade is restructuring supplier relationships and raw material sourcing patterns.
Growth Catalysts
- EPA 40 CFR Part 59 VOC thresholds:Tightening emission limits for architectural coatings are disqualifying solvent-based concrete sealers from federal and state procurement contracts.
- Polished concrete specification:Retail and logistics facility designers are mandating lithium silicate densifiers for warehouse floors requiring abrasion resistance above 3,000 psi surface hardness.
- China infrastructure rehabilitation:Provincial transportation departments are specifying lithium silicate for bridge deck and tunnel lining restoration projects.
Market Restraints
- Spodumene concentrate volatility:Battery-grade lithium carbonate competition is compressing chemical-grade supply availability for silicate manufacturers.
- REACH registration dossiers:ECHA toxicological data requirements for imports above one tonne annually block non-EU suppliers from direct market access.
- Colloidal silica substitution:Nano-silica dispersions are capturing specification share in premium polished concrete applications requiring sub-micron penetration.
Strategic Opportunities
- India commercial real estate:BIS certification pathways for green building materials are opening specification channels for low-alkali densifiers in LEED-registered projects.
- Colloidal silica convergence:Hybrid formulations combining lithium silicate with nano-silica dispersions are enabling premium pricing in aerospace and pharmaceutical cleanroom flooring.
- Performance-based maintenance contracts:Facility management firms are adopting surface durability guarantees that lock in recurring chemical replenishment schedules.
Industry Challenges
- Concrete substrate assessment expertise:Applicator networks lack standardized training for moisture vapor emission testing that determines lithium silicate dosage rates.
- OSHA silica dust compliance:Surface preparation grinding operations trigger permissible exposure limit monitoring that extends project timelines and labor costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lithium Silicate Market |
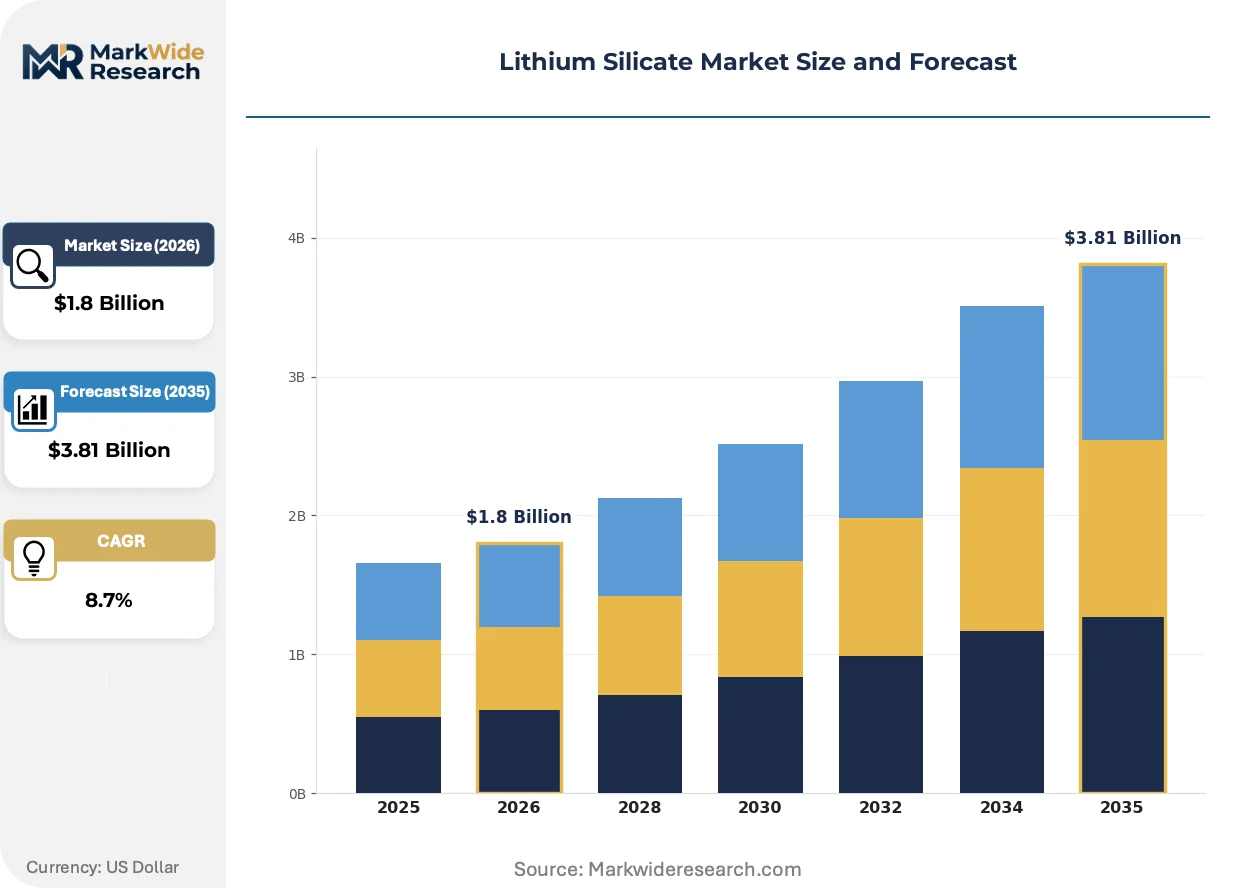
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fast-Setting, Long-Lasting, Water-Resistant, High-Strength Application: Floor Coatings, Concrete Sealers, Fireproofing, Surface Treatments End User: Construction, Industrial, Automotive, Aerospace Technology: Nano-Coating, Polymer Modification, Chemical Reaction, Surface Optimization |
| Companies Covered | Sterling Chemicals, RongXiang, PQ Corporation, Ganfeng Lithium, Tongxin, Silmaco, NYACOL Nano Technologies, Shandong Bangde Chemical, Nippon Chemical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lithium Silicate Market Shifts & Advancements
Formulation chemistry is converging with application robotics and real-time substrate analytics, compressing the traditional specification-to-completion cycle while raising performance verification standards.
Hybrid lithium silicate-colloidal silica systems are integrating nano-scale particle distributions that penetrate concrete capillaries below 500 nanometers. High-performance automotive and electronics manufacturing facilities in Germany and South Korea are specifying these formulations for electrostatic discharge control. The technology is integrating quality assurance protocols that were previously separate laboratory procedures into field-deployable spectroscopic verification.
REACH registration deadlines for lithium silicate substances are forcing importers to submit full toxicological dossiers by fixed regulatory cutoffs. Industrial surface treatment suppliers without EU-based legal entities are losing specification status in public infrastructure tenders. Formulators with pre-registered substance volumes are capturing market access that competitors cannot replicate within compliance timelines.
Facility owners are unbundling material supply from application labor, separating chemical procurement from certified installer networks. Large retail chains in the United States are direct-sourcing lithium silicate concentrates while contracting regional polishers for surface preparation and burnishing. This disintermediation is compressing distributor margins while rewarding formulators with bulk logistics capabilities and technical service documentation.
Lithium Silicate Market Segmentation
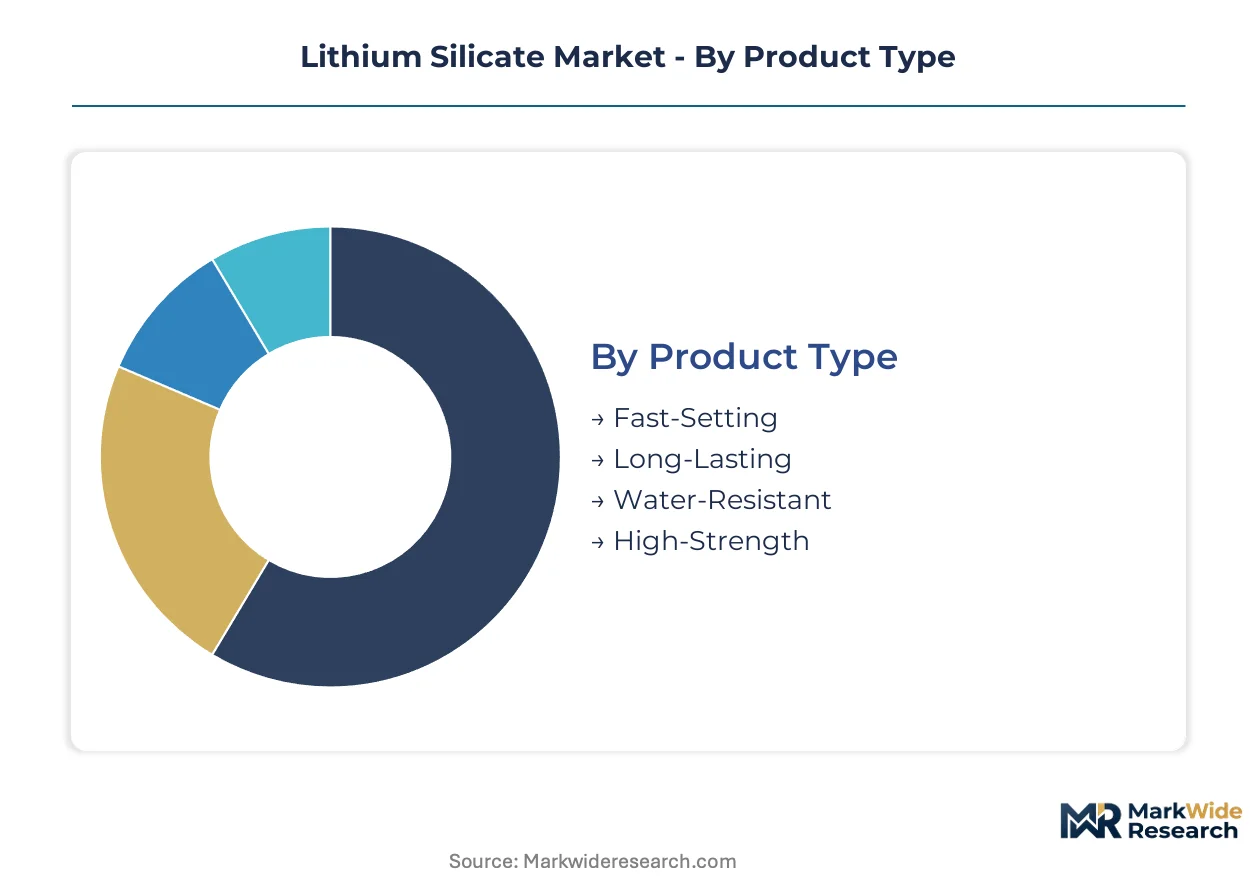
Lithium silicate formulations diverge sharply across performance tiers, with specification chemistry determining adoption in premium polished concrete versus commodity infrastructure sealing. Segmentation reveals how manufacturers align product architecture with substrate requirements, regulatory thresholds, and end-use durability demands.
Product Type:
Performance specifications differentiate lithium silicate systems by cure kinetics, hydrophobicity, and compressive strength contribution.
- Fast-Setting:Accelerated lithium silicate formulations reduce return-to-service intervals from 72 hours to 24 hours in retail and logistics facilities. Demand concentrates in the United States where big-box retailers enforce strict construction window penalties.
- High-Strength:Molar ratios above 7.0 deliver surface hardness exceeding 4,000 psi for aerospace hangar and electronics manufacturing floors. Germany and South Korea specify these formulations for electrostatic discharge control in cleanroom environments.
- Long-Lasting:Extended service life formulations target bridge deck and tunnel rehabilitation with 15-year performance warranties.
- Water-Resistant:Hydrophobic lithium silicate systems reduce moisture vapor emission rates below 3 pounds per 1,000 square feet per 24 hours.
Mature deployment sits with Long-Lasting formulations in infrastructure rehabilitation. Newer deployment is concentrated in High-Strength systems for precision manufacturing environments.
Application:
End-use segmentation tracks how substrate preparation depth and aesthetic finish requirements reshape chemical specification.
- Floor Coatings:Polished concrete systems integrate lithium silicate densifiers with diamond grinding sequences to achieve mirror-finish surfaces. Retail chains and third-party logistics operators in the United States specify these for warehouse facilities requiring abrasion resistance above 3,000 psi.
- Concrete Sealers:Penetrating lithium silicate treatments dominate volume in bridge deck, parking structure, and municipal infrastructure rehabilitation across China and India.
- Fireproofing:Intumescent lithium silicate coatings provide passive fire protection for steel-reinforced concrete in high-rise construction.
- Surface Treatments:Specialty formulations address efflorescence control and chloride ingress prevention in marine and coastal environments.
Volume leadership belongs to Concrete Sealers across public infrastructure procurement. Floor Coatings command premium pricing and represent the steepest expansion trajectory in commercial construction specification.
End User:
Customer segmentation reflects divergent procurement patterns between project-based construction and ongoing facility maintenance.
- Construction:General contractors and concrete polishers specify lithium silicate during new commercial build-outs and tenant improvements. LEED-registered projects in the United States increasingly mandate low-alkali densifiers for indoor air quality credits.
- Industrial:Manufacturing facility operators adopt performance-based maintenance contracts with guaranteed surface durability metrics. Food and beverage processing plants in Germany specify lithium silicate for hygienic flooring compliance.
- Automotive:Assembly plant floors require electrostatic discharge control and chemical resistance to hydraulic fluids and solvents.
- Aerospace:Hangar and cleanroom flooring specifications in France and South Korea integrate hybrid lithium silicate-colloidal silica systems for sub-micron penetration.
Procurement consolidation is most advanced in Industrial end users with multi-site facility management frameworks. Construction remains fragmented across regional contractor networks.
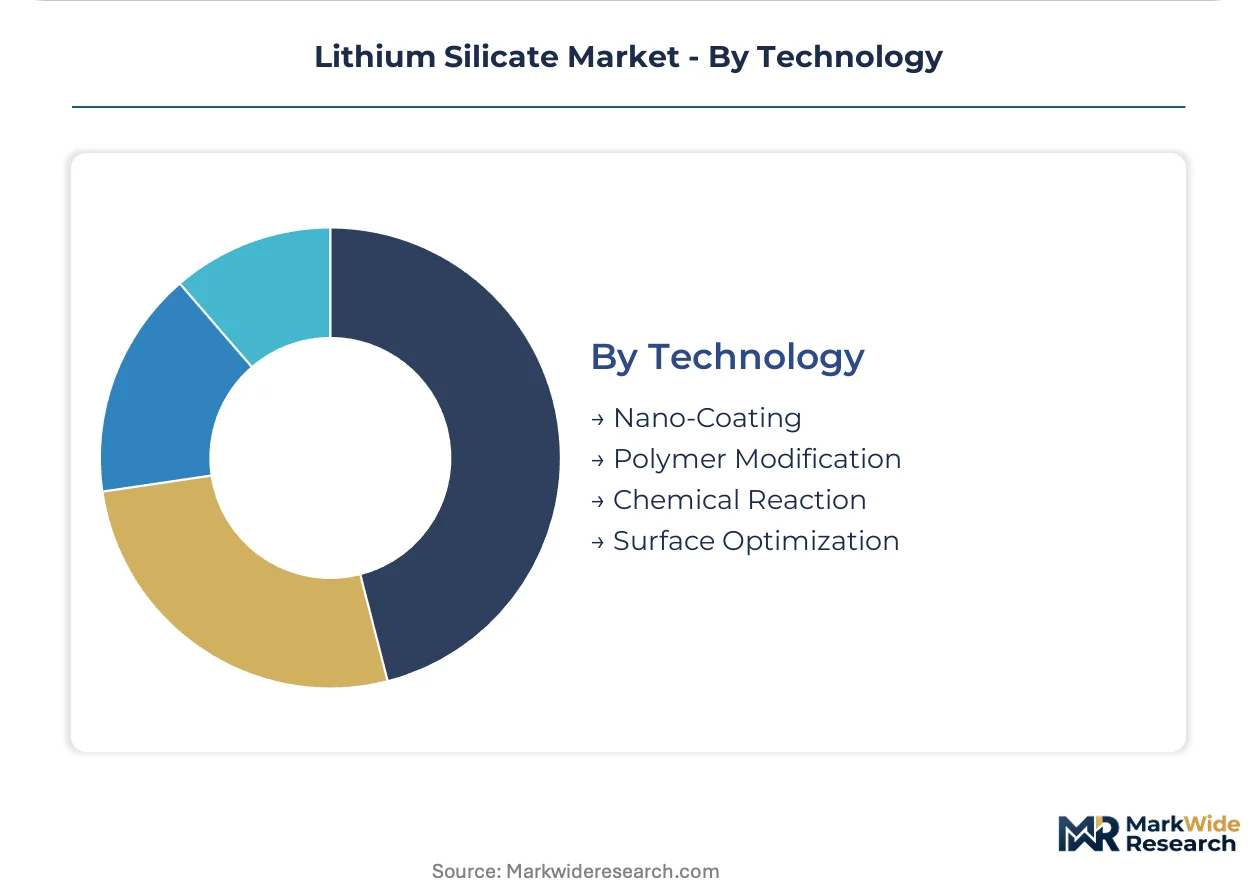
Technology:
Process innovation distinguishes penetration depth, reaction kinetics, and quality verification protocols.
- Nano-Coating:Colloidal silica integration achieves capillary penetration below 500 nanometers, outperforming conventional lithium silicate in premium polished concrete applications. German automotive manufacturers and South Korean electronics fabricators specify these formulations for precision manufacturing environments.
- Chemical Reaction:Standard lithium silicate reacts with calcium hydroxide to form insoluble calcium silicate hydrate, the foundational mechanism for all densification applications.
- Polymer Modification:Acrylic and polyurethane additives enhance stain resistance and gloss retention in retail and hospitality flooring.
- Surface Optimization:Real-time spectroscopic verification integrates quality assurance directly into field application protocols.
Established deployment centers on Chemical Reaction technology across commodity infrastructure applications. Nano-Coating is gaining specification share fastest in high-performance manufacturing and cleanroom environments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai anchors the lithium silicate trade corridor, with Jiangsu and Zhejiang provinces feeding raw material streams into densifier manufacturing for domestic infrastructure and export markets.
United States
Big-box retailers and third-party logistics operators in Dallas-Fort Worth and the Inland Empire mandate lithium silicate densifiers for warehouse floors requiring abrasion resistance above 3,000 psi. EPA 40 CFR Part 59 VOC thresholds disqualify solvent-based sealers from federal procurement contracts. California's South Coast Air Quality Management District enforces the nation's strictest architectural coating limits, concentrating specification-grade formulation demand in Los Angeles and San Diego counties.
Germany
Automotive manufacturers in Stuttgart and Wolfsburg specify hybrid lithium silicate-colloidal silica systems for electrostatic discharge control in cleanroom environments. REACH registration requirements through ECHA mandate full toxicological dossiers for imports above one tonne annually. The Bavarian industrial corridor around Munich hosts precision electronics fabricators driving nano-coating specification growth.
China
Provincial transportation departments in Guangdong and Sichuan specify lithium silicate for bridge deck and tunnel lining restoration projects. Domestic lithium processing capacity in Jiangxi and Qinghai creates concentrated pull for high-strength formulations. The Yangtze River Delta manufacturing cluster around Shanghai produces the majority of Asia's densifier exports.
India
Commercial real estate developers in Mumbai and Bengaluru pursue BIS certification pathways for green building materials in LEED-registered projects. Central Public Works Department specifications increasingly reference low-alkali densifiers for government infrastructure. The Delhi-Mumbai Industrial Corridor anchors demand for concrete sealers in logistics park construction.
South Korea
Electronics manufacturers in Suwon and Pyeongtaek integrate lithium silicate flooring for semiconductor cleanroom compliance. The country's national chemical regulator enforces stringent import documentation for industrial surface treatments. Busan's port infrastructure rehabilitation programs specify long-lasting formulations with 15-year performance warranties.
Lithium Silicate Market Competitive Landscape
Capital-heavy producers compete with asset-light formulators across the lithium silicate value chain. Integrated lithium compound manufacturers leverage captive carbonate supply, while specialized silicate fabricators focus on REACH-compliant formulation chemistry. Three archetypes dominate: upstream lithium producers with downstream silicate units, independent chemical specialists with regional formulation expertise, and nano-material innovators integrating colloidal silica technology. Capacity expansion and strategic partnerships represent the primary competitive vectors as firms secure raw material access and distribution networks.
Among North American chemical specialists, PQ Corporation exemplifies the distribution-anchored archetype with bulk supply relationships across ready-mix concrete networks. Ganfeng Lithium occupies a position as an upstream-integrated producer leveraging captive lithium carbonate feedstock. Silmaco represents the European formulation specialist archetype navigating REACH registration requirements for industrial surface treatments.
| Leading Market Players |
|---|
| Sterling Chemicals |
| RongXiang |
| PQ Corporation |
| Ganfeng Lithium |
| Tongxin |
| Silmaco |
| NYACOL Nano Technologies |
| Shandong Bangde Chemical |
| Nippon Chemical |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up specialists across North American distribution networks enforce pricing discipline through volume-commitment contracts with ready-mix concrete producers, while sovereign-backed producers in China leverage state-financed lithium carbonate capacity to undercut chemical-grade pricing in export markets. This ownership fragmentation creates divergent supply behaviors: financial sponsors prioritize margin extraction through specification-grade premiums, whereas state-linked entities absorb upstream volatility to secure downstream offtake.
Pricing Analysis
Performance-based pricing anchored to floor hardness outcomes dominates specification-grade lithium silicate, with formulators charging premiums tied to measurable compressive strength gains above 3,000 psi. Three-tier pricing structure across premium, standard, and economy levels separates nano-coating hybrid formulations from commodity penetrating sealers and bulk infrastructure grades. Cost compression in standard-grade densifiers is intensifying because battery-grade lithium carbonate competition is compressing chemical-grade spodumene availability. Warehouse operators and third-party logistics firms exhibit the highest price sensitivity, while aerospace cleanroom specifiers accept substantial premiums for REACH-registered, sub-500-nanometer penetration systems.
Supply Chain Analysis
Empty container repositioning and bulk liquid return logistics constrain export economics for aqueous lithium silicate formulations, forcing regional production footprints near terminal markets. Manufacturing concentrates in China, Germany, and the United States, with Jiangsu and Zhejiang provinces feeding raw material streams into densifier production for domestic infrastructure and export markets. Formulation chemistry draws from lithium carbonate, sodium silicate feedstock, and colloidal silica dispersions. Single-source vulnerability in battery-grade lithium carbonate allocation decisions threatens chemical-grade supply security for silicate manufacturers. Distribution runs through ready-mix concrete networks, specialized coating distributors, and direct procurement channels to large facility owner-operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spodumene concentrate conversion capacity bottlenecks at hard-rock lithium operations prop pricing power for integrated silicate manufacturers with captive carbonate supply. This supply-constrained structure rewards early positioning in qualified supplier programs before REACH registration deadlines foreclose market access.
For Market Incumbents: Deploy specification-capture strategies by deepening technical service capabilities for moisture vapor emission testing and dosage optimization. Incumbents should secure backward integration into lithium carbonate through long-term offtake agreements with Australian and Canadian spodumene producers, insulating against battery-grade competition. Colloidal silica substitution in premium polished concrete applications threatens margin-accretive nano-coating segments, requiring accelerated R&D investment in hybrid formulation patents. For New Entrants and Emerging Players: Regional concrete polishing contractors underserved by certified applicator networks represent the most penetrable entry vector. New entrants should target India's BIS certification pathways for LEED-registered commercial real estate, where specification-grade demand outpaces qualified supplier availability. A go-to-market angle anchored to performance-based maintenance contracts with guaranteed surface durability metrics bypasses entrenched distributor relationships and locks in recurring revenue streams. For Investors and Strategic Acquirers: Distressed-cycle entries favor REACH-registered European formulation specialists with pre-submitted toxicological dossiers and established public infrastructure tender status. Long-term viability across a five-to-ten-year window hinges on positioning ahead of green building certification criteria evolution and EPA VOC threshold tightening. The signal to watch is lithium carbonate price spreads between battery-grade and chemical-grade specifications, with narrowing differentials indicating upstream supply release favorable to silicate manufacturing economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lithium Carbonate | Captive supply from Australian spodumene operations insulates against battery-grade competition for chemical-grade allocation. |
| REACH Registration Completion | Full ECHA toxicological dossiers unlock public infrastructure tender access across European Union member states. |
| Hybrid Nano-Coating R&D Investment | Colloidal silica integration captures specification share in German automotive and South Korean electronics cleanroom flooring. |
| Performance-Based Maintenance Contracts | Surface durability guarantees lock in recurring chemical replenishment schedules with industrial facility operators. |
| India BIS Certification Pathway | Green building material approval opens specification channels for low-alkali densifiers in LEED-registered commercial projects. |
Research Methodology
Trade flow databases, ECHA registration filings, and SEC 10-K disclosures from lithium compound manufacturers formed the secondary backbone for supply-side calibration. Primary interviews with plant managers at densifier production facilities, procurement leads at ready-mix concrete networks, distribution channel partners in industrial coatings, and technical R&D directors at formulation specialists combined with secondary validation through customs records and industry association reports. Bottom-up and top-down triangulation reconciled capacity announcements with apparent consumption patterns across end-use segments.
Historical trendline analysis established baseline growth trajectories across floor coatings, concrete sealers, fireproofing, and surface treatment applications. The analytical framework modeled product type, application, end user, and technology dimensions across the projection horizon. CAGRs derived from segment-level growth rate reconciliation with macroeconomic drivers including commercial construction spending and infrastructure rehabilitation budgets. Forecast inputs incorporated EPA 40 CFR Part 59 VOC threshold evolution and REACH registration deadline impacts on supplier market access.
Revisions become necessary when spodumene concentrate price volatility, battery-grade lithium carbonate demand surges, or REACH enforcement intensity shifts materialize. Forecasts reflect assumptions regarding continued specification migration from sodium-based to lithium-based densifiers and stable green building certification criteria evolution. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Fire Clay Market
Ceramics
GCC Ceramic Tiles and Sanitary Ware Market
Ceramics
Fly Ash and Ceramic Microsphere Market
Ceramics
Advanced Ceramic Additives Market
Ceramics
Global Alumina Market
Ceramics
Calcite Market
Ceramics
Refractories Market
Ceramics
South Korea Ceramic Sanitaryware Market
Ceramics
China Ceramic Market
Ceramics
Stoneware Market
Ceramics
Diatomite Market
Ceramics
Global Magnesium Silicate Market
Ceramics
Global Metal and Ceramic Injection Molding Market
Ceramics
India Kaolin Market
Ceramics
Thailand Ceramic Tiles Market
Ceramics
Pottery Ceramics Market