
 Ceramics Market | 2026-2036
Ceramics Market Size, Share, and Industry Trends Forecast 2026-2036
Ceramics Market Intelligence
The adoption of binder jetting and stereolithography for ceramic 3D printing is narrowing the gap between prototyping and mass production. KYOCERA Corporation leverages its deep expertise in fine ceramics for advanced electronics and biomedical devices. Concurrently, Corning Inc. specializes in glass-ceramics for display technologies and scientific equipment. Saint Gobain sustains a broad portfolio, covering refractory ceramics for industrial furnaces and whiteware for construction.
Ceramics are inorganic, non-metallic materials processed and hardened at high temperatures, often exhibiting a crystalline or amorphous structure. Their primary industrial value stems from properties like high compressive strength, chemical inertness, and exceptional thermal and electrical insulation. Advanced ceramics command the highest value, driven by rigorous performance requirements in aerospace components and biomedical devices. In contrast, the whiteware segment, encompassing tiles and sanitaryware, is a high-volume, mature market where scale and distribution efficiency dictate competitive success.
Global product standards are governed by ISO specifications for technical ceramics, ensuring interoperability and quality. In Europe, the REACH regulation restricts the use of certain raw materials, while in the United States, OSHA standards mandate worker safety protocols for handling ceramic dust like silica. Navigating the divergent environmental regulations and material lifecycle requirements across key markets remains a central strategic challenge for manufacturers.
Market Dynamics
Energy consumption intensity remains the central structural force shaping the ceramics market. This creates a direct conflict between the high-temperature processing required for advanced ceramics and escalating pressure from end-markets to reduce the embodied carbon of components used in their supply chains.
Growth Catalysts
- Additive Manufacturing:The use of binder jetting and stereolithography enables the creation of complex geometries for medical implants and aerospace prototypes, which are impossible to produce with traditional molding or machining.
- Aerospace Demand:Requirements from the aerospace and defense sector for lightweight, thermally stable ceramic matrix composites (CMCs) in engine components and heat shields continue to expand.
- State-Backed Industrialization:China's industrial policies, guided by MIIT, provide significant support for developing domestic manufacturing clusters for electronics-grade ceramics, securing supply for its semiconductor and consumer electronics industries.
Market Restraints
- Energy Price Volatility:The high energy consumption of kilns and furnaces makes ceramic manufacturing profitability highly sensitive to fluctuations in natural gas and electricity prices, particularly in Europe.
- Raw Material Concentration:A significant portion of the global supply of high-purity alumina and zirconia is concentrated in China, creating supply chain vulnerability and price risk for manufacturers elsewhere.
- Inherent Brittleness:The brittle fracture nature of monolithic ceramics limits their use in applications with high tensile or impact stress, requiring complex and costly composite reinforcement to overcome.
Strategic Opportunities
- Solid-State Batteries:Development of ceramic electrolytes and separators for solid-state batteries represents a new, high-volume application with significant performance and safety advantages over current lithium-ion technologies.
- Indian Market Expansion:India's Production Linked Incentive (PLI) schemes create an opportunity to establish domestic technical ceramics manufacturing to serve its growing electronics, automotive, and healthcare sectors.
- Embedded Sensing:The integration of sensors directly into structural ceramic components allows for real-time health and performance monitoring, creating value in industrial machinery and aerospace systems.
Industry Challenges
- Specialized Talent Scarcity:A persistent shortage of materials scientists and process engineers with expertise in advanced ceramic formulation, sintering, and 3D printing hinders product development and process optimization.
- Regulatory Divergence:Manufacturers face complexity in managing a global supply chain while complying with divergent chemical regulations, such as Europe's REACH and California's Proposition 65.
- Capital-Intensive Modernization:Upgrading kilns and finishing equipment to meet the stringent purity and dimensional tolerance requirements for semiconductor and medical applications demands significant capital investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ceramics Market |
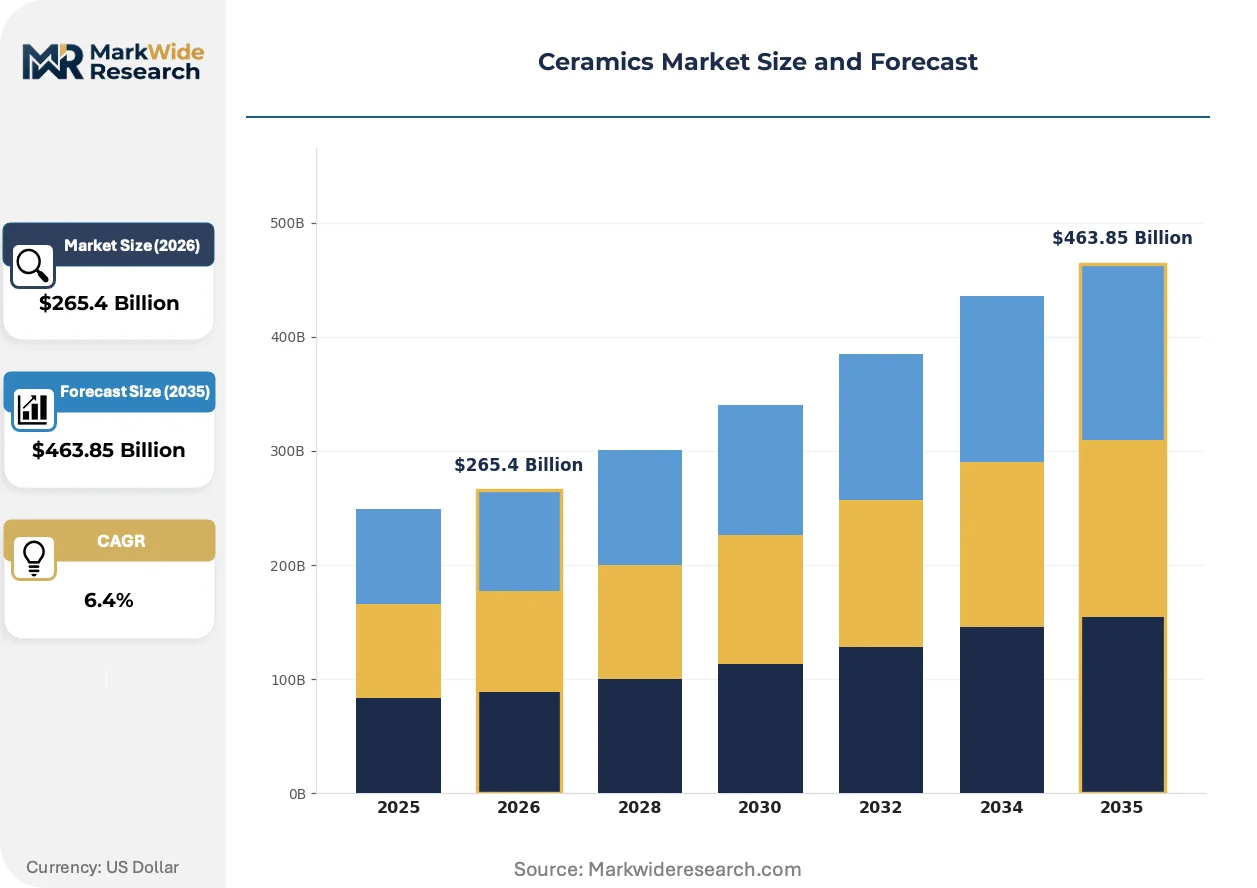
| Market Size in 2026 | $265.4 Billion |
| Market Size in 2035 | $463.85 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Technical Ceramics, Whiteware, Structural Ceramics, Refractory Ceramics, Advanced Ceramics Form: Powder, Tiles, Coatings, Films, Fibers Application: Electronics, Aerospace Components, Oilfield Equipment, Consumer Goods, Biomedical Devices End User: Manufacturing Plants, Research Laboratories, Construction Firms, Defense Contractors |
| Companies Covered | CoorsTek, Morgan Advanced Materials, KYOCERA Corporation, Corning Inc., Saint Gobain, 3M, CeramTec, NGK Insulators, Murata Manufacturing, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ceramics Market Strategic Shifts & Innovations
The market is shifting from supplying bulk materials to delivering precisely engineered components. This evolution is driven by digital fabrication methods that allow for functional complexity and a concurrent regulatory push toward material lifecycle management and sustainability.
Ceramic binder jetting is a 3D printing process that uses a liquid binding agent to join ceramic powders layer by layer. Aerospace and biomedical device manufacturers are rapidly adopting this technology for prototyping and small-batch production. This technique's ability to create intricate internal channels and lattice structures is rendering obsolete traditional subtractive machining and molding for complex, low-volume parts.
The European Union's REACH regulation continues to tighten restrictions on the use of specific raw materials, including certain lead and cadmium compounds in ceramic glazes. This forces a reformulation of materials and impacts global supply chains sourcing from regions with less stringent oversight. Whiteware and decorative ceramic segments are most affected, prompting investment in alternative, non-toxic formulations to maintain market access in Europe.
A shift toward lifecycle cost analysis is altering procurement for high-performance industrial applications. Buyers are moving away from simple unit-price purchasing of refractory bricks and toward performance-based contracts that value longevity and energy efficiency. This change is most visible in the steel and glass manufacturing sectors, where furnace uptime and thermal efficiency are critical operational metrics.
Ceramics Market Segmentation
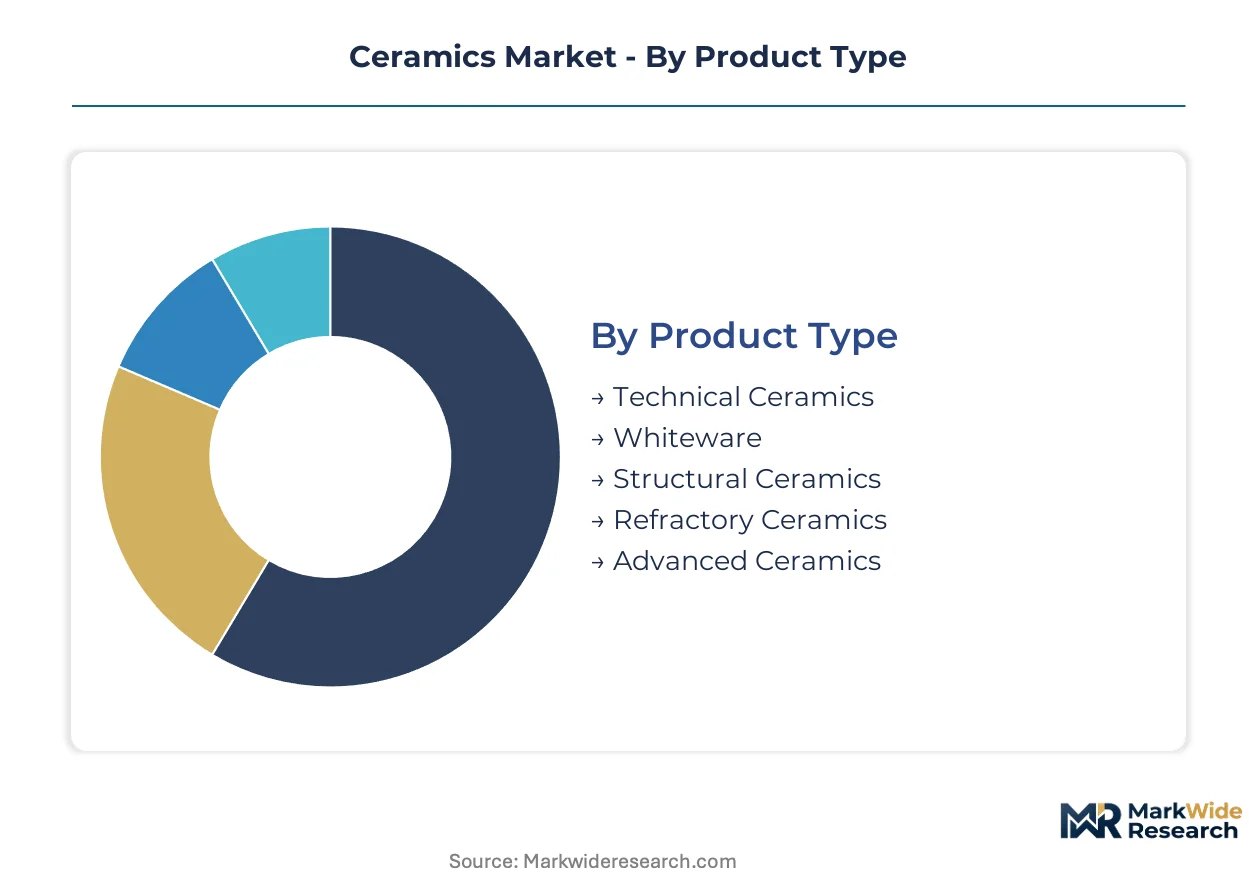
Understanding the varied properties and applications of ceramic materials is crucial for strategic market positioning. Segmentation clarifies how different ceramic compositions, forms, and end-uses influence processing methods, performance requirements, and competitive dynamics across the industry.
Product Type:
The material complexity and performance characteristics define distinct product types within the ceramics market.
- Advanced Ceramics:These materials exhibit superior mechanical, thermal, or electrical properties, often requiring specialized processing. Demand concentrates in aerospace and medical devices, where extreme conditions necessitate rigorous performance specifications.
- Technical Ceramics:Engineered for specific functional properties, these ceramics are critical for industrial and electronic applications. The automotive sector drives consumption for sensors and engine components, valuing their durability and heat resistance.
- Whiteware:This segment includes traditional ceramics like tiles, sanitaryware, and tableware, primarily serving construction and consumer markets.
- Refractory Ceramics:Designed to withstand high temperatures, these materials are essential for lining industrial furnaces and kilns in steel and glass manufacturing.
- Structural Ceramics:These materials are chosen for their load-bearing capacity and wear resistance in demanding industrial environments.
Whiteware holds significant installed capacity. Advanced Ceramics is rotating up the share rankings.
Form:
The physical manifestation of ceramic materials dictates their immediate utility and processing methods for end-users.
- Tiles:Manufactured as rigid, flat pieces, tiles are extensively used in construction for flooring, walls, and roofing. The residential and commercial building sectors in India drive substantial volume.
- Powder:Ceramic powders serve as foundational raw materials for advanced manufacturing techniques like additive manufacturing and pressing. The electronics industry uses high-purity powders for substrates and components.
- Coatings:Applied as thin layers, ceramic coatings enhance surface properties such as hardness, wear resistance, and thermal insulation for various industrial parts.
- Films:Ultra-thin ceramic films are integral to microelectronics and optical devices, providing dielectric and protective functionalities.
- Fibers:Ceramic fibers are woven into composites, offering lightweight and high-temperature resistance for aerospace and defense applications.
The largest volume of ceramic materials is processed into Tiles. Powder exhibits the steepest expansion trajectory.
Application:
Specific end-use requirements dictate the selection of ceramic materials based on their unique performance attributes.
- Aerospace Components:Ceramics are vital for lightweight, high-temperature resistant parts in jet engines and heat shields. The defense sector demands ceramic matrix composites for enhanced aircraft performance.
- Biomedical Devices:Biocompatible ceramics are used in implants, prosthetics, and dental applications due to their inertness and mechanical strength. Regulatory bodies like the FDA rigorously approve these materials.
- Electronics:Ceramics function as insulators, capacitors, and substrates in integrated circuits and other electronic devices.
- Consumer Goods:This segment includes ceramics for household items, decorative pieces, and some functional components in appliances.
- Oilfield Equipment:Ceramics provide wear and corrosion resistance for drilling tools and downhole components in harsh extraction environments.
Demand from Aerospace Components drives significant innovation. Biomedical Devices represents a rapidly expanding niche.
End User:
Organizational purchasing patterns and operational scales define distinct end-user segments within the ceramics market.
- Manufacturing Plants:Industrial facilities consume large volumes of ceramics for refractories, wear parts, and process equipment. The steel and cement industries are major purchasers of these materials.
- Defense Contractors:These entities procure advanced ceramics for ballistic protection, aerospace components, and specialized electronic systems. Government spending in the United States influences this segment.
- Construction Firms:Primarily using whiteware and structural ceramics, these firms drive demand for tiles, sanitaryware, and building materials.
- Research Laboratories:These institutions require specialized and high-purity ceramics for experimentation, prototyping, and materials development.
The largest procurement volume originates from Manufacturing Plants. Defense Contractors show increasing strategic importance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global ceramics market exhibits a complex interplay between regional production capabilities and end-market consumption. Significant export volumes originate from manufacturing hubs with integrated supply chains, while key consuming regions often rely on imported advanced ceramic components. This dynamic shapes investment flows and strategic positioning across diverse geographies.
China
China's massive industrial base drives demand for electronics-grade ceramics and high-volume whiteware for construction. MIIT industrial policies provide significant support for developing domestic manufacturing clusters. The Yangtze River Delta region concentrates electronics-grade ceramic production, securing supply for its semiconductor and consumer electronics industries.
United States
Demand for advanced ceramics in the United States stems from aerospace components and biomedical devices. OSHA standards mandate worker safety protocols for handling ceramic dust like silica in manufacturing facilities. Southern California hosts a cluster of advanced materials firms developing high-performance ceramic matrix composites for defense applications.
Germany
Germany's strong automotive sector and industrial machinery manufacturing propel demand for technical ceramics and specialized components. The European REACH regulation continues to tighten restrictions on certain raw materials used in ceramic glazes. Bavaria is a prominent hub for technical ceramics research and development, supporting high-precision engineering applications.
India
India's burgeoning construction sector drives substantial volume for ceramic tiles, alongside growing demand for electronics manufacturing. The country's Production Linked Incentive (PLI) schemes create opportunities for domestic technical ceramics manufacturing. Gujarat's ceramic industry is a major tile manufacturing center, serving both domestic and export markets with whiteware products.
Japan
Japanese industries require advanced ceramics for precision electronics and high-performance automotive components. METI initiatives support research and development in advanced ceramic materials for next-generation technologies. Aichi Prefecture serves as a significant automotive and ceramics manufacturing base, fostering innovation in functional ceramics.
Ceramics Market Key Industry Players
On the supply side, the industry is characterized by a tiered structure, with established global conglomerates alongside specialized niche players. This landscape includes large, diversified materials science companies and smaller, agile firms focused on advanced ceramic manufacturing. Strategic archetypes include integrated materials producers, application-specific solution providers, and regional commodity suppliers. Competitive moves often involve capacity expansion in high-growth segments and strategic partnerships to access new technologies or markets.
Among the diversified materials science conglomerates, KYOCERA Corporation and Corning Inc. exemplify companies leveraging deep expertise across multiple ceramic segments. KYOCERA Corporation, a Japanese-based entity, extends its reach into advanced electronics and biomedical devices through its fine ceramics. Corning Inc., an American corporation, occupies a strong position in glass-ceramics, serving display technologies and scientific equipment. Saint Gobain, a French industrial group, represents another archetype, sustaining a broad portfolio covering refractory ceramics for industrial furnaces and whiteware for construction. These entities anchor the high-value end of the market, focusing on performance-driven applications and integrated solutions.
| Leading Market Players |
|---|
| CoorsTek |
| Morgan Advanced Materials |
| KYOCERA Corporation |
| Corning Inc. |
| Saint Gobain |
| 3M |
| CeramTec |
| NGK Insulators |
| Murata Manufacturing |
| Others |
Cost & Logistics Intelligence
The China-Europe rail freight corridor's cost dynamics directly influence the pricing power of concentrated raw material suppliers and impact downstream price differentiation for ceramic products.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake agreements for advanced ceramics. Price differentiation stems from the quality grade, particularly the purity required for electronics, and the customization level for aerospace components. Pricing pressure from escalating energy costs for kiln operation is pushing prices upward across all segments. Construction firms purchasing whiteware exhibit the highest price sensitivity, while biomedical device manufacturers demonstrate the lowest.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities are common practices to manage working capital for raw material procurement. Geographic supply concentrates significantly in China for high-purity alumina and zirconia, alongside India for high-volume ceramic tiles. Raw material dependencies include specialized clays and rare earth elements for certain advanced ceramics. Supply chain vulnerability arises from this raw material concentration, creating potential single-source risks. Distribution for advanced and technical ceramics primarily occurs through direct sales, while whiteware relies on established distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market requires a strong substitution defense, as incumbents must navigate the threat of advanced polymers displacing ceramics in certain lightweight structural applications.
For Market Incumbents: Harden core manufacturing processes through capital investment in advanced kiln technologies to meet stringent purity and dimensional tolerance requirements for semiconductor applications. Develop ceramic matrix composites that overcome the inherent brittle fracture nature of monolithic ceramics. This counters margin pressure from energy price volatility by increasing value capture per unit, leveraging existing expertise in fine ceramics.
For New Entrants and Emerging Players: Pursue niche applications enabled by additive manufacturing techniques like binder jetting, targeting complex geometries for medical implants. Focus on underserved geographies such as India, leveraging its Production Linked Incentive (PLI) schemes to establish domestic manufacturing. A go-to-market angle emphasizing rapid prototyping and customized, low-volume production offers a competitive entry point.
For Investors and Strategic Acquirers: Carve-out targets emerge from large industrial conglomerates seeking to divest non-core ceramic material divisions. Long-term viability is sustained by demand from aerospace components and biomedical devices, requiring specialized materials. A signal to watch is the successful commercialization of ceramic electrolytes for solid-state batteries, indicating a new, high-volume application with significant disruptive potential.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Advanced Ceramics | Increases supply for aerospace components and biomedical devices with rigorous performance requirements. |
| Research in Ceramic Matrix Composites | Addresses the inherent brittleness of monolithic ceramics, expanding application possibilities in high-stress environments. |
| Investment in Additive Manufacturing | Enables production of complex ceramic geometries for prototyping and small-batch production, reducing lead times. |
| Strategic Partnerships for Talent | Mitigates the specialized talent scarcity in materials science and process engineering for advanced ceramic formulation. |
| Geographic Expansion into India | Leverages India's PLI schemes and growing electronics sector to establish new technical ceramics manufacturing hubs. |
Research Approach
A spread of perspectives from materials scientists, process engineers, procurement leads, and regulatory specialists converged on the working assumptions for the Ceramics Market. Primary interviews with industry stakeholders were combined with secondary validation from sources like ISO specifications, REACH regulations, OSHA standards, and MIIT policy documents. This approach ensured a robust understanding of market dynamics, triangulating insights from both bottom-up and top-down analyses.
Demand-supply-balance framing guided the analytical framework across the analysis window, modeling segmentation by product type, form, application, end user, and critical regional demand dynamics. Compound Annual Growth Rates (CAGRs) were derived through a synthesis of historical data analysis and expert projections, incorporating industry-specific forecast inputs such as projected energy price fluctuations and raw material availability trends.
Macroeconomic conditions sit as an overlay; deviation in global trade policies or raw material supply stability would shift the trajectory. Forecasts reflect assumptions regarding technological development and regulatory enforcement. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
North America Ceramic Coatings Market
Ceramics
Calcium Oxide Market
Ceramics
Refractory Material Market
Ceramics
Transparent Ceramics Market
Ceramics
Ceramic Substrate Market
Ceramics
Advanced Sintering Technologies Market
Ceramics
Ceramic Solid End Mills Market
Ceramics
Global Zirconia Oxygen Sensors Market
Ceramics
Global Ceramic and Porcelain Tiles Market
Ceramics
Japan Ceramic Tiles Market
Ceramics
East Africa Ceramic Tiles Market
Ceramics
Global Wollastonite Powder Market
Ceramics
Ceramic Proppant Market
Ceramics
Solid-Ion Conductors Market
Ceramics
Tetra-N-Butyl Titanate Market
Ceramics
Automotive Ceramics Market