
 Global Thermal Ceramics Market | 2026-2036
Global Thermal Ceramics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Thermal Ceramics Market Foresight
ISO 9001 and IATF 16949 qualification cycles are rotating supplier rosters in aerospace and automotive-adjacent thermal ceramics procurement. Morgan Advanced Materials leverages its vertically integrated fiber production network across Europe and North America to sustain long-term foundry contracts. RHI Magnesita anchors its position through captive magnesia sources and dense refractory know-how that extends into ceramic fiber-laminate hybrids. Unifrax competes aggressively on aluminosilicate wool formulations for chemical processing and power generation.
Thermal ceramics encompass engineered inorganic materials designed to withstand temperatures exceeding 1,000°C while providing thermal insulation, corrosion resistance, and dimensional stability in extreme environments. These materials typically feature porous microstructures with low thermal conductivity, measured in watts per meter-kelvin, to minimize heat loss in industrial furnaces, kilns, and reactors. Ceramic fibers dominate technology-level value capture due to their flexibility and lower installed mass versus insulating fire bricks. Refractory castables represent the fastest-growing technology segment as monolithic installation methods displace traditional bricklaying in metal processing and petrochemical turnarounds. Alumina and zirconia product types concentrate margin pools where high-purity requirements from glass manufacturing and aerospace applications command specification premiums.
EPA NESHAP standards for hazardous air pollutants and EU REACH chemical registration frameworks are tightening permissible fiber chemistries and mandating workplace exposure controls across US and European manufacturing bases. China's GB standards and MEE environmental enforcement are similarly elevating barrier-to-entry for domestic thermal ceramics producers serving steel and cement sectors. India's BIS certification requirements for refractory products used in critical infrastructure are expanding compliance scope for imported ceramic fiber systems. Stakeholders must monitor evolving carcinogenicity classifications for refractory ceramic fibers in multiple jurisdictions to anticipate product substitution timelines and reformulation investments.
Market Dynamics
Steel furnace relining cycles in emerging economies and EPA NESHAP enforcement are compressing specification timelines while elevating low-thermal-mass insulation procurement. Regulatory chemistry restrictions are forcing simultaneous product reformulation across three continents.
Growth Catalysts
- EU F-Gas Regulation:Phase-down mandates for fluorinated greenhouse gases are accelerating ceramic fiber substitution in industrial refrigeration and process heating equipment across German and Italian manufacturing bases.
- India steel capacity expansion:Government-backed furnace modernization programs under the PLI scheme are concentrating aluminosilicate wool demand in integrated steel plants across Odisha and Jharkhand.
- Refractory castable technology:Monolithic installation methods are displacing traditional bricklaying in petrochemical turnarounds, reducing turnaround duration and labor intensity for Gulf Coast US refiners.
Market Restraints
- Magnesite supply concentration:Captive ore access in China and limited alternative sourcing elevates input cost volatility for high-purity alumina-zirconia formulations.
- REACH registration friction:ECHA chemical dossier requirements for novel fiber chemistries extend product launch timelines by 18-24 months for European producers.
- Bio-soluble fiber substitution:Alternative low-biopersistence insulation materials are capturing specification share in HVAC and appliance applications where thermal severity permits.
Strategic Opportunities
- Indonesia nickel processing:HPAL (high-pressure acid leach) facility construction is creating virgin demand for acid-resistant ceramic fiber linings in Southeast Asian battery precursor supply chains.
- US IRA clean manufacturing credits:Section 45X advanced manufacturing production credits are incentivizing domestic thermal ceramics capacity for solar and semiconductor equipment supply chains.
- Aerospace thermal protection convergence:Ceramic matrix composite integration with fiber insulation is opening specification pathways in hypersonic vehicle development programs.
Industry Challenges
- IATF 16949 certification timelines:Automotive-adjacent thermal ceramics qualification cycles now span 36-48 months, locking supplier rosters and freezing out new entrants.
- Refractory ceramic fiber carcinogenicity reclassification:Evolving IARC and national toxicology assessments across France, Germany, and the US are forcing anticipatory reformulation investments ahead of definitive regulatory action.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Thermal Ceramics Market |
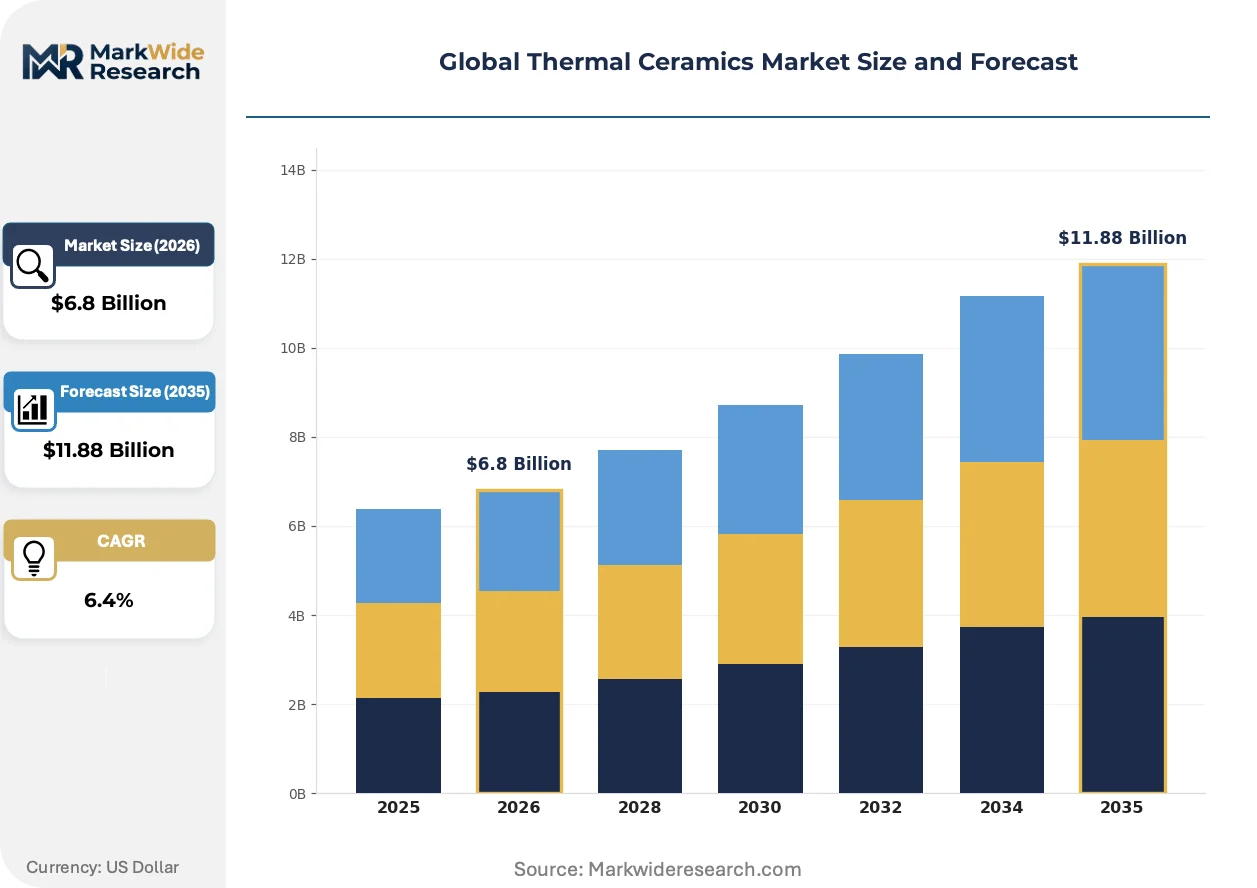
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.88 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Alumina, Silica, Mullite, Zirconia, Cordierite, Bauxite Technology: Refractory Castables, Ceramic Fibers, Insulating Fire Bricks, Rigid Insulation, Coating Solutions Application: Metal Processing, Glass Manufacturing, Chemical Processing, Power Generation, Petrochemical Plants, Aerospace End User: Foundries, Glassworks, Chemical Plants, Power Plants, Petrochemical Facilities, Aerospace Manufacturers |
| Companies Covered | Morgan Advanced Materials, 3M Company, CeramTec, RHI Magnesita, Unifrax, Ibiden Co., Ltd., Dyson Technical Ceramics, FibreCast Inc., Isolite Insulating Products Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Thermal Ceramics Market Shifts & Advancements
Product architectures are splitting between legacy dense refractory systems and engineered low-mass alternatives. Regulatory chemistry constraints and installation labor economics are the twin forces reshaping specification behavior across end-use verticals.
Ceramic fiber-laminate hybrid systems are bifurcating the thermal ceramics market into flexible mat solutions for cyclic furnace operation and rigid composite panels for static high-temperature barriers. Aerospace heat shield contractors and semiconductor diffusion furnace OEMs are adopting hybrid laminates at contrasting velocities. The technology is bifurcating margin pools between commodity fiber producers and specialized composite fabricators with in-house lamination capability.
EPA NESHAP standards for hazardous air pollutants are mandating workplace exposure controls and emissions monitoring at US ceramic fiber production facilities. The regulatory burden is elevating compliance costs for domestic manufacturers while creating specification preference for pre-certified imported systems. Metal processing and petrochemical end-users in Texas and Louisiana are consolidating procurement around suppliers with validated emissions data packages.
Specification authority is migrating from plant engineering departments to centralized corporate procurement functions with sustainability mandates. Long-term foundry contracts and steel mill maintenance agreements are being restructured around lifecycle carbon metrics rather than unit cost. This behavioral shift is most visible in German automotive supply chains and Nordic pulp-and-paper processing equipment procurement.
Global Thermal Ceramics Market Segmentation
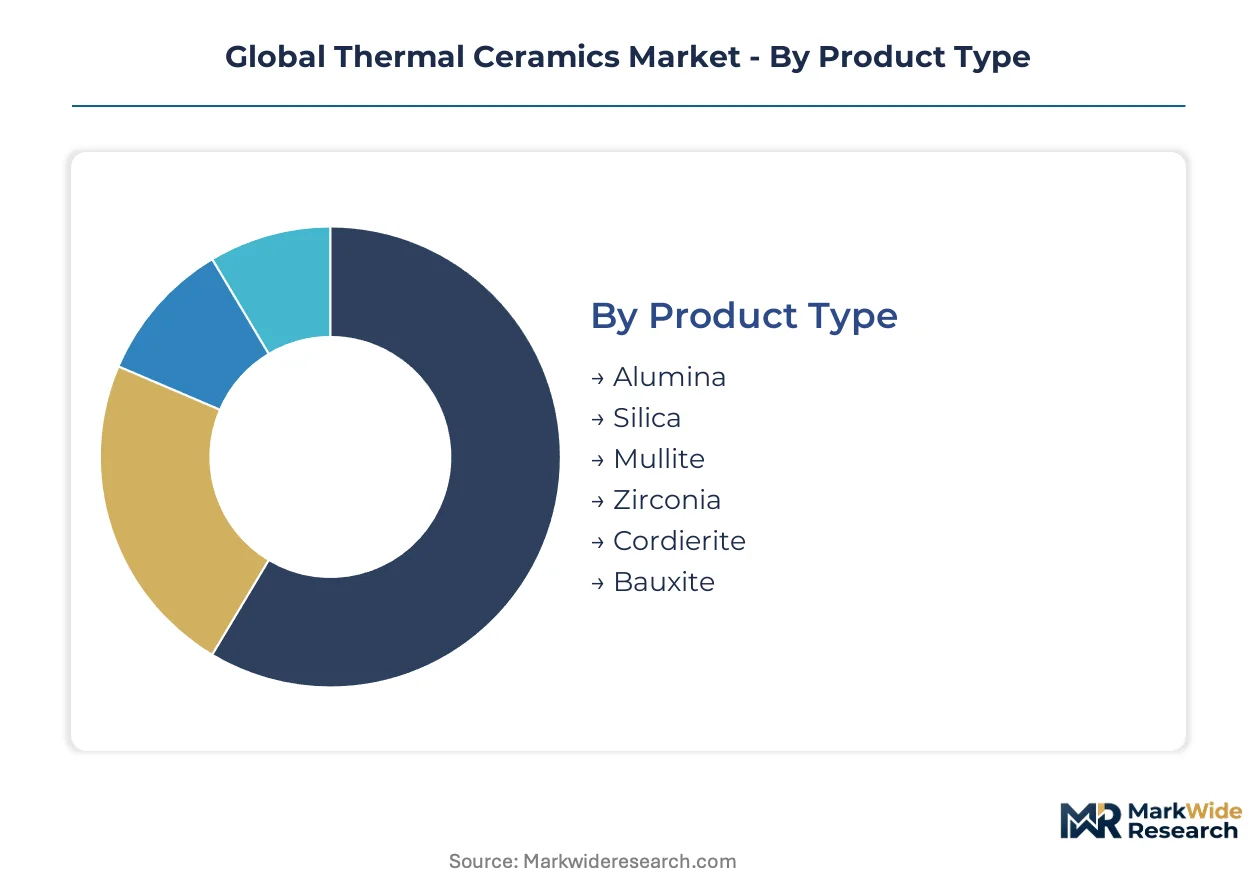
Thermal ceramics procurement splits sharply between specification-driven aerospace and automotive-adjacent buyers versus cost-sensitive steel and cement operators. Understanding where margin pools concentrate across product chemistry, installation technology, and end-use severity enables suppliers to align R&D with defendable revenue streams.
Product Type:
Domestic consumption dominates alumina and silica grades in China and India, while zirconia and high-purity alumina flow disproportionately to export markets serving German automotive glass and US semiconductor diffusion furnaces.
- Alumina:High-purity formulations command specification premiums in aerospace heat shields and semiconductor wafer processing equipment. Indian steel relining programs and Chinese cement kiln upgrades are concentrating mid-grade alumina demand in Asia.
- Silica:Lower thermal shock resistance restricts silica to static furnace applications below 1,200°C. German foundry operators and Italian ceramic tile manufacturers anchor European consumption despite gradual substitution by aluminosilicate wools.
- Mullite:Synthetic mullite serves kiln furniture and investment casting shells in Japanese precision foundries.
- Zirconia:Partially and fully stabilized zirconia enable thermal barrier coatings in jet engine hot sections; US and French aerospace contractors specify yttria-stabilized grades exclusively.
- Cordierite:Low thermal expansion suits automotive catalytic converter substrates and diesel particulate filters; Mexican and Thai auto parts exporters drive volume.
- Bauxite:Raw bauxite underpins Chinese refractory cement production; Guinean ore quality variations force blend optimization at Shandong processing facilities.
Alumina holds the largest share; momentum sits with zirconia as hypersonic thermal protection systems advance.
Technology:
Installation labor economics and turnaround duration requirements are bifurcating specification behavior between monolithic systems and pre-formed fiber products.
- Refractory Castables:Monolithic installation eliminates bricklaying labor and reduces petrochemical turnaround duration by 30-40%. Gulf Coast US refiners and Rotterdam chemical cluster operators are standardizing on low-cement and ultra-low-cement formulations.
- Ceramic Fibers:Flexible mat and blanket configurations enable rapid furnace relining in cyclic steel operations. Indian integrated steel plants under PLI-backed modernization are absorbing aluminosilicate wool volumes at unprecedented rates.
- Insulating Fire Bricks:Traditional bricklaying persists in legacy glass tank regenerators where dimensional stability over decades outweighs installation speed.
- Rigid Insulation:Pre-formed boards serve static barrier applications in aluminum melting furnaces and backup linings.
- Coating Solutions:Ceramic fiber-reinforced coatings extend refractory life in slag-line erosion zones; Brazilian and South African ferrochrome producers specify spray-applied zirconia-enriched layers.
Ceramic fibers capture the dominant revenue pool; refractory castables are climbing the fastest as petrochemical turnarounds accelerate globally.
Application:
Severity of thermal cycling and chemical exposure determines whether buyers prioritize fiber flexibility, castable monolithic integrity, or dense refractory durability.
- Metal Processing:Steel furnace relining cycles in India, Indonesia, and Vietnam concentrate demand for low-thermal-mass fiber systems. Electric arc furnace delta sections and ladle preheating stations specify ceramic fiber modules exclusively.
- Glass Manufacturing:Float glass tank crowns and regenerators require fused-cast AZS blocks and zirconia-mullite composites. German and Italian container glass producers are trialing fiber-module crown insulation to reduce heat loss.
- Chemical Processing:Sulfuric acid plant converters and ethylene cracking furnace linings specify acid-resistant castables. US Gulf Coast petrochemical expansions are absorbing high-alumina, low-silica formulations.
- Power Generation:Combined cycle turbine exhaust ducts and HRSG insulation specify biosoluble fiber blankets where regulatory pressure permits.
- Petrochemical Plants:Fluid catalytic cracker regenerators and reactor vessels require erosion-resistant castable linings with stainless steel fiber reinforcement.
- Aerospace:Hypersonic vehicle leading edges and rocket nozzle extensions drive ceramic matrix composite integration with fibrous insulation; US defense contractors and French launch vehicle suppliers co-develop specifications.
Metal processing commands the largest application share; aerospace is gaining share fastest as thermal protection system budgets expand.
End User:
Procurement centralization varies dramatically: foundries and glassworks retain plant-level specification authority while petrochemical and aerospace buyers consolidate at corporate engineering centers.
- Foundries:Investment casting shell manufacturers and ferrous foundry operators in Ohio, Michigan, and Stuttgart industrial clusters specify fused silica and zircon-based slurries.
- Glassworks:Container, flat, and specialty glass producers in Murano, Toledo, and Guangdong balance refractory life against thermal efficiency in 15-20 year tank campaigns.
- Chemical Plants:BASF Ludwigshafen and Dow Texas Operations centralize refractory procurement through global engineering standards.
- Power Plants:Indian NTPC and Chinese Huaneng specify insulation packages through centralized technical committees.
- Petrochemical Facilities:ExxonMobil Baytown and Shell Pernis enforce corporate refractory qualification lists that freeze out unapproved suppliers.
- Aerospace Manufacturers:Boeing, Airbus, and their tier-one heat shield contractors qualify thermal protection systems through 36-48 month IATF 16949-aligned cycles.
Foundries represent the broadest end-user base; aerospace manufacturers concentrate the highest value per kilogram despite smaller volumes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
IRA clean manufacturing credits and India's PLI scheme are redirecting capital toward domestic thermal ceramics capacity. Steel furnace modernization and semiconductor diffusion furnace demand are concentrating procurement in specific industrial clusters across four major economies.
United States
Section 45X production credits are incentivizing thermal ceramics capacity for solar and semiconductor equipment supply chains. EPA NESHAP enforcement mandates workplace exposure controls at ceramic fiber production facilities. Texas and Louisiana petrochemical clusters are consolidating procurement around suppliers with validated emissions data packages.
China
GB standards and MEE environmental enforcement are elevating barrier-to-entry for domestic producers serving steel and cement sectors. Dual carbon goals are accelerating substitution of dense refractory systems with low-thermal-mass alternatives. Shandong processing facilities are optimizing blend formulations to manage Guinean bauxite quality variations.
Germany
EU F-Gas Regulation phase-down mandates are accelerating ceramic fiber substitution in industrial refrigeration equipment. REACH registration requirements extend product launch timelines for novel fiber chemistries. Stuttgart and Ludwigshafen industrial clusters anchor automotive-adjacent and chemical processing demand respectively.
India
PLI scheme furnace modernization programs are concentrating aluminosilicate wool demand in integrated steel plants. BIS certification requirements for refractory products used in critical infrastructure are expanding compliance scope for imported systems. Odisha and Jharkhand steel corridors are absorbing ceramic fiber volumes at unprecedented rates.
Global Thermal Ceramics Market Competitive Landscape
Player mix skews toward vertically integrated material specialists and regional formulation houses. The vendor base separates into three tiers: global multi-product conglomerates with captive raw material access, mid-scale specialists with lamination or coating capabilities, and regional castable producers serving single-country steel and cement markets. Dominant competitive moves include backward integration into magnesia and alumina sourcing, and technology licensing partnerships to bypass REACH registration friction.
Within the integrated-materials tier, Morgan Advanced Materials and RHI Magnesita exemplify archetypes built on captive fiber production networks and dense refractory know-how respectively. Unifrax occupies a position among North American formulation specialists competing on aluminosilicate wool chemistries. These three represent the strategic poles around which mid-scale competitors and regional players orbit.
| Leading Market Players |
|---|
| Morgan Advanced Materials |
| 3M Company |
| CeramTec |
| RHI Magnesita |
| Unifrax |
| Ibiden Co., Ltd. |
| Dyson Technical Ceramics |
| FibreCast Inc. |
| Isolite Insulating Products Co., Ltd. |
| Others |
Supply & Pricing Matrix
EU REACH registration dossiers gate both European market entry and price tier qualification simultaneously, compressing product launch timelines while elevating compliance costs that suppliers recover through specification premiums on certified fiber chemistries.
Pricing Analysis
Certification level (ISO 9001/IATF 16949/CE-marked) creates the primary spread across three-tier pricing structure across premium, standard, and economy levels. Premium tiers command specification premiums in aerospace heat shields and semiconductor diffusion furnaces where IATF 16949 alignment spans 36-48 month qualification cycles. Standard grades serve Indian steel relining and Chinese cement kiln upgrades where volume procurement compresses margins. Price differentiation stems from captive magnesia sourcing versus merchant alumina dependence, with cost compression in mid-grade alumina-silica formulations intensifying because Guinean bauxite quality variations force blend optimization overhead. Foundry operators in Ohio and Stuttgart industrial clusters exhibit highest price sensitivity on commodity ceramic fibers, while Boeing and Airbus tier-one contractors demonstrate lowest sensitivity on qualified thermal protection systems.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes and Red Sea routing disruptions are elevating inbound logistics costs for European ceramic fiber processors dependent on Chinese magnesia and Guinean bauxite intermediates. Raw material supply concentrates in China for magnesia and alumina, Guinea for bauxite ore, and Australia for high-purity zirconia sands. Manufacturing output feeds from Shandong processing clusters, RHI Magnesita's Austrian captive magnesia operations, and Morgan Advanced Materials' vertically integrated European fiber production network. Single-source vulnerability concentrates in Chinese magnesia where captive ore access limits alternative sourcing for high-purity alumina-zirconia formulations. Distribution runs through authorized refractory distributors serving Texas and Louisiana petrochemical clusters, direct mill supply contracts for Indian PLI-scheme steel plants, and OEM qualification channels for aerospace heat shield contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as specification authority migrates from plant engineering to centralized corporate procurement with sustainability mandates, creating niche openings for certified low-carbon fiber suppliers and regional castable formulators.
For Market Incumbents: Consolidate long-term foundry contracts through lifecycle carbon metric restructuring rather than unit cost competition, defending against bio-soluble fiber substitution in HVAC and appliance applications. Deepen backward integration into Guinean bauxite blending optimization and Austrian magnesia captive supply to buffer input cost volatility from ore quality variations. Add ceramic fiber-laminate hybrid capacity in Texas and Louisiana corridors where EPA NESHAP enforcement concentrates procurement around validated emissions data packages.
For New Entrants and Emerging Players: Technical service gaps in rapid furnace relining for Indian PLI-scheme steel plants present white-space entry points where incumbent response times lag 24-48 hour turnaround requirements. Target Indonesian HPAL nickel processing facilities for acid-resistant ceramic fiber linings where virgin demand lacks established supplier relationships. Penetrate through coating solutions partnerships with Brazilian and South African ferrochrome producers specifying spray-applied zirconia-enriched layers for slag-line erosion zones.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional castable producers serving single-country steel and cement markets in Southeast Asia and Eastern Europe. Long-term viability over the next decade hinges on REACH registration completion and IATF 16949 qualification pipeline depth rather than commodity volume scale. Watch for IARC refractory ceramic fiber carcinogenicity reclassification announcements across France, Germany, and the US as inflection indicators forcing anticipatory reformulation investments and supplier roster disruption.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Magnesia Sourcing | Captive ore access in Austria and China buffers RHI Magnesita against Guinean bauxite volatility. |
| Ceramic Fiber-Laminate Hybrid Capacity Expansion | Morgan Advanced Materials serves Boeing and Airbus hypersonic thermal protection convergence programs. |
| REACH Registration Completion for Novel Chemistries | ECHA dossier approval unlocks 18-24 month product launch timelines for European fiber producers. |
| Long-term Supply Agreement with Indian PLI Steel Plants | Odisha and Jharkhand corridors absorb aluminosilicate wool volumes at unprecedented qualification rates. |
| Emissions Data Package Certification for US Gulf Coast | EPA NESHAP compliance enables ExxonMobil Baytown and Shell Pernis procurement list inclusion. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with steel mill maintenance directors, petrochemical turnaround managers, aerospace heat shield procurement leads, and ceramic fiber plant engineers. Secondary validation drew from SEC 10-K filings of listed refractory producers, ECHA REACH registration databases, Indian BIS certification records, and customs trade data tracking magnesia and alumina cross-border flows. Bottom-up volume estimates from end-use consumption patterns were triangulated against top-down capacity assessments from major production clusters.
Across the analysis window, projections integrated product type segmentation by alumina, zirconia, and silica grades; technology splits between ceramic fibers, refractory castables, and insulating fire bricks; and application dimensions spanning metal processing, aerospace, and petrochemical end-uses. CAGRs were derived from regression analysis of historical capacity expansion announcements and steel furnace relining cycle data. Industry-specific inputs included PLI scheme disbursement schedules for Indian steel modernization and Section 45X credit qualification timelines for US solar equipment supply chains.
Underlying assumptions cover sustained EPA NESHAP enforcement stringency, EU F-Gas Regulation phase-down adherence, and Indian BIS certification scope expansion, with deviation risk concentrated in IARC carcinogenicity reclassification timing and magnesia supply disruption from Chinese environmental enforcement actions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Dielectric Ceramics Market
Ceramics
Calcium Oxide Market
Ceramics
Global Industrial Clay Market
Ceramics
Asia-Pacific Ceramic Coatings Market
Ceramics
Ceramic Proppant Market
Ceramics
United States Ceramics Tableware Market
Ceramics
Cerium Carbonate Market
Ceramics
Calcined Kaolin Market
Ceramics
Taiwan Ceramic Tiles Market
Ceramics
US Kaolin Market
Ceramics
Tetramethyl Orthosilicate Market
Ceramics
Aluminium Nitride Market
Ceramics
West Africa Ceramic Tiles Market
Ceramics
Cerium Nitride Market
Ceramics
Polymer-Derived Ceramics Market
Ceramics
Pyrolytic Boron Nitride Market