
 US Kaolin Market | 2026-2036
US Kaolin Market Size, Share, and Industry Trends Forecast 2026-2036
US Kaolin Market Insights
Subscription-based technical support and predictive maintenance contracts for calcination kiln operations is shifting how kaolin processors monetize customer relationships beyond raw material sales. KaMin LLC leverages vertical integration from mine to refined product to sustain margin capture across the value chain. Thiele Kaolin Company anchors its competitive position through deep specialization in delaminated grades for high-gloss paper coating applications. Active Minerals International competes on geographic reach, operating multiple processing facilities that reduce freight costs for Eastern and Midwestern buyers.
Kaolin is a hydrated aluminum silicate clay mineral with a theoretical composition of approximately 46 percent silica, 40 percent alumina, and 14 percent water, formed through the hydrothermal alteration or weathering of feldspathic rocks; its platy particle structure and controlled particle size distribution deliver functional properties including brightness, opacity, and rheological modification in industrial formulations. The mineral primarily serves as a functional extender and performance additive across paper, paint, rubber, and ceramic manufacturing processes. Calcined kaolin commands premium positioning in paints and coatings applications where high brightness and opacity replacement for titanium dioxide create concentrated margin pools. Delaminated kaolin leads paper coating segments due to superior gloss and printability performance, while natural kaolin retains volume dominance in lower-specification ceramic body and rubber filler applications where cost efficiency outweighs performance optimization.
EPA enforcement of National Ambient Air Quality Standards constrains calciner emissions, pushing processors toward natural gas conversion and particulate capture investments that raise operational costs but create compliance barriers for smaller competitors. OSHA silica exposure limits under the Respirable Crystalline Silica standard shape workplace controls and product handling specifications throughout mining and processing operations. Georgia Environmental Protection Division mining permits and reclamation requirements govern extraction timelines and land-use commitments that influence reserve access and long-term supply planning. Stakeholders must monitor evolving state-level carbon accounting rules and federal infrastructure procurement standards that could redirect demand toward domestically sourced, lower-carbon-intensity clay grades.
Market Dynamics
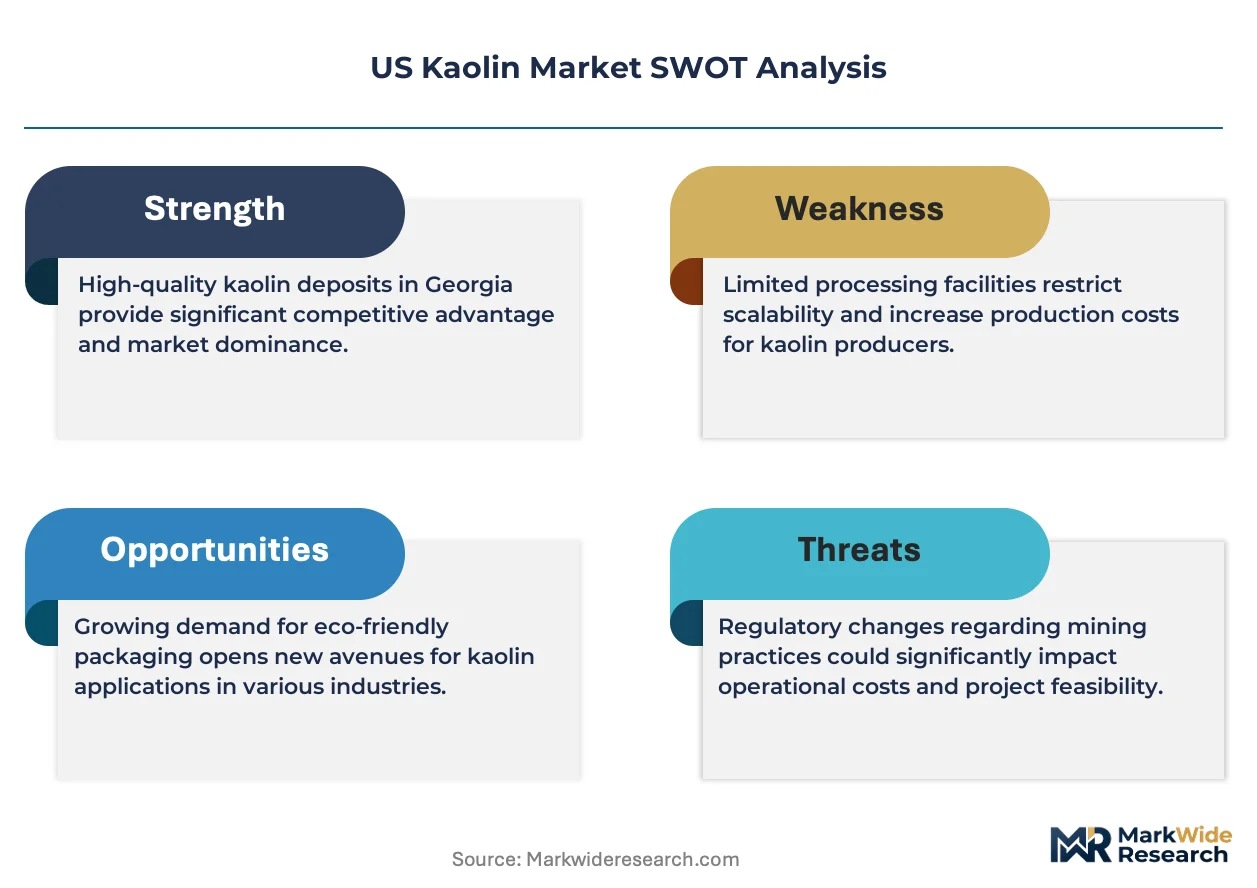
EPA enforcement of National Ambient Air Quality Standards is compressing calciner capacity and forcing natural gas conversion investments, tightening supply availability for high-brightness grades while elevating compliance costs for smaller processors.
Growth Catalysts
- Paint Formulation Evolution:Architectural coatings manufacturers are expanding titanium dioxide extension programs using calcined kaolin to manage raw material costs in decorative paints.
- OSHA Silica Standards:Workplace exposure controls under the Respirable Crystalline Silica standard are accelerating mechanized handling system upgrades that improve processing consistency.
- Georgia Mining District Concentration:Sandersville-Washington County hosts over half of domestic reserves, creating infrastructure density that reduces extraction logistics costs for regional processors.
Market Restraints
- Natural Gas Price Volatility:Calcination kiln operations depend on natural gas feedstock, exposing processors to energy cost swings that compress margin stability.
- Georgia Reserve Concentration:Domestic supply concentrates in a single mining district, creating geographic vulnerability to localized weather disruptions or permitting delays.
- Calcined Product Premium Compression:High-brightness grades face substitution pressure from precipitated calcium carbonate in select coating applications where opacity requirements moderate.
Strategic Opportunities
- Texas Shale Basin Expansion:Oilfield drilling fluid demand in Permian Basin operations represents an underpenetrated geography for specialty kaolin grades.
- Infrastructure Procurement Standards:Federal Buy America provisions in infrastructure spending create preference tailwinds for domestically sourced clay in ceramic and construction applications.
- Predictive Maintenance Contracts:Kiln telemetry integration with IoT sensors enables subscription-based technical support models that extend customer lifetime value beyond commodity sales.
Industry Challenges
- Calciner Emissions Compliance:EPA Clean Air Act enforcement demands particulate capture retrofits that strain capital allocation for mid-scale processors with aging equipment.
- Reclamation Bond Requirements:Georgia Environmental Protection Division mining permits impose long-term land-use commitments that complicate reserve valuation and financing structures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Kaolin Market |
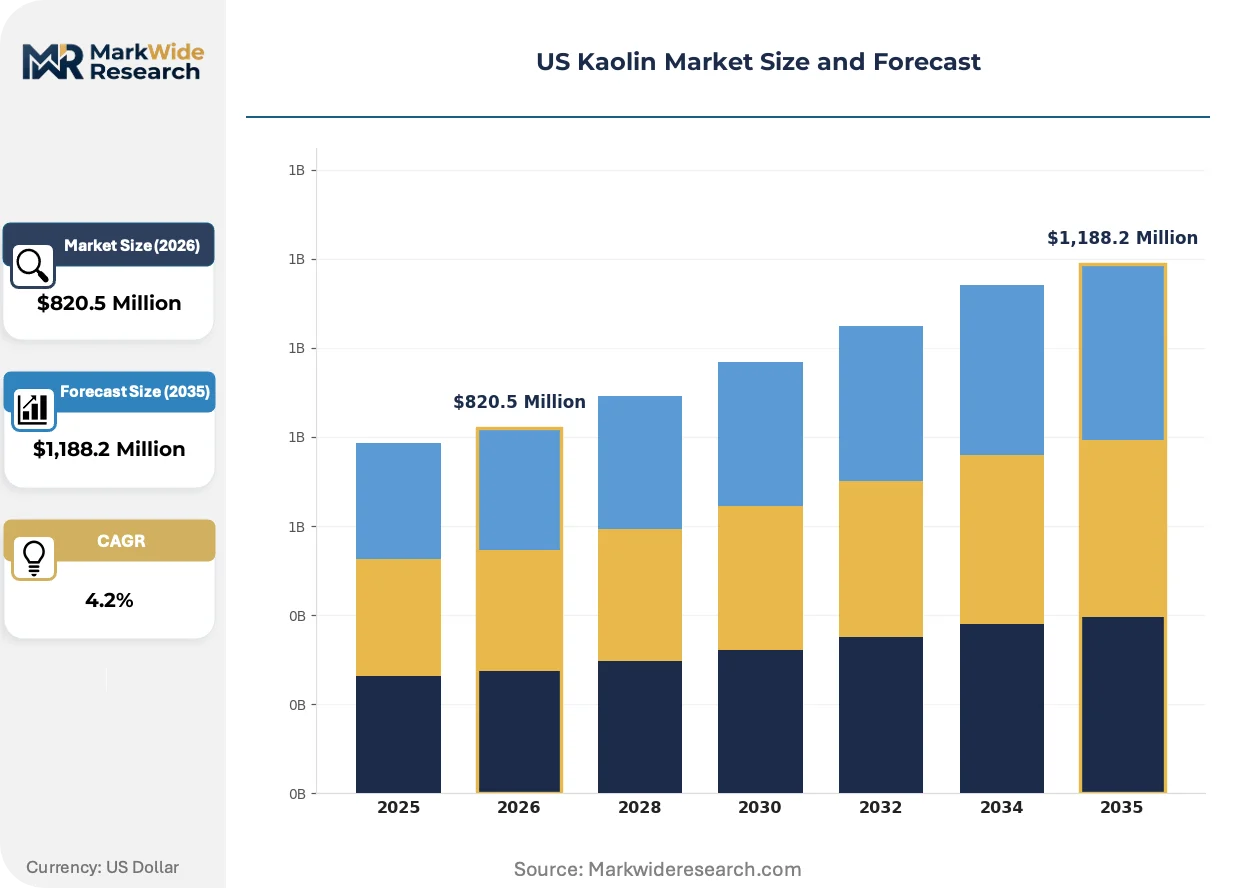
| Market Size in 2026 | $820.5 Million |
| Market Size in 2035 | $1,188.2 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Calcined Kaolin, Delaminated Kaolin, Coated Kaolin, Natural Kaolin Application: Paper Coating, Paints & Coatings, Rubber Fillers, Ceramics, Adhesives & Sealants End User Industry: Pulp & Paper Mills, Paint Manufacturers, Rubber Industry, Ceramic Production Units, Sealant Producers Packaging Type: Bulk Bags, Paper Bags, Flexible Intermediate Bulk Containers, Poly Bags |
| Companies Covered | KaMin LLC, Thiele Kaolin Company, Active Minerals International, Imerys S.A., Sibelco, R.T. Vanderbilt Holding Company, W. R. Grace & Co., KaMin LLC/CADAM, BASF SE, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Kaolin Market Trends and Innovations
Digital kiln monitoring and emissions control technologies are restructuring how kaolin processors compete, shifting advantage toward operators with capital depth for compliance infrastructure and data-driven process optimization.
Flash calcination systems are overtaking traditional rotary kiln designs in new capacity installations. Paint and coatings manufacturers adopting flash-calcined grades report improved particle morphology consistency. This thermal processing shift is overtaking legacy equipment investments and compressing the viable scale threshold for market entry.
EPA enforcement of National Ambient Air Quality Standards is tightening allowable particulate emissions from calcination operations. Processors are retrofitting baghouse systems and converting fuel sources to meet compliance deadlines. Georgia-based calciners face the most concentrated enforcement pressure and are accelerating natural gas burner upgrades ahead of inspection cycles.
Technical service unbundling is fragmenting traditional supply relationships. Paper mills and coatings formulators now contract predictive maintenance and formulation support separately from material procurement. This service model decomposition is most visible in the Southeast, where KaMin LLC and Thiele Kaolin Company compete on kiln telemetry integration and laboratory support responsiveness rather than tonnage pricing alone.
US Kaolin Market Segmentation
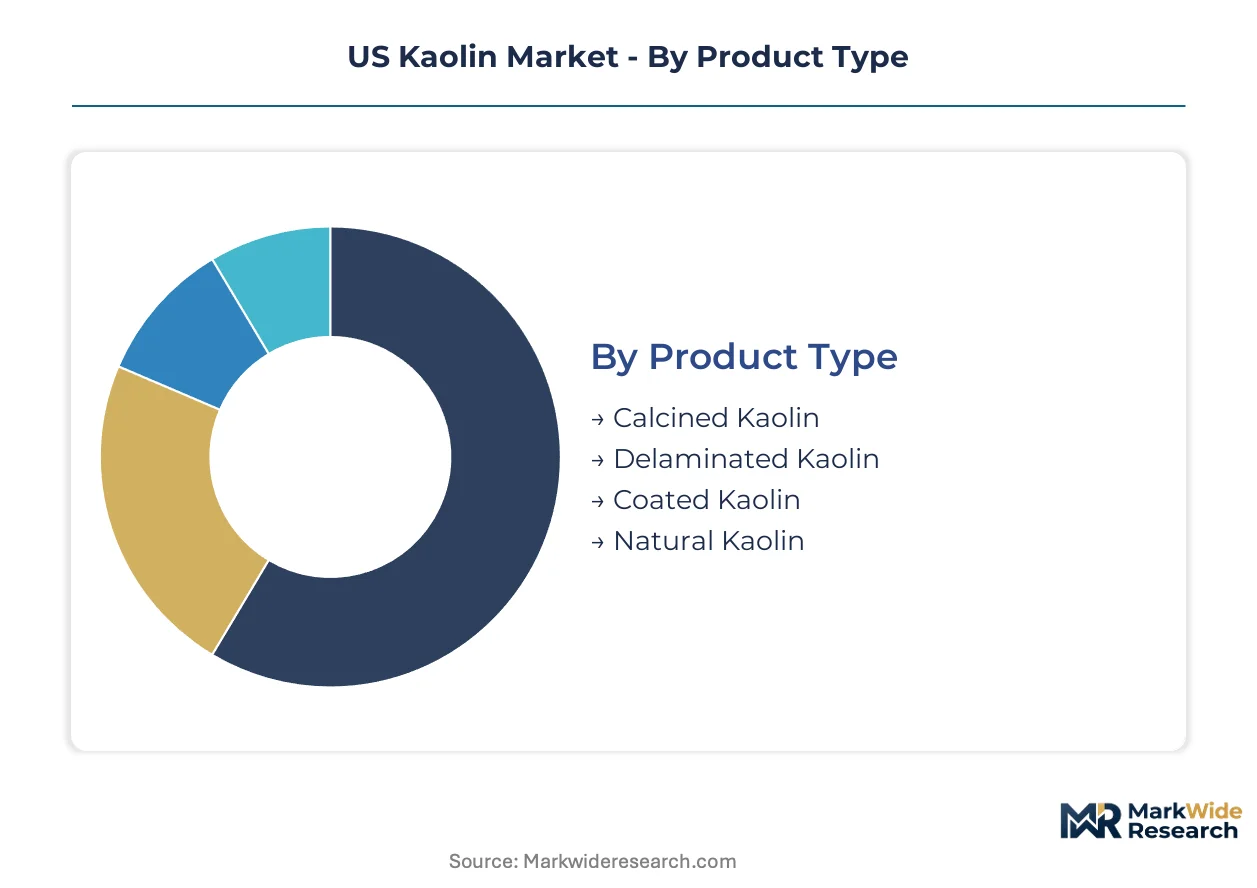
Kaolin processors configure production assets around thermal treatment intensity and particle engineering requirements. Segment boundaries reflect capital deployment patterns and margin capture potential across distinct value chain positions.
Product Type:
Calcination infrastructure demands the heaviest capital commitment, with rotary and flash kiln systems requiring sustained investment in emissions control and fuel conversion.
- Calcined Kaolin:High-temperature thermal treatment drives off structural water to create metakaolin with elevated brightness and opacity. Paint manufacturers in the Southeast deploy this grade for titanium dioxide extension in architectural coatings facing EPA emission compliance pressures.
- Delaminated Kaolin:Mechanical shearing separates stacked platelets to enhance aspect ratio and gloss properties. Specialty paper mills in the Carolinas specify this grade for high-gloss publication papers where printability performance commands formulation priority.
- Coated Kaolin:Surface modification with organic or inorganic treatments improves dispersibility and compatibility with polymer matrices. Functional filler applications in adhesives and sealants drive modest volume uptake.
- Natural Kaolin:Air-floated or water-washed grades without thermal processing serve cost-sensitive ceramic body and rubber filler markets. Georgia's Sandersville-Washington County mining district supplies the bulk of this uncalcined volume.
Natural kaolin absorbs the bulk of installed capacity; calcined kaolin is expanding most quickly.
Application:
Formulation sophistication and performance specifications determine pricing power across end-use categories.
- Paper Coating:Delaminated and fine-particle hydrous grades deliver gloss, opacity, and ink receptivity for coated publication and packaging papers. Integrated pulp and paper mills in the Southeast maintain captive blending operations for coating color preparation.
- Paints & Coatings:Calcined grades provide titanium dioxide extension and sheen control in decorative and industrial formulations. Architectural coatings producers facing raw material cost pressure are accelerating kaolin adoption as a functional extender.
- Rubber Fillers:Hard and soft clay grades reinforce elastomer compounds and improve processing characteristics. Tire manufacturers and rubber goods producers specify controlled particle size for tensile strength optimization.
- Ceramics:Plastic kaolins with controlled rheology shape whiteware, sanitaryware, and electrical porcelain bodies. Domestic ceramic tile and sanitaryware producers source from Georgia deposits for body formulation consistency.
- Adhesives & Sealants:Surface-modified grades enhance viscosity control and reinforcement in construction and industrial sealant systems. Formulators value low moisture content and controlled particle distribution.
Paper coating commands the deepest volume base; paints and coatings applications are climbing the fastest.
End User Industry:
Procurement scale and technical service requirements segment the customer base by integration depth and specification complexity.
- Pulp & Paper Mills:Integrated producers with captive coating facilities purchase bulk hydrous and delaminated grades under long-term supply agreements. Technical service demands center on coating color rheology and runnability support.
- Paint Manufacturers:Regional and national coatings formulators source calcined grades for titanium dioxide replacement programs. Formulation support and quality consistency outweigh tonnage pricing in supplier selection.
- Rubber Industry:Tire producers and industrial rubber goods manufacturers specify kaolin for reinforcement and processing aids. Compound consistency and low grit content drive qualification protocols.
- Ceramic Production Units:Whiteware, sanitaryware, and electrical porcelain producers depend on plastic kaolin for body plasticity and fired strength. Body formulation stability requires consistent mineralogy and particle size distribution.
- Sealant Producers:Construction and industrial sealant formulators employ surface-modified grades for viscosity control and reinforcement. Low moisture and controlled oil absorption specifications dominate procurement criteria.
Pulp and paper mills anchor the largest procurement volumes; paint manufacturers are gaining share fastest.
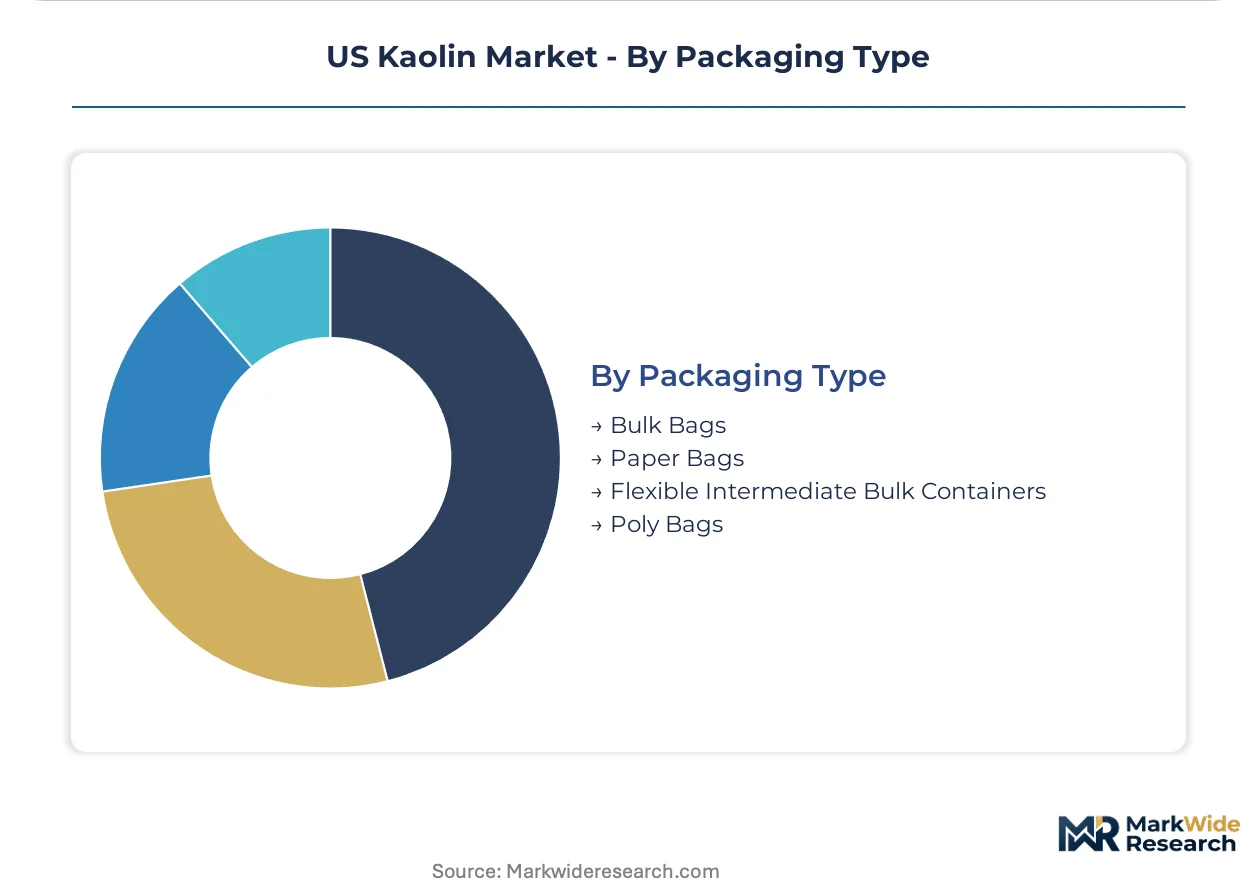
Packaging Type:
Logistics economics and handling automation shape packaging selection across customer scale and geographic dispersion.
- Bulk Bags:One-ton flexible intermediate bulk containers serve high-volume paper mill and coatings plant deliveries. Rail and truck bulk handling infrastructure supports this format for integrated producers.
- Paper Bags:Multi-wall paper packaging remains standard for mid-volume ceramic and rubber industry shipments. Recyclability and handling familiarity sustain this format despite moisture sensitivity limitations.
- Flexible Intermediate Bulk Containers:Woven polypropylene FIBCs with discharge spouts accommodate automated handling systems at large manufacturing facilities. Reusability and stacking efficiency improve logistics economics for regional distributors.
- Poly Bags:Polyethylene packaging protects moisture-sensitive calcined grades and specialty surface-modified products. Sealant producers and smaller formulators favor this format for warehouse stability and contamination control.
Bulk bags carry the majority of tonnage movements; flexible intermediate bulk containers are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Georgia produces the bulk of domestic kaolin while consuming regions spread across paper mills in the Carolinas and paint manufacturers in the Midwest. This production-consumption gap shapes logistics economics and regional pricing differentials throughout the value chain.
Southeast (Georgia Core)
Sandersville-Washington County hosts over half of US kaolin reserves with dense mining and calcination infrastructure. EPA Clean Air Act enforcement targets Georgia calciners with particulate capture retrofits and natural gas conversion deadlines. Sandersville processors face concentrated compliance pressure while maintaining supply to regional paper coating operations.
Carolinas Paper Belt
Integrated pulp and paper mills in North and South Carolina drive delaminated grade consumption for high-gloss publication papers. OSHA Respirable Crystalline Silica standards accelerate mechanized handling investments at mill receiving facilities. Charlotte-Greensboro corridor facilities source coating clays under long-term supply agreements tied to runnability performance.
Midwest Manufacturing
Ohio and Illinois anchor rubber filler and ceramic body demand from tire producers and whiteware manufacturers. Infrastructure procurement standards under federal Buy America provisions create preference tailwinds for domestically sourced clay in construction ceramics. Cleveland-Chicago industrial corridor distributors maintain bulk handling infrastructure for cost-sensitive natural grade shipments.
Southwest Oilfield Corridor
Texas Permian Basin drilling operations represent underpenetrated demand for specialty kaolin grades in oilfield drilling fluids. Railroad Commission of Texas permitting governs extraction logistics for regional mineral suppliers. Midland-Odessa service companies evaluate domestic clay alternatives to imported barite for density control applications.
West Coast Construction
California ceramic tile and sanitaryware producers source plastic kaolins for body formulation consistency under state-level carbon accounting rules. California Air Resources Board emission standards influence supplier selection toward lower-carbon-intensity transportation modes. Los Angeles-Long Beach port complex handles limited import volumes for specialty surface-modified grades.
US Kaolin Market Competitive Landscape
Top-tier vendors anchor calcination and delamination infrastructure, while mid-scale processors compete on geographic reach and service bundling. The vendor base stratifies around capital depth for emissions compliance and kiln telemetry integration. Three archetypes dominate: vertically integrated mine-to-refinery operators, specialty grade specialists, and multi-site distributors. Competitive moves concentrate on flash calcination capacity additions and predictive maintenance contract expansion.
Among Georgia-based integrated processors, KaMin LLC and Thiele Kaolin Company occupy positions exemplifying vertical control from extraction through refined product. Active Minerals International represents the geographic diversification archetype with multiple processing facilities reducing freight costs for Eastern and Midwestern buyers. These three entities anchor the competitive structure through distinct strategic postures rather than overlapping capability investments.
| Leading Market Players |
|---|
| KaMin LLC |
| Thiele Kaolin Company |
| Active Minerals International |
| Imerys S.A. |
| Sibelco |
| R.T. Vanderbilt Holding Company |
| W. R. Grace & Co. |
| KaMin LLC/CADAM |
| BASF SE |
| Others |
Pricing and Supply Chain Analysis
Family-owned mining operations concentrated in Georgia's Sandersville-Washington County district anchor supply discipline through long-term reserve stewardship and limited spot-market participation, insulating contract pricing from commodity volatility while constraining rapid capacity response to demand surges.
Pricing Analysis
Cost-down pressure on calcined grades accelerates because EPA-mandated natural gas conversion and baghouse retrofits compress processor margins without full pass-through to buyers. Three-tier pricing structure across premium calcined, standard delaminated, and economy natural grades segments the market by brightness specification and thermal processing intensity. Paint manufacturers exhibit highest price sensitivity as titanium dioxide extension programs prioritize cost management over performance optimization. Paper mills show lowest sensitivity, accepting premium positioning for runnability guarantees and coating color technical support.
Supply Chain Analysis
Natural gas supply rests on Appalachian basin pipeline infrastructure and Henry Hub pricing benchmarks that expose calcination operations to regional energy cost swings. Georgia's Sandersville-Washington County mining district hosts over half of domestic reserves, with supplemental draw from South Carolina's Aiken County deposits for specialty ceramic grades. Single-district concentration creates weather disruption vulnerability and permitting delay exposure that extends lead times unpredictably. Distribution runs through unit-train rail shipments to Southeast paper mills and bulk truck deliveries to Midwest rubber and ceramic processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Calciner capacity constraints under EPA Clean Air Act enforcement prop pricing power for compliant operators, creating supply-constrained conditions that favor incumbents with emissions control infrastructure already deployed.
For Market Incumbents: Deepen backward integration into captive natural gas procurement or long-term pipeline capacity reservations to isolate margin stability from Henry Hub volatility. Accelerate flash calcination capacity additions ahead of rotary kiln obsolescence to capture premium positioning from improved particle morphology consistency. Defend against precipitated calcium carbonate substitution in coating applications by embedding formulation technical service into long-term supply agreements. For New Entrants and Emerging Players: Regional distributors with established rail siding access and bulk handling infrastructure offer the lowest-friction partnership pathway to penetrate the Texas Permian Basin drilling fluids segment. Target oilfield service companies seeking domestic barite alternatives for density control applications where supply security outweighs performance optimization. Lead with logistics cost advantage rather than product differentiation to displace imported specialty clay grades. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale Georgia calciners facing EPA compliance capital demands beyond their balance sheet capacity, particularly those with permitted reserves and existing rail infrastructure. Long-term viability hinges on flash calcination technology migration and predictive maintenance service revenue streams extending customer lifetime value beyond commodity margins. Monitor Railroad Commission of Texas permitting activity for Permian Basin extraction logistics as inflection indicator for regional demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Flash Calcination Capacity Expansion | Flash kiln systems deliver superior particle morphology consistency that commands premium positioning in titanium dioxide extension programs. |
| Predictive Maintenance Service Contracts | Kiln telemetry integration with IoT sensors enables subscription revenue streams extending customer lifetime value beyond tonnage sales. |
| Natural Gas Fuel Conversion | EPA Clean Air Act compliance deadlines force burner upgrades that create regulatory barriers for capital-constrained competitors. |
| Permian Basin Distribution Partnership | Midland-Odessa oilfield service relationships unlock underpenetrated drilling fluids demand with domestic supply security advantages. |
| Reserve Positioning and Permitting | Georgia Environmental Protection Division mining permits with secured reclamation bonds protect long-term supply planning against regulatory disruption. |
Research Methodology
Multi-period observation of calcination capacity utilization rates, EPA enforcement action patterns, and coating color formulation trends anchored the trend analysis, supplemented by interviews with plant managers at Georgia-based processors, procurement leads at Southeast paper mills, technical directors at architectural coatings formulators, and distribution channel partners serving the Midwest ceramic industry. Secondary validation drew from EPA enforcement and compliance databases, SEC filings of publicly traded mineral processors, Georgia Environmental Protection Division mining permit records, and American Coatings Association formulation trend reports. Bottom-up volume estimates by grade tier and application triangulated against top-down industry value chain analysis.
Segment-weighting approaches modeled product type splits across calcined, delaminated, coated, and natural grades alongside application dimensions spanning paper coating, paints and coatings, rubber fillers, ceramics, and adhesives and sealants. End-use industry segmentation captured pulp and paper mills, paint manufacturers, rubber compounders, ceramic production units, and sealant formulators. CAGRs were derived from regression analysis of historical volume movements applied to projected capacity expansion timelines and regulatory constraint scenarios. Forecast inputs incorporated natural gas price trajectory assumptions and EPA compliance deadline schedules.
Caveats apply where Railroad Commission of Texas permitting delays, Georgia Environmental Protection Division reclamation bond requirement changes, or precipitated calcium carbonate substitution acceleration could materially shift the outlook. Forecasts reflect assumptions about flash calcination adoption rates and EPA enforcement consistency that may revise with regulatory priority shifts. A small set of triggers—Permian Basin drilling activity inflection, Georgia mining permit moratoria, and natural gas infrastructure investment delays—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Cerium Nitride Market
Ceramics
India Kaolin Market
Ceramics
North America Activated Alumina Market
Ceramics
Global High Performance Ceramic Coatings Market
Ceramics
Germany Ceramic Tiles Market
Ceramics
Hot-Pressed Aluminum Titanate Ceramics Market
Ceramics
Global Functional Ceramics Market
Ceramics
Europe Ceramic Coatings Market
Ceramics
Global Thermal Ceramics Market
Ceramics
Transparent Ceramics Market
Ceramics
Calcined Kaolin Market
Ceramics
Ceramic Armor Materials Market
Ceramics
Calcium Silicate Market
Ceramics
Magnesia Carbon Bricks Market
Ceramics
Global Ceramic Foams Market
Ceramics
Ceramic Ware Market