
 Calcite Market | 2026-2036
Calcite Market Size, Share, and Industry Trends Forecast 2026-2036
Calcite Market Analysis
The direct-to-mill supply channel for ground calcite is narrowing as producers consolidate logistics networks. Imerys S.A. leverages its captive quarry network across France and Belgium to control raw material flows. Omya AG sustains a technical-service-led model that locks in paint and coatings formulators with customized slurry grades. Minerals Technologies Inc. competes through precipitated calcium carbonate specialization for paper and plastics substitution.
Calcite is calcium carbonate mineral with Mohs hardness of three and trigonal crystalline structure, primarily extracted through open-pit mining or precipitated from brine solutions for industrial filler and extender applications. Ground calcite dominates volume flows into construction and paints, where cost efficiency and particle size distribution determine specification adherence. Precipitated calcium carbonate commands premium positioning in plastics and high-performance coatings due to controlled morphology and brightness indices. Powder form leads shipment volumes, though slurry concentrates margin pools in water-based coatings systems where dispersion quality reduces downstream processing costs.
EPA regulations in the United States govern air emissions from calcite processing facilities, while REACH in Europe mandates registration and hazard communication for calcium carbonate variants used in consumer applications. OSHA workplace exposure limits for respirable crystalline silica intersect with calcite mining operations, shaping dust control investments and product classification protocols. Stakeholders must track evolving purity standards in construction applications as green building certifications tighten material disclosure requirements across multiple jurisdictions.
Market Dynamics
Calcite supply chains are consolidating around captive quarry networks as producers seek to secure raw material flows against tightening purity standards in construction-grade applications.
Growth Catalysts
- REACH and EU Green Deal standards:Tightened purity requirements for construction-grade calcium carbonate in Europe are filtering low-grade producers from specification chains.
- Infrastructure investment clusters:Cement and concrete demand in China, India, and the United States is pulling ground calcite volumes through direct-to-mill channels.
- Precipitated calcium carbonate morphology control:Brightness indices and particle engineering for plastics substitution are opening premium positioning in high-performance coatings.
Market Restraints
- Energy input cost volatility:Calcite processing and grinding operations face margin compression from electricity and fuel price swings in quarry-to-mill logistics.
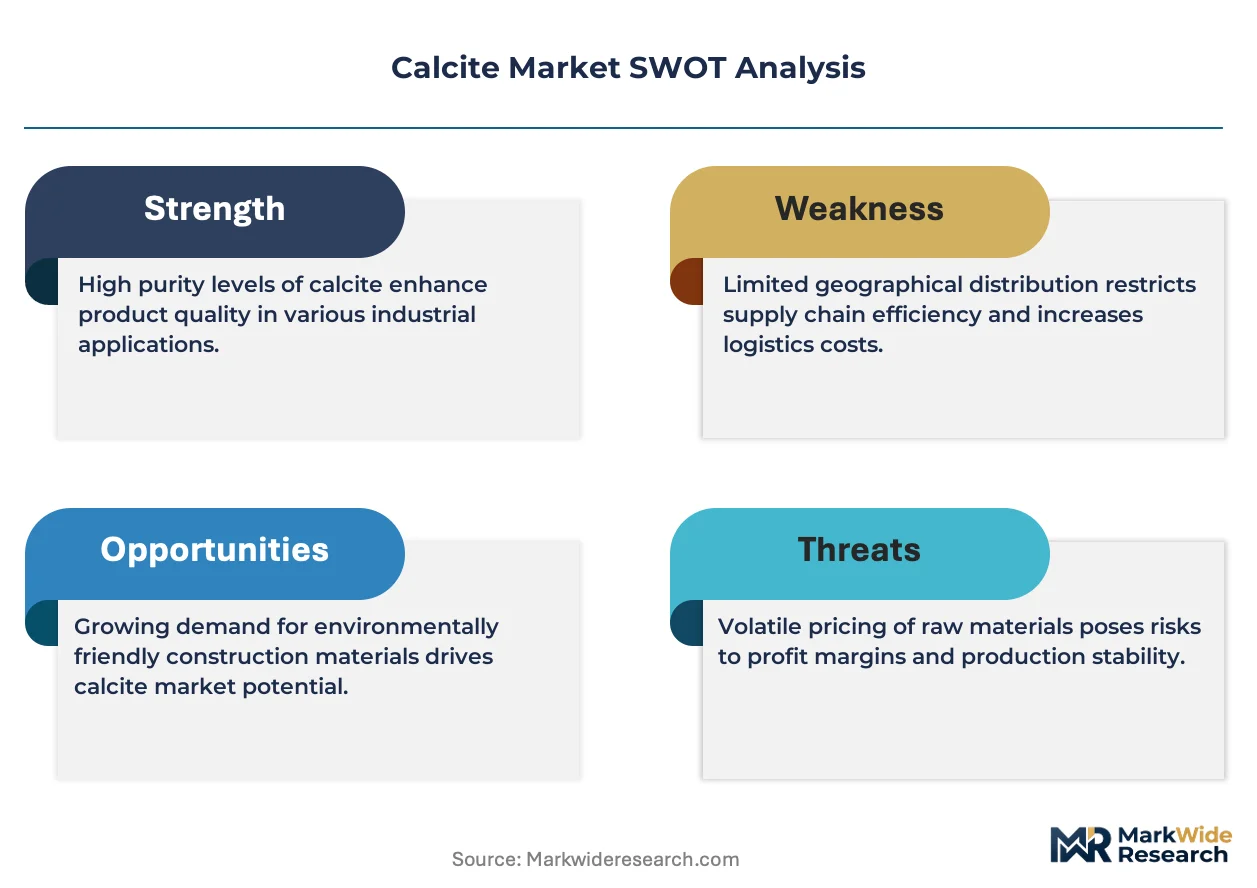
- Quarry concentration in France and Belgium:Imerys S.A.'s captive network controls a disproportionate share of high-purity white calcite deposits, constraining independent processor access.
- Talc and kaolin substitution in paper fillers:Precipitated calcium carbonate faces displacement in certain brightness-sensitive paper grades where mineral alternatives achieve comparable opacity.
Strategic Opportunities
- Slurry concentrate penetration in water-based coatings:Dispersion-quality slurry grades reduce downstream processing costs for paint formulators seeking operational efficiency.
- Green building certification tailwinds:LEED and BREEAM material disclosure requirements are creating preference premiums for traceable, low-carbon-intensity calcium carbonate sources.
- Bioplastics compounding convergence:Controlled-morphology precipitated calcium carbonate is integrating with polylactic acid and starch-based matrices for biodegradable packaging films.
Industry Challenges
- Respirable crystalline silica compliance:OSHA workplace exposure limits intersect with calcite mining operations, requiring dust control capital deployment and product reclassification protocols.
- Legacy slurry distribution infrastructure:Tank farm and rail terminal networks for bulk slurry delivery constrain geographic expansion for regional processors without terminal access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Calcite Market |
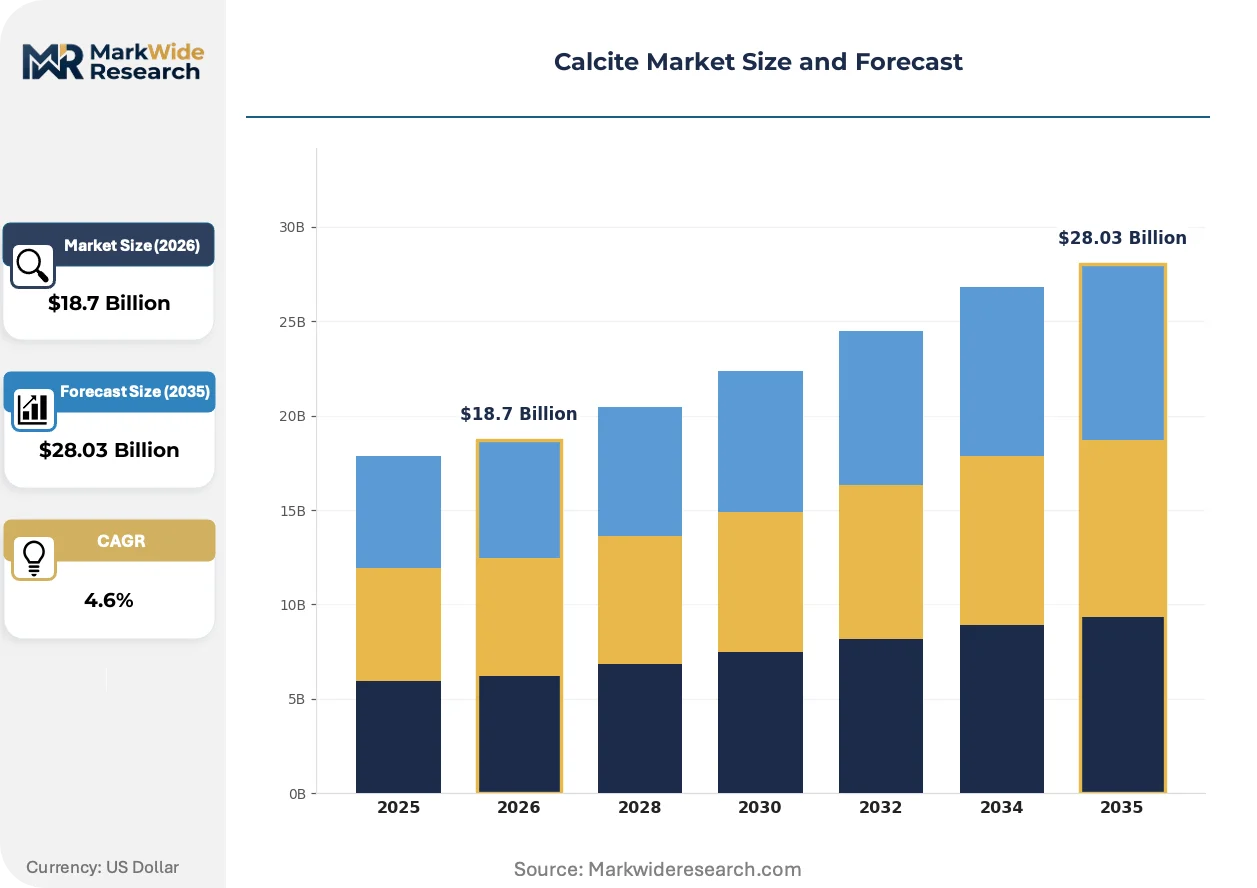
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.03 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Calcium Carbonate, Ground Calcite, Precipitated Calcium Carbonate, Quicklime End Use Industry: Construction, Paints & Coatings, Plastics, Agriculture Form: Powder, Granules, Slurry, Liquid Packaging Type: Bulk Bags, 25 kg Bags, 50 kg Bags, Drums |
| Companies Covered | Imerys S.A., Omya AG, Minerals Technologies Inc., Huber Engineered Materials, Nordkalk Corporation, Sibelco, Gulshan Polyols Ltd., Wolkem India Ltd., Mississippi Lime Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Calcite Market Emerging Trajectories
Digital process control and sustainability traceability are compressing traditional specification cycles in calcite procurement. Formulators now demand real-time quality data and carbon footprint documentation alongside physical product delivery.
Surface-modified nano-calcite dispersions are virtualizing traditional extender roles in automotive clearcoats and flexible packaging films. Coatings formulators in Germany and Japan are adopting these grades to reduce TiO2 loading without sacrificing hiding power. The technology is virtualizing the cost structure of premium decorative paints by enabling lower pigment volumes at equivalent performance.
EPA air emission standards for mineral processing facilities are tightening particulate matter thresholds in the United States. Calcite grinding operations face retrofit investments in baghouse and scrubber systems to maintain operating permits. The paper and plastics segments are absorbing compliance costs through supplier qualification tightening that favors integrated producers with environmental management system certification.
Formulator procurement is consolidating around technical-service partnerships rather than transactional spot purchasing. Paint and coatings manufacturers in Italy and Spain are locking in multi-year slurry supply agreements with embedded laboratory support. This behavior concentrates volume with suppliers capable of customizing particle size distributions and dispersion stability for specific water-based resin systems.
Calcite Market Segmentation
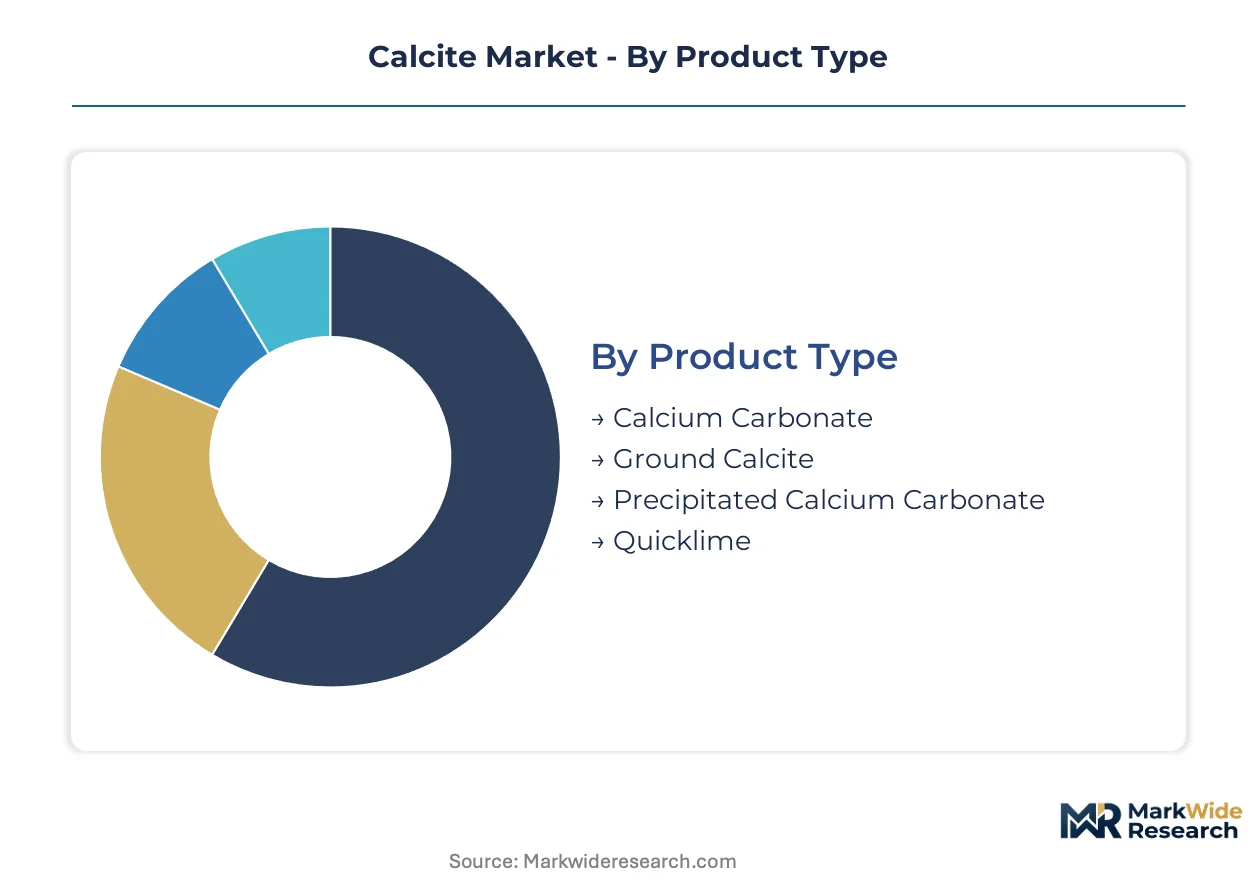
Calcite procurement patterns diverge sharply across product grades and delivery formats, with construction buyers prioritizing bulk powder economics while coatings formulators pay premiums for dispersion-ready slurries. Understanding these segment boundaries reveals where margin pools concentrate and which specifications command technical-service partnerships.
Product Type:
Industrial applications span a cost-performance spectrum from commodity ground material to engineered precipitated grades with controlled morphology.
- Ground Calcite:Mechanically milled from quarried limestone with particle sizes ranging from 1 to 100 microns. Cement and concrete producers in China and India pull the majority of volume through direct-to-mill channels as infrastructure investment accelerates.
- Precipitated Calcium Carbonate:Synthetic production via carbonation of calcium hydroxide yields sub-micron particles with precise brightness control. Plastics compounders and high-performance coatings formulators absorb premium pricing for morphology-engineered grades that enable TiO2 reduction.
- Calcium Carbonate:Generic mineral designation covering both natural and synthetic sources with lower processing specificity. Agricultural lime applications and lower-grade construction fillers represent the primary demand concentration.
- Quicklime:Calcined calcium oxide requiring additional slaking before industrial use. Steel fluxing and environmental remediation drive procurement, with energy-intensive kiln operations constraining supply elasticity.
Established volume favors Ground Calcite; emerging adoption favors Precipitated Calcium Carbonate.
End Use Industry:
Customer technical requirements range from bulk chemical specification to surface chemistry customization.
- Construction:Cement kiln feed and concrete aggregate applications demand high-volume, consistent-grade material. REACH and EU Green Deal purity standards in Europe are filtering low-grade producers from specification chains for structural concrete.
- Paints & Coatings:Water-based systems require slurry concentrates with optimized dispersion stability to reduce downstream processing costs. German and Italian formulators are locking in multi-year supply agreements with embedded laboratory support.
- Plastics:Polypropylene and PVC compounding utilizes surface-modified grades for nucleation and stiffness enhancement.
- Agriculture:Soil pH correction and animal feed supplementation consume lower-specification material with minimal processing.
Construction anchors volume throughput; Paints & Coatings generates the steepest margin expansion.
Form:
Physical delivery state determines logistics infrastructure requirements and customer processing economics.
- Powder:Dominant shipment format for construction and agriculture with established bulk handling infrastructure. Dust control investments escalate as OSHA respirable crystalline silica compliance tightens across United States quarry operations.
- Slurry:Pre-dispersed aqueous concentrates eliminate milling steps for water-based coatings manufacturers. Tank farm and rail terminal networks constrain geographic expansion for processors without terminal access.
- Granules:Intermediate sizing for specific agricultural spreading equipment and selective industrial feed applications.
- Liquid:Specialized suspensions for automated dosing systems in water treatment and chemical processing.
Powder retains shipment leadership; slurry concentrates are gaining share fastest in coatings corridors.
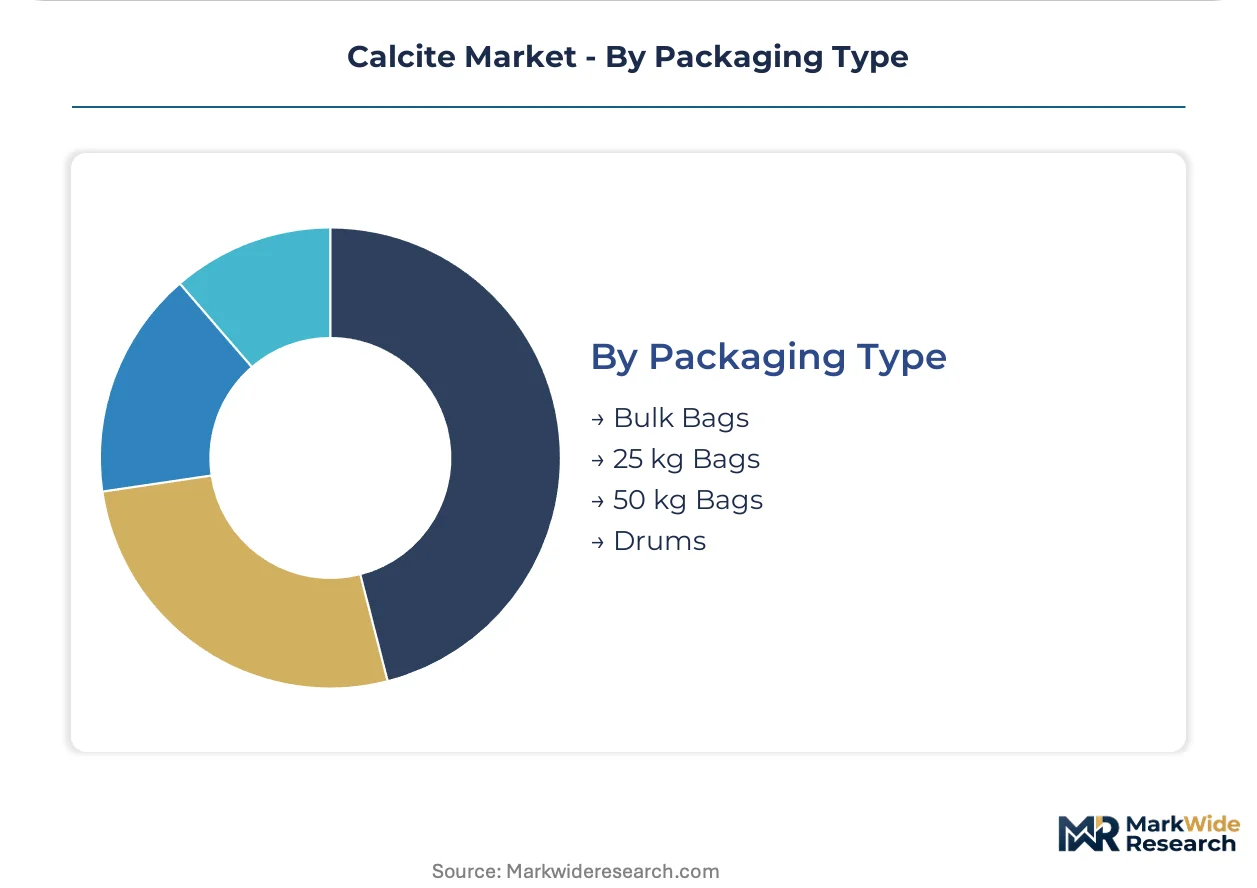
Packaging Type:
Containerization strategy reflects customer scale and material handling automation levels.
- Bulk Bags:One-ton flexible intermediate bulk containers serve high-volume construction and plastics compounders with pneumatic unloading systems. Direct-to-plant delivery minimizes handling costs for integrated manufacturers.
- 25 kg Bags:Standard unit for coatings laboratories, agricultural retail, and small-batch industrial users requiring manual handling compatibility.
- 50 kg Bags:Traditional construction sector format in developing markets with limited bulk handling infrastructure.
- Drums:Liquid and high-value slurry grades for specialized chemical and pharmaceutical applications with contamination sensitivity.
Bulk Bags command volume leadership; 25 kg Bags sustain premium positioning in technical-service segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Western European quarry networks while Asian processors compete on volume scale. Infrastructure investment clusters in China, India, and the United States are pulling divergent specification requirements through regional supply chains.
China
Cement kiln feed demand from Yangtze River Delta infrastructure projects absorbs bulk ground calcite volumes. The Ministry of Ecology and Environment enforces dual carbon goals that tighten emission thresholds for mineral processing facilities. Shandong Province hosts concentrated precipitated calcium carbonate capacity serving plastics compounders in Jiangsu and Zhejiang.
United States
Concrete aggregate specifications for federal infrastructure spending require consistent high-purity material. EPA air emission standards govern particulate matter thresholds from grinding operations, forcing retrofit investments in baghouse systems. The Ohio River Valley corridor concentrates limestone quarrying capacity feeding Midwest construction markets.
India
Highway and dam construction in Maharashtra and Gujarat drives direct-to-mill procurement of construction-grade material. Bureau of Indian Standards certification requirements for structural concrete are filtering substandard imports from regional suppliers. Rajasthan and Andhra Pradesh host expanding ground calcium carbonate capacity serving domestic paints and coatings formulators.
Germany
Water-based coatings formulators in Bavaria and North Rhine-Westphalia lock in multi-year slurry supply agreements. REACH registration mandates hazard communication protocols for calcium carbonate variants in consumer-facing applications. The Frankfurt-Rhine-Main logistics corridor enables rail-terminal distribution of dispersion-ready slurry concentrates.
France
High-purity white calcite deposits in the Paris Basin supply premium construction and coatings applications. EU Green Deal material disclosure requirements are creating preference premiums for traceable, low-carbon-intensity sources. Lorraine and Champagne-Ardenne quarry networks feed integrated processing operations serving Benelux export markets.
Calcite Market Vendor Landscape
Captive-quarry operators and technical-service specialists split the market between volume efficiency and specification premium capture. Consolidation around high-purity white calcite deposits in France and Belgium constrains independent processor access to top-tier raw material. Three archetypes dominate: integrated quarry-to-mill operators controlling upstream supply, precipitated calcium carbonate specialists engineering morphology for plastics substitution, and regional slurry distributors leveraging terminal infrastructure for coatings corridor penetration. Competitive moves center on logistics network consolidation and multi-year technical-service partnerships that embed laboratory support in supply agreements.
Among European integrated operators, Imerys S.A. and Omya AG exemplify divergent strategic positions. Imerys represents the captive-quarry archetype with upstream control over high-purity deposits. Omya occupies a technical-service-led position emphasizing customized slurry grades and formulator partnerships. Minerals Technologies Inc. anchors the precipitated calcium carbonate specialization vector, with morphology control capabilities serving paper and plastics substitution demand. These three patterns illustrate how geographic asset control, technical service intensity, and synthetic production expertise segment competitive positioning across construction, coatings, and compounding end uses.
| Leading Market Players |
|---|
| Imerys S.A. |
| Omya AG |
| Minerals Technologies Inc. |
| Huber Engineered Materials |
| Nordkalk Corporation |
| Sibelco |
| Gulshan Polyols Ltd. |
| Wolkem India Ltd. |
| Mississippi Lime Company |
| Others |
Supply Flow & Price Mechanics
Single-source dependency on Imerys S.A.'s captive quarry network in France and Belgium compresses pricing tier spreads while forcing supply chain consolidation around rail-terminal infrastructure. REACH purity mandates and EU Green Deal disclosure requirements simultaneously widen premium spreads for traceable grades and eliminate low-purity spot suppliers from specification chains.
Pricing Analysis
Configured-to-order pricing for precipitated calcium carbonate with morphology control commands substantial premiums over standard ground calcite spot transactions. Three-tier pricing structure across premium, standard, and economy levels stratifies by brightness index, particle size distribution, and embedded technical service. Cost compression in economy-grade ground calcite intensifies because electricity and fuel volatility erodes processor margins. Cement and concrete buyers exhibit highest price sensitivity due to bulk volume procurement, while coatings formulators absorbing slurry concentrates prioritize dispersion stability over unit cost.
Supply Chain Analysis
Tariff exposure between China and developed markets dominates supply chain risk calculus for precipitated calcium carbonate equipment and processing technology imports. Production gravity centers on China, India, and the United States for ground calcite, with France and Belgium anchoring high-purity white calcite extraction. Raw material flows draw from limestone deposits, calcium hydroxide feedstock, and surface-modification chemical agents. Single-source vulnerability concentrates in Imerys S.A.'s Paris Basin quarry network. Distribution runs through direct-to-mill channels for construction volumes and rail-terminal slurry networks for coatings corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Calcite incumbents face sustained substitution pressure from talc and kaolin in paper filler applications, requiring defensive positioning around morphology-controlled precipitated grades and captive quarry access.
For Market Incumbents: Build captive quarry moats through consolidation of high-purity white calcite deposits in France and Belgium against independent processor encroachment. Secure backward integration into limestone extraction to lock raw material flows. Invest in surface-modification R&D for nano-calcite dispersions displacing TiO2 in automotive clearcoats. Defend against talc substitution in brightness-sensitive paper grades through brightness index engineering. For New Entrants and Emerging Players: Build out slurry concentrate capabilities in water-based coatings corridors where dispersion-quality premiums offset capital-intensive tank farm infrastructure. Target underpenetrated bioplastics compounding convergence with polylactic acid and starch-based matrices. Establish technical-service partnerships with German and Italian formulators seeking embedded laboratory support. Leverage regional rail-terminal access to bypass legacy distribution constraints. For Investors and Strategic Acquirers: EU Green Deal material disclosure requirements reshape the acquisition landscape toward traceable, low-carbon-intensity calcium carbonate sources. Long-term viability hinges on integrated quarry-to-mill operators controlling upstream supply rather than toll processors. Target acquisition archetypes: precipitated calcium carbonate specialists with morphology control patents and slurry distributors with terminal infrastructure in coatings corridors. Monitor OSHA respirable crystalline silica enforcement tightening as inflection indicator for dust control capital deployment requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Quarry Acquisition | Upstream control over high-purity white calcite deposits in France and Belgium secures specification-grade supply. |
| Slurry Terminal Expansion | Rail-terminal infrastructure in German and Italian coatings corridors captures dispersion-quality premium pools. |
| Surface-Modification R&D | Nano-calcite engineering for TiO2 reduction in automotive clearcoats opens high-performance substitution markets. |
| Technical-Service Partnership | Embedded laboratory support in multi-year supply agreements locks in paint and coatings formulator volume. |
| Green Certification Program | LEED and BREEAM traceability documentation creates preference premiums for low-carbon-intensity sources. |
Methodological Framework
The analysis maps ground calcite, precipitated calcium carbonate, and slurry concentrate sub-sectors, each validated through plant managers at integrated quarry-to-mill operators, procurement leads at cement and coatings manufacturers, and technical R&D directors. Primary interviews with distribution channel partners and regulatory affairs specialists intersect with secondary validation from customs/trade data, SEC 10-K filings, and ECHA REACH registration databases. Bottom-up volume triangulation against top-down value estimates ensures segment-level coherence.
Assumptions held fixed include REACH and EU Green Deal regulatory trajectories, while energy input cost volatility and infrastructure investment cycles varied across sensitivity scenarios. The analytical framework models product type, end-use industry, form, and regional production hub dimensions across the analysis window. CAGRs derive from regression against historical volume elasticities and substitution coefficient modeling. Key inputs include cement demand coefficients from infrastructure spending and coatings formulation shift rates toward water-based systems.
Practitioners should monitor OSHA silica enforcement intensity, EU carbon border adjustment implementation, and bioplastics compounding adoption curves for early signals of forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Ceramic Binders Market
Ceramics
Advanced Ceramic Additives Market
Ceramics
GCC Ceramic Tiles and Sanitary Ware Market
Ceramics
Egypt Ceramic Tiles Market
Ceramics
Saudi Arabia Ceramic Tiles Market
Ceramics
Cordierite Market
Ceramics
Optical Ceramics Market
Ceramics
Dielectric Ceramics Market
Ceramics
Aluminium Nitride Market
Ceramics
Quartz Powder Market
Ceramics
Global Zirconia Oxygen Sensors Market
Ceramics
Global Industrial Clay Market
Ceramics
Clay Market
Ceramics
Spain Ceramic Tiles Market
Ceramics
Calcined Alumina Market
Ceramics
Asia-Pacific Activated Alumina Market