
 Sanitary Paper Products Market | 2026-2036
Sanitary Paper Products Market Size, Share, and Industry Trends Forecast 2026-2036
Sanitary Paper Products Market Analytics
Specialized pulp chemistry expertise is redrawing competitive boundaries across the sanitary paper products industry. Kimberly-Clark Corporation leverages its captive air-laid manufacturing base to sustain premium tissue margins in North America. Essity AB anchors European private-label supply through integrated Nordic pulp sourcing. Georgia-Pacific LLC dominates the North American away-from-home channel with concentrated towel and napkin capacity.
Sanitary paper products comprise absorbent tissue-based disposables engineered from bleached kraft pulp or recycled fiber, typically formed through through-air-drying or conventional wet-pressing to achieve controlled bulk, wet strength, and softness for personal and institutional hygiene. Toilet paper and paper towels command the largest production volumes, though facial tissues carry superior per-unit margins due to premium positioning and branded loyalty. The hospitality end-user segment shows the fastest structural expansion as hotel chains standardize bulk amenity procurement, while virgin fiber formulations retain share in clinical healthcare settings where lint control and sterility protocols override sustainability preferences.
The EPA governs effluent discharge from US tissue mills under Clean Water Act permits, while REACH and the EU Green Deal constrain chlorine-based bleaching chemistries and mandate recycled content disclosures across European markets. India's BIS enforces absorbent quality benchmarks for imported tissue grades, shaping procurement criteria for hospital and hotel buyers. Stakeholders must monitor evolving fiber certification schemes and regional carbon border adjustments to secure long-term raw material access without surrendering cost parity.
Market Dynamics
Fiber certification mandates and carbon border mechanisms are restructuring raw material procurement economics across sanitary paper manufacturing, forcing mills to requalify supply chains and absorb compliance premiums.
Growth Catalysts
- EU Green Deal packaging mandates:Single-use plastics directives accelerate transitions to bleached kraft and bamboo fiber formulations, expanding addressable demand for compliant tissue grades across European institutional buyers.
- India urban sanitation infrastructure:Municipal sewerage expansion and hotel construction in tier-two cities amplifies volume commitments for away-from-home towel and napkin categories.
- Through-air-drying (TAD) technology diffusion:Premium bulk and softness specifications now achievable at mid-scale capacity levels, enabling private-label suppliers to capture branded market share in facial tissue segments.
Market Restraints
- Softwood pulp price volatility:Scandinavian and Canadian fiber supply concentration exposes converters to input cost swings that compress margin buffers on fixed-price hospitality contracts.
- REACH chemical compliance friction:Chlorine-free bleaching transitions require capital-intensive process reengineering at legacy European mills, extending payback periods for sustainability investments.
- Reusable textile substitution:Industrial laundry services in Nordic healthcare facilities displace single-use surgical towels where sterility protocols permit sterilization cycles.
Strategic Opportunities
- Indian private-label penetration:Modern trade expansion in Maharashtra and Karnataka creates white space for contract manufacturers to supply domestic retail chains with localized tissue specifications.
- Bamboo-pulp convergence with TAD forming:Alternative fiber processing breakthroughs enable premium product positioning without virgin softwood dependency, unlocking sustainability-premium capture.
- E-commerce bulk channel emergence:Direct-to-institutional platforms bypass traditional paper merchant networks, reducing working capital cycles for mid-scale converters serving restaurant groups.
Industry Challenges
- Air-laid equipment specialization scarcity:Qualified process engineers capable of optimizing thermal bonding parameters command premium compensation, constraining capacity expansion timelines.
- FSC chain-of-custody certification complexity:Multi-tier pulp sourcing documentation requirements delay qualification for European retail private-label contracts by six to twelve months.
- Legacy wet-press asset stranding:Conventional tissue machines face obsolescence risk as premium specifications migrate toward TAD-capable platforms, complicating reinvestment decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sanitary Paper Products Market |
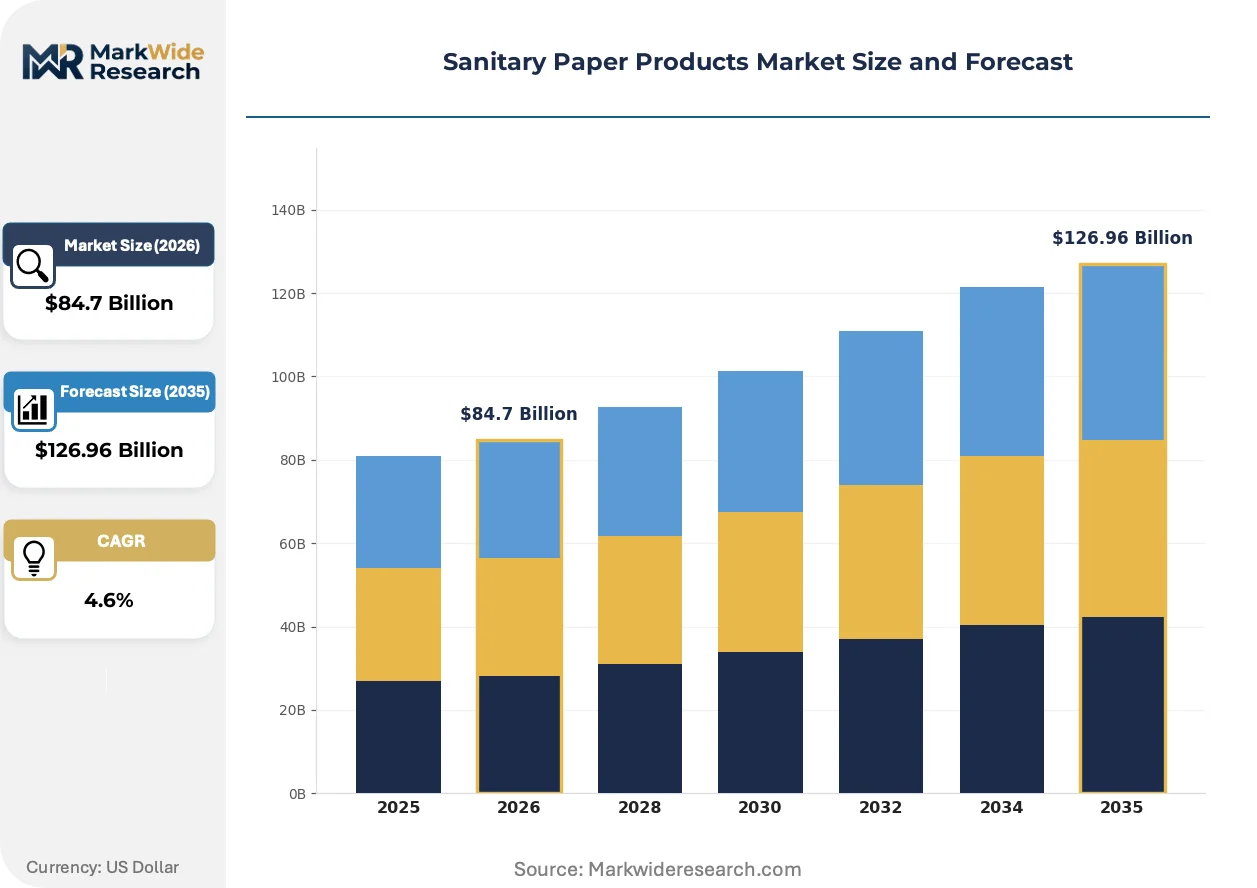
| Market Size in 2026 | $84.7 Billion |
| Market Size in 2035 | $126.96 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Toilet Paper, Paper Towels, Napkins, Facial Tissues End User: Residential, Commercial, Healthcare, Hospitality Material: Recycled Paper, Virgin Fiber, Bamboo, Non-Woven Fabrics Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Wholesale |
| Companies Covered | Procter & Gamble Company, Kimberly-Clark Corporation, Essity AB, Georgia-Pacific LLC, Hengan International Group Company Limited, Asia Pulp and Paper Group, Sofidel Group, Cascades Inc., Svenska Cellulosa Aktiebolaget SCA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sanitary Paper Products Market Evolving Landscape
Material science breakthroughs and procurement platform digitization are compressing product development cycles while fragmenting traditional channel structures across tissue categories.
Bamboo-pulp fiber engineering is decomposing the historical link between premium softness and virgin softwood dependency. Specialty mills in Sichuan and Guangxi provinces now supply bleached bamboo pulp meeting TAD bulk specifications. European facial tissue brands are adopting these formulations to satisfy EU Green Deal recycled-content disclosures without sacrificing tactile performance.
REACH authorization requirements for formaldehyde-based wet-strength resins are forcing chemistry substitutions across European sanitary paper production. Manufacturers are qualifying glyoxal and polyamide-epichlorohydrin alternatives that maintain wet tensile performance. The clinical healthcare segment faces the steepest reformulation burden, as patient-contact applications trigger the most stringent exposure limits.
Bulk institutional procurement platforms are consolidating specification-setting authority within hospitality purchasing cooperatives. Large hotel chains now mandate standardized amenity formats across multi-brand portfolios, displacing property-level discretion. This concentration is most visible in the United Arab Emirates and Saudi Arabia, where sovereign wealth-backed hospitality groups centralize procurement for dozens of properties simultaneously.
Sanitary Paper Products Market Segmentation
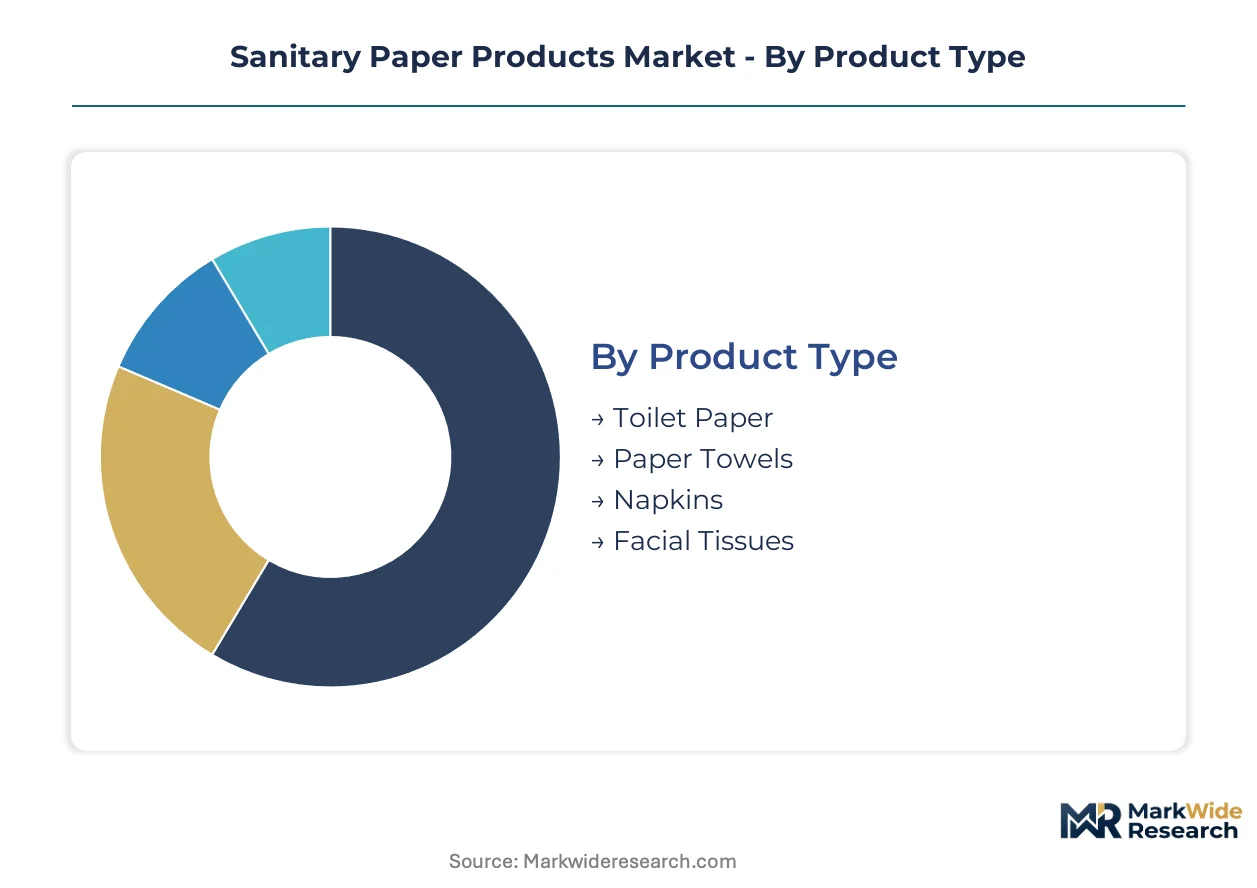
Sanitary paper procurement decisions fragment across regulatory thresholds, fiber certification requirements, and sterility protocols that vary by end-use environment. Understanding these segment boundaries reveals where compliance premiums convert to margin capture versus commodity pressure.
Product Type:
REACH chemical authorizations and FDA food-contact rulings split manufacturing compliance burdens across tissue categories.
- Toilet Paper:Conventional wet-pressed forming dominates mass-market rolls, though TAD-capable platforms now penetrate mid-tier private-label supply. Hospital and hotel buyers in Maharashtra and Karnataka specify bulk jumbo-roll formats that reduce changeout frequency in high-traffic restrooms.
- Paper Towels:Multi-fold and roll towel specifications carry divergent wet-strength resin requirements under EPA effluent permits. The away-from-home channel concentrates procurement authority within hospitality purchasing cooperatives across the United Arab Emirates and Saudi Arabia.
- Napkins:Food-service grades face FDA indirect food additive scrutiny for wet-strength chemistry migration.
- Facial Tissues:Premium positioning commands softness specifications that historically required virgin softwood pulp, though bamboo fiber formulations now qualify under EU Green Deal mandates.
Established volume favors toilet paper; emerging adoption favors facial tissues as premium private-label penetration deepens.
End User:
Cost tier stratification separates specification-intensive institutional buyers from price-sensitive residential procurement.
- Residential:Supermarket and e-commerce channels dominate, with bulk purchasing patterns concentrated in urban India as sewerage infrastructure expands. Brand loyalty erodes fastest where modern trade private-label alternatives achieve TAD-comparable softness.
- Commercial:Office building and facility management contracts run on fixed-price multi-year terms that expose converters to softwood pulp volatility. BIS absorbent quality benchmarks shape import qualification timelines for hospital and hotel buyers sourcing from ASEAN suppliers.
- Healthcare:Clinical sterility protocols override sustainability preferences, preserving virgin fiber share where lint control and wet tensile performance govern patient safety. REACH formaldehyde resin restrictions force glyoxal alternative qualification cycles.
- Hospitality:Sovereign wealth-backed hotel groups in the Gulf Cooperation Council centralize amenity procurement across multi-brand portfolios, standardizing formats and displacing property-level discretion.
Contract concentration favors hospitality; margin sustainability favors healthcare despite chemistry reformulation burdens.
Material:
Supply concentration geography determines fiber access economics and carbon border exposure.
- Recycled Paper:Post-consumer fiber sourcing faces FSC chain-of-custody documentation complexity that delays European retail qualification by six to twelve months. De-inking capacity constraints in India limit domestic supply scale for away-from-home towel production.
- Virgin Fiber:Scandinavian and Canadian softwood pulp concentration exposes converters to input cost swings. Clinical healthcare settings retain preference where sterility protocols demand controlled fiber provenance.
- Bamboo:Sichuan and Guangxi specialty mills now supply bleached pulp meeting TAD bulk specifications, enabling EU Green Deal compliance without tactile performance sacrifice.
- Non-Woven Fabrics:Air-laid thermal bonding technology creates surgical towel alternatives where Nordic healthcare facilities permit sterilization cycles.
Scale economies favor virgin fiber; sustainability-premium capture favors bamboo as TAD forming convergence matures.
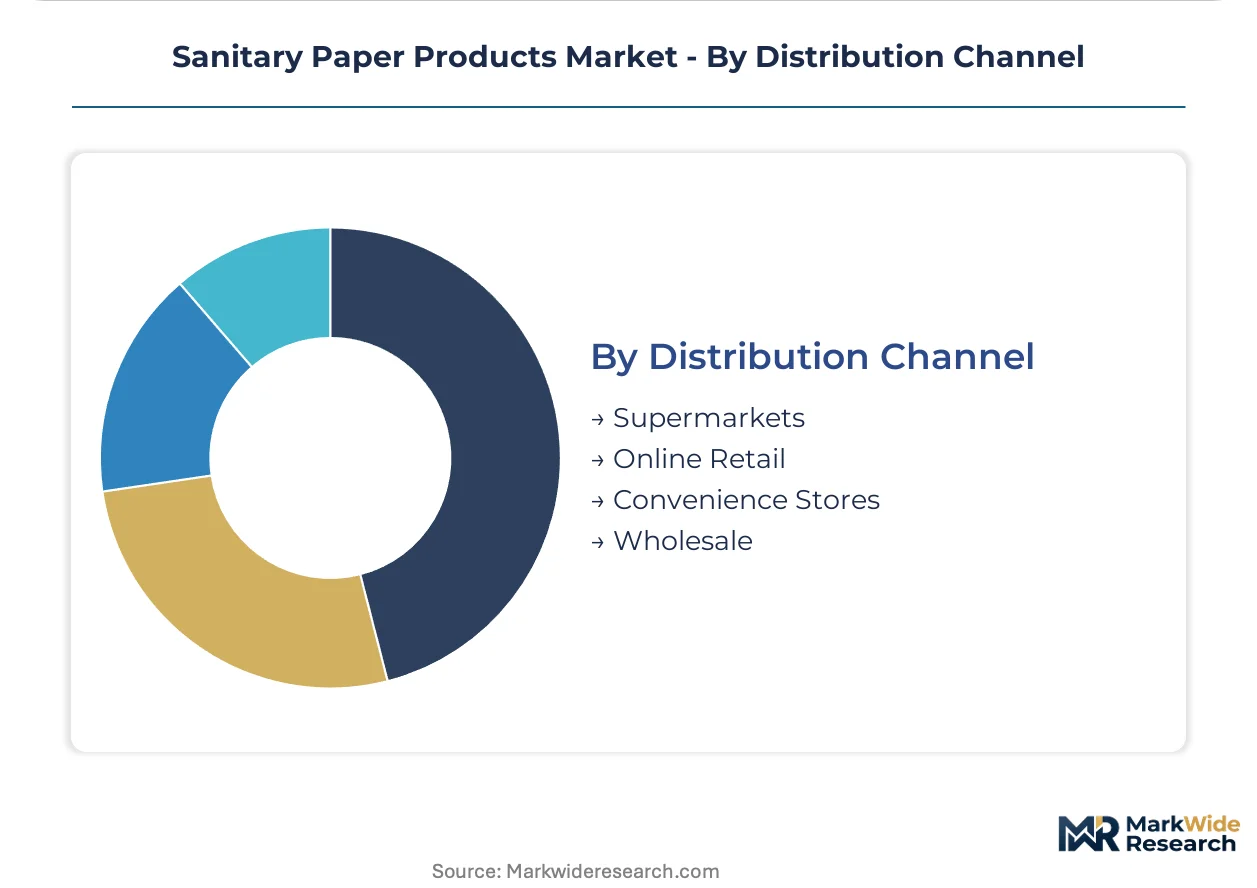
Distribution Channel:
Customer type and order scale split working capital requirements and margin structures.
- Supermarkets:Modern trade expansion in India creates shelf-space competition between multinational brands and emerging private-label suppliers. BIS certification requirements shape import sourcing criteria.
- Online Retail:Direct-to-institutional platforms bypass traditional paper merchant networks, compressing working capital cycles for mid-scale converters serving restaurant groups.
- Convenience Stores:Small-format retail concentrates emergency replenishment demand with limited SKU breadth.
- Wholesale:Bulk institutional procurement consolidates specification-setting authority within hospitality cooperatives and healthcare group purchasing organizations.
Volume throughput favors wholesale; margin expansion favors online retail as platform intermediation fragments traditional merchant control.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA effluent permits under the Clean Water Act govern US tissue mill discharge standards, while REACH and the EU Green Deal constrain chlorine-based bleaching across European markets. BIS absorbent quality benchmarks shape import qualification timelines for hospital and hotel buyers in India.
United States
Hospital construction and hospitality amenity standardization drive institutional tissue procurement. EPA Clean Water Act permits regulate mill effluent discharge, constraining chlorine chemistry use. Wisconsin and Georgia host concentrated towel and napkin capacity serving the away-from-home channel.
Germany
REACH authorization requirements for formaldehyde-based wet-strength resins force chemistry substitutions across facial tissue production. EU Green Deal packaging mandates accelerate transitions to bleached kraft formulations. North Rhine-Westphalia mills anchor European private-label supply through integrated Nordic pulp sourcing.
India
Municipal sewerage expansion in tier-two cities amplifies volume commitments for away-from-home categories. BIS enforces absorbent quality benchmarks for imported tissue grades, shaping procurement criteria for hospital buyers. Maharashtra and Karnataka modern trade expansion creates white space for contract manufacturers supplying domestic retail chains.
China
Specialty mills in Sichuan and Guangxi provinces now supply bleached bamboo pulp meeting through-air-drying bulk specifications. Dual carbon goals pressure fiber-source transitions away from virgin softwood dependency. Yangtze River Delta converters process alternative pulp for European facial tissue brands seeking EU Green Deal compliance.
Saudi Arabia
Sovereign wealth-backed hospitality groups centralize amenity procurement across multi-brand portfolios, standardizing formats and displacing property-level discretion. SFDA regulates patient-contact tissue applications in clinical settings. Riyadh and Jeddah hotel construction concentrates bulk institutional demand for standardized towel and napkin specifications.
Sanitary Paper Products Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in sanitary paper manufacturing. The upper tier commands captive pulp sourcing and air-laid manufacturing infrastructure, while mid-scale converters compete on private-label flexibility and regional logistics. Three archetypes dominate: integrated fiber-to-retail conglomerates, hospitality-focused away-from-home specialists, and bamboo-pulp technology pioneers. Consolidation pressure manifests through strategic partnerships for alternative fiber qualification and capacity expansion in high-growth geographies.
Within the integrated tier, Procter & Gamble Company and Kimberly-Clark Corporation exemplify scale-driven positioning through North American manufacturing density. Essity AB occupies a position representing European private-label supply integration. Hengan International Group Company Limited anchors the Asia-Pacific specialist archetype. These three entities collectively represent divergent geographic and channel strategies without overlapping operational footprints.
| Leading Market Players |
|---|
| Procter & Gamble Company |
| Kimberly-Clark Corporation |
| Essity AB |
| Georgia-Pacific LLC |
| Hengan International Group Company Limited |
| Asia Pulp and Paper Group |
| Sofidel Group |
| Cascades Inc. |
| Svenska Cellulosa Aktiebolaget SCA |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts between Scandinavian pulp suppliers and European tissue converters lock in fiber access and price visibility for eighteen-to-thirty-six month windows, insulating margin buffers against softwood volatility while constraining formulation flexibility under REACH chemical mandates.
Pricing Analysis
Contract-based long-term offtake dominates institutional procurement, with hospitality purchasing cooperatives negotiating fixed-price multi-year terms that expose converters to pulp cost swings. Price differentiation hinges on FSC chain-of-custody certification tier and TAD-capable platform access. Cost compression in mid-tier private-label supply is intensifying because bamboo fiber qualification cycles extend payback periods. Residential supermarket buyers exhibit highest price sensitivity; healthcare clinical settings show least sensitivity due to sterility protocol rigidity.
Supply Chain Analysis
Inventory cycles stretch to ninety days for bleached kraft pulp moving from Swedish and Finnish ports to European tissue mills, compressing to forty-five days for bamboo pulp sourced from Sichuan province. Supply concentrates in Sweden, Finland, and Canada for softwood pulp; China dominates bamboo fiber processing. Raw material dependencies include Nordic softwood chips, Guangxi bamboo stalks, and glyoxal wet-strength resins. Single-source vulnerability runs through Scandinavian pulp concentration. Distribution runs through hospitality purchasing cooperatives and healthcare group purchasing organizations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sanitary paper products sit in early-cycle expansion as EU Green Deal mandates force fiber-source transitions that expand addressable demand for compliant tissue grades across institutional buyers.
For Market Incumbents: Fortify captive pulp sourcing through backward integration into Nordic softwood holdings or long-term offtake with Guangxi bamboo processors. Accelerate TAD platform capacity additions in Maharashtra to capture Indian modern trade expansion. Defensive positioning requires preemptive FSC chain-of-custody certification investment before European retail qualification windows tighten. For New Entrants and Emerging Players: BIS certification fast-track for imported tissue grades opens white space in Karnataka hospital supply and tier-two Indian hotel construction. Maharashtra modern trade private-label penetration represents the most penetrable geography. Direct-to-institutional e-commerce platforms bypass entrenched paper merchant networks with working capital advantages. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated fiber-to-retail conglomerates with captive air-laid manufacturing and hospitality contract backlogs. Long-term viability across the next decade favors specialists with alternative fiber processing patents and TAD technology licenses. Acquisition target archetype: mid-scale converters with qualified bamboo-pulp supply relationships and underutilized European mill assets. Watch TAD equipment order backlogs as inflection signal for premium capacity expansion timing.| Strategic Initiative | Industry Significance |
|---|---|
| Alternative Fiber Qualification | Bamboo pulp certification under EU Green Deal unlocks sustainability-premium capture for facial tissue brands. |
| TAD Platform Capacity Expansion | Mid-scale converters in Maharashtra capture branded market share through premium softness specifications. |
| Direct-to-Institutional Platform Launch | E-commerce bulk channels compress working capital cycles for restaurant group supply contracts. |
| FSC Chain-of-Custody Investment | Certification documentation accelerates European retail private-label qualification timelines. |
| REACH Chemical Reformulation | Glyoxal wet-strength resin substitution maintains clinical healthcare segment access under formaldehyde restrictions. |
Research Methodology
The analysis maps toilet paper, paper towels, facial tissues, and napkins, each validated through procurement directors at hospitality purchasing cooperatives, tissue mill operations managers, pulp trading specialists, and BIS certification consultants. Primary fieldwork combined with secondary validation from customs trade records, EPA effluent permit filings, EU ECHA authorization databases, and FSC chain-of-custody registries. Bottom-up capacity modeling and top-down demand triangulation cross-checked segment outputs.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include product type, end-user environment, fiber material tier, and distribution channel structure. CAGRs derived from installed capacity trajectories, pulp price elasticity coefficients, and regulatory compliance cost curves. Industry-specific inputs incorporated REACH chemical authorization timelines and Indian municipal sewerage expansion schedules.
Decision-makers should treat outputs as directional under assumptions of sustained EU Green Deal enforcement and stable Scandinavian pulp supply; material deviation in regulatory stringency or trade policy would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper Products
Printing and Writing Papers Market
Paper Products
Recording Chart Paper Market
Paper Products
Wood Paper and Paperboard Recycling Market
Paper Products
GCC Paper Products Market
Paper Products
Paper Doilies Market
Paper Products
Bleached Softwood Kraft Pulp Market
Paper Products
Billing Paper Market
Paper Products
Polyester Synthetic Paper Market
Paper Products
Paper Dry Strength Agents Market
Paper Products
Abaca Pulp Market
Paper Products
White Top Testliner Market
Paper Products
Coated Wood Free Papers Market
Paper Products
Metallized Paper Market
Paper Products
Europe Paper Market
Paper Products
BPA Free Thermal Paper Market
Paper Products
Chemical Cellulose Market