
 China Ceramic Market | 2026-2036
China Ceramic Market Size, Share, and Industry Trends Forecast 2026-2036
China Ceramic Market Insights
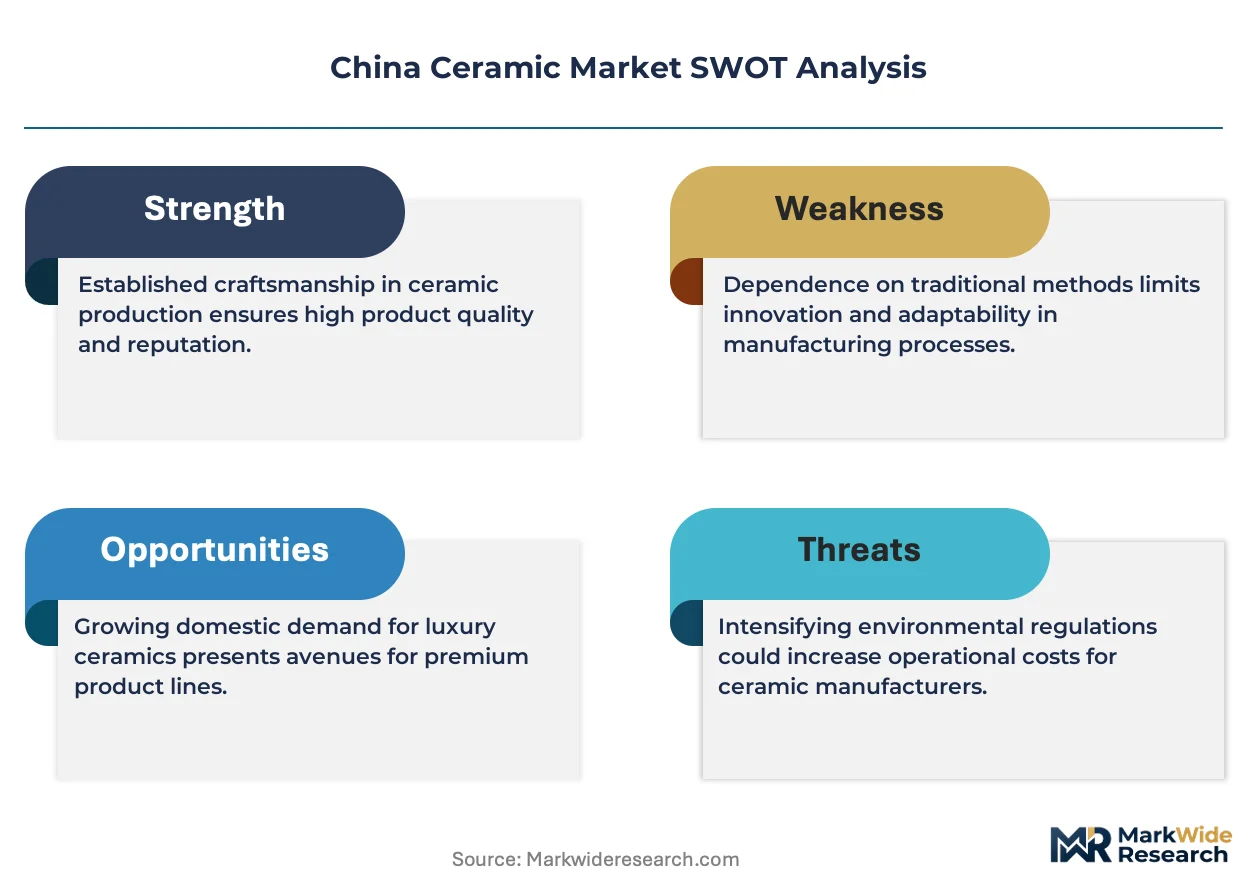
Project finance for distributed natural gas-fired kilns is reshaping competitive entry in China's ceramic sector, lowering capital barriers for mid-scale producers. Dongpeng Ceramic leverages its vertically integrated supply chain across Foshan to sustain cost advantages in porcelain tile manufacturing. Sinoma Advanced Materials anchors its position through R&D intensity in advanced ceramic substrates for industrial applications. Monalisa Group differentiates via brand strength in the premium decorative segment, controlling distribution through flagship retail channels.
China ceramic encompasses fired clay-based materials with alumina-silica compositions typically processed through roller-kiln or tunnel-kiln sintering above 1,200°C, serving structural, decorative, and functional applications across construction and consumer industries. Porcelain commands the dominant value share due to its low water absorption and high mechanical strength in flooring and wall tile applications. Sanitary ware represents the fastest-growing application segment, driven by urban residential renovation cycles and commercial hospitality buildouts. The wholesale distribution channel retains structural importance for bulk construction procurement, though online platforms are gaining traction in replacement and renovation demand.
MIIT enforces GB standards for ceramic energy consumption and emission intensity, while SAMR monitors product quality labeling under national certification requirements, collectively elevating compliance costs for smaller kiln operators. The dual carbon goals from China's central government mandate kiln electrification and waste-heat recovery investments, reshaping capital allocation across Guangdong and Shandong production bases. Stakeholders must monitor regulatory enforcement differentiation between provincial environmental bureaus and the pace of carbon-border adjustment mechanisms affecting export-oriented ceramic manufacturers.
Market Dynamics
MIIT's dual carbon goals are compressing kiln economics across Guangdong and Shandong production bases, forcing wholesale electrification of firing processes and waste-heat recovery retrofits that favor capital-rich incumbents over fragmented operators.
Growth Catalysts
- Urban residential renovation cycles:Tier-two city real estate development sustains volume pull for sanitary ware and porcelain tile replacement demand across interior finishing markets.
- GB standards for energy-efficient building materials:Mandatory efficiency labeling elevates certified product premiums and accelerates obsolescence of legacy kiln output.
- Roller-kiln electrification:Natural gas-to-electricity conversion in Foshan ceramic clusters lowers emission intensity and unlocks green financing for technology upgrades.
Market Restraints
- High-purity alumina supply concentration:Import dependency for advanced ceramic substrates creates input cost volatility and inventory risk for industrial-grade producers.
- Emission compliance cost escalation:MEE enforcement of particulate and NOx limits imposes scrubber and filtration capex that squeezes margin structures for sub-scale operators.
- Thin-film surface finishing substitution:Large-format sintered stone panels displace traditional porcelain in premium flooring specifications, compressing addressable volume in high-value segments.
Strategic Opportunities
- Advanced ceramic substrates for EV power electronics:Automotive thermal management applications create demand pull for alumina and aluminum nitride precision components from domestic battery supply chains.
- Western China logistics corridor expansion:Chengdu-Chongqing infrastructure buildout opens distribution access for Sichuan and Jiangxi production bases previously constrained by coastal freight costs.
- SAMR quality certification premiumization:National standards enforcement enables branded players to capture price separation from unlabeled commodity tile imports.
Industry Challenges
- Electrical kiln engineering talent scarcity:Shortage of technicians capable of optimizing resistive heating profiles and thermal uniformity controls slows electrification project timelines.
- Legacy tunnel-kiln asset stranding:Sunk capital in gas-fired continuous kilns creates disincentive for early replacement despite regulatory pressure, trapping mid-scale producers in compliance gaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Ceramic Market |
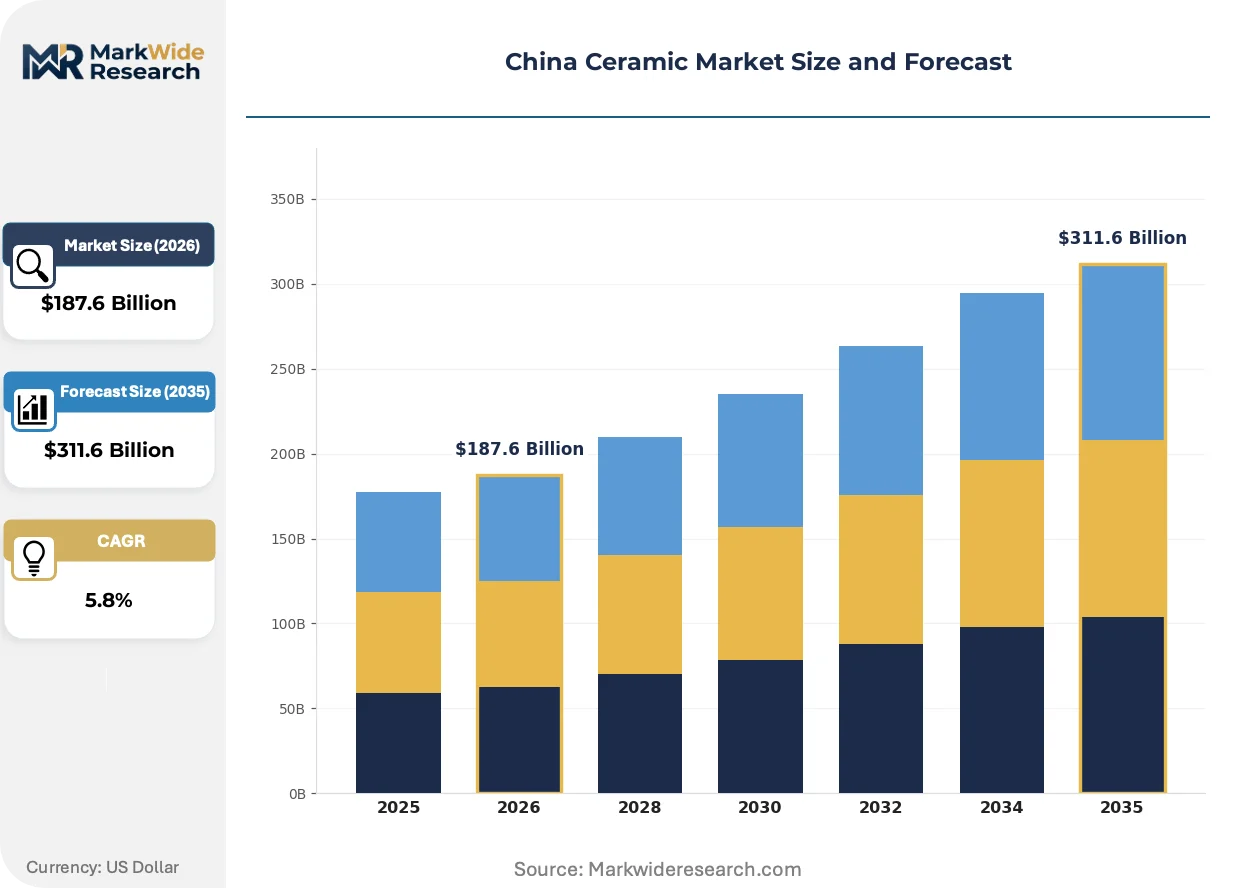
| Market Size in 2026 | $187.6 Billion |
| Market Size in 2035 | $311.6 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Porcelain, Stoneware, Earthenware, Bone China Application: Dinnerware, Tiles, Sanitary Ware, Decorative Items End User: Residential, Commercial, Industrial, Hospitality Distribution Channel: Online, Retail, Wholesale, Direct Sales |
| Companies Covered | Marco Polo Holdings, Sinoma Advanced Materials, Dongpeng Ceramic, Guangdong Xinruncheng Ceramics, Guangdong Kito Ceramics Group, Guangdong Newpearl Ceramic Group, GGS Ceramic, Foshan Shiwan Eagle Brand Ceramic, Monalisa Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Ceramic Market Trends and Innovations
Digital firing control systems and low-carbon material formulations are restructuring production economics, while distribution digitization reconfigures how specification decisions flow from architects to manufacturers.
Intelligent kiln management platforms integrating real-time thermal profiling with predictive maintenance algorithms are collapsing the efficiency gap between automated and manual firing operations. Large-format tile producers in Foshan are adopting these systems fastest, compressing energy consumption variance and reducing reject rates to levels that marginalize conventional kiln operators.
MIIT's progressive tightening of GB 21252 energy consumption limits for ceramic tile manufacturing is mandating waste-heat recovery installation and natural gas efficiency thresholds. Compliance deadlines are accelerating capital replacement cycles, with Guangdong environmental bureaus enforcing stricter local standards than national baselines and pushing exporters toward carbon-border readiness.
Specification influence is migrating from wholesale distributors to design-oriented digital platforms serving renovation contractors and retail consumers. Online channels now capture significant replacement demand volume in tier-one cities, compressing traditional bulk procurement cycles and forcing manufacturers to maintain dual inventory strategies for project and retail fulfillment.
China Ceramic Market Segmentation
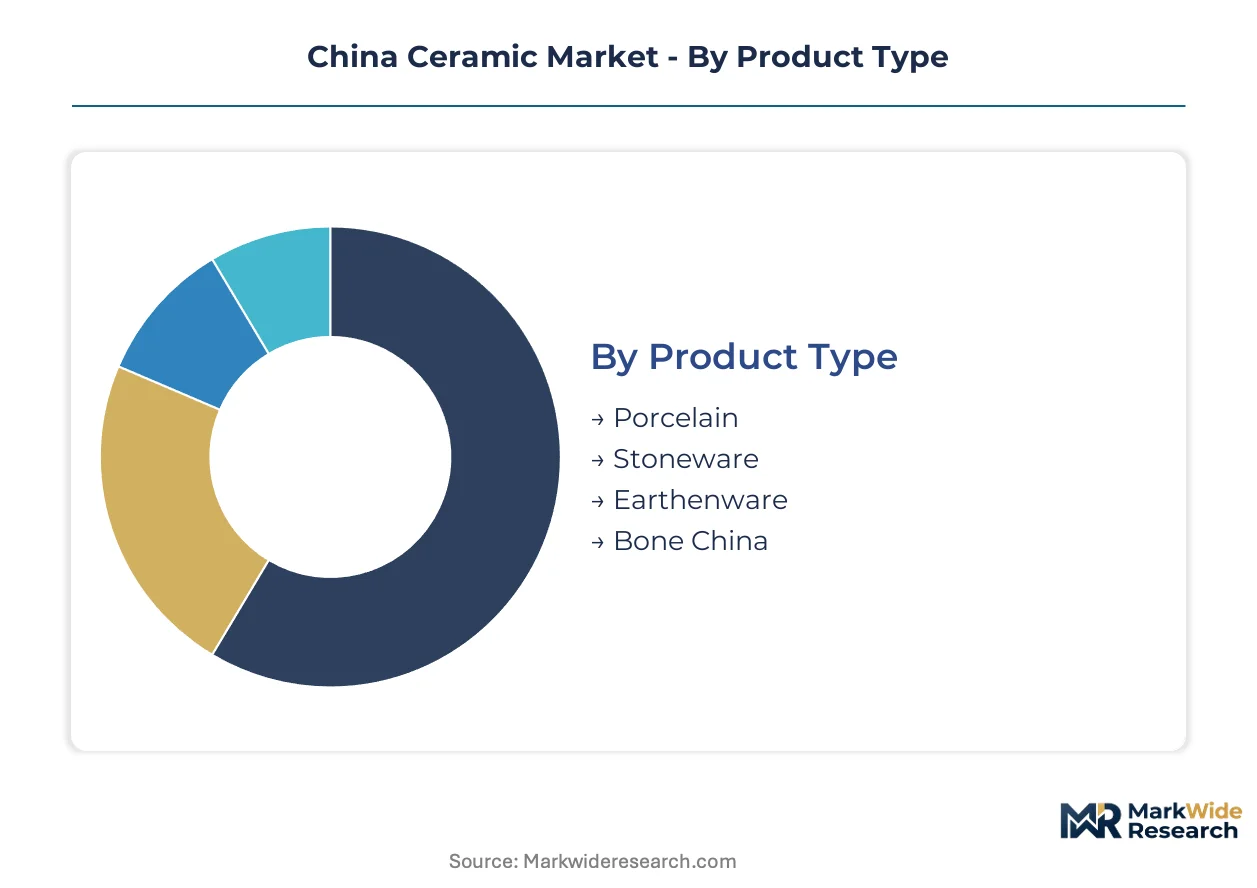
Segmentation in China's ceramic sector reveals how divergent technical specifications and end-use requirements fragment manufacturing capabilities. Distinct firing temperatures, raw material purity standards, and surface finish specifications create natural boundaries between product categories that resist cross-segment competition.
Product Type:
Mature segments dominate volume while emerging formulations capture technology premiums in specialized applications.
- Porcelain:Dense vitrified ceramic with water absorption below 0.5% fired above 1,200°C, delivering mechanical strength for heavy-traffic flooring. Foshan and Chaozhou clusters supply Guangdong's construction pipeline, with MIIT GB standards certifying energy-efficient variants for green building projects.
- Stoneware:Semi-vitrified body with 0.5-3% absorption fired at 1,180-1,280°C, balancing durability with lower production energy than full vitrification. Shandong producers target mid-market tableware and garden pottery, constrained by thin-film surface finishing substitution in premium tableware specifications.
- Earthenware:Porous low-fire ceramic with decorative glaze emphasis serving craft and ornamental demand.
- Bone China:High-translucency formulation with bone ash content, concentrated in export-oriented tableware for hospitality procurement.
Porcelain handles the majority of throughput; bone china is the fastest mover on share.
Application:
Cost tier separation between structural building materials and decorative consumer goods determines margin architecture across the value chain.
- Tiles:Wall and flooring surfaces in formats from 300x300mm to 1,600x3,200mm, with large-format sintered stone panels displacing traditional porcelain in premium specifications. Tier-two city real estate development sustains volume pull for standard formats, while roller-kiln electrification investments concentrate in Foshan producers serving this segment.
- Sanitary Ware:Toilets, basins, and bathroom fixtures requiring glazed vitreous china or porcelain with specific water efficiency ratings. Urban residential renovation cycles and commercial hospitality buildouts in Chengdu-Chongqing corridor drive replacement demand, with water conservation GB standards elevating certified product premiums.
- Dinnerware:Table service ceramics spanning hotel procurement to retail consumer segments.
- Decorative Items:Ornamental and art ceramics with lower volume but higher per-unit value concentration.
Tiles command the dominant revenue position; sanitary ware is expanding most quickly on volume contribution.
End User:
Customer type fragmentation splits procurement patterns between project-scale construction and fragmented retail replacement cycles.
- Residential:Individual homeowners and renovation contractors purchasing for interior finishing and fixture replacement. Online platforms now capture significant replacement demand volume in tier-one cities, compressing traditional bulk procurement cycles and forcing dual inventory strategies.
- Commercial:Office, retail, and institutional buildouts with specification-driven procurement through architectural channels.
- Hospitality:Hotels, restaurants, and foodservice operations requiring durable, high-cycle tableware and sanitary fixtures.
- Industrial:Advanced ceramic substrates for thermal management and electrical insulation in manufacturing equipment.
Residential absorbs the largest volume share; hospitality is climbing the fastest on post-renovation cycle recovery.
Distribution Channel:
Supply concentration in coastal manufacturing clusters dictates logistics economics and channel viability for inland market penetration.
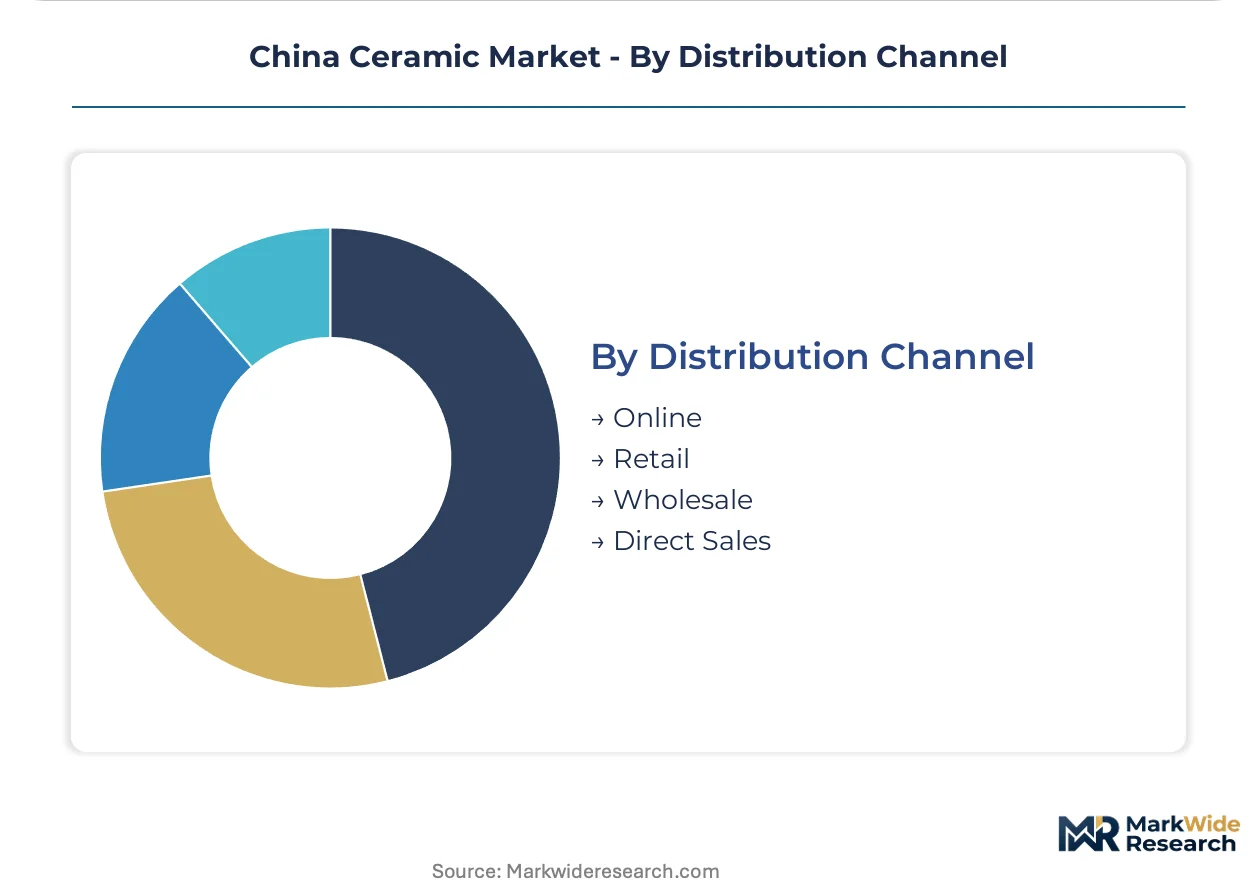
- Wholesale:Bulk procurement through distributor networks serving construction contractors and project developers. Retains structural importance for bulk construction procurement in tier-two and tier-three cities, though margin compression from distributor consolidation pressures manufacturer pricing power.
- Online:E-commerce platforms and direct-to-consumer digital channels. Gaining traction in replacement and renovation demand, with specification influence migrating from wholesale distributors to design-oriented digital platforms serving renovation contractors.
- Retail:Branded flagship stores and multi-brand showrooms for consumer selection and specification support.
- Direct Sales:Manufacturer-direct relationships with large project developers and hospitality chains.
Wholesale handles the majority of throughput; online is gaining share fastest on channel mix shift.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MIIT dual carbon goals redirect kiln technology investments toward electrification and waste-heat recovery across China's ceramic production bases. Provincial environmental bureaus enforce differentiated standards that reshape capital allocation patterns. Guangdong and Shandong clusters face the most stringent compliance timelines.
Guangdong Province
Foshan and Chaozhou ceramic clusters dominate national porcelain tile output for construction markets. MIIT GB 21252 energy consumption limits mandate waste-heat recovery installation and natural gas efficiency thresholds. Guangdong environmental bureaus enforce stricter local standards than national baselines, pushing exporters toward carbon-border readiness.
Shandong Province
Stoneware and sanitary ware producers target mid-market tableware and bathroom fixture demand. MEE enforcement of particulate and NOx limits imposes scrubber and filtration capex that squeezes margin structures for sub-scale operators. Zibo and Linyi production bases concentrate roller-kiln electrification investments to meet dual carbon compliance deadlines.
Sichuan-Chongqing Corridor
Chengdu-Chongqing infrastructure buildout opens distribution access for Sichuan and Jiangxi production bases previously constrained by coastal freight costs. Urban residential renovation cycles and commercial hospitality buildouts drive replacement demand for sanitary ware. Western China logistics corridor expansion enables inland manufacturers to compete in tier-two city procurement.
Jiangxi Province
Jingdezhen's historic ceramic heritage anchors decorative and art pottery production for domestic and export markets. High-purity alumina supply concentration creates input cost volatility for advanced ceramic substrate producers. Provincial industrial policy supports kiln electrification pilots to reduce emission intensity in traditional craft manufacturing.
Hebei Province
Beijing-Tianjin-Hebei integration drives sanitary ware demand from urban residential renovation and commercial office buildouts. SAMR quality certification requirements elevate compliance costs for smaller kiln operators. Tangshan production bases supply construction-grade porcelain tile for northern China infrastructure projects.
China Ceramic Market Competitive Landscape
On the supply side, the industry is consolidating around capital-rich incumbents capable of absorbing electrification and emission compliance investments. Fragmented mid-scale operators face asset stranding risks from legacy tunnel-kiln holdings. Three archetypes dominate: vertically integrated porcelain tile manufacturers, advanced ceramic substrate specialists, and premium decorative brand houses. Competitive moves concentrate on backward integration into raw material supply and strategic partnerships for green financing access.
Among Guangdong-based producers, Dongpeng Ceramic, Monalisa Group, and Guangdong Kito Ceramics Group occupy distinct positioning vectors. Dongpeng exemplifies the scale-driven integrated archetype with captive supply chain control across Foshan. Monalisa represents premium brand differentiation through flagship retail channel ownership. Guangdong Kito sits within the mid-tier efficiency-focused segment, balancing standard-format volume production with compliance upgrade requirements.
| Leading Market Players |
|---|
| Marco Polo Holdings |
| Sinoma Advanced Materials |
| Dongpeng Ceramic |
| Guangdong Xinruncheng Ceramics |
| Guangdong Kito Ceramics Group |
| Guangdong Newpearl Ceramic Group |
| GGS Ceramic |
| Foshan Shiwan Eagle Brand Ceramic |
| Monalisa Group |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Shandong's stoneware segment is compressing kiln utilization rates below breakeven thresholds, forcing distressed pricing from fragmented operators while Guangdong's electrified Foshan clusters capture premium spreads through MIIT-certified green product lines.
Pricing Analysis
GB standards certification level creates the primary spread between commodity tile and premium porcelain tiers. Three-tier pricing structure across premium, standard, and economy levels stratifies by energy-efficiency labeling and water absorption specifications. Cost compression in standard-format porcelain is intensifying because distributor consolidation concentrates buyer power. Project developers exhibit highest price sensitivity, while hospitality procurement prioritizes certified durability over unit cost.
Supply Chain Analysis
Export-control regimes on high-purity alumina from Australian and Indonesian sources are constraining advanced ceramic substrate flows to domestic EV component manufacturers. Geographic supply concentration centers on China, Vietnam, and India for clay body formulations and surface glaze chemicals. Raw material dependencies draw from kaolin deposits in Fujian, feldspar from Liaoning, and natural gas from Central Asian pipeline contracts. Single-source vulnerability in high-grade alumina imports threatens industrial-grade producers. Distribution runs through wholesale contractor networks in tier-two cities and emerging direct-to-platform fulfillment for renovation demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's ceramic sector is approaching a platform-economics inflection where specification influence migrates from distributor networks to design-oriented digital channels, rewiring how architects and contractors discover and procure finished materials.
For Market Incumbents: Insulate margin structures by accelerating captive supply of Foshan clay body formulations and securing SAMR quality certification ahead of enforcement waves. Sintered stone substitution in premium flooring specifications threatens porcelain tile addressable volume, making backward integration into raw material supply the priority defensive lever.
For New Entrants and Emerging Players: Pursue white-space opportunities in Chengdu-Chongqing corridor sanitary ware distribution, where western logistics infrastructure buildout has lagged coastal manufacturing penetration. Advanced ceramic substrates for EV thermal management represent the most penetrable segment, with automotive battery supply chains creating demand pull for alumina precision components.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across electrified kiln technology deployments, favoring acquisition of distressed mid-scale operators with stranded gas-fired assets over greenfield capacity additions. Target archetypes include Foshan-based porcelain tile producers with partial compliance upgrades and established wholesale channel relationships. Monitor MIIT enforcement differentiation between provincial environmental bureaus as the signal for consolidation velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Roller-Kiln Electrification | MIIT dual carbon compliance unlocks green financing for Foshan production base upgrades. |
| Waste-Heat Recovery Installation | GB 21252 energy consumption limits mandate retrofits that favor capital-rich incumbents. |
| Advanced Ceramic Substrate R&D | EV power electronics thermal management creates demand pull from domestic battery supply chains. |
| Digital Platform Distribution | Online specification channels capture renovation demand in tier-one cities from wholesale networks. |
| Western Logistics Corridor Expansion | Chengdu-Chongqing infrastructure buildout opens inland distribution access for Sichuan and Jiangxi bases. |
Research Methodology
A standing panel of kiln operations managers, ceramic tile procurement leads at construction developers, MIIT regulatory affairs specialists, and Foshan distributor network heads provided ongoing calibration across primary interview cycles. Secondary validation drew from MIIT GB standard filings, SAMR certification databases, Guangdong environmental bureau enforcement notices, and customs trade data for alumina imports. Bottom-up production capacity surveys triangulated against top-down construction spending projections.
Scenario-bracketing framed volume and value outputs across the projection horizon, with segmentation dimensions spanning product type, application, end user, and distribution channel. CAGRs derived from modeled kiln capacity utilization, electrification investment cycles, and tier-two city real estate development pipelines. Industry-specific forecast inputs incorporated MIIT compliance deadline phasing and carbon-border adjustment mechanism readiness.
Sensitivities concentrate around MIIT enforcement intensity variation between provincial environmental bureaus and high-purity alumina import cost volatility. Forecasts reflect assumptions on dual carbon goal implementation pace and sintered stone substitution rates in premium specifications. Material shifts in GB standards certification requirements or natural gas-to-electricity conversion subsidies would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Global Alumina Market
Ceramics
Clay Market
Ceramics
Asia-Pacific Ceramic Coatings Market
Ceramics
High Temperature Ceramics Market
Ceramics
Japan Ceramic Tiles Market
Ceramics
Liquid Sodium Silicate Market
Ceramics
Global Metal and Ceramic Injection Molding Market
Ceramics
Activated Alumina Market
Ceramics
Methyl Silicate Market
Ceramics
Glazed Ceramic Tile Market
Ceramics
Global Industrial Clay Market
Ceramics
Ceramic Injection Molding Market
Ceramics
Saudi Arabia Ceramic Tiles Market
Ceramics
Advanced Sintering Technologies Market
Ceramics
Traditional Ceramic Market
Ceramics
China Clay Market