
 Calcined Kaolin Market | 2026-2036
Calcined Kaolin Market Size, Share, and Industry Trends Forecast 2026-2036
Calcined Kaolin Market Analytics
High-brightness calcined kaolin is reorganizing competitive dynamics across the industrial minerals space. Imerys S.A. leverages its integrated mining-to-delivery infrastructure across multiple continents to sustain supply security for tier-one coatings customers. KaMin LLC anchors North American production with deep reserves in Georgia, while Sibelco competes through specialized fine-particle grades serving premium plastics applications in Western Europe.
Calcined kaolin refers to hydrous kaolin clay thermally treated at temperatures between 1,000°C and 1,200°C to remove structural hydroxyl groups, yielding an anhydrous aluminum silicate with controlled particle size distribution and oil absorption typically ranging from 45 to 60 grams per 100 grams. This transformation delivers enhanced opacity, electrical resistivity, and chemical inertness, making the material indispensable as a functional filler in paints, paper coatings, and engineered plastics where mechanical and barrier properties must balance against weight reduction targets. Among product types, high-performance kaolin commands the most concentrated margin pool due to its restricted supplier base and exacting brightness specifications above 90 percent GE, while calcined kaolin itself remains the volume anchor as paper coating mills in Asia-Pacific transition from hydrous alternatives. The rubber application segment shows the most pronounced structural momentum, driven by tire manufacturers reformulating compounds to meet rolling-resistance standards without sacrificing reinforcement.
Regulators including the EPA in the United States, ECHA under REACH in Europe, and China's MEE enforce particulate emission thresholds and chemical registration requirements that elevate compliance costs for calciner operations while simultaneously screening out lower-grade imports. These frameworks effectively tighten market access, concentrating supply among operators with verified environmental management systems and certified product stewardship programs. Stakeholders must monitor evolving classification debates around respirable crystalline silica content, as downstream liability standards in construction and consumer goods applications remain unsettled across major jurisdictions.
Market Dynamics
Thermal processing efficiency standards and automotive lightweighting mandates are compressing calciner margins while simultaneously expanding addressable volume for high-performance filler grades across plastics and rubber compounding.
Growth Catalysts
- REACH compliance in Europe:ECHA registration requirements for chemical substances are redirecting coating formulators toward calcined kaolin with verified low crystalline silica content.
- Automotive plastics substitution:Tire manufacturers in Germany and Japan are reformulating compounds to meet rolling-resistance standards using calcined kaolin as a partial carbon black replacement.
- China ceramics scaling:Domestic sanitaryware and tableware production in Guangdong and Fujian provinces is absorbing rising volumes of medium-brightness calcined grades.
Market Restraints
- Natural gas price volatility:Calcination energy intensity ties operational economics to input cost swings, particularly affecting European kiln operations.
- Georgia deposit concentration:Premium hydrous feedstock for North American calciners originates from a limited geological formation, creating supply security exposure.
- Precipitated calcium carbonate substitution:PCC advances in paper coating brightness and particle size are capturing share in magazine and catalog grades.
Strategic Opportunities
- India infrastructure buildout:BIS certification pathways for construction-grade calcined kaolin in cementitious applications remain underdeveloped relative to demand potential.
- Battery separator films:Ceramic-coated polyethylene separators for electric vehicle cells require ultra-fine calcined kaolin with controlled dielectric properties.
- EU Green Deal industrial incentives:Carbon border adjustment mechanisms favor low-emission calcination technologies, rewarding kiln electrification investments.
Industry Challenges
- Process control engineering talent:Retention of specialists capable of optimizing rotary kiln temperature profiles and residence time distribution is intensifying.
- ISO 14001 certification timelines:Major coatings customers now require eighteen-month environmental management system validation before supplier qualification.
- Legacy ERP integration:Real-time particle size distribution data from in-line laser diffraction sensors must interface with existing manufacturing execution systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Calcined Kaolin Market |
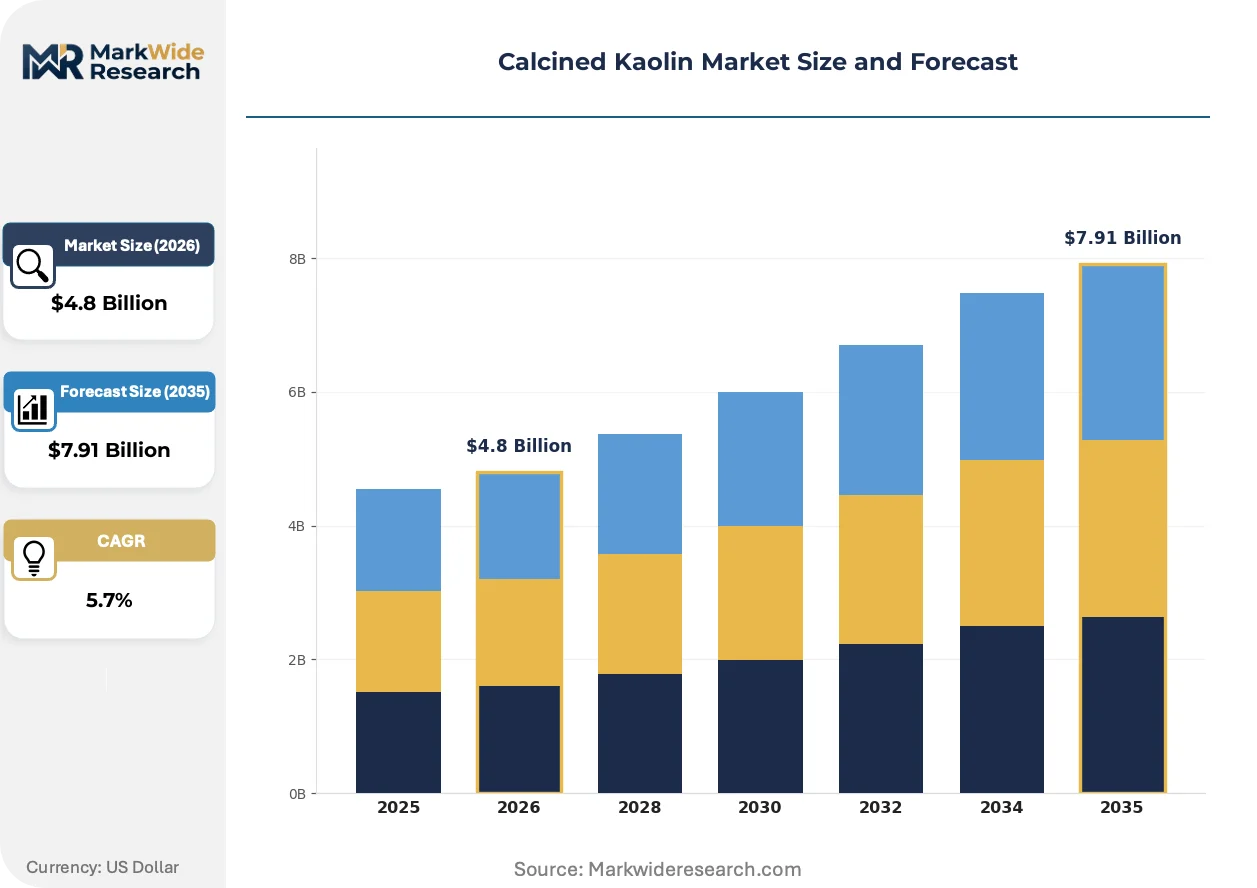
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrous Kaolin, Calcined Kaolin, High-Performance Kaolin, Ultra-White Kaolin Application: Paints, Paper Coatings, Plastics, Rubber End User: Construction, Automotive, Packaging, Consumer Goods Distribution Channel: Direct Sales, Distributors, Online Retailers, Brokers |
| Companies Covered | Imerys S.A., KaMin LLC, Sibelco, Thiele Kaolin Company, BASF SE, EICL Limited, Quarzwerke GmbH, Ashapura Group, Sedlecký Kaolin a.s., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Calcined Kaolin Market Evolving Landscape
Flash calcination and controlled atmosphere processing are redefining product performance boundaries while digital quality assurance systems compress batch-to-batch variability windows.
Advanced flash calcination technology using suspension heating rather than rotary kiln exposure is fragmenting traditional supply relationships. Tier-one plastics compounders in the US and Germany are qualifying these materials for thin-wall electrical connector housings. The shift is fragmenting established procurement patterns by enabling direct relationships between end-users and technology-licensed producers bypassing conventional distributor networks.
ECHA's ongoing crystalline silica classification review under REACH is forcing reformulation transparency across construction coatings. Industrial paint manufacturers must now document respirable silica content down to trace contamination levels. Western European architectural coatings producers are responding by consolidating supplier bases to those with certified low-silica calcination protocols.
Specification-driven procurement through centralized technical buying desks is displacing traditional regional purchasing autonomy. Automotive OEMs in Stuttgart and Detroit now mandate corporate-level filler approval before plant-level sourcing. This concentration is most visible in tire manufacturing where compound standardization across multinational production networks overrides local supplier preferences.
Calcined Kaolin Market Segmentation
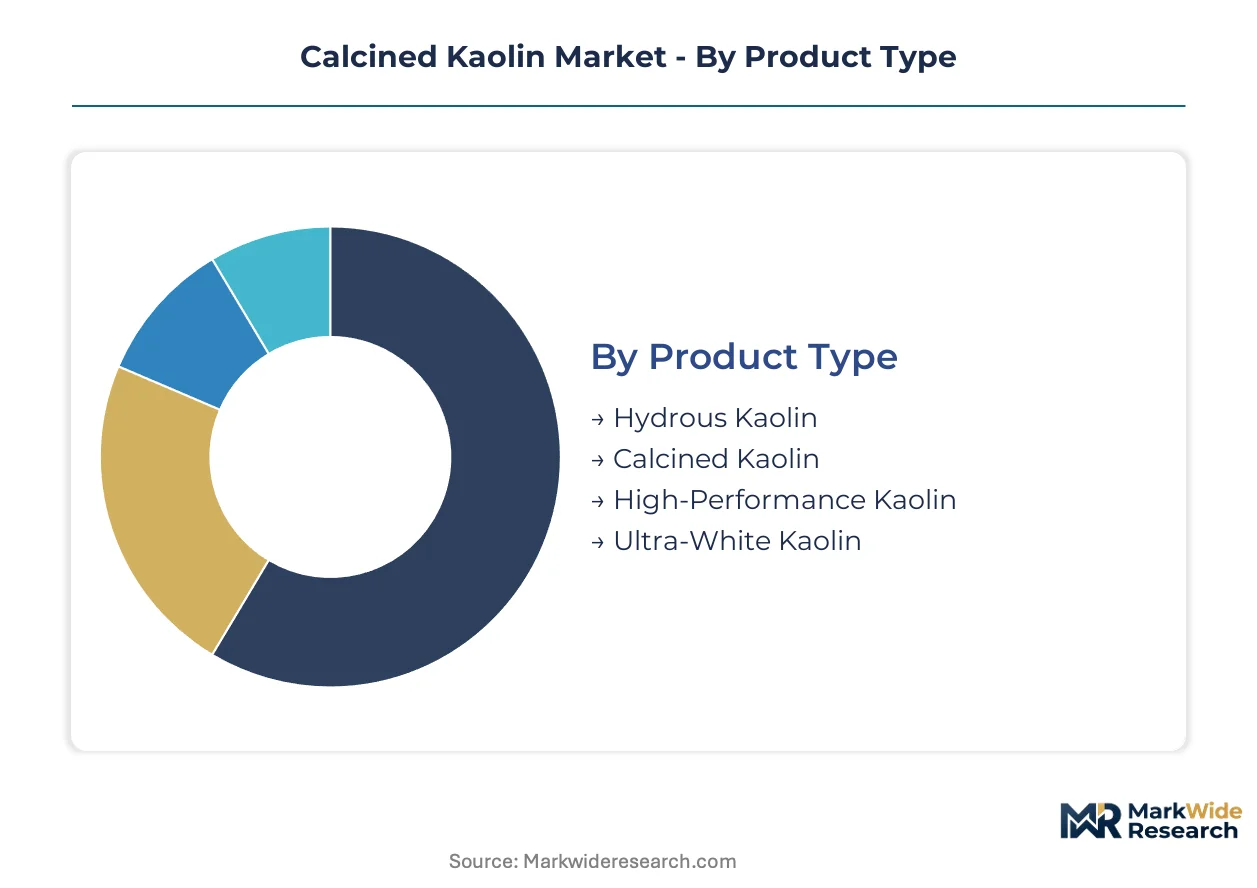
Calcined kaolin procurement increasingly hinges on specification-grade matching rather than commodity sourcing, as regulatory thresholds for crystalline silica content and brightness parameters fragment what was historically a uniform mineral category. End-users now segment suppliers by certified compliance pathways rather than price alone, reshaping how volumes flow through direct versus intermediary channels.
Product Type:
ECHA's REACH crystalline silica classification and China's GB standards for ceramic raw materials enforce divergent purity requirements that elevate certain thermal treatment grades above commodity alternatives.
- Calcined Kaolin:Thermally treated at 1,000°C–1,200°C to remove structural hydroxyl groups, yielding anhydrous aluminum silicate with oil absorption of 45–60 g/100g. Paper coating mills in China absorb the largest volumes as domestic production scales in Guangdong and Fujian provinces, though natural gas price volatility compresses calciner margins across European kiln operations.
- High-Performance Kaolin:Engineered to brightness specifications above 90 percent GE with restricted particle size distribution. Tire manufacturers in Germany and Japan qualify these grades for rolling-resistance compound reformulation, creating concentrated margin pools due to limited supplier bases with verified low-silica protocols.
- Hydrous Kaolin:Unprocessed clay retaining structural water, serving as feedstock for thermal treatment rather than direct functional filler application.
- Ultra-White Kaolin:Premium brightness grade targeting specialized coatings and cosmetic applications where optical properties override cost considerations.
Established volume favors calcined kaolin; emerging adoption favors high-performance kaolin.
Application:
Cost tier differentiation separates specification-driven automotive procurement from price-sensitive construction coatings, with mid-tier packaging applications exhibiting mixed sourcing patterns.
- Rubber:Partial carbon black replacement in tire compounding delivers rolling-resistance compliance without sacrificing reinforcement. Compound standardization across multinational production networks in Stuttgart and Detroit now mandates corporate-level filler approval before plant-level sourcing.
- Plastics:Functional filler for engineered polymers requiring mechanical and barrier properties balanced against weight reduction targets. Tier-one US and German plastics compounders qualify flash-calcined materials for thin-wall electrical connector housings.
- Paints:Opacity and scrub resistance in architectural and industrial coatings, with ECHA's silica review forcing respirable content documentation down to trace contamination levels.
- Paper Coatings:Brightness and printability enhancement, though precipitated calcium carbonate substitution captures share in magazine and catalog grades.
Automotive specification intensity concentrates procurement in rubber; packaging cost pressures sustain volume in paints.
End User:
Customer type maturity separates legacy construction procurement from emerging electric vehicle supply chain integration, with packaging serving as the volume bridge between specification extremes.
- Automotive:OEM technical buying desks in Stuttgart and Detroit now centralize filler approval, overriding regional purchasing autonomy. Battery separator film applications for electric vehicle cells require ultra-fine calcined kaolin with controlled dielectric properties.
- Construction:Cementitious applications in India remain underdeveloped relative to infrastructure demand potential, with BIS certification pathways still maturing.
- Packaging:Container and label coatings absorb medium-brightness grades where performance specifications tolerate broader particle distribution.
- Consumer Goods:Tableware and sanitaryware production scales in China, absorbing rising volumes of domestically produced calcined grades.
Construction volume dominates current offtake; automotive applications are climbing the fastest.
Distribution Channel:
Supply concentration geography favors direct relationships in premium grades while fragmented construction markets sustain intermediary networks.
- Direct Sales:Tier-one coatings and plastics compounders consolidate supplier bases to operators with ISO 14001 certification and eighteen-month environmental management validation. Flash calcination technology licensing enables end-users to bypass conventional distributor networks.
- Distributors:Regional construction coatings markets in Europe and North America rely on established mineral distribution networks for medium-brightness grades.
- Brokers:Spot market facilitation for variable-quality feedstock and small-volume specialty orders.
- Online Retailers:Emerging channel for sample procurement and small-laboratory quantities, though bulk industrial volumes remain offline.
Direct relationships capture specification-grade margins; distributor networks retain construction market access.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in China demonstrate the highest price elasticity as domestic calcination capacity scales, while German automotive compounders absorb premium-grade premiums with minimal volume sensitivity. This demand-elasticity contrast shapes regional procurement strategies and supplier qualification timelines.
China
Guangdong and Fujian provinces drive consumption as sanitaryware and tableware manufacturers scale domestic production. MEE enforcement of particulate emission thresholds elevates compliance costs for kiln operators while screening lower-grade imports. The Pearl River Delta concentrates medium-brightness calcined grade absorption as paper coating mills transition from hydrous alternatives.
Germany
Tire manufacturers in Stuttgart reformulate compounds to meet rolling-resistance standards using high-performance filler grades. ECHA REACH registration requirements redirect formulators toward calcined kaolin with verified low crystalline silica content. The Baden-Württemberg automotive cluster anchors corporate-level filler approval mandates that override regional purchasing autonomy.
United States
Georgia's deep hydrous kaolin reserves feed North American calcination capacity, though geological concentration creates supply security exposure. EPA particulate emission standards tighten market access for operators lacking certified environmental management systems. The Southeast industrial corridor sustains volume demand from plastics compounders seeking lightweight filler materials.
India
Infrastructure buildout potential remains underdeveloped relative to cementitious application demand. BIS certification pathways for construction-grade calcined kaolin lag behind market readiness, creating qualification bottlenecks. Maharashtra and Gujarat industrial zones absorb spot volumes through distributor networks pending standardization.
Japan
Tire producers qualify high-performance grades for rolling-resistance compliance alongside German counterparts. METI industrial standards enforce consistent quality benchmarks for imported filler materials. The Kansai manufacturing belt concentrates technical buying desk influence over regional procurement decisions.
Calcined Kaolin Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, fragmenting competitive dynamics across the calcined kaolin space. Integrated mining-to-delivery operators command supply security premiums from tier-one coatings customers. Specialized fine-particle producers capture concentrated margin pools in premium plastics applications. Flash calcination technology licensors and traditional rotary kiln operators represent the primary competitive divide, with capacity expansion and environmental certification acceleration dominating strategic moves.
Among France-based industrial mineral conglomerates, Imerys S.A. exemplifies the integrated archetype spanning multiple continents. KaMin LLC and Thiele Kaolin Company occupy positions within the North American reserve-based tier, anchoring regional supply security narratives. Sibelco represents the specialized European fine-particle positioning, while BASF SE sits within diversified chemical portfolios where calcined kaolin serves as a functional filler segment among broader material offerings.
| Leading Market Players |
|---|
| Imerys S.A. |
| KaMin LLC |
| Sibelco |
| Thiele Kaolin Company |
| BASF SE |
| EICL Limited |
| Quarzwerke GmbH |
| Ashapura Group |
| Sedlecký Kaolin a.s. |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts between Georgia-based calciners and tier-one coatings manufacturers lock in multi-year supply access while anchoring price visibility against natural gas volatility swings. These arrangements concentrate procurement power among buyers with verified ISO 14001 certification, forcing spot-market participants to absorb sharper margin compression during energy price spikes.
Pricing Analysis
REACH registration requirements under ECHA dictate the pricing tier structure across European markets, separating certified low-silica grades from commodity alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects brightness specifications above 90 percent GE, ECHA compliance verification, and volume scale commitments. Cost compression in standard grades is intensifying because precipitated calcium carbonate captures paper coating share, while automotive compounders in Stuttgart show minimal price sensitivity for high-performance filler grades. Packaging coatings buyers in Asia-Pacific demonstrate the highest elasticity, pivoting between domestic Chinese supply and imported alternatives on quarterly cost comparisons.
Supply Chain Analysis
Inventory buffers at rotary kiln operations typically cover six to eight weeks of feedstock, creating vulnerability during Georgia deposit disruptions or shipping delays through Savannah port corridors. Supply concentrates in the United States, China, and Brazil, with premium hydrous feedstock drawn from Georgia's limited geological formation. Energy inputs—natural gas for calcination, diesel for mining operations, and electricity for particle classification—represent the dominant cost stack. Single-source vulnerability runs through Georgia's sedimentary kaolin belt, where geological concentration creates irreplaceable feedstock access. Distribution runs through direct sales channels for specification grades and regional mineral distributors for construction coatings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Calcined kaolin incumbents face sustained substitution pressure from precipitated calcium carbonate in paper coatings and engineered silicas in premium plastics, requiring defensive repositioning around certification barriers and supply security guarantees.
For Market Incumbents: Shield margin pools by accelerating kiln electrification investments ahead of EU carbon border adjustments, and deepen backward integration into captive Georgia feedstock reserves to neutralize supply security exposure from geological concentration. Flash calcination technology licensing offers channel control against distributor disintermediation by tier-one plastics compounders. For New Entrants and Emerging Players: Lead with battery separator film qualification for electric vehicle cell manufacturers, where ultra-fine dielectric-grade supply remains constrained and technical barriers limit incumbent expansion. India's cementitious applications present the most penetrable geography, with BIS certification pathways still maturing relative to infrastructure demand. Direct technical selling to automotive OEM buying desks in Stuttgart and Detroit bypasses entrenched distributor relationships. For Investors and Strategic Acquirers: Capital is best deployed toward integrated mining-to-calcination operators with verified environmental management systems and multi-continent logistics footprints, as these assets command supply security premiums from consolidating coatings customers. Long-term viability hinges on electrification capex execution and crystalline silica classification navigation under REACH. The signal to monitor is flash calcination adoption rates among tier-one compounders, which would accelerate technology-licensing revenue models over traditional volume-based supply.| Strategic Initiative | Industry Significance |
|---|---|
| Kiln Electrification Investment | EU carbon border adjustments reward low-emission calcination, securing qualification for Green Deal industrial incentives. |
| Backward Integration into Feedstock Reserves | Captive Georgia hydrous kaolin access neutralizes supply security exposure from geological concentration in a single formation. |
| Flash Calcination Technology Licensing | Direct end-user relationships with US and German plastics compounders fragment traditional distributor procurement patterns. |
| Battery Separator Film Qualification | Ceramic-coated polyethylene separator demand from electric vehicle cell manufacturers opens ultra-fine grade margin pools. |
| REACH Low-Silica Certification Acceleration | ECHA registration requirements redirect coating formulators toward verified protocols, consolidating supplier bases. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs trade data, SEC filings from industrial mineral conglomerates, ECHA registration databases, and Association of China Ceramics production statistics. Primary interviews encompassed rotary kiln operations managers, procurement leads at tire manufacturers in Stuttgart and Detroit, technical buying desk directors at automotive OEMs, and distribution channel partners across European coatings markets. Bottom-up volume modeling from individual calciner capacity and top-down demand triangulation from end-use consumption patterns were cross-validated for consistency.
Segmentation dimensions modeled include product type tier, application end-use, brightness specification grade, and regional regulatory cluster across the analysis window. CAGRs were derived from slope analysis of historical consumption trajectories and projected formulation shifts in automotive compounding. Key forecast inputs incorporated natural gas price scenarios for kiln economics, ECHA crystalline silica classification timelines, and battery separator film adoption curves in electric vehicle manufacturing.
The analysis sits within stated boundaries; outcomes outside sustained automotive lightweighting mandates, stable REACH enforcement trajectories, or continued Georgia feedstock accessibility would require recalibration. Forecasts reflect documented assumptions around energy input costs and regulatory compliance pathways. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Advanced Structural Ceramics Market
Ceramics
Global Magnesium Silicate Market
Ceramics
Global Ceramic Coating Market
Ceramics
Aluminium Nitride Market
Ceramics
Zirconium Dioxide Market
Ceramics
Glass Ceramics Market
Ceramics
Germany Ceramic Tiles Market
Ceramics
Global Wollastonite Powder Market
Ceramics
Ceramics Market
Ceramics
Titanates Market
Ceramics
Construction Ceramics Market
Ceramics
Ceramic Fabrication Services Market
Ceramics
Automotive Ceramics Market
Ceramics
Ceramics Packaging Market
Ceramics
Potassium Feldspar Market
Ceramics
Europe Activated Alumina Market