
 Glazed Bricks Market | 2026-2036
Glazed Bricks Market Size, Share, and Industry Trends Forecast 2026-2036
Glazed Bricks Market Analysis
Poland's expanding brick manufacturing corridor is reshaping supply dynamics across Central Europe. Wienerberger AG leverages its integrated clay-to-glaze operations across multiple kilns in the region to sustain margin control. Ibstock Brick Limited anchors its position through specialized firing techniques that differentiate output for premium facade contracts. CRH plc competes on scale, operating one of the continent's largest automated glazing lines to occupy volume-tier segments.
Glazed bricks are clay or concrete masonry units coated with mineral-based glass-forming compounds, then fired at temperatures exceeding 1000°C to create impervious, color-stable surfaces resistant to weathering and chemical exposure. Their primary purpose is protective and aesthetic envelope cladding for buildings requiring low maintenance and high thermal mass. Standard glazed bricks dominate residential facade applications where cost predictability matters, while custom glazed bricks command margin pools in boutique commercial and heritage restoration projects where architects specify unique chromatic ranges. Clay-based formulations retain leadership in load-bearing wall systems, though concrete substrates are gaining specification in non-structural rainscreen assemblies.
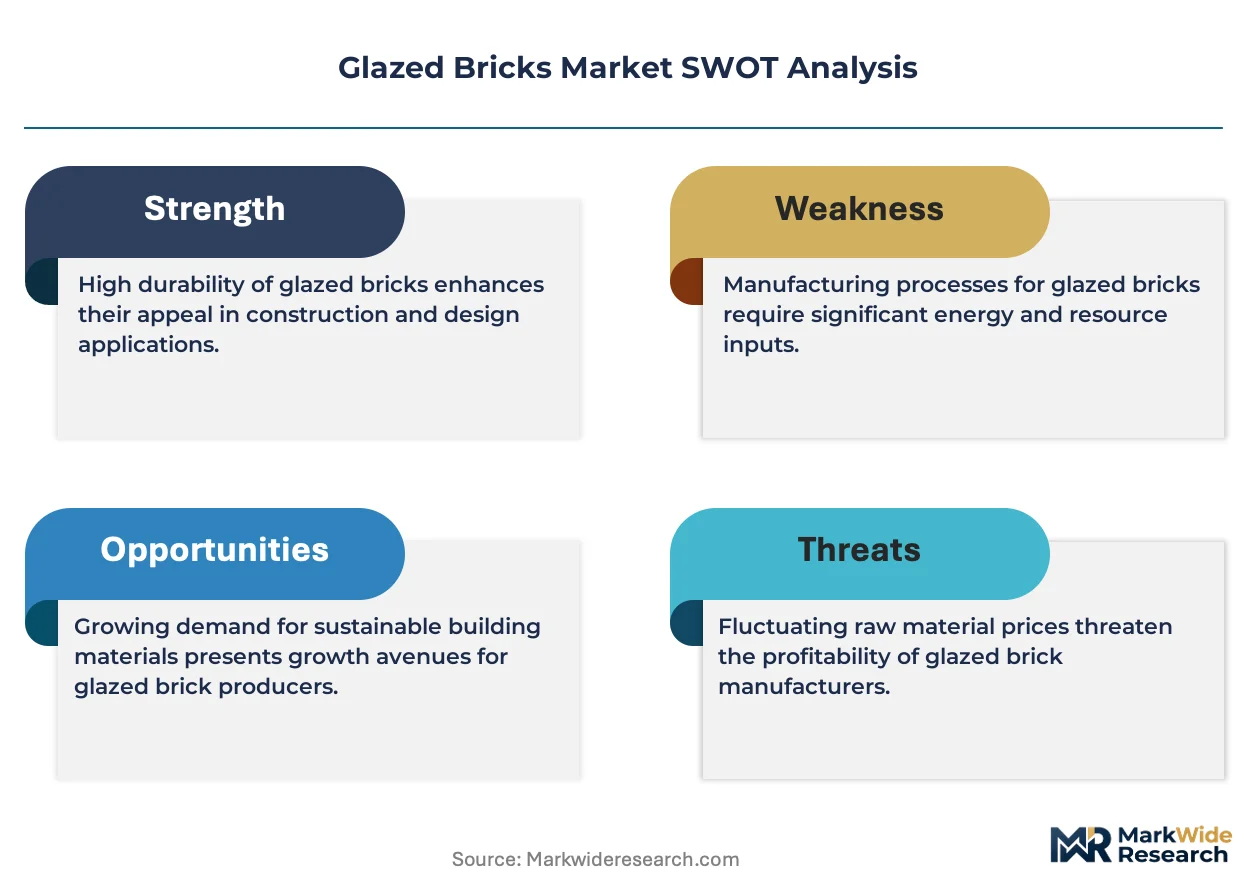
EU Ecodesign requirements and national building codes in Germany, France, and Poland are mandating lower thermal transmittance values, pushing manufacturers to certify insulating glazed brick variants under harmonized EN standards. REACH compliance for glaze chemistry restricts certain heavy metal colorants, redirecting R&D investment toward mineral-derived pigment alternatives. Stakeholders must monitor how the EU Green Deal's embodied carbon thresholds for construction products reshape material specifications and kiln energy sourcing decisions across the value chain.
Market Dynamics
EU Green Deal embodied carbon thresholds are forcing kiln operators to restructure fuel sourcing and glaze chemistry, compressing margins for manufacturers without captive clay reserves or renewable energy contracts.
Growth Catalysts
- EU Ecodesign thermal performance mandates:Harmonized EN standards for insulating glazed brick variants are pulling specification upgrades across German and Polish residential construction.
- Urbanization corridor expansion:Housing starts between Warsaw and Krakow are absorbing record volumes of facade-grade glazed brick for multi-family envelopes.
- Mineral-derived pigment innovation:REACH-compliant alternatives to heavy metal colorants are unlocking heritage restoration contracts previously blocked by chemical restrictions.
Market Restraints
- Natural gas price volatility:Kiln firing costs fluctuate with European energy markets, squeezing operators lacking long-term power purchase agreements.
- Clay deposit geographic concentration:Premium kaolin reserves cluster in specific Polish and German basins, creating supply vulnerability for peripheral manufacturers.
- Concrete rainscreen substitution:Lightweight concrete cladding systems are capturing specification share in non-structural commercial facades.
Strategic Opportunities
- Carbon-negative glaze formulations:Bio-based flux agents and waste-derived colorants align with EU Green Deal procurement preferences for public buildings.
- Heritage restoration specialization:Boutique chromatic matching services command premium positioning in French monument conservation contracts.
- Direct-to-developer digital channels:Online specification platforms are disintermediating traditional merchant distributors for mid-scale Polish housing projects.
Industry Challenges
- Kiln engineer talent scarcity:Specialized firing technicians with expertise in controlled atmosphere glazing are retiring faster than training programs replace them.
- EN standard certification timelines:New insulating brick variants face 18-24 month testing cycles before market entry.
- Legacy ERP integration:Automated glazing lines require data architecture upgrades incompatible with decades-old production management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glazed Bricks Market |
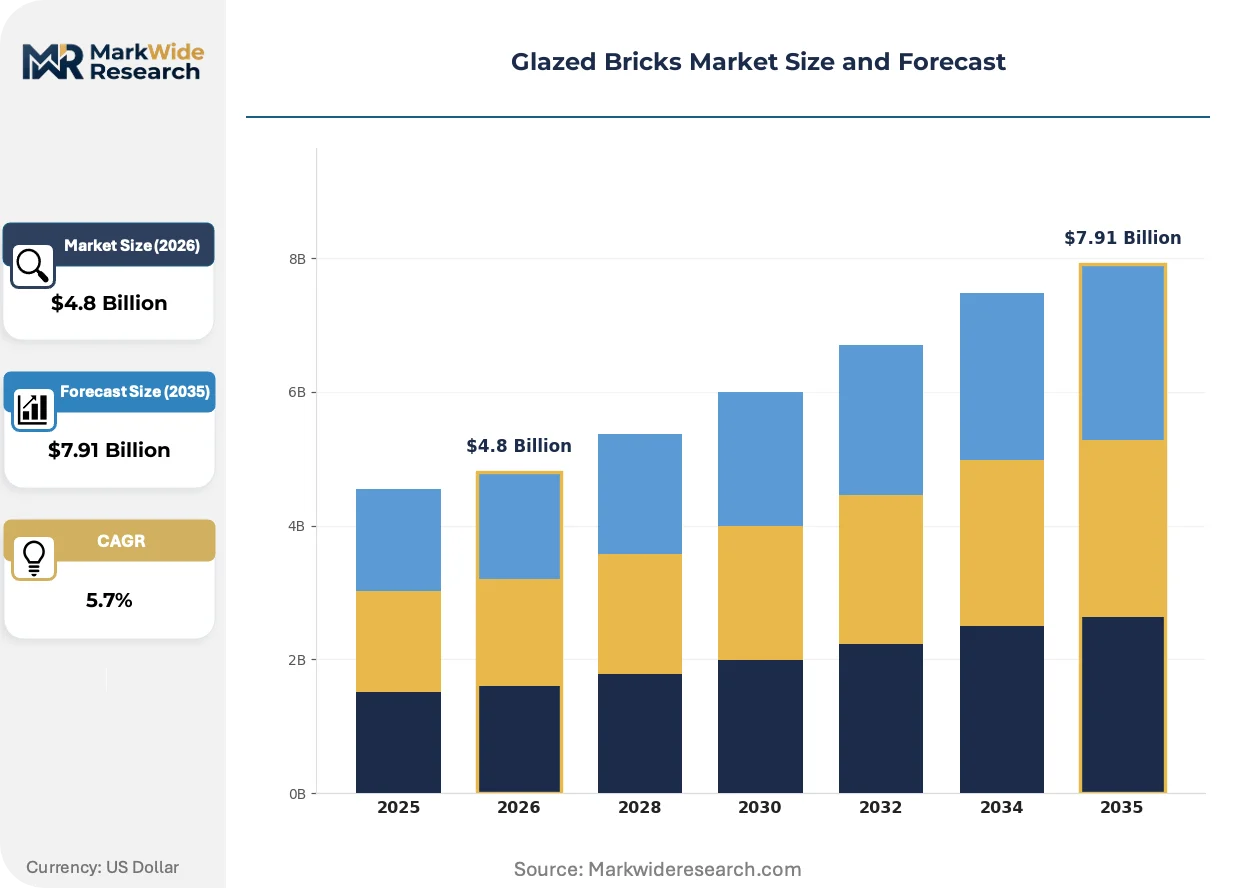
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Glazed Bricks, Insulating Glazed Bricks, Custom Glazed Bricks, Decorative Glazed Bricks Application: Facade Cladding, Flooring, Landscaping, Interior Walls End User: Residential Buildings, Commercial Buildings, Industrial Structures, Public Infrastructure Material: Clay, Concrete, Refractory, Others |
| Companies Covered | Wienerberger AG, Ibstock Brick Limited, Acme Brick Company, Glen-Gery Corporation, General Shale Brick, Inc., Boral Limited, CRH plc, Brickworks Limited, Michelmersh Brick Holdings PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glazed Bricks Market Emerging Trajectories
Digital specification tools and low-carbon process innovations are compressing traditional decision cycles while opening new competitive axes beyond unit cost.
Computational glaze formulation software is virtualizing the traditional trial-and-error firing process. German and Austrian manufacturers deploy these platforms to compress new color development from months to weeks. The technology is virtualizing R&D cost structures for mid-tier producers previously locked out of custom color markets.
REACH Annex XVII restrictions on lead and cadmium pigments are redirecting formulation investment toward rare-earth and iron-oxide alternatives. ECHA compliance deadlines are accelerating substitution timelines for red and orange chromatic ranges. Polish manufacturers with early mineral partnership agreements are securing preferential pigment supply positions.
Architects are consolidating specification authority through centralized procurement platforms that aggregate volume across multiple projects. Traditional merchant distributors in France and Belgium are losing influence to these digital intermediaries. The shift is most visible in commercial facade contracts where design-build contracts compress material selection windows.
Glazed Bricks Market Segmentation
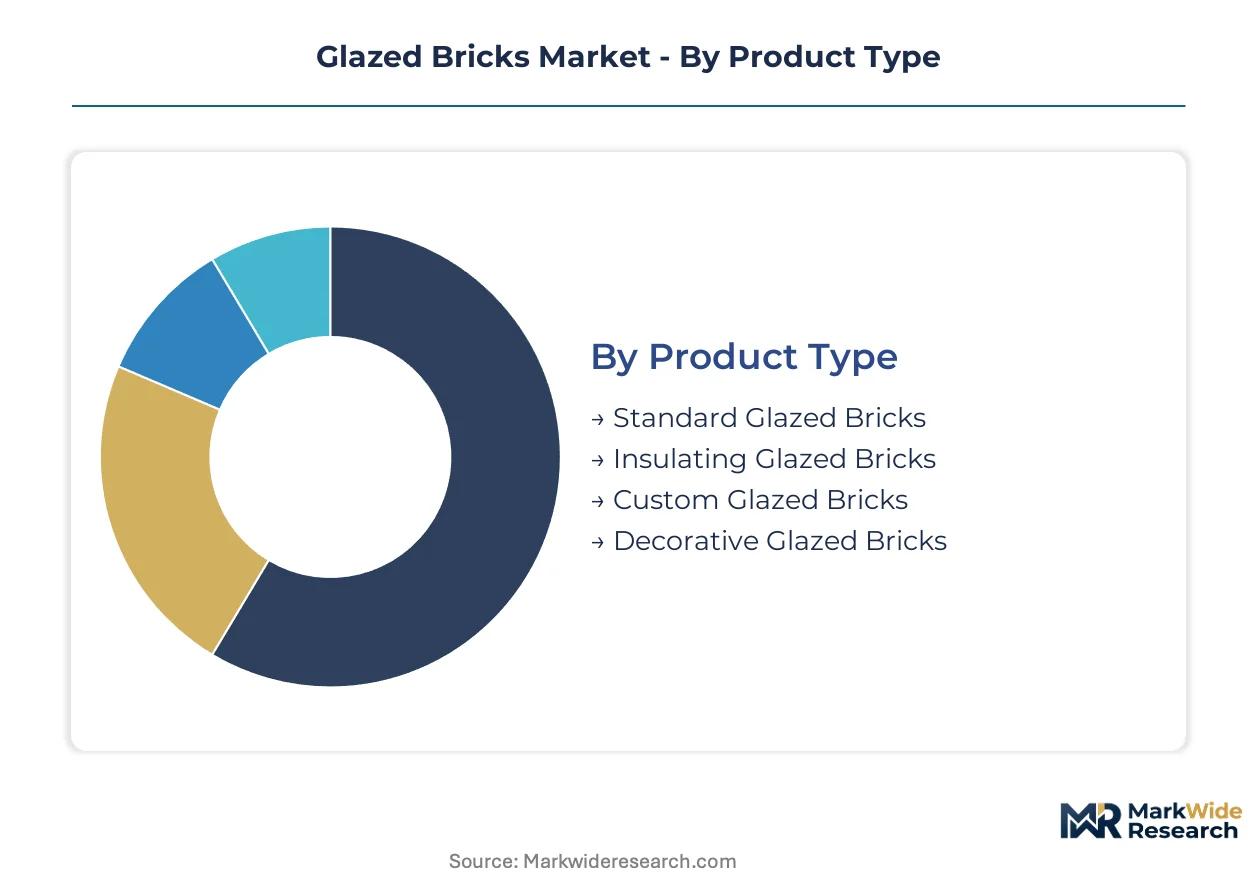
Glazed brick segmentation reveals how manufacturers align product portfolios with divergent performance requirements across thermal envelopes, aesthetic specifications, and structural loads. Distinct formulation and firing approaches separate commodity volume plays from premium positioning strategies.
Product Type:
Use-case spectrum spans mass-market residential envelopes to bespoke architectural statements, with thermal performance mandates creating new intermediate tiers.
- Standard Glazed Bricks:Mineral-coated clay units fired at 1000°C-plus temperatures deliver weather-resistant facades with predictable color stability. German and Polish housing developers specify these for multi-family residential blocks where cost certainty outweighs customization needs, though EU Ecodesign thermal transmittance thresholds are pushing specification toward insulating variants.
- Insulating Glazed Bricks:Engineered substrates with integrated thermal breaks and low-conductivity glaze formulations achieve harmonized EN standard certification for high-performance envelopes. Demand concentrates in Warsaw-Krakow corridor housing starts where building code enforcement is tightening fastest, with 18-24 month certification timelines creating supply bottlenecks for early movers.
- Custom Glazed Bricks:Boutique chromatic matching and non-standard dimensions serve heritage restoration and signature commercial facades.
- Decorative Glazed Bricks:Surface-optimized variants prioritize aesthetic texture over structural performance for interior and landscaping applications.
Established volume favors Standard Glazed Bricks; emerging adoption favors Insulating Glazed Bricks.
Application:
Functional role determines substrate selection, firing intensity, and surface engineering priorities across building envelope zones.
- Facade Cladding:Exterior-grade glazed bricks withstand freeze-thaw cycling, UV exposure, and airborne pollutants through dense vitreous surfaces. French and Belgian commercial specifications increasingly require REACH-compliant mineral pigments rather than legacy heavy metal colorants, redirecting R&D investment toward rare-earth alternatives.
- Flooring:Abrasion-resistant glaze formulations with enhanced Mohs hardness ratings serve high-traffic commercial and industrial installations.
- Landscaping:Frost-resistant units with textured slip-resistant surfaces address pedestrian pathways and retaining wall applications.
- Interior Walls:Lower-fired decorative glazes prioritize aesthetic range over weathering resistance for climate-controlled environments.
Facade Cladding commands premium pricing power; Interior Walls deliver volume throughput for kiln capacity utilization.
End User:
Procurement authority and specification complexity vary sharply across owner types, from centralized public procurement to fragmented residential development.
- Residential Buildings:Multi-family developers in Poland's urbanizing corridor drive standardized bulk procurement with compressed decision cycles. Direct-to-developer digital platforms are disintermediating traditional merchant distributors for mid-scale Warsaw housing projects, compressing margins but accelerating volume capture.
- Commercial Buildings:Design-build contracts with architect-led specification concentrate authority in centralized procurement platforms. French and Belgian distributors are losing influence to these digital intermediaries as material selection windows narrow.
- Industrial Structures:Chemical-resistant glaze specifications serve manufacturing facilities with aggressive atmospheric exposure.
- Public Infrastructure:EU Green Deal procurement preferences for embodied carbon thresholds favor bio-based flux agents and waste-derived colorants in German municipal contracts.
Residential Buildings anchor current volume; Public Infrastructure offers steepest expansion trajectory under green procurement mandates.
Material:
Substrate chemistry determines load-bearing capacity, firing energy intensity, and compatibility with emerging low-carbon process innovations.
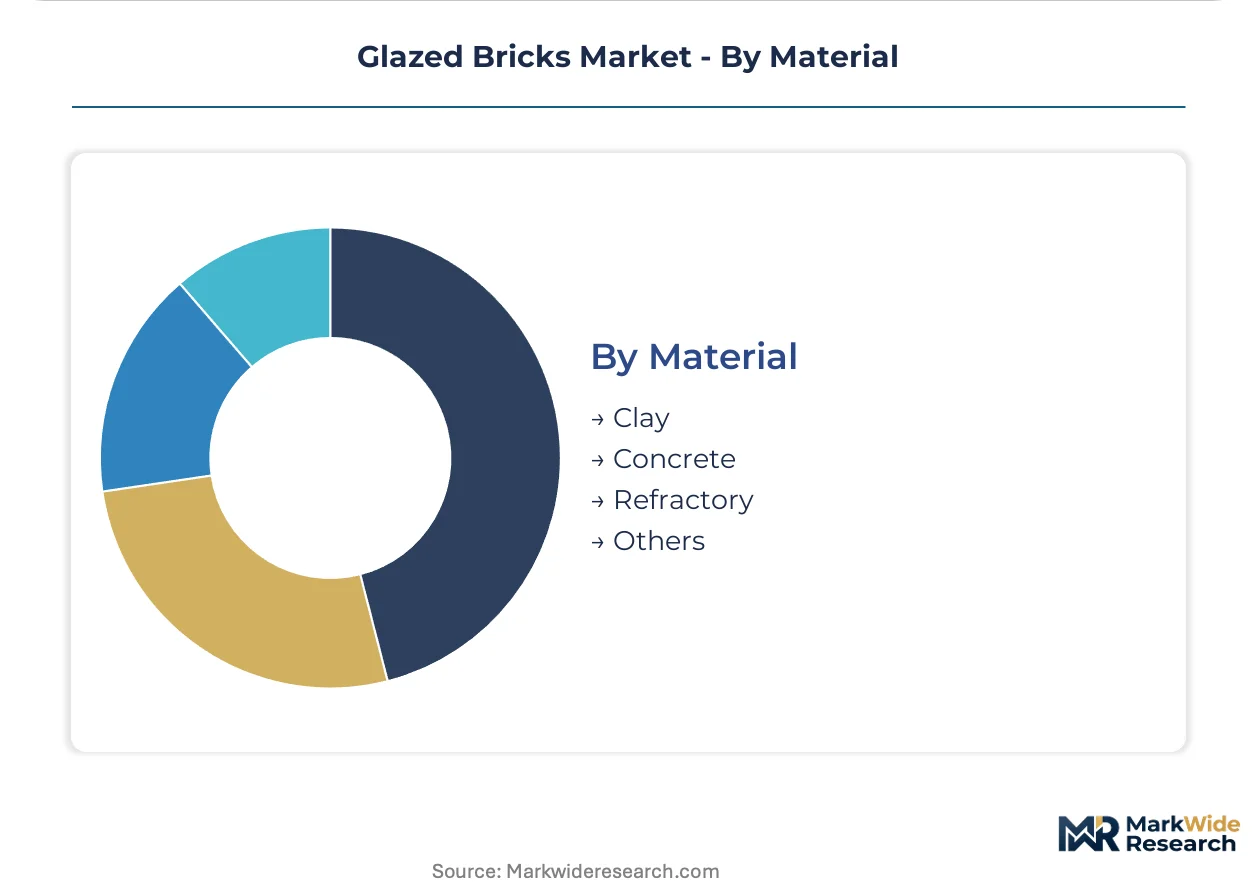
- Clay:Kaolin-based formulations retain leadership in load-bearing wall systems where thermal mass and compressive strength are specified. Premium deposits cluster in specific Polish and German basins, creating supply vulnerability for peripheral manufacturers without captive reserves or long-term extraction agreements.
- Concrete:Lightweight substrates are gaining specification in non-structural rainscreen assemblies where reduced dead load offsets higher embodied carbon. Austrian and German manufacturers deploy these for commercial facades where structural framing economics favor cladding over masonry.
- Refractory:High-alumina compositions serve extreme temperature industrial applications beyond standard architectural specifications.
- Others:Experimental substrates including recycled glass and industrial waste streams are piloting under EU circular economy funding mechanisms.
Clay dominates structural applications; Concrete is climbing fastest in commercial rainscreen specification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany consumes glazed bricks primarily for high-performance thermal envelopes, while Poland deploys them for cost-efficient multi-family housing volume, creating divergent specification patterns across Central Europe.
Germany
Multi-family developers in Berlin and Munich specify insulating glazed brick variants to meet federal building energy efficiency ordinances. The EU Green Deal's embodied carbon thresholds pressure kiln operators in North Rhine-Westphalia to secure renewable power purchase agreements. Industrial clay processing clusters around the Westerwald basin sustain captive supply chains for facade-grade manufacturers.
Poland
Housing starts between Warsaw and Krakow absorb record volumes of standard glazed bricks for rapidly urbanizing residential corridors. National building codes aligning with EU Ecodesign directives accelerate demand for thermally certified variants. Clay deposit concentration in Lower Silesia enables integrated clay-to-glaze operations that control input costs for regional producers.
France
Heritage restoration contracts in Paris and Lyon drive specification of custom chromatic ranges for monument conservation projects. REACH Annex XVII restrictions on heavy metal pigments redirect formulation investment toward rare-earth alternatives. Commercial facade procurement platforms are consolidating specification authority away from traditional merchant distributors in the Île-de-France region.
Belgium
Design-build commercial contracts in Brussels and Antwerp compress material selection windows, favoring digital specification platforms. EU Ecodesign thermal transmittance mandates push envelope specifications toward insulating variants. Cross-border supply relationships with Dutch and German manufacturers create competitive pricing pressure for domestic kiln operators.
Austria
Computational glaze formulation software adoption among Viennese manufacturers compresses new color development timelines from months to weeks. The country's national building regulator enforces harmonized EN standards for high-performance envelopes. Alpine region clay deposits support specialized firing operations for premium facade applications.
Glazed Bricks Market Vendor Landscape
Capability concentration sits with integrated clay-to-glaze specialists; scale advantage sits with diversified building materials conglomerates. The market structures around three tiers: captive-reserve integrated manufacturers, boutique chromatic specialists, and volume-tier automated producers. Strategic moves center on securing long-term clay extraction agreements and deploying digital specification platforms to bypass traditional distribution channels.
Within the integrated manufacturing tier, Wienerberger AG exemplifies the archetype of clay-reserve-backed production control across multiple kiln sites. CRH plc occupies a position representing scale-driven automated glazing line deployment for volume-tier segments. Ibstock Brick Limited sits within the specialization vector, anchoring premium facade positioning through differentiated firing capabilities. These three patterns illustrate how competitive advantage fragments across input security, manufacturing scale, and technical differentiation.
| Leading Market Players |
|---|
| Wienerberger AG |
| Ibstock Brick Limited |
| Acme Brick Company |
| Glen-Gery Corporation |
| General Shale Brick, Inc. |
| Boral Limited |
| CRH plc |
| Brickworks Limited |
| Michelmersh Brick Holdings PLC |
| Others |
Supply Flow & Price Mechanics
Natural gas price volatility determines both pricing tier spreads and supply chain shape across the European glazed brick industry. Kiln operators without long-term power purchase agreements face compressed margins that force selective capacity allocation toward premium insulating variants, while integrated manufacturers with captive clay reserves absorb fuel cost spikes through upstream input control.
Pricing Analysis
Polish standard glazed bricks trade at meaningful discounts to German and Austrian insulating variants, reflecting divergent thermal certification requirements and energy input costs. Pricing stratifies across premium custom chromatic matching, standard facade-grade volume, and economy-tier non-certified units, with REACH-compliant mineral pigments commanding measurable premiums over legacy formulations. Cost compression in standard-grade segments is intensifying as concrete rainscreen systems capture specification share in non-structural commercial envelopes. Multi-family developers in Poland's Warsaw-Krakow corridor exhibit the highest price sensitivity, while French heritage restoration architects demonstrate minimal elasticity for bespoke chromatic services.
Supply Chain Analysis
Extended payment terms from merchant distributors now stretch to 90-120 days for mid-tier Polish manufacturers, forcing supply-chain finance facilities from clay extractors to bridge working capital gaps. Raw material dependencies center on Lower Silesian kaolin deposits, Westerwald basin clay reserves, and rare-earth mineral pigments sourced through Polish-German extraction partnerships. Single-source vulnerability concentrates in premium kaolin basins where long-term extraction agreements lock out peripheral competitors. Distribution runs through traditional merchant networks in France and Belgium, though direct-to-developer digital platforms are disintermediating these channels for mid-scale Polish housing projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment. EU Ecodesign thermal performance mandates and REACH compliance timelines create certification barriers that favor established kiln operators with dedicated testing resources and harmonized EN standard relationships.
For Market Incumbents: Entrench position by securing long-term renewable power purchase agreements to neutralize natural gas volatility exposure in North Rhine-Westphalia and Silesian production clusters. Acquire or deepen captive clay reserve positions in Lower Silesia and the Westerwald basin to insulate margin structures from extraction cost inflation. Invest in computational glaze formulation software to compress custom color development timelines and defend against Austrian and German technical specialists.
For New Entrants and Emerging Players: Mid-market commercial buildings in Belgium and the Netherlands represent the most penetrable entry point, where design-build contracts compress specification windows and favor agile digital specification platforms. Heritage restoration subcontracting in French monument conservation offers boutique margin pools with lower capital intensity than integrated manufacturing. Pursue go-to-market angles through architect-led procurement platforms that aggregate volume across multiple projects, bypassing traditional merchant distributor relationships.
For Investors and Strategic Acquirers: EU Green Deal embodied carbon threshold enforcement reshapes the acquisition landscape toward kiln operators with verified renewable energy contracts and bio-based flux agent R&D pipelines. Five-to-ten year viability favors integrated clay-to-glaze specialists with captive reserve positions over volume-tier automated producers exposed to commodity fuel pricing. Monitor ECHA REACH Annex XVII enforcement timelines as the critical signal for pigment formulation substitution economics and compliance cost allocation across the value chain.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Clay Reserves | Captive supply from Lower Silesian deposits secures margin control against extraction cost volatility. |
| Renewable Power Purchase Agreement | Long-term contracts with German and Polish utilities neutralize natural gas price exposure in kiln operations. |
| Computational Glaze Formulation Investment | Virtualized R&D platforms compress color development from months to weeks for custom architectural contracts. |
| Direct-to-Developer Digital Channel Launch | Online specification platforms disintermediate traditional merchant distributors for Warsaw-Krakow corridor housing. |
| REACH-Compliant Pigment Partnership | Mineral-derived colorant agreements with Polish extractors secure preferential supply for heritage restoration markets. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with kiln operations managers, facade specification architects, merchant distribution buyers, and EU regulatory compliance officers. Secondary validation drew from harmonized EN standard certification databases, ECHA REACH Annex XVII regulatory filings, EU Green Deal procurement disclosure records, and national building energy efficiency ordinance implementations. Bottom-up volume modeling from identified production facilities was cross-checked against top-down construction sector absorption estimates.
Calibration against historical thermal envelope specification trends and kiln capacity utilization rates anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type tier, application function, end-user procurement authority, and substrate material chemistry. CAGRs were derived from regression analysis of housing start correlations and building code enforcement intensity, with inputs from clay deposit extraction cost curves and renewable energy contract pricing dynamics.
Macroeconomic conditions sit as an overlay; deviation in European natural gas pricing, construction lending availability, or EU Ecodesign implementation timelines would shift the trajectory. Forecasts reflect documented assumptions regarding housing start correlations and regulatory enforcement intensity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Co-Fired Ceramic Market
Ceramics
Diatomite Market
Ceramics
Industrial Ceramics Market
Ceramics
Traditional Ceramic Market
Ceramics
Low Temperature Co-Fired Ceramic (LTCC) Market
Ceramics
Global Magnesium Silicate Market
Ceramics
Feldspar and Nepheline Syenite Market
Ceramics
China Clay Market
Ceramics
Optical Ceramics Market
Ceramics
ME K-Feldspar Market
Ceramics
West Africa Ceramic Tiles Market
Ceramics
China Ceramic Tiles Market
Ceramics
Pyrolytic Boron Nitride Market
Ceramics
Titanium Carbide Market
Ceramics
Europe Aluminum Oxide Market
Ceramics
Fly Ash and Ceramic Microsphere Market