
 Clay Market | 2026-2036
Clay Market Size, Share, and Industry Trends Forecast 2026-2036
Clay Market Intelligence
Aftermarket technical service revenue is tilting toward mineral processing optimization and custom blend formulation. Imerys S.A. leverages its integrated mining-to-distribution network across multiple continents. SCR Sibelco NV anchors its position through deep reserves of high-purity kaolin and silica clays. Active Minerals International LLC specializes in tailored attapulgite and gel-grade clay solutions for industrial absorbents.
Clay comprises fine-grained natural earthy material with particle sizes below 0.002 millimeters, composed primarily of hydrous aluminum silicates such as kaolinite, illite, and montmorillonite, formed through weathering of feldspathic rocks and subsequent sedimentary deposition; manufacturers process raw clay through washing, screening, and calcination to achieve specified plasticity, shrinkage, and fired color for ceramic, construction, and filler applications. Porcelain commands premium pricing due to its low iron content, high vitrification temperature, and translucency requirements in tableware and sanitaryware. Construction applications dominate volume consumption, with unfired clay gaining traction in sustainable building materials and 3D-printed architectural components.
EPA surface mining regulations and OSHA silica exposure limits constrain extraction economics and workplace protocols in the United States, while REACH registration and the EU Green Deal carbon-border adjustments elevate compliance costs for European clay processors. India's BIS certification mandates and China's GB standards on ceramic raw material purity create divergent market access requirements across major supply regions. Stakeholders must monitor evolving national mining codes and carbon-accounting rules to secure long-term feedstock access and maintain product qualification across export destinations.
Market Dynamics
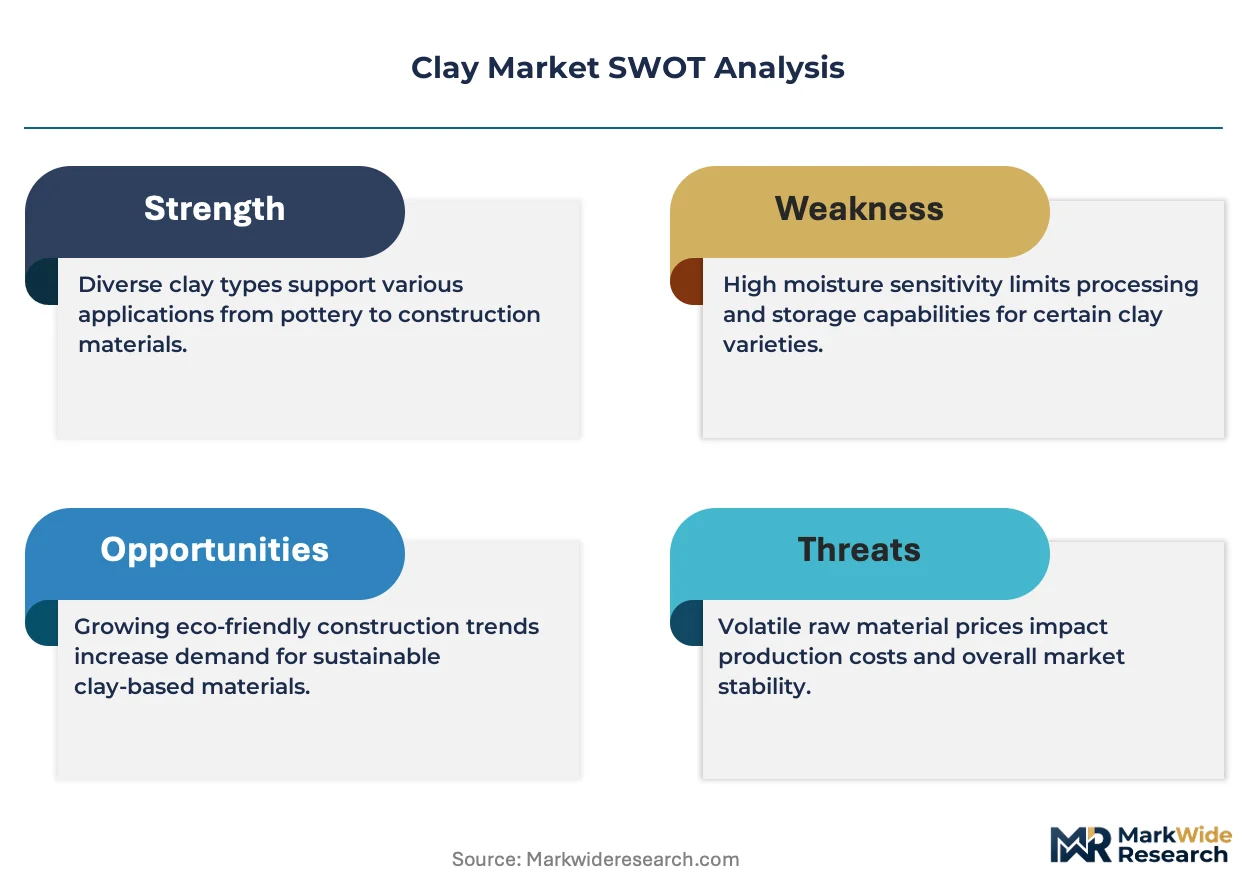
Construction-grade kaolin consumption is tightening extraction economics as residential and commercial building projects absorb larger raw clay volumes, while REACH compliance and EPA mining standards simultaneously elevate beneficiation costs and compress permitted operating margins across major supply basins.
Growth Catalysts
- EPA surface mining standards:Tightened extraction protocols in the United States are accelerating investment in closed-loop washing systems and dry-stack tailings management, expanding the addressable market for advanced mineral processing equipment.
- Ceramics manufacturing clusters:Guangdong and Fujian provinces in China absorb substantial raw clay volumes, creating concentrated demand pull that stabilizes offtake agreements for high-purity kaolin grades.
- Unfired clay building materials:Sustainable construction codes in multiple jurisdictions are mandating lower-carbon alternatives to fired brick and concrete, directly expanding specification opportunities for raw clay in structural applications.
Market Restraints
- Energy cost volatility:Natural gas and electricity price swings disproportionately impact calcination economics, forcing processors to absorb margin compression or pass through costs to price-sensitive construction segments.
- Reserve concentration risk:High-purity kaolin deposits cluster in specific sedimentary basins, creating feedstock vulnerability when single-source jurisdictions impose export licensing or environmental moratoria.
- Silica exposure compliance:OSHA respirable crystalline silica limits mandate costly ventilation and personal protective equipment upgrades, structurally elevating labor costs per ton extracted.
Strategic Opportunities
- 3D-printed architectural components:Additive manufacturing with clay-based inks enables complex geometries for facade elements and interior partitions, opening premium specification channels in commercial construction.
- EU Green Deal carbon-border adjustments:European importers face escalating compliance costs on high-carbon ceramic imports, creating competitive positioning space for low-carbon domestic clay processors.
- Attapulgite industrial absorbents:Gel-grade clay solutions for spill containment and pet litter applications remain underpenetrated in Southeast Asian markets relative to saturation levels in North America.
Industry Challenges
- Beneficiation chemist scarcity:Specialized expertise in particle size distribution control and rheology modification is concentrating at established processors, constraining new entrant operational ramp speed.
- Multi-jurisdiction certification timelines:Simultaneous pursuit of India's BIS certification and China's GB standards creates sequential approval bottlenecks that delay market entry by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Clay Market |
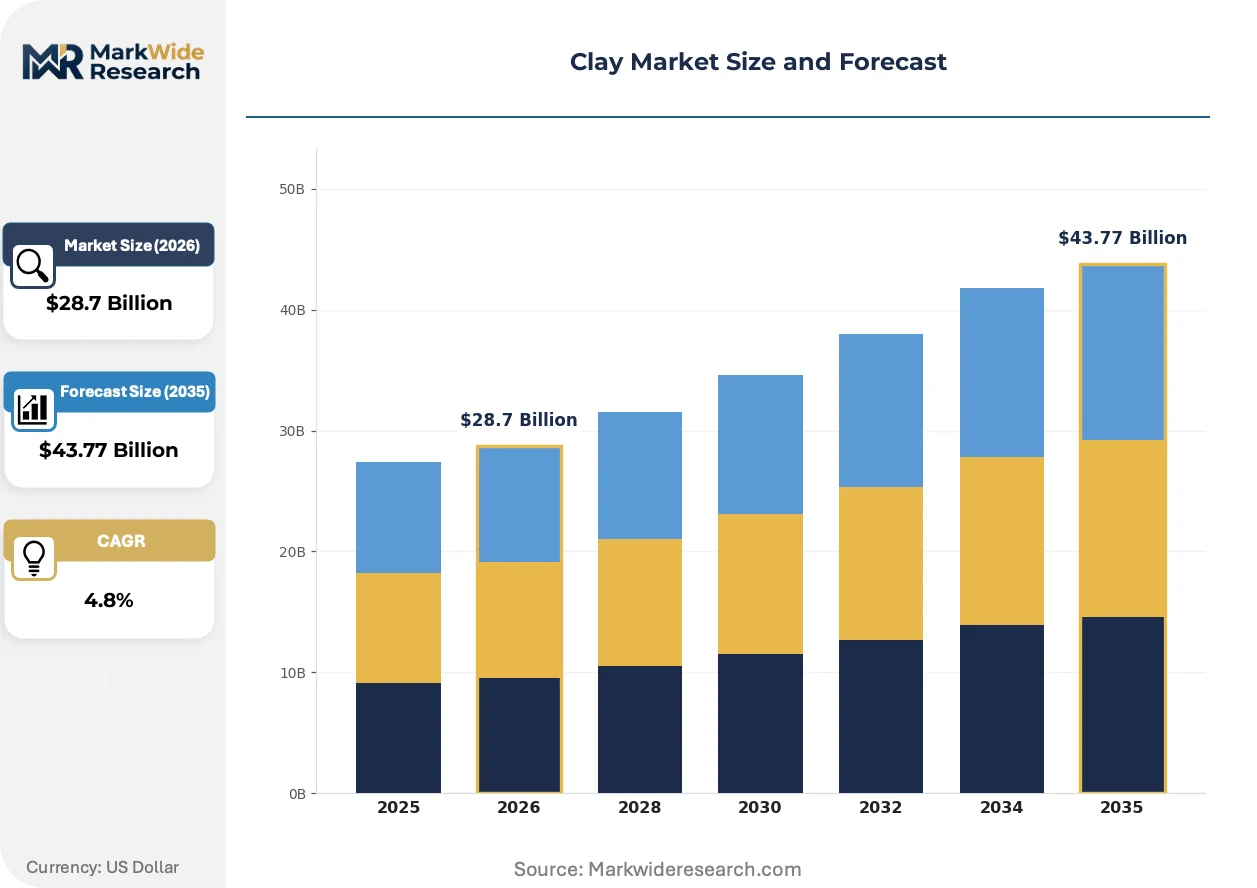
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $43.77 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Earthenware, Stoneware, Porcelain, Terracotta Application: Artistic Ceramics, Tableware, Construction, Unfired Clay End User: Retailers, Artists, Manufacturers, Hobbyists Distribution Channel: Online, Retail Stores, Art Shows, Wholesale |
| Companies Covered | Imerys S.A., SCR Sibelco NV, Minerals Technologies Inc., KaMin LLC, Thiele Kaolin Company, Active Minerals International LLC, Burgess Pigment Co., Lhoist SA, Ashapura Minechem Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Clay Market Strategic Shifts & Innovations
Digital process control and sustainable beneficiation methods are compressing traditional extraction economics while enabling new product grades that meet tightening purity specifications across ceramic and construction end-uses.
Flash calcination technology is hybridizing with conventional rotary kiln systems to reduce energy intensity in kaolin processing. Major ceramics manufacturers in Germany and Italy are piloting these hybrid thermal circuits to maintain vitrification performance at lower carbon intensity. The technology is hybridizing cost structures across the premium porcelain segment, forcing legacy kiln operators to accelerate retrofit timelines or cede specification share.
REACH registration requirements for imported clay feedstocks are tightening documentary evidence standards for substance identity and impurity profiles. European processors now face mandatory re-registration cycles that demand updated toxicological dossiers and supply chain audit trails. Sanitaryware manufacturers in Spain and Portugal are responding by consolidating supplier bases to reduce compliance fragmentation and audit burden.
Buyers are unbundling technical service contracts from bulk material supply agreements, treating mineral processing optimization as a separate procurement category. Large ceramics groups in China and Italy now engage specialized consultants directly rather than relying on clay suppliers for formulation support. This pattern is most visible in tableware manufacturing, where proprietary body recipes are treated as core intellectual property distinct from commodity feedstock sourcing.
Clay Market Segmentation
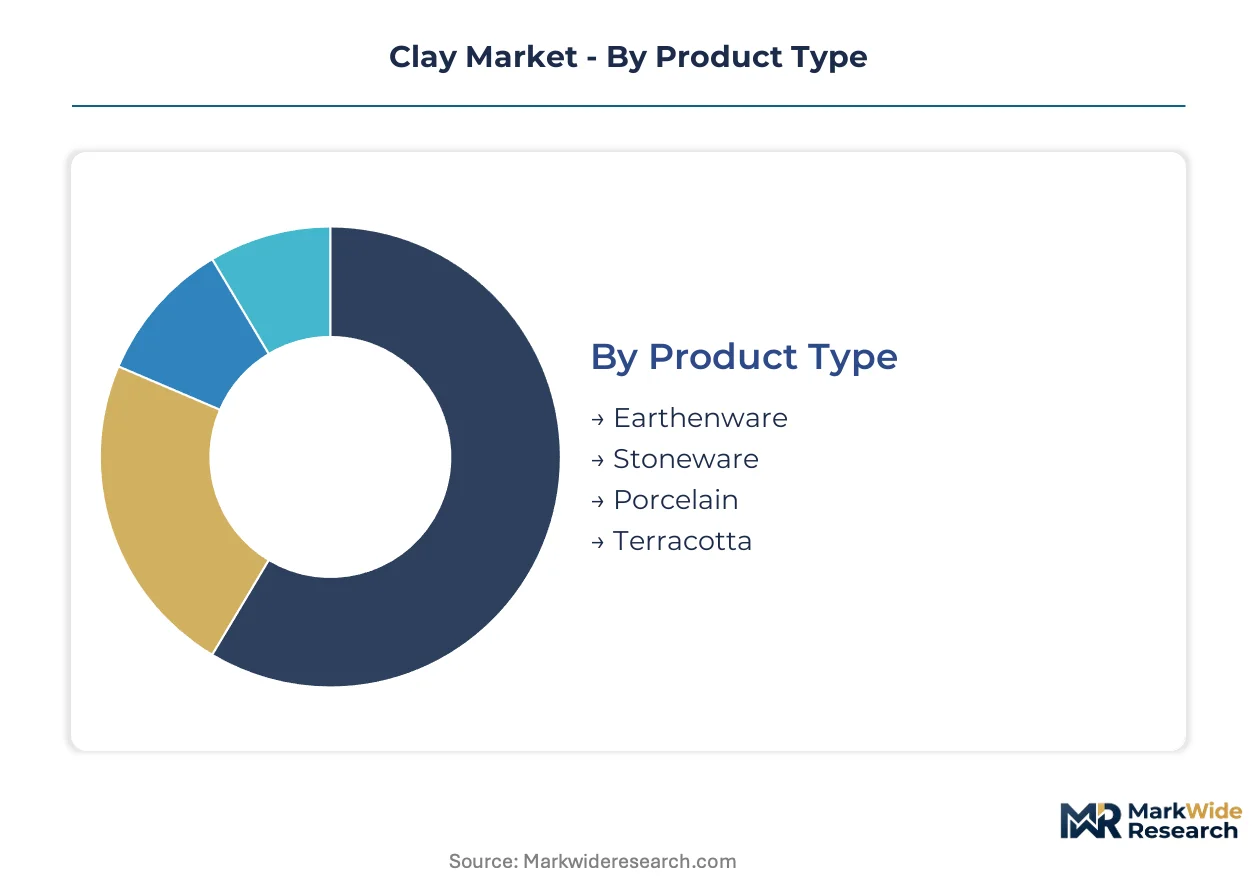
Clay market segmentation reveals divergent specification requirements across ceramic firing temperatures, construction performance standards, and distribution economics. Each dimension carries distinct margin profiles and regulatory exposure that reshape procurement priorities for processors and end-users.
Product Type:
The use-case spectrum spans low-fired decorative ware to high-vitrification technical ceramics, with each product type commanding different kaolin purity grades and thermal processing intensity.
- Earthenware:Porous, low-fired ceramic body fired below 1,100°C with high iron content tolerance; demand concentrates in Mexico and Italy for traditional tableware where artisan production clusters absorb substantial terracotta-grade clay volumes despite energy cost volatility compressing kiln economics.
- Stoneware:Dense, vitrified body fired at 1,200-1,300°C requiring medium-purity kaolin with controlled flux content; German and Japanese manufacturers favor this grade for durable tableware and sanitaryware, with REACH compliance elevating beneficiation costs for European processors.
- Porcelain:High-alumina, low-iron composition demanding premium kaolin grades for translucency; commands specification in fine dining and luxury sanitaryware segments.
- Terracotta:Unglazed, porous earthenware with minimal processing requirements; anchors volume consumption in architectural cladding and garden pottery.
Established volume favors stoneware; emerging adoption favors porcelain.
Application:
Cost tier differentiation separates commodity construction feedstocks from premium ceramic formulations, with unfired clay gaining traction as a lower-carbon structural alternative.
- Artistic Ceramics:Studio-scale production emphasizing plasticity and color range over fired strength; US and UK art school supply chains sustain offtake for specialized body blends.
- Tableware:Food-contact ceramic requiring lead-free glazes and thermal shock resistance; dominates revenue concentration in hotel and restaurant procurement.
- Construction:Brick, tile, and structural clay products absorbing the largest raw volumes; China's infrastructure pipeline and India's urban housing mandates sustain demand despite natural gas price swings compressing firing economics.
- Unfired Clay:Raw material for rammed earth, adobe, and 3D-printed architectural components; French and German sustainable building codes are mandating lower-carbon alternatives, expanding specification opportunities fastest.
Construction commands volume leadership; unfired clay represents the steepest expansion trajectory.
End User:
Customer type determines order scale, technical service intensity, and price elasticity, with manufacturers consolidating procurement while hobbyists fragment demand.
- Retailers:Garden centers and home improvement chains sourcing packaged clay for consumer ceramics; volume scales with seasonal DIY activity in North American and European markets.
- Artists:Individual practitioners requiring small-batch consistency and color predictability; sustain premium pricing for prepared clay bodies.
- Manufacturers:Industrial ceramic producers with captive blending operations; leverage long-term offtake agreements to secure high-purity kaolin reserves.
- Hobbyists:Amateur ceramics enthusiasts purchasing through online channels and community studios; price-sensitive segment with high churn.
Manufacturers anchor contract stability; hobbyists drive channel experimentation.
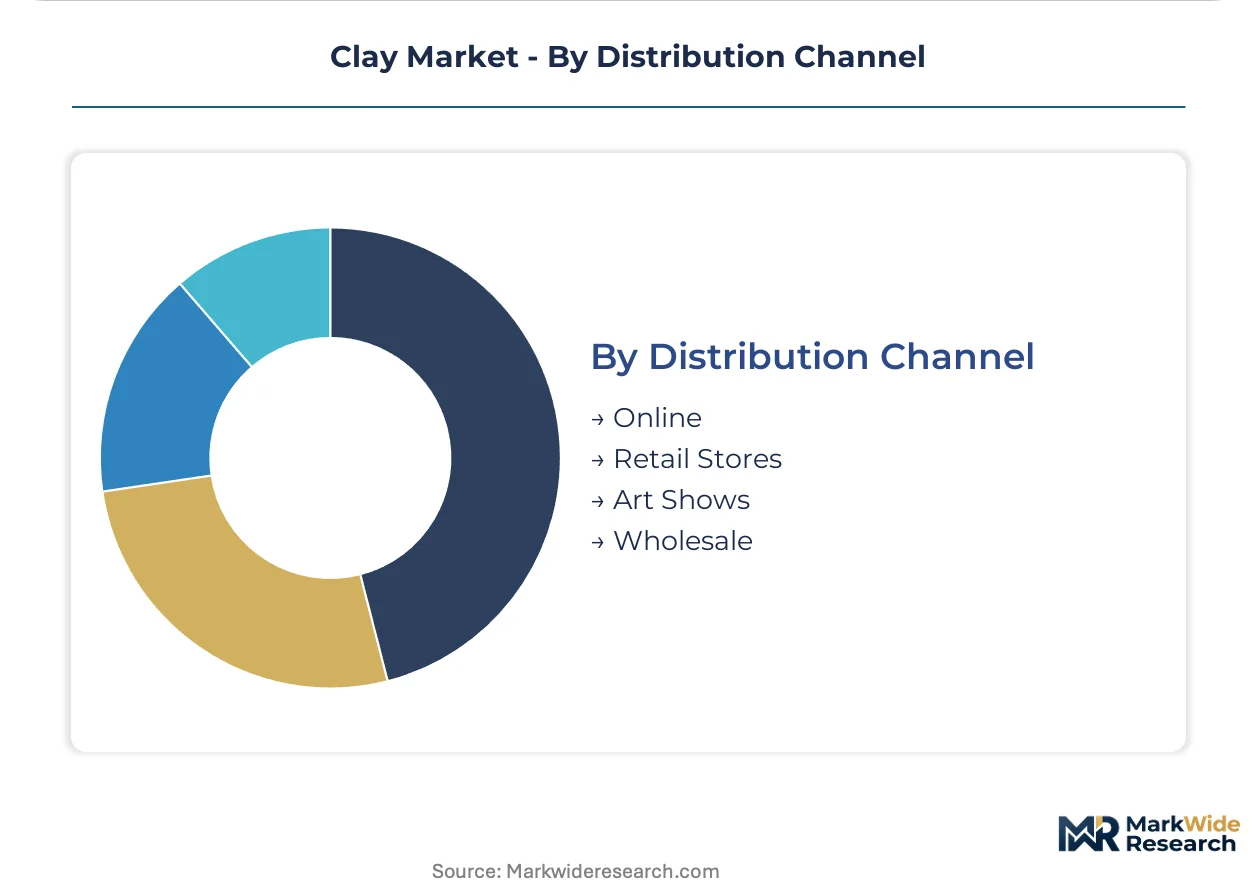
Distribution Channel:
Supply concentration varies by geography and customer scale, with wholesale dominating industrial procurement while digital channels reshape hobbyist access.
- Online:Direct-to-consumer and B2B platforms enabling small-order fulfillment; accelerates market access for specialty clay grades in remote regions.
- Retail Stores:Bricks-and-mortar presence for immediate product inspection; art supply chains in Japan and South Korea maintain dense networks.
- Art Shows:Event-based sales connecting regional producers with studio potters; sustains craft-grade pricing in North American and European markets.
- Wholesale:Bulk supply agreements to industrial processors and construction material distributors; captures volume concentration through rail and barge logistics.
Wholesale retains industrial dominance; online channels are gaining share fastest among non-manufacturer segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Construction-grade kaolin buyers in India and Southeast Asia exhibit acute price sensitivity, while German and Italian porcelain manufacturers absorb premium pricing for high-purity grades with minimal volume elasticity.
United States
Residential housing starts and commercial infrastructure projects drive construction-grade kaolin consumption across the Southeast and Southwest. EPA surface mining regulations under the Clean Water Act constrain extraction permits in Georgia and South Carolina sedimentary basins. The Sandersville-Washington County kaolin belt in Georgia anchors domestic high-purity reserves, where processors are retrofitting facilities to meet OSHA silica exposure limits.
China
Guangdong and Fujian ceramics manufacturing clusters absorb substantial raw clay volumes for tableware and sanitaryware export production. GB standards on ceramic raw material purity mandate stricter impurity thresholds for food-contact applications. The Chaozhou sanitaryware corridor concentrates firing capacity, with local processors sourcing beneficiated kaolin from domestic mines and Southeast Asian import channels.
Germany
Technical ceramics and advanced porcelain manufacturers in Bavaria and North Rhine-Westphalia sustain demand for premium kaolin grades with controlled rheology. REACH registration requirements and EU Green Deal carbon-border adjustments elevate compliance costs for imported feedstocks. The Westerwald region's traditional ceramics cluster is piloting flash calcination hybrids to reduce thermal processing emissions.
India
Urban housing mandates under the Pradhan Mantri Awas Yojana and commercial real estate expansion drive brick and tile consumption. BIS certification requirements for construction materials create sequential approval bottlenecks for imported clay grades. Gujarat's Morbi ceramics cluster dominates sanitaryware production, with local processors blending domestic ball clay with imported kaolin to meet export quality specifications.
Brazil
Rammed earth construction codes in São Paulo and Minas Gerais are mandating lower-carbon alternatives to fired concrete, expanding unfired clay specification. ANVISA regulations on construction material safety parallel evolving Mercosur technical standards. The São Paulo metropolitan corridor anchors demand for structural clay products, with regional distributors consolidating procurement to offset logistics cost volatility.
Clay Market Key Industry Players
Capability concentration sits with integrated mining-to-distribution networks; scale advantage sits with deep-reserve holders commanding multi-decade feedstock security. The vendor base stratifies across three tiers: global integrated processors with continental logistics networks, regional specialists anchored to specific sedimentary basins, and niche formulators serving custom blend requirements. Dominant competitive moves include backward integration into captive mining assets and portfolio diversification into industrial absorbents and construction additives.
Within the integrated processor tier, Imerys S.A. and SCR Sibelco NV exemplify archetypes of multi-continent logistics networks and deep-reserve positioning respectively. Active Minerals International LLC occupies a specialist position in tailored attapulgite solutions. These three entities represent the spectrum from broad mineral processing capability to focused gel-grade formulation expertise, with each anchoring distinct competitive vectors in industrial absorbent and ceramic feedstock segments.
| Leading Market Players |
|---|
| Imerys S.A. |
| SCR Sibelco NV |
| Minerals Technologies Inc. |
| KaMin LLC |
| Thiele Kaolin Company |
| Active Minerals International LLC |
| Burgess Pigment Co. |
| Lhoist SA |
| Ashapura Minechem Ltd |
| Others |
Cost & Logistics Intelligence
The Chaozhou sanitaryware corridor concentrates firing capacity that shapes downstream pricing power across Guangdong province, with beneficiated kaolin processors leveraging captive mine access to resist margin compression from energy cost volatility in construction-grade segments.
Pricing Analysis
Aftermarket technical service revenue from mineral processing optimization and custom blend formulation drives lifetime value beyond commodity feedstock margins. Three-tier pricing structure across premium porcelain, standard stoneware, and economy earthenware levels reflects purity grade and thermal processing intensity differentials. Pricing pressure stems from natural gas cost volatility forcing calcination operators to absorb margin compression or risk volume loss to unfired clay alternatives. Construction-grade buyers in India and Southeast Asia exhibit acute price sensitivity, while German and Italian porcelain manufacturers absorb premium pricing with minimal volume elasticity.
Supply Chain Analysis
Extended payment terms from ceramics manufacturers in China and Italy strain working capital for mid-tier beneficiation operators, accelerating consolidation toward integrated processors with balance-sheet depth. Raw clay extraction concentrates in Georgia's Sandersville-Washington County belt, China's Fujian province, and Brazil's São Paulo corridor, with each hub feeding distinct specification requirements. Supply chains draw from high-purity kaolin reserves, silica sand inputs, and flux mineral additives, with single-source vulnerability in sedimentary basin concentration creating feedstock disruption risk when jurisdictions impose environmental moratoria. Distribution runs through rail and barge logistics networks serving industrial processors, with digital channels gaining share fastest among hobbyist and artist segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Clay market fragmentation creates entry opportunities as sustainable construction codes fragment demand across fired and unfired material specifications, enabling specialized positioning.
For Market Incumbents: Insulate reserve-position advantage by accelerating captive mining acquisitions in Georgia and Fujian basins before regulatory tightening constrains new extraction permits. Deepen technical service capabilities in 3D-printed architectural component formulation to offset commodity pricing pressure from energy cost volatility. Consolidate supplier relationships with sanitaryware manufacturers in Spain and Portugal to reduce REACH compliance fragmentation and audit burden. For New Entrants and Emerging Players: Mid-market gel-grade attapulgite solutions for industrial absorbents in Southeast Asia represent the most penetrable entry point, with pet litter and spill containment applications underpenetrated relative to North American saturation levels. Unfired clay building materials for rammed earth construction in Brazil and France offer specification-driven positioning away from calcination-dependent competitors. Direct technical consultant engagement with large ceramics groups, bypassing traditional supplier-formulator relationships, enables proprietary body recipe development as a service offering. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified mining conglomerates with non-core clay assets in high-purity kaolin basins, where operational focus and beneficiation expertise concentration unlock value. Long-term viability centers on feedstock security across multi-decade reserve horizons and carbon-accounting positioning for EU Green Deal compliance. Monitor flash calcination hybrid adoption rates in German and Italian technical ceramics as inflection indicator for legacy kiln operator distress.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Mining | Secures multi-decade kaolin reserve access in Georgia's Sandersville-Washington County belt ahead of EPA permit constraints. |
| Flash Calcination Hybrid Retrofit | Reduces thermal processing emissions for Bavarian porcelain manufacturers facing EU Green Deal carbon-border adjustments. |
| Custom Blend Formulation Service | Captures technical service revenue as Chinese and Italian ceramics groups unbundle formulation from bulk material supply. |
| Unfired Clay Specification Expansion | Aligns product portfolios with French and German sustainable building codes mandating lower-carbon structural alternatives. |
| Attapulgite Absorbent Market Development | Penetrates Southeast Asian pet litter and spill containment segments where gel-grade clay solutions remain underdistributed. |
Research Approach
Initial hypotheses were tested against primary input from beneficiation plant managers, ceramics procurement leads at tableware manufacturers, mineral processing R&D directors, and construction material distributors, and refined through secondary validation against customs trade data, SEC 10-K filings from integrated processors, EPA mining permit databases, and REACH registration dossiers. Bottom-up volume modeling across product type, application, and end-user segments was triangulated with top-down market sizing from trade flow analysis.
Demand-supply balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning firing temperature tier, end-use industry, distribution channel, and regional production cluster. CAGRs were derived from elasticity-adjusted volume projections and value-per-ton escalation patterns. Forecast inputs incorporated natural gas price scenario modeling, regulatory compliance cost trajectories under evolving EPA and REACH standards, and ceramics manufacturing capacity expansion pipelines in Guangdong and Fujian provinces.
Stress conditions across energy cost volatility bands, export licensing moratoria scenarios, and carbon-border adjustment implementation timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on reserve depletion rates, beneficiation technology adoption curves, and construction activity intensity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Mullite Market
Ceramics
Calcium Aluminosilicate Market
Ceramics
Ceramic Binders Market
Ceramics
Ceramic Injection Molding Market
Ceramics
High Purity Mullite Powder Market
Ceramics
India Kaolin Market
Ceramics
East Africa Ceramic Tiles Market
Ceramics
Nano Ceramic Coatings Market
Ceramics
Global Metal and Ceramic Injection Molding Market
Ceramics
Automotive Ceramics Market
Ceramics
Cordierite Market
Ceramics
Zeolite 4A Market
Ceramics
Ceramic Additives Market
Ceramics
Advanced Sintering Technologies Market
Ceramics
Pottery Ceramics Market
Ceramics
Advanced Ceramic Additives Market