
 Post-Traumatic Stress Disorder Treatment Market | 2026-2036
Post-Traumatic Stress Disorder Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Post-Traumatic Stress Disorder Treatment Market Intelligence
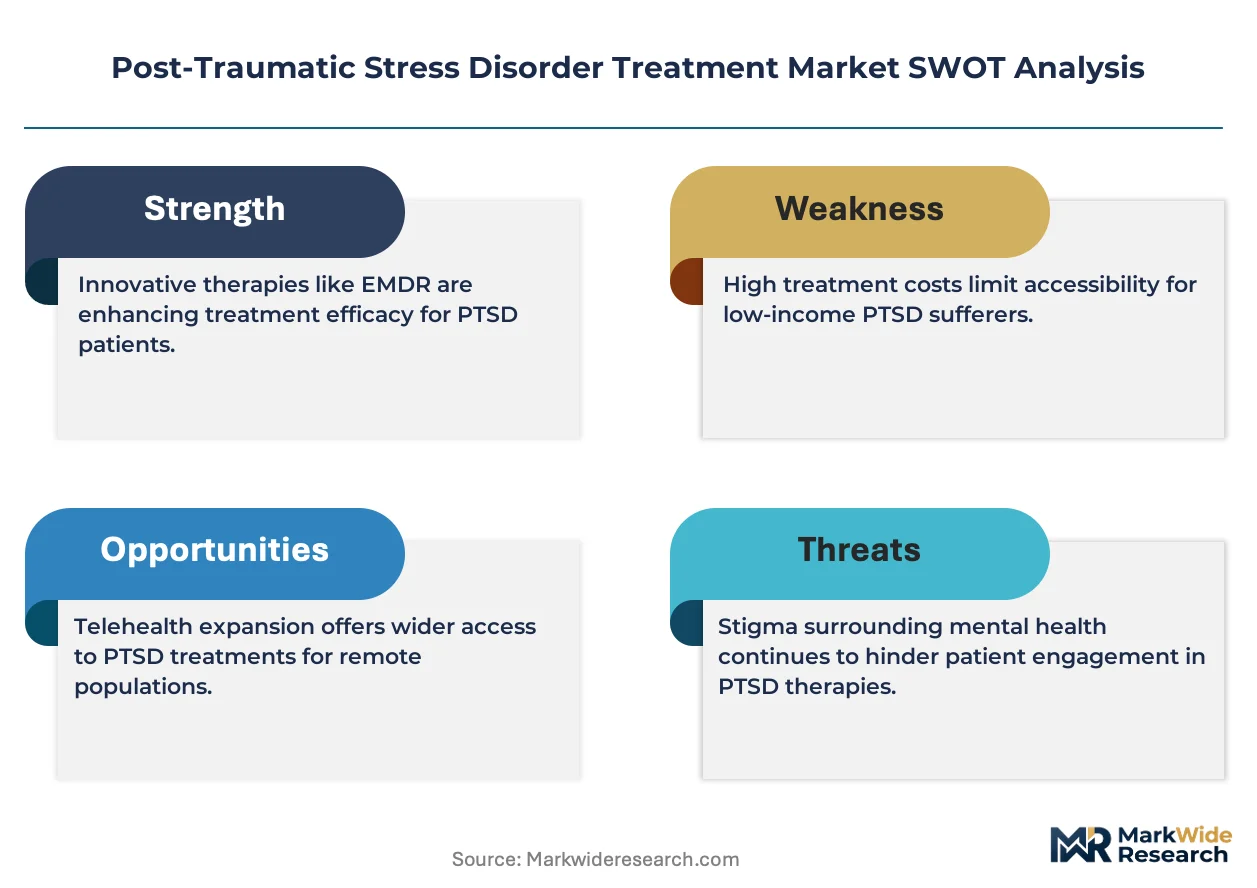
Capital-intensity divergence between large pharmaceutical manufacturers and emerging digital therapeutics developers is reorganizing competitive boundaries in PTSD care. Pfizer Inc. leverages its global manufacturing scale to sustain supply security for established serotonergic agents across institutional channels. Jazz Pharmaceuticals, Inc. anchors its position through specialized CNS development infrastructure and regulatory expertise in controlled-substance formulations. Bionomics competes via targeted ion-channel modulators aimed at trauma-specific neurological pathways rather than broad-spectrum psychiatric indications.
Post-traumatic stress disorder treatment encompasses pharmacological interventions, psychotherapeutic protocols, and adjunctive support modalities designed to attenuate hyperarousal, intrusive re-experiencing, and avoidant behavioral patterns following traumatic exposure. Selective serotonin reuptake inhibitors and trauma-focused cognitive behavioral therapy constitute first-line interventions, with pharmacological mechanisms targeting noradrenergic and glutamatergic dysregulation. Medications and psychotherapy together capture the dominant share of clinical encounters, though telehealth delivery has emerged as the fastest-expanding treatment setting as asynchronous and synchronous remote platforms overcome geographic and stigma barriers to access. Mobile apps occupy a nascent but contested margin pool, with reimbursement validation still unresolved across most payer systems.
FDA breakthrough therapy designation and EMA adaptive pathways accelerate development timelines for novel PTSD mechanisms, compressing traditional phase-transition intervals. HIPAA interoperability mandates and EU GDPR constraints on digital phenotyping data reshape how telehealth and mobile app developers architect patient monitoring infrastructure. Stakeholders must monitor evolving payer evidence requirements for digital therapeutic reimbursement, as coverage determinations will likely separate sustainable platform economics from unsupported pilot deployments.
Market Dynamics
FDA breakthrough therapy designation and EMA adaptive pathways are compressing development timelines for novel PTSD mechanisms, while telehealth infrastructure expansion is redistributing clinical encounters away from traditional brick-and-mortar settings toward asynchronous remote platforms.
Growth Catalysts
- Accelerated Regulatory Pathways:FDA breakthrough therapy designation compresses phase-transition intervals for novel mechanisms targeting glutamatergic and noradrenergic dysregulation. EMA adaptive pathways provide parallel European market access.
- Military Healthcare Expansion:Veteran healthcare infrastructure in the United States drives institutional procurement of trauma-focused cognitive behavioral therapy protocols and pharmacological interventions through specialized VA networks.
- Telehealth Platform Maturation:HIPAA interoperability mandates enable synchronous and asynchronous remote delivery, overcoming geographic barriers and stigma-related access constraints in rural and underserved areas.
Market Restraints
- Reimbursement Validation Gaps:Mobile app and digital therapeutic platforms face unresolved coverage determinations across commercial and public payer systems, constraining sustainable platform economics.
- Specialized Workforce Scarcity:Trauma-focused cognitive behavioral therapy requires certified clinicians with specific trauma training, creating bottleneck conditions in high-demand metropolitan clusters.
- Controlled-Substance Regulatory Burden:DEA scheduling requirements for emerging pharmacological agents impose extended safety monitoring obligations and distribution restrictions that delay commercial rollout.
Strategic Opportunities
- Digital Phenotyping Integration:Convergence of wearable biometric sensors with machine learning analytics enables real-time hyperarousal detection and personalized intervention timing in ambulatory settings.
- EU GDPR-Compliant Infrastructure:European digital health developers can capture market share by architecting patient monitoring systems that satisfy cross-border data portability requirements under unified regulatory frameworks.
- Employer-Sponsored Mental Health Benefits:Large self-insured employers in the United States are expanding carve-out contracts for PTSD-specific care navigation, creating direct-to-payer channel opportunities outside traditional clinical networks.
Industry Challenges
- Evidence Generation Burden:Digital therapeutic developers must produce randomized controlled trial data comparable to pharmacological standards to secure formulary inclusion from pharmacy benefit managers.
- Interoperability Fragmentation:Electronic health record integration requires costly API development across Epic, Cerner, and Meditech systems, duplicating implementation expenses for multi-hospital deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Post-Traumatic Stress Disorder Treatment Market |
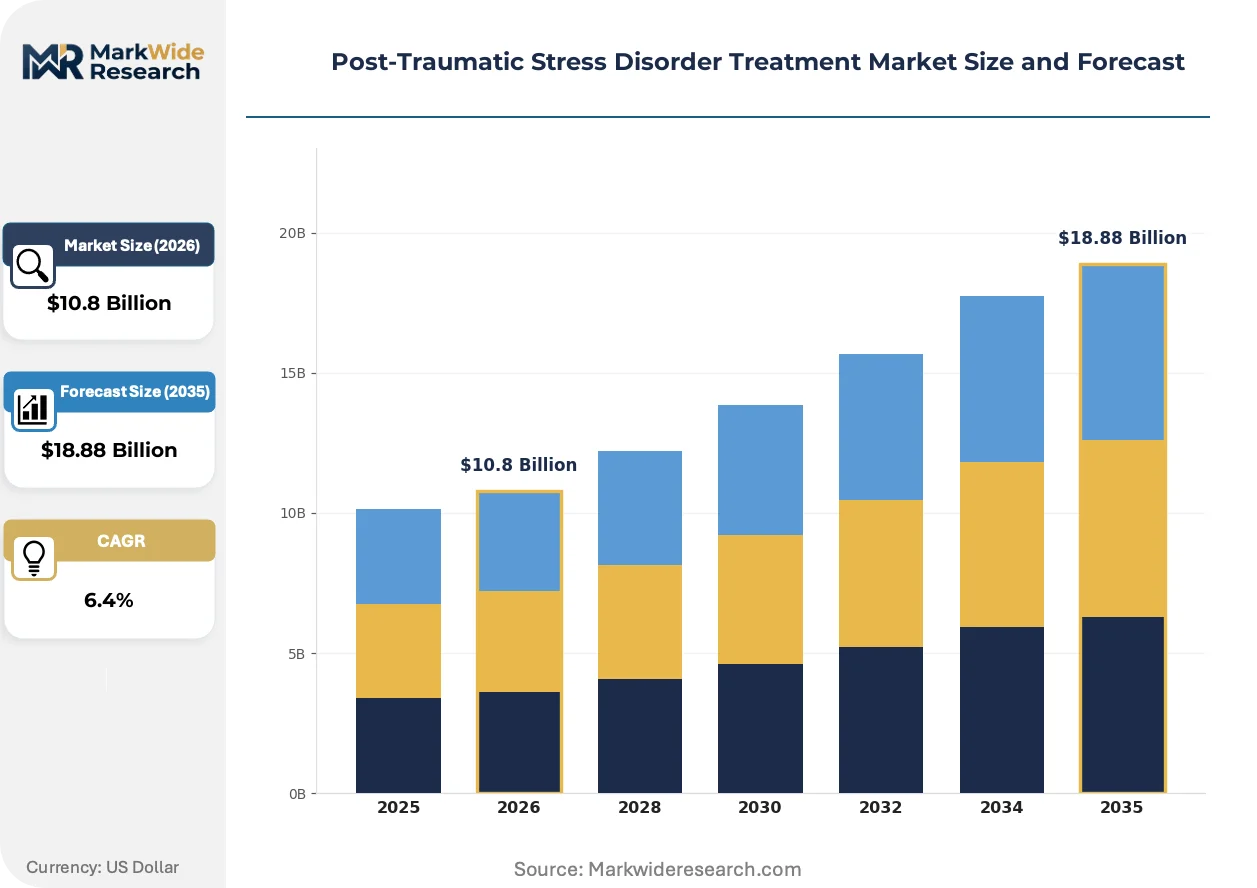
| Market Size in 2026 | $10.8 Billion |
| Market Size in 2035 | $18.88 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medications, Psychotherapy, Support Groups, Mobile Apps Therapeutic Technique: Cognitive Behavioral Therapy, Exposure Therapy, EMDR, Mindfulness Patient Type: Veterans, Survivors of Assault, First Responders, Civilian Trauma Treatment Setting: Residential Facilities, Outpatient Clinics, Hospitals, Telehealth |
| Companies Covered | Pfizer Inc., AstraZeneca, GSK plc., Jazz Pharmaceuticals, Inc., Otsuka Holdings Co., Ltd, Merck KGaA, Viatris Inc., Eli Lilly and Company, Bionomics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Post-Traumatic Stress Disorder Treatment Market Strategic Shifts & Innovations
Biometric monitoring hardware and algorithmic intervention systems are converging to enable continuous rather than episodic PTSD management, while regulatory frameworks on both sides of the Atlantic adapt to accommodate software-as-medical-device classifications.
Implantable vagus nerve stimulation devices are miniaturizing from pacemaker-scale hardware to injectable microstimulators, enabling ambulatory bioelectronic intervention without surgical implantation infrastructure. Military healthcare systems are piloting these platforms for rapid field deployment. This technology is miniaturizing the treatment setting from specialized surgical centers to primary care and even forward-deployed medical units.
EMA's Medical Device Regulation and FDA's software-as-medical-device guidance are creating parallel premarket authorization pathways for algorithm-based PTSD interventions. Developers must maintain dual technical documentation systems to access both markets. European notified bodies are processing submissions more slowly than FDA's digital health pre-certification pilot, shifting early revenue concentration toward United States commercialization.
Self-insured employers and pharmacy benefit managers are unbundling mental health navigation from traditional health plan administration, contracting directly with PTSD-focused virtual care platforms. This disintermediation bypasses health system gatekeepers and compresses patient acquisition costs. The pattern is most visible in United States technology and financial services sectors with concentrated veteran hiring programs.
Post-Traumatic Stress Disorder Treatment Market Segmentation
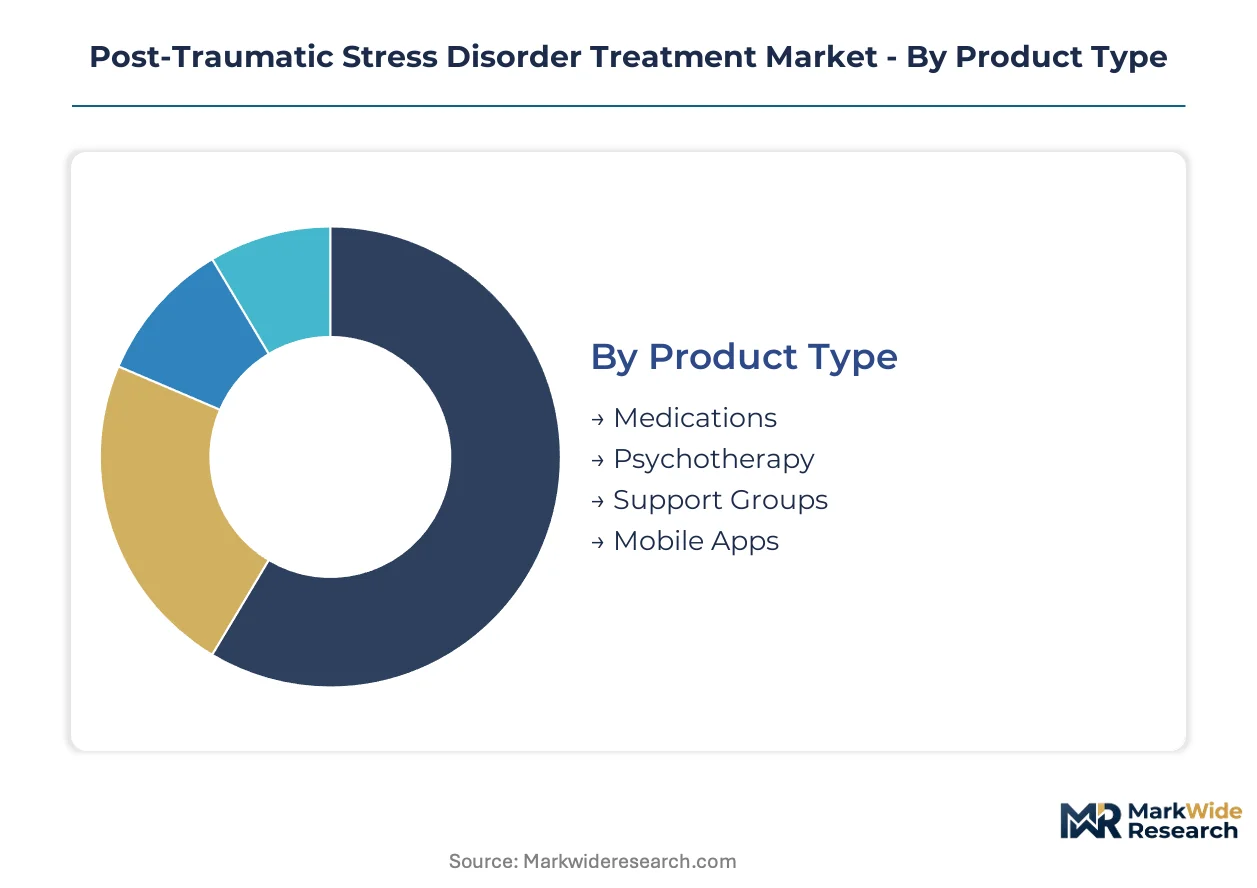
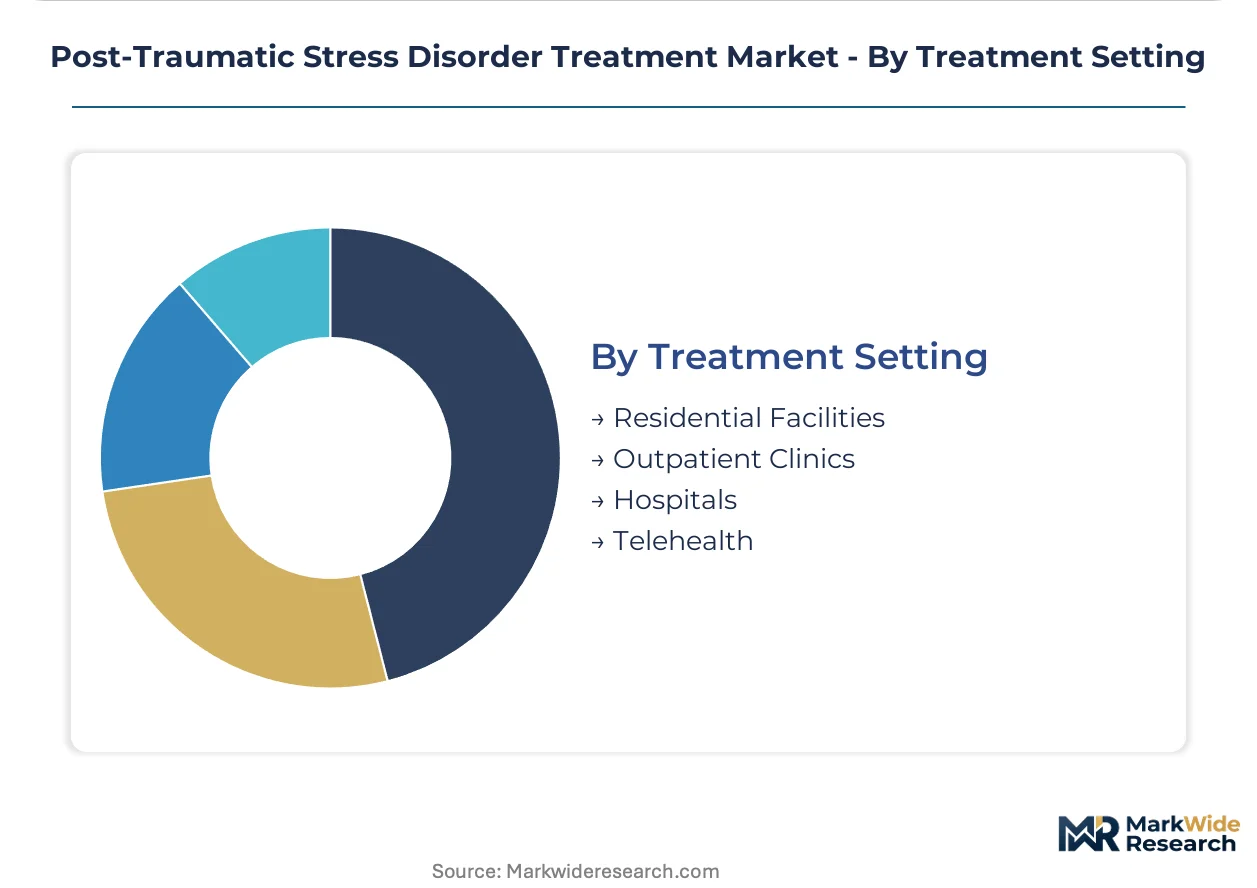
PTSD treatment segmentation reveals how therapeutic modalities, patient populations, and delivery settings compete for reimbursement dollars and clinical adoption. Substitution pressures between pharmacological and psychotherapeutic approaches, combined with telehealth's encroachment on traditional brick-and-mortar delivery, reshape competitive boundaries across every dimension.
Product Type:
Medications face intensifying substitution pressure from trauma-focused psychotherapy protocols and emerging digital therapeutics, as payers scrutinize long-term pharmacological dependency against durable cognitive outcomes.
- Medications:Serotonergic agents, alpha-blockers, and atypical antipsychotics target noradrenergic and glutamatergic dysregulation. Veteran healthcare networks in the United States drive institutional procurement through VA formularies, though DEA scheduling requirements delay novel mechanism rollout.
- Psychotherapy:Trauma-focused cognitive behavioral therapy and prolonged exposure protocols deliver durable symptom reduction without pharmacological side-effect burden. Demand concentrates in metropolitan clusters with certified clinician availability, creating access bottlenecks in rural geographies.
- Support Groups:Peer-facilitated interventions provide low-cost adjunctive care outside formal clinical infrastructure.
- Mobile Apps:Algorithm-based symptom tracking and guided self-help modules occupy contested reimbursement territory pending randomized trial validation.
Medications retain volume leadership; mobile apps hold the steepest expansion curve.
Therapeutic Technique:
Cost tier stratification separates reimbursed clinical protocols from self-pay wellness modalities, with EMDR and prolonged exposure commanding premium reimbursement while mindfulness applications compete in employer-sponsored carve-outs.
- Cognitive Behavioral Therapy:Trauma-focused CBT remains the gold-standard protocol with strongest evidence base for durable remission. First responder occupational health programs in Australia and Canada drive specialized protocol adaptation for high-trauma professions.
- Exposure Therapy:Prolonged and imaginal exposure techniques deliver targeted habituation to trauma cues. VA healthcare systems standardize virtual reality-augmented delivery, compressing treatment timelines for veteran populations.
- EMDR:Eye movement desensitization and reprocessing targets memory reconsolidation through bilateral stimulation protocols.
- Mindfulness:Acceptance-based interventions integrate into employer wellness platforms with limited payer coverage.
Cognitive Behavioral Therapy captures the dominant reimbursement tier; exposure therapy gains share fastest through VA technology integration.
Patient Type:
Application-specific demand patterns concentrate procurement authority in institutional buyers, with veteran networks and first responder occupational health programs wielding disproportionate contract leverage.
- Veterans:Military healthcare infrastructure in the United States anchors specialized service delivery through dedicated VA facilities and community care networks. Congressional appropriations for PTSD research create stable funding for novel mechanism development.
- First Responders:Police, fire, and emergency medical personnel present distinct trauma exposure profiles requiring occupational health integration. Canadian provincial workers' compensation boards pilot early intervention protocols to reduce long-term disability claims.
- Survivors of Assault:Gender-based violence and sexual assault trauma drive demand through victim services and criminal justice system referrals.
- Civilian Trauma:Motor vehicle accidents, natural disasters, and workplace incidents constitute the broadest addressable population with most fragmented access pathways.
Veterans anchor institutional procurement volume; first responders represent the most concentrated expansion opportunity through occupational health integration.
Treatment Setting:
Volume redistribution from residential and hospital-based delivery toward telehealth platforms accelerates as HIPAA interoperability mandates enable remote clinical encounters at scale.
- Telehealth:Synchronous video and asynchronous messaging platforms overcome geographic and stigma barriers to access. United States technology sector employers contract directly with virtual PTSD platforms, bypassing traditional health system gatekeepers.
- Outpatient Clinics:Community mental health centers and private practice networks deliver the majority of reimbursed encounters. Specialized trauma clinics in Germany and the Netherlands concentrate certified EMDR and CBT practitioners.
- Residential Facilities:Intensive inpatient programs serve severe, complex, or comorbid presentations requiring 24-hour monitoring.
- Hospitals:Emergency department and psychiatric inpatient units provide crisis stabilization with limited long-term engagement.
Outpatient clinics retain encounter volume leadership; telehealth climbs the fastest as employer direct contracting expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Reimbursement premiums in the United States exceed German rates by substantial margins, while VA procurement volumes concentrate purchasing power in ways unmatched by European national health systems. This pricing-power asymmetry shapes where developers prioritize regulatory submissions and commercial launch sequencing.
United States
VA healthcare networks and commercial payer carve-outs drive institutional procurement of trauma-focused protocols. FDA breakthrough therapy designation compresses development timelines for novel glutamatergic mechanisms. Boston and San Diego anchor specialized CNS development clusters with concentrated venture funding for digital therapeutics.
Germany
Statutory health insurance funds mandate coverage for trauma-focused cognitive behavioral therapy with standardized reimbursement codes. EMA adaptive pathways provide parallel European market access for novel mechanisms. Heidelberg and Berlin concentrate certified EMDR practitioners and university-affiliated trauma research centers.
United Kingdom
NHS England's Improving Access to Psychological Therapies program procures stepped-care protocols for civilian trauma populations. NICE technology appraisals set evidence thresholds for digital therapeutic reimbursement. London and Manchester host specialized veteran mental health services with integrated occupational health pathways.
Canada
Provincial workers' compensation boards pilot early intervention protocols for first responder populations to reduce long-term disability claims. Health Canada expedites reviews for PTSD indications in occupational health contexts. Toronto and Vancouver concentrate telehealth platform development serving rural access gaps.
Australia
Department of Veterans' Affairs funds specialized trauma services through community provider networks with outcome-based contracting. TGA aligns software-as-medical-device guidance with FDA precedents to accelerate digital therapeutic registration. Melbourne and Sydney anchor research partnerships between defense health services and academic psychiatry departments.
Post-Traumatic Stress Disorder Treatment Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes, with large pharmaceutical manufacturers sustaining global supply security for established serotonergic agents while emerging digital therapeutics developers compress patient acquisition costs through direct-to-payer channels. The market structures around three tiers: global scale manufacturers with institutional formulary dominance, specialized CNS developers with regulatory expertise in controlled substances, and venture-backed platform companies targeting reimbursement validation for algorithm-based interventions. Dominant competitive moves include strategic partnerships between telehealth platforms and self-insured employers, plus portfolio diversification into digital phenotyping capabilities.
Within the global pharmaceutical tier, Pfizer Inc. and AstraZeneca occupy positions defined by manufacturing scale and institutional channel access. Jazz Pharmaceuticals, Inc. represents the specialized CNS archetype with concentrated expertise in controlled-substance development infrastructure. Bionomics exemplifies the targeted-mechanism approach, competing via ion-channel modulators rather than broad-spectrum psychiatric indications.
| Leading Market Players |
|---|
| Pfizer Inc. |
| AstraZeneca |
| GSK plc. |
| Jazz Pharmaceuticals, Inc. |
| Otsuka Holdings Co., Ltd |
| Merck KGaA |
| Viatris Inc. |
| Eli Lilly and Company |
| Bionomics |
| Others |
Cost & Logistics Intelligence
Long-term capacity reservation contracts between VA healthcare networks and specialized CNS manufacturers lock in supply access for controlled-substance formulations while anchoring price visibility across multi-year procurement cycles. These institutional agreements buffer against spot-market volatility for novel glutamatergic mechanisms while compressing margins for generic serotonergic agents exposed to open formulary competition.
Pricing Analysis
The customization-premium spread separates FDA breakthrough-therapy designated formulations from standard-of-care generics, with ion-channel modulators and digital therapeutics commanding configured-to-order pricing against commoditized SSRI volumes. Three-tier pricing structure across premium, standard, and economy levels reflects certification intensity, with DEA Schedule III-V compliance adding regulatory cost layers that standard psychiatric indications avoid. Pricing pressure stems from telehealth platform disintermediation, which collapses patient acquisition costs and forces brick-and-mortar clinics toward volume discounts. Self-insured employers exhibit lowest price sensitivity through direct-to-payer carve-outs, while rural community health centers face acute budget constraints.
Supply Chain Analysis
The United States and Germany anchor pharmaceutical manufacturing for trauma-focused CNS agents, with India supplying active pharmaceutical ingredients for generic serotonergic compounds. Active ingredients draw from specialized chemical synthesis facilities in Gujarat and Hyderabad, while controlled-substance precursors hinge on domestic DEA-registered production sites. Single-source vulnerability concentrates in novel mechanism API supply, where limited GMP-certified capacity creates bottleneck risk for accelerated regulatory pathways. Distribution runs through VA central procurement, specialty pharmacy networks, and direct-to-employer virtual care platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Post-traumatic stress disorder treatment exhibits cyclical recovery dynamics tied to military deployment cycles and veteran population health expenditure authorization patterns. Congressional appropriations for PTSD research create predictable funding waves that synchronize R&D investment windows across pharmaceutical and digital therapeutic developers.
For Market Incumbents: Fortify formulary position through backward integration into digital phenotyping capabilities, capturing real-time hyperarousal data streams that differentiate from generic pharmacological offerings. Expand manufacturing capacity in FDA-registered sites to preempt DEA scheduling bottlenecks for emerging controlled-substance mechanisms. Counter telehealth platform disintermediation by embedding proprietary protocols into employer-sponsored navigation contracts. For New Entrants and Emerging Players: FDA breakthrough therapy designation fast-track offers the most penetrable regulatory pathway for novel glutamatergic and noradrenergic mechanisms, compressing phase-transition timelines against standard IND routes. Target first responder occupational health programs in Canada and Australia, where workers' compensation boards pilot early intervention with outcome-based contracting. Deploy direct-to-payer sales models that bypass health system gatekeepers and capture employer carve-out budgets. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among telehealth platforms with embedded PTSD-specific care navigation, generating subscription visibility superior to episodic pharmaceutical prescribing. Long-term viability centers on reimbursement validation for algorithm-based interventions, with sustainable platform economics separating from unsupported pilot deployments. Monitor pharmacy benefit manager formulary inclusion decisions as the critical inflection signal for digital therapeutic commercial scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Breakthrough Therapy Designation Pursuit | FDA accelerated pathways compress development timelines for novel glutamatergic mechanisms targeting trauma-specific neurological pathways. |
| Digital Phenotyping Platform Development | Wearable biometric integration with machine learning analytics enables real-time hyperarousal detection in ambulatory veteran populations. |
| Employer Direct Contracting Expansion | Self-insured technology and financial services firms with veteran hiring programs bypass traditional health system gatekeepers. |
| EU GDPR-Compliant Infrastructure Buildout | European notified body processing delays create first-mover advantage for developers architecting cross-border data portability systems. |
| Controlled-Substance Manufacturing Scale-Up | DEA-registered production capacity anchors supply security for novel mechanisms facing extended safety monitoring obligations. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with VA formulary directors, trauma-focused CBT certified clinicians, digital therapeutic product managers, and pharmacy benefit manager access specialists. Secondary validation drew from FDA breakthrough therapy designation filings, EMA adaptive pathway submissions, ClinicalTrials.gov PTSD protocol registries, and CMS Medicare telehealth utilization data. Bottom-up encounter volume modeling triangulated against top-down military healthcare expenditure projections.
Across the analysis window, the forecasting framework segmented by therapeutic modality, patient population archetype, delivery setting, and regional regulatory cluster. CAGRs were derived from logistic adoption curves for telehealth penetration and institutional procurement cycle analysis for VA network formulary updates. Model inputs incorporated HIPAA interoperability mandate implementation timelines and DEA scheduling review duration patterns for novel CNS mechanisms.
Underlying assumptions cover reimbursement validation trajectories for digital therapeutics, with deviation risk concentrated in payer evidence requirement evolution and workforce certification bottlenecks for trauma-focused protocols. Recalibration cycles align with material shifts in FDA digital health pre-certification pilot expansion and EMA Medical Device Regulation notified body processing capacity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Cutaneous Fibrosis Treatment Market
Specialty Medicine
Glaucoma Market
Specialty Medicine
Cryptococcosis Market
Specialty Medicine
Dementia Management Market
Specialty Medicine
Vascular Dementia Treatment Market
Specialty Medicine
Global Overactive Bladder Treatment Market
Specialty Medicine
Europe Idiopathic Pulmonary Fibrosis Treatment Market
Specialty Medicine
Adrenogenital Syndrome Treatment Market
Specialty Medicine
Transient Ischemic Attack Market
Specialty Medicine
Cirrhosis Management Market
Specialty Medicine
Progressive Pulmonary Fibrosis (PPF) Treatment Market
Specialty Medicine
Global Gastroparesis Treatment Market
Specialty Medicine
Muscle Wasting Disorders Market
Specialty Medicine
Thyroid Cancer Therapeutics Market
Specialty Medicine
Behcet's Syndrome Market
Specialty Medicine
Global Cryptococcosis Treatment Market