
 Progressive Pulmonary Fibrosis (PPF) Treatment Market | 2026-2036
Progressive Pulmonary Fibrosis (PPF) Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Progressive Pulmonary Fibrosis (PPF) Treatment Market Analytics
The PPF treatment landscape is recalibrating around a sharp divergence between premium antifibrotic therapies and commodity corticosteroid regimens. Boehringer Ingelheim dominates the premium tier with its established idiopathic pulmonary fibrosis franchise, while Roche Holding AG leverages its immunology pipeline to compete in combination approaches. FibroGen Inc. anchors the emerging segment with connective tissue disease-associated ILD assets.
Progressive Pulmonary Fibrosis treatment encompasses pharmacological and supportive interventions targeting irreversible lung parenchymal scarring, with antifibrotic agents such as nintedanib and pirfenidone functioning as tyrosine kinase inhibitors that slow forced vital capacity decline. The primary purpose centers on delaying disease progression and reducing acute exacerbation frequency in patients with progressive fibrosing interstitial lung diseases. Antifibrotic agents command the dominant revenue pool due to chronic administration requirements and premium positioning, while inhalation delivery modes represent the fastest-growing structural segment as device manufacturers improve lung deposition efficiency. Homecare settings emerge as a high-growth end user category driven by remote patient monitoring integration and reimbursement shifts favoring outpatient management.
The FDA maintains stringent efficacy benchmarks for PPF drug approvals through its Division of Pulmonology, while the EMA's Committee for Medicinal Products for Human Use applies parallel fibrosis progression endpoints across European markets. These frameworks elevate clinical trial costs but simultaneously protect validated therapies from premature generic erosion. Stakeholders must monitor evolving composite endpoint definitions and their implications for pipeline asset valuation.
Market Dynamics
The FDA's Breakthrough Therapy designation pathway is compressing development timelines for novel antifibrotic candidates while simultaneously elevating evidence requirements for reimbursement eligibility. This regulatory acceleration is redrawing competitive positioning between established tyrosine kinase inhibitors and emerging biologic approaches.
Growth Catalysts
- Expanded Medicare Reimbursement:The Centers for Medicare & Medicaid Services has broadened coverage for interstitial lung disease management, enabling pulmonology departments in tertiary hospitals to standardize antifibrotic prescribing without prior authorization barriers.
- EMA Parallel Endpoint Harmonization:The Committee for Medicinal Products for Human Use applies consistent fibrosis progression endpoints across European markets, reducing duplicate trial requirements and accelerating multi-country market entry for validated therapies.
- Homecare Monitoring Integration:Remote patient monitoring platforms are capturing forced vital capacity data continuously, creating longitudinal datasets that support value-based contracting and outpatient therapy optimization.
Market Restraints
- Clinical Trial Cost Escalation:The FDA Division of Pulmonology mandates composite endpoint definitions requiring larger patient populations and extended follow-up periods, inflating Phase III expenditure for PPF candidates.
- Active Pharmaceutical Ingredient Concentration:Tyrosine kinase inhibitor raw material synthesis concentrates in a limited supplier base in India and China, exposing manufacturers to import tariff volatility and geopolitical supply interruptions.
- Corticosteroid Substitution Persistence:Commodity immunosuppressant regimens retain prescribing inertia among general pulmonologists despite inferior progression data, particularly in resource-constrained healthcare systems.
Strategic Opportunities
- Connective Tissue Disease-Associated ILD:Systemic sclerosis and rheumatoid arthritis patient populations remain underpenetrated by antifibrotic therapy relative to idiopathic pulmonary fibrosis, presenting expansion potential for indication-widened assets.
- Inhalation Delivery Device Convergence:Nebulized antifibrotic formulations combined with smart inhaler technology enable direct lung parenchyma deposition while capturing adherence data for payor contracting.
- Japan's Sakigake Designation:Japan's PMDA offers priority review for innovative therapies addressing unmet needs in fibrotic lung disease, creating an accelerated path to reimbursement in the world's third-largest pharmaceutical market.
Industry Challenges
- Biomarker Validation Talent Scarcity:Qualified translational medicine specialists capable of developing predictive progression markers are concentrated at a handful of academic medical centers, constraining pipeline asset differentiation.
- Legacy EHR Integration Friction:Pulmonology practices face technical complexity embedding ILD-specific clinical decision support into existing electronic health record workflows, delaying guideline-concordant prescribing adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Progressive Pulmonary Fibrosis (PPF) Treatment Market |
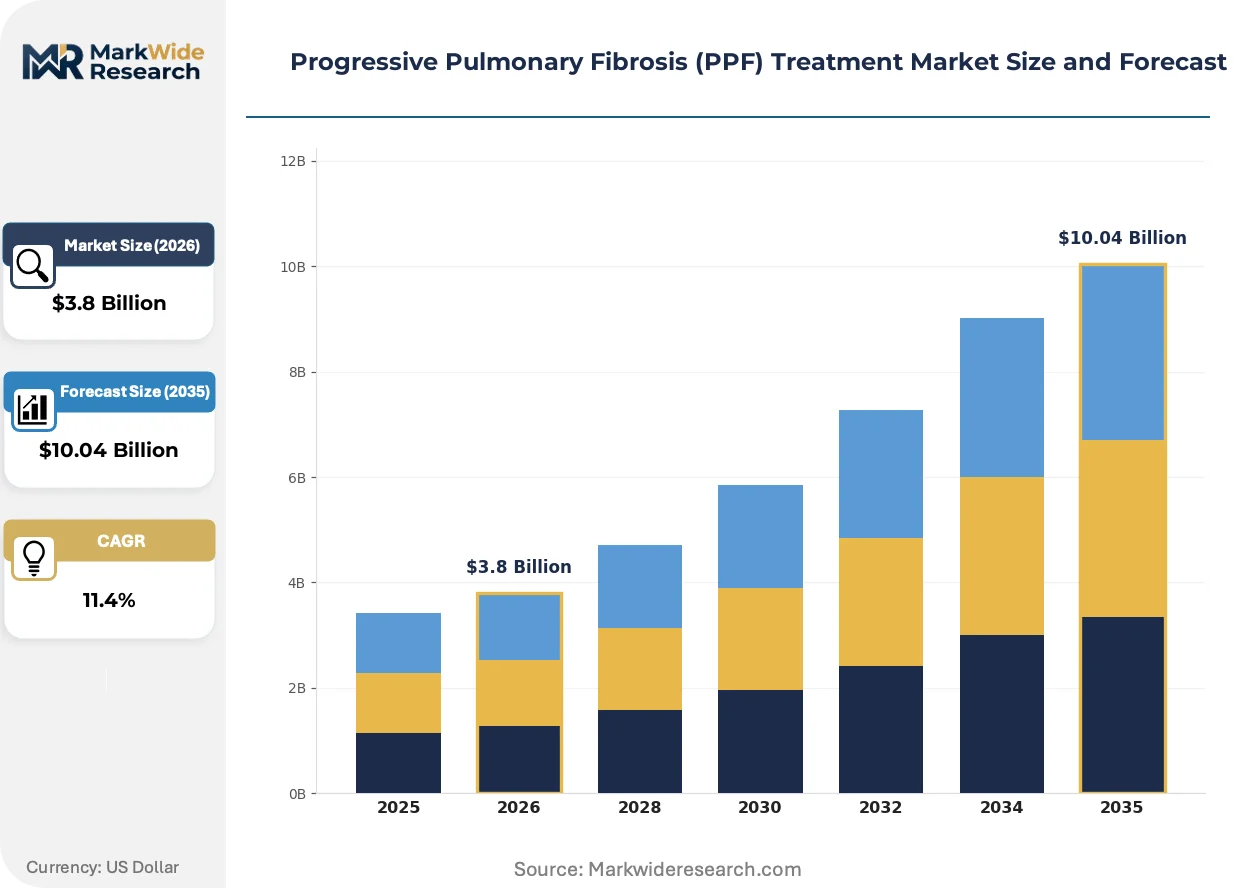
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antifibrotic Agents, Corticosteroids, Immunosuppressants, Oxygen Therapy Delivery Mode: Oral, Injectable, Inhalation, Transdermal End User: Hospitals, Clinics, Homecare Settings, Long-term Care Facilities Application: Disease Management, Symptom Relief, Clinical Trials, Patient Support Programs |
| Companies Covered | Boehringer Ingelheim, Roche Holding AG, FibroGen Inc., Bristol Myers Squibb, Galapagos NV, United Therapeutics Corporation, Pliant Therapeutics, Vicore Pharma, Avalyn Pharma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Progressive Pulmonary Fibrosis (PPF) Treatment Market Evolving Landscape
Device manufacturers and pharmaceutical developers are converging on inhalation delivery as the dominant administration modality, while regulatory frameworks on both sides of the Atlantic tighten evidentiary standards for progression claims. This dual pressure is forcing portfolio reconfiguration toward combination regimens and digital biomarker integration.
Smart nebulizer systems with embedded sensors are absorbing the chronic administration burden from oral antifibrotic regimens. Pulmonology departments in US academic medical centers are piloting these devices for nintedanib and pirfenidone delivery. The technology is absorbing patient adherence monitoring costs while generating real-world evidence streams that manufacturers leverage for payor negotiations.
The EU's Medical Device Regulation imposes stricter clinical evidence requirements on inhalation devices classified as Class IIb or higher. Manufacturers must now submit performance data specific to lung deposition efficiency for each drug-device combination. German and French notified bodies are enforcing this most aggressively, delaying market entry for non-integrated device submissions.
Hospital procurement committees are unbundling antifibrotic therapy decisions from traditional pharmacy formulary processes. Integrated delivery networks in the United States are establishing separate ILD therapeutic committees with pulmonologist majorities, displacing general pharmacy and therapeutics governance. This concentration of prescribing authority is most visible in Medicare Advantage–dominated markets where risk-bearing entities capture progression-delay savings directly.
Progressive Pulmonary Fibrosis (PPF) Treatment Market Segmentation
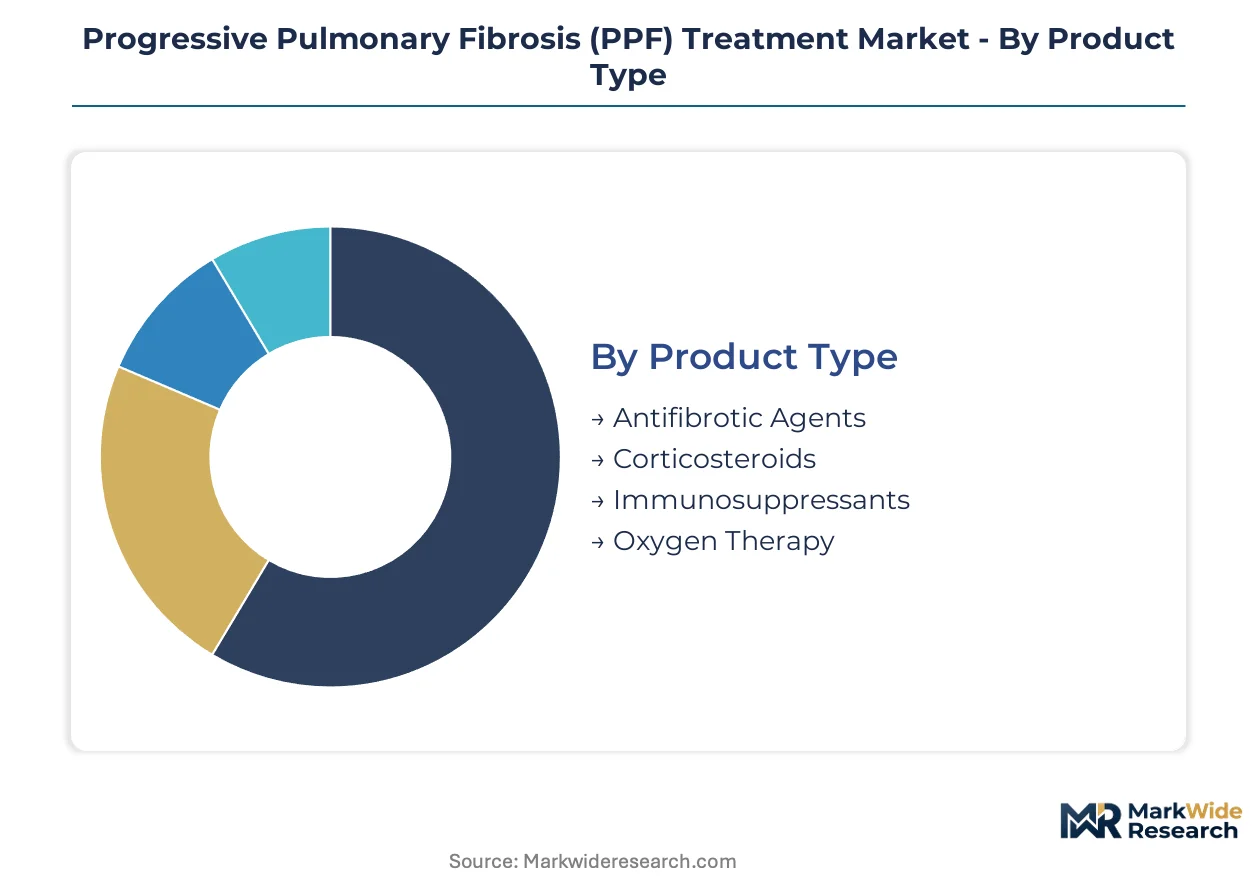
PPF treatment segmentation reveals how therapeutic modalities, administration routes, and care settings interact to determine patient access and reimbursement economics. Understanding these intersecting categories enables stakeholders to identify where portfolio investments align with evolving clinical workflows and payer preferences.
Product Type:
Pharmacological mechanisms differentiate segments by clinical positioning, chronic administration burden, and premium pricing eligibility.
- Antifibrotic Agents:Tyrosine kinase inhibitors including nintedanib and pirfenidone slow forced vital capacity decline through targeted fibrogenesis interruption. Demand concentrates in tertiary hospital pulmonology departments across Germany and the United States, driven by Medicare reimbursement expansion for interstitial lung disease management.
- Corticosteroids:Commodity immunosuppressant regimens such as prednisone remain widely prescribed despite inferior progression data, particularly in resource-constrained healthcare systems where prior authorization barriers limit antifibrotic access.
- Immunosuppressants:Azathioprine and mycophenolate mofetil serve combination protocols for connective tissue disease-associated ILD subtypes.
- Oxygen Therapy:Long-term supplemental oxygen addresses hypoxemia in advanced fibrotic disease stages.
Mature deployment sits with Corticosteroids. Newer deployment is concentrated in Antifibrotic Agents.
Delivery Mode:
Administration technology determines lung deposition efficiency, adherence monitoring capability, and outpatient versus inpatient care economics.
- Inhalation:Nebulized antifibrotic formulations combined with smart inhaler technology enable direct lung parenchyma deposition while capturing adherence data for payor contracting in US academic medical centers.
- Oral:Capsule and tablet formulations dominate current prescribing volumes due to established distribution infrastructure and patient familiarity.
- Injectable:Subcutaneous and intravenous routes support acute exacerbation management and clinical trial settings.
- Transdermal:Patch-based delivery remains experimental for antifibrotic agents, with limited commercial penetration.
Established volume sits with Oral delivery. Steepest expansion trajectory belongs to Inhalation systems.
End User:
Care setting selection reflects disease severity staging, reimbursement structure, and remote monitoring infrastructure maturity.
- Homecare Settings:Remote patient monitoring platforms capture forced vital capacity data continuously, creating longitudinal datasets that support value-based contracting and outpatient therapy optimization in Medicare Advantage–dominated markets.
- Hospitals:Tertiary academic medical centers anchor antifibrotic initiation protocols and clinical trial enrollment.
- Clinics:Community pulmonology practices manage stable patients with guideline-concordant prescribing.
- Long-term Care Facilities:Skilled nursing settings address advanced disease palliation and oxygen dependency.
Current patient volume concentrates in Hospitals. Gaining share fastest are Homecare Settings.
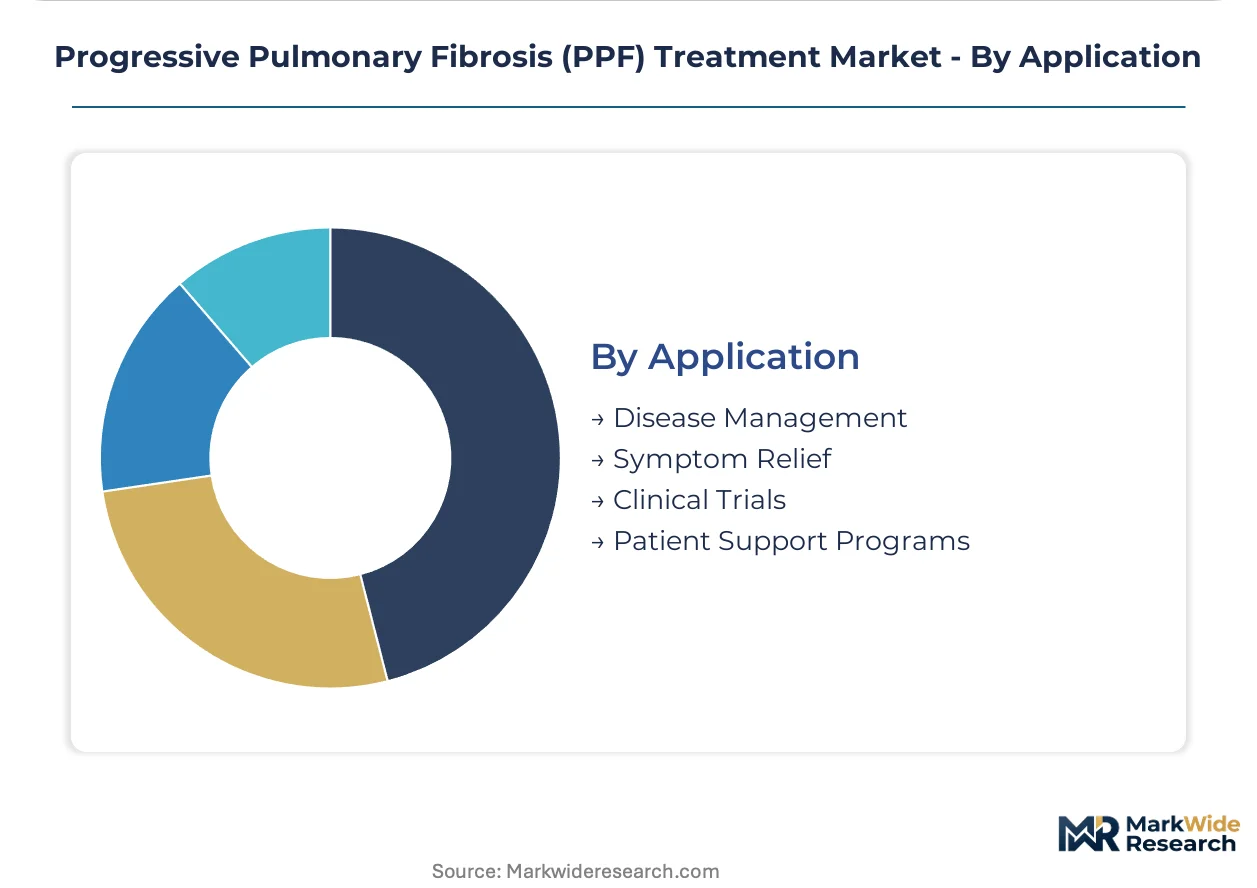
Application:
Use case segmentation separates revenue-generating therapeutic administration from supporting services and research activities.
- Disease Management:Chronic antifibrotic administration with progression monitoring constitutes the core revenue pool.
- Symptom Relief:Palliative interventions address cough, dyspnea, and quality-of-life endpoints.
- Clinical Trials:Investigational site networks generate service revenue and pipeline optionality.
- Patient Support Programs:Adherence services and copay assistance programs differentiate manufacturer offerings.
Revenue concentration rests with Disease Management. Investment flow is accelerating into Patient Support Programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston's academic medical corridor anchors clinical trial density for antifibrotic therapies, while reimbursement policy divergence across national healthcare systems fragments patient access pathways.
United States
Medicare Advantage penetration in Florida and Arizona accelerates homecare monitoring adoption for forced vital capacity tracking. The FDA Division of Pulmonology maintains composite endpoint requirements that inflate Phase III trial costs. The Cleveland Clinic and Mayo Clinic anchor multi-site enrollment networks for nintedanib extension studies.
Germany
Integrated care contracts in Bavaria and North Rhine-Westphalia bundle antifibrotic dispensing with pulmonologist case management. The EMA's Committee for Medicinal Products for Human Use applies harmonized fibrosis progression endpoints that reduce duplicate regulatory submissions. Heidelberg and Munich university hospitals coordinate the European ILD registry data collection infrastructure.
Japan
Aging demographics in the Kanto region expand the addressable patient pool for progressive fibrosing interstitial lung diseases. The PMDA's Sakigake designation pathway compresses priority review timelines for novel antifibrotic candidates. Tokyo and Osaka medical centers lead Asia-Pacific adoption of smart nebulizer pilot programs.
United Kingdom
NICE technology appraisals in England create coverage uncertainty for premium antifibrotic positioning outside idiopathic pulmonary fibrosis. The MHRA operates parallel recognition pathways with EMA decisions post-Brexit. The Royal Brompton Hospital and Manchester University NHS Foundation Trust anchor specialized ILD service configurations.
India
Domestic corticosteroid prescribing persistence in tier-2 cities limits antifibrotic penetration despite rising diagnosis rates. The CDSCO's accelerated approval pathway for unmet respiratory needs remains underutilized relative to oncology. Mumbai and Delhi tertiary pulmonology departments concentrate imported nintedanib access through hospital pharmacy carve-outs.
Progressive Pulmonary Fibrosis (PPF) Treatment Market Competitive Landscape
Premium-margin players sit above commodity-margin players across the antifibrotic-corticosteroid divide, with tyrosine kinase inhibitors commanding reimbursement premiums while generic immunosuppressants compete on access convenience. The vendor base consolidates around three structural tiers: established IPF franchise holders, emerging biologics developers, and device-integrated delivery specialists. Dominant competitive moves include indication expansion beyond idiopathic pulmonary fibrosis and nebulizer technology partnerships that capture adherence data.
Within the established franchise tier, Boehringer Ingelheim and Roche Holding AG occupy positions that exemplify divergent strategic vectors—one anchored in small-molecule kinase inhibition, the other leveraging immunology pipeline breadth. FibroGen Inc. represents the emerging biologics archetype with connective tissue disease-associated ILD positioning. These three entities collectively illustrate how regulatory acceleration pathways and reimbursement expansion are reshaping competitive positioning across the antifibrotic landscape.
| Leading Market Players |
|---|
| Boehringer Ingelheim |
| Roche Holding AG |
| FibroGen Inc. |
| Bristol Myers Squibb |
| Galapagos NV |
| United Therapeutics Corporation |
| Pliant Therapeutics |
| Vicore Pharma |
| Avalyn Pharma |
| Others |
Value Network & Pricing Analysis
EMA compliance with the EU Medical Device Regulation gates qualified supply of smart nebulizer systems and premium-tier antifibrotic access, as manufacturers must submit drug-device combination performance data to notified bodies in Germany and France before pricing authority materializes.
Pricing Analysis
Value-based contracting anchored to forced vital capacity decline reduction dominates reimbursement negotiations with Medicare Advantage plans. Three-tier pricing structure across premium antifibrotics, standard corticosteroid combinations, and economy generic immunosuppressants reflects certification tier and indication breadth. Cost compression in the corticosteroid tier is intensifying because of commodity API oversupply from Indian manufacturers. Community pulmonology practices exhibit highest price sensitivity, while tertiary academic medical centers prioritize clinical outcome guarantees over per-unit cost.
Supply Chain Analysis
Direct-to-hospital pharmacy channels handle antifibrotic dispensing for tertiary academic medical centers, with specialty distributors managing cold-chain logistics for clinical trial materials. API synthesis concentrates in India and China, with finished dose manufacturing anchored in Germany and the United States. Raw material dependencies span tyrosine kinase inhibitor intermediates, nebulizer device electronics, and medical-grade polymers. Single-source vulnerability in Chinese API feedstock exposes manufacturers to geopolitical supply interruptions. Distribution runs through integrated delivery network formularies with pulmonologist-majority therapeutic committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The PPF treatment market sits in a technology-transition phase, with smart nebulizer systems and remote patient monitoring platforms displacing oral capsule regimens as the standard of care anchor.
For Market Incumbents: Anticipate biosimilar pressure on tyrosine kinase inhibitor franchises by securing backward integration into API supply and embedding adherence sensors into next-generation delivery devices. Defensive consolidation around connective tissue disease-associated ILD indications preserves pricing power as idiopathic pulmonary fibrosis saturates. For New Entrants and Emerging Players: Community pulmonology practices in Medicare Advantage-dominated markets represent the most penetrable buyer archetype, as these settings lack prior authorization infrastructure for antifibrotic initiation. White-space targets include nebulized formulation development and value-based contracting pilots with risk-bearing entities. Go-to-market execution should prioritize hospital-at-home partnerships with remote monitoring integration. For Investors and Strategic Acquirers: FDA Breakthrough Therapy designation awards are the leading indicator that pipeline assets will command premium reimbursement trajectories. Long-term viability centers on indication expansion beyond idiopathic pulmonary fibrosis and device-therapy convergence capabilities. Acquisition targets should display biomarker-validated progression endpoints and pulmonology KOL network density. Watch EMA parallel endpoint harmonization decisions as the inflection signal for multi-country market entry economics.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA Breakthrough Therapy designation compresses development timelines for novel antifibrotic candidates. |
| Clinical Trial Advancement | Composite endpoint validation with forced vital capacity progression anchors Phase III evidence packages. |
| Manufacturing Scale-Up | Smart nebulizer production capacity expansion captures inhalation delivery mode growth trajectories. |
| Licensing Agreement | Device-therapy partnerships with German notified bodies accelerate EU MDR compliance timelines. |
| Pipeline Diversification | Connective tissue disease-associated ILD indications unlock underpenetrated rheumatology referral channels. |
Research Methodology
FDA filings, EMA submission documents, and ClinicalTrials.gov records formed the secondary backbone, supplemented by CMS Medicare reimbursement data and hospital procurement database extracts. Primary interviews with drug development executives, regulatory affairs leads, formulary directors, and payer access specialists validated prescribing pattern assumptions. Bottom-up patient flow modeling and top-down revenue triangulation converged on segment-level estimates across the analysis window.
Historical antifibrotic adoption curves and forced vital capacity endpoint progression rates informed the analytical framework over the projection horizon. Segmentation dimensions included pharmacological mechanism, delivery mode technology, care setting infrastructure, and regional regulatory cluster. CAGRs were derived from fitted growth curves applied to patient population projections and pricing trajectory assumptions. Forecast inputs incorporated Medicare Advantage penetration rates and smart nebulizer pilot program expansion timelines.
Revisions become necessary when FDA composite endpoint definitions shift, EMA harmonization protocols change, or API supply disruptions from geopolitical events materialize. Forecasts reflect assumptions about reimbursement stability and pulmonology guideline adoption velocity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Neurodegenerative Disorder Market
Specialty Medicine
Polychondritis Disease Treatment Market
Specialty Medicine
Asia-Pacific Sports Medicine Market
Specialty Medicine
Global Anal Fistula Treatment Market
Specialty Medicine
Hypopigmentation Disorder Treatment Market
Specialty Medicine
Global Parkinsons Disease Treatment Market
Specialty Medicine
Global Gastrointestinal Therapeutics Market
Specialty Medicine
Acute Myeloid Leukemia Therapeutics Market
Specialty Medicine
Granulomatosis with Polyangiitis Treatment Market
Specialty Medicine
Tularemia Therapeutics Market
Specialty Medicine
Dural Arteriovenous Fistulas Treatment Market
Specialty Medicine
Primary Ciliary Dyskinesia Market
Specialty Medicine
Borderline Personality Disorder Market
Specialty Medicine
Thoracic Outlet Syndrome Market
Specialty Medicine
Multiple Endocrine Neoplasia Market
Specialty Medicine
Asbestosis Treatment Market