
 Thyroid Cancer Therapeutics Market | 2026-2036
Thyroid Cancer Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Thyroid Cancer Therapeutics Market Analytics
Multi-source API procurement for kinase inhibitors is hardening as manufacturers hedge against supply disruptions. Bayer AG leverages its radiopharmaceutical infrastructure to sustain leadership in radioactive iodine therapies. Novartis AG anchors its position through differentiated RET and TRK inhibitor portfolios. Eisai Co., Ltd competes on geographic reach across Asian oncology markets.
Thyroid cancer therapeutics comprise systemic agents targeting molecular drivers of carcinogenesis, including small-molecule tyrosine kinase inhibitors, monoclonal antibodies, and radioisotope compounds administered via oral or intravenous routes. These agents function by interrupting angiogenic signaling, immune checkpoint evasion, or delivering localized radiation to follicular-derived malignancies. Targeted therapy dominates current revenue pools due to premium pricing for selective kinase inhibitors in radioactive iodine-refractory settings. Immunotherapy represents the fastest-expanding segment as PD-1/PD-L1 combinations advance through late-stage trials for anaplastic carcinoma. Hospital-based administration still captures the largest volume share, though oral targeted agents are shifting utilization toward clinics and homecare settings.
FDA oncology center reviews, EMA's Committee for Medicinal Products for Human Use assessments, and Japan's PMDA orphan drug frameworks collectively determine market access timelines for novel thyroid cancer agents. These regulators increasingly mandate real-world evidence portfolios alongside traditional trial endpoints, elevating post-market study commitments as a cost of entry. Stakeholders must monitor biomarker-defined trial designs and companion diagnostic co-development requirements as the pathway to differentiated positioning.
Market Dynamics
FDA breakthrough therapy designations and EMA conditional approvals are compressing development timelines for novel kinase inhibitors, while hospital-based oncology departments expand targeted therapy protocols and manufacturers harden multi-source API procurement.
Growth Catalysts
- Radioactive Iodine-Refractory Pathways:Well-established reimbursement frameworks in the United States, Germany, and Japan concentrate demand for selective kinase inhibitors. Hospital-based oncology departments actively expand protocol adoption for molecularly defined patient subsets.
- PD-1/PD-L1 Combination Trials:Late-stage immunotherapy development for anaplastic carcinoma creates new addressable populations. Academic medical centers in Japan and the United States drive patient enrollment for biomarker-stratified cohorts.
- EMA Conditional Approvals:Accelerated regulatory pathways compress time-to-market for novel agents. European reference pricing systems reward early entrants with preferential reimbursement status.
Market Restraints
- API Supply Concentration:Kinase inhibitor active pharmaceutical ingredient manufacturing clusters in India and China create single-source vulnerability. Geopolitical friction elevates forced localization mandates.
- Radiopharmaceutical Cold Chain:Iodine-131 and lutetium-177 require specialized logistics infrastructure with limited qualified carriers. Distribution radius constraints restrict patient access outside major metropolitan clusters.
- Companion Diagnostic Co-Development:FDA-mandated biomarker testing adds 18-24 months to development timelines. Small-cap developers lack capital for parallel diagnostic platform investment.
Strategic Opportunities
- Brazil and Mexico Expansion:ANVISA regulatory harmonization with FDA standards reduces duplicate trial requirements. Private oncology networks in São Paulo and Mexico City build capacity for targeted therapy administration.
- Homecare Oral Administration:Shift from hospital-based infusion to clinic and home settings for selective kinase inhibitors reduces capacity constraints. Specialty pharmacy networks capture dispensing margin.
- Real-World Evidence Mandates:FDA and EMA post-market study requirements create demand for data analytics infrastructure. Contract research organizations with oncology registries gain preferred vendor status.
Industry Challenges
- RET/TRK Biomarker Testing Penetration:Community oncology practices lack molecular pathology capacity for fusion detection. Academic center referral patterns fragment patient identification.
- Radiopharmaceutical Manufacturing Capacity:Cyclotron and reactor infrastructure requires 8-figure capital commitment with 7-year depreciation cycles. Reimbursement uncertainty deters capacity expansion.
- Cross-Border Reference Pricing:European ex-factory price disclosure creates parallel trade arbitrage. Manufacturers face margin compression in higher-price markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thyroid Cancer Therapeutics Market |
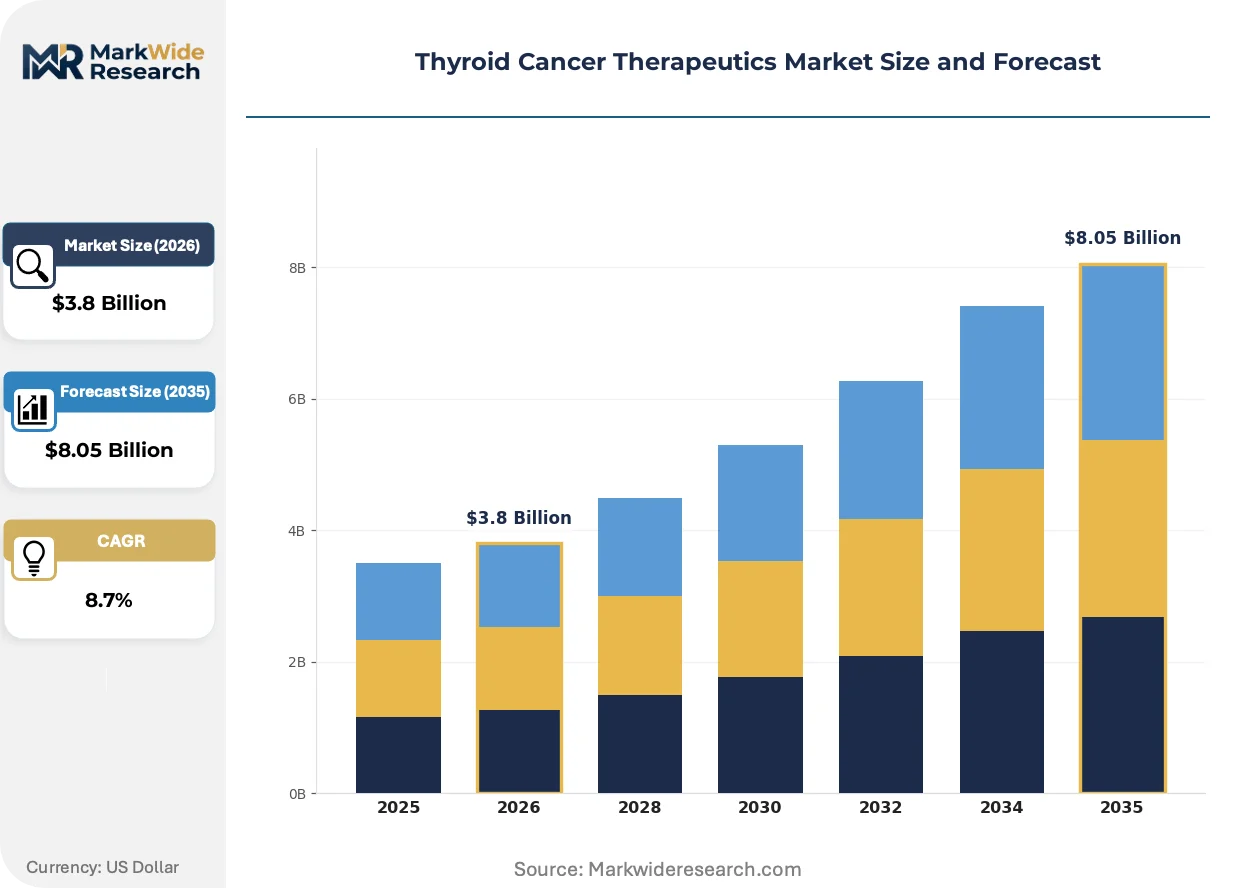
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Targeted Therapy, Immunotherapy, Chemotherapy, Radiotherapy Delivery Mode: Intravenous, Oral, Subcutaneous, Topical End User: Hospitals, Clinics, Homecare, Research Institutes Application: Papillary Carcinoma, Follicular Carcinoma, Anaplastic Carcinoma, Medullary Carcinoma |
| Companies Covered | Eisai Co., Ltd, Bayer AG, Novartis AG, AstraZeneca plc, Sanofi, F. Hoffmann-La Roche Ltd., Pfizer Inc, Exelixis Inc, Takeda Pharmaceutical Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thyroid Cancer Therapeutics Market Evolving Landscape
Next-generation sequencing is overtaking single-gene testing as the standard of care, while regulators demand real-world evidence portfolios and oral targeted agents shift administration settings away from hospitals.
Selective RET and TRK inhibitors are overtaking multikinase VEGF blockers as first-line options for fusion-positive disease. Academic medical centers in the United States and Japan now sequence all radioactive iodine-refractory patients at progression. This molecular stratification is overtaking histology-based treatment algorithms and compressing the addressable population for non-selective agents.
EMA's Committee for Medicinal Products for Human Use now mandates patient-reported outcome data alongside traditional progression-free survival endpoints. Conditional marketing authorizations require 5-year follow-up commitments with mandatory registry enrollment. Anaplastic carcinoma trials face the steepest compliance burden as regulators demand overall survival data from smaller patient pools.
Specialty pharmacy dispensing is overtaking hospital outpatient procurement for oral kinase inhibitors. Payers in Germany and the United States steer volume toward limited distribution networks with adherence monitoring. This channel consolidation is most visible in Medicare Part D and statutory health insurance frameworks where outcomes-based contracts are piloted.
Thyroid Cancer Therapeutics Market Segmentation
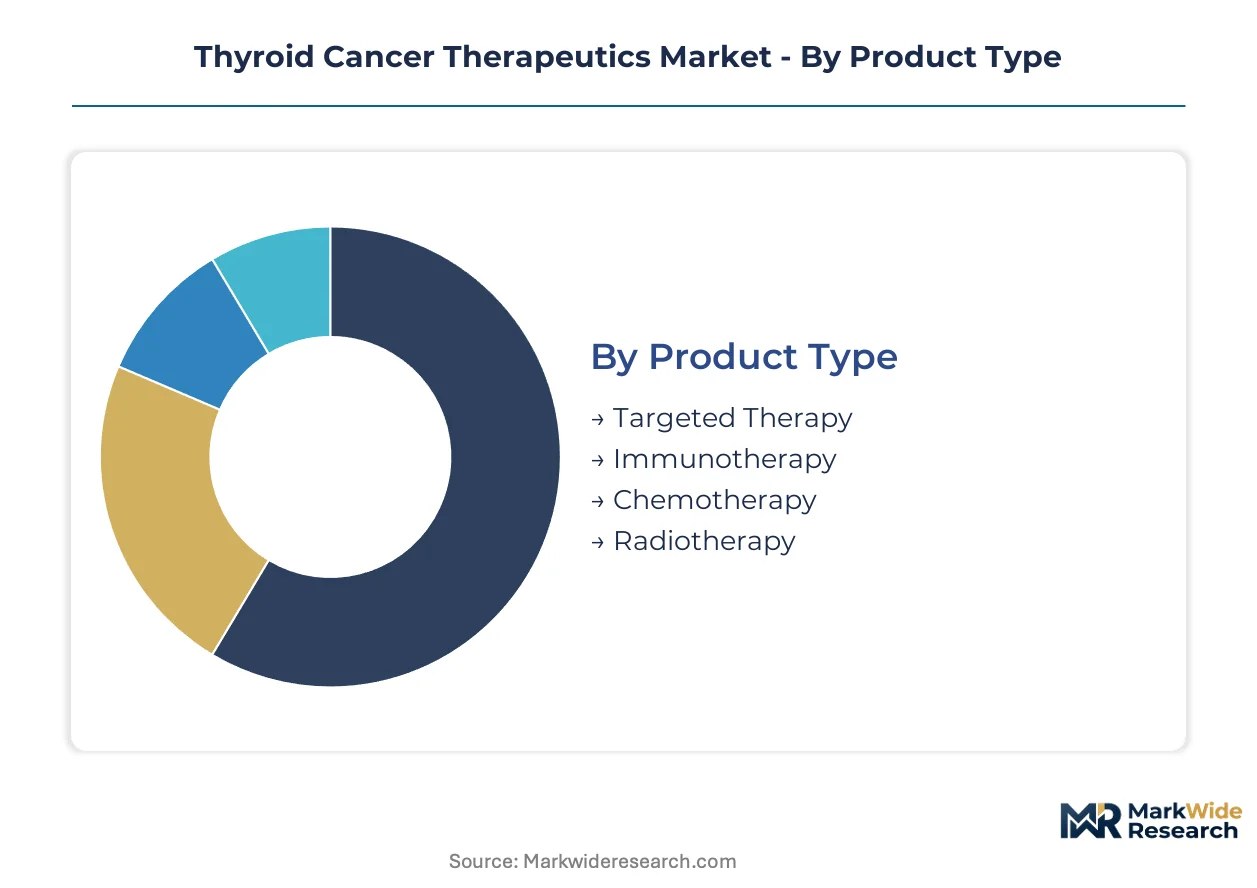
Segmentation in thyroid cancer therapeutics reveals how treatment selection follows molecular stratification rather than histology alone. Product categories diverge sharply between premium-priced kinase inhibitors and commoditized cytotoxic agents, while delivery modes track reimbursement incentives for site-of-care optimization.
Product Type:
Technology sophistication determines pricing tiers and development pipeline allocation across systemic treatment categories.
- Targeted Therapy:Small-molecule tyrosine kinase inhibitors selectively interrupt RET, TRK, and BRAF oncogenic signaling. United States academic medical centers drive demand for selective agents over multikinase VEGF blockers in radioactive iodine-refractory differentiated thyroid cancer.
- Immunotherapy:PD-1/PD-L1 checkpoint inhibitors function by reactivating T-cell surveillance against tumor immune evasion. Japan's PMDA orphan drug framework accelerates access for anaplastic carcinoma combinations where chemotherapy has failed.
- Chemotherapy:Doxorubicin and paclitaxel regimens retain utility in undifferentiated histologies lacking actionable mutations. Community oncology practices in Germany deploy these agents where molecular testing infrastructure remains limited.
- Radiotherapy:Iodine-131 and lutetium-177 deliver localized beta radiation to iodine-avid follicular-derived malignancies. Hospital-based nuclear medicine departments control access through specialized handling protocols.
Mature deployment sits with targeted therapy. Newer deployment is concentrated in immunotherapy.
Delivery Mode:
Route of administration directly shapes site-of-care economics and patient adherence monitoring requirements.
- Oral:Kinase inhibitors with once-daily dosing enable outpatient dispensing through specialty pharmacy networks. Medicare Part D and German statutory health insurance frameworks increasingly mandate limited distribution channels with telehealth adherence support.
- Intravenous:Checkpoint inhibitors and cytotoxic agents require infusion center capacity with hypersensitivity monitoring. Hospital outpatient departments capture margin from administration fees and drug markup in fee-for-service reimbursement environments.
- Subcutaneous:Emerging formulations of established antibodies reduce infusion duration and chair time constraints. Clinics in São Paulo pilot these alternatives to decompress hospital capacity.
- Topical:Investigational formulations for cutaneous metastases remain confined to early-phase trials with limited commercial trajectory.
Volume concentrates in intravenous delivery. Oral administration is climbing the fastest as payers steer toward lower-cost sites of care.
End User:
Care setting fragmentation reflects reimbursement differentials and regulatory complexity for radioactive isotope handling.
- Hospitals:Academic medical centers in the United States and Japan anchor molecular tumor board decision-making for fusion-positive disease. Nuclear medicine infrastructure for iodine-131 therapy requires institutional licensing unavailable in smaller facilities.
- Clinics:Community oncology practices in Germany handle oral targeted therapy initiation with remote academic center consultation for complex cases. Payer contracts increasingly exclude infusion-only agents from this channel.
- Homecare:Specialty pharmacy networks with nursing support manage oral kinase inhibitor adherence monitoring. United States commercial payers pilot outcomes-based contracts linking reimbursement to progression-free survival metrics.
- Research Institutes:Phase I units in Tokyo and Boston enroll biomarker-defined cohorts for novel mechanism agents. EMA conditional approval pathways mandate continued registry enrollment through these sites.
Hospital infrastructure dominates radiotherapy administration. Homecare penetration is expanding most quickly for oral targeted agents with established safety profiles.
Application:
Histology-specific treatment algorithms have fragmented as next-generation sequencing identifies actionable drivers across traditional categories.
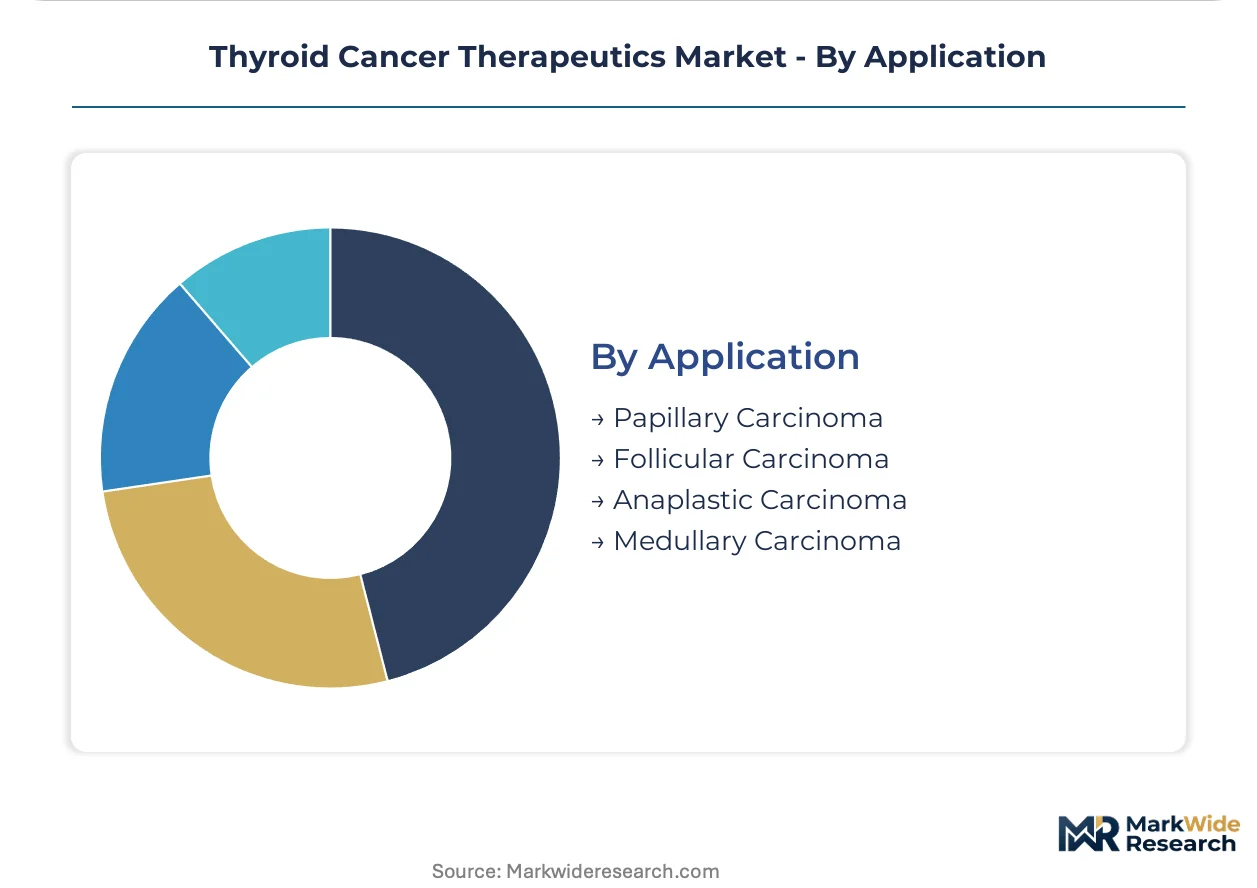
- Papillary Carcinoma:The most common differentiated subtype now stratifies into BRAF-mutant, RET-fusion, and RAS-mutant molecular cohorts with distinct therapeutic trajectories. United States community oncology practices face pressure to refer all radioactive iodine-refractory cases for molecular profiling.
- Anaplastic Carcinoma:Undifferentiated histology with dismal prognosis has become the focus of PD-1/PD-L1 combination trials. Japan's PMDA offers expedited review for agents demonstrating survival benefit in this orphan indication.
- Medullary Carcinoma:RET-mutant disease, whether sporadic or MEN2-associated, now receives selective RET inhibitor therapy rather than multikinase blockade. German reference pricing systems reward early entrants with preferential reimbursement status.
- Follicular Carcinoma:RAS-mutant and PAX8-PPAR-gamma rearranged subtypes retain iodine avidity longer than other differentiated cancers. Radioactive iodine therapy remains first-line in this population outside the United States.
Papillary carcinoma commands the largest patient volume. Anaplastic carcinoma represents the steepest expansion trajectory as immunotherapy combinations create first viable therapeutic options.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Radioisotope manufacturing infrastructure anchors therapeutic access across major markets, with cyclotron and reactor capacity determining patient reach for iodine-avid disease. Reimbursement pathways for radioactive iodine-refractory settings concentrate demand in markets with established molecular testing infrastructure. Regulatory acceleration mechanisms now shape competitive entry timelines more than manufacturing scale alone.
United States
Academic medical centers in Boston and Houston drive biomarker-stratified trial enrollment for anaplastic carcinoma combinations. FDA breakthrough therapy designations compress review timelines for selective RET inhibitors. MD Anderson Cancer Center and Memorial Sloan Kettering anchor molecular tumor board decision-making for fusion-positive differentiated disease.
Germany
Statutory health insurance frameworks reward early entrants with preferential reimbursement status for kinase inhibitors. EMA conditional marketing authorizations mandate five-year follow-up commitments with mandatory registry enrollment. Heidelberg and Munich university hospitals control access to lutetium-177 through specialized nuclear medicine licensing.
Japan
PMDA orphan drug frameworks accelerate access for anaplastic carcinoma where chemotherapy has failed. Tokyo and Osaka academic centers enroll biomarker-defined cohorts for PD-1 combination trials. Domestic manufacturers leverage geographic reach across Asian oncology markets through established distribution networks.
United Kingdom
NICE technology appraisals determine NHS funding for selective kinase inhibitors in radioactive iodine-refractory settings. The Royal Marsden and Christie Hospital anchor molecular testing capacity for RET and TRK fusion detection. London and Manchester oncology networks pilot outcomes-based contracts linking reimbursement to progression-free survival metrics.
Brazil
ANVISA regulatory harmonization with FDA standards reduces duplicate trial requirements for novel agents. Private oncology networks in São Paulo build capacity for targeted therapy administration outside hospital settings. Domestic reference pricing creates parallel trade pressure from Argentine and Chilean markets.
Thyroid Cancer Therapeutics Market Competitive Landscape
Global majors compete with regional champions across radiopharmaceutical infrastructure and kinase inhibitor portfolios. Market structure concentrates around three strategic tiers: integrated radiopharma manufacturers with reactor access, selective kinase inhibitor specialists with biomarker-defined positioning, and immunotherapy developers targeting anaplastic carcinoma. Dominant competitive moves include M&A for molecular diagnostic capabilities and strategic partnerships for real-world evidence generation.
Within the radiopharmaceutical tier, Bayer AG exemplifies integrated manufacturing infrastructure. Among kinase inhibitor specialists, Novartis AG and Eisai Co., Ltd occupy positions defined by RET and TRK portfolio differentiation. These three anchors represent distinct competitive archetypes: backward integration into isotope production, selective target precision, and geographic reach expansion respectively.
| Leading Market Players |
|---|
| Eisai Co., Ltd |
| Bayer AG |
| Novartis AG |
| AstraZeneca plc |
| Sanofi |
| F. Hoffmann-La Roche Ltd. |
| Pfizer Inc |
| Exelixis Inc |
| Takeda Pharmaceutical Company |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap API manufacturers in India and China anchor kinase inhibitor production, linking concentrated upstream ownership to disciplined contract pricing for multinationals seeking supply security. Their financing structures favor long-term offtake agreements over spot-market exposure, creating pricing rigidity that transfers cost volatility downstream to finished-dose marketers.
Pricing Analysis
Warranty-bundled cold-chain guarantees separate radiopharmaceutical contracts from standard pharmaceutical procurement, with iodine-131 shipments commanding premium logistics fees unavailable to oral kinase inhibitors. Three-tier pricing structure across premium selective RET inhibitors, standard multikinase VEGF blockers, and economy cytotoxic agents reflects biomarker stratification and reimbursement tiering. Pricing pressure stems from European reference pricing systems that compress ex-factory margins through cross-border parallel trade. Community oncology practices in Germany exhibit highest price sensitivity due to statutory health insurance reimbursement ceilings, while United States academic medical centers demonstrate lowest sensitivity where breakthrough therapy designations support premium positioning.
Supply Chain Analysis
Direct-to-hospital channels handle radioactive isotope demand, with nuclear medicine departments in Boston, Heidelberg, and Tokyo controlling patient access through specialized licensing. Active pharmaceutical ingredient manufacturing draws from India, China, and Switzerland for kinase inhibitor precursors, while reactor-produced isotopes rest on Canadian and European supply. Single-source vulnerability concentrates in lutetium-177 production, where limited qualified cyclotron infrastructure creates patient access bottlenecks outside major metropolitan clusters. Distribution runs through hospital-based nuclear pharmacies for radiopharmaceuticals, contrasting with specialty pharmacy networks for oral targeted agents.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race, with radiopharmaceutical infrastructure and biomarker testing capacity serving as the decisive upstream levers separating integrated manufacturers from asset-light competitors.
For Market Incumbents: Cement control over isotope manufacturing infrastructure through reactor access agreements or cyclotron partnerships, insulating against supply interruptions that would halt radioactive iodine therapy protocols. Secure molecular diagnostic co-development relationships with companion diagnostic platforms, as FDA-mandated biomarker testing requirements now gate market entry for selective kinase inhibitors. For New Entrants and Emerging Players: Specialty pharmacy networks with adherence monitoring capabilities offer the most penetrable channel for oral targeted agents, particularly where Medicare Part D and German statutory health insurance frameworks steer volume toward limited distribution. Target Brazil and Mexico through ANVISA regulatory harmonization pathways, positioning for private oncology network expansion in São Paulo and Mexico City. For Investors and Strategic Acquirers: EMA conditional approval announcements are the leading indicator that five-year registry enrollment commitments will create sustained revenue visibility for novel mechanism agents. Focus acquisition screening on selective RET and TRK inhibitor developers with differentiated biomarker-defined positioning, as molecular stratification displaces histology-based treatment algorithms across the projection horizon.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | PD-1 combination trials for anaplastic carcinoma create first viable therapeutic options in orphan indication. |
| Regulatory Approval Pathway | FDA breakthrough therapy designations compress review timelines for selective kinase inhibitors. |
| Manufacturing Scale-Up | Cyclotron capacity expansion addresses lutetium-177 supply constraints in major metropolitan clusters. |
| Licensing Agreement | Companion diagnostic co-development satisfies FDA biomarker testing mandates for fusion-positive disease. |
| Pipeline Diversification | Real-world evidence infrastructure investments meet EMA five-year follow-up registry requirements. |
Research Methodology
Multi-period observation of FDA breakthrough therapy designations, EMA conditional marketing authorizations, and Japan PMDA orphan drug approvals anchored the trend analysis, supplemented by interviews with drug development executives, regulatory affairs leads, formulary directors at United States payers, and hospital procurement managers in Germany and Japan. Secondary validation drew from FDA filings, EMA Committee for Medicinal Products for Human Use assessments, ClinicalTrials.gov protocol registries, and statutory health insurance formulary databases. Bottom-up patient-flow modeling and top-down revenue triangulation cross-checked segment-level projections.
Input-output matrices mapped treatment line progression, administration route shifts from hospital to homecare settings, and regional regulatory cluster adoption curves across the analysis window. Segmentation dimensions included product type, delivery mode, end-user setting, and histology-specific application. CAGRs derived from patient population epidemiology, pricing trajectory assumptions, and protocol penetration rates for molecularly defined subsets. Forecast inputs incorporated biomarker testing infrastructure buildout and reimbursement pathway evolution for radioactive iodine-refractory disease.
Caveats apply where radiopharmaceutical manufacturing disruptions, companion diagnostic platform delays, or European reference pricing arbitrage could materially shift the outlook. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Scleritis Market
Specialty Medicine
Hashimoto's Thyroiditis Therapeutics Market
Specialty Medicine
Mitochondrial Disorders Treatment Market
Specialty Medicine
Ulcerated Necrobiosis Lipoidica Management Market
Specialty Medicine
Glioma Therapeutics Market
Specialty Medicine
Pleurisy Market
Specialty Medicine
Sjogrens Syndrome Market
Specialty Medicine
Global Constipation Treatment Market
Specialty Medicine
Piriformis Syndrome Market
Specialty Medicine
Metabolic Disorders Therapeutics Market
Specialty Medicine
Global Urea Cycle Disorder Market
Specialty Medicine
Gaucher and Pompe Diseases Enzyme Replacement Therapy (ERT) Market
Specialty Medicine
Global Bladder Disorders Market
Specialty Medicine
Synovial Sarcoma Market
Specialty Medicine
Asbestosis Treatment Market
Specialty Medicine
Global Prurigo Nodularis Treatment Market