
 Glaucoma Market | 2026-2036
Glaucoma Market Size, Share, and Industry Trends Forecast 2026-2036
Glaucoma Market Analytics
Ophthalmology clinic procurement is rewriting how glaucoma therapies reach patients in developed markets. Glaukos Corporation leverages its micro-invasive stent portfolio to dominate the surgical segment. Pfizer sustains broad commercial reach through established primary care and specialist networks across multiple continents.
Glaucoma comprises a group of optic neuropathies characterized by progressive retinal ganglion cell loss and visual field defects, with intraocular pressure reduction serving as the primary modifiable treatment target. Prostaglandin analogues anchor first-line medical therapy due to superior efficacy and once-daily dosing convenience. Implantable delivery systems represent the fastest-expanding modality as manufacturers pursue multi-year sustained-release formulations that reduce patient adherence failures.
FDA 510(k) and PMA pathways govern device-based interventions, while EMA centralized procedures shape European market access for novel drug-device combinations. The EU MDR transition is forcing manufacturers to resubmit clinical evidence for legacy ophthalmic implants. Stakeholders must monitor how sustained-release platform approvals in one jurisdiction create precedent pressure in others.
Market Dynamics
Sustained-release implant platforms are compressing the traditional daily drop regimen into multi-year interventions, forcing manufacturers to restructure clinical trial designs and reimbursement negotiations around surgical procedure economics rather than pharmaceutical recurring revenue models.
Growth Catalysts
- EU MDR transition:Legacy ophthalmic implants require resubmitted clinical evidence, accelerating consolidation among manufacturers with robust quality management systems and clinical data archives.
- Minimally invasive glaucoma surgery (MIGS):Ophthalmology clinics in Germany and Japan are expanding MIGS suites as first-line surgical intervention before trabeculectomy, creating procedural volume growth.
- Aging demographics:The United States, Germany, and Japan exhibit concentrated demand from patients over 65 requiring advanced therapy uptake supported by established reimbursement frameworks.
Market Restraints
- Silicone raw material volatility:Implantable delivery systems depend on medical-grade silicone supply chains concentrated in East Asian contract manufacturers, exposing cost structure pressure.
- FDA PMA pathway duration:Novel drug-device combinations face 18-36 month review timelines with iterative clinical data requests, delaying commercialization.
- Pharmacological substitution:Prostaglandin analogues with once-daily dosing convenience and generic availability limit surgical conversion rates in cost-sensitive patient segments.
Strategic Opportunities
- Japan's PMDA Sakigake designation:Expedited review pathways for sustained-release implants enable first-mover positioning in the Asia-Pacific's highest-value ophthalmology market.
- Telemedicine integration:Remote intraocular pressure monitoring via home tonometry devices creates adherence tracking data that supports value-based reimbursement negotiations with United States payers.
- Neuroprotection convergence:Combining pressure-lowering implants with retinal ganglion cell preservation therapies represents unclaimed white space in disease modification.
Industry Challenges
- Microsurgical skill scarcity:MIGS procedures require specialized training in angle anatomy visualization, limiting adoption velocity in community ophthalmology practices.
- EU MDR notified body capacity:Certification backlog for legacy implant resubmissions extends compliance timelines, freezing product portfolio decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glaucoma Market |
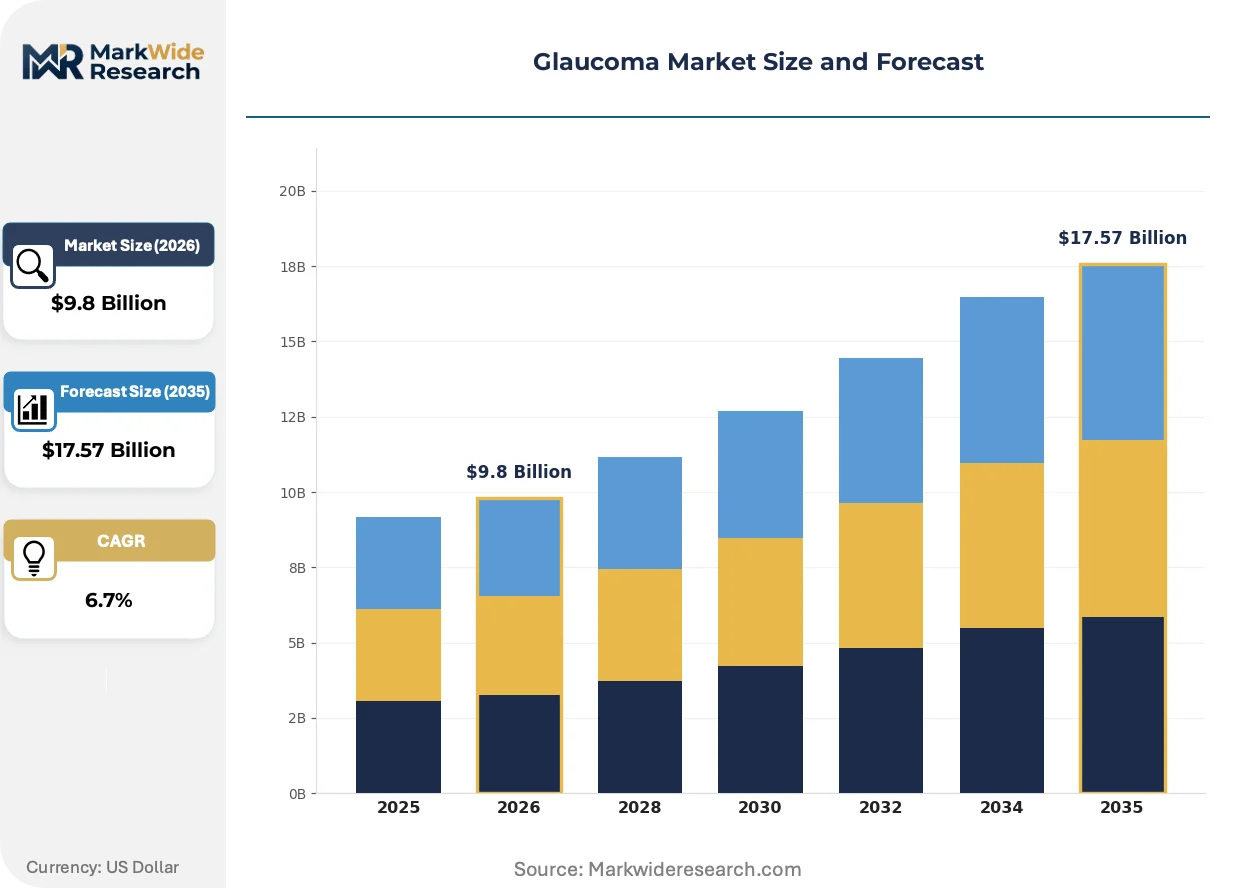
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $17.57 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prostaglandin Analogues, Beta Blockers, Alpha Agonists, Carbonic Anhydrase Inhibitors Delivery Mode: Topical, Injectable, Implantable, Oral End User: Ophthalmology Clinics, Hospitals, Home Care, Research Laboratories Indication: Open-Angle Glaucoma, Angle-Closure Glaucoma, Normal-Tension Glaucoma, Secondary Glaucoma |
| Companies Covered | Glaukos Corporation, Pfizer, Alcon, Nicox Ophthalmics, Merck & Co. Inc, Allergan, Santen Pharmaceutical, AbbVie, Bausch + Lomb, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glaucoma Market Evolving Landscape
Implantable sustained-release platforms are collapsing the boundary between pharmaceutical and device regulatory frameworks, compelling manufacturers to build hybrid clinical evidence packages that satisfy both FDA Center for Drug Evaluation and Research and Center for Devices and Radiological Health requirements simultaneously.
Biodegradable polymer matrices loaded with prostaglandin analogues are hybridizing the pharmacokinetic profile of daily drops with the compliance assurance of surgical intervention. Academic medical centers in the United States are piloting these systems in treatment-naïve patients, compressing the traditional step-care algorithm that reserved surgery for refractory cases. This hybridization is eroding the historical segmentation between medical and surgical management paradigms.
EMA's centralized procedure for drug-device combinations under the EU MDR is mandating single-quality management system audits spanning pharmaceutical GMP and ISO 13485 requirements. Manufacturers must now maintain unified technical documentation that satisfies both medicinal product and medical device conformity assessment criteria. European ophthalmology clinics are responding by consolidating supplier relationships toward vendors with demonstrated dual-framework compliance.
Hospital procurement departments are unbundling device procurement from surgeon preference, establishing value analysis committees that evaluate sustained-release implants against total cost-of-care metrics including adherence monitoring and progression-related vision loss. United States integrated delivery networks are most advanced in this transition, replacing individual physician choice with formulary-based technology assessment protocols that prioritize longitudinal economic modeling over upfront device cost.
Glaucoma Market Segmentation
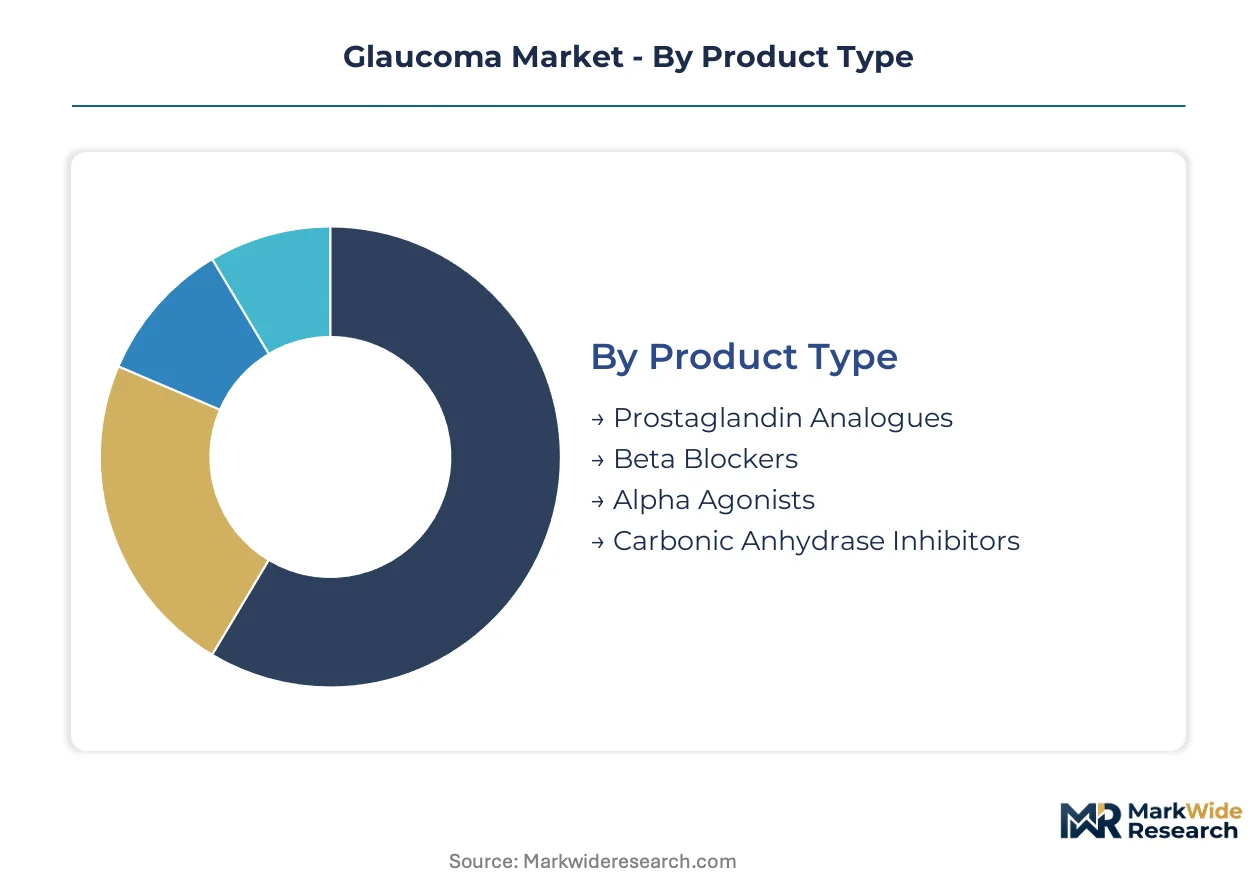
Glaucoma therapeutics fragment across pharmacological mechanisms, procedural interventions, and care settings that each impose distinct regulatory and reimbursement requirements. Manufacturers must align portfolio development with where clinical decision-making authority concentrates.
Product Type:
Pharmacological classes span the adherence-complexity spectrum from convenient daily drops to complex surgical adjuncts.
- Prostaglandin Analogues:Synthetic prostaglandin F2α analogues reduce intraocular pressure by enhancing uveoscleral outflow with once-daily dosing convenience. Demand concentrates in United States retail pharmacy channels where generic latanoprost availability has compressed branded pricing.
- Beta Blockers:Non-selective beta-adrenergic antagonists decrease aqueous humor production through ciliary body suppression. Germany's statutory health insurance funds maintain preferred formulary status for timolol despite prostaglandin efficacy advantages in cost-sensitive patient segments.
- Alpha Agonists:Dual-mechanism agents combining aqueous suppression and uveoscleral outflow enhancement serve as second-line therapy.
- Carbonic Anhydrase Inhibitors:Systemic and topical formulations target aqueous production reduction in refractory cases.
Established volume favors prostaglandin analogues; emerging adoption favors carbonic anhydrase inhibitors in combination regimens.
Delivery Mode:
Administrative route determines regulatory pathway duration and reimbursement coding complexity.
- Topical:Eye drop formulations dominate first-line therapy through patient self-administration and pharmacy distribution economics. Japan's NHI price listing revisions every two years create pricing volatility for preserved and preservative-free formulations.
- Implantable:Sustained-release devices inserted via minimally invasive procedures eliminate adherence failures. FDA PMA submissions for biodegradable matrices are climbing as manufacturers pursue multi-year dosing intervals.
- Injectable:Intravitreal and intracameral administrations target refractory cases.
- Oral:Systemic carbonic anhydrase inhibitors serve acute pressure reduction.
Topical administration captures procedure volume; implantable systems are expanding most quickly through surgical suite integration.
End User:
Site-of-care economics reshape procurement authority and technology adoption velocity.
- Ophthalmology Clinics:Ambulatory surgery centers and specialist practices perform the majority of MIGS procedures with direct device purchasing authority. United States integrated delivery networks are consolidating vendor contracts across clinic networks.
- Hospitals:Academic medical centers conduct complex trabeculectomy and tube shunt surgeries for refractory glaucoma. Germany's DRG-based hospital reimbursement favors outpatient migration where clinically appropriate.
- Home Care:Self-administered topical therapy dominates chronic management.
- Research Laboratories:Academic and commercial research sites drive neuroprotection pipeline development.
Ophthalmology clinics command device procurement; hospital systems retain complex surgical volume.
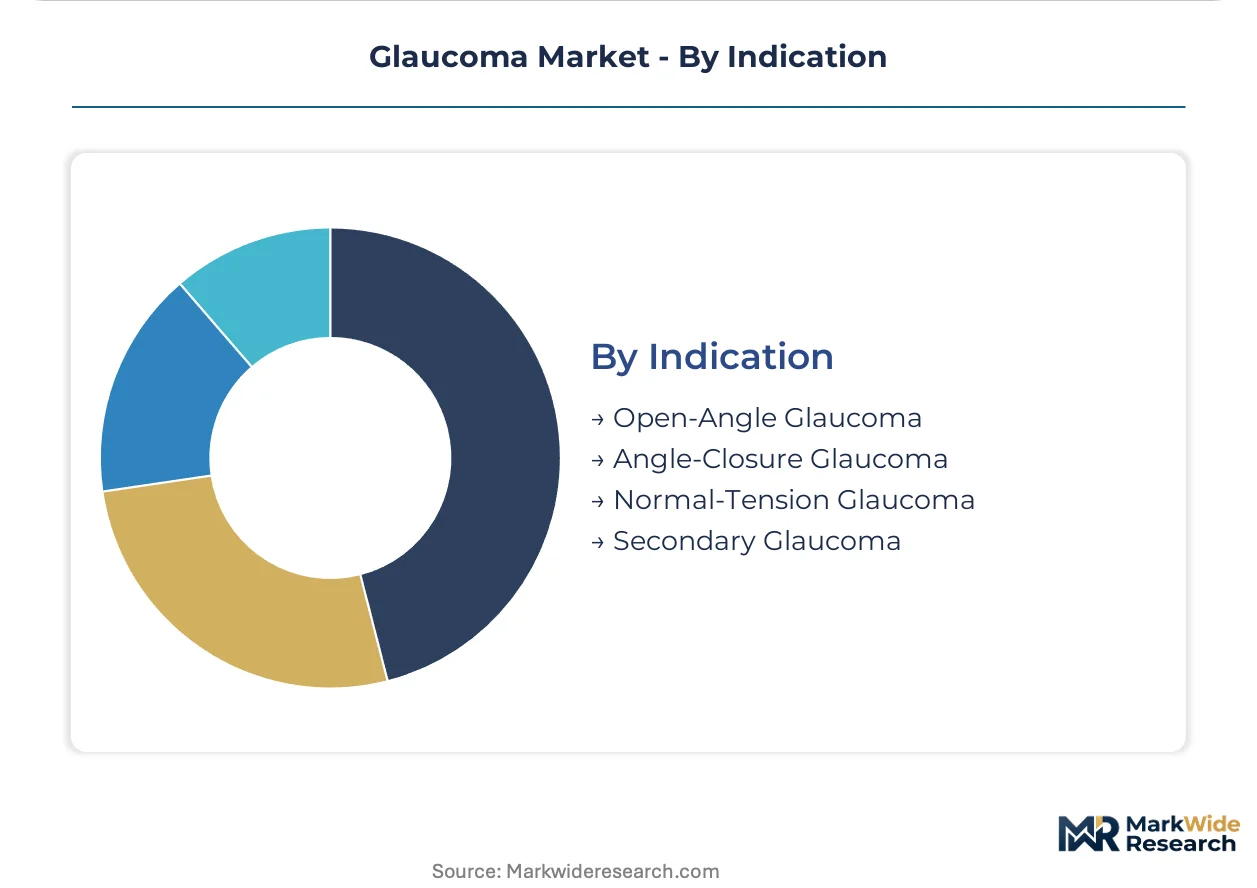
Indication:
Disease subtype dictates pressure target aggressiveness and surgical candidacy thresholds.
- Open-Angle Glaucoma:Chronic progressive optic neuropathy with normal anterior chamber anatomy represents the predominant surgical addressable market. Japan's aging demographic concentrates prevalence in patients over 70 requiring sustained-release alternatives to drop burden.
- Angle-Closure Glaucoma:Anatomical iris-cornea apposition creates acute pressure emergencies requiring immediate laser or surgical intervention. United States emergency department presentations drive acute procedural volume.
- Normal-Tension Glaucoma:Optic nerve damage progresses despite statistically normal intraocular pressure.
- Secondary Glaucoma:Steroid-induced, traumatic, and neovascular etiologies require etiology-specific management.
Open-angle glaucoma anchors procedural economics; angle-closure presentations generate acute intervention demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in the United States exceeds that in Germany by substantial margins, while Japan commands premium positioning for sustained-release implants. Reimbursement frameworks and aging demographics concentrate demand across these three markets, with regulatory pathways in each jurisdiction creating distinct commercialization timelines.
United States
Medicare Part B coverage for MIGS procedures drives ophthalmology clinic investment in surgical suites, with integrated delivery networks consolidating vendor contracts across multi-state footprints. FDA PMA pathway requirements for novel implants extend review timelines, favoring manufacturers with established quality management systems. The Cleveland Clinic and Bascom Palmer Eye Institute anchor clinical trial recruitment for biodegradable matrix platforms.
Germany
Statutory health insurance funds maintain prostaglandin analogue formularies despite surgical efficacy advantages, compressing branded pricing in retail pharmacy channels. EU MDR transition mandates resubmitted clinical evidence for legacy implants, accelerating consolidation among notified body-certified manufacturers. The Rhine-Ruhr metropolitan region concentrates ophthalmology clinic networks performing outpatient MIGS migration from hospital DRG reimbursement.
Japan
PMDA Sakigake designation for sustained-release implants enables expedited review pathways, attracting manufacturers seeking first-mover positioning in Asia-Pacific's highest-value market. NHI price listing revisions every two years create pricing volatility for preserved and preservative-free formulations. Tokyo and Osaka metropolitan areas concentrate patients over 70 requiring alternatives to daily drop burden.
United Kingdom
NICE technology appraisals for glaucoma interventions emphasize cost-effectiveness thresholds that favor generic prostaglandin analogues over premium surgical devices. NHS England's specialized commissioning framework restricts MIGS procedure authorization to designated centers of excellence. Moorfields Eye Hospital anchors national referral patterns for complex surgical cases requiring trabeculectomy or tube shunt interventions.
Switzerland
Swissmedic's streamlined approval pathways for drug-device combinations attract manufacturers seeking European market entry ahead of EMA centralized procedures. Mandatory health insurance coverage for glaucoma management supports uptake of advanced surgical interventions in private clinic settings. The Lake Geneva region concentrates ophthalmology research institutions piloting neuroprotection combination therapies.
Glaucoma Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying biodegradable matrices and micro-stent geometries. The market structures around three tiers: multinational pharmaceutical conglomerates with device divisions, pure-play ophthalmic device specialists, and regional generic manufacturers. Dominant competitive moves include strategic partnerships between drug and device developers, plus geographic expansion through distributor acquisitions in Asia-Pacific markets.
Among pure-play device specialists, Glaukos Corporation exemplifies the micro-invasive stent archetype, while Santen Pharmaceutical occupies a position bridging pharmaceutical and surgical modalities. Pfizer anchors the multinational conglomerate tier with broad commercial infrastructure spanning primary care and specialist networks. These three entities represent distinct strategic postures: device-centric innovation, hybrid drug-device development, and scale-driven pharmaceutical distribution.
| Leading Market Players |
|---|
| Glaukos Corporation |
| Pfizer |
| Alcon |
| Nicox Ophthalmics |
| Merck & Co. Inc |
| Allergan |
| Santen Pharmaceutical |
| AbbVie |
| Bausch + Lomb |
| Others |
Value Network & Pricing Analysis
East Asian medical-grade silicone manufacturing clusters anchor implantable delivery system supply, with capacity allocation decisions in these hubs transmitting directly into downstream pricing power for sustained-release glaucoma device manufacturers.
Pricing Analysis
Configured-to-order pricing for patient-customized implant geometries commands substantial premiums over standard off-the-shelf stent configurations. Three-tier pricing structure across premium, standard, and economy levels stratifies by FDA PMA approval status and biodegradable polymer matrix composition. Cost compression in the standard tier is intensifying because generic prostaglandin analogues limit surgical conversion rates. Hospital procurement committees exhibit highest price sensitivity, while academic medical centers demonstrate lowest sensitivity due to research funding overlays.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculus for medical-grade silicone procurement. Manufacturing concentrates in China, South Korea, and Japan, with raw material dependencies spanning pharmaceutical-grade polymers, precision micro-molding components, and biocompatible coating chemistries. Single-source vulnerability persists for specialized angle-anatomy visualization equipment. Distribution runs through ophthalmology clinic networks and hospital value analysis committees rather than traditional pharmaceutical wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through United States integrated delivery network consolidation, with multi-state ophthalmology clinic chains extracting volume discounts that reshape vendor profitability thresholds.
For Market Incumbents: Build regulatory data moats through preemptive FDA 510(k) and PMA pathway submissions for next-generation biodegradable matrices. Consolidate backward integration into pharmaceutical-grade polymer production to offset silicone raw material volatility. Channel control through exclusive ophthalmology clinic partnerships represents the critical defensive lever against emerging hybrid drug-device competitors. For New Entrants and Emerging Players: Community ophthalmology practices in Germany's Rhine-Ruhr region represent the most penetrable entry point, given MIGS suite expansion outpacing specialized microsurgical training availability. Japan's PMDA Sakigake designation pathway offers regulatory fast-track positioning for sustained-release implant platforms. Direct-to-clinic sales models bypassing traditional hospital procurement committees provide the optimal go-to-market angle. For Investors and Strategic Acquirers: Long-term, this sits as a disease-modification convergence play because neuroprotection combination therapies represent unclaimed white space beyond pressure-lowering mechanistic boundaries. Acquisition targets should prioritize dual-framework compliance capabilities spanning pharmaceutical GMP and ISO 13485 quality management systems. The signal to watch is sustained-release implant approval precedents creating cross-jurisdiction regulatory pressure.| Strategic Initiative | Industry Significance |
|---|---|
| FDA PMA Pathway Advancement | Preemptive submissions for biodegradable matrices secure multi-year dosing interval market positioning. |
| EU MDR Resubmission Compliance | Legacy implant recertification accelerates consolidation among notified body-certified manufacturers. |
| Hospital System Partnership | Integrated delivery network formulary placement replaces individual surgeon preference with value-based procurement. |
| Telemedicine Platform Integration | Remote intraocular pressure monitoring generates adherence data supporting payer reimbursement negotiations. |
| Biodegradable Polymer R&D Investment | Hybrid pharmacokinetic profiles compress step-care algorithms toward earlier surgical intervention. |
Research Methodology
Operator-level perspectives from ophthalmology clinic procurement directors, hospital value analysis committee members, biomedical engineers, and GPO contracts managers anchored the qualitative base. Primary interview data combined with secondary validation from FDA 510(k) and PMA filings, EMA centralized procedure submissions, ClinicalTrials.gov registries, and CMS Medicare reimbursement databases. Bottom-up procedure volume modeling and top-down pharmaceutical revenue triangulation converged on segment-level estimates.
Scenario-bracketing framed the analytical approach across the projection horizon, with segmentation dimensions spanning pharmacological mechanism, delivery mode, end-user site-of-care, and disease indication subtype. CAGRs derived from procedure volume trajectories and pricing elasticity modeling incorporated EU MDR transition timelines, PMDA Sakigake designation pathways, and NHI price revision cycles as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in statutory health insurance reimbursement rates or medical-grade silicone commodity pricing would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory approval timelines and surgical training adoption curves. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Atopic Dermatitis Market
Specialty Medicine
Rumination Syndrome Market
Specialty Medicine
Glucagon Therapy Market
Specialty Medicine
Chimeric Antigen Receptor (CAR) T-Cell Therapy Market
Specialty Medicine
Global Brain Tumor Therapeutics Market
Specialty Medicine
Bulimia Nervosa Market
Specialty Medicine
Grand Mal Seizure Market
Specialty Medicine
Acute Lymphocytic-Lymphoblastic Leukemia (ALL) Therapeutics Market
Specialty Medicine
Non-Alcoholic Fatty Liver Disease (NAFLD) Market
Specialty Medicine
Desmoid Tumor Market
Specialty Medicine
Cystic Fibrosis Transmembrane Conductance Regulator (CFTR) Market
Specialty Medicine
Middle East and Africa Primary Angle-Closure Glaucoma Market
Specialty Medicine
Global Polycystic Ovarian Syndrome Treatment Market
Specialty Medicine
Toxic Epidermal Neurolysis Market
Specialty Medicine
Intramedullary Osteosarcoma Treatment Market
Specialty Medicine
Selectin Blocker Market