
 Adrenogenital Syndrome Treatment Market | 2026-2036
Adrenogenital Syndrome Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Adrenogenital Syndrome Treatment Market Outlook
Multi-source API procurement for hydrocortisone and fludrocortisone is repositioning supply security for generic-dependent treatment protocols. Pfizer Inc. leverages its established corticosteroid manufacturing infrastructure to sustain cost-competitive tablet production. Novo Nordisk anchors its endocrine portfolio through specialized hormone replacement competencies. Sandoz competes aggressively on oral formulation accessibility across European and North American hospital formularies.
Adrenogenital syndrome treatment encompasses pharmacological and surgical interventions targeting congenital adrenal hyperplasia, a group of autosomal recessive disorders impairing cortisol biosynthesis due to 21-hydroxylase deficiency or related enzyme defects; hydrocortisone doses are titrated to mimic physiologic cortisol circadian rhythm while fludrocortisone replaces deficient aldosterone. The primary purpose is preventing adrenal crisis, normalizing virilization, and enabling standard growth trajectories in pediatric patients while maintaining fertility and metabolic stability in adults. Hormonal therapy occupies the dominant revenue share as lifelong glucocorticoid and mineralocorticoid replacement remains non-discretionary for all classical presentations. Enzyme replacement therapy represents the fastest-evolving segment as biologic approaches to restore CYP21A2 function advance through clinical pipelines. Hospital-based administration routes retain the highest margin capture due to acute crisis management requirements, though subcutaneous pump delivery is gaining traction in home care settings.
FDA orphan drug incentives and EMA's pediatric regulation framework shape development economics by extending market exclusivity and mandating age-appropriate formulation studies. The WHO's Essential Medicines List inclusion of hydrocortisone and fludrocortisone underpins procurement prioritization in national health systems across low- and middle-income settings. Stakeholders must monitor emerging gene therapy candidates and real-world evidence requirements for corticosteroid dose optimization algorithms that could redefine standard-of-care protocols.
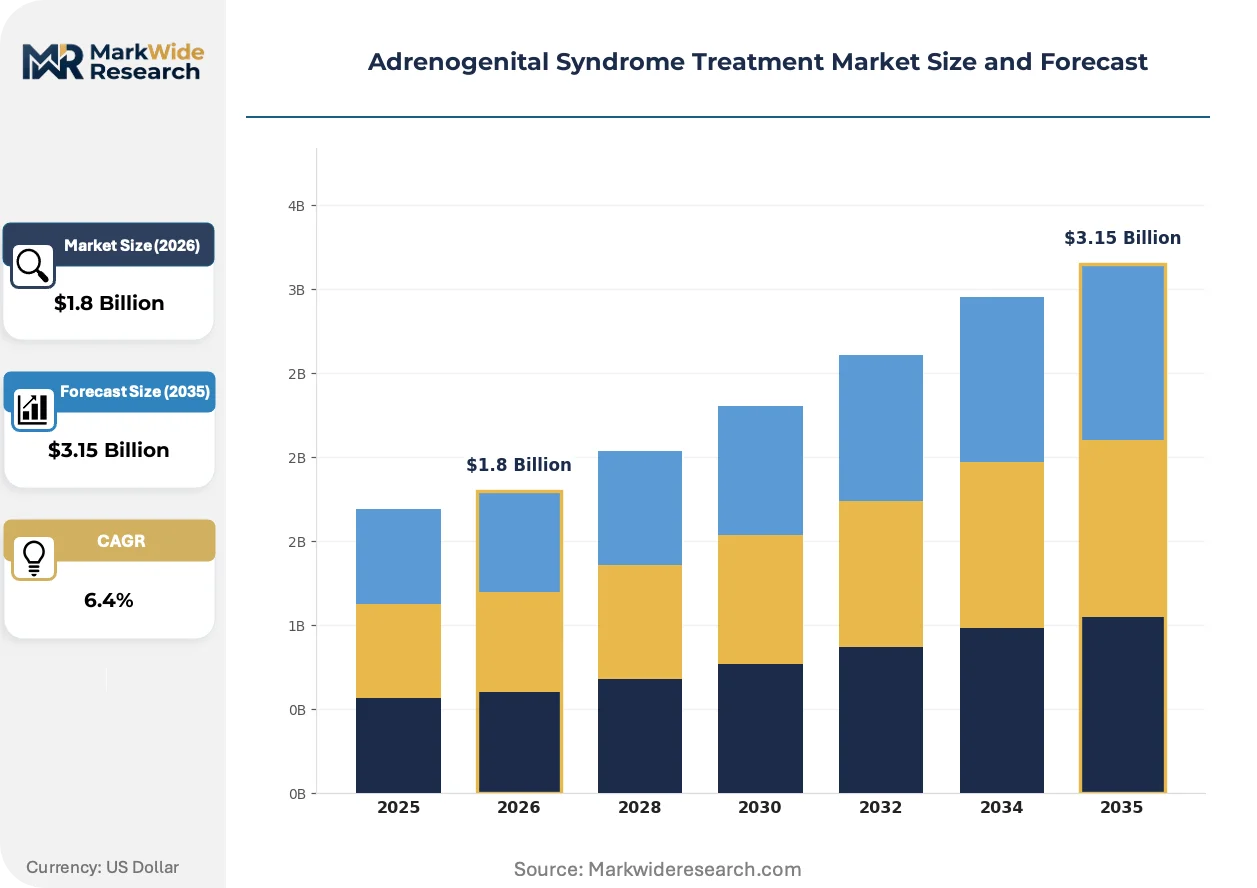
Market Dynamics
Orphan drug incentives and pediatric investigation mandates are compressing development timelines while fragmenting competitive positioning across hormone replacement and emerging biologic modalities.
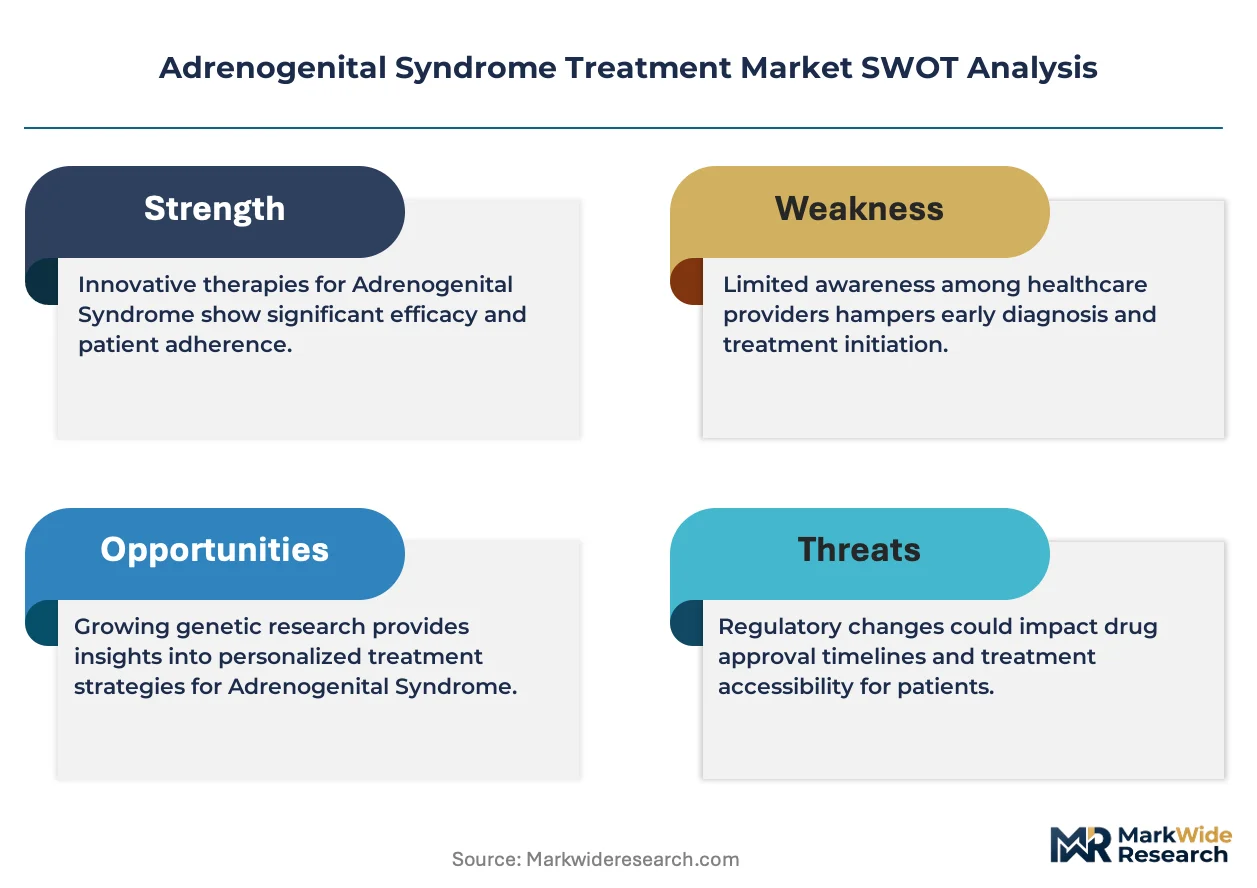
Growth Catalysts
- Newborn screening mandates:United States state-level CAH screening programs generate captive pediatric patient volumes requiring immediate pharmacological intervention. Diagnostic protocol standardization sustains treatment demand.
- EMA pediatric investigation plans:Regulatory frameworks mandate age-appropriate formulation development, accelerating novel delivery mechanism research. Sponsors gain market exclusivity extensions through compliance.
- Subcutaneous pump technology:Home-based cortisol delivery systems reduce hospital dependency. Pediatric endocrinology clinics in Germany and Japan are piloting continuous hydrocortisone infusion protocols.
Market Restraints
- API supply concentration:Hydrocortisone active pharmaceutical ingredient production concentrates among limited contract manufacturers. Multi-source procurement strategies face qualification timeline constraints.
- Fludrocortisone input volatility:Mineralocorticoid synthesis depends on fluorination chemistry with energy-intensive process requirements. European natural gas price fluctuations transmit to formulation costs.
- Gene therapy technical barriers:CYP21A2 enzyme replacement via viral vector delivery faces immunogenicity and durable expression challenges. Clinical translation remains pre-commercial.
Strategic Opportunities
- Real-world evidence algorithms:Machine learning-driven corticosteroid dose optimization creates service-layer value. Academic medical centers in the United States are building predictive models for stress-dose adjustment.
- WHO Essential Medicines procurement:Hydrocortisone and fludrocortisone inclusion enables national health system prioritization. Low- and middle-income country access programs represent volume expansion vectors.
- Home care channel development:Remote patient monitoring integration with subcutaneous delivery reduces acute crisis incidence. Reimbursement frameworks in Japan are adapting to support this transition.
Industry Challenges
- Pediatric formulation expertise scarcity:Age-appropriate hydrocortisone dosing requires specialized compounding capabilities. Clinical pharmacology talent pools are insufficient for pipeline demands.
- Regulatory evidence standard divergence:FDA orphan drug requirements and EMA pediatric investigation plans impose non-overlapping clinical trial obligations. Sponsor resource allocation faces jurisdictional complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Adrenogenital Syndrome Treatment Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Treatment Type: Hormonal Therapy, Enzyme Replacement Therapy, Surgery, Lifestyle Management Formulation: Tablet, Injection, Solution, Cream End User: Clinics, Hospitals, Home Care, Pharmacies Administration Route: Oral, Subcutaneous, Intravenous, Topical |
| Companies Covered | Neurocrine Biosciences, Diurnal Group, Pfizer Inc., Spruce Biosciences, Teva Pharmaceuticals, Novo Nordisk, AbbVie Inc., Sandoz, Sanofi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Adrenogenital Syndrome Treatment Market Strategic Shifts
Continuous monitoring and algorithmic dosing are displacing fixed-schedule replacement protocols, while regulatory frameworks accelerate pediatric formulation development and procurement models adapt to outpatient administration expansion.
Subcutaneous hydrocortisone pump systems are decentralizing acute crisis management from hospital emergency departments to home environments. Pediatric endocrinology programs in academic medical centers are adopting these devices for classical CAH patients. The technology is decentralizing margin capture toward device manufacturers and remote monitoring platforms while compressing hospital pharmacy revenue.
EMA's pediatric investigation plan mandates are reshaping clinical trial design requirements for corticosteroid sponsors. Formulation sponsors must now generate age-appropriate pharmacokinetic data across neonatal through adolescent cohorts. European development programs are responding by embedding juvenile toxicology studies earlier in candidate selection.
Consolidated procurement by integrated delivery networks is displacing fragmented hospital formulary purchasing. United States academic medical centers are negotiating multi-year hormone replacement supply agreements with outcome-linked pricing. This concentration is most visible in pediatric endocrinology networks spanning California, Massachusetts, and Texas.
Adrenogenital Syndrome Treatment Market Segmentation
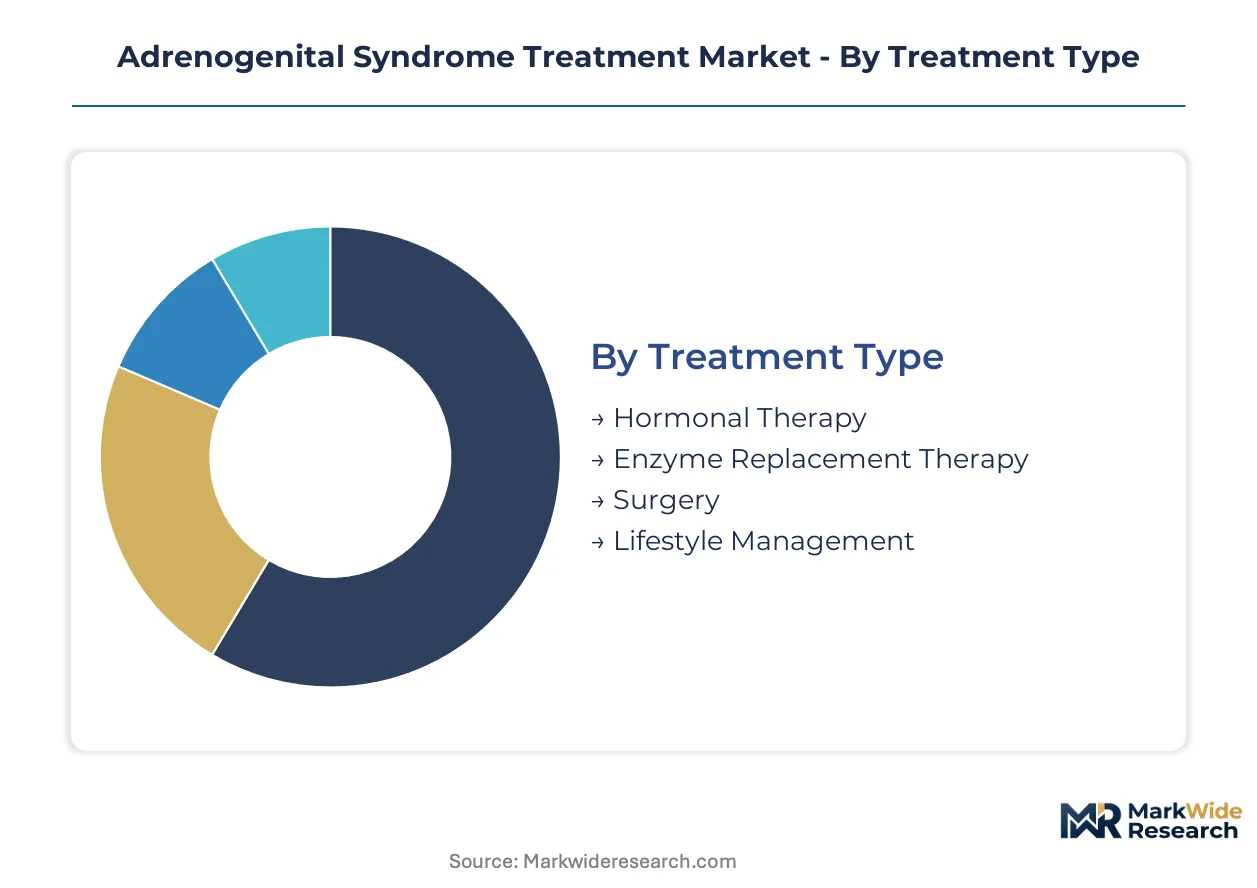
Adrenogenital syndrome treatment segmentation reveals how therapeutic modalities, delivery mechanisms, and care settings distribute value across patient lifecycles. Understanding these partitions exposes where pharmaceutical investment concentrates and which channels capture margin from chronic disease management.
Treatment Type:
Standalone hormonal replacement dominates maintenance protocols, while emerging biologics embed within precision medicine frameworks.
- Hormonal Therapy:Lifelong glucocorticoid and mineralocorticoid replacement using hydrocortisone and fludrocortisone constitutes the foundational intervention. Demand concentrates in academic pediatric endocrinology clinics across the United States, Germany, and Japan where newborn screening mandates generate immediate treatment initiation. FDA orphan drug incentives reinforce sponsor commitment to these established molecules.
- Enzyme Replacement Therapy:Experimental CYP21A2 restoration approaches via viral vector delivery target the underlying enzymatic defect rather than downstream hormone deficiency. Pre-commercial programs face immunogenicity barriers that delay clinical translation despite substantial unmet need in salt-wasting presentations.
- Surgery:Feminizing genitoplasty and corrective procedures address virilization complications in 46,XX patients with classical CAH. Specialized pediatric urology centers in Massachusetts and California maintain concentrated surgical volumes.
- Lifestyle Management:Stress-dose education, medical alert protocols, and emergency hydrocortisone availability complement pharmacological intervention. Patient advocacy organizations in the United States drive standardization of home crisis prevention resources.
Volume placements concentrate in Hormonal Therapy; the faster expansion belongs to Enzyme Replacement Therapy.
Formulation:
Cost stratification separates commodity oral generics from premium delivery innovations and specialized compounding services.
- Tablet:Immediate-release and modified-release hydrocortisone tablets dominate maintenance therapy. Pfizer Inc. and Sandoz compete on cost positioning across hospital formularies and retail pharmacy channels.
- Injection:Soluble hydrocortisone hemisuccinate formulations enable acute adrenal crisis reversal in emergency settings. Hospital pharmacy procurement concentrates this high-margin presentation in academic medical center emergency departments.
- Solution:Liquid hydrocortisone formulations address neonatal and infant dosing requirements where tablet fractionation proves impractical. EMA pediatric investigation plan mandates accelerate age-appropriate solution development.
- Cream:Topical hydrocortisone preparations manage minor dermatological manifestations of androgen excess. Dermatology clinics in Japan incorporate these into adjunctive care protocols.
Tablet formulations capture the highest prescription volumes; solution development is climbing the fastest as pediatric regulatory requirements intensify.
End User:
Patient acuity and reimbursement frameworks determine whether care localizes to institutional settings or migrates toward outpatient and home environments.
- Hospitals:Acute crisis management, newborn screening confirmation, and surgical intervention anchor institutional revenue. Integrated delivery networks in Texas and California negotiate multi-year hormone replacement supply agreements with outcome-linked pricing structures.
- Clinics:Specialized pediatric endocrinology programs manage chronic dosing titration and growth monitoring. German university hospitals are piloting continuous subcutaneous hydrocortisone infusion protocols that shift margin toward device-mediated care.
- Home Care:Subcutaneous pump delivery and remote patient monitoring reduce emergency department utilization. Japanese reimbursement frameworks are adapting to support this transition from institutional to domiciliary administration.
- Pharmacies:Retail and specialty pharmacy channels dispense maintenance prescriptions. WHO Essential Medicines List inclusion of hydrocortisone and fludrocortisone enables national health system prioritization in low- and middle-income settings.
Hospital channels retain the highest per-patient revenue; home care is gaining share fastest as pump technology matures.
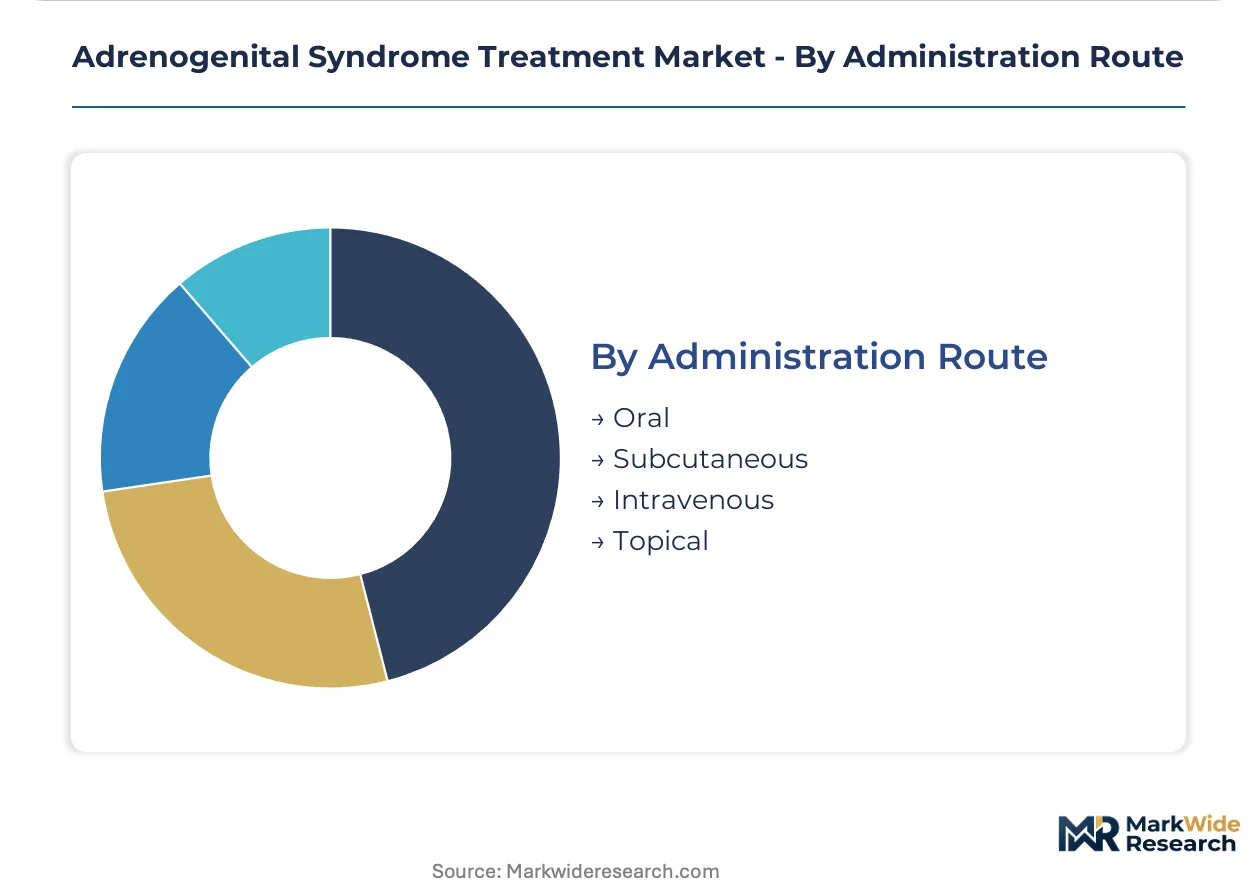
Administration Route:
Pharmacokinetic optimization drives migration from fixed-schedule oral replacement toward circadian-mimetic delivery systems.
- Oral:Conventional tablet administration three times daily remains the default maintenance protocol. Novo Nordisk anchors endocrine portfolio positioning through specialized hormone replacement competencies in this route.
- Subcutaneous:Continuous hydrocortisone infusion pumps replicate physiological circadian rhythm with programmable basal and bolus delivery. Pediatric endocrinology clinics in Germany and Japan are adopting these devices for classical CAH patients.
- Intravenous:Soluble hydrocortisone injection provides emergency crisis rescue in hospital settings. Acute care protocols mandate immediate intravenous access for adrenal crisis presentations.
- Topical:Transdermal absorption plays minimal role in systemic cortisol replacement but addresses localized androgenic skin manifestations. Dermatology practices incorporate topical therapy as adjunctive intervention.
Oral administration maintains the dominant prescription volume; subcutaneous delivery is expanding most quickly as home-based technology diffuses.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States academic medical centers generate the highest treatment volumes through newborn screening mandates and specialized pediatric endocrinology concentration. Regulatory frameworks across developed markets are accelerating formulation development while procurement models shift toward integrated network agreements.
United States
State-level congenital adrenal hyperplasia screening programs and academic medical center density sustain captive pediatric patient flows. FDA orphan drug designation extends market exclusivity for sponsors developing age-appropriate hydrocortisone formulations. Pediatric endocrinology networks across California, Massachusetts, and Texas negotiate multi-year supply agreements with outcome-linked pricing structures.
Germany
University hospital pediatric endocrinology programs pilot continuous subcutaneous hydrocortisone infusion protocols for classical CAH patients. EMA pediatric investigation plans mandate juvenile toxicology studies earlier in candidate selection timelines. Bavarian and North Rhine-Westphalian medical centers anchor specialized hormone replacement service delivery.
Japan
Metropolitan pediatric specialty clinics drive adoption of home-based cortisol delivery systems with remote patient monitoring integration. METI reimbursement frameworks adapt to support transition from institutional to domiciliary administration routes. Kanto region academic hospitals concentrate device-mediated care pilot programs.
United Kingdom
National Health Service procurement prioritization through WHO Essential Medicines List inclusion enables hydrocortisone and fludrocortisone access program expansion. MHRA pediatric formulation requirements align with EMA investigation plan standards. London and Southeast England pediatric endocrinology centers maintain specialized CAH program concentration.
India
National health system essential medicines procurement creates volume expansion opportunities for generic hormone replacement manufacturers. CDSCO pediatric investigation guidelines are evolving toward age-appropriate formulation mandates. Maharashtra and Karnataka hospital networks develop specialized endocrinology service lines for congenital adrenal hyperplasia management.
Adrenogenital Syndrome Treatment Market Competitive Environment
Portfolio diversification dominates the current landscape as established pharmaceutical manufacturers extend corticosteroid competencies into rare disease verticals. The vendor base clusters around three strategic archetypes: large-cap diversified pharmaceutics with orphan drug infrastructure, mid-cap endocrine specialists with hormone replacement focus, and generic manufacturers competing on oral formulation cost positioning. Capacity expansion in multi-source API procurement and strategic partnerships for subcutaneous delivery technology represent the dominant competitive moves reshaping supply security.
Within the diversified pharmaceutical tier, Pfizer Inc. and Novo Nordisk exemplify contrasting approaches to endocrine portfolio construction. Pfizer leverages established corticosteroid manufacturing infrastructure to sustain cost-competitive tablet production across hospital formularies. Novo Nordisk anchors specialized hormone replacement competencies through concentrated endocrine expertise. Sandoz occupies a distinct position as a generic-focused manufacturer competing aggressively on oral formulation accessibility across European and North American procurement channels.
| Leading Market Players |
|---|
| Neurocrine Biosciences |
| Diurnal Group |
| Pfizer Inc. |
| Spruce Biosciences |
| Teva Pharmaceuticals |
| Novo Nordisk |
| AbbVie Inc. |
| Sandoz |
| Sanofi |
| Others |
Value Chain & Pricing Dynamics
Pediatric formulation pharmacologists concentrate in Massachusetts and North Rhine-Westphalia, and their specialized labor-cost differentials widen pricing spreads between premium continuous-infusion systems and commodity oral generics.
Pricing Analysis
Warranty and remote monitoring service bundling separates premium subcutaneous pump offerings from unbundled tablet procurement. Three-tier pricing structure across premium device-integrated, standard modified-release oral, and economy immediate-release generic levels dominates the market. Price differentiation hinges on FDA pediatric exclusivity status and German university hospital outcome-linked contract scale. Pricing pressure stems from European natural gas volatility transmitting to fludrocortisone fluorination costs. Hospital procurement committees show lowest price sensitivity; retail pharmacy channels in low- and middle-income settings exhibit highest elasticity.
Supply Chain Analysis
Single-source vulnerability sits with Chinese contract manufacturers for hydrocortisone API intermediates. Active pharmaceutical ingredient production concentrates in India, China, and Italy, while finished formulation manufacturing clusters in Germany, the United States, and Japan. Raw material dependencies include cortisol precursor steroids, fluorinated mineralocorticoid synthons, and specialized pump device electronics. Tariff exposure on Chinese-sourced intermediates represents the dominant structural risk. Distribution runs through integrated delivery network central pharmacies in the United States and hospital consortium procurement in Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around sponsors with EMA pediatric investigation plan execution capabilities, as regulatory compliance costs force smaller generic manufacturers toward exit.
For Market Incumbents: Acquire subcutaneous pump technology platforms to anchor device-mediated care positioning. Novo Nordisk and Pfizer Inc. should deepen backward integration into corticosteroid API production to secure supply against Indian and Chinese contract manufacturer concentration. Sandoz must defend European hospital formulary share through accelerated EMA solution formulation submissions before exclusivity windows close. For New Entrants and Emerging Players: Capture WHO Essential Medicines procurement contracts in Maharashtra and Karnataka state health systems, where national essential medicines prioritization creates volume expansion vectors. Home care remote monitoring integration in Japan's Kanto region offers the most penetrable geographic entry point. Partner with German university hospitals on continuous infusion protocol validation to establish clinical credibility before FDA orphan drug pathway entry. For Investors and Strategic Acquirers: Re-rating potential sits with mid-cap endocrine specialists given EMA pediatric investigation plan compliance acceleration. Five-to-ten-year viability favors sponsors with enrolled neonatal pharmacokinetic studies and established academic medical center relationships. Monitor FDA orphan drug designation grants to Diurnal Group and Spruce Biosciences as inflection indicators for gene therapy and novel delivery mechanism validation.| Strategic Initiative | Industry Significance |
|---|---|
| EMA Pediatric Investigation Plan Execution | Accelerates age-appropriate formulation timelines and extends market exclusivity for compliant sponsors. |
| Subcutaneous Pump Technology Licensing | Shifts margin capture toward device manufacturers and enables home-based crisis prevention protocols. |
| Backward Integration into API Production | Reduces dependency on Chinese and Indian contract manufacturers for hydrocortisone intermediates. |
| WHO Essential Medicines Procurement Partnership | Unlocks national health system volume in Maharashtra and Karnataka through essential medicines prioritization. |
| Continuous Infusion Protocol Validation | Generates real-world evidence for German and Japanese reimbursement framework adaptation. |
Study Parameters
Independent corroboration across pediatric endocrinology program directors, hospital pharmacy procurement managers, regulatory affairs leads at EMA-compliant sponsors, and WHO essential medicines specialists underwrites the qualitative findings. Primary interviews with formulary directors at academic medical centers in California, Massachusetts, and Texas combined with secondary validation from FDA orphan drug designation databases, EMA pediatric investigation plan registries, ClinicalTrials.gov CAH intervention listings, and German university hospital procurement disclosures. Bottom-up prescription volume modeling and top-down revenue triangulation anchored the market sizing.
Comparable-period anchoring to historical newborn screening mandate expansion phases and EMA pediatric regulation implementation waves structured the forecast window. Segmentation modeling spanned treatment modality, formulation type, administration route, patient lifecycle stage, and regional regulatory cluster. CAGRs derived from prescription volume trajectories, pricing evolution patterns, and technology adoption S-curves. Forecast inputs incorporated EMA investigation plan completion rates, subcutaneous pump reimbursement approval velocity, and WHO essential medicines procurement scale-up assumptions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to gene therapy clinical translation delays, API supply disruption events, and pediatric formulation regulatory standard divergence between FDA and EMA jurisdictions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Cystinuria Treatment Market
Specialty Medicine
Rosacea Therapeutics Market
Specialty Medicine
Avascular Necrosis Market
Specialty Medicine
Global Post Traumatic Stress Disorder (PTSD) Therapeutics Market
Specialty Medicine
Global Lung Transplant Therapeutics Market
Specialty Medicine
Polycystic Kidney Disease Treatment Market
Specialty Medicine
Global Appendiceal Cancer Treatment Market
Specialty Medicine
Neuromyelitis Optica Market
Specialty Medicine
Uterine Cancer Therapeutics and Diagnostics Market
Specialty Medicine
Growth Hormone Deficiency Market
Specialty Medicine
Global Fuchs Endothelial Corneal Dystrophy (FECD) Market
Specialty Medicine
Global Phenylketonuria Treatment Market
Specialty Medicine
Global Myopia and Presbyopia Treatment Market
Specialty Medicine
Sporothrix Schenckii Infection Treatment Market
Specialty Medicine
Narcolepsy Market
Specialty Medicine
Anaplastic Large Cell Lymphoma (ALCL) Therapeutics Market