
 Transient Ischemic Attack Market | 2026-2036
Transient Ischemic Attack Market Size, Share, and Industry Trends Forecast 2026-2036
Transient Ischemic Attack Market Outlook
Digital biomarker integration with portable EEG and wearable cerebrovascular monitors is tilting diagnostic workflows toward real-time, pre-hospital detection. Pfizer Inc. leverages its anticoagulant manufacturing scale to anchor supply security for emergency departments. Sanofi competes through specialized neurology-focused commercial teams that dominate hospital formulary access.
A transient ischemic attack constitutes a brief neurological dysfunction caused by focal brain, spinal cord, or retinal ischemia without acute infarction, typically resolving within 24 hours and serving as a critical warning signal for imminent stroke risk. Antiplatelet agents occupy the core of secondary prevention protocols, while diagnostic imaging represents the fastest-expanding product category as hospitals prioritize rapid vessel imaging and perfusion assessment. Emergency departments sustain the highest patient throughput, with outpatient clinics extending follow-on rehabilitation and long-term medication management.
The FDA governs antithrombotic efficacy standards and diagnostic device clearances, while HIPAA mandates strict neuroimaging data handling across integrated stroke networks. The Centers for Medicare & Medicaid Services shapes reimbursement intensity for TIA-specific emergency protocols, directly influencing hospital capital allocation toward dedicated stroke units. Stakeholders must monitor how evolving FDA guidance on artificial intelligence-enabled stroke detection will reshape competitive requirements for imaging platform vendors and alter clinical adoption thresholds.
Market Dynamics
The FDA's updated stroke biomarker guidance is compressing diagnostic imaging validation timelines while hospital emergency departments accelerate TIA protocol standardization, creating dual pressure on device manufacturers to demonstrate clinical utility faster.
Growth Catalysts
- Integrated stroke center networks:Hospital systems in the United States are consolidating emergency neurology capabilities into certified hubs, driving standardized anticoagulant and antiplatelet utilization protocols across affiliated facilities.
- Portable EEG and wearable cerebrovascular monitors:Digital biomarker integration is enabling real-time, pre-hospital detection workflows that extend diagnostic windows before patient arrival at emergency departments.
- HIPAA-mandated neuroimaging data infrastructure:Strict handling requirements across integrated stroke networks are catalyzing capital investment in secure, interoperable imaging platforms that support rapid vessel assessment.
Market Restraints
- Diagnostic imaging capital intensity:Perfusion assessment equipment and rapid vessel imaging systems require substantial upfront hospital expenditure, limiting adoption to well-capitalized stroke centers.
- Antithrombotic efficacy validation costs:FDA standards for demonstrating clinical benefit in secondary prevention protocols impose lengthy, expensive trial requirements on therapeutic developers.
- Specialized neurology workforce scarcity:The limited pool of stroke-certified physicians constrains expansion of dedicated TIA units beyond major metropolitan hospital clusters.
Strategic Opportunities
- Outpatient clinic medication management:Long-term anticoagulant adherence programs represent an underdeveloped channel for extending patient touchpoints beyond initial emergency department discharge.
- Centers for Medicare & Medicaid Services reimbursement incentives:TIA-specific emergency protocol payments are reshaping hospital capital allocation priorities toward dedicated stroke unit construction.
- Artificial intelligence-enabled stroke detection convergence:Machine learning algorithms paired with portable monitoring hardware are creating new regulatory pathways for pre-hospital diagnostic authorization.
Industry Challenges
- Neuroimaging data interoperability:Legacy picture archiving and communication systems require expensive retrofitting to achieve real-time integration with wearable cerebrovascular monitors and emergency department workflows.
- Stroke biomarker validation timelines:The gap between algorithm development and FDA clearance for AI-assisted diagnostic tools creates competitive uncertainty for imaging platform vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Transient Ischemic Attack Market |
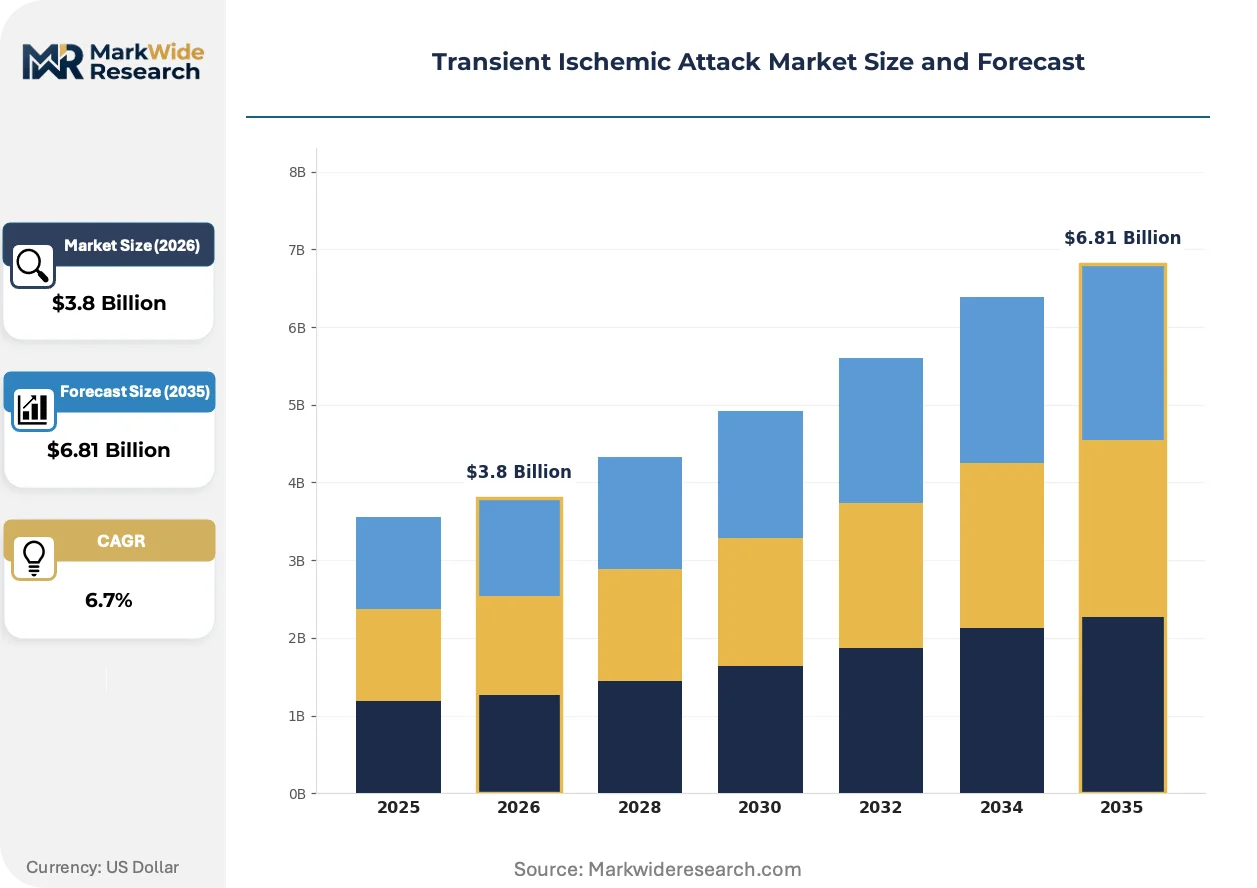
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Therapy Area: Neurology, Stroke Management, Rehabilitation, Cardiovascular Care Product Type: Antiplatelet Agents, Anticoagulants, Thrombolytics, Diagnostic Imaging End User: Hospitals, Outpatient Clinics, Emergency Departments, Nursing Homes Delivery Mode: Intravenous, Oral, Intra-arterial, Subcutaneous |
| Companies Covered | Bristol-Myers Squibb Company, Sanofi, Pfizer Inc., Johnson & Johnson Services, Inc., Novartis AG, Bayer AG, AstraZeneca, Eli Lilly and Company, Boehringer Ingelheim International GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Transient Ischemic Attack Market Strategic Shifts
Diagnostic workflows are virtualizing across the care continuum, with hardware decentralization and algorithmic interpretation redistributing clinical decision-making from centralized hospitals toward ambulatory and pre-hospital settings.
Portable EEG systems with embedded machine learning classifiers are virtualizing traditional in-hospital neurological assessment by enabling seizure and ischemia detection during ambulance transport. Emergency medical services in the United States are piloting these devices at accelerating rates. This virtualization is compressing the diagnostic window and forcing hospital-based neurology departments to reconfigure triage protocols around incoming pre-validated data streams.
The FDA's artificial intelligence-enabled stroke detection guidance is establishing performance benchmarks for algorithmic sensitivity and specificity in vessel occlusion identification. Device manufacturers must now submit prospective clinical validation data rather than retrospective algorithm training sets. Diagnostic imaging vendors serving the United States market are restructuring regulatory affairs teams and expanding clinical trial operations to meet these evidentiary demands.
Hospital procurement of TIA diagnostic equipment is consolidating through integrated delivery network contracts rather than individual facility purchasing. Stroke center certification requirements are concentrating buying authority within network-level value analysis committees. This behavioral shift is most visible in the United States, where multi-hospital systems are leveraging scale to negotiate exclusive platform agreements that lock out competing imaging vendors.
Transient Ischemic Attack Market Segmentation
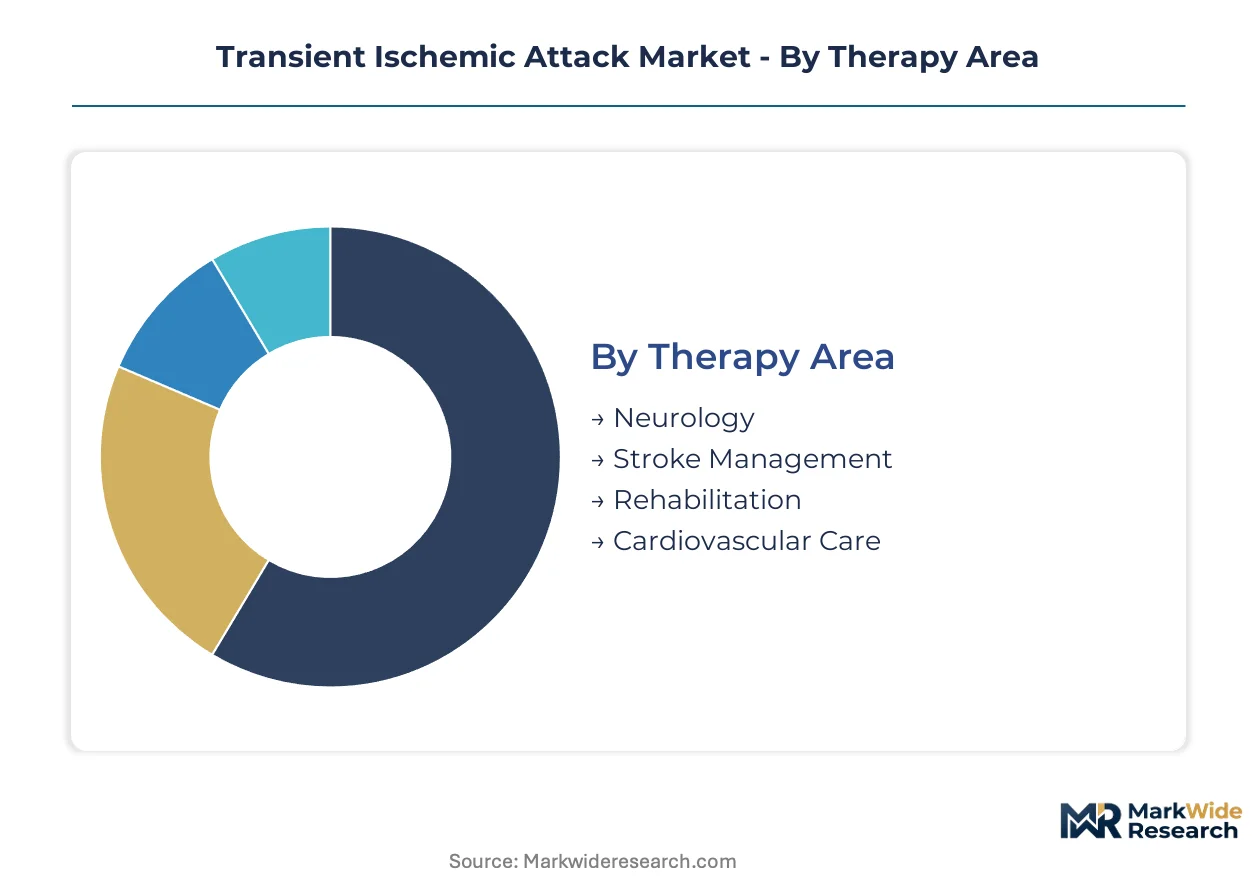
Segmentation in the Transient Ischemic Attack Market reveals how clinical workflows, reimbursement structures, and patient acuity distribute value across distinct product and service categories. Understanding these divisions enables stakeholders to align R&D investment, commercial deployment, and partnership strategies with where capital flows and where clinical outcomes are measured.
Therapy Area:
Clinical specialization determines reimbursement intensity and regulatory pathway complexity across neurology-focused care settings.
- Neurology:Centers on acute cerebral ischemia evaluation and neuroprotective intervention protocols. Demand concentrates in United States academic medical centers where fellowship-trained vascular neurologists direct comprehensive stroke programs.
- Stroke Management:Encompasses rapid triage systems, protocol standardization, and time-critical therapeutic decision-making. Emergency departments in integrated stroke center networks drive utilization of coordinated response frameworks.
- Rehabilitation:Post-acute functional recovery services including speech, physical, and occupational therapy. Outpatient clinics in Germany and Japan extend patient touchpoints through structured secondary prevention programs.
- Cardiovascular Care:Addresses shared risk factor modification and comorbidity management. Cardiology departments in United States hospital systems increasingly co-manage TIA patients with atrial fibrillation profiles.
Neurology holds installed capacity. Stroke Management is rotating up the share rankings.
Product Type:
Therapeutic and diagnostic modalities compete for capital allocation based on FDA clearance timelines and hospital procurement cycles.
- Antiplatelet Agents:Aspirin and clopidogrel combinations form the pharmacological backbone of secondary prevention. United States emergency departments standardize dual-antiplatelet protocols within 24-hour diagnostic windows.
- Anticoagulants:Direct oral anticoagulants displace warfarin in atrial fibrillation-associated TIA cases. Formulary committees in United Kingdom NHS trusts prioritize agents with reversible mechanisms and fewer dietary interactions.
- Thrombolytics:Tissue plasminogen activator and tenecteplase for acute ischemic stroke extension. Administration remains restricted to certified stroke centers with neurosurgical backup.
- Diagnostic Imaging:MRI perfusion, CT angiography, and carotid ultrasound systems enable vessel assessment. United States hospitals prioritize platforms with AI-embedded occlusion detection to compress door-to-needle intervals.
Antiplatelet Agents anchor current revenue. Diagnostic Imaging is climbing the fastest.
End User:
Care setting determines patient volume, acuity mix, and the intensity of therapeutic intervention authorized.
- Hospitals:Inpatient units manage complex TIA cases requiring multidisciplinary coordination. Stroke center certification in United States drives capital investment in dedicated neurovascular beds.
- Outpatient Clinics:Long-term antithrombotic monitoring and risk factor modification. Clinics in France and Australia extend patient management through nurse-led adherence programs.
- Emergency Departments:Highest-acuity presentation point with time-critical diagnostic and therapeutic decisions. United States EDs pilot portable EEG integration to validate pre-hospital stroke alerts.
- Nursing Homes:Post-acute transitional care and medication reconciliation for elderly populations. Facilities in Japan face workforce constraints limiting specialized neurological assessment capacity.
Emergency Departments command throughput volume. Outpatient Clinics are gaining share fastest.
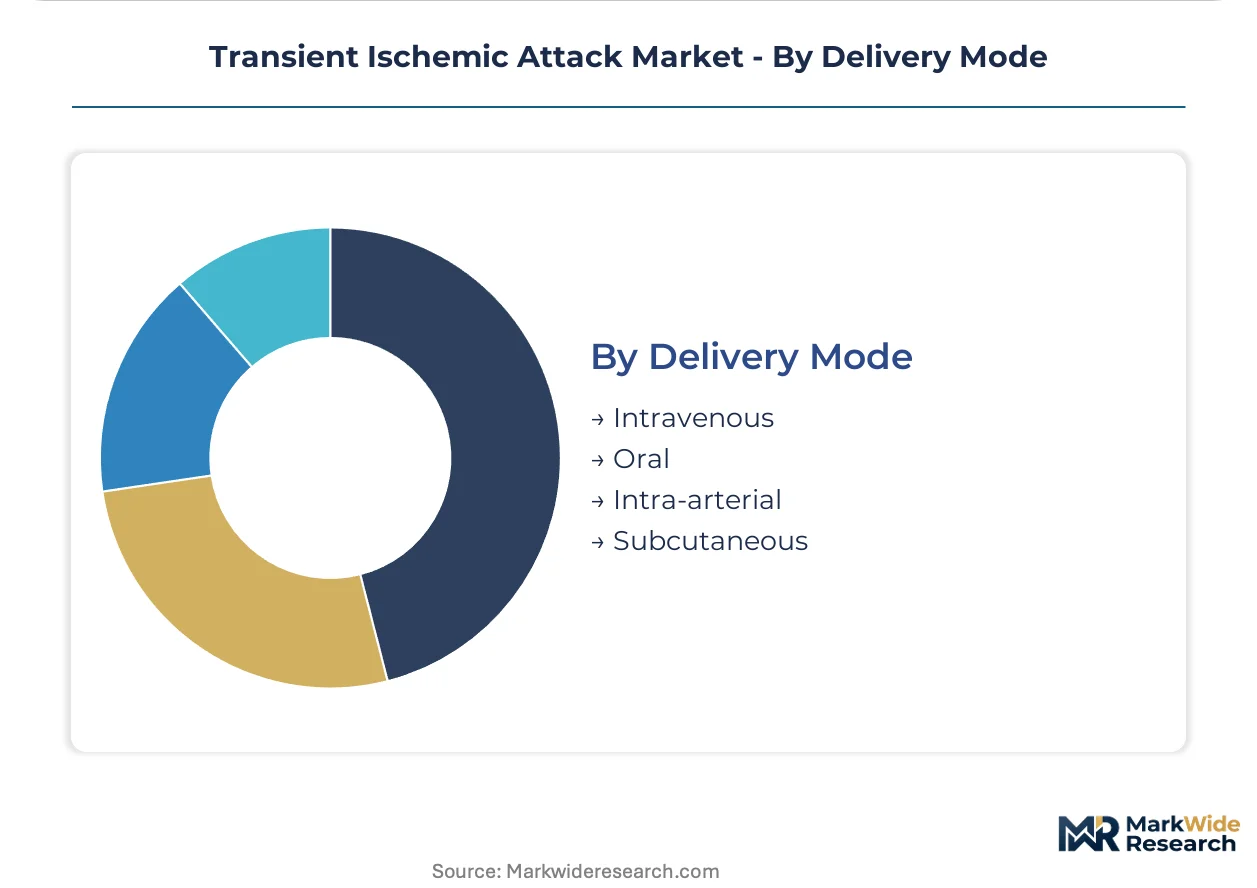
Delivery Mode:
Route of administration shapes pharmacokinetic profiles, monitoring requirements, and the care settings where therapy can be initiated.
- Intravenous:Enables rapid anticoagulant and thrombolytic effect for acute intervention. United States emergency departments standardize IV heparin bridges before oral agent transition.
- Oral:Direct oral anticoagulants and antiplatelet agents for maintenance therapy. Patient preference in United Kingdom primary care drives adherence advantage over parenteral alternatives.
- Intra-arterial:Catheter-directed thrombolysis and mechanical thrombectomy for proximal vessel occlusion. Availability restricts to comprehensive stroke centers with interventional neuroradiology coverage.
- Subcutaneous:Low-molecular-weight heparin for bridging or prophylaxis in transition periods. Nursing homes in Germany utilize subcutaneous administration where IV access is impractical.
Oral formulations hold installed capacity. Intravenous delivery is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German diagnostic imaging manufacturers export MRI perfusion systems to United States stroke centers, while Japanese pharmaceutical producers supply antiplatelet agents to European hospital networks.
United States
Integrated stroke center networks in Texas and Florida drive anticoagulant utilization through standardized emergency protocols. CMS reimbursement incentives for TIA-specific emergency care reshape hospital capital allocation toward dedicated neurovascular units. The Mayo Clinic in Rochester anchors clinical validation trials for AI-enabled occlusion detection platforms.
Germany
Outpatient clinics in Bavaria and North Rhine-Westphalia extend patient management through nurse-led antithrombotic adherence programs. The country's national pharmaceutical regulator enforces strict post-market surveillance for direct oral anticoagulants. Siemens Healthineers in Erlangen concentrates manufacturing of CT angiography systems serving European hospital networks.
Japan
Aging demographics in Tokyo and Osaka prefectures concentrate TIA incidence among elderly populations requiring specialized neurological assessment. METI funding accelerates domestic production of portable EEG systems with embedded machine learning classifiers. The University of Tokyo Hospital pilots real-time pre-hospital stroke alert integration with emergency medical services.
United Kingdom
NHS trusts in Greater London and Manchester prioritize direct oral anticoagulants with reversible mechanisms for atrial fibrillation-associated TIA cases. NICE technology appraisals determine formulary access for secondary prevention agents across regional hospital networks. The National Hospital for Neurology and Neurosurgery leads protocol standardization for rapid vessel imaging workflows.
China
Provincial hospital systems in Shanghai and Beijing expand certified stroke center capacity to address rising cerebrovascular disease burden. NMPA accelerated review pathways compress diagnostic device clearance timelines for domestic imaging platform vendors. Fudan University Huashan Hospital anchors multi-center clinical trials for AI-assisted perfusion assessment algorithms.
Transient Ischemic Attack Market Competitive Environment
Channel-controlling players compete with product-specialist players across the antithrombotic and diagnostic imaging segments. Hospital formulary committees and integrated delivery network contracts determine market access, consolidating purchasing authority within multi-hospital systems. Three archetypes dominate: diversified pharmaceutical conglomerates with anticoagulant manufacturing scale, specialized neurology-focused commercial organizations, and diagnostic imaging platform vendors with AI-embedded hardware. Competitive moves center on exclusive platform agreements with stroke center networks and regulatory affairs expansion to meet FDA validation requirements.
Among diversified pharmaceutical conglomerates, Bristol-Myers Squibb Company and Pfizer Inc. occupy positions defined by antiplatelet and anticoagulant manufacturing infrastructure. Sanofi sits within the specialized neurology-focused tier, with commercial teams concentrated on hospital formulary access. Bayer AG represents the diagnostic imaging intersection, bridging pharmaceutical and device capabilities across stroke care workflows.
| Leading Market Players |
|---|
| Bristol-Myers Squibb Company |
| Sanofi |
| Pfizer Inc. |
| Johnson & Johnson Services, Inc. |
| Novartis AG |
| Bayer AG |
| AstraZeneca |
| Eli Lilly and Company |
| Boehringer Ingelheim International GmbH |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in United States stroke center networks for AI-embedded diagnostic imaging platforms is compressing supplier lead times and amplifying pricing power for device manufacturers serving certified emergency departments.
Pricing Analysis
Cost-plus contracts with raw material indexation dominate anticoagulant procurement between United States hospital systems and pharmaceutical suppliers. Three-tier pricing structure across premium, standard, and economy levels separates novel direct oral anticoagulants from established dual-antiplatelet protocols and generic aspirin-clopidogrel combinations. Price differentiation centers on FDA approval tier and stroke center certification requirements, with integrated delivery networks leveraging volume scale for rebates. Pricing pressure stems from CMS reimbursement compression on TIA-specific emergency protocols, squeezing margins on mid-tier diagnostic imaging platforms while premium AI-enabled occlusion detection systems maintain pricing resilience.
Supply Chain Analysis
Upstream active pharmaceutical ingredient production for antiplatelet agents concentrates in India and China, with final formulation and packaging anchored in United States and European Union facilities. The supply chain draws from heparin sodium derived from porcine intestinal mucosa, synthetic direct thrombin inhibitors, and contrast media for perfusion imaging. Single-source vulnerability in heparin feedstock creates exposure to agricultural disease outbreaks and export licensing shifts. Distribution runs through integrated delivery network central warehouses directly to hospital pharmacy and materials management departments, bypassing traditional wholesale intermediaries for anticoagulant and antiplatelet agents.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Transient Ischemic Attack Market sits in early-cycle expansion as pre-hospital digital biomarker adoption accelerates diagnostic window compression and creates new reimbursement pathways for portable monitoring technologies.
For Market Incumbents: Harden formulary lock-in through exclusive platform agreements with expanding integrated stroke center networks in Texas and Florida. Deepen backward integration into AI algorithm development to defend against emerging diagnostic imaging entrants with FDA clearance advantages. Prioritize clinical trial investment in reversible anticoagulant mechanisms to preempt regulatory preference shifts in United Kingdom NHS trusts.
For New Entrants and Emerging Players: Pursue outpatient clinic medication management programs in Germany and Japan as the most penetrable channel for long-term antithrombotic adherence solutions. Target nurse-led secondary prevention workflows where hospital formulary committees exert weaker control. Deploy direct-to-clinic commercial models with telemedicine integration to circumvent emergency department procurement consolidation.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among diagnostic imaging platform vendors with AI-embedded hardware and software subscription bundling. Stroke center certification mandates create durable installed bases with switching costs extending across the projection horizon. Monitor FDA artificial intelligence-enabled stroke detection guidance finalization as the inflection signal for imaging vendor consolidation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| AI-Enabled Diagnostic Platform Development | FDA validation requirements for algorithmic sensitivity benchmarks reshape competitive entry barriers for imaging vendors. |
| Integrated Stroke Center Network Partnership | Exclusive platform agreements with multi-hospital systems in United States consolidate purchasing authority and lock out competing suppliers. |
| Pre-Hospital Monitoring Hardware Launch | Portable EEG systems with embedded machine learning classifiers extend diagnostic windows before emergency department arrival. |
| Reimbursement Strategy Alignment | CMS TIA-specific emergency protocol incentives direct hospital capital allocation toward dedicated neurovascular unit construction. |
| Regulatory Affairs Expansion | Prospective clinical validation data requirements for AI-assisted diagnostic tools demand expanded trial operations in United States. |
Study Parameters
Two parallel data streams informed the analysis: primary field engagement with stroke care stakeholders and secondary validation across regulatory and commercial databases. Interview sources included vascular neurologists directing comprehensive stroke programs, hospital formulary committee chairs, emergency department medical directors, biomedical engineers evaluating imaging platforms, and GPO contracts managers at integrated delivery networks. Secondary sources encompassed FDA 510(k) and PMA filings, CMS Medicare reimbursement databases, ClinicalTrials.gov stroke intervention protocols, and hospital procurement records from United States academic medical centers. Bottom-up patient volume modeling and top-down pharmaceutical expenditure estimates were triangulated against stroke center certification rosters.
Forecast inputs incorporated therapy area specialization, product type modality, end user care setting, and delivery mode route across the projection horizon. Segmentation dimensions modeled included neurology versus stroke management versus rehabilitation service lines, antiplatelet versus anticoagulant versus diagnostic imaging product categories, and hospital versus outpatient clinic versus emergency department utilization patterns. CAGRs were derived from patient incidence projections, protocol penetration curves, and reimbursement intensity indices. Industry-specific inputs included FDA artificial intelligence guidance implementation timelines and integrated stroke center network expansion trajectories.
Macroeconomic conditions sit as an overlay; deviation in Medicare reimbursement rates, hospital capital expenditure cycles, or pharmaceutical input costs would shift the trajectory. Forecasts reflect assumptions regarding regulatory clearance timelines, clinical adoption thresholds, and competitive dynamics. Cross-checking against CMS Hospital Outpatient Prospective Payment System data and FDA diagnostic device approval databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Microcephaly Market
Specialty Medicine
Carcinoid Syndrome Diarrhea Treatment Market
Specialty Medicine
Radioimmunotherapy (RIT) Market
Specialty Medicine
Amino Acid Metabolism Disorders Treatment Market
Specialty Medicine
Dry Eye Disease Market
Specialty Medicine
Chronic Urticaria Market
Specialty Medicine
Cerebral Folate Deficiency Market
Specialty Medicine
Nonalcoholic Steatohepatitis Market
Specialty Medicine
Premenstrual Dysphoric Disorder Market
Specialty Medicine
Global Psoriatic Arthritis Therapeutics Market
Specialty Medicine
Intestine (Small) Cancer Therapeutics Market
Specialty Medicine
Intussusception Market
Specialty Medicine
Wet Age-Related Macular Degeneration (Wet AMD) Market
Specialty Medicine
Global Herpes Market
Specialty Medicine
Latin America Bladder Cancer Therapeutics and Diagnostics Market
Specialty Medicine
Dermatomyositis Treatment Market