
 Post-Traumatic Stress Disorder (PTSD) Market | 2026-2036
Post-Traumatic Stress Disorder (PTSD) Market Size, Share, and Industry Trends Forecast 2026-2036
Post-Traumatic Stress Disorder (PTSD) Market Insights
Platform licensing for digital therapeutic modules is reshaping how PTSD care reaches remote patient populations. Pfizer Inc. leverages its psychiatric drug portfolio to sustain formulary positions across outpatient clinics. Jazz Pharmaceuticals anchors its competitive stance through specialty therapeutics for trauma-related sleep disturbances. Bionomics Limited differentiates via novel GABA-targeting compounds in clinical development for anxiety-spectrum disorders.
Post-traumatic stress disorder constitutes a psychiatric condition triggered by exposure to actual or threatened death, serious injury, or sexual violence, characterized by intrusion symptoms, avoidance behaviors, negative alterations in cognition and mood, and marked alterations in arousal and reactivity persisting beyond one month. Its primary commercial purpose centers on restoring functional capacity in occupational, social, and interpersonal domains through evidence-based interventions. Pharmacotherapy commands the largest revenue share among treatment types due to chronic maintenance requirements and established reimbursement pathways. Teletherapy represents the fastest-expanding delivery mode as asynchronous digital platforms reduce geographic and stigma-related access barriers. Veterans segment carries concentrated payer investment given dedicated federal funding streams and service-connected disability frameworks.
FDA regulates all novel PTSD drug candidates through psychiatric drug development guidelines, while HIPAA mandates data protection standards for digital mental health platforms transmitting protected health information. The DEA additionally controls Schedule I substance research permissions for emerging psychedelic-assisted therapies including MDMA and psilocybin protocols. Stakeholders must monitor regulatory determinations on breakthrough therapy designations and digital health software pre-certification pathways to anticipate reimbursement and market access trajectories.
Market Dynamics
Psychedelic-assisted therapy protocols are forcing a structural recalibration of PTSD treatment hierarchies, compressing decades of psychiatric drug development timelines while elevating novel mechanism candidates alongside established SSRI maintenance regimens.
Growth Catalysts
- FDA Breakthrough Therapy Designation:Accelerated review pathways for MDMA-assisted psychotherapy compress development timelines and signal reimbursement viability to institutional payers.
- Veterans Health Administration Screening Mandates:Systematic PTSD detection protocols across VA medical centers generate concentrated demand for scalable intervention modalities.
- Digital Phenotyping Platforms:Smartphone-based biometric monitoring enables remote symptom tracking, expanding addressable populations beyond traditional clinic catchment areas.
Market Restraints
- DEA Schedule I Research Controls:Strict substance scheduling creates investigator licensing bottlenecks and multi-site protocol approval delays for psychedelic trials.
- Specialized Psychotherapy Workforce Scarcity:Limited availability of trauma-focused cognitive behavioral therapy practitioners constrains scalable delivery of evidence-based psychosocial interventions.
- Reimbursement Pathway Uncertainty:Commercial payers maintain prior authorization requirements for novel pharmacotherapies, creating access friction for non-veteran patient segments.
Strategic Opportunities
- Asynchronous Teletherapy Platforms:Text-based and video-asynchronous modalities reduce stigma barriers and clinician time constraints in rural and underserved counties.
- Companion Diagnostic Integration:Pharmacogenomic profiling for antidepressant metabolism variants enables personalized dosing protocols and reduces trial-and-error prescribing cycles.
- Employer-Sponsored Mental Health Benefits:Large self-insured employers are expanding PTSD coverage within employee assistance programs, creating direct-to-payer contracting channels.
Industry Challenges
- Digital Therapeutic FDA 510(k) Navigation:Software-as-medical-device submissions require clinical validation studies that extend time-to-market for mental health applications.
- Psychedelic Therapy Training Infrastructure:Therapist certification for MDMA and psilocybin protocols demands specialized programs that currently outpace accredited program availability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Post-Traumatic Stress Disorder (PTSD) Market |
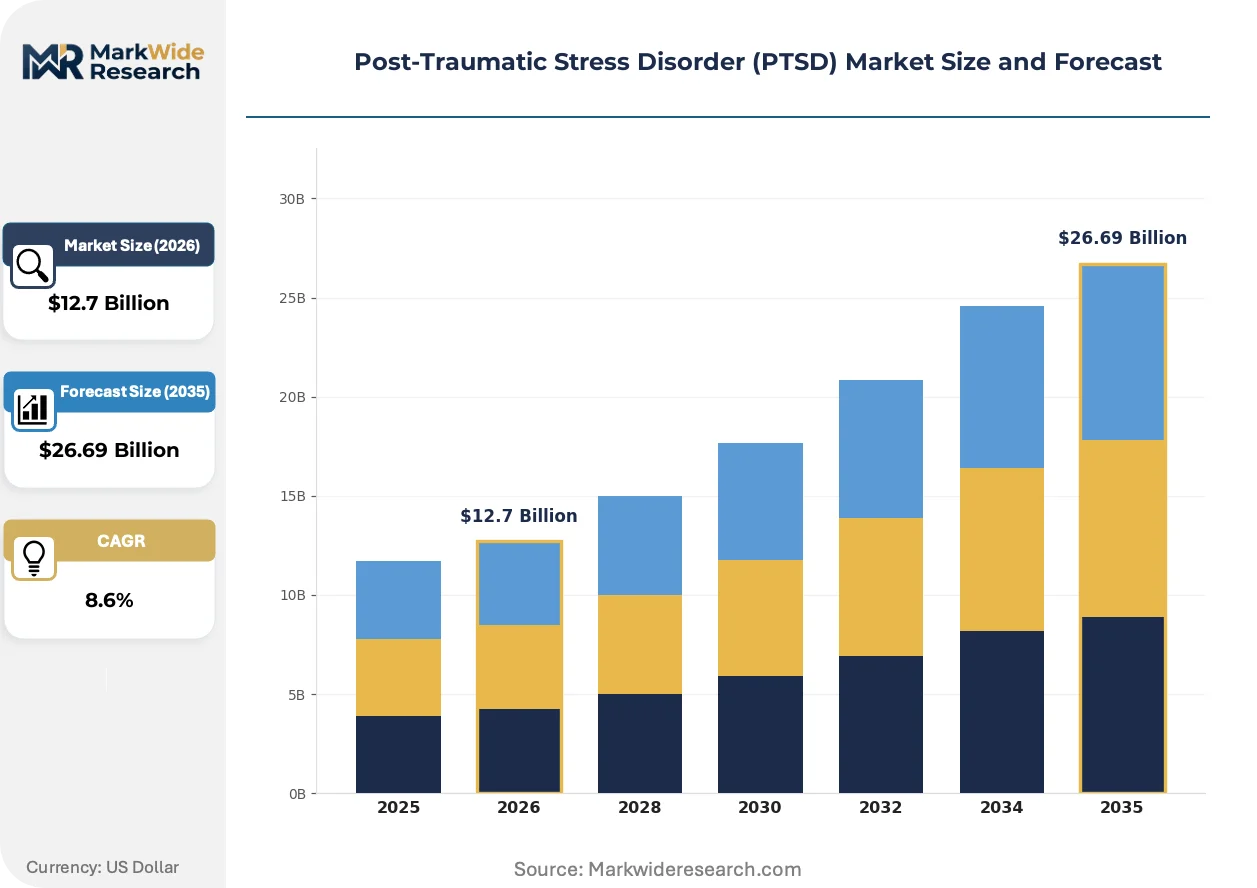
| Market Size in 2026 | $12.7 Billion |
| Market Size in 2035 | $26.69 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Treatment Type: Cognitive Behavioral Therapy, EMDR, Pharmacotherapy, Group Therapy Delivery Mode: In-Person Sessions, Online Therapy, Mobile Apps, Teletherapy Patient Type: Veterans, First Responders, Civilians, Children Care Setting: Hospitals, Outpatient Clinics, Rehabilitation Centers, Community Organizations |
| Companies Covered | Pfizer Inc., GlaxoSmithKline plc, Jazz Pharmaceuticals, Merck KGaA, Otsuka Pharmaceutical, AstraZeneca, Viatris Inc., Bionomics Limited, H. Lundbeck A/S, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Post-Traumatic Stress Disorder (PTSD) Market Trends and Innovations
Immersive technologies are restructuring how exposure therapy delivers controlled trauma processing, compressing the gap between clinical efficacy and patient accessibility while creating new regulatory categories for software-based interventions.
Virtual reality exposure therapy systems are virtualizing the traditional imaginal exposure protocol, enabling precise stimulus control and real-time physiological feedback integration. VA medical centers and academic medical centers are deploying these platforms for combat-related trauma populations. This virtualization is compressing the geographic and resource barriers that previously limited prolonged exposure therapy to specialized urban clinics.
EMA's emerging guidance on psychedelic medicine development is establishing quality standards for synthetic drug substance manufacturing and therapist training frameworks. European member states are preparing national implementation pathways ahead of anticipated centralised marketing authorisations. Germany and the Netherlands are positioning as early-adopter markets through existing compassionate use frameworks and academic research infrastructure.
Patient advocacy networks are demanding faster transitions from clinical trial access to standard-of-care reimbursement, compressing historical lag times between regulatory approval and payer coverage determinations. Employer purchasers and Medicaid managed care plans are revising behavioral health carve-out structures to accommodate novel mechanism therapies. This pressure is most visible in United States markets where veterans service organizations maintain direct legislative access and commercial influence over federal health policy.
Post-Traumatic Stress Disorder (PTSD) Market Segmentation
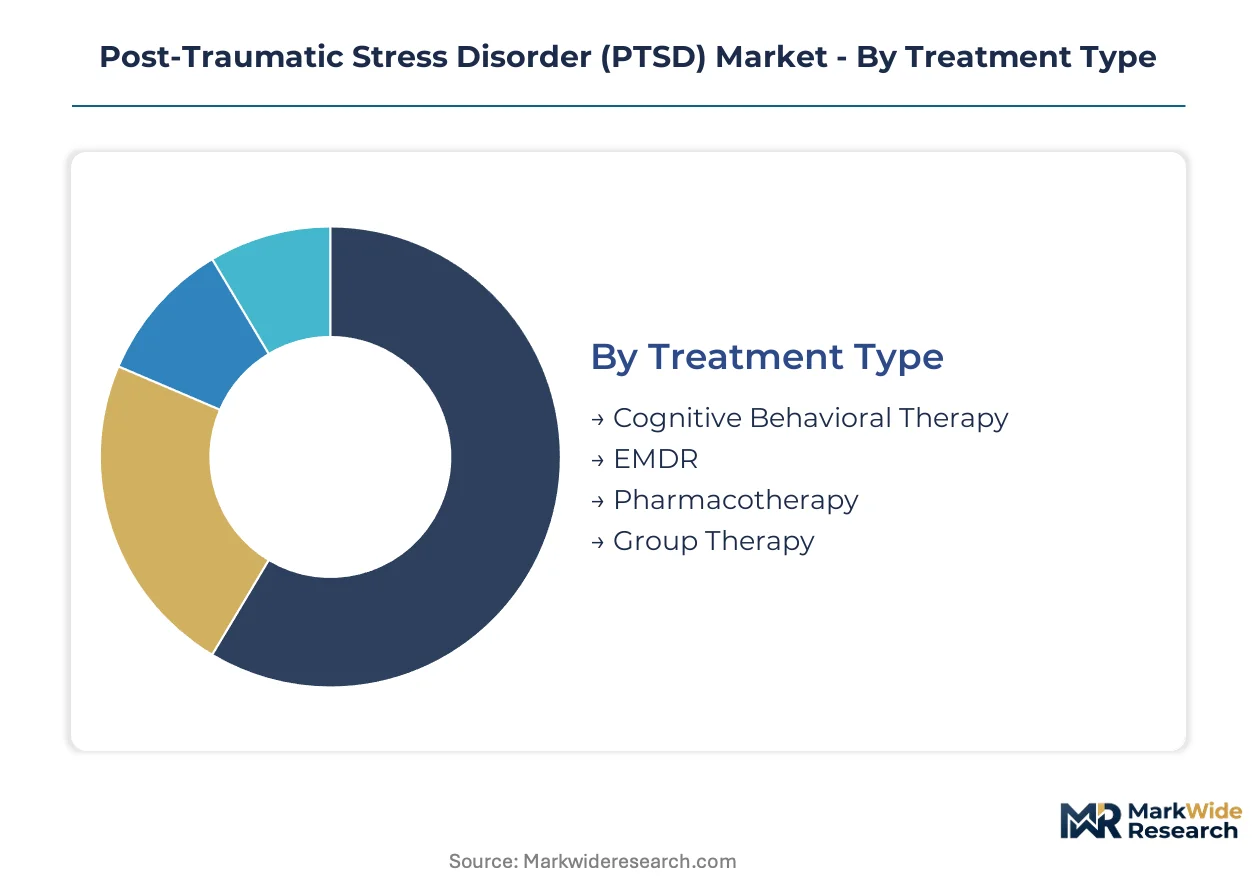
PTSD market segmentation reflects divergent reimbursement pathways, workforce availability constraints, and patient population-specific access requirements. Treatment hierarchies vary sharply across military, civilian, and pediatric cohorts, each demanding tailored service configurations and regulatory compliance frameworks.
Treatment Type:
Cost tier stratification separates maintenance pharmacotherapy from higher-intensity psychosocial interventions requiring specialized practitioner certification.
- Cognitive Behavioral Therapy:Trauma-focused CBT protocols incorporate prolonged exposure and cognitive processing techniques. Demand concentrates in VA medical centers and academic medical centers where reimbursement rates support 12-16 session treatment courses.
- EMDR:Eye movement desensitization and reprocessing employs bilateral stimulation during trauma memory activation. First responder programs in major metropolitan fire and police departments are expanding EMDR capacity through employee assistance contracts.
- Pharmacotherapy:SSRI and SNRI maintenance regimens anchor standard-of-care protocols with established pharmacy benefit coverage.
- Group Therapy:Cohort-based processing models reduce per-patient clinician hours while leveraging peer support dynamics.
Pharmacotherapy holds installed capacity. EMDR is rotating up the share rankings.
Delivery Mode:
Application modality determines regulatory classification, with software-based interventions facing distinct FDA premarket pathways compared to clinician-delivered services.
- Teletherapy:Synchronous video-based psychiatric consultation extends specialist reach into rural health professional shortage areas. Medicaid managed care plans in Texas and Florida are expanding teletherapy reimbursement parity for trauma-focused services.
- Mobile Apps:Smartphone-delivered interventions incorporate biofeedback and mood tracking for between-session symptom management. Veterans Health Administration pilot programs are validating digital phenotyping tools for remote monitoring.
- In-Person Sessions:Traditional clinic-based delivery maintains preference for complex diagnostic presentations and medication management.
- Online Therapy:Asynchronous text and audio messaging platforms reduce stigma barriers for employed civilian populations.
Teletherapy holds installed capacity. Mobile apps are climbing the fastest.
Patient Type:
Customer type segmentation aligns with dedicated funding streams and service-connected disability frameworks that shape purchasing authority.
- Veterans:Federal appropriations through the Veterans Health Administration create concentrated demand with streamlined procurement. Specialized PTSD clinical teams operate at 172 VA medical centers with embedded compensation and pension examination services.
- First Responders:Occupational trauma exposure generates employer-sponsored intervention demand through municipal self-insured plans. Fire department behavioral health programs in Chicago, Los Angeles, and New York are expanding peer support and clinical service integration.
- Civilians:Commercial insurance and out-of-pocket payment dominates this diffuse population with variable benefit design.
- Children:Pediatric PTSD protocols require developmental adaptation and specialized practitioner training, constraining supply.
Veterans holds installed capacity. First responders is gaining share fastest.
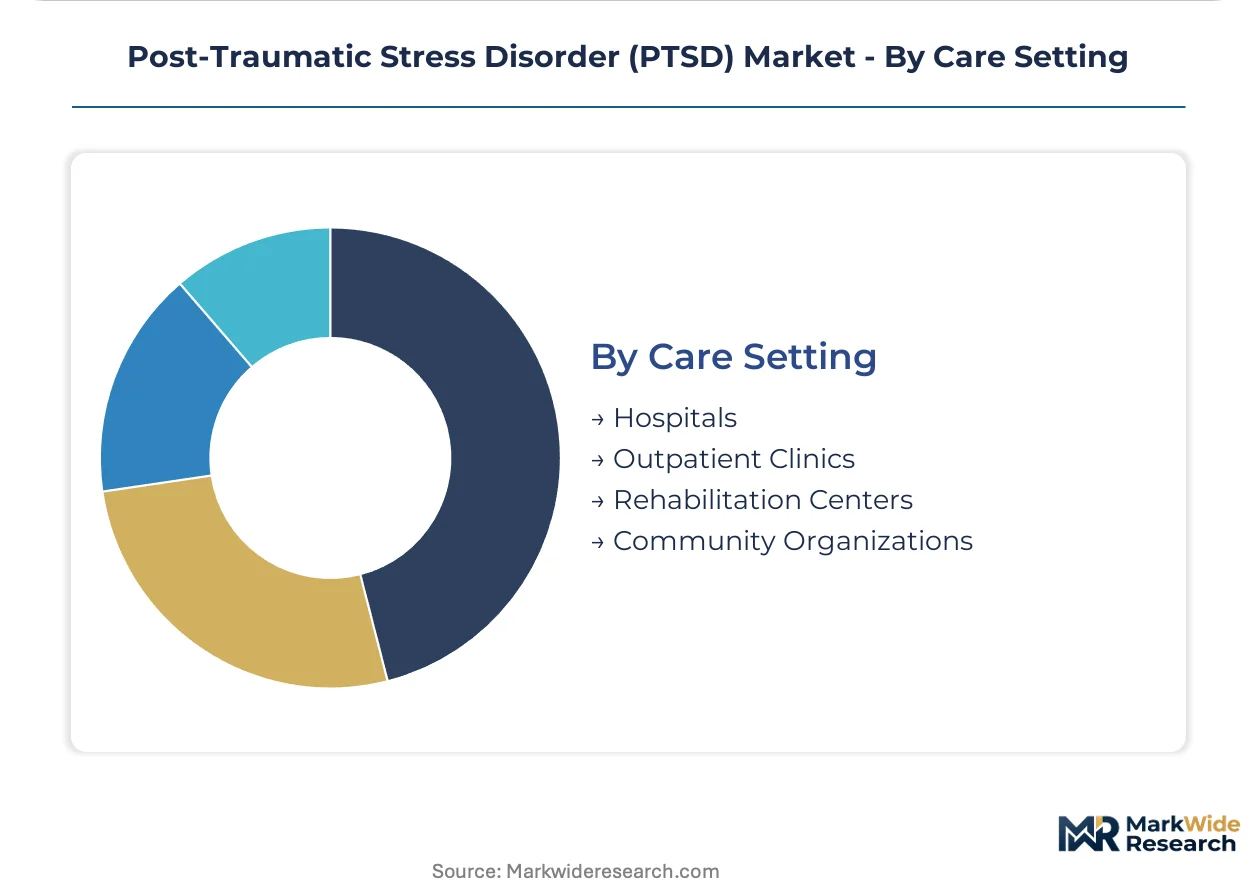
Care Setting:
Supply concentration varies across institutional settings with differing capital requirements and regulatory oversight intensity.
- Outpatient Clinics:Community mental health centers and private practice networks deliver the majority of trauma-focused psychotherapy. Federally qualified health centers in California and New York are expanding PTSD screening through integrated primary care models.
- Hospitals:Inpatient psychiatric units manage acute crisis stabilization and complex comorbid presentations. Academic medical centers in Boston and Baltimore anchor research-intensive treatment programs with embedded clinical trial access.
- Rehabilitation Centers:Residential substance use programs incorporate trauma-informed care for dual diagnosis populations.
- Community Organizations:Nonprofit providers serve uninsured and underinsured populations through grant-funded service delivery.
Outpatient clinics holds installed capacity. Hospitals is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies: the United States concentrates investment in veteran-specific infrastructure and psychedelic research pathways, while European markets emphasize centralized regulatory harmonization and Germany leverages existing compassionate use frameworks for novel therapies.
United States
Veterans Health Administration procurement drives concentrated demand through 172 specialized medical centers with embedded disability examination services. FDA breakthrough therapy designations for MDMA-assisted psychotherapy compress development timelines and signal reimbursement viability to institutional payers. Boston and Baltimore academic medical centers anchor research-intensive treatment programs with embedded clinical trial access.
Germany
Compassionate use frameworks and academic research infrastructure position Germany as an early-adopter market for psychedelic-assisted protocols. EMA emerging guidance on psychedelic medicine development establishes quality standards for synthetic drug substance manufacturing and therapist training frameworks. Heidelberg and Berlin clinical research clusters are preparing national implementation pathways ahead of anticipated centralized marketing authorizations.
United Kingdom
NHS England trauma services are expanding digital therapeutic reimbursement pilots for remote patient populations. MHRA operates under EMA-aligned psychiatric drug development guidelines while maintaining independent digital health software pre-certification pathways. London and Manchester academic centers are validating smartphone-based biometric monitoring for between-session symptom management.
Netherlands
Existing psychedelic research infrastructure and liberal therapeutic policy frameworks accelerate clinical protocol development. The Dutch Health and Youth Care Inspectorate coordinates with EMA on quality standards for therapist certification programs. Amsterdam and Utrecht research institutions are deploying virtual reality exposure therapy systems for combat-related trauma populations.
Australia
TGA regulatory pathways for psychedelic-assisted therapies are advancing through authorized prescriber schemes for treatment-resistant psychiatric conditions. State-based mental health commissioning in Victoria and New South Wales is expanding teletherapy reimbursement parity for rural health professional shortage areas. Melbourne and Sydney academic medical centers are integrating pharmacogenomic profiling into antidepressant prescribing protocols.
Post-Traumatic Stress Disorder (PTSD) Market Competitive Landscape
Capability concentration sits with specialty pharmaceutical developers possessing psychiatric drug portfolios; scale advantage sits with diversified multinationals with established formulary positions and global distribution infrastructure. The market structures around three tiers: large-cap pharmaceutical incumbents with maintenance pharmacotherapy franchises, mid-cap specialty players targeting trauma-related sleep and anxiety comorbidities, and emerging biotechnology developers with novel GABA-targeting and psychedelic-assisted mechanisms. Competitive moves center on platform licensing for digital therapeutic modules and strategic positioning ahead of anticipated FDA approvals for breakthrough-designated therapies.
Among large-cap diversified incumbents, Pfizer Inc. and AstraZeneca occupy positions anchored by established SSRI and SNRI maintenance regimens with entrenched pharmacy benefit coverage. Jazz Pharmaceuticals exemplifies the specialty-tier archetype, concentrating on trauma-related sleep disturbance therapeutics within narrower but higher-reimbursement clinical niches. Bionomics Limited represents the emerging biotechnology vector, advancing novel mechanism candidates through GABA-targeting compound development for anxiety-spectrum disorders.
| Leading Market Players |
|---|
| Pfizer Inc. |
| GlaxoSmithKline plc |
| Jazz Pharmaceuticals |
| Merck KGaA |
| Otsuka Pharmaceutical |
| AstraZeneca |
| Viatris Inc. |
| Bionomics Limited |
| H. Lundbeck A/S |
| Others |
Pricing and Supply Chain Analysis
DEA Schedule I research controls constitute a regulatory chokepoint that compresses both pricing tier spreads and supply chain configuration, forcing psychedelic-assisted therapy developers into specialized manufacturing partnerships and extended approval timelines that inflate development costs while limiting production scale.
Pricing Analysis
Project-based contracting for psychedelic-assisted therapy protocols dominates reimbursement negotiations, with three-tier pricing structure across premium, standard, and economy levels reflecting FDA breakthrough designation status, therapist certification tier, and site-of-service delivery cost. Price differentiation hinges on pharmacogenomic companion diagnostic bundling and vertical integration into digital phenotyping platforms. Cost compression in standard-tier SSRI maintenance regimens is intensifying because of pharmacy benefit manager formulary exclusions. Veterans Health Administration procurement represents the least price-sensitive buyer segment; civilian commercial payers exhibit highest sensitivity to prior authorization friction.
Supply Chain Analysis
Active pharmaceutical ingredient synthesis for MDMA and psilocybin derivatives draws from specialized contract manufacturing organizations concentrated in Switzerland, the Netherlands, and selected U.S. facilities with DEA licensing. Synthetic drug substance production rests on precursor chemical availability, GMP-certified reactor capacity, and analytical validation services. Single-source vulnerability permeates therapist certification program availability, constraining scalable protocol deployment. Distribution runs through academic medical center research pharmacies and, upon approval, specialty pharmacy networks with cold-chain and controlled-substance handling capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized psychotherapy workforce scarcity defines competitive boundaries in this market, with certified practitioner availability constraining scalable delivery of evidence-based interventions regardless of pharmaceutical innovation velocity.
For Market Incumbents: Build formulary moats through deep integration with Veterans Health Administration procurement channels and embedded compensation and pension examination services. Secure exclusive digital therapeutic platform licensing to preempt asynchronous teletherapy disruption. Expand manufacturing capacity in DEA-licensed facilities to capture psychedelic-assisted therapy production upon FDA approval.
For New Entrants and Emerging Players: Rural health professional shortage areas in Texas and Florida present the most penetrable geographic white space for teletherapy-first deployment models. Target municipal first responder employee assistance programs through direct employer contracting channels. Pursue pharmacogenomic profiling partnerships to differentiate antidepressant prescribing protocols.
For Investors and Strategic Acquirers: FDA breakthrough therapy designation for MDMA-assisted psychotherapy reshapes the acquisition landscape by validating reimbursement viability and compressing development risk profiles. Long-term viability centers on platform licensing revenue streams and companion diagnostic integration capabilities. Acquisition target archetypes include digital therapeutic developers with validated clinical outcomes and GABA-targeting biotechnology platforms. The signal to watch is DEA rescheduling determinations for Schedule I substances.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Phase III MDMA-assisted psychotherapy data anchors FDA breakthrough pathway validation. |
| Regulatory Approval Pathway | DEA Schedule I research permission expansion unlocks multi-site protocol scaling. |
| Licensing Agreement | Digital therapeutic module platform deals extend reach into rural health shortage areas. |
| Manufacturing Scale-Up | GMP-certified synthetic drug substance capacity addresses psychedelic therapy supply constraints. |
| Pipeline Diversification | Novel GABA-targeting compounds address anxiety-spectrum comorbidities in trauma populations. |
Research Methodology
Operator-level perspectives from drug development executives, regulatory affairs leads, formulary directors, and payer access specialists anchored the qualitative base for this analysis. Primary interview data combined with secondary validation from FDA filings, ClinicalTrials.gov registry entries, Veterans Health Administration procurement records, and hospital formulary databases. Bottom-up patient population modeling and top-down pharmaceutical revenue triangulation ensured cross-verification across estimation approaches.
Scenario-bracketing framed the analytical approach across the projection horizon, with segmentation dimensions spanning treatment type, delivery mode, patient population, and regional regulatory cluster. CAGRs derived from longitudinal prescribing pattern analysis and reimbursement rate trajectory modeling. Forecast inputs incorporated DEA scheduling determination timelines and digital therapeutic FDA 510(k) approval velocity assumptions.
The forecast holds incumbent behavior within observed patterns; aggressive moves by emerging psychedelic biotechnology developers or digital health platform entrants would shift outcomes. Material shifts in FDA breakthrough therapy designation criteria or DEA research control enforcement posture would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Mental Health Services
Anxiety Disorders and Depression Treatment Market
Mental Health Services
Post-Partum Depression Market
Mental Health Services
US Behavioral Health Market
Mental Health Services
Mental Health Market
Mental Health Services
US Workplace Stress Management Market
Mental Health Services
Panic Attack Treatment Market
Mental Health Services
Behavioral Health Software Market
Mental Health Services
US Psychiatry Clinic Market
Mental Health Services
South Korea Post-Traumatic Stress Disorder Treatment Market
Mental Health Services
Behavioral Health Care Software and Services Market
Mental Health Services
Global Workplace Stress Management Market
Mental Health Services
Spain Post-Traumatic Stress Disorder Treatment Market
Mental Health Services
Agoraphobia Market
Mental Health Services
Schizoaffective Disorders Treatment Market
Mental Health Services
Global Mental Health Apps Market
Mental Health Services
Seasonal Affective Disorder (SAD) Market