
 Cirrhosis Management Market | 2026-2036
Cirrhosis Management Market Size, Share, and Industry Trends Forecast 2026-2036
Cirrhosis Management Market Outlook
Hepatology specialist shortages across North America and Western Europe are reorganizing how care networks deploy cirrhosis management resources. Gilead Sciences sustains leadership in antiviral portfolios for hepatitis-related cirrhosis through deep clinical trial infrastructure. Novo Nordisk anchors metabolic cirrhosis adjacencies with its emerging NASH-to-cirrhosis pipeline investments. Bristol-Myers Squibb Company differentiates through immuno-oncology overlap in hepatocellular carcinoma prevention within cirrhotic patient populations.
Cirrhosis management encompasses pharmacological intervention, surgical transplantation, diagnostic monitoring, and nutritional support aimed at halting fibrotic progression and managing portal hypertension complications. The field relies on elastography-based liver stiffness measurement and serum biomarker panels to stage fibrosis without invasive biopsy. Medications dominate current revenue pools as antiviral and antifibrotic therapies capture chronic treatment volumes, while diagnostic devices represent the fastest-expanding segment driven by point-of-care liver function testing adoption. Liver transplantation within the therapy area category commands premium pricing but faces structural constraints from organ availability, pushing investment toward palliative care protocols and lifestyle modification programs.
The FDA's breakthrough therapy designation and EMA's priority medicines scheme are accelerating market access for novel antifibrotic candidates, while WHO inclusion criteria for essential medicines shape procurement patterns in emerging health systems. HIPAA compliance requirements and EU MDR device classification rules are elevating data security and clinical evidence standards for connected diagnostic platforms. Stakeholders must monitor how regenerative medicine regulatory frameworks evolve to determine whether stem cell and gene therapy approaches will displace conventional cirrhosis management paradigms.
Market Dynamics
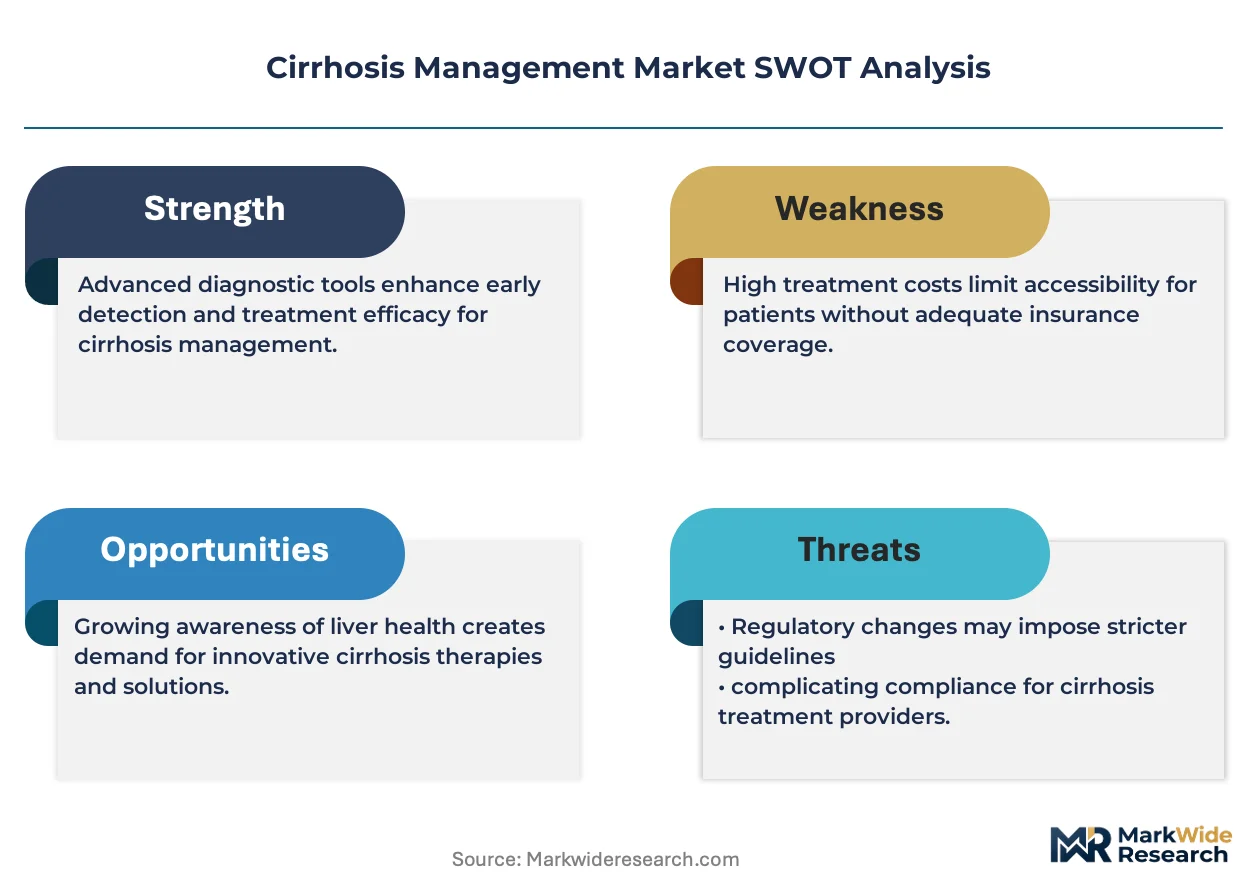
FDA breakthrough therapy designations and EMA priority medicines schemes are compressing clinical trial timelines for novel antifibrotic candidates, while hepatology specialist shortages across tertiary care networks force resource reallocation toward telemedicine and nurse-led monitoring protocols.
Growth Catalysts
- Non-invasive diagnostic protocols:Elastography-based liver stiffness measurement and serum biomarker panels are eliminating invasive biopsy requirements. Hospital-based hepatology departments in the United States, Germany, and Japan are standardizing these workflows.
- WHO essential medicines inclusion:Procurement frameworks in emerging health systems are aligning with WHO criteria, expanding access to antiviral and antifibrotic therapies in Brazil, India, and South Africa.
- Point-of-care liver function testing:Portable diagnostic devices are decentralizing cirrhosis staging from centralized labs to primary care settings and community health centers.
Market Restraints
- Organ availability constraints:Liver transplantation faces structural supply limitations from deceased donor shortages, pushing demand toward palliative protocols and creating pricing pressure on immunosuppressive regimens.
- EU MDR device classification rules:Elevated clinical evidence requirements for connected diagnostic platforms are extending certification timelines and raising development costs for elastography manufacturers.
- Biopsy-dependent reimbursement:Several national health technology assessment bodies continue requiring histological confirmation for advanced therapy reimbursement, slowing non-invasive test adoption.
Strategic Opportunities
- NASH-to-cirrhosis pipeline adjacencies:Metabolic dysfunction-associated steatohepatitis progression pathways offer entry points for metabolic therapy developers to capture pre-cirrhotic populations before fibrotic decompensation.
- Stem cell and gene therapy regulatory frameworks:Evolving regenerative medicine pathways in the United States, Switzerland, and South Korea may displace conventional management paradigms for end-stage liver disease.
- Remote patient monitoring platforms:Telemedicine infrastructure investments by United States tertiary care networks are enabling continuous portal hypertension surveillance outside traditional clinic settings.
Industry Challenges
- Hepatology specialist workforce gaps:Fellowship program output in the United States and Western Europe fails to match cirrhosis prevalence growth, forcing care delegation to advanced practice providers and automated decision support systems.
- HIPAA compliance for connected diagnostics:Data security requirements for cloud-based liver stiffness databases are complicating multi-site clinical trial designs and cross-border data pooling for AI training sets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cirrhosis Management Market |
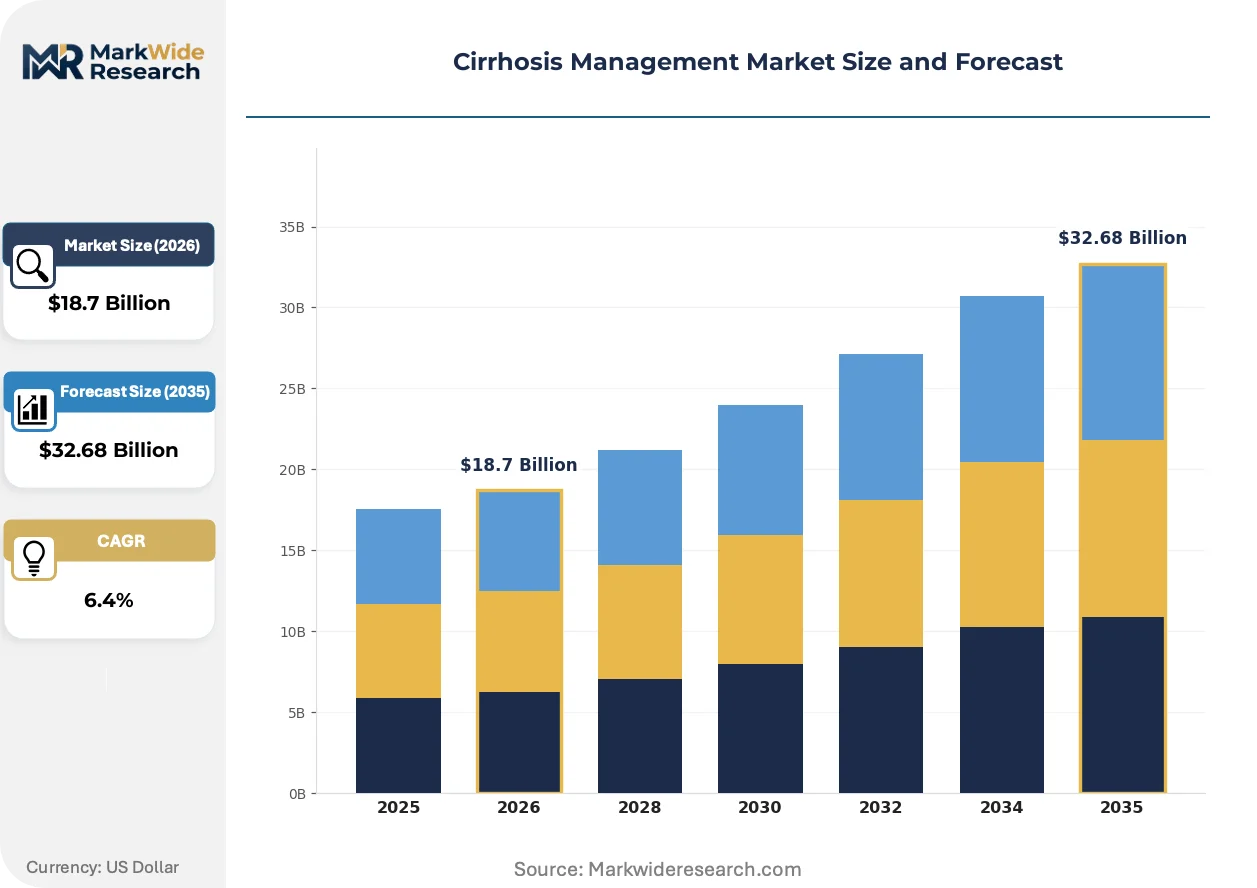
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medications, Surgical Procedures, Diagnostic Devices, Nutritional Supplements Therapy Area: Antiviral Treatment, Liver Transplantation, Palliative Care, Lifestyle Modification End User: Hospitals, Clinics, Homecare, Rehabilitation Centers Delivery Mode: Oral Administration, Injectable, Intravenous, Topical Application |
| Companies Covered | AstraZeneca, B. Braun Medical Inc., Gilead Sciences, Inc., Histogen Inc., Alliancells Bioscience Corporation Ltd., Madrigal Pharmaceuticals, Novo Nordisk, Stempeutics Research Pvt. Ltd., Bristol-Myers Squibb Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cirrhosis Management Market Strategic Shifts
Antifibrotic drug development and diagnostic miniaturization are converging to shift cirrhosis management from reactive decompensation treatment toward preemptive fibrosis reversal and early complication detection.
Transient elastography and magnetic resonance elastography are decomposing the diagnostic monopoly of percutaneous liver biopsy. Tertiary hepatology departments in the United States, France, and Japan are adopting these modalities as first-line staging tools. The technology is decomposing referral patterns by enabling primary care physicians to stage fibrosis severity without specialist consultation, compressing time-to-treatment initiation.
The FDA's breakthrough therapy designation and EMA's priority medicines scheme are accelerating market access for novel antifibrotic candidates. These pathways compress Phase II-to-approval timelines and reduce regulatory uncertainty for mechanism-first drug development. Small-molecule and biologic developers targeting transforming growth factor-beta and integrin pathways are the primary beneficiaries, with United States-based sponsors capturing the majority of designations.
Consolidation of liver disease management programs within United States tertiary care networks is concentrating procurement authority at the health system level rather than individual physician discretion. Integrated delivery networks are standardizing formularies and diagnostic equipment across affiliated hospitals, displacing independent hepatology practice purchasing patterns. This behavioral shift is most visible in Texas, California, and Florida, where large Catholic and academic health systems dominate regional market access.
Cirrhosis Management Market Segmentation
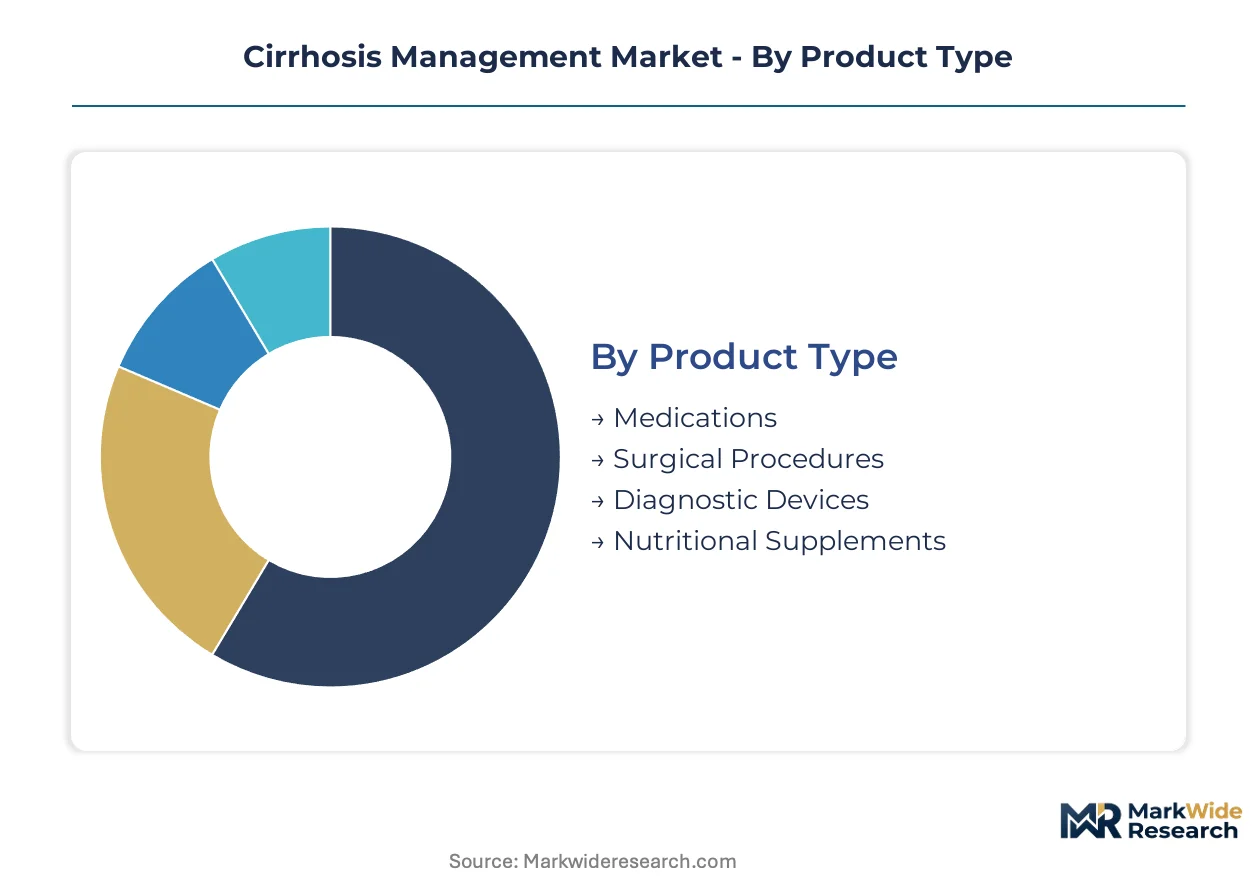
Cirrhosis management requires coordinated deployment across pharmacological, interventional, and monitoring modalities. Segmentation reveals how regulatory pathways and care settings determine commercial access and reimbursement structures for each product category.
Product Type:
FDA breakthrough therapy designations and EMA priority medicines schemes create tiered approval timelines that favor certain modalities over others.
- Medications:Antiviral and antifibrotic compounds dominate current revenue pools through chronic treatment volumes. Hepatitis C direct-acting antivirals and emerging NASH-targeted therapies command premium pricing in United States integrated delivery networks.
- Diagnostic Devices:Elastography systems and serum biomarker panels are eliminating invasive biopsy requirements. Point-of-care liver function testing is decentralizing staging from centralized laboratories to primary care settings in Germany, Japan, and Texas.
- Surgical Procedures:Transjugular intrahepatic portosystemic shunt placement and variceal band ligation address portal hypertension complications. Demand concentrates in tertiary hepatology departments with interventional radiology capabilities.
- Nutritional Supplements:Branched-chain amino acid formulations and specialized enteral nutrition support hepatic encephalopathy management. Homecare distribution channels are expanding access outside hospital settings.
Medications handle the majority of throughput; Diagnostic Devices is expanding most quickly on share.
Therapy Area:
Cost tier differentiation separates curative interventions from chronic management protocols.
- Antiviral Treatment:Direct-acting antiviral regimens for hepatitis B and C represent the foundational pharmacological approach. WHO essential medicines inclusion is expanding procurement frameworks in Brazil, India, and South Africa.
- Liver Transplantation:Deceased donor and living donor transplantation commands premium pricing but faces structural organ availability constraints. Immunosuppressive regimen costs persist across decades post-procedure.
- Palliative Care:Symptom management for end-stage disease includes ascites drainage, hepatic encephalopathy control, and pain protocols. Demand is climbing as transplant eligibility criteria tighten.
- Lifestyle Modification:Alcohol cessation programs and metabolic syndrome management address underlying etiologies. Nurse-led protocols are filling hepatology specialist workforce gaps across United States tertiary care networks.
Antiviral Treatment captures the largest patient volume; Palliative Care is gaining share fastest as transplant waiting lists lengthen.
End User:
Care setting determines technology sophistication requirements and reimbursement coding complexity.
- Hospitals:Tertiary hepatology departments house elastography systems, interventional suites, and transplant coordination. United States academic medical centers in California, Florida, and Texas are consolidating liver disease management programs.
- Clinics:Community hepatology and gastroenterology practices handle stable cirrhosis monitoring and antiviral prescribing. Portable diagnostic devices are enabling fibrosis staging without specialist referral.
- Homecare:Remote patient monitoring platforms and self-administered nutritional protocols extend management beyond facility walls. Telemedicine infrastructure investments support continuous portal hypertension surveillance.
- Rehabilitation Centers:Post-transplant recovery and alcohol use disorder programs address functional restoration. Medicare reimbursement patterns favor shorter acute stays with extended rehabilitation.
Hospitals manage the most complex cases; Homecare shows the steepest expansion trajectory as remote monitoring platforms mature.
Delivery Mode:
Patient compliance and administration setting dictate formulation development priorities.
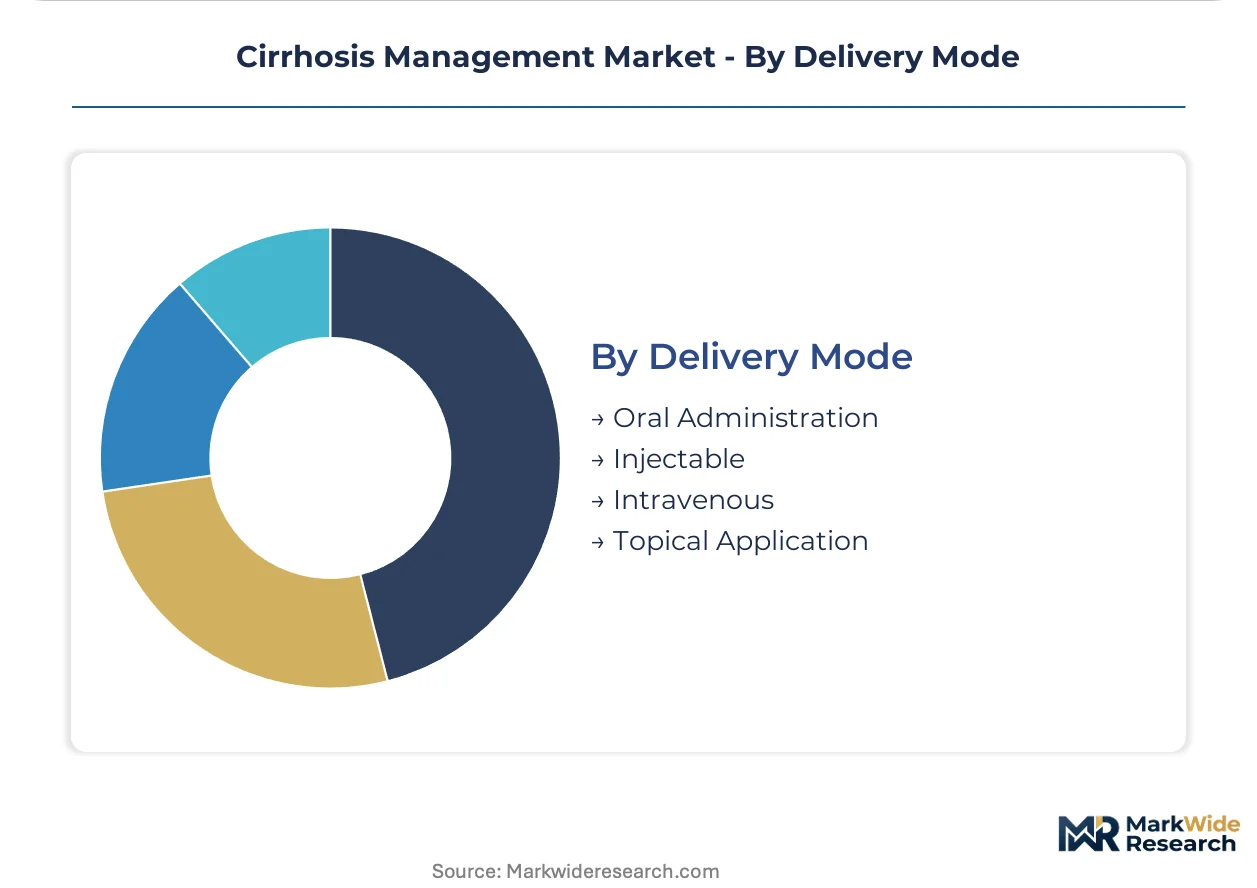
- Oral Administration:Once-daily direct-acting antiviral tablets maximize adherence for hepatitis C eradication. Fixed-dose combinations reduce pill burden in chronic cirrhosis populations.
- Injectable:Pegylated interferon and emerging antifibrotic biologics require clinical administration. Subcutaneous formulations are shifting some volume toward home self-injection.
- Intravenous:Hospital-based infusions include albumin replacement, antibiotics for spontaneous bacterial peritonitis, and terlipressin for hepatorenal syndrome. Acute decompensation episodes drive intermittent utilization.
- Topical Application:Limited current use in cirrhosis management; transdermal delivery research targets hepatic drug targeting with reduced systemic exposure.
Oral Administration dominates prescription volumes; Injectable formats are climbing fastest as biologic antifibrotics advance through clinical pipelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns for cirrhosis management diverge sharply across geographies. The United States concentrates spending on premium diagnostic devices and transplant infrastructure, while emerging health systems prioritize antiviral access through WHO-aligned procurement frameworks.
United States
Tertiary care networks in Texas, California, and Florida are consolidating liver disease management programs within integrated delivery systems. FDA breakthrough therapy designations compress Phase II-to-approval timelines for novel antifibrotic candidates. The Mayo Clinic Rochester and Cleveland Clinic anchor advanced elastography standardization efforts across Midwestern academic medical centers.
Germany
Hospital-based hepatology departments in Bavaria and North Rhine-Westphalia lead EU adoption of non-invasive diagnostic protocols. EU MDR device classification rules elevate clinical evidence requirements for connected diagnostic platforms, extending certification timelines for elastography manufacturers. The Heidelberg University Hospital cluster drives magnetic resonance elastography research translation into clinical workflows.
Japan
Metabolic dysfunction-associated steatohepatitis progression pathways command rising diagnostic investment as obesity-linked cirrhosis prevalence climbs. PMDA priority review vouchers accelerate market access for regenerative medicine candidates. The Tokyo-Kanto region concentrates tertiary hepatology capacity with interventional radiology suites at University of Tokyo Hospital and Keio University Hospital.
Brazil
WHO essential medicines inclusion shapes procurement frameworks for hepatitis C direct-acting antivirals through the national health system. ANVISA regulatory harmonization with FDA standards streamlines approval pathways for imported diagnostic devices. São Paulo state anchors hepatology specialist training programs at Hospital das Clínicas da Universidade de São Paulo.
India
CDSCO accelerated approval pathways for breakthrough therapies are reshaping product development timelines for domestic antifibrotic developers. Hepatitis B-related cirrhosis dominates disease burden, driving demand for affordable antiviral regimens. The Delhi-NCR cluster concentrates transplant coordination capacity at Institute of Liver and Biliary Sciences and Medanta-The Medicity.
Cirrhosis Management Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in cirrhosis management. Pharmaceutical conglomerates with antiviral and metabolic portfolios command revenue pools through chronic treatment volumes, while diagnostic device specialists capture share in the fastest-expanding segment. Three archetypes dominate: antiviral therapy developers with deep clinical trial infrastructure, metabolic disease specialists extending into NASH-to-cirrhosis pathways, and regenerative medicine pioneers advancing stem cell approaches. Competitive moves concentrate on portfolio diversification through NASH pipeline acquisitions and strategic partnerships for point-of-care diagnostic distribution.
Within the antiviral and metabolic therapy tier, Gilead Sciences, Novo Nordisk, and Bristol-Myers Squibb occupy positions reflecting distinct strategic anchors. Gilead Sciences exemplifies the integrated pharmaceutical archetype with established hepatitis-related cirrhosis portfolios. Novo Nordisk represents metabolic disease specialists extending pipeline investments into pre-cirrhotic populations. Bristol-Myers Squibb sits within the immuno-oncology overlap segment targeting hepatocellular carcinoma prevention. These three entities illustrate how therapeutic focus areas determine competitive positioning without requiring uniform capability breadth.
| Leading Market Players |
|---|
| AstraZeneca |
| B. Braun Medical Inc. |
| Gilead Sciences, Inc. |
| Histogen Inc. |
| Alliancells Bioscience Corporation Ltd. |
| Madrigal Pharmaceuticals |
| Novo Nordisk |
| Stempeutics Research Pvt. Ltd. |
| Bristol-Myers Squibb Company |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake agreements for direct-acting antivirals lock in supply access and price visibility for United States integrated delivery networks negotiating with Gilead Sciences and Bristol-Myers Squibb. These contracts stabilize procurement costs across multi-year treatment protocols while exposing buyers to formulary rigidity if breakthrough therapies emerge outside existing arrangements.
Pricing Analysis
Project-based pricing for liver transplantation services dominates high-acuity interventions, with three-tier pricing structure across premium, standard, and economy levels separating academic medical centers from community hospitals and ambulatory surgical centers. Price differentiation hinges on transplant volume scale and UNOS certification tier, with Medicare reimbursement benchmarks exerting downward pressure on immunosuppressive regimen margins. Price-sensitive buyers cluster in Brazilian and Indian public health systems, while United States commercial payers show lowest sensitivity to hepatitis C antiviral costs.
Supply Chain Analysis
Strategic stockpiling of branched-chain amino acid formulations and albumin replacement products characterizes hospital pharmacy inventory management, contrasting with just-in-time preferences for point-of-care diagnostic devices. Active pharmaceutical ingredient production draws from India, China, and Switzerland, with elastography system manufacturing concentrated in France, Japan, and the United States. Single-source vulnerability for hepatitis C polymerase inhibitors creates supply chain risk, while distribution runs through GPO contracts and direct manufacturer agreements with tertiary care networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA breakthrough therapy designations and EMA priority medicines schemes are compressing development timelines, creating a high-growth disruption window as regenerative medicine candidates threaten conventional cirrhosis management paradigms.
For Market Incumbents: Secure exclusive distribution rights for point-of-care elastography devices through long-term hospital system partnerships, insulating against diagnostic miniaturization threats from emerging device specialists. Deepen backward integration into serum biomarker assay development to capture recurring revenue from fibrosis monitoring protocols. Prioritize R&D investment in transforming growth factor-beta pathway inhibitors ahead of mechanism-first competitor entries. For New Entrants and Emerging Players: Remote patient monitoring platform deployment represents the most penetrable service-layer gap, as United States tertiary care networks struggle with hepatology specialist workforce shortages. Target homecare settings in Texas and Florida where telemedicine infrastructure investments enable continuous portal hypertension surveillance outside traditional clinic settings. Pursue strategic partnerships with existing GPO contracts managers to bypass hospital procurement committee barriers. For Investors and Strategic Acquirers: Diagnostic device specialists with magnetic resonance elastography software capabilities offer compelling acquisition targets as non-invasive staging protocols displace biopsy-dependent reimbursement structures. Long-term viability frames around stem cell therapy regulatory framework maturation in the United States, Switzerland, and South Korea. Watch for PMDA priority review voucher issuance as an inflection indicator signaling regenerative medicine pathway acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | FDA breakthrough therapy designation compresses Phase II-to-approval timelines for antifibrotic candidates. |
| Regulatory Approval Pathway | EMA priority medicines scheme accelerates market access for novel mechanism-first drug development. |
| Hospital System Partnership | Integrated delivery networks in California and Texas consolidate liver disease management program procurement authority. |
| Software Companion Development | AI-enabled liver stiffness databases enable automated fibrosis staging without specialist consultation. |
| Reimbursement Strategy | WHO essential medicines inclusion shapes antiviral procurement frameworks in Brazil, India, and South Africa. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with hepatology department heads, formulary directors at integrated delivery networks, regulatory affairs specialists, and GPO contracts managers; and secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital procurement databases. Bottom-up patient volume modeling and top-down pharmaceutical revenue triangulation anchored market size estimates across the projection horizon.
Across the analysis window, forecasts segmented by product type, therapy area, end user, and delivery mode were calibrated against elastography adoption curves and antiviral treatment initiation rates. CAGRs derived from historical volume trajectories and regulatory approval velocity assumptions, with NASH-to-cirrhosis progression modeling and transplant waiting list dynamics as disease-specific forecast inputs.
Forecasts assume regulatory continuity in FDA breakthrough therapy pathways and EMA priority medicines schemes; material policy shifts would require re-modeling. Antifibrotic pipeline failure rates and organ donation policy changes represent specific revision triggers. Revision becomes warranted when stem cell therapy regulatory framework clarity crosses commercialization thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Immunoglobulin (Igg) Replacement Therapy Market
Specialty Medicine
Intussusception Market
Specialty Medicine
Global Melanoma Diagnostics and Therapeutics Market
Specialty Medicine
Global Cough Hypersensitivity Syndrome Treatment Market
Specialty Medicine
Systemic Scleroderma Treatment Market
Specialty Medicine
Acute Intermittent Porphyria Market
Specialty Medicine
Mantle Cell Lymphoma Market
Specialty Medicine
Global Neurotrophic Keratitis Treatment Market
Specialty Medicine
Hidradenitis Suppurativa (HS) Treatment Market
Specialty Medicine
Global Female Sexual Dysfunction Treatment Market
Specialty Medicine
Cystinuria Treatment Market
Specialty Medicine
Global Liver Cancer Treatment Market
Specialty Medicine
HER2 Positive Gastric Cancer Market
Specialty Medicine
Bipolar Disorder Therapeutics Market
Specialty Medicine
Anaplastic Large Cell Lymphoma (ALCL) Therapeutics Market
Specialty Medicine
Mucinoses Management Market