
 Europe Idiopathic Pulmonary Fibrosis Treatment Market | 2026-2036
Europe Idiopathic Pulmonary Fibrosis Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Idiopathic Pulmonary Fibrosis Treatment Market Intelligence
Combination therapy bundling is shifting prescribing patterns across European pulmonology practices. Boehringer Ingelheim International GmbH leverages its nintedanib franchise to anchor market presence in Western Europe. F. Hoffmann-La Roche Ltd competes through pirfenidone portfolio extensions and specialist channel control. Galapagos NV differentiates via JAK inhibitor innovation targeting fibrotic pathways.
Idiopathic pulmonary fibrosis treatment encompasses pharmaceutical interventions targeting progressive interstitial lung scarring of unknown etiology, primarily involving oral antifibrotic agents that slow forced vital capacity decline. The therapeutic category serves to delay disease progression, reduce acute exacerbation frequency, and extend transplant-free survival in patients with confirmed usual interstitial pneumonia patterns. Antifibrotic agents dominate current revenue pools due to established reimbursement and proven efficacy profiles. Small molecules retain structural importance for manufacturing scale and cost containment, while biologics represent the fastest-growing technology segment driven by pipeline monoclonal antibodies. Hospitals capture the largest end-user share through centralized infusion and monitoring protocols.
EMA orphan drug designation frameworks shape market access timelines and exclusivity incentives for novel IPF compounds. The EU MDR and national health technology assessment bodies, including NICE in the United Kingdom and IQWiG in Germany, govern pricing negotiations and clinical evidence thresholds. Stakeholders must monitor conditional reimbursement pathways and real-world evidence requirements as regulatory stringency intensifies across European jurisdictions.
Market Dynamics
EMA's tightening EU MDR evidence requirements for orphan lung therapies are compressing market access timelines and forcing manufacturers to front-load clinical investment before reimbursement negotiations.
Growth Catalysts
- Hospital-based pulmonology expansion:Tertiary respiratory centers across Germany, France, and Italy are consolidating antifibrotic procurement into centralized formularies, creating volume concentration that rewards established suppliers.
- EMA orphan drug exclusivity:Extended market protection periods for novel IPF compounds incentivize pipeline investment despite small patient populations, accelerating therapeutic innovation cycles.
- Biomarker-guided patient stratification:Progressive fibrosis phenotyping via genomic and proteomic profiling is expanding addressable patient pools beyond traditional diagnostic boundaries.
Market Restraints
- Reimbursement compression from IQWiG and NICE:German and British health technology assessment bodies are demanding incremental cost-effectiveness ratios that challenge pricing power for existing antifibrotics.
- Active pharmaceutical ingredient concentration:Synthesis of nintedanib and pirfenidone intermediates depends on limited European contract manufacturing capacity, creating supply vulnerability.
- Diagnostic latency:Average four-year delay from symptom onset to confirmed usual interstitial pneumonia pattern shrinks effective treatment windows and limits addressable prevalence.
Strategic Opportunities
- Eastern European market development:Poland, Hungary, and Czech Republic exhibit rising IPF diagnosis rates with nascent reimbursement frameworks that favor first-mover positioning.
- Real-world evidence generation:Conditional reimbursement pathways under EU MDR Article 97 create openings for post-authorization efficacy data to secure permanent market access.
- JAK inhibitor combination protocols:Convergence of antifibrotic small molecules with selective JAK1/2 inhibition offers mechanistic synergy for progressive fibrosing interstitial lung disease expansion.
Industry Challenges
- Specialized interstitial lung disease nursing shortage:Tertiary centers in Italy and Spain face recruitment gaps for trained coordinators who manage antifibrotic monitoring protocols.
- EU MDR technical documentation burden:Legacy device-drug combination products require extensive clinical evidence recertification, straining regulatory affairs capacity.
- Cross-border patient mobility complexity:S4A rare disease networks fragment treatment continuity when patients seek care outside home jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Idiopathic Pulmonary Fibrosis Treatment Market |
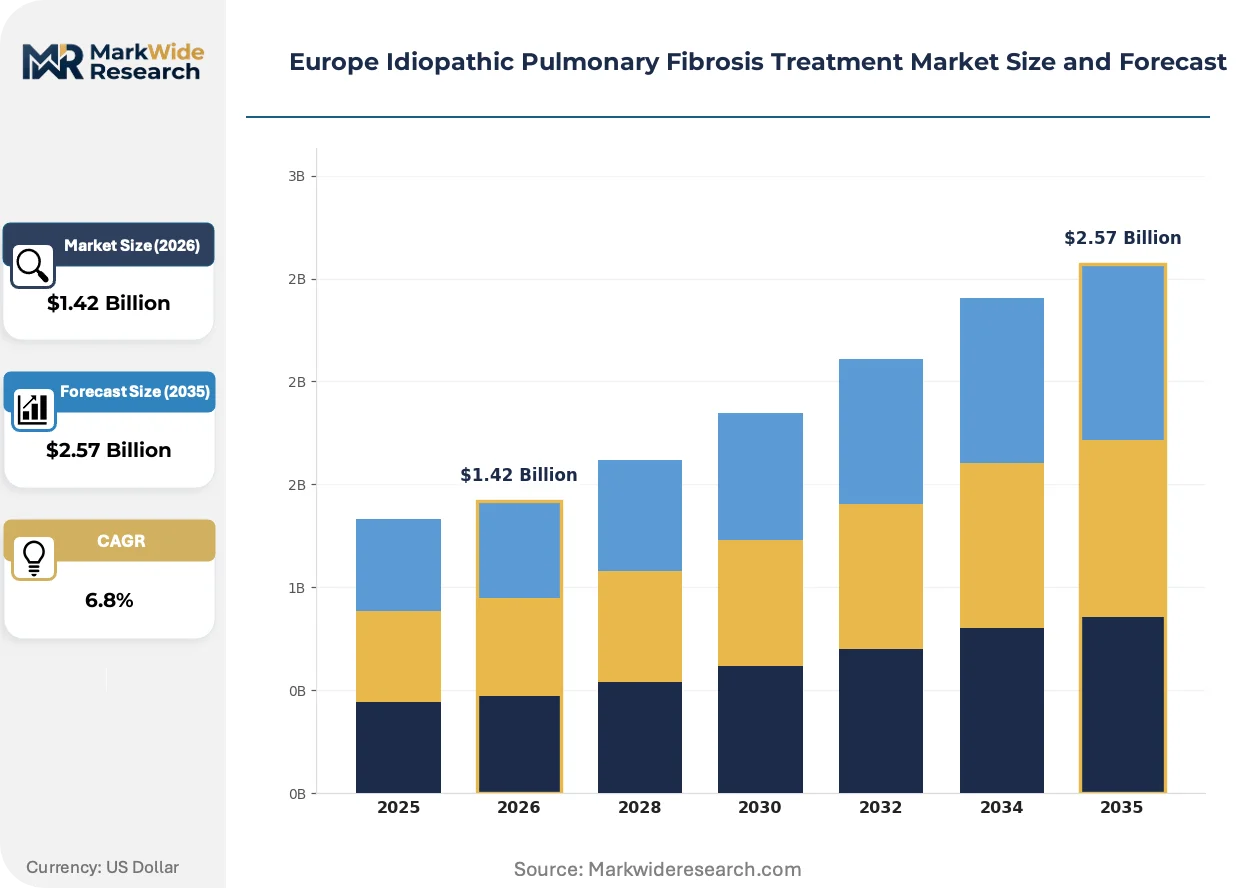
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antifibrotic Agents, Corticosteroids, Pathway Inhibitors, Supportive Therapies Technology: Biologics, Small Molecules, Combination Therapies, Gene Therapy End User: Hospitals, Specialty Clinics, Home Care Settings, Research Institutions Delivery Mode: Oral, Injectable, Inhalation, Infusion |
| Companies Covered | Boehringer Ingelheim International GmbH, F. Hoffmann-La Roche Ltd, Galapagos NV, United Therapeutics Corporation, FibroGen, Inc., Bristol-Myers Squibb Company, Cipla Inc., MediciNova, Inc., Vicore Pharma AB, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Idiopathic Pulmonary Fibrosis Treatment Market Strategic Shifts & Innovations
Antifibrotic therapy development is pivoting from monotherapy maintenance toward mechanistic combination approaches that target multiple fibrotic pathway nodes simultaneously.
Multiplex biomarker platforms integrating serum protein signatures with high-resolution CT quantification are unifying diagnostic and prognostic workflows. Pulmonology departments at Charité Berlin and Brompton London are deploying these systems to compress time-to-treatment initiation. The technology is unifying previously separate radiology, pathology, and clinical assessment silos into single-decision protocols that accelerate patient stratification.
EU MDR Article 10 post-market surveillance requirements are mandating systematic collection of device-related adverse events across combination products. Manufacturers must now integrate pharmacovigilance with medical device incident reporting, doubling regulatory compliance overhead. German notified bodies are prioritizing audits of inhaled delivery systems paired with oral antifibrotics, creating certification bottlenecks for portfolio extensions.
Specialist pharmacy channels are displacing traditional hospital dispensing for oral antifibrotics in France and the Netherlands. Home delivery models with embedded nurse education are capturing patient adherence monitoring functions previously managed through outpatient pulmonology visits. This channel rotation is most visible in Paris and Amsterdam metropolitan areas where regional health agencies have authorized third-party logistics providers for controlled-temperature distribution.
Europe Idiopathic Pulmonary Fibrosis Treatment Market Segmentation
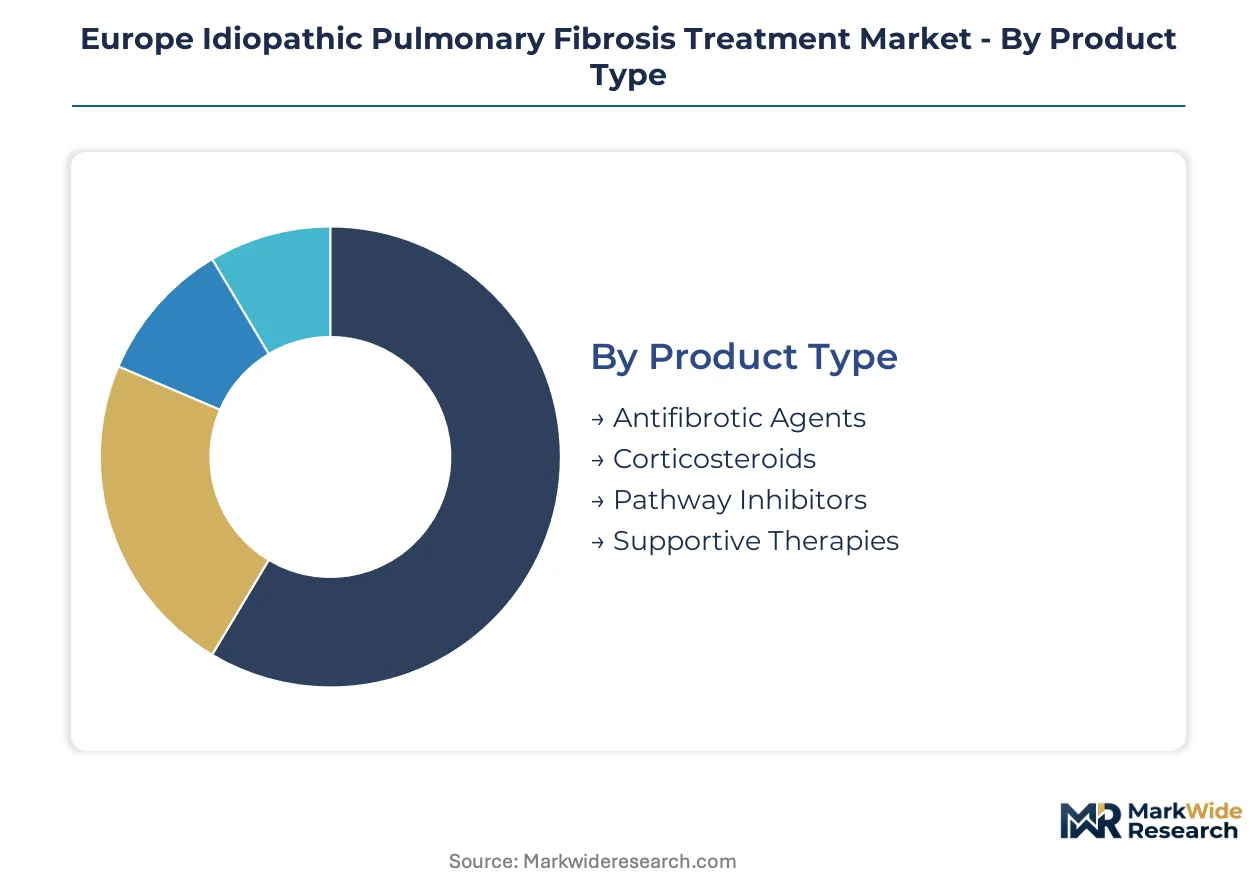
Segmentation in the Europe IPF treatment market reveals how therapeutic value flows through distinct technical and channel configurations. Product type and technology choices determine reimbursement positioning, while end-user and delivery mode selections shape patient adherence economics.
Product Type:
Standardization dominates antifibrotic agents, while corticosteroid protocols retain customization through tapering regimens.
- Antifibrotic Agents:Oral nintedanib and pirfenidone formulations constitute the clinical backbone, with established EMA orphan drug status securing reimbursement across Germany, France, and Italy. Tertiary respiratory centers in Berlin, Paris, and Milan concentrate procurement volume through centralized formularies that favor proven efficacy profiles over novel mechanisms.
- Corticosteroids:Prednisone and methylprednisolone regimens address acute exacerbation management rather than disease modification. Demand clusters in Spanish and Italian hospitals where diagnostic latency leaves larger untreated inflammatory burdens.
- Pathway Inhibitors:Emerging JAK and tyrosine kinase inhibitors target mechanistic nodes beyond TGF-beta pathways. Clinical trials at Charité Berlin and Brompton London are validating biomarker-guided patient stratification for these agents.
- Supportive Therapies:Oxygen supplementation, pulmonary rehabilitation, and palliative care bundles manage symptom burden without altering fibrotic progression. Home care networks in the Netherlands and Belgium are integrating these services with oral antifibrotic delivery.
Most installed capacity flows through Antifibrotic Agents. Expansion is steepest in Pathway Inhibitors.
Technology:
Cost tiers separate mature small molecules from premium-priced biologics and developmental gene therapies.
- Biologics:Monoclonal antibodies targeting CTGF, IL-13, and integrin pathways represent the technology frontier. EMA's conditional approval frameworks are accelerating access timelines for these agents in progressive fibrosing interstitial lung disease extensions.
- Small Molecules:Nintedanib and pirfenidone maintain manufacturing scale advantages through established European contract synthesis networks. IQWiG and NICE assessments favor these agents for incremental cost-effectiveness benchmarks.
- Combination Therapies:Bundled antifibrotic and immunomodulatory protocols are gaining traction in French and German specialist centers. Real-world evidence requirements under EU MDR Article 97 are shaping post-authorization study designs.
- Gene Therapy:AAV-delivered antifibrotic constructs remain preclinical or early-phase, with manufacturing complexity limiting European trial activation to select academic medical centers.
Volume concentrates in Small Molecules. Biologics are gaining share fastest through orphan exclusivity incentives.
End User:
Customer type determines service intensity, with hospitals managing complexity and home settings capturing adherence monitoring.
- Hospitals:Tertiary pulmonology departments at Heidelberg, Pavia, and Barcelona coordinate multidisciplinary diagnostic confirmation and treatment initiation. Centralized infusion protocols and transplant evaluation pathways anchor patient flow.
- Specialty Clinics:Interstitial lung disease centers in London, Amsterdam, and Vienna deliver focused outpatient management with embedded clinical trial access. Nurse coordinator staffing limits expansion in Italian and Spanish markets.
- Home Care Settings:Third-party logistics providers in France and the Netherlands now handle controlled-temperature distribution with embedded patient education. Regional health agencies in Paris and Amsterdam metropolitan areas authorized this channel rotation.
- Research Institutions:Academic medical centers at Charité Berlin, Brompton London, and Karolinska Stockholm conduct biomarker validation and mechanistic combination studies. EMA's EU MDR framework intensifies clinical evidence requirements for these collaborations.
Patient volume flows predominantly through Hospitals. Home Care Settings are expanding most quickly through specialist pharmacy channel displacement.
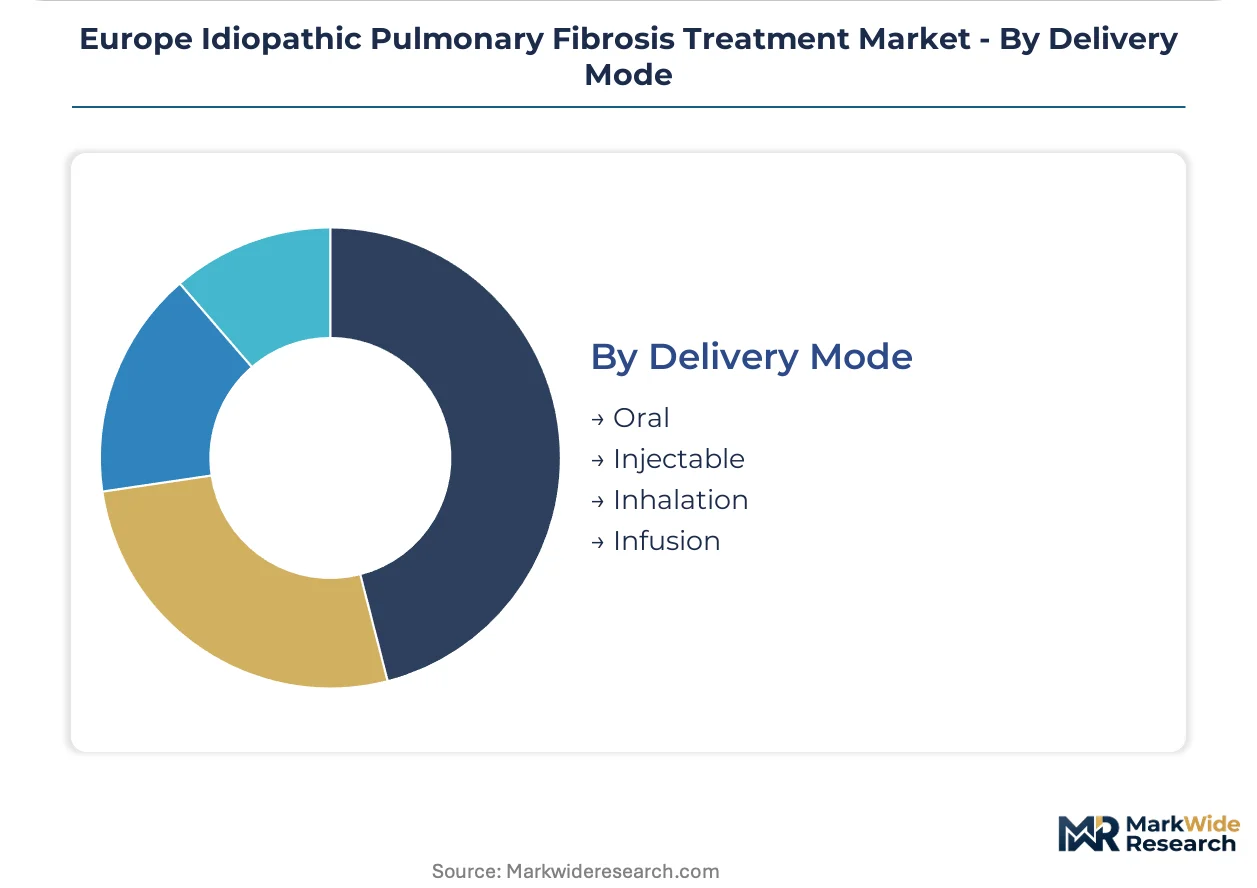
Delivery Mode:
Maturity gradients separate established oral administration from developmental inhalation and gene therapy infusion platforms.
- Oral:Twice-daily nintedanib and thrice-daily pirfenidone capsules dominate maintenance therapy. German and British health technology assessments prioritize these modalities for cost-effectiveness thresholds.
- Injectable:Subcutaneous biologics in development for progressive fibrosing interstitial lung disease require cold-chain infrastructure that concentrates trial activation in Northern European centers.
- Inhalation:Dry powder and nebulized antifibrotic formulations target localized lung delivery with reduced systemic exposure. EU MDR technical documentation burdens are delaying notified body certification for device-drug combinations.
- Infusion:Intravenous monoclonal antibodies and gene therapy constructs demand hospital-based administration with cardiac monitoring protocols. Capacity constraints at tertiary centers limit throughput.
Oral delivery commands the largest installed base. Inhalation platforms are climbing the fastest through pulmonary targeting advantages.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Idiopathic pulmonary fibrosis therapeutics first achieved commercial scale in Germany during the mid-2000s, when nintedanib and pirfenidone secured EMA orphan drug designation. The clinical infrastructure established at Heidelberg and Munich tertiary centers subsequently diffused across Western Europe. Today, procurement patterns concentrate in Germany, France, Italy, the United Kingdom, and Spain.
Germany
Tertiary respiratory centers at Charité Berlin and Heidelberg University Hospital anchor antifibrotic procurement volume through centralized formularies. IQWiG assessments enforce incremental cost-effectiveness thresholds that shape pricing negotiations for established therapies. Bavaria's medical device corridor supplies diagnostic imaging systems that compress time-to-treatment initiation.
France
Paris metropolitan pulmonology departments deploy specialist pharmacy channels with embedded nurse education for home delivery models. ANSM pharmacovigilance requirements mandate systematic adverse event reporting across device-drug combinations. Lyon and Marseille academic centers coordinate S4A rare disease network participation for cross-border patient continuity.
Italy
Pavia and Milan interstitial lung disease centers face nursing coordinator recruitment gaps that constrain antifibrotic monitoring protocol expansion. AIFA reimbursement frameworks prioritize proven efficacy profiles over novel mechanisms in regional formulary decisions. The Po Valley industrial cluster manufactures active pharmaceutical ingredients for European contract synthesis networks.
United Kingdom
Brompton London and Manchester tertiary centers validate biomarker-guided patient stratification for mechanistic combination protocols. NICE technology appraisals demand real-world evidence generation under conditional reimbursement pathways. The Southeast England research corridor integrates pharmacovigilance with medical device incident reporting for combination products.
Spain
Barcelona and Madrid hospitals manage larger untreated inflammatory burdens due to diagnostic latency in regional healthcare systems. AEMPS orphan drug frameworks accelerate access timelines for novel IPF compounds. The Catalonia biotech cluster supports early-phase clinical trial activation for JAK inhibitor combinations.
Europe Idiopathic Pulmonary Fibrosis Treatment Market Key Industry Players
Premium-margin players sit above commodity-margin players across evidence-generation capabilities and specialist channel control. The vendor base concentrates around three multinational pharmaceutical groups with established EMA orphan drug franchises, supplemented by mid-cap biotechnology firms pursuing mechanistic differentiation. Two strategic archetypes dominate: integrated respiratory specialists with pulmonology department relationships, and platform-technology developers targeting fibrotic pathway nodes. Competitive moves center on real-world evidence generation for conditional reimbursement and JAK inhibitor combination protocol development.
Among Germany-based integrated respiratory specialists, Boehringer Ingelheim International GmbH exemplifies the established franchise archetype through its nintedanib portfolio. Swiss pharmaceutical group F. Hoffmann-La Roche Ltd occupies a comparable position in the antifibrotic maintenance tier. Belgium-based Galapagos NV represents the platform-technology vector, anchoring innovation positioning through selective kinase inhibition approaches. These three entities collectively illustrate how geographic origin and corporate structure map to competitive positioning in European orphan lung therapeutics.
| Leading Market Players |
|---|
| Boehringer Ingelheim International GmbH |
| F. Hoffmann-La Roche Ltd |
| Galapagos NV |
| United Therapeutics Corporation |
| FibroGen, Inc. |
| Bristol-Myers Squibb Company |
| Cipla Inc. |
| MediciNova, Inc. |
| Vicore Pharma AB |
| Others |
Cost & Logistics Intelligence
EU MDR sustainability mandates for medical device-drug combinations gate qualified supply access and premium-tier pricing power, forcing manufacturers to recertify legacy products before maintaining margin positions in German and French hospital formularies.
Pricing Analysis
Three-tier pricing structure across premium biologics, standard small molecules, and economy supportive therapies stratifies the European IPF market. Price differentiation rests on EMA orphan drug exclusivity status and IQWiG cost-effectiveness tiering, with biologics commanding substantial premiums over nintedanib and pirfenidone. Cost compression in the small-molecule tier is intensifying because NICE technology appraisals demand incremental evidence for maintenance therapy positioning. Academic medical centers exhibit lowest price sensitivity due to research funding buffers, while Eastern European regional formularies face acute budget constraints.
Supply Chain Analysis
Single-source vulnerability sits with Italian and Spanish contract manufacturers for pirfenidone active pharmaceutical intermediates. API synthesis draws from concentrated European chemical corridors in the Po Valley and Catalonia, with limited qualified alternatives for nintedanib precursor molecules. Supply chain risk centers on regulatory restriction as EU MDR notified body capacity bottlenecks delay device-drug combination recertification. Distribution runs through specialist pharmacy channels in France and the Netherlands, displacing traditional hospital dispensing for oral antifibrotics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in European IPF therapeutics hinges on biomarker-guided patient stratification enabling premium-tier biologic positioning and reduced small-molecule cost exposure through manufacturing scale efficiencies.
For Market Incumbents: To counter JAK inhibitor pipeline entrants from Belgian and Swiss biotechnology firms, Boehringer Ingelheim and Roche should deepen pulmonology department relationships through real-world evidence generation partnerships and secure backward integration into European API synthesis capacity to defend against supply disruption. IQWiG pricing pressure represents the primary threat requiring defensive evidence investment. For New Entrants and Emerging Players: Mechanistic combination protocols targeting progressive fibrosing interstitial lung disease extensions offer the most penetrable white space, with Poland and Hungary presenting nascent reimbursement environments favorable to first-mover biologic positioning. A biomarker-companion diagnostic bundling strategy unlocks specialist clinic access in Vienna and Amsterdam where diagnostic infrastructure concentrates. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap platform-technology developers with selective kinase inhibition assets pre-Phase III. Long-term viability framing favors acquisition targets with EU MDR-ready technical documentation and established EMA orphan drug designation. The signal to watch is conditional reimbursement pathway conversion rates under EU MDR Article 97 as inflection indicator for permanent market access security.| Strategic Initiative | Industry Significance |
|---|---|
| Real-World Evidence Generation | EMA Article 97 conditional reimbursement pathways demand post-authorization efficacy data from Charité Berlin and Brompton London centers. |
| JAK Inhibitor Combination Development | Mechanistic synergy with antifibrotic small molecules expands addressable patient pools in progressive fibrosing interstitial lung disease. |
| Specialist Pharmacy Channel Partnership | Paris and Amsterdam regional health agencies authorize third-party logistics for controlled-temperature antifibrotic distribution. |
| Biomarker Platform Integration | Multiplex serum protein signatures with high-resolution CT quantification compress time-to-treatment initiation at Heidelberg and Pavia. |
| Eastern European Market Development | Poland, Hungary, and Czech Republic exhibit rising IPF diagnosis rates with favorable first-mover reimbursement positioning. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with drug development executives, regulatory affairs leads, formulary directors at German tertiary centers, and payer access specialists with secondary validation through EMA submission databases, ClinicalTrials.gov records, IQWiG benefit assessments, and NICE technology appraisal documentation. Bottom-up patient flow modeling and top-down pharmaceutical revenue triangulation anchored market sizing.
Comparable-period anchoring linked historical antifibrotic prescription volumes to projected patient incidence across the analysis window. The analytical framework modeled treatment line, dosage form, administration route, and regional regulatory cluster segmentation dimensions. CAGRs derived from weighted average of epidemiological trend extrapolation and pricing scenario sensitivity testing, with inputs including diagnostic latency compression rates and biomarker adoption curves at academic medical centers.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU MDR implementation delays, IQWiG benefit assessment stringency shifts, and JAK inhibitor clinical trial readouts. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Global Neurotrophic Keratitis Treatment Market
Specialty Medicine
Thyroid Cancer Therapeutics Market
Specialty Medicine
Pleurisy Market
Specialty Medicine
Oral Cancer Treatment Market
Specialty Medicine
Primary Sclerosing Cholangitis (PSC) Market
Specialty Medicine
Chemotherapy Induced Peripheral Neuropathy Treatment Market
Specialty Medicine
Glucagon Therapy Market
Specialty Medicine
Cutaneous T-Cell Lymphoma (CTLC) Market
Specialty Medicine
Global Acute Agitation and Aggression Treatment Market
Specialty Medicine
Alcoholic Liver Diseases Treatment Market
Specialty Medicine
Glaucoma Market
Specialty Medicine
Chromoblastomycosis Treatment Market
Specialty Medicine
Global Post Traumatic Stress Disorder (PTSD) Therapeutics Market
Specialty Medicine
Respiratory Syncytial Virus (RSV) Therapeutics Market
Specialty Medicine
Central Pontine Myelinolysis Market
Specialty Medicine
Hemorrhagic Stroke Treatment Market