
 Diamond-Blackfan Anemia Syndrome Therapeutics Market | 2026-2036
Diamond-Blackfan Anemia Syndrome Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Diamond-Blackfan Anemia Syndrome Therapeutics Market Outlook
The FDA's orphan drug designation framework is realigning investment priorities toward rare hematologic conditions. Pfizer Inc leverages its established corticosteroid manufacturing infrastructure to sustain supply security for chronic pediatric protocols. Novartis anchors its position through specialized distribution channels serving academic medical centers. Amgen competes in erythropoiesis-stimulating agents through recombinant protein platforms optimized for transfusion-dependent patients.
Diamond-Blackfan Anemia syndrome therapeutics comprise pharmacologic and supportive interventions targeting ribosomal protein defects that impair erythroid progenitor maturation, with corticosteroids functioning as first-line agents to stimulate stress erythropoiesis in bone marrow microenvironments. Corticosteroids dominate initial therapy decisions across pediatric populations, while immunosuppressive therapy captures refractory cases where steroid tolerance limits long-term use. Erythropoiesis-stimulating agents represent the fastest-growing segment as biosimilar competition expands access in outpatient settings.
The FDA, EMA, and national health technology assessment bodies shape market access through orphan exclusivity periods, pediatric investigation plans, and value-based reimbursement thresholds for chronic transfusion alternatives. The EMA's priority medicines scheme accelerates centralized marketing authorization for therapies addressing unmet needs in ultra-rare anemias. Stakeholders must monitor evolving biomarker-defined patient stratification approaches that promise to reshape trial enrollment criteria and post-market evidence requirements.
Market Dynamics
FDA orphan drug exclusivity periods are compressing development timelines for rare hematology indications, while pediatric investigation plans reshape clinical trial design for infant corticosteroid protocols.
Growth Catalysts
- EMA Priority Medicines Scheme:Centralized marketing authorization acceleration for ultra-rare anemia therapies reduces time-to-market for novel erythropoiesis-stimulating agents.
- NIH-Funded Research Consortia:Coordinated multi-center data sharing improves biomarker-defined patient stratification and expands eligible trial populations.
- Academic Medical Center Networks:Specialized pediatric hematology-oncology centers standardize corticosteroid-first protocols, creating predictable demand baselines for chronic therapy supply.
Market Restraints
- Biosimilar Manufacturing Concentration:Recombinant protein production capacity clusters in contract manufacturing organizations with limited GMP-certified sites for erythropoietin analogs.
- Pediatric Investigation Plan Burden:EMA-mandated PIP requirements extend pre-approval timelines for therapies lacking adult comparator indications.
- Chronic Transfusion Dependency:Iron chelation therapy substitutes reduce addressable patient pool for pharmacologic erythropoiesis stimulation in refractory cases.
Strategic Opportunities
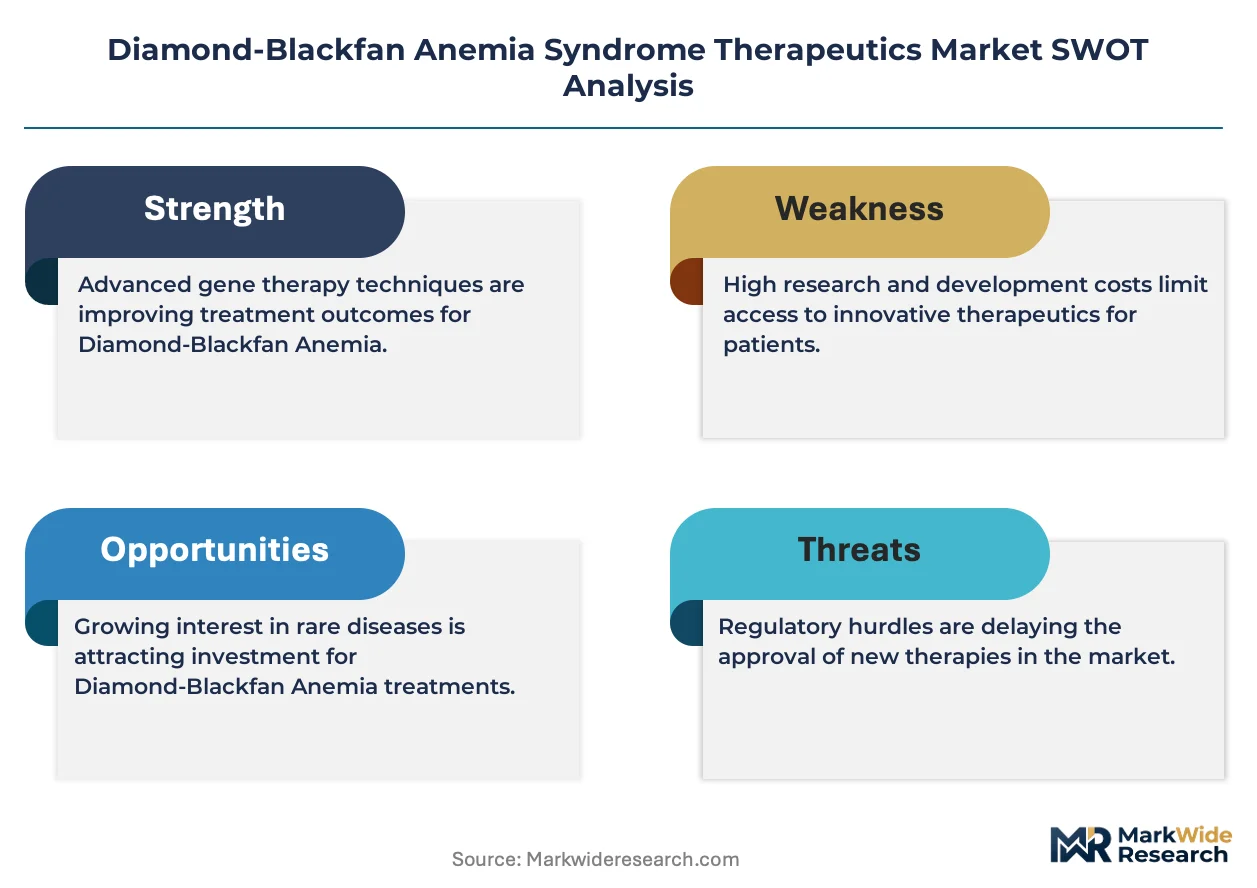
- Gene Therapy Convergence:CRISPR-based ribosomal protein correction combined with lentiviral delivery platforms opens curative intervention pathways beyond chronic management.
- Outpatient Infusion Centers:Hospital-at-home programs create alternative administration channels for erythropoiesis-stimulating agents, reducing academic medical center capacity constraints.
- US Orphan Drug Exclusivity:Seven-year market protection windows incentivize development of corticosteroid-sparing alternatives for steroid-intolerant pediatric populations.
Industry Challenges
- Pediatric Trial Enrollment:Ultra-rare disease prevalence limits site activation and patient recruitment velocity across multi-regional protocols.
- Biomarker Validation:Ribosomal protein mutation heterogeneity complicates companion diagnostic development and regulatory qualification pathways.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Diamond-Blackfan Anemia Syndrome Therapeutics Market |
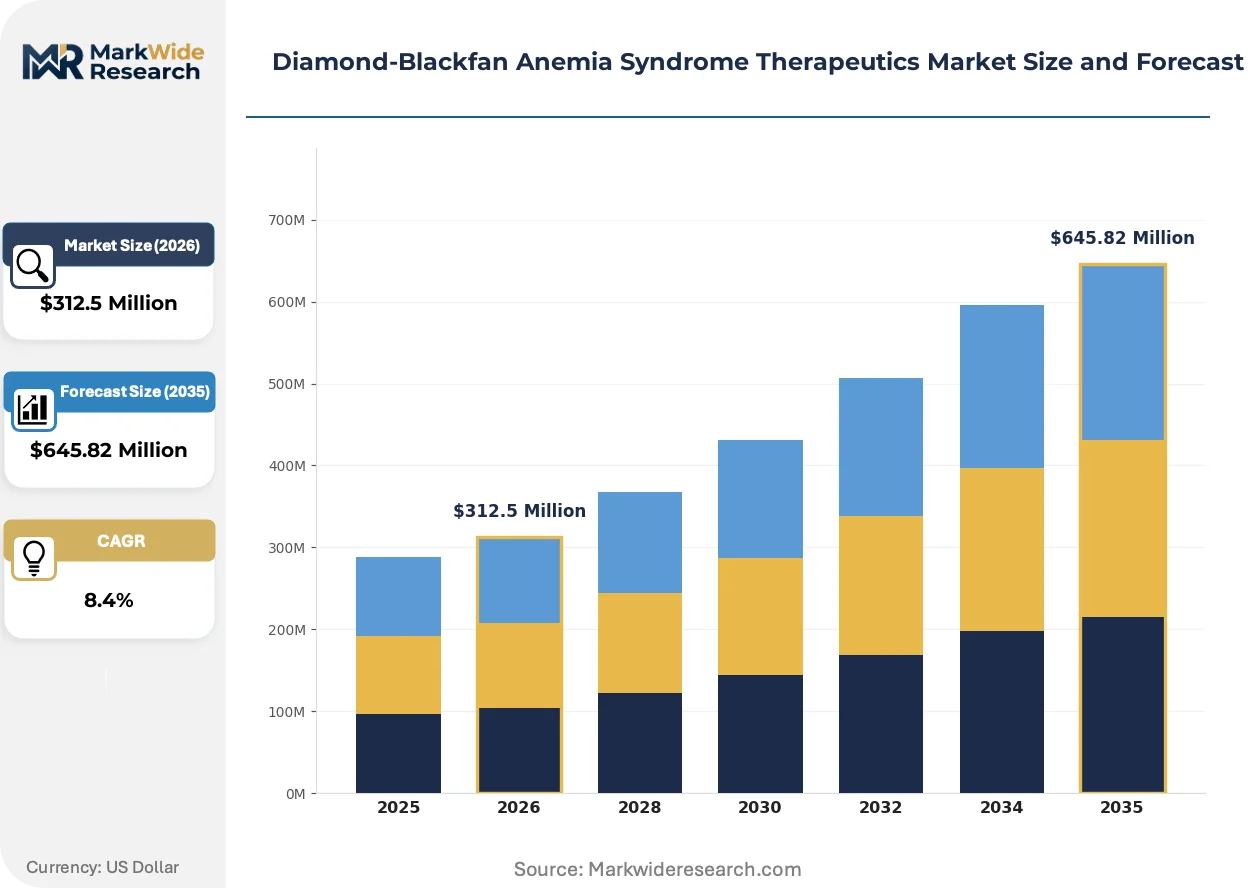
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $645.82 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Therapy Type: Corticosteroids, Immunosuppressive Therapy, Erythropoiesis-Stimulating Agents, Blood Transfusions Patient Age Group: Children, Adolescents, Adults, Infants Administration Route: Oral, Intravenous, Subcutaneous, Intramuscular Treatment Setting: Outpatient, Inpatient, Home Care, Specialized Clinics |
| Companies Covered | Pfizer Inc, Novartis, Amgen, Bristol Myers Squibb, Sanofi, Roche, Cipla Ltd, Takeda, NIKSAN PHARMACEUTICAL, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Diamond-Blackfan Anemia Syndrome Therapeutics Market Strategic Shifts
Biomarker-driven trial design is fragmenting the traditional one-size-fits-all corticosteroid approach, while regulatory incentives pull investment toward transfusion-sparing modalities.
Next-generation sequencing panels for ribosomal protein gene mutations are modularizing patient stratification in clinical development. Pediatric hematology centers deploy these platforms to identify corticosteroid-responsive genotypes before initiating therapy. This technology is modularizing trial eligibility criteria and compressing enrollment timelines for targeted interventions.
EMA's priority medicines scheme is accelerating centralized authorization timelines for therapies addressing unmet needs in ultra-rare anemias. Biopharmaceutical developers reallocate regulatory resources toward PRIME designation applications. Erythropoiesis-stimulating agent developers in the European Union prioritize this pathway over national reimbursement negotiations.
Academic medical centers are unbundling chronic transfusion services from inpatient admissions. Hospital-at-home programs now coordinate iron monitoring and chelation therapy in residential settings. This operational shift is most visible in United States pediatric networks with established home-infusion infrastructure.
Diamond-Blackfan Anemia Syndrome Therapeutics Market Segmentation
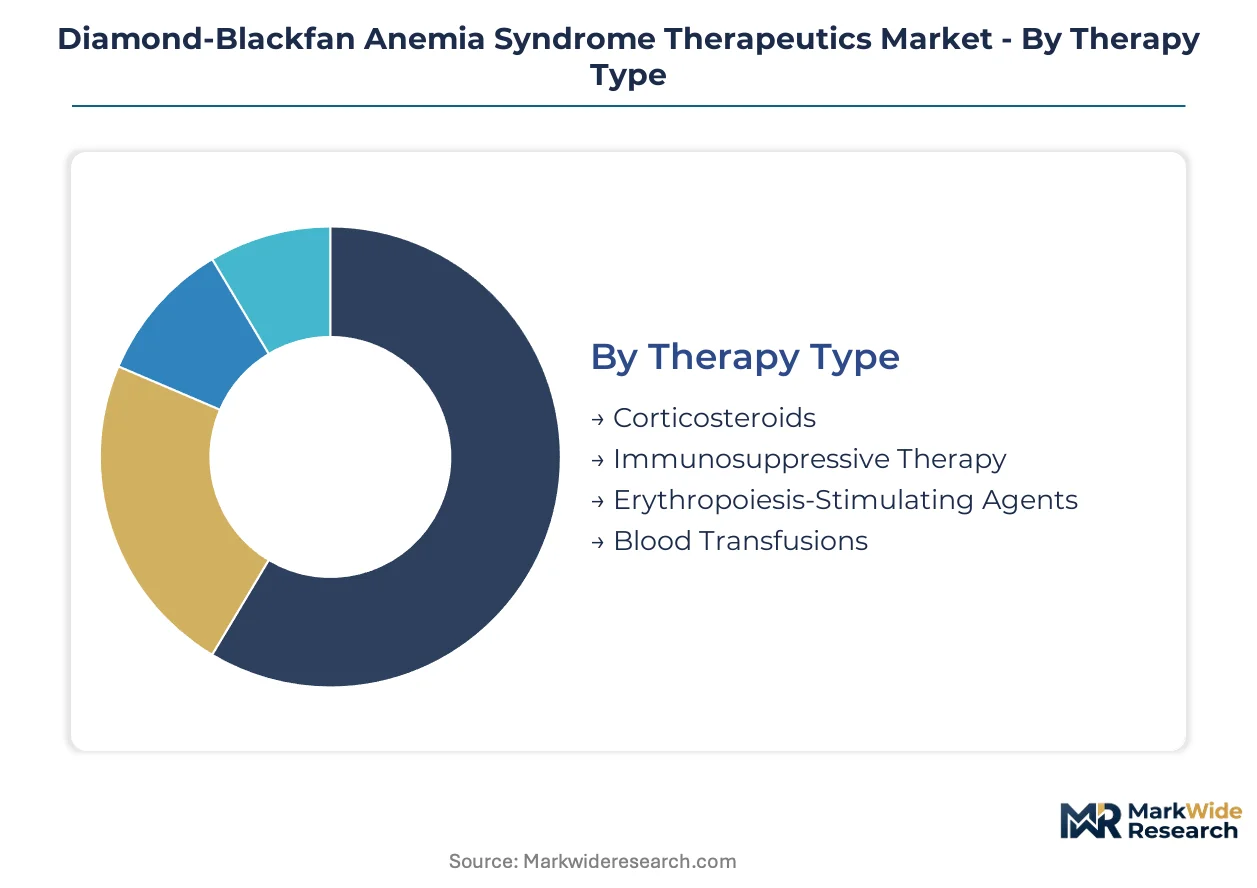
Diamond-Blackfan Anemia syndrome therapeutics fragment across therapy mechanisms, patient demographics, and care delivery models. Supply concentration in recombinant protein manufacturing and corticosteroid API production shapes competitive positioning within each segment tier.
Therapy Type:
Active pharmaceutical ingredient sourcing clusters in specialized manufacturing networks with GMP-certified capacity for pediatric-grade formulations.
- Corticosteroids:Synthetic glucocorticoid formulations, primarily prednisone and prednisolone derivatives, modulate erythroid progenitor stress response in ribosomal protein-deficient bone marrow microenvironments. Demand concentrates in United States pediatric hematology-oncology centers where NIH-funded consortia standardize first-line protocols for infant patients. Chronic corticosteroid exposure drives steroid-sparing development priorities.
- Erythropoiesis-Stimulating Agents:Recombinant erythropoietin analogs and biosimilars stimulate erythroid colony formation in transfusion-dependent patients with refractory steroid responses. Subcutaneous administration in outpatient settings expands fastest as hospital-at-home programs reduce academic medical center capacity constraints. Biosimilar competition compresses pricing while expanding geographic access.
- Immunosuppressive Therapy:Cyclosporine and tacrolimus regimens target T-cell mediated erythroid suppression in corticosteroid-intolerant pediatric populations.
- Blood Transfusions:Leukoreduced packed red blood cell units provide immediate hemoglobin support in acute anemia crises or pre-surgical stabilization.
Today's leader: Corticosteroids. Tomorrow's challenger: Erythropoiesis-Stimulating Agents.
Patient Age Group:
Clinical trial enrollment and dosing protocols diverge sharply across developmental stages with distinct pharmacokinetic profiles and toxicity thresholds.
- Infants:Patients under 12 months present the most severe transfusion-dependent phenotypes requiring immediate corticosteroid initiation or chronic transfusion programs. United States specialized treatment networks concentrate diagnostic expertise and longitudinal care coordination for this ultra-rare neonatal population.
- Children:Ages 1-12 years represent the core steroid-responsive population where sustained remission rates determine long-term transfusion independence. Growth trajectory monitoring and bone density preservation dominate therapeutic decision-making in this segment.
- Adolescents:Pubertal development complications and treatment adherence challenges characterize this transitional care population.
- Adults:Late-onset DBA presentations and secondary malignancy surveillance requirements define management complexity in this smallest segment.
Infants command the highest per-patient resource intensity. Children offer the largest addressable volume for chronic therapy optimization.
Administration Route:
Formulation development investments track toward patient-administered alternatives that reduce hospital dependency and improve quality-of-life metrics.
- Oral:Corticosteroid tablets and liquid suspensions enable home-based chronic administration with dose-tapering flexibility for pediatric patients. Palatability engineering and compliance packaging address adherence barriers in young children.
- Subcutaneous:Erythropoiesis-stimulating agent pen devices and pre-filled syringes support caregiver-administered home therapy with reduced injection pain versus intravenous alternatives.
- Intravenous:Hospital-based iron chelation and acute transfusion protocols maintain inpatient infrastructure dependency.
- Intramuscular:Depot corticosteroid formulations provide extended-release options for patients with erratic oral absorption or severe compliance limitations.
Oral dominates corticosteroid volume. Subcutaneous is gaining share fastest among erythropoiesis-stimulating modalities.
Treatment Setting:
Care delivery decentralization is redistributing patient encounters from tertiary academic centers toward community-accessible and residential alternatives.
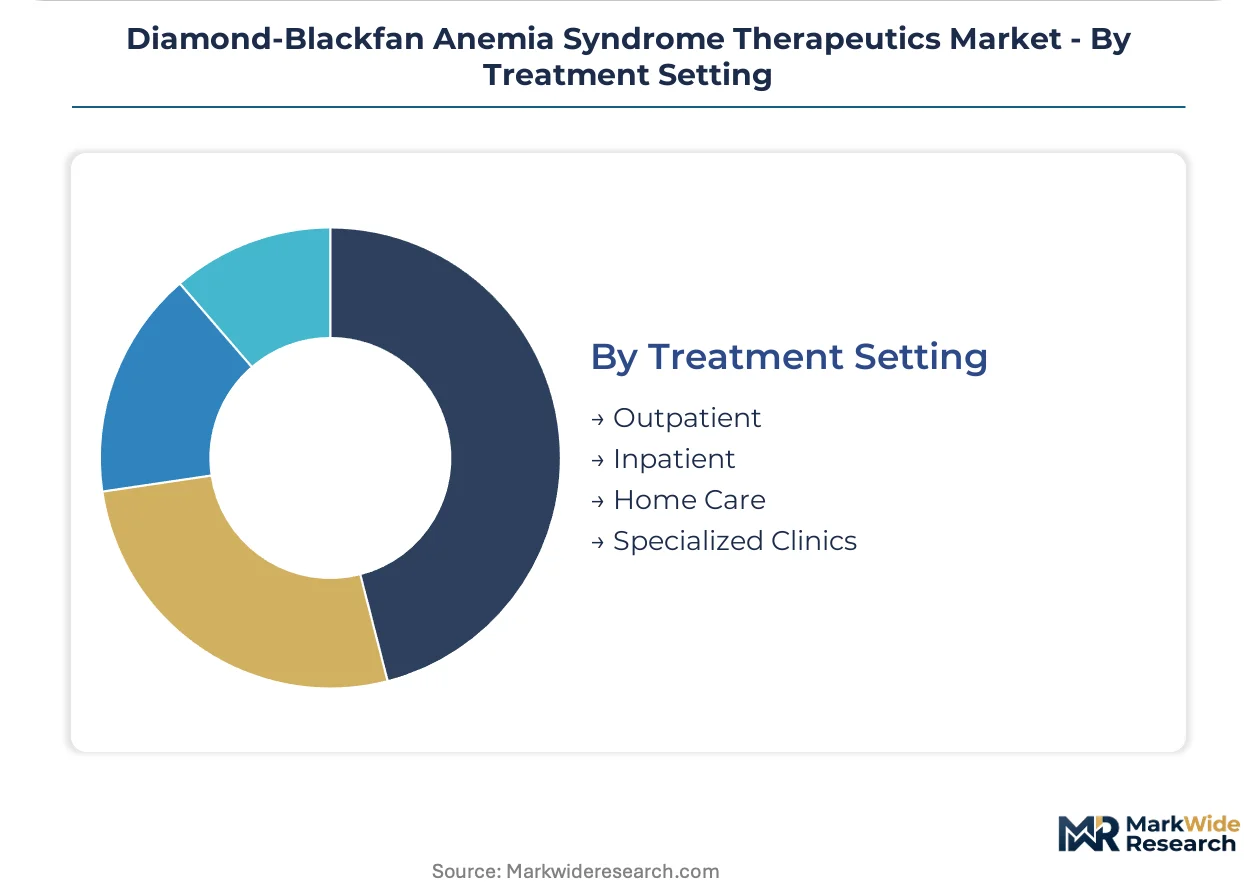
- Specialized Clinics:Pediatric hematology-oncology centers coordinate multidisciplinary care with genetics, cardiology, and endocrinology integration for complex DBA phenotypes. United States networks with NIH research consortium participation anchor clinical trial access and novel therapy availability.
- Outpatient:Ambulatory infusion centers and hospital-based clinics handle routine erythropoiesis-stimulating agent administration and transfusion monitoring.
- Home Care:Skilled nursing services and family caregiver training programs enable subcutaneous therapy and transfusion-independent monitoring in residential settings.
- Inpatient:Acute hemodynamic instability, surgical preparation, and iron chelation complications retain hospital admission requirements.
Specialized clinics anchor complex case management. Home care represents the steepest expansion trajectory as reimbursement frameworks adapt.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Diamond-Blackfan Anemia syndrome therapeutics originated in North American academic medical centers during the mid-20th century, with corticosteroid protocols first systematized at Boston Children's Hospital and Memorial Sloan Kettering. NIH-funded research consortia subsequently anchored therapeutic innovation in specialized pediatric networks across multiple countries.
United States
Pediatric hematology-oncology centers at Boston Children's Hospital and Cincinnati Children's Hospital Medical Center anchor the highest patient volumes globally. FDA orphan drug exclusivity periods accelerate clinical trial timelines for rare disease therapies. The Dana-Farber/Boston Children's Cancer and Blood Disorders Center coordinates multi-site biomarker research with pharmaceutical sponsors.
Germany
University hospitals in Heidelberg and Hamburg maintain Europe's largest DBA patient registries with longitudinal treatment outcome databases. EMA priority medicines scheme applications from German sponsors receive centralized marketing authorization support. The German Society for Pediatric Oncology and Hematology standardizes corticosteroid-first protocols across 37 specialized treatment centers.
United Kingdom
Great Ormond Street Hospital and Birmingham Children's Hospital concentrate diagnostic expertise for ultra-rare neonatal presentations. NICE technology appraisals determine reimbursement thresholds for erythropoiesis-stimulating agents in pediatric settings. The NHS England Highly Specialised Services program funds centralized transfusion coordination for complex DBA phenotypes.
Japan
PMDA sakigake designation pathway accelerates review timelines for pediatric hematology innovations from domestic sponsors. National Center for Child Health and Development in Tokyo coordinates Asia-Pacific clinical trial site activation. Japanese pharmaceutical companies prioritize biosimilar erythropoietin development for transfusion-dependent populations.
Switzerland
Swissmedic pediatric investigation plan requirements align with EMA standards while offering streamlined parallel consultation procedures. University Hospital Zurich maintains ribosomal protein mutation reference laboratories serving central European diagnostic networks. Roche's Basel headquarters anchors regional distribution infrastructure for recombinant protein therapeutics.
Diamond-Blackfan Anemia Syndrome Therapeutics Market Competitive Environment
Premium-margin players sit above commodity-margin players across therapy innovation intensity, with gene therapy developers commanding valuation multiples above established corticosteroid suppliers. The market structures around three tiers: multinational pharmaceutical conglomerates with rare disease divisions, specialized hematology biotechs, and generic API manufacturers. Consolidation pressure concentrates among biosimilar producers seeking GMP-certified recombinant protein capacity. Strategic moves center on orphan drug designation acquisitions and pediatric investigation plan partnerships with academic medical centers.
Within the multinational tier, Pfizer Inc and Novartis occupy positions shaped by established corticosteroid manufacturing infrastructure and specialized distribution channels respectively. Amgen exemplifies the biologic-focused archetype through recombinant protein platform investments. These three companies represent distinct competitive vectors: legacy small-molecule scale, integrated rare disease commercialization, and biosimilar market expansion.
| Leading Market Players |
|---|
| Pfizer Inc |
| Novartis |
| Amgen |
| Bristol Myers Squibb |
| Sanofi |
| Roche |
| Cipla Ltd |
| Takeda |
| NIKSAN PHARMACEUTICAL |
| Others |
Value Chain & Pricing Dynamics
Pediatric hematology-oncology centers in the United States concentrate purchasing power for corticosteroid-first protocols, anchoring a value-based pricing model where clinical outcomes determine reimbursement thresholds for chronic therapy regimens.
Pricing Analysis
Three-tier pricing structure across originator biologics, biosimilars, and generic corticosteroids stratifies the market by manufacturing complexity and regulatory exclusivity. Price differentiation hinges on FDA orphan drug designation status and GMP certification tier for pediatric-grade formulations. Cost compression in erythropoiesis-stimulating agents intensifies as biosimilar entrants multiply, while corticosteroid segments show pricing stability. Academic medical centers exhibit highest price sensitivity due to bundled reimbursement constraints; specialized clinics with NIH consortium participation demonstrate lowest sensitivity due to research funding offsets.
Supply Chain Analysis
Specialized workforce availability for recombinant protein production clusters in Switzerland, Germany, and the United States, constraining GMP-certified capacity expansion for erythropoiesis-stimulating agents. Active pharmaceutical ingredient sourcing draws from Indian and Chinese contract manufacturing organizations for corticosteroid precursors. Single-source vulnerability pervades lentiviral vector production for emerging gene therapies. Distribution runs through cold-chain logistics networks serving academic medical centers with validated temperature monitoring.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in Diamond-Blackfan Anemia therapeutics rests on biosimilar cost-down trajectories in erythropoiesis-stimulating agents and premium-tier pricing for corticosteroid-sparing alternatives in steroid-intolerant pediatric populations.
For Market Incumbents: Anchor market position through backward integration into recombinant protein manufacturing capacity and exclusive distribution partnerships with NIH-funded pediatric hematology consortia. Gene therapy developers threaten long-term corticosteroid volume; defend through biomarker-driven patient stratification investments that preserve eligible populations for chronic pharmacologic management. For New Entrants and Emerging Players: Capture white-space opportunity in outpatient infusion center networks and hospital-at-home program partnerships for subcutaneous erythropoiesis-stimulating agent administration. The most penetrable segment lies in community-accessible care settings underserved by academic medical center concentration; pursue go-to-market alignment with pediatric home health nursing franchises. For Investors and Strategic Acquirers: Rare disease divisions of multinational pharmaceutical conglomerates represent the most active acquirer category in this space, prioritizing gene therapy platforms and companion diagnostic capabilities. Long-term viability over a multi-year horizon favors developers with curative intervention pipelines beyond chronic management. Watch EMA priority medicines scheme designation velocity as inflection indicator for regulatory risk-adjusted returns.| Strategic Initiative | Industry Significance |
|---|---|
| Orphan Drug Designation Acquisition | FDA seven-year exclusivity windows protect corticosteroid-sparing alternatives from immediate biosimilar erosion. |
| Pediatric Investigation Plan Partnership | EMA-mandated PIP requirements with academic medical centers compress pre-approval timelines for infant-focused protocols. |
| Gene Therapy Platform Licensing | CRISPR-based ribosomal protein correction technologies open curative pathways beyond chronic transfusion dependency. |
| Biosimilar Manufacturing Scale-Up | GMP-certified recombinant protein capacity expansion addresses supply concentration in Swiss and German production sites. |
| Hospital-at-Home Program Integration | Outpatient infusion center partnerships reduce academic medical center capacity constraints for subcutaneous administration. |
Study Parameters
Multiple input streams — clinical trial registry data, regulatory submission documents, and hospital procurement records — were reconciled through structured interviews with pediatric hematologists, regulatory affairs specialists at orphan drug developers, formulary directors at academic medical centers, and payer access managers at national health technology assessment bodies. Secondary validation drew from FDA orphan drug designation databases, EMA priority medicines scheme filings, ClinicalTrials.gov protocol records, and NIH research consortium publication archives. Bottom-up patient population estimates and top-down pharmaceutical revenue triangulation anchored market sizing.
Data-stream reconciliation across therapy mechanism, patient age group, administration route, and regional regulatory cluster dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from longitudinal treatment protocol adoption curves and biomarker-defined patient stratification trends. Forecast inputs incorporated corticosteroid response rate assumptions and transfusion dependency prevalence shifts.
Underlying measurement precision varies by segment; erythropoiesis-stimulating agent volume estimates carry tighter precision than gene therapy pipeline valuations due to commercial availability differentials. Forecasts reflect assumptions about regulatory approval timelines and biomarker validation progress. Material deviation in FDA orphan exclusivity period enforcement or EMA centralized authorization velocity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Ovarian Cysts Market
Specialty Medicine
Global Acquired Aplastic Anemia Market
Specialty Medicine
Kaposi Sarcoma Market
Specialty Medicine
Hypersensitivity Pneumonitis Market
Specialty Medicine
Cutaneous T-Cell Lymphoma (CTLC) Market
Specialty Medicine
Global Anal Fistula Treatment Market
Specialty Medicine
Neuromuscular Disorders Treatment Market
Specialty Medicine
United States Specialty Generics Market
Specialty Medicine
Autoimmune Hemolytic Anemia Therapeutics Market
Specialty Medicine
Cystic Fibrosis Therapeutics Market
Specialty Medicine
Global Photodynamic Therapy Market
Specialty Medicine
Lung Disease Therapeutics Market
Specialty Medicine
Global Female Sexual Dysfunction Treatment Market
Specialty Medicine
Aarskog Syndrome Treatment Market
Specialty Medicine
Chromoblastomycosis Treatment Market
Specialty Medicine
Global Hammertoe Market