
 Global Cryptococcosis Treatment Market | 2026-2036
Global Cryptococcosis Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cryptococcosis Treatment Market Foresight
The divergence between liposomal amphotericin B formulations and conventional amphotericin B deoxycholate is repositioning procurement economics across hospital formularies. Pfizer Inc. leverages its manufacturing scale to sustain supply reliability for liposomal products in high-burden regions. Gilead Sciences, Inc. anchors its position through flucytosine access programs that compete on total cost of care rather than unit price alone.
Cryptococcosis treatment encompasses pharmaceutical and biological interventions targeting Cryptococcus neoformans and Cryptococcus gattii infections, with amphotericin B requiring intravenous infusion at 0.7–1.0 mg/kg daily alongside flucytosine 100 mg/kg for induction therapy. Its primary purpose is reducing mortality from cryptococcal meningitis, the most common manifestation, through fungicidal cerebrospinal fluid clearance. Antifungal Agents dominate current revenue due to entrenched clinical protocols, while Immunotherapy represents the fastest-expanding category as monoclonal antibody adjuncts advance through development pipelines. HIV/AIDS Patients constitute the largest application segment, though Organ Transplant Recipients generate higher per-patient spending due to prolonged prophylactic regimens.
FDA approval pathways for antifungal therapies and WHO Essential Medicines List inclusion criteria shape product commercialization timelines and access eligibility across endemic countries. EMA orphan drug designations and South African Health Products Regulatory Authority registration requirements create layered compliance obligations for manufacturers. Stakeholders must monitor consolidation of national treatment guidelines and prequalification status to anticipate procurement shifts before tender cycles finalize.

Market Dynamics
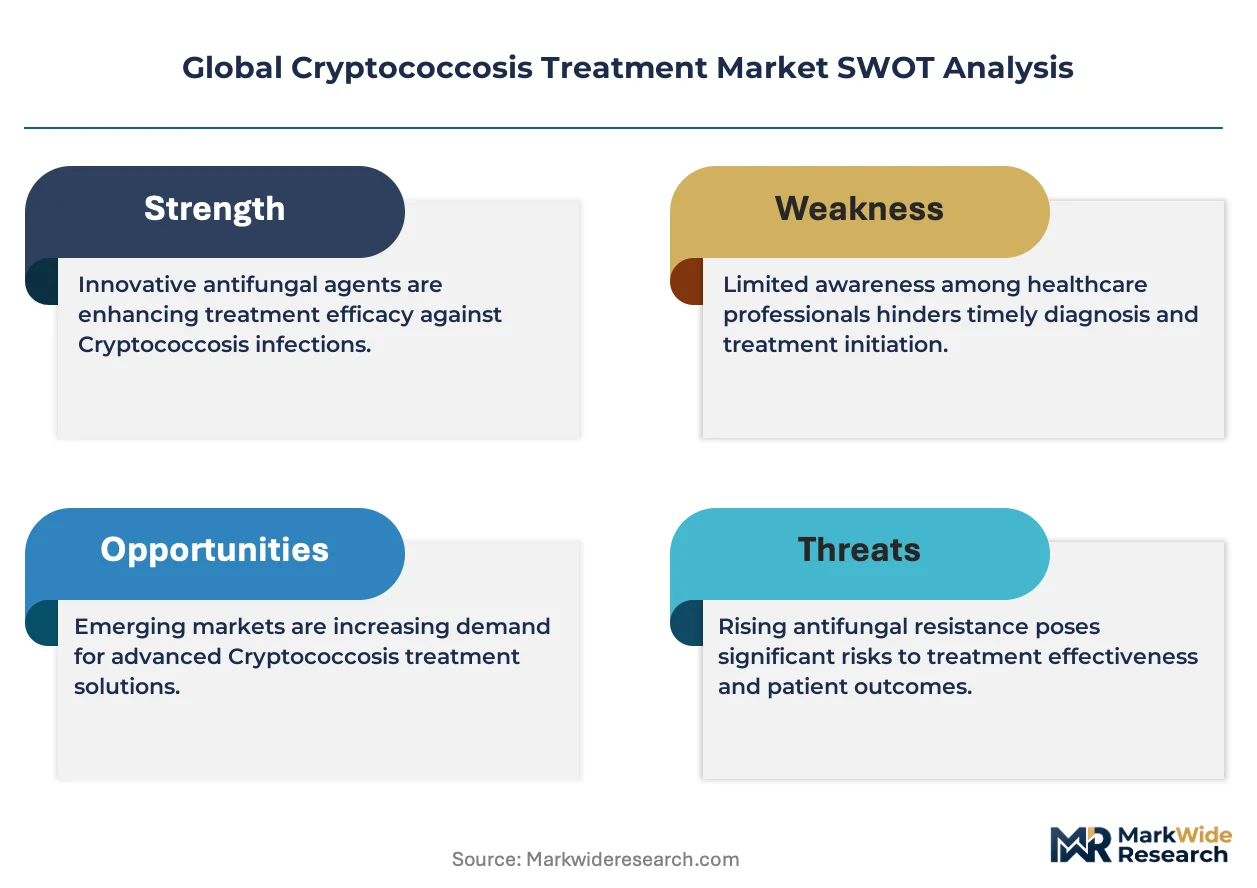
The divergence between liposomal amphotericin B and conventional amphotericin B deoxycholate formulations is compressing procurement economics across hospital formularies, forcing payers to weigh cerebrospinal fluid clearance efficacy against total cost of care in high-burden regions.
Growth Catalysts
- WHO Essential Medicines List inclusion:The 2022 revision prioritizing amphotericin B and flucytosine for cryptococcal meningitis is expanding procurement eligibility across sub-Saharan African national programs.
- HIV/AIDS patient concentration in South Africa:The country carries the world's largest antiretroviral therapy cohort, generating sustained clinical demand for induction-phase antifungal regimens.
- Immunotherapy pipeline advancement:Monoclonal antibody adjuncts targeting Cryptococcus neoformans polysaccharide capsule are accelerating through Phase II trials, creating new therapeutic categories.
Market Restraints
- Amphotericin B raw material concentration:Fermentation-derived polyene production clusters with a limited supplier base in Southern Europe, exposing formularies to batch consistency risk.
- Flucytosine manufacturing scarcity:The pyrimidine analog requires specialized chemical synthesis capacity that has consolidated among contract manufacturers in India and China.
- Cold chain requirements for liposomal formulations:Temperature-controlled distribution infrastructure gaps in rural Nigeria and eastern Democratic Republic of Congo limit formulary access.
Strategic Opportunities
- Point-of-care diagnostic expansion in Uganda:Lateral flow cryptococcal antigen testing at antiretroviral therapy initiation sites is creating pre-symptomatic treatment entry points.
- EMA orphan drug designation pathway:The incentive structure for neglected tropical diseases offers protocol assistance and market exclusivity extensions for novel antifungal combinations.
- Subscription-based access models:South Africa's national tender system is piloting volume guarantees that de-risk manufacturer supply commitments for flucytosine.
Industry Challenges
- Pharmacovigilance infrastructure gaps:Post-marketing surveillance for nephrotoxicity and electrolyte disturbances remains underdeveloped in high-burden countries, complicating risk-benefit communication.
- Formulary harmonization delays:Divergent national treatment guidelines between South Africa, Nigeria, and India create regulatory fragmentation for multinational registration strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cryptococcosis Treatment Market |
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $662.2 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antifungal Agents, Immunotherapy, Adjunctive Treatments, Vaccines Application: HIV/AIDS Patients, Organ Transplant Recipients, Cancer Patients, Immunocompromised Adults, Pediatric Cases End User: Hospitals, Specialty Clinics, Infectious Disease Centers, Research Institutes Delivery Mode: Oral Medication, Intravenous Therapy, Intrathecal Administration, Subcutaneous Injection |
| Companies Covered | Pfizer Inc., Gilead Sciences, Inc., Merck & Co., Inc., Bristol-Myers Squibb Company, Astellas Pharma Inc., Novartis AG, F. Hoffmann-La Roche Ltd, Glenmark Pharmaceuticals, Janssen Biotech, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cryptococcosis Treatment Market Shifts & Advancements
Technology convergence between antifungal pharmacology and host-directed immunomodulation is redefining therapeutic protocols. Three developments are compressing development timelines and reshaping competitive positioning across the value chain.
Monoclonal antibody adjuncts targeting the Cryptococcus polysaccharide capsule are expanding into combination regimens with standard-of-care amphotericin B. Academic medical centers in the United States and South Africa are enrolling patients in Phase II trials evaluating safety and cerebrospinal fluid penetration. This expansion is compressing the traditional antifungal development cycle and forcing incumbent manufacturers to reposition around combination therapy rather than monotherapy dominance.
EMA's 2023 revised orphan drug criteria for neglected tropical diseases now explicitly includes cryptococcal meningitis, streamlining protocol assistance and reducing regulatory fees for qualifying sponsors. The industrial consequence is accelerated dossier preparation for novel formulations targeting the HIV/AIDS patient segment. European manufacturers are responding by prioritizing liposomal amphotericin B line extensions over conventional deoxycholate submissions.
Hospital procurement committees in India are unbundling antifungal purchasing from bundled infectious disease contracts, creating direct manufacturer-to-formulary relationships. This disintermediation replaces distributor-mediated supply with tender-based volume commitments. The shift is most visible in Maharashtra and Karnataka state hospital systems, where centralized purchasing authorities now negotiate induction-phase regimen pricing separately from maintenance therapy.
Global Cryptococcosis Treatment Market Segmentation
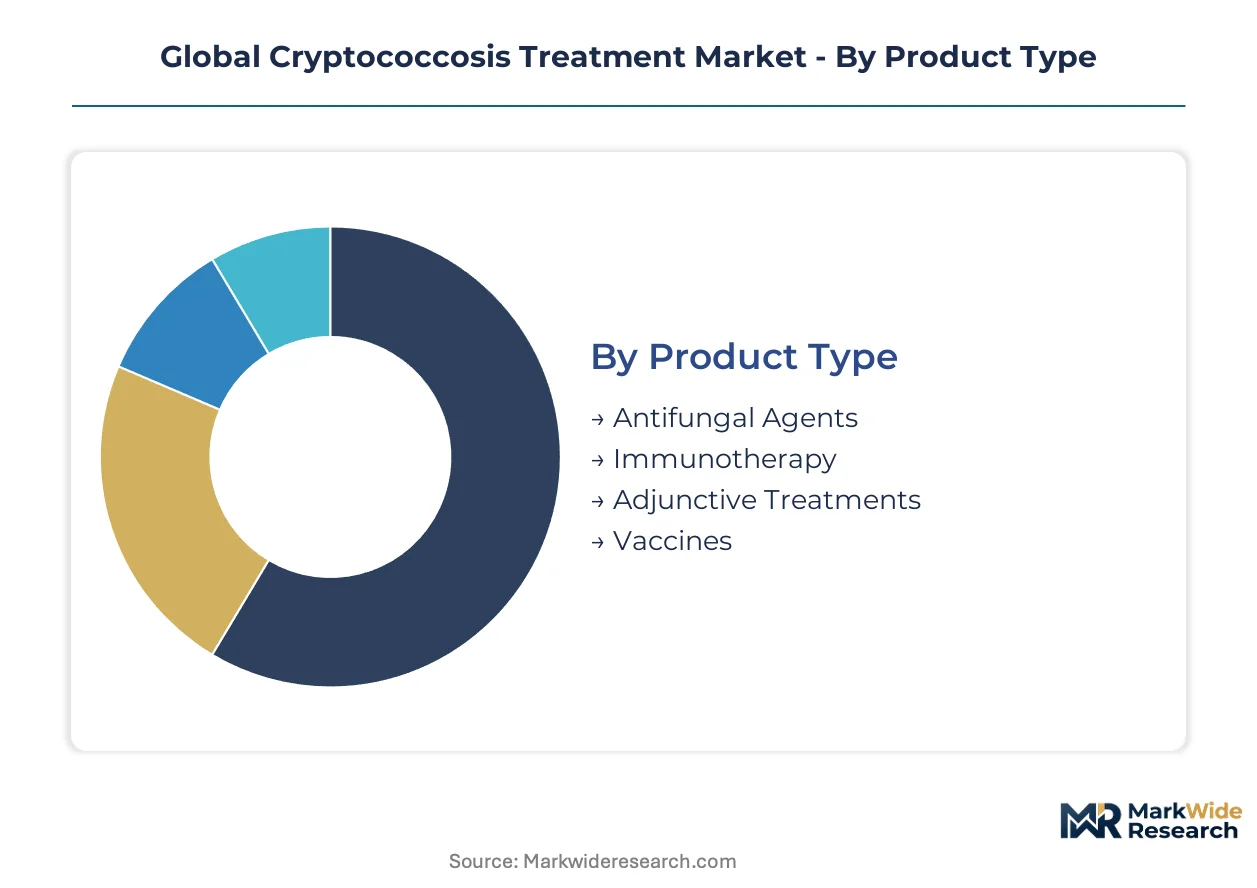
Segmentation in the cryptococcosis treatment market reveals distinct procurement patterns across therapeutic modalities and care settings. Hospital formularies prioritize induction-phase antifungal regimens while research institutes drive immunotherapy pipeline advancement.
Product Type:
Standardization dominates polyene antifungals while immunotherapy formats demand customization for combination protocols.
- Antifungal Agents:Amphotericin B formulations—liposomal and deoxycholate—deliver fungicidal cerebrospinal fluid clearance through intravenous infusion. Demand concentrates in South African public hospital networks where WHO guideline compliance drives procurement volume.
- Immunotherapy:Monoclonal antibody adjuncts targeting Cryptococcus polysaccharide capsule are advancing through Phase II trials. Expansion is steepest in United States academic medical centers pursuing combination therapy protocols.
- Adjunctive Treatments:Corticosteroid and electrolyte management protocols support nephrotoxicity mitigation during amphotericin B induction.
- Vaccines:Prophylactic candidates remain in early development with no commercialized products yet available.
Most installed capacity flows through Antifungal Agents. Expansion is steepest in Immunotherapy.
Application:
Volume scales with HIV/AIDS patient concentration while per-patient spending peaks in transplant populations requiring extended prophylaxis.
- HIV/AIDS Patients:The largest addressable population with cryptococcal meningitis as the leading AIDS-related mortality cause. Nigeria and India national programs generate sustained induction-phase demand.
- Organ Transplant Recipients:Prolonged antifungal prophylaxis drives the highest per-patient spending. Procurement concentrates in tertiary referral hospitals with dedicated transplant units.
- Cancer Patients:Chemotherapy-induced immunosuppression creates secondary cryptococcosis risk requiring targeted surveillance.
- Immunocompromised Adults:Broad category spanning autoimmune therapy recipients and primary immunodeficiency cases with heterogeneous treatment protocols.
- Pediatric Cases:Limited incidence with dosing challenges restricting dedicated formulation development.
Procurement volume concentrates in HIV/AIDS Patients. Revenue intensity peaks in Organ Transplant Recipients.
End User:
Centralized purchasing authority varies from national tender systems to institutional formularies.
- Hospitals:Primary site for induction-phase intravenous therapy and inpatient monitoring. South Africa's provincial health departments operate centralized antifungal procurement.
- Specialty Clinics:Outpatient maintenance therapy administration with fluconazole consolidation regimens.
- Infectious Disease Centers:Uganda's national referral network integrates point-of-care cryptococcal antigen testing with treatment initiation.
- Research Institutes:Clinical trial execution for novel combination therapies and immunotherapy candidates.
Product flow concentrates through Hospitals. Patient enrollment expansion is fastest in Infectious Disease Centers.
Delivery Mode:
Cold chain infrastructure requirements create geographic access disparities across administration routes.
- Intravenous Therapy:Liposomal amphotericin B requires temperature-controlled distribution with infusion center capability. Access gaps persist in rural Democratic Republic of Congo.
- Oral Medication:Fluconazole maintenance therapy enables outpatient continuation without cold chain dependency.
- Intrathecal Administration:Direct cerebrospinal fluid delivery for refractory cases with specialized neurosurgical requirements.
- Subcutaneous Injection:Emerging route for monoclonal antibody adjuncts in development pipelines.
Current utilization concentrates in Intravenous Therapy. Route diversification is advancing fastest in Subcutaneous Injection formats.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized infectious disease clinicians concentrate in South Africa's academic medical centers, while pharmaceutical manufacturing talent clusters in Western Europe and the Indian subcontinent. These workforce distributions shape regional treatment access and supply chain reliability.
South Africa
The world's largest antiretroviral therapy cohort generates sustained induction-phase demand for amphotericin B regimens. The South African Health Products Regulatory Authority maintains stringent registration requirements for liposomal formulations. Gauteng province's Johannesburg-Pretoria corridor anchors the national referral network where centralized provincial procurement operates.
India
Flucytosine manufacturing capacity concentrates among contract chemical synthesis specialists serving global formularies. The Central Drugs Standard Control Organization oversees import licensing for finished liposomal products. Maharashtra and Karnataka state hospital systems now unbundle antifungal purchasing from bundled infectious disease contracts.
United States
Academic medical centers enroll patients in Phase II monoclonal antibody combination trials. The FDA maintains approval pathways for novel antifungal therapies with expedited review for breakthrough designations. Boston and San Francisco research clusters advance immunotherapy pipeline candidates through investigator-sponsored studies.
Nigeria
Rural cold chain infrastructure gaps limit liposomal amphotericin B distribution to tertiary centers in Lagos and Abuja. WHO treatment guideline adoption through the national AIDS control program expands procurement eligibility for conventional amphotericin B. Point-of-care cryptococcal antigen testing scales through the infectious disease center network.
Germany
EMA orphan drug designation incentives attract dossier preparation for neglected tropical disease indications. REACH compliance obligations shape raw material sourcing for fermentation-derived polyene production. Baden-Württemberg's specialized chemical manufacturers supply intermediates for pyrimidine analog synthesis.
Global Cryptococcosis Treatment Market Competitive Landscape
Top-tier vendors anchor liposomal formulation supply, while mid-tier manufacturers concentrate on conventional amphotericin B deoxycholate and flucytosine synthesis. The competitive structure stratifies across research-intensive biopharmaceuticals, established antifungal specialists, and contract manufacturing organizations. Three archetypes dominate: vertically integrated innovators with manufacturing scale, regional formulation specialists with tender expertise, and research-stage immunotherapy developers. Capacity expansion and strategic partnerships represent the dominant competitive moves as players secure fermentation capacity and distribution networks.
Among research-intensive biopharmaceuticals, Pfizer Inc., Gilead Sciences, Inc., and Merck & Co., Inc. exemplify the integrated archetype combining manufacturing scale with access program infrastructure. Pfizer occupies a position as a supply reliability anchor for liposomal products in high-burden regions. Gilead exemplifies the total-cost-of-care competitive vector through flucytosine access initiatives. Merck represents the diversified pharmaceutical model with antifungal assets embedded within broader infectious disease portfolios.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Gilead Sciences, Inc. |
| Merck & Co., Inc. |
| Bristol-Myers Squibb Company |
| Astellas Pharma Inc. |
| Novartis AG |
| F. Hoffmann-La Roche Ltd |
| Glenmark Pharmaceuticals |
| Janssen Biotech, Inc. |
| Others |
Supply & Pricing Matrix
WHO guideline adoption across sub-Saharan African national programs is compressing procurement timelines and forcing suppliers to absorb logistics costs that previously passed through distributor markups, tightening margins on liposomal amphotericin B while expanding volume commitments.
Pricing Analysis
Bundled infectious disease contracts are fragmenting into unbundled antifungal procurement in Maharashtra and Karnataka state hospital systems, where centralized purchasing authorities now negotiate induction-phase regimen pricing separately from maintenance therapy. Price differentiation rests on cold chain capability and WHO prequalification status, with South Africa's provincial tenders showing lowest sensitivity to unit price when supply reliability is guaranteed. Cost compression in conventional amphotericin B deoxycholate is intensifying because Indian contract manufacturers are absorbing fermentation yield volatility to secure volume guarantees. National AIDS control programs in Nigeria and Uganda demonstrate highest price sensitivity, while transplant centers in tertiary referral hospitals show lowest sensitivity due to bundled total-cost-of-care accounting.
Supply Chain Analysis
Single-source vulnerability sits with Southern European fermentation specialists supplying polyene raw materials, exposing formularies to batch consistency risk when demand surges coincide with production scheduling constraints. Manufacturing capacity for amphotericin B concentrates in Italy, Spain, and Portugal, while flucytosine chemical synthesis feeds from contract manufacturers in India and China. Supply chain risk centers on temperature-controlled distribution infrastructure gaps in rural Nigeria and eastern Democratic Republic of Congo, where cold chain failures degrade liposomal formulation efficacy before patient administration. Distribution runs through national tender systems and hospital formularies with direct manufacturer relationships replacing distributor intermediation in India's state health systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on flucytosine manufacturing scale economies and the shift toward premium-tier liposomal formulations as WHO guidelines consolidate procurement standards across high-burden regions.
For Market Incumbents: Cement supply reliability advantages through captive fermentation capacity expansion in Southern Europe and backward integration into polyene raw material production. Lock in multi-year volume commitments with South Africa's provincial health departments before subscription-based access models mature. The priority defensive lever is cold chain infrastructure partnerships that extend distribution reach into rural Nigeria and Democratic Republic of Congo, foreclosing competitor entry points. For New Entrants and Emerging Players: Infectious disease centers in Uganda and Nigeria represent the most penetrable channel partner type for point-of-care diagnostic integration that creates pre-symptomatic treatment entry points. Target the immunotherapy pipeline gap with monoclonal antibody adjuncts advancing through Phase II trials, where combination therapy protocols lack established supplier relationships. The optimal go-to-market angle is EMA orphan drug designation pathway navigation that offers protocol assistance and market exclusivity extensions for novel antifungal combinations. For Investors and Strategic Acquirers: Asymmetric upside sits with vertically integrated fermentation specialists possessing WHO prequalification status and existing South African tender relationships. Long-term viability over the projection horizon favors manufacturers with dual capability in both liposomal formulation and conventional deoxycholate production, enabling portfolio flexibility as procurement economics shift. The signal to watch is consolidation of national treatment guidelines between South Africa, Nigeria, and India, which would accelerate formulary harmonization and reward early movers with multinational registration dossiers.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Phase II monoclonal antibody combination trials in United States and South Africa academic centers compress development timelines. |
| Regulatory Approval Pathway | EMA orphan drug designation for cryptococcal meningitis streamlines protocol assistance and reduces regulatory fees for sponsors. |
| Manufacturing Scale-Up | Fermentation capacity expansion in Southern Europe secures polyene raw material supply reliability for liposomal formulations. |
| Long-term Supply Agreement | Subscription-based access models in South Africa's national tender system de-risk manufacturer commitments for flucytosine. |
| Strategic Partnership | Cold chain infrastructure partnerships with logistics providers extend liposomal amphotericin B access into rural Democratic Republic of Congo. |
Research Methodology
Direct dialogue with hospital procurement managers, formulary directors at South African provincial health departments, regulatory affairs leads at EMA and FDA, infectious disease specialists in Uganda's national referral network, and contract manufacturing executives in India grounded the qualitative foundation. Secondary validation drew from WHO Essential Medicines List revisions, EMA orphan drug designation databases, ClinicalTrials.gov enrollment records, South African Health Products Regulatory Authority registration filings, and Central Drugs Standard Control Organization import licensing data. Bottom-up patient volume modeling and top-down pharmaceutical expenditure analysis were triangulated to anchor market sizing.
Bottom-up demand modeling tracked induction-phase regimen volumes across HIV/AIDS patient populations in high-burden countries, while top-down analysis calibrated against national health expenditure data and donor program disbursements. Segmentation dimensions included therapeutic modality, patient population risk stratification, administration route, and regional regulatory cluster. CAGRs were derived from epidemiological trend extrapolation and procurement volume forecasting across the analysis window. Industry-specific forecast inputs incorporated antiretroviral therapy coverage expansion rates and cryptococcal antigen screening penetration at treatment initiation sites.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to HIV/AIDS epidemiological shifts, donor funding volatility for cryptococcal meningitis programs, and regulatory harmonization timelines across South Africa, Nigeria, and India. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Psychedelic Medicine Market
Specialty Medicine
Global Autism Spectrum Disorders Treatment Market
Specialty Medicine
Radiation-Induced Fibrosis Treatment Market
Specialty Medicine
Pyoderma Gangrenosum Therapeutics Market
Specialty Medicine
Transthyretin (TTR) Amyloidosis Market
Specialty Medicine
Bullous Pemphigoid Treatment Market
Specialty Medicine
Facial Paralysis Market
Specialty Medicine
Dravet Syndrome Treatment Market
Specialty Medicine
Global Focal Segmental Glomerulosclerosis Market
Specialty Medicine
Subdural Haematoma Market
Specialty Medicine
Chemotherapy Induced Peripheral Neuropathy Treatment Market
Specialty Medicine
Global Polycystic Ovarian Syndrome Treatment Market
Specialty Medicine
Ankylosing Spondylitis Treatment Market
Specialty Medicine
Factor V Leiden Thrombophilia Treatment Market
Specialty Medicine
Hypertrophic Cardiomyopathy (HCM) Therapeutics Market
Specialty Medicine
Global Alcoholic Hepatitis Therapeutics Market