
 Global Gastroparesis Treatment Market | 2026-2036
Global Gastroparesis Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Gastroparesis Treatment Market Foresight
North American pharmaceutical manufacturing is restructuring its gastroparesis pipeline capacity around novel prokinetic mechanisms. AbbVie Inc. leverages its established gastroenterology infrastructure to sustain clinical trial momentum across multiple therapy areas. Takeda Pharmaceutical Company Limited anchors its position through deep expertise in motility disorders and regulatory navigation in Japan and the United States. Evoke Pharma Inc. specializes in late-stage development of targeted therapies for diabetic gastroparesis, occupying a narrow but critical niche.
Gastroparesis treatment encompasses pharmacological, device-based, and nutritional interventions designed to restore gastric motility and alleviate symptoms of delayed gastric emptying. Prokinetic agents such as 5-HT4 receptor agonists and dopamine D2 antagonists represent the dominant pharmacological class, while gastric electrical stimulators deliver high-frequency impulses to the stomach wall for refractory cases. Prokinetic agents command the largest revenue share due to established reimbursement and broad prescriber familiarity, though gastric electrical stimulators are generating outsized interest as surgical referral patterns shift toward device-first protocols for drug-refractory patients. The idiopathic therapy area remains the most clinically heterogeneous, creating fragmented treatment pathways that pharmaceutical firms must navigate.
The FDA, EMA, and Japan's PMDA collectively shape market access through divergent efficacy endpoints and safety monitoring requirements for prokinetic therapies. FDA guidance on patient-reported outcomes in gastroparesis trials has tightened evidentiary standards, while the EU Medical Device Regulation imposes enhanced clinical evaluation obligations on gastric electrical stimulator manufacturers. Stakeholders must monitor evolving biomarker qualification efforts and adaptive trial designs that could compress development timelines for next-generation motility agents.
Market Dynamics
The gastroparesis treatment landscape is restructuring around FDA's tightened evidentiary standards for patient-reported outcomes, which are compressing clinical trial timelines and forcing sponsors to front-load biomarker qualification efforts before pivotal studies commence.
Growth Catalysts
- Accelerated Approval Pathways:The FDA's streamlined routes for novel prokinetic agents are shortening development cycles for motility-targeted therapies, enabling earlier commercialization of 5-HT4 receptor agonists.
- Diabetic Gastroparesis Prevalence:Rising incidence of diabetic complications across the United States is expanding addressable patient populations and securing prioritized reimbursement codes for disease-specific interventions.
- Device-First Surgical Protocols:Shifting referral patterns toward gastric electrical stimulators for drug-refractory cases are creating new intervention points earlier in the treatment algorithm.
Market Restraints
- Prolonged Regulatory Friction:Divergent efficacy endpoints between FDA, EMA, and PMDA force sponsors to run parallel clinical programs, inflating development costs and delaying harmonized market access.
- Reimbursement Concentration Risk:Heavy dependence on United States CMS coverage decisions creates vulnerability to policy shifts affecting gastric electrical stimulator and prokinetic agent payment rates.
- Biomarker Validation Gaps:Lack of qualified surrogate endpoints for gastric emptying acceleration forces reliance on subjective symptom scales, complicating trial design and label expansion.
Strategic Opportunities
- Japan's Aging Demographics:METI and PMDA incentives for geriatric-focused motility therapies create favorable regulatory tailwinds for entrants targeting idiopathic gastroparesis in elderly populations.
- Non-Invasive Neuromodulation:Convergence of transcutaneous electrical stimulation with wearable monitoring platforms opens ambulatory care channels previously restricted to implantable devices.
- Specialty Clinic Networks:Expansion of dedicated gastroparesis centers across Germany and France enables direct-to-specialist distribution models bypassing traditional hospital pharmacy procurement.
Industry Challenges
- Adaptive Trial Expertise Scarcity:Shortage of biostatisticians experienced in Bayesian gastroparesis study designs limits sponsor ability to exploit FDA's flexibility on interim analyses and sample size re-estimation.
- Legacy Stimulator Integration:New entrants face technical friction connecting next-generation gastric electrical stimulators to existing implantable pulse generator infrastructure in already-implanted patients.
- EU MDR Compliance Burden:Enhanced clinical evaluation obligations for active implantable devices are extending certification timelines and requiring additional post-market surveillance infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Gastroparesis Treatment Market |
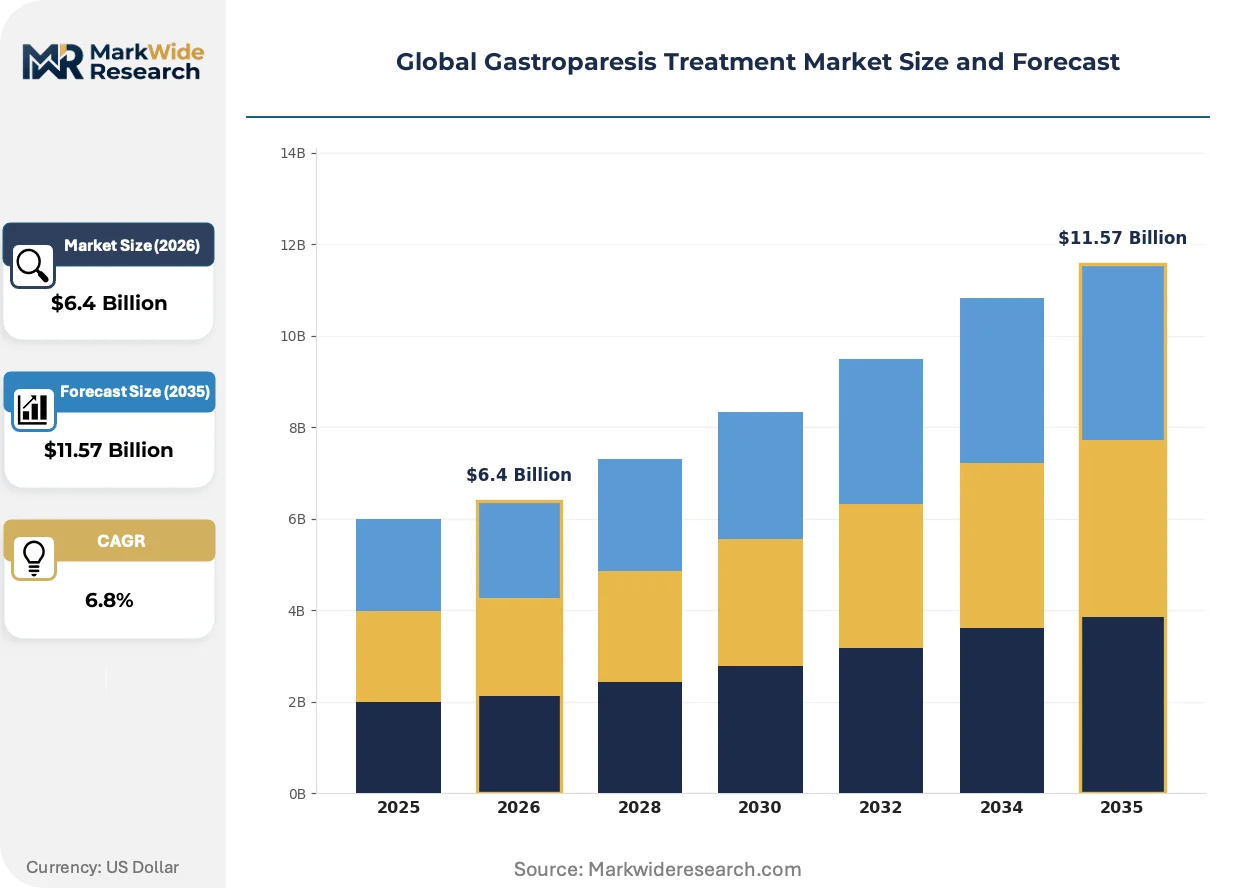
| Market Size in 2026 | $6.4 Billion |
| Market Size in 2035 | $11.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prokinetic Agents, Antiemetics, Antidepressants, Gastric Electrical Stimulators, Nutritional Therapy Therapy Area: Idiopathic, Diabetic, Post-Surgical, Drug-Induced End User: Specialty Clinics, Ambulatory Surgical Centers, Research Institutes, Pharmacies Delivery Mode: Oral, Intravenous, Subcutaneous, Transdermal |
| Companies Covered | AbbVie Inc., Takeda Pharmaceutical Company Limited, Evoke Pharma Inc., Vanda Pharmaceuticals, Medtronic Plc, Johnson & Johnson, Pfizer Inc., AstraZeneca plc, Neurogastrx, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Gastroparesis Treatment Market Shifts & Advancements
Digital biomarker capture and decentralized trial infrastructure are actively compressing the gap between clinical measurement and regulatory acceptance, reshaping how motility disorders demonstrate treatment effect.
High-resolution gastric mapping systems equipped with multi-electrode arrays are rewriting the precision of gastric electrical stimulation delivery. Academic medical centers in the United States and Netherlands are adopting these platforms for patient selection and parameter optimization. The technology is rewriting the economics of device therapy by reducing non-responder rates and justifying earlier surgical referral.
The EU Medical Device Regulation's enhanced clinical evaluation requirements are forcing gastric electrical stimulator manufacturers to generate prospective real-world evidence. Manufacturers must now maintain post-market clinical follow-up registries spanning multiple member states. German and French notified bodies are applying the most stringent interpretations, delaying CE mark renewals for legacy devices.
Patient advocacy networks are consolidating purchasing influence through disease-specific foundations that negotiate directly with manufacturers. These organizations are displacing traditional hospital procurement committees in the United States for gastric electrical stimulator selection. The shift is most visible in tertiary referral centers where foundation-endorsed protocols determine device brand inclusion on formulary.
Global Gastroparesis Treatment Market Segmentation
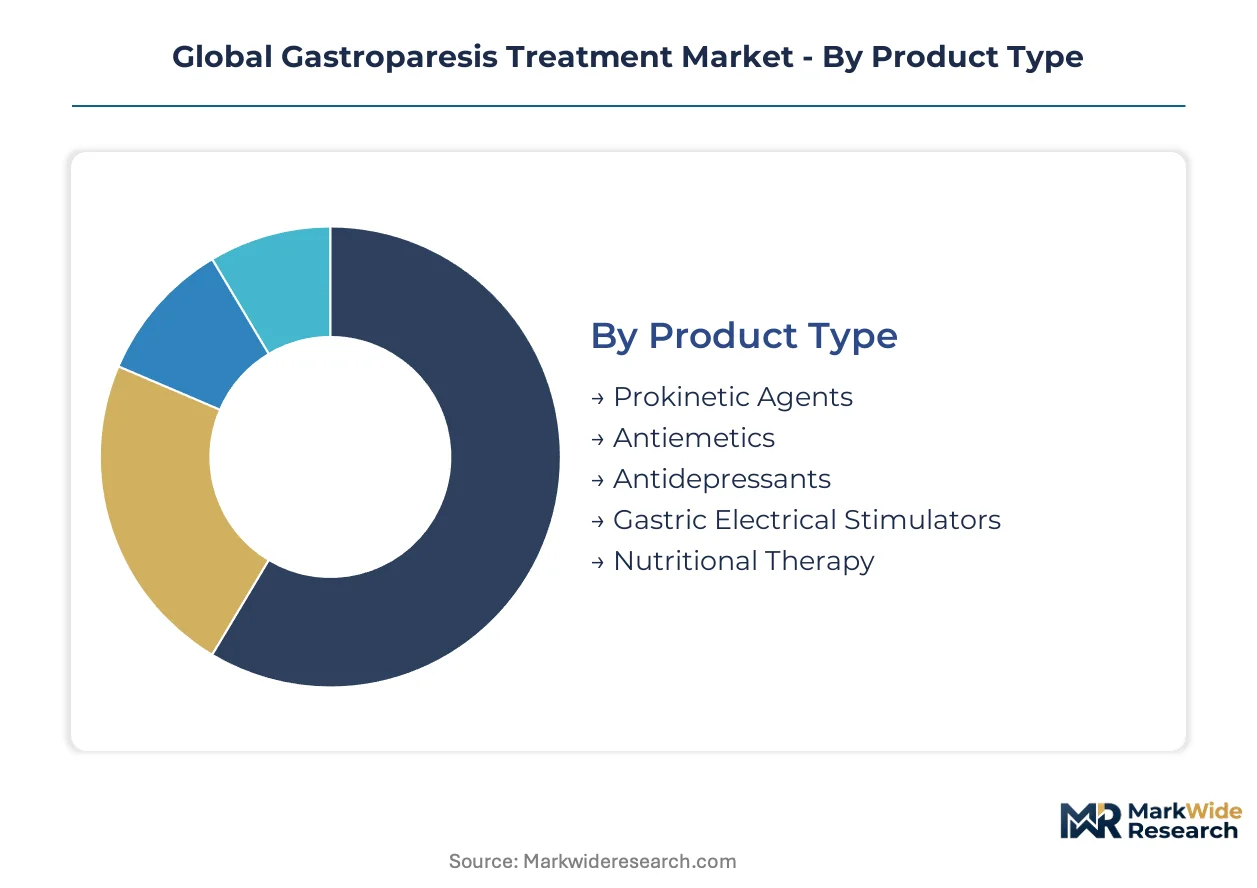
Segmentation in gastroparesis treatment reveals how capital allocation, regulatory pathways, and clinical workflows fragment across intervention types. Understanding these divisions exposes where pricing power concentrates and which segments absorb the bulk of R&D investment.
Product Type:
Capital intensity varies sharply across this category, with implantable devices demanding manufacturing infrastructure that pharmaceutical agents do not require.
- Prokinetic Agents:5-HT4 receptor agonists and dopamine D2 antagonists dominate prescription volume through established gastroenterology formularies. Demand clusters in United States specialty clinics where CMS reimbursement codes prioritize diabetic gastroparesis pharmacotherapy, though FDA evidentiary standards for patient-reported outcomes continue tightening approval requirements.
- Gastric Electrical Stimulators:High-frequency impulse generators require cleanroom manufacturing and biocompatibility testing that inflate upfront investment. United States tertiary centers are driving adoption as device-first surgical protocols expand, with academic medical centers in Boston and Houston pioneering high-resolution gastric mapping for patient selection.
- Antiemetics:Dopamine antagonists and 5-HT3 receptor blockers serve adjunctive symptom management in emergency and inpatient settings.
- Antidepressants:Low-dose tricyclics address neuropathic pain components in idiopathic presentations through off-label utilization.
- Nutritional Therapy:Enteral formulations and dietary modification protocols require minimal capital deployment but depend on specialized dietitian networks.
Most installed capacity flows through Prokinetic Agents. Expansion is steepest in Gastric Electrical Stimulators.
Therapy Area:
Clinical heterogeneity across etiologies forces sponsors to design parallel trial programs rather than unified development strategies.
- Diabetic:Hyperglycemia-induced vagal neuropathy produces the most addressable patient population with clearest reimbursement pathways. United States endocrinology and gastroenterology co-management models are expanding, though biomarker validation gaps complicate surrogate endpoint selection for regulatory submissions.
- Idiopathic:Absence of identifiable cause fragments treatment algorithms across motility clinics in Germany, France, and the United States. Patient advocacy foundations in these geographies are consolidating purchasing influence and displacing traditional hospital procurement for device selection.
- Post-Surgical:Vagal nerve injury from bariatric or fundoplication procedures creates refractory cases requiring multimodal intervention.
- Drug-Induced:Opioid and anticholinergic effects drive reversible presentations managed through medication adjustment rather than device implantation.
Revenue concentration sits with Diabetic presentations. Idiopathic cases are gaining share fastest as diagnostic criteria standardize.
End User:
Procurement authority is shifting from hospital pharmacy committees toward disease-specific foundations and direct-to-specialist distribution channels.
- Specialty Clinics:Dedicated gastroparesis centers in Germany and France are bypassing traditional procurement through direct manufacturer negotiations. These facilities concentrate device implantation volume and influence referral patterns for refractory cases across their respective national healthcare systems.
- Ambulatory Surgical Centers:Same-day gastric electrical stimulator implantation is expanding in United States outpatient settings where reimbursement permits. Centers in Florida and Texas are achieving throughput levels that justify dedicated inventory and technician staffing.
- Research Institutes:Academic medical centers in the Netherlands and United States host high-resolution gastric mapping trials that shape device parameter optimization.
- Pharmacies:Retail and specialty pharmacy channels handle oral prokinetic distribution with limited clinical influence over prescribing decisions.
Specialty Clinics absorb the majority of high-value interventions. Ambulatory Surgical Centers are climbing the fastest as surgical migration accelerates.
Delivery Mode:
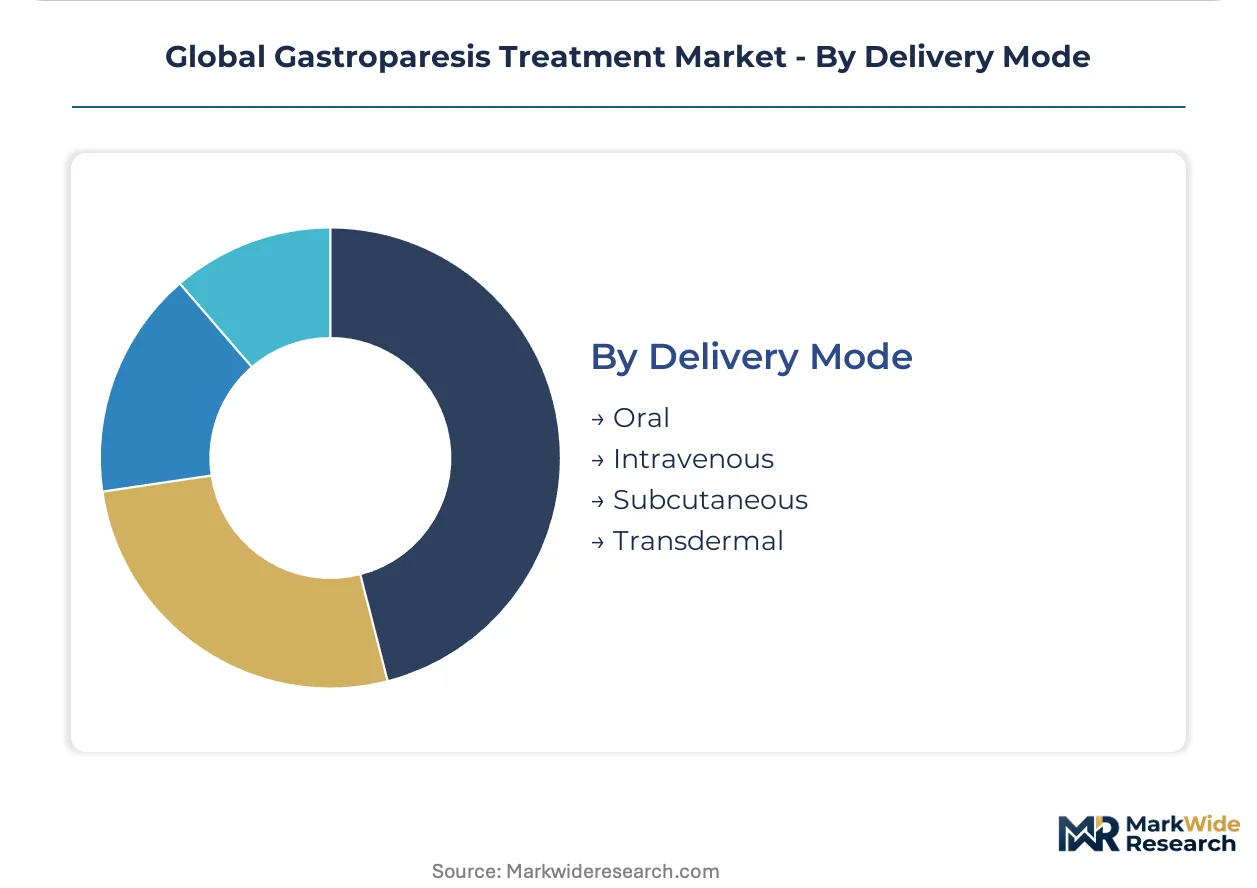
Route selection determines manufacturing complexity, cold chain requirements, and administration site economics.
- Oral:Tablet and liquid formulations of metoclopramide and domperidone dominate maintenance therapy. United States gastroenterology practices favor oral routes for outpatient titration, though bioavailability limitations in delayed gastric emptying constrain efficacy.
- Intravenous:Hospital-based acute management of severe exacerbations requires infusion infrastructure that concentrates in tertiary centers. United States emergency departments and inpatient units represent the primary demand locus for IV prokinetics during refractory vomiting episodes.
- Subcutaneous:Novel injectable prokinetics in development are targeting home administration to reduce hospital dependency.
- Transdermal:Patch-based antiemetics serve palliative and perioperative applications with limited gastroparesis-specific utilization.
Oral delivery commands the largest installed base. Intravenous administration is expanding most quickly in acute care settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting gastroparesis clinical trial investment toward jurisdictions with streamlined motility-disorder approval frameworks, as sponsors seek to compress development timelines amid divergent evidentiary standards.
United States
CMS reimbursement prioritization for diabetic gastroparesis pharmacotherapy concentrates demand in endocrinology-gastroenterology co-management models. FDA tightened patient-reported outcome standards for prokinetic trials, forcing sponsors to front-load biomarker qualification. Academic medical centers in Boston and Houston pioneer high-resolution gastric mapping for device patient selection.
Germany
Specialty clinic networks in Bavaria and North Rhine-Westphalia bypass traditional hospital procurement through direct manufacturer negotiations for gastric electrical stimulators. EU MDR enhanced clinical evaluation obligations extend certification timelines for active implantable devices. Berlin-Brandenburg hosts post-market surveillance registries spanning multiple member states.
Japan
METI and PMDA incentives for geriatric-focused motility therapies create favorable regulatory tailwinds targeting idiopathic gastroparesis in elderly populations. Aging demographics expand addressable patient populations beyond diabetic etiologies. Kanto region academic centers anchor adaptive trial designs for next-generation 5-HT4 receptor agonists.
France
Patient advocacy foundations in Île-de-France consolidate purchasing influence for device selection, displacing traditional hospital pharmacy committees. ANSM applies stringent interpretations of EU MDR clinical evaluation requirements for gastric electrical stimulator renewals. Auvergne-Rhône-Alpes specialty centers concentrate refractory case referral patterns.
Netherlands
Academic medical centers in the Randstad region host high-resolution gastric mapping trials shaping device parameter optimization protocols. Eindhoven's medical technology cluster supports multi-electrode array manufacturing for next-generation stimulator platforms. Dutch notified bodies coordinate with German and French counterparts on harmonized MDR implementation timelines.
Global Gastroparesis Treatment Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue novel prokinetic mechanisms and non-invasive neuromodulation platforms. The competitive structure fragments across pharmaceutical prokinetic developers, implantable device manufacturers, and digital health integrators. Three archetypes dominate: diversified gastroenterology incumbents leveraging established infrastructure, pure-play motility specialists concentrating late-stage assets, and surgical device firms expanding into ambulatory stimulation protocols. Consolidation activity concentrates on adaptive trial expertise acquisition and gastric mapping technology licensing.
Within the diversified pharmaceutical tier, AbbVie Inc. and Takeda Pharmaceutical Company Limited exemplify infrastructure-heavy positioning across multiple therapy areas. Evoke Pharma Inc. occupies the pure-play specialist archetype with concentrated exposure to diabetic gastroparesis development. These three entities collectively represent the spectrum from broad gastroenterology platforms to narrow therapeutic focus, illustrating how capital allocation diverges between risk-mitigated diversification and targeted indication betting.
| Leading Market Players |
|---|
| AbbVie Inc. |
| Takeda Pharmaceutical Company Limited |
| Evoke Pharma Inc. |
| Vanda Pharmaceuticals |
| Medtronic Plc |
| Johnson & Johnson |
| Pfizer Inc. |
| AstraZeneca plc |
| Neurogastrx |
| Others |
Supply & Pricing Matrix
Biostatisticians experienced in Bayesian adaptive trial designs cluster in Boston and Basel, and their scarcity widens spreads between premium-tier prokinetic sponsors and economy-tier generic manufacturers. Labor-cost differentials in clinical trial execution cascade into pricing-tier stratification across pharmaceutical and device segments.
Pricing Analysis
Distributor margins on gastric electrical stimulators absorb 15-25 points before hospital procurement, compressing manufacturer net pricing. Three-tier pricing structure across premium, standard, and economy levels separates high-resolution mapping-enabled devices from legacy pulse generators from commodity antiemetics. Pricing pressure stems from CMS reimbursement code consolidation for diabetic gastroparesis pharmacotherapy. Specialty clinics demonstrate lowest price sensitivity due to foundation-negotiated protocols, while ambulatory surgical centers exhibit acute margin consciousness.
Supply Chain Analysis
Domestic-content mandates in Japan's METI incentive programs are reshaping sourcing for geriatric-focused motility therapies toward Kanto-region CRO networks. Implantable pulse generator manufacturing concentrates in Ireland, Malaysia, and Costa Rica. Raw material dependencies span platinum-iridium electrodes, medical-grade silicone, and lithium-ion cells. Single-source vulnerability sits with multi-electrode array foundries in Eindhoven. Distribution runs through specialty clinic direct-negotiation channels bypassing traditional hospital procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The gastroparesis treatment market functions as a regulatory compounder, where FDA's tightened patient-reported outcome standards for prokinetic trials are accelerating biomarker qualification investments and compressing development timelines for prepared sponsors.
For Market Incumbents: Anchor adaptive trial infrastructure through acquisition of Bayesian biostatistics capabilities in Boston or Basel. Consolidate high-resolution gastric mapping technology licensing to defend against non-invasive neuromodulation entrants. Prioritize EU MDR post-market surveillance registry investments in Germany to preempt certification delays. For New Entrants and Emerging Players: Begin with Japan's idiopathic geriatric segment where METI incentives reduce regulatory friction against established diabetic-focused incumbents. Target transcutaneous electrical stimulation platforms for ambulatory care white space. Pursue direct-to-specialty-clinic distribution in France's foundation-negotiated procurement environment. For Investors and Strategic Acquirers: Valuations sit cheapest among pure-play motility specialists with late-stage diabetic gastroparesis assets but limited device integration. Long-term viability favors platforms spanning pharmaceutical prokinetics and neuromodulation hardware. Watch FDA biomarker qualification letters as inflection signal for accelerated approval pathway access.| Strategic Initiative | Industry Significance |
|---|---|
| Adaptive Trial Design Investment | Bayesian methodologies compress gastroparesis study timelines per FDA interim analysis guidance. |
| High-Resolution Mapping Licensing | Multi-electrode array technology reduces gastric electrical stimulator non-responder rates in academic centers. |
| EU MDR Post-Market Surveillance | German registry infrastructure satisfies enhanced clinical evaluation obligations for device renewals. |
| Direct-to-Specialty-Clinic Distribution | Bypassing hospital procurement committees captures foundation-negotiated device volumes in France. |
| Japan Geriatric Regulatory Pathway | METI incentives for elderly idiopathic gastroparesis open differentiated market access. |
Research Methodology
Bottom-up specialty clinic and ambulatory surgical center modeling reconciled against top-down pharmaceutical and device manufacturer tracking forms the analytical core. Primary interviews with regulatory affairs leads at prokinetic developers, hospital procurement managers for gastric electrical stimulators, formulary directors at United States payers, and biomedical engineers at academic medical centers combined with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov protocols, and CMS Medicare reimbursement databases.
Historical trendline analysis across prokinetic prescription volumes, device implantation procedures, and patient-reported outcome instrument adoption informed projection frameworks. Segmentation dimensions modeled span product type, therapy area etiology, end-user facility category, and delivery mode across the analysis window. CAGRs derived from regression-adjusted growth rates applied to diabetic prevalence trajectories and surgical referral pattern shifts. Forecast inputs incorporated FDA biomarker qualification timelines and EU MDR implementation pace.
Several conditions sit outside the modeled scope, including unforeseen regulatory reversals on patient-reported outcome standards, abrupt CMS reimbursement code eliminations, and breakthrough non-invasive neuromodulation technologies achieving parity with implantable devices. Forecasts reflect documented assumptions subject to revision from these factors. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Necrobiosis Lipoidica Diabeticorum Market
Specialty Medicine
Global Thyroid Disorder Market
Specialty Medicine
Serotonin Syndrome Market
Specialty Medicine
Anaplastic Astrocytoma Market
Specialty Medicine
Listeriosis Treatment Market
Specialty Medicine
Generalized Anxiety Disorder Treatment Market
Specialty Medicine
Strep Throat Treatment Market
Specialty Medicine
Meningitis Treatment Market
Specialty Medicine
Global Childhood Absence Epilepsy Treatment Market
Specialty Medicine
Small Molecule Targeted Cancer Therapy Market
Specialty Medicine
Moderate-To-Severe Acne Therapeutics Market
Specialty Medicine
Bleeding Disorders Treatment Market
Specialty Medicine
Latin America Bladder Cancer Therapeutics and Diagnostics Market
Specialty Medicine
Aldosteronism Treatment Market
Specialty Medicine
Global Primary Angle-Closure Glaucoma Market
Specialty Medicine
Epilepsy Treatment Market