
 Vascular Dementia Treatment Market | 2026-2036
Vascular Dementia Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Vascular Dementia Treatment Market Analytics
Maintenance contracts for cognitive monitoring platforms is broadening what pharmaceutical companies bundle with drug therapies. Eisai Co., Ltd. leverages its amyloid-targeting expertise to extend into vascular cognitive impairment protocols. AbbVie Inc. anchors its neuroscience portfolio through sustained R&D investment in cerebrovascular mechanisms. Novartis AG competes on manufacturing scale for injectable neuroprotective formulations across European and Asian markets.
Vascular dementia treatment encompasses pharmacological and non-pharmacological interventions targeting cognitive decline resulting from cerebrovascular pathology, including ischemic and hemorrhagic brain lesions. Cholinesterase inhibitors remain the dominant pharmacological class, though memantine formulations for moderate-to-severe cases command premium positioning due to their NMDA receptor antagonism mechanism. Oral administration modes still occupy the largest volume share, yet transdermal delivery systems are gaining traction among nursing facilities seeking reduced caregiver burden. Hospital-based care settings currently dominate revenue capture, while home care segments are expanding fastest as remote patient monitoring technologies mature.
The FDA's Breakthrough Therapy designation and EMA's PRIME scheme are accelerating market access for novel vascular dementia therapeutics, though post-marketing safety requirements are intensifying. Japan's PMDA maintains stringent pharmacovigilance standards for cognitive enhancers that shape regional product development priorities. Stakeholders must monitor how evolving biomarker-based diagnostic criteria will redefine eligible patient populations and reimbursement thresholds across regulatory jurisdictions.
Market Dynamics
The FDA's accelerated approval pathways for neurodegenerative therapies are compressing clinical trial timelines while simultaneously intensifying post-marketing surveillance obligations for vascular dementia drug developers.
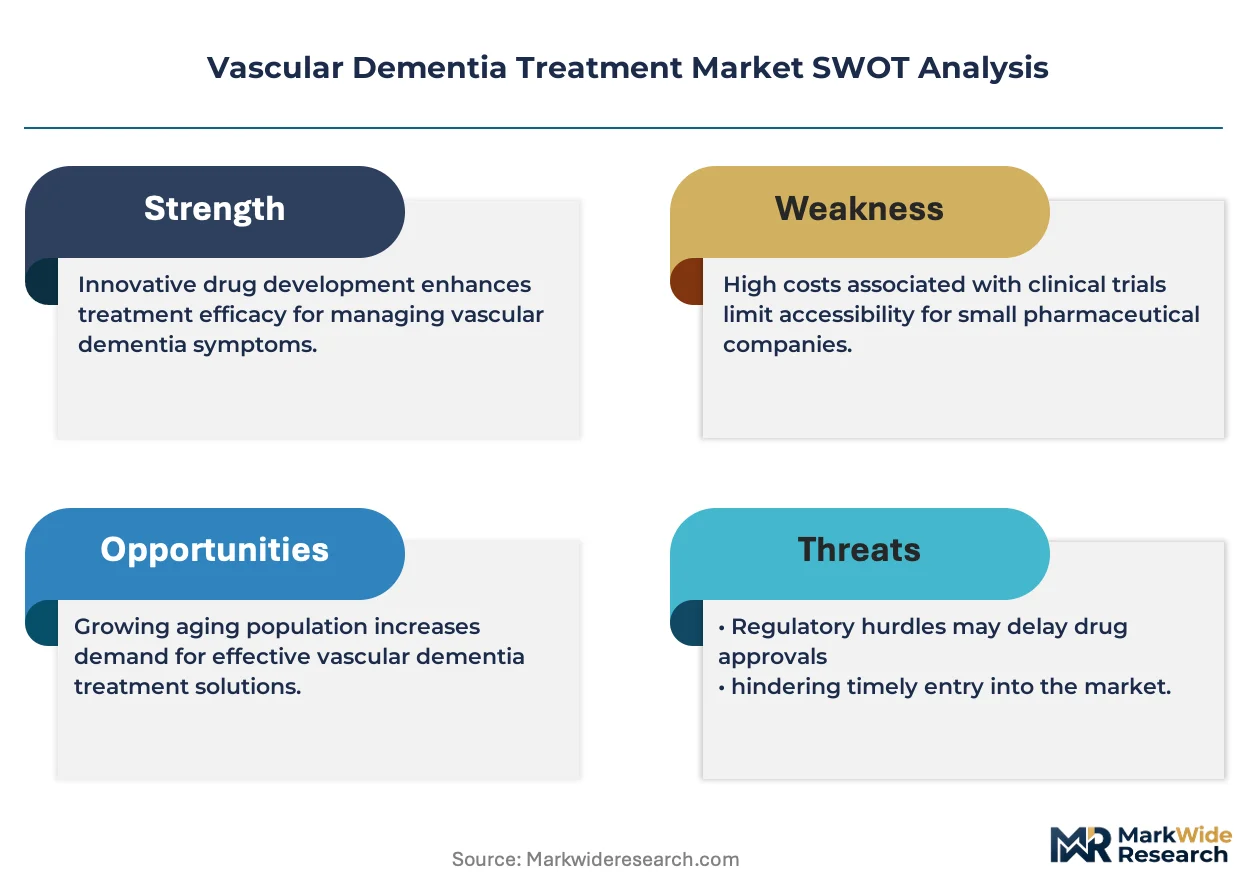
Growth Catalysts
- Medicare reimbursement expansion:The United States Medicare program now covers dementia care management codes, driving specialist referrals into hospital neurology departments and cognitive assessment protocols.
- Biomarker-based diagnostic criteria:Evolving cerebrovascular pathology markers from EMA's PRIME scheme eligibility assessments are redefining addressable patient populations for therapeutic developers.
- Remote patient monitoring maturation:Home care segments are absorbing transdermal delivery systems as nursing facilities prioritize reduced caregiver burden alongside cognitive monitoring platform integration.
Market Restraints
- Japan's pharmacovigilance stringency:PMDA cognitive enhancer surveillance standards impose extended development timelines and regional product adaptation costs.
- Injectable formulation manufacturing concentration:European and Asian neuroprotective drug production clusters create supply vulnerability for novel cerebrovascular mechanism therapies.
- Cholinesterase inhibitor clinical ceiling:Dominant pharmacological class efficacy plateaus limit premium pricing power for incremental vascular dementia therapeutics.
Strategic Opportunities
- Transdermal delivery system penetration:Nursing facility procurement channels favor patch-based administration modes that reduce hourly nursing intervention requirements.
- Maintenance contract bundling:Pharmaceutical developers can capture recurring revenue streams by packaging cognitive monitoring platforms with chronic drug therapy protocols.
- Moderate-to-severe case NMDA positioning:Memantine formulation gaps in vascular cognitive impairment protocols offer premium pricing entry points distinct from Alzheimer's overlap therapies.
Industry Challenges
- Cerebrovascular mechanism R&D talent scarcity:Specialized neuroscience research functions command premium compensation as Eisai, AbbVie, and Novartis compete for identical expertise pools.
- Post-marketing safety infrastructure capex:FDA Breakthrough Therapy designation recipients must build real-world evidence collection systems before commercial launch.
- Biomarker standardization delays:Inconsistent cerebrovascular lesion quantification protocols across FDA, EMA, and PMDA jurisdictions fragment clinical endpoint design.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vascular Dementia Treatment Market |
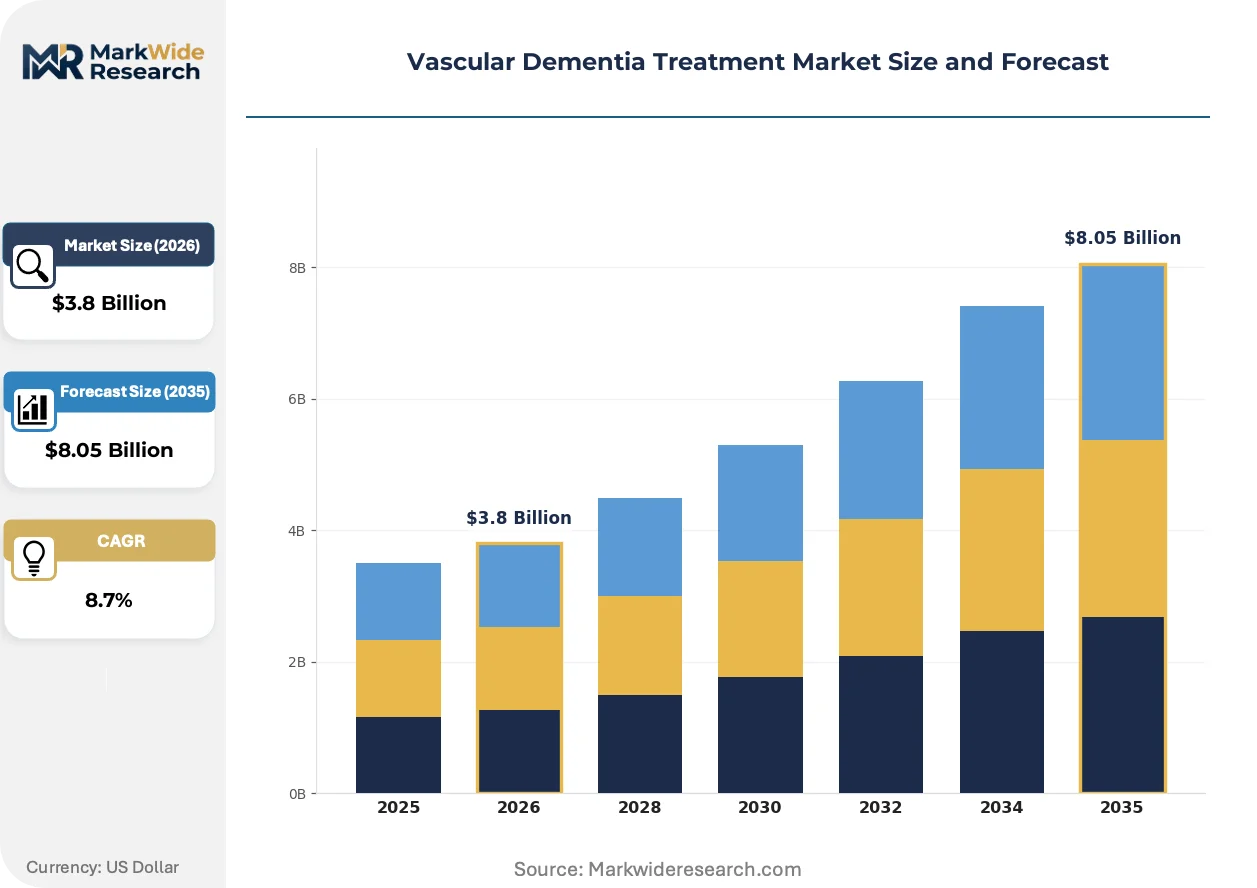
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cholinesterase Inhibitors, Memantine, Antidepressants, Others Administration Mode: Oral, Injectable, Transdermal, Others Care Setting: Hospitals, Outpatient Clinics, Home Care, Nursing Facilities End User: Healthcare Providers, Caregivers, Patients, Family Members |
| Companies Covered | Eisai Co., Ltd., AbbVie Inc., Novartis AG, Eli Lilly and Company, CSPC Ouyi Pharmaceutical, Lundbeck, Biogen Inc., Sun Pharmaceutical Industries Ltd., Daiichi Sankyo Company Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vascular Dementia Treatment Market Evolving Landscape
Digital biomarker integration and decentralized trial infrastructure are rewriting how vascular dementia therapeutics demonstrate efficacy outside traditional hospital-based cognitive assessment frameworks.
Digital twin modeling of cerebrovascular lesion progression is rewriting clinical trial simulation practices. Contract research organizations serving neurology drug developers now deploy virtual patient cohorts to optimize NMDA receptor antagonist dosing protocols before Phase II initiation. This compression of traditional dose-ranging studies is rewriting development economics for moderate-to-severe vascular cognitive impairment indications.
EMA's PRIME scheme eligibility criteria now explicitly reward cerebrovascular biomarker stratification in trial design. European developers targeting vascular cognitive impairment must demonstrate measurable white matter lesion correlation with cognitive endpoints to secure accelerated assessment pathways. Hospital neurology departments across Germany, France, and the Netherlands are retrofitting MRI protocols to capture these regulatory-mandated biomarker datasets.
After-sales service unbundling from drug pricing is restructuring pharmaceutical-commercial relationships with hospital pharmacy directors. Maintenance contracts for cognitive monitoring platforms now separate from per-unit drug procurement, enabling nursing facilities to source monitoring technology from independent digital health vendors while retaining therapeutic relationships with established neuroscience portfolios. This bifurcation is most visible in United States Medicare Advantage plan negotiations, where cognitive care management reimbursement codes incentivize technology vendor diversification.
Vascular Dementia Treatment Market Segmentation
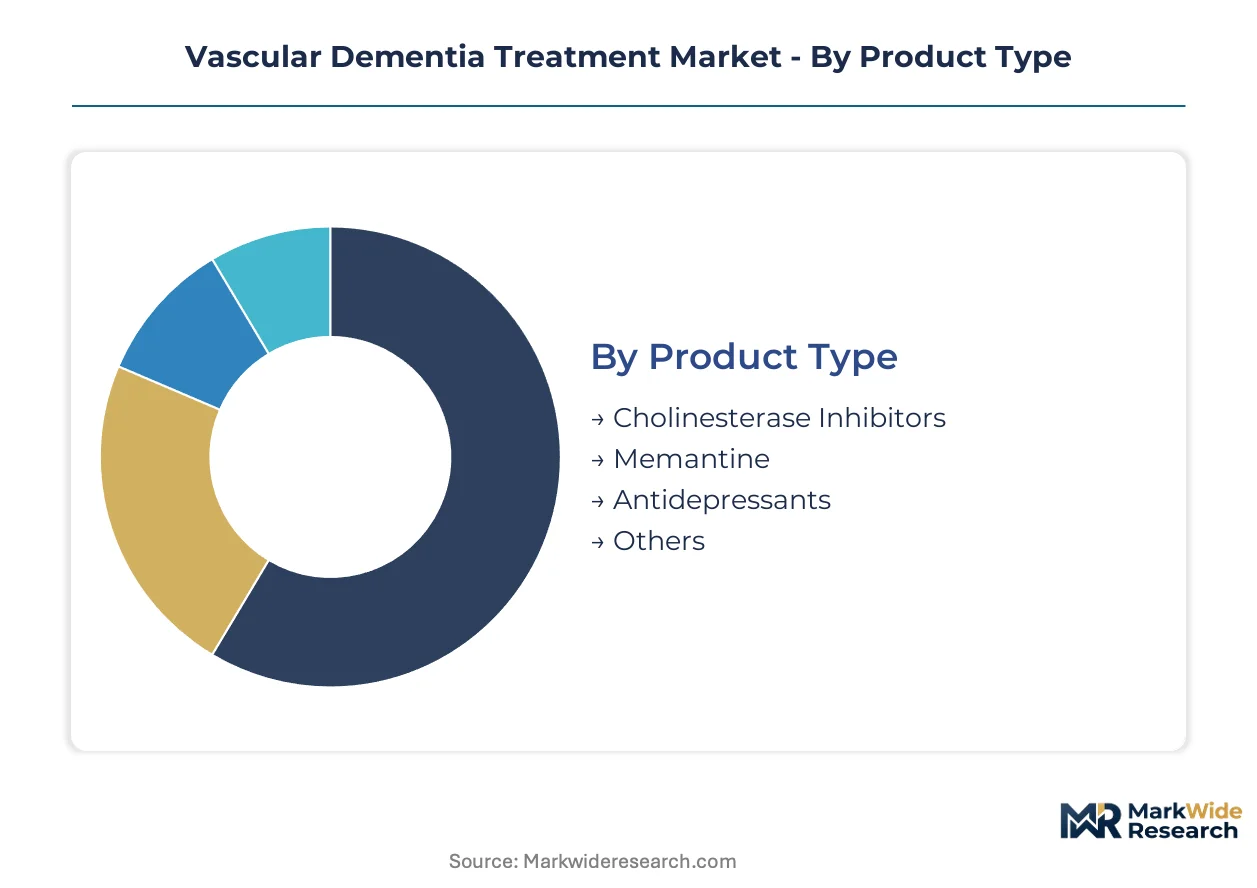
Treatment modality selection in vascular dementia depends on disease staging, caregiver capacity, and reimbursement infrastructure. Segmentation reveals how pharmacological classes, delivery mechanisms, and care settings compete for patient flow across acute and chronic management pathways.
Product Type:
Standalone pharmacological agents dominate prescription volumes, while combination protocols embed cognitive enhancers within broader neurodegenerative management systems.
- Cholinesterase Inhibitors:These agents enhance cholinergic neurotransmission through acetylcholinesterase blockade, improving attention and memory scores in mild-to-moderate cases. Demand concentrates in United States hospital neurology departments where Medicare dementia care management codes reimburse specialist oversight. Efficacy plateaus in advanced cerebrovascular pathology limit premium pricing power for incremental entrants.
- Memantine:NMDA receptor antagonism reduces glutamate-mediated excitotoxicity in moderate-to-severe vascular cognitive impairment. Nursing facilities in Germany and the Netherlands favor this class for behavioral symptom management where caregiver burden reduction justifies higher acquisition costs. Premium positioning remains distinct from Alzheimer's overlap therapies.
- Antidepressants:Selective serotonin reuptake inhibitors address mood disturbances complicating vascular dementia progression.
- Others:Neuroprotective adjuncts and vascular risk factor modifiers complete combination protocols.
Cholinesterase inhibitors lead volumes today; memantine is gaining share fastest in institutional settings.
Administration Mode:
Cost tier stratification separates high-intervention injectable delivery from self-administered oral and patch-based alternatives.
- Oral:Tablet and liquid formulations occupy the largest volume share across outpatient and home settings. United States Medicare Advantage plans drive utilization through pharmacy benefit structures that favor established oral cognitive enhancers with demonstrated bioequivalence.
- Injectable:Intravenous and subcutaneous neuroprotective formulations command hospital pharmacy budgets in acute cerebrovascular event protocols. European manufacturing clusters in Switzerland and Germany concentrate production capacity for these higher-margin delivery systems.
- Transdermal:Patch-based delivery reduces hourly nursing intervention requirements in long-term care.
- Others:Nasal and sublingual routes address specific absorption challenges in dysphagic patients.
Oral administration dominates prescription counts; transdermal systems are expanding most quickly in nursing facility procurement channels.
Care Setting:
Patient acuity and reimbursement mechanics determine whether treatment occurs in institutional, ambulatory, or residential environments.
- Hospitals:Acute neurology departments manage initial diagnosis, comorbidity stabilization, and therapeutic initiation. Japan's PMDA pharmacovigilance standards shape protocol design for cognitive enhancers administered in these high-oversight settings.
- Nursing Facilities:Long-term residential care integrates medication administration with 24-hour monitoring for behavioral and psychological symptoms. Transdermal delivery systems reduce staffing costs while maintaining therapeutic adherence.
- Outpatient Clinics:Specialist neurology practices manage stable patients through periodic cognitive assessment and medication adjustment.
- Home Care:Remote patient monitoring technologies mature to support domiciliary management with caregiver oversight.
Hospitals capture the highest revenue per patient episode; home care segments are climbing the fastest as digital biomarker platforms enable decentralized monitoring.
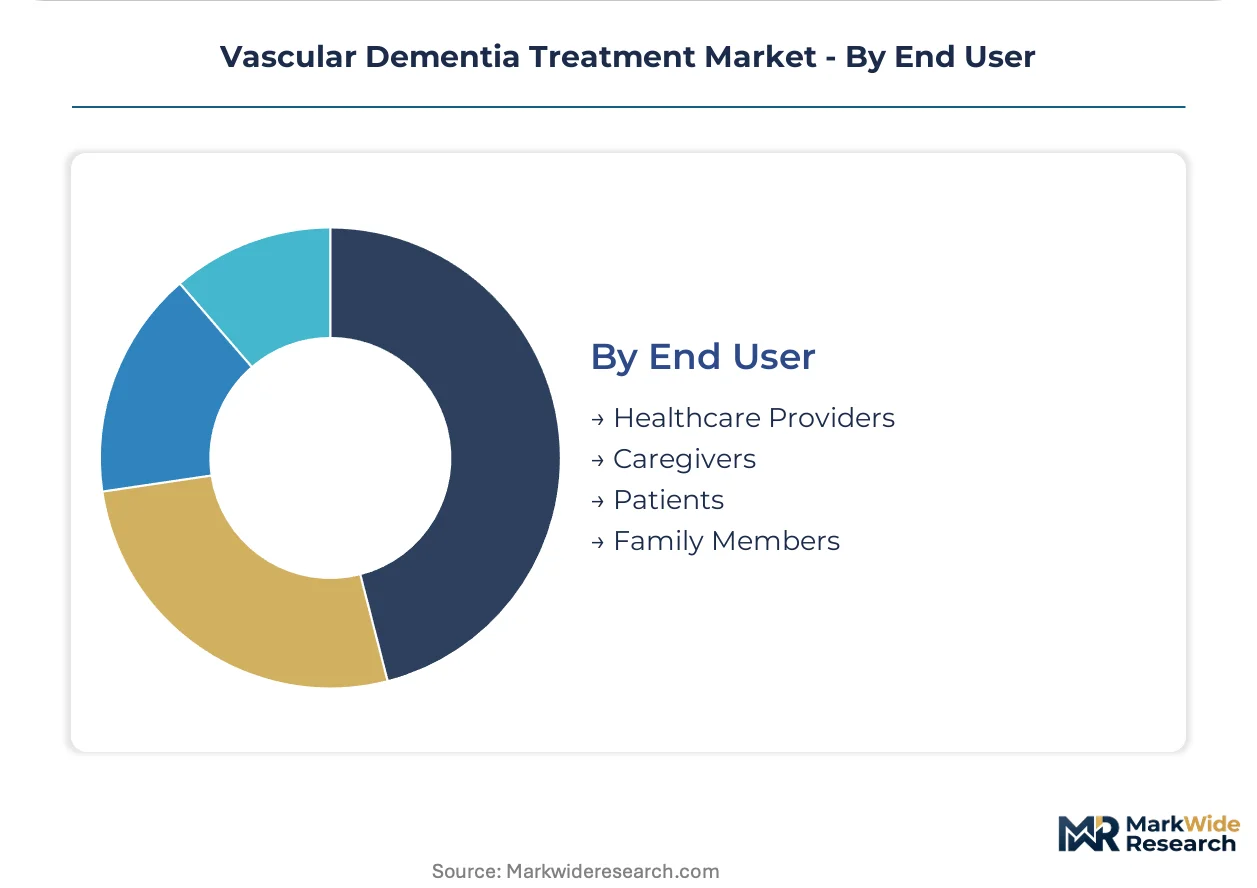
End User:
Decision-making authority fragments across professional, familial, and patient stakeholders with divergent information access and risk tolerance.
- Healthcare Providers:Neurologists and geriatricians drive formulary selection through evidence-based protocol adherence. EMA's PRIME scheme eligibility criteria influence prescriber confidence in novel vascular cognitive impairment therapeutics.
- Caregivers:Professional and informal care partners administer treatments and monitor behavioral responses in daily practice.
- Patients:Individual recipients exercise autonomy where cognitive capacity permits shared decision-making.
- Family Members:Surrogate decision-makers navigate advance care planning and financial commitment for long-term therapy.
Healthcare providers control initial prescribing decisions; caregiver influence is expanding most quickly as administration burden shapes product selection.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping where vascular dementia drug development concentrates, with manufacturers migrating toward jurisdictions offering streamlined neurodegenerative therapy pathways while maintaining pharmacovigilance credibility.
United States
Medicare reimbursement expansion for dementia care management codes drives specialist referrals into hospital neurology departments. FDA accelerated approval pathways compress clinical trial timelines for novel cerebrovascular therapeutics. The Boston-Cambridge biotechnology corridor anchors neuroprotective formulation R&D, with contract research organizations deploying digital twin modeling for virtual patient cohorts.
Germany
Hospital pharmacy budgets absorb injectable neuroprotective formulations for acute cerebrovascular protocols. EMA PRIME scheme eligibility criteria mandate white matter lesion biomarker correlation in trial design. The Rhine-Ruhr industrial cluster concentrates manufacturing capacity for higher-margin parenteral delivery systems serving European institutional markets.
Japan
Aging demographics concentrate demand for moderate-to-severe case management in long-term care facilities. PMDA pharmacovigilance standards for cognitive enhancers impose extended development timelines that shape regional product adaptation priorities. The Kanto region around Tokyo anchors specialist neurology practice networks integrating remote patient monitoring technologies.
Switzerland
Swissmedic regulatory frameworks attract neurodegenerative therapy developers seeking precision medicine credibility. Injectable formulation manufacturing clusters leverage cross-border supply chains into Germany and France. The Basel-Zurich corridor hosts contract manufacturing organizations serving European and Asian markets for cerebrovascular mechanism therapeutics.
China
Domestic pharmaceutical producers expand cholinesterase inhibitor production for outpatient and home care segments. NMPA regulatory harmonization efforts with ICH standards accelerate market access for multinational neuroprotective drug developers. The Yangtze River Delta region concentrates active pharmaceutical ingredient manufacturing and clinical trial site networks.
Vascular Dementia Treatment Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with research-intensive developers commanding premium positioning in moderate-to-severe indications while generic producers capture volume in established cholinesterase inhibitor categories. Market structure tilts toward consolidation at the therapeutic-class level, though manufacturing capacity remains fragmented across regional production clusters. Three archetypes dominate: amyloid-targeting platform extenders, cerebrovascular mechanism specialists, and scale-driven injectable formulation producers. Competitive moves center on cognitive monitoring platform bundling and transdermal delivery system partnerships with nursing facility procurement channels.
Within the amyloid-targeting extender archetype, Eisai Co., Ltd. and Biogen Inc. occupy positions leveraging neuroscience platform expertise into vascular cognitive impairment protocols. AbbVie Inc. anchors the cerebrovascular mechanism specialist tier through sustained R&D portfolio investment. Novartis AG represents the scale-driven manufacturing archetype, with Basel-based production networks supplying injectable neuroprotective formulations across European and Asian hospital pharmacy markets.
| Leading Market Players |
|---|
| Eisai Co., Ltd. |
| AbbVie Inc. |
| Novartis AG |
| Eli Lilly and Company |
| CSPC Ouyi Pharmaceutical |
| Lundbeck |
| Biogen Inc. |
| Sun Pharmaceutical Industries Ltd. |
| Daiichi Sankyo Company Limited |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up contract research organizations have consolidated Phase II-III trial execution capacity across the Boston-Cambridge corridor, tightening bid discipline for vascular dementia protocol design while simultaneously compressing margin capture for standalone pharmacovigilance services. This ownership concentration feeds directly into how pharmaceutical developers negotiate cognitive monitoring platform bundling and transdermal delivery system procurement.
Pricing Analysis
Capacity additions in Switzerland and Germany are reshaping price floors for injectable neuroprotective formulations serving European hospital pharmacy budgets. Three-tier pricing structure across premium NMDA receptor antagonists, standard cholinesterase inhibitors, and economy-tier generic cognitive enhancers stratifies procurement decisions. Cost compression in the transdermal segment is intensifying because nursing facilities prioritize reduced hourly intervention requirements. Medicare Advantage plans exhibit the highest price sensitivity; Japan's PMDA-compliant premium formulations command the least.
Supply Chain Analysis
Single-source vulnerability sits with concentrated active pharmaceutical ingredient production in the Yangtze River Delta region of China. Finished dose formulation draws from Switzerland, Germany, and the United States for higher-margin parenteral delivery systems. Supply chain risk centers on regulatory restriction divergence between FDA Breakthrough Therapy pathways and EMA PRIME biomarker requirements. Distribution runs through hospital pharmacy direct purchasing and nursing facility group procurement organizations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vascular dementia therapeutics represent a late-cycle quality story as demand shifts toward biomarker-validated premium protocols that satisfy EMA PRIME eligibility criteria and command sustained reimbursement traction.
For Market Incumbents: To counter transdermal delivery system commoditization, Eisai and AbbVie should deepen backward integration into cognitive monitoring platform software development while securing exclusive channel control through Medicare Advantage plan formulary placement. Certification investment in FDA Breakthrough Therapy designation maintenance contracts offers defensive moat construction against emerging amyloid-targeting platform extenders. For New Entrants and Emerging Players: The price-point gap between premium memantine formulations and economy cholinesterase inhibitors creates white-space opportunity in moderate-to-severe vascular cognitive impairment protocols for nursing facilities. Target home care segments in Japan's Kanto region where remote patient monitoring maturation outpaces incumbent digital health bundling. Position through independent cognitive assessment platform partnerships rather than pharmaceutical co-development. For Investors and Strategic Acquirers: Valuations sit cheapest among scale-driven injectable formulation producers lacking cerebrovascular mechanism R&D depth. Long-term viability across the analysis window favors acquisition of contract manufacturing organizations with Basel-Zurich corridor production networks and existing EMA regulatory relationships. Watch for FDA post-marketing safety infrastructure capex announcements as inflection indicators for real-world evidence collection capability premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Biomarker-Based Trial Design | EMA PRIME scheme eligibility now mandates white matter lesion correlation for accelerated assessment pathways. |
| Transdermal Delivery Partnerships | Nursing facility procurement channels favor patch-based administration reducing hourly nursing intervention requirements. |
| Cognitive Monitoring Platform Bundling | Maintenance contracts separate from per-unit drug procurement enable recurring revenue capture in Medicare Advantage negotiations. |
| Regulatory Approval Pathway Diversification | Simultaneous FDA Breakthrough Therapy and PMDA consultation submissions compress timeline risk across jurisdictions. |
| Manufacturing Scale-Up in European Clusters | Rhine-Ruhr and Basel-Zurich production networks supply injectable neuroprotective formulations across institutional markets. |
Research Methodology
Direct dialogue with drug development executives, regulatory affairs leads at FDA and EMA, hospital formulary directors, and nursing facility procurement managers grounded qualitative assessment in operational reality. Secondary validation drew from FDA Breakthrough Therapy designation filings, EMA PRIME scheme eligibility assessments, ClinicalTrials.gov vascular cognitive impairment protocol registrations, and CMS Medicare dementia care management reimbursement data. Bottom-up prescription volume modeling and top-down pharmaceutical revenue triangulation cross-checked segment-level estimates.
Bottom-up patient flow analysis by treatment line, administration route, and care setting combined with top-down therapeutic class revenue allocation across the projection horizon. CAGRs derived from segmented growth rate blending weighted by addressable population biomarker eligibility. Forecast inputs incorporated evolving diagnostic criteria adoption curves and remote patient monitoring technology penetration assumptions.
Caveats apply where biomarker standardization delays across FDA, EMA, and PMDA jurisdictions could materially shift the outlook for clinical endpoint design and regulatory approval timelines. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Peptide-Based Metabolic Disorders Therapeutics Market
Specialty Medicine
Chimeric Antigen Receptor (CAR) T-Cell Therapy Market
Specialty Medicine
Disruptive Behavior Disorder (DBD) Treatment Market
Specialty Medicine
Head and Neck Cancer Therapeutics Market
Specialty Medicine
Growth Hormone Deficiency Market
Specialty Medicine
Tularemia Therapeutics Market
Specialty Medicine
GCC Idiopathic Pulmonary Fibrosis Treatment Market
Specialty Medicine
China Ulcerative Colitis Market
Specialty Medicine
Global Breast Cancer Therapeutics Market
Specialty Medicine
Biliary Atresia Treatment Market
Specialty Medicine
Hermansky Pudlak Syndrome Therapeutics Market
Specialty Medicine
Global Endometrial Cancer Market
Specialty Medicine
Interstitial Lung Disease Treatment Market
Specialty Medicine
Transient Ischemic Attack Market
Specialty Medicine
Mitochondrial Disorders Treatment Market
Specialty Medicine
Cubital Tunnel Syndrome Market