
 Global Overactive Bladder Treatment Market | 2026-2036
Global Overactive Bladder Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Overactive Bladder Treatment Market Foresight
Hospital procurement committees are bifurcating between cost-driven antimuscarinic contracts and premium beta-3 agonist tenders. Astellas Pharma anchors its position through deep urology specialization across Asia-Pacific markets. Pfizer leverages established primary care channels to sustain volume in oral therapy segments. AbbVie differentiates via integrated access programs that link physician education with patient adherence monitoring.
Overactive bladder treatment encompasses pharmacological and device-based interventions targeting detrusor overactivity, with antimuscarinics functioning through M3 receptor antagonism to reduce involuntary contractions and neuromodulation devices delivering sacral nerve stimulation at 10-14 Hz frequencies to restore normal voiding patterns. The therapy area dimension shows medication segments occupying mature margin pools while combination therapy captures fastest-growing prescriber interest. Delivery mode analysis reveals oral formulations dominating script volume, though intravesical administration is gaining ground in refractory patient subsets where systemic side effect minimization drives clinical preference.
FDA's 505(b)(2) pathway and EMA's centralized pediatric investigation plans shape development timelines, while Japan's PMDA Sakigake designation accelerates novel mechanism approvals for unmet need populations. The EU Medical Device Regulation imposes strengthened clinical evidence requirements on neuromodulation systems, elevating barriers for new entrants. Stakeholders must monitor reimbursement parity decisions between oral pharmacotherapy and device-based interventions as health technology assessment bodies recalibrate value frameworks.
Market Dynamics
The FDA's 505(b)(2) pathway is compressing development timelines for reformulated urology drugs, while hospital procurement committees simultaneously bifurcate purchasing strategies between cost-driven antimuscarinic contracts and premium beta-3 agonist tenders.
Growth Catalysts
- Geriatric care infrastructure:Long-term care facilities in Japan and Germany are expanding combination therapy protocols for detrusor overactivity management. This institutional shift creates sustained demand pull for integrated pharmacological regimens.
- EMA's centralized pediatric investigation plans:The framework accelerates pediatric indication approvals for existing antimuscarinic compounds, opening previously restricted prescriber segments across EU member states.
- Sacral neuromodulation frequency optimization:Device manufacturers are refining 10-14 Hz stimulation parameters to improve voiding pattern restoration, driving clinical preference in refractory patient subsets.
Market Restraints
- Anticholinergic cognitive burden:The Beers Criteria restrictions on antimuscarinic use in elderly populations limit script volume expansion in Medicare-eligible demographics.
- Device reimbursement parity gaps:Health technology assessment bodies in Germany and France maintain divergent value frameworks for oral pharmacotherapy versus neuromodulation systems, creating access friction.
- Specialized urology nursing shortage:Sacral nerve lead placement and programming require trained interventionalists; workforce constraints bottleneck device adoption in community hospital settings.
Strategic Opportunities
- Intravesical administration protocols:Botulinum toxin instillation techniques are gaining prescriber interest in the United States for patients failing systemic therapy, minimizing anticholinergic side effect profiles.
- Japan's PMDA Sakigake designation:The fast-track mechanism rewards novel mechanism submissions for unmet need populations, compressing approval timelines for first-in-class beta-3 agonists.
- Continence management program integration:Dedicated reimbursement codes for multidisciplinary bladder care in US accountable care organizations are creating bundled payment opportunities.
Industry Challenges
- EU MDR clinical evidence requirements:The Medical Device Regulation mandates expanded trial data for neuromodulation system renewals, elevating regulatory compliance costs for manufacturers.
- Physician education-adherence linkage:Integrated access programs require simultaneous investment in prescriber training and patient monitoring infrastructure, straining commercial operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Overactive Bladder Treatment Market |
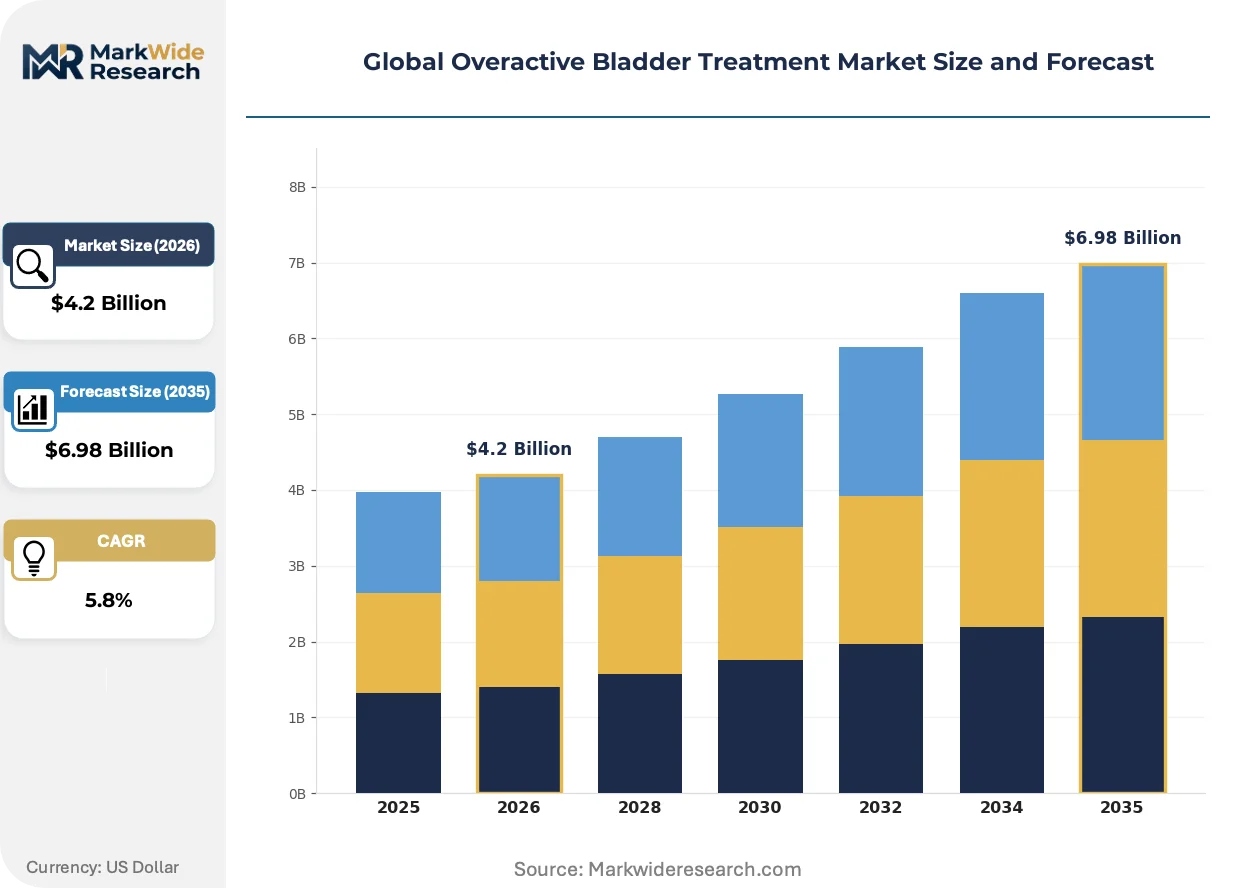
| Market Size in 2026 | $4.2 Billion |
| Market Size in 2035 | $6.98 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antimuscarinics, Beta-3 Agonists, Neuromodulation Devices, Botox Injections Therapy Area: Medication, Behavioral Therapy, Surgical Intervention, Combination Therapy End User: Hospitals, Clinics, Home Care, Rehabilitation Centers Delivery Mode: Oral, Injectable, Transdermal, Intravesical |
| Companies Covered | Astellas Pharma Inc., Pfizer Inc., AbbVie Inc., Medtronic, Teva Pharmaceutical Industries Ltd., Viatris Inc., Hisamitsu Pharmaceutical Co., Inc., Endo International plc, Sumitomo Pharma America, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Overactive Bladder Treatment Market Shifts & Advancements
Oral formulation dominance is fragmenting as delivery mode preferences split between systemic convenience and localized efficacy, with device-based interventions capturing prescriber attention in therapy-resistant populations.
Extended-release antimuscarinic formulations are bifurcating prescriber choice architecture. These once-daily compounds reduce dry mouth incidence through modified-release kinetics. Urologists in US academic medical centers are adopting them as first-line therapy for cognitively intact patients. The technology is bifurcating market share between convenience-optimized oral segments and efficacy-focused device alternatives.
REACH chemical safety assessments are reshaping excipient sourcing for transdermal oxybutynin patches. The framework imposes substance-of-very-high-concern screening on adhesive matrices and penetration enhancers. German and French formulators are reformulating patch compositions to maintain CE marking compliance, accelerating substitution toward polymer-based delivery platforms.
Hospital value analysis committees are consolidating vendor contracts for oral therapy categories while maintaining open tender processes for premium device segments. This bifurcated procurement model concentrates volume with established pharmaceutical suppliers in antimuscarinic categories. The pattern is most pronounced in US integrated delivery networks where pharmacy benefit managers influence therapeutic class standardization.
Global Overactive Bladder Treatment Market Segmentation
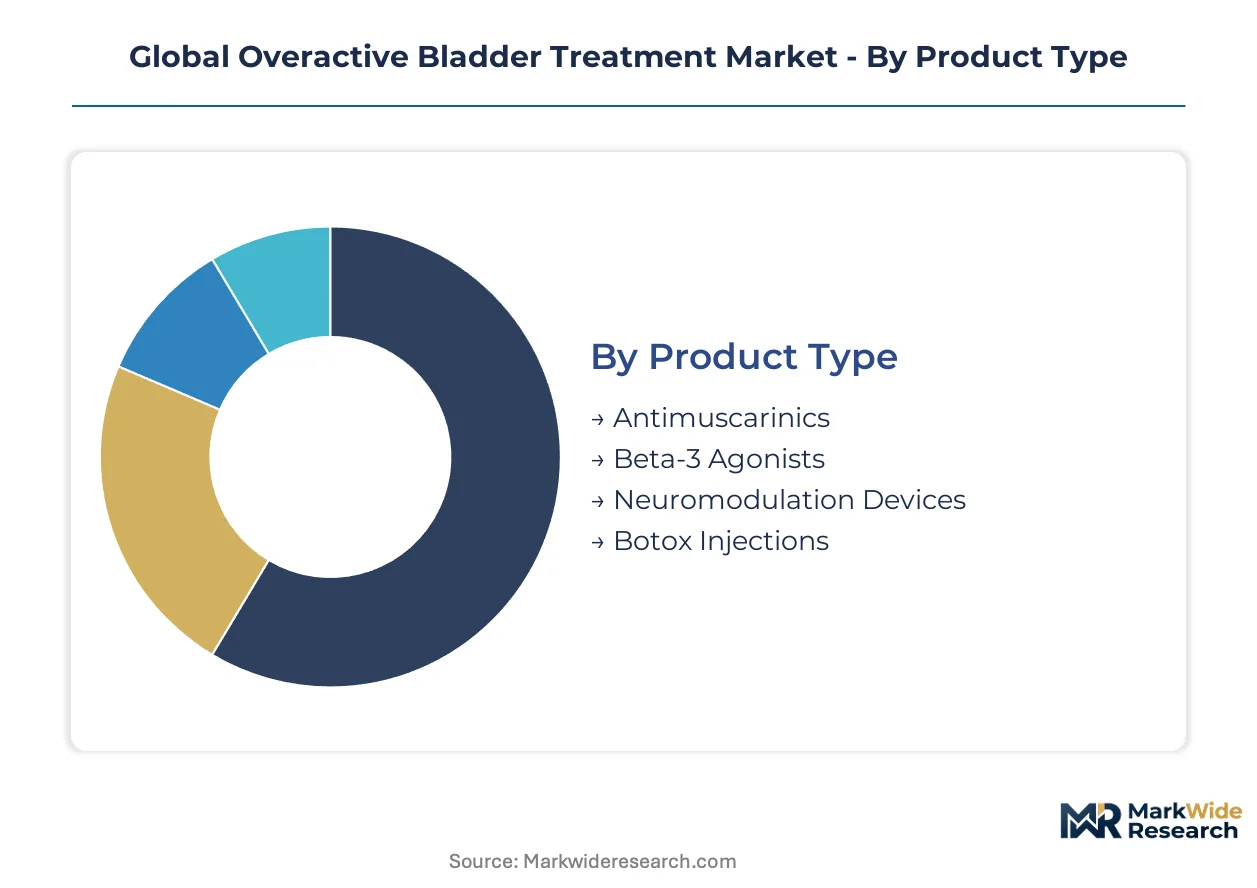
Treatment modality selection in overactive bladder care follows distinct geographic and institutional patterns. Hospital procurement committees, long-term care administrators, and urology specialists each drive demand through different segment combinations based on reimbursement frameworks and patient acuity.
Product Type:
Antimuscarinics dominate domestic prescription volumes in the United States and Japan, while beta-3 agonists and neuromodulation devices concentrate in export-led premium markets across Germany and Switzerland.
- Antimuscarinics:These M3 receptor antagonists reduce involuntary detrusor contractions through competitive muscarinic blockade. Demand concentrates in US Medicare populations and Japanese geriatric facilities where cost-driven formularies prioritize established oral therapies. The Beers Criteria restrictions on cognitive burden limit expansion in elderly demographics.
- Beta-3 Agonists:Mirabegron-class agents relax bladder smooth muscle through adrenergic receptor stimulation without anticholinergic side effects. Prescriber adoption accelerates in German university hospitals and US academic medical centers where cardiovascular safety profiles support use in polypharmacy patients. Japan's PMDA Sakigake designation compresses approval timelines for novel mechanism entrants.
- Neuromodulation Devices:Sacral nerve stimulation systems at 10-14 Hz frequencies restore coordinated voiding patterns. US and Swiss implant volumes lead as specialized interventional urology programs expand.
- Botox Injections:Intradetrusor botulinum toxin blocks acetylcholine release at neuromuscular junctions. OnabotulinumtoxinA demand clusters in French and UK tertiary referral centers for refractory cases.
Antimuscarinics hold the largest share; momentum sits with beta-3 agonists.
Therapy Area:
Cost tier stratification separates acute intervention budgets from chronic management allocations, with surgical segments commanding premium reimbursement while behavioral protocols operate at minimal marginal cost.
- Medication:Pharmacological first-line therapy encompasses oral antimuscarinics and beta-3 agonists prescribed through primary care and urology channels. Volume concentrates in US integrated delivery networks where pharmacy benefit managers standardize therapeutic class selection.
- Behavioral Therapy:Pelvic floor rehabilitation and bladder training protocols require specialized nursing infrastructure. German continence management programs and Japanese long-term care facilities embed these services in bundled reimbursement codes.
- Surgical Intervention:Augmentation cystoplasty and urinary diversion procedures address end-stage refractory disease. Demand localizes in high-volume academic centers across France, Italy, and the United States.
- Combination Therapy:Integrated pharmacological and device protocols optimize outcomes in complex patients. This segment expands most quickly in Japanese and German geriatric institutions deploying multidisciplinary care pathways.
Medication dominates absolute volume; combination therapy climbs the fastest.
End User:
Patient acuity and reimbursement sophistication determine institutional preference, with acute care hospitals managing complex device implants and home care settings absorbing stable maintenance therapy.
- Hospitals:Inpatient and outpatient surgical departments handle neuromodulation device implantation, botulinum toxin injection procedures, and complex diagnostic workups. US hospital value analysis committees bifurcate procurement between cost-driven antimuscarinic contracts and premium device tenders.
- Clinics:Ambulatory urology practices manage stable oral therapy titration and behavioral therapy supervision. French and German clinic networks concentrate prescriber decision-making for maintenance pharmacotherapy.
- Home Care:Long-term care facilities and domiciliary nursing services administer extended-release oral formulations and monitor adherence. Japanese geriatric care infrastructure drives sustained demand pull for convenient dosing regimens.
- Rehabilitation Centers:Post-acute facilities coordinate pelvic floor rehabilitation and neuromodulation programming adjustments. US Medicare skilled nursing facilities represent emerging sites for device maintenance.
Hospitals capture the highest procedure value; home care scales the broadest patient reach.
Delivery Mode:
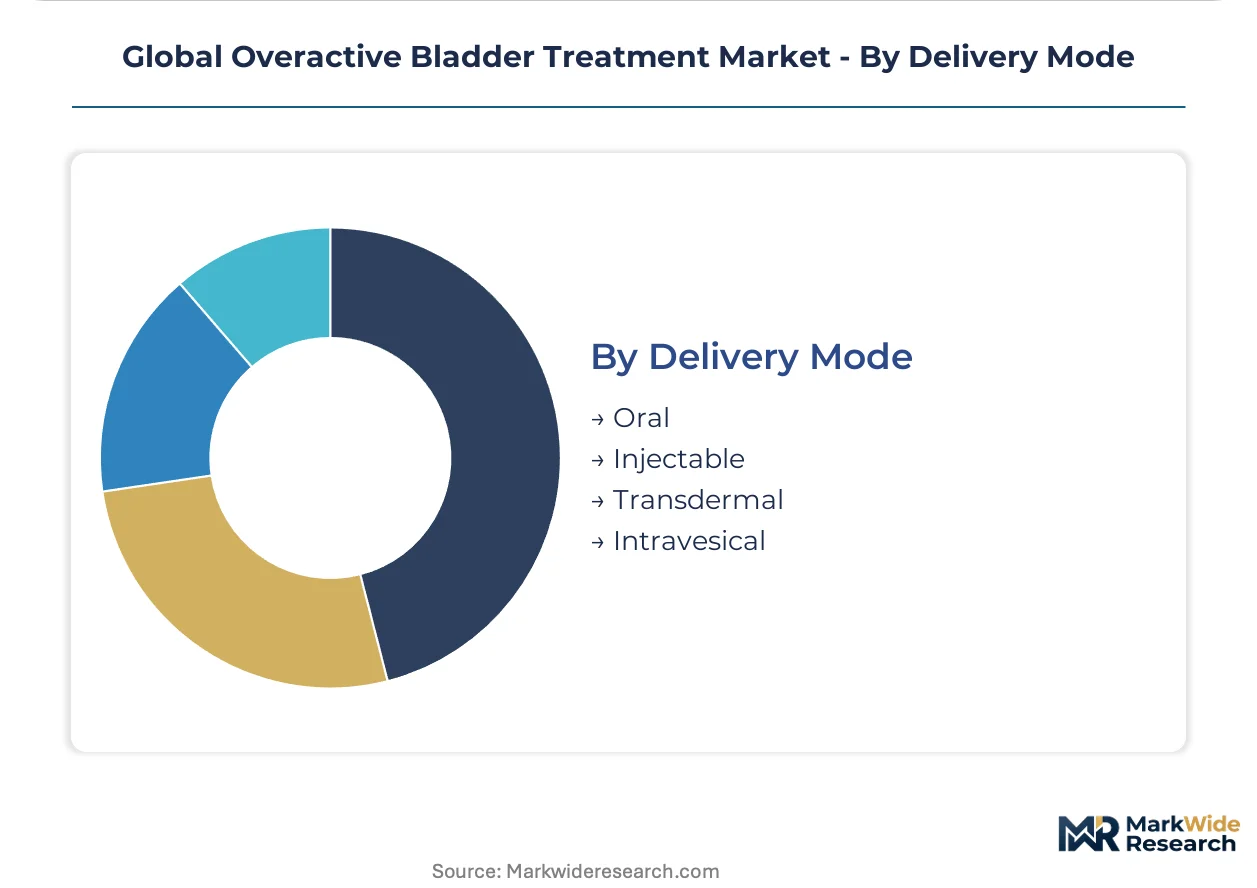
Systemic versus localized administration routes split along side effect tolerance and efficacy requirements, with oral convenience competing against targeted intervention in refractory populations.
- Oral:Extended-release tablets and capsules dominate script volume through modified-release kinetics that reduce dry mouth incidence. US academic medical centers adopt these as first-line therapy for cognitively intact patients.
- Injectable:Intramuscular and subcutaneous administration includes botulinum toxin and emerging gene therapy candidates. Tertiary centers in the United Kingdom and France specialize in injection protocol standardization.
- Transdermal:Oxybutynin patches bypass hepatic first-pass metabolism to minimize anticholinergic central effects. REACH chemical safety assessments are reshaping excipient sourcing for German and French formulators.
- Intravesical:Direct bladder instillation of botulinum toxin and investigational agents targets detrusor muscle with minimal systemic exposure. US academic urology programs pioneer instillation techniques for anticholinergic-intolerant patients.
Oral formulations maintain volume leadership; intravesical administration gains share fastest in refractory subsets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's pharmaceutical distribution infrastructure underwrites the Netherlands' role as Europe's urology drug logistics hub, channeling antimuscarinic and beta-3 agonist formulations to German and French hospital networks.
United States
Medicare Advantage penetration and accountable care organization bundling drive demand for combination therapy protocols. The FDA's 505(b)(2) pathway compresses approval timelines for reformulated urology drugs. The Cleveland Clinic and Mayo Clinic anchor specialized interventional urology programs that pioneer sacral neuromodulation implant volumes.
Germany
Hospital procurement committees bifurcate purchasing between cost-driven antimuscarinic contracts and premium beta-3 agonist tenders. The EU Medical Device Regulation imposes strengthened clinical evidence requirements on neuromodulation systems. The Rhine-Ruhr metropolitan region concentrates device implantation capacity across university hospitals in Düsseldorf and Cologne.
Japan
Long-term care facilities expand combination therapy protocols for detrusor overactivity management in aging populations. The PMDA Sakigake designation accelerates novel mechanism approvals for unmet need populations. Tokyo and Osaka metropolitan areas host specialized continence management programs that integrate pharmacological and behavioral interventions.
United Kingdom
NICE technology appraisals recalibrate value frameworks between oral pharmacotherapy and device-based interventions. The MHRA maintains parallel recognition pathways for EMA-approved urology indications post-Brexit. London's tertiary referral centers cluster botulinum toxin injection protocol standardization for refractory patient subsets.
Switzerland
Swissmedic's streamlined recognition of FDA and EMA approvals accelerates market entry for novel beta-3 agonists. Premium reimbursement frameworks support neuromodulation device adoption in polypharmacy patients. The Basel-Zurich corridor anchors pharmaceutical R&D concentration for next-generation bladder-targeted formulations.
Global Overactive Bladder Treatment Market Competitive Landscape
Listed leaders compete with private specialists across therapeutic modality and geographic footprint dimensions. The vendor base concentrates around three tiers: multinational pharmaceutical conglomerates with established urology divisions, device manufacturers with specialized interventional portfolios, and regional generic formulators competing on cost-driven tenders. Strategic archetypes include urology-dedicated specialists, primary care channel generalists, and integrated access program operators. Dominant competitive moves encompass portfolio diversification into combination therapy regimens and geographic expansion through regulatory pathway optimization.
Within the urology-dedicated specialist tier, Astellas Pharma Inc. and Hisamitsu Pharmaceutical Co., Inc. exemplify Asia-Pacific-origin players with deep regional specialization, while Medtronic occupies a position among device-centric interventional platforms. Pfizer Inc. and AbbVie Inc. represent primary care channel generalists leveraging established physician networks, and Teva Pharmaceutical Industries Ltd. anchors the generic formulator archetype competing on volume-driven contracts. These named entities illustrate competitive positioning without exhausting the participant base.
| Leading Market Players |
|---|
| Astellas Pharma Inc. |
| Pfizer Inc. |
| AbbVie Inc. |
| Medtronic |
| Teva Pharmaceutical Industries Ltd. |
| Viatris Inc. |
| Hisamitsu Pharmaceutical Co., Inc. |
| Endo International plc |
| Sumitomo Pharma America, Inc. |
| Others |
Supply & Pricing Matrix
Sixty-to-ninety-day API inventory buffers at German and Japanese finished-dose manufacturers concentrate pricing power with bulk antimuscarinic suppliers while compressing margins for neuromodulation device assemblers facing just-in-time component schedules. This lead-time asymmetry between oral pharmaceutical inputs and precision electronic hardware shapes divergent procurement strategies across hospital value analysis committees.
Pricing Analysis
Volume-discount tiering structures separate hospital procurement committees negotiating antimuscarinic contracts from academic medical centers tendering for beta-3 agonist and neuromodulation device access. Three-tier pricing stratifies across premium beta-3 agonist formulations, standard extended-release antimuscarinics, and economy generic oxybutynin. Cost compression in the generic tier intensifies as Indian and Chinese API suppliers expand capacity. Long-term care facilities demonstrate highest price sensitivity due to per-diem reimbursement constraints, while specialized interventional urology programs show lowest sensitivity for device-based interventions.
Supply Chain Analysis
Inventory concentration for critical antimuscarinic APIs rests on manufacturing clusters in India, China, and Italy, with finished-dose formulation and packaging distributed across Germany, Japan, and the United States. Active pharmaceutical ingredient sourcing draws from hyoscyamine plant extraction and synthetic tolterodine precursors, while neuromodulation device assembly depends on implantable pulse generator batteries and lead electrodes. Single-source vulnerability for sacral nerve stimulation battery cells creates supply chain risk. Distribution runs through pharmaceutical wholesale distributors and specialized medical device sales representatives into hospital procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through integrated delivery network consolidation in the United States and hospital alliance purchasing in Germany, shifting negotiating leverage toward formulary standardization and away from individual prescriber preference.
For Market Incumbents: Fortify formulary positioning through backward integration into API manufacturing for antimuscarinic compounds, securing supply continuity against Indian and Chinese competitor expansion. Deepen vertical control over extended-release formulation technology to defend margin position against generic erosion. Invest in FDA 505(b)(2) pathway expertise to accelerate reformulated product timelines before patent cliffs. For New Entrants and Emerging Players: Differentiate on intravesical administration protocols for anticholinergic-intolerant patient subsets, where prescriber interest is accelerating fastest. Target Japanese long-term care facilities through PMDA Sakigake fast-track submissions for novel beta-3 agonist mechanisms. Pursue hospital system partnership models that bundle device implantation with maintenance programming services. For Investors and Strategic Acquirers: Carve-out targets emerge from pharmaceutical conglomerates divesting mature urology divisions to focus on oncology and immunology pipelines. Mid-term viability through the next decade hinges on reimbursement parity between oral pharmacotherapy and neuromodulation systems. Monitor health technology assessment body decisions in Germany and France as inflection indicators for device segment expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway Optimization | FDA 505(b)(2) submissions compress timelines for reformulated antimuscarinics against standard NDA routes. |
| Hospital System Partnership | Integrated access programs linking Cleveland Clinic and Mayo Clinic urology networks secure device implant volume. |
| Manufacturing Scale-Up | Extended-release tablet capacity expansion in German Rhine-Ruhr region supports European antimuscarinic demand. |
| Pipeline Diversification | Combination therapy regimens integrating beta-3 agonists with behavioral protocols capture fastest-growing prescriber interest. |
| Reimbursement Strategy | Medicare Advantage bundled payment codes for continence management programs create sustainable revenue streams. |
Research Methodology
Desk research of FDA 505(b)(2) submission databases, EMA centralized pediatric investigation plans, and Japanese PMDA Sakigake approval records preceded structured interviews with hospital procurement managers, urology department heads, formulary directors, and medical device reimbursement specialists. Secondary validation drew from ClinicalTrials.gov protocol registries, CMS Medicare claims data, and EU Medical Device Regulation guidance documents. Bottom-up prescription volume modeling and top-down pharmaceutical revenue triangulation anchored market sizing.
Variance decomposition across therapy area, delivery mode, and end-user segments isolates growth contribution by dimension throughout the forecast period. The analytical framework models antimuscarinic versus beta-3 agonist share evolution, oral versus device-based intervention penetration, and geriatric care infrastructure expansion as core drivers. CAGRs derive from segment-level volume projections calibrated to regulatory approval timelines and reimbursement code adoption curves.
The analysis sits within stated boundaries; outcomes outside FDA 505(b)(2) pathway efficiency assumptions or EU MDR compliance cost trajectories would require recalibration. Forecasts reflect documented assumptions regarding PMDA Sakigake designation utilization rates and Medicare Advantage penetration curves. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Optic Atrophy Management Market
Specialty Medicine
Vascular Dementia Treatment Market
Specialty Medicine
Gingivostomatitis Market
Specialty Medicine
Overt Hepatic Encephalopathy Market
Specialty Medicine
Asbestosis Treatment Market
Specialty Medicine
Global Retinal Biologics Market
Specialty Medicine
Primary Immunodeficiency Market
Specialty Medicine
Global Urea Cycle Disorder Market
Specialty Medicine
Treatment-Resistance Depression Treatment Market
Specialty Medicine
Papillary Thyroid Cancer Market
Specialty Medicine
Radiation Toxicity Treatment Market
Specialty Medicine
Sports Medicine Market
Specialty Medicine
Global Alopecia Market
Specialty Medicine
Hepatic Encephalopathy Treatment Market
Specialty Medicine
Gallbladder Cancer Therapeutics Market
Specialty Medicine
Ankylosing Spondylitis Treatment Market