
 Stable Angina Management Market | 2026-2036
Stable Angina Management Market Size, Share, and Industry Trends Forecast 2026-2036
Stable Angina Management Market Analytics
European pharmaceutical manufacturers is expanding their output of antianginal active pharmaceutical ingredients to serve contract manufacturing demand across North America and Asia. AstraZeneca leverages its respiratory-cardiovascular crossover expertise to sustain pipeline momentum in fixed-dose combination therapies. Abbott Laboratories anchors its position through upstream control over coronary stent supply chains and catheter-based delivery systems. Novartis competes on the strength of its established beta-blocker and calcium channel blocker portfolios across mature markets.
Stable angina management encompasses the clinical and therapeutic interventions used to reduce myocardial oxygen demand, restore coronary perfusion, and prevent acute coronary syndrome progression in patients with chronic ischemic heart disease. Pharmacological regimens typically combine nitrates, beta-blockers, calcium channel antagonists, and antiplatelet agents to achieve hemodynamic stabilization and symptom relief. Medications occupy the largest value share within product type segmentation due to chronic dispensing patterns and generic substitution dynamics. The hybrid treatment approach is gaining structural prominence as payers demand evidence that procedural interventions are paired with optimized medical therapy. Cardiology clinics represent a concentrated margin pool among end users, given their capacity to perform diagnostic workup and interventional triage within single-visit workflows.
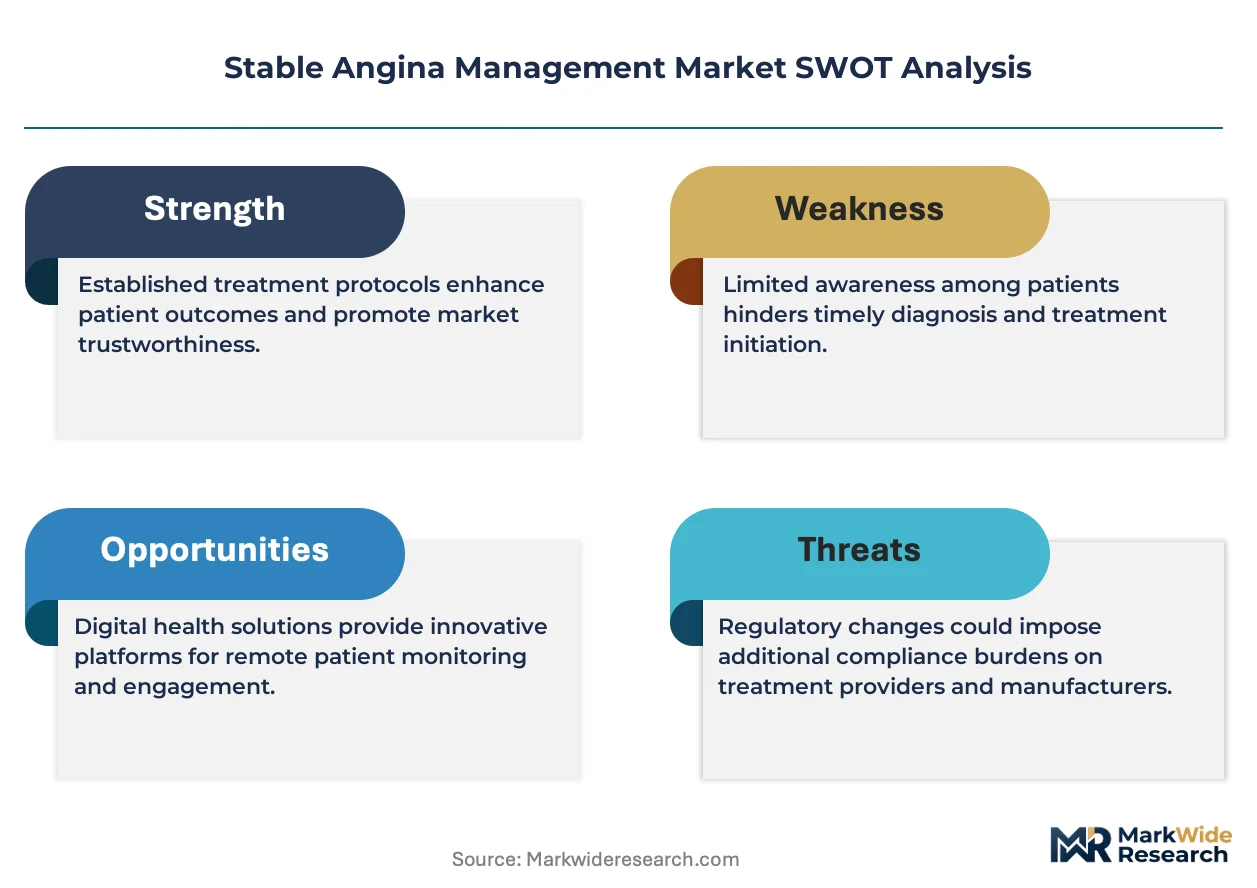
The FDA maintains stringent premarket approval requirements for coronary revascularization devices, while the EMA's Medical Device Regulation imposes enhanced clinical evidence standards that lengthen commercialization timelines. Japan's PMDA applies distinct pharmacovigilance protocols for antianginal agents that influence multinational trial design and labeling negotiations. Stakeholders must monitor how reimbursement authority consolidation across Medicare, national health services, and statutory insurers reshapes prescribing incentives and site-of-care migration.
Market Dynamics
Hybrid treatment protocols are compressing the traditional divide between pharmacological management and interventional cardiology, forcing device manufacturers and pharmaceutical suppliers to coordinate value demonstrations across single-episode reimbursement frameworks.
Growth Catalysts
- Japan's PMDA pharmacovigilance protocols:These distinct monitoring requirements for antianginal agents are accelerating multinational trial investments that generate robust safety datasets, expanding addressable patient populations for approved therapies.
- Cardiology clinic consolidation:Single-visit diagnostic and interventional workflows are concentrating patient throughput, creating captive demand channels for integrated device-drug protocols.
- Fixed-dose combination therapies:Respiratory-cardiovascular crossover expertise is enabling novel beta-blocker and calcium channel antagonist formulations that reduce pill burden and improve adherence metrics.
Market Restraints
- EMA Medical Device Regulation clinical evidence standards:Enhanced documentation requirements are lengthening commercialization timelines for coronary revascularization devices, compressing effective patent life.
- Generic substitution dynamics:Chronic dispensing patterns for nitrates and antiplatelet agents are eroding branded pricing power across mature markets.
- Coronary stent supply chain concentration:Upstream control over catheter-based delivery systems rests with a limited supplier base, creating procurement vulnerability for downstream manufacturers.
Strategic Opportunities
- Preventive cardiac care infrastructure in Germany:Statutory insurer investment in ambulatory monitoring is opening reimbursement pathways for remote ischemia detection technologies.
- United States Medicare reimbursement authority consolidation:Site-of-care migration incentives are favoring integrated clinic-hospital networks that can bundle diagnostic and interventional services.
- Digital therapeutics convergence:Wearable hemodynamic monitoring is converging with algorithmic risk stratification to enable pre-symptomatic intervention protocols.
Industry Challenges
- FDA premarket approval evidentiary requirements:Coronary revascularization device submissions demand extensive clinical trial infrastructure that strains mid-cap development budgets.
- Legacy electronic health record integration:Hybrid protocol documentation across pharmacy and procedural billing systems requires expensive workflow reconfiguration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stable Angina Management Market |
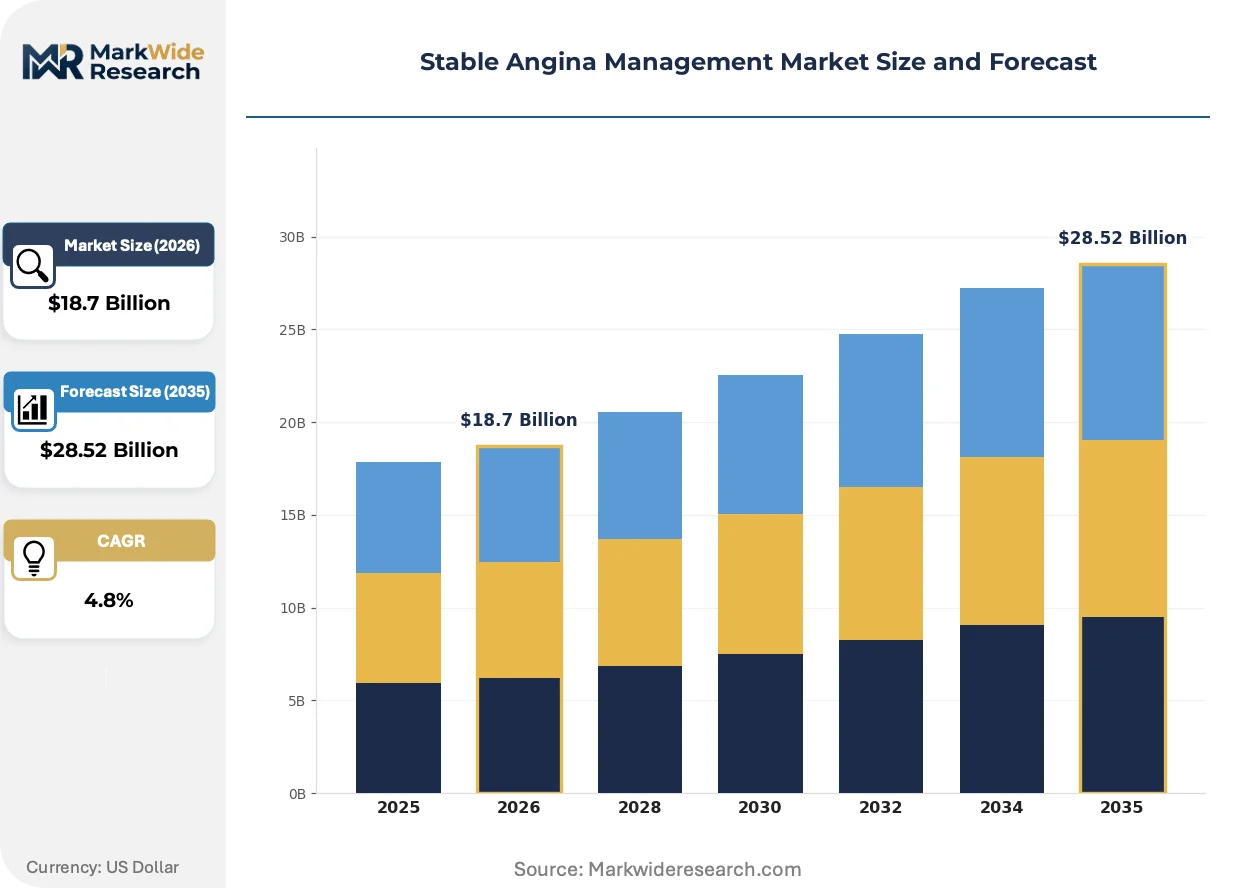
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medications, Medical Devices, Lifestyle Programs, Surgical Procedures End User: Hospitals, Cardiology Clinics, Home Healthcare, Rehabilitation Centers Treatment Approach: Pharmacological, Non-Pharmacological, Hybrid, Preventive Care Delivery Mode: Oral, Injectable, Transdermal, Intravenous |
| Companies Covered | Bayer AG, Johnson & Johnson, AstraZeneca, Bristol-Myers Squibb, Abbott Laboratories, Novartis AG, Gilead Sciences, Sanofi, Pfizer Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stable Angina Management Market Evolving Landscape
Computational physiology and miniaturized sensor platforms are displacing static risk scores with dynamic ischemia prediction models that reshape how cardiology clinics triage stable angina patients.
Fractional flow reserve computed tomography is converging with machine-interpreted coronary angiography to reduce unnecessary catheterization procedures. Cardiology clinics in the United States and Japan are adopting these hybrid imaging protocols at accelerating pace. The structural consequence is converging with traditional interventional referral patterns, compressing diagnostic episode costs while elevating demand for contrast agents and computational software licenses.
The EU Medical Device Regulation imposes post-market surveillance obligations that extend liability exposure for coronary stent manufacturers across the entire product lifecycle. Industrial consequence includes mandatory clinical follow-up registries that increase fixed compliance costs. High-risk device categories are responding by consolidating under larger entities with dedicated regulatory affairs infrastructure.
Site-of-care economics now dominate procurement decisions as payers demand documentation that procedural interventions occurred only after optimized medical therapy failure. United States cardiology clinics are unbundling after-sales device support from capital equipment purchases, shifting toward per-procedure service agreements. This behavioral pivot is most visible in Medicare Advantage networks where episode-based reimbursement creates direct accountability for total cost of care.
Stable Angina Management Market Segmentation
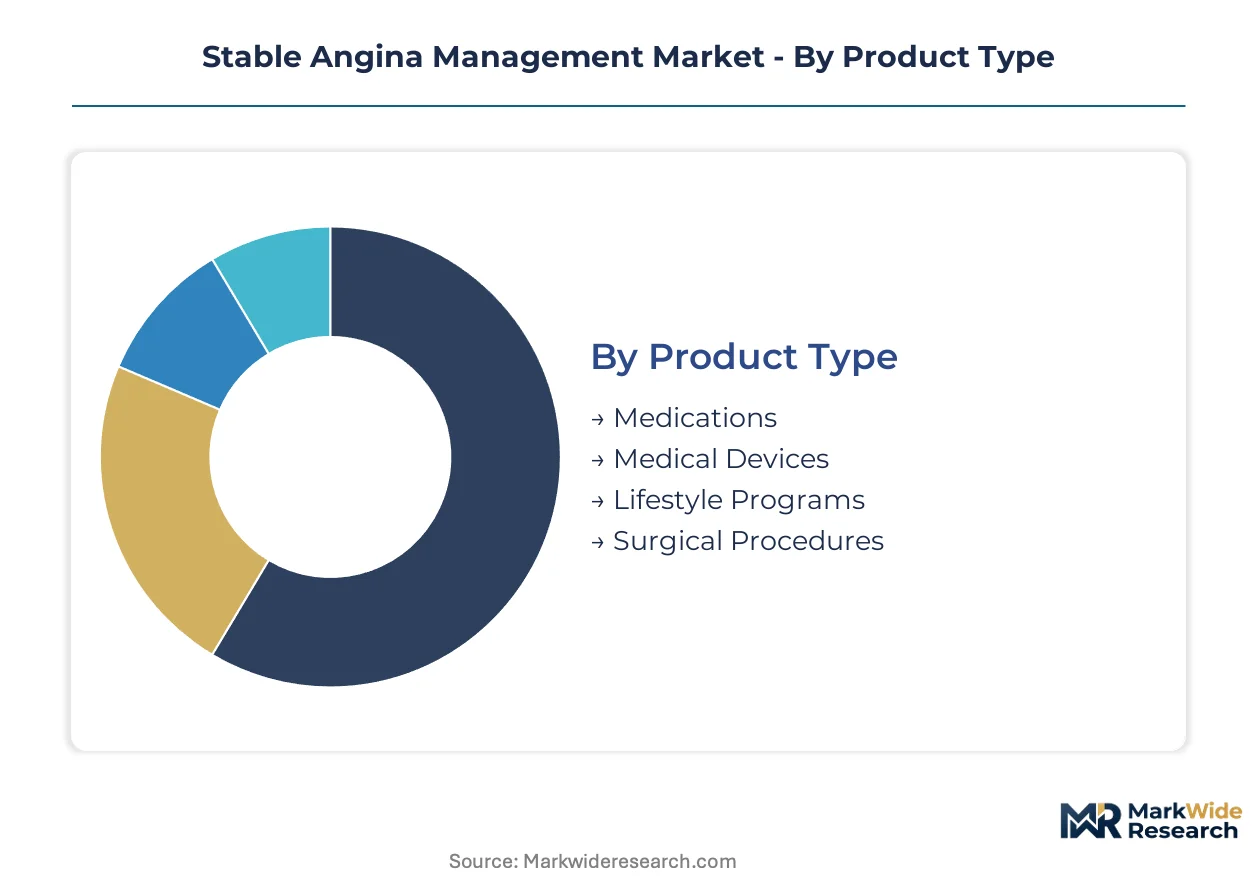
Segmentation in stable angina management reveals how therapeutic value migrates across integrated care pathways. Product and delivery distinctions matter less than whether interventions operate within single-visit workflows or span fragmented provider networks.
Product Type:
Integration depth separates chronic maintenance therapies from acute procedural interventions, with embedded diagnostic-procedural systems commanding premium positioning against standalone pharmaceutical dispensing.
- Medications:Nitrates, beta-blockers, calcium channel antagonists, and antiplatelet agents form the chronic backbone of symptom control. Demand concentrates in cardiology clinics across the United States, Germany, and Japan where payers require documented failure of optimized medical therapy before authorizing procedural escalation.
- Medical Devices:Coronary stents, catheter-based delivery systems, and hemodynamic monitoring platforms enable mechanical revascularization. Procurement in Medicare Advantage networks is shifting toward per-procedure service agreements that bundle capital equipment with consumables and technical support.
- Lifestyle Programs:Structured cardiac rehabilitation and risk-factor modification protocols reduce recurrent events through supervised exercise and dietary intervention.
- Surgical Procedures:Coronary artery bypass grafting remains reserved for complex multivessel disease when percutaneous approaches prove anatomically unsuitable.
Medications lead volumes today; medical devices are gaining share fastest as hybrid protocols elevate procedural intensity.
End User:
Cost tier stratification distinguishes capital-intensive hospital infrastructures from ambulatory settings optimized for episode-based reimbursement.
- Hospitals:Acute care facilities manage unstable presentations and complex comorbidities requiring surgical backup. Emergency department throughput in the United States is compressing as site-of-care migration incentives favor integrated clinic-hospital networks.
- Cardiology Clinics:Specialized ambulatory centers combine diagnostic workup with interventional triage within single-visit workflows. Japan's PMDA pharmacovigilance protocols for antianginal agents are accelerating multinational trial investments that expand addressable populations for approved therapies.
- Home Healthcare:Remote monitoring and visiting nurse services extend chronic disease management beyond facility walls.
- Rehabilitation Centers:Post-event structured programs restore functional capacity and modify behavioral risk factors.
Cardiology clinics lead volumes today; home healthcare is climbing the fastest as wearable hemodynamic monitoring enables pre-symptomatic intervention protocols.
Treatment Approach:
Application logic governs whether patients progress through sequential therapy intensification or receive concurrent multimodal intervention from diagnosis.
- Pharmacological:Drug-based regimens reduce myocardial oxygen demand and prevent acute coronary syndrome progression. Generic substitution dynamics in Germany and the United States are eroding branded pricing power for nitrates and antiplatelet agents.
- Non-Pharmacological:Revascularization procedures and device-based interventions restore coronary perfusion mechanically. EMA Medical Device Regulation clinical evidence standards are lengthening commercialization timelines for coronary revascularization devices.
- Hybrid:Coordinated drug-device protocols pair optimized medical therapy with selective procedural intervention. Payers now demand documentation that catheterization occurred only after documented pharmacological failure.
- Preventive Care:Risk stratification and lifestyle modification aim to delay or prevent symptomatic disease onset.
Pharmacological approaches lead volumes today; hybrid protocols show the steepest expansion trajectory as reimbursement frameworks bundle diagnostic and interventional services.
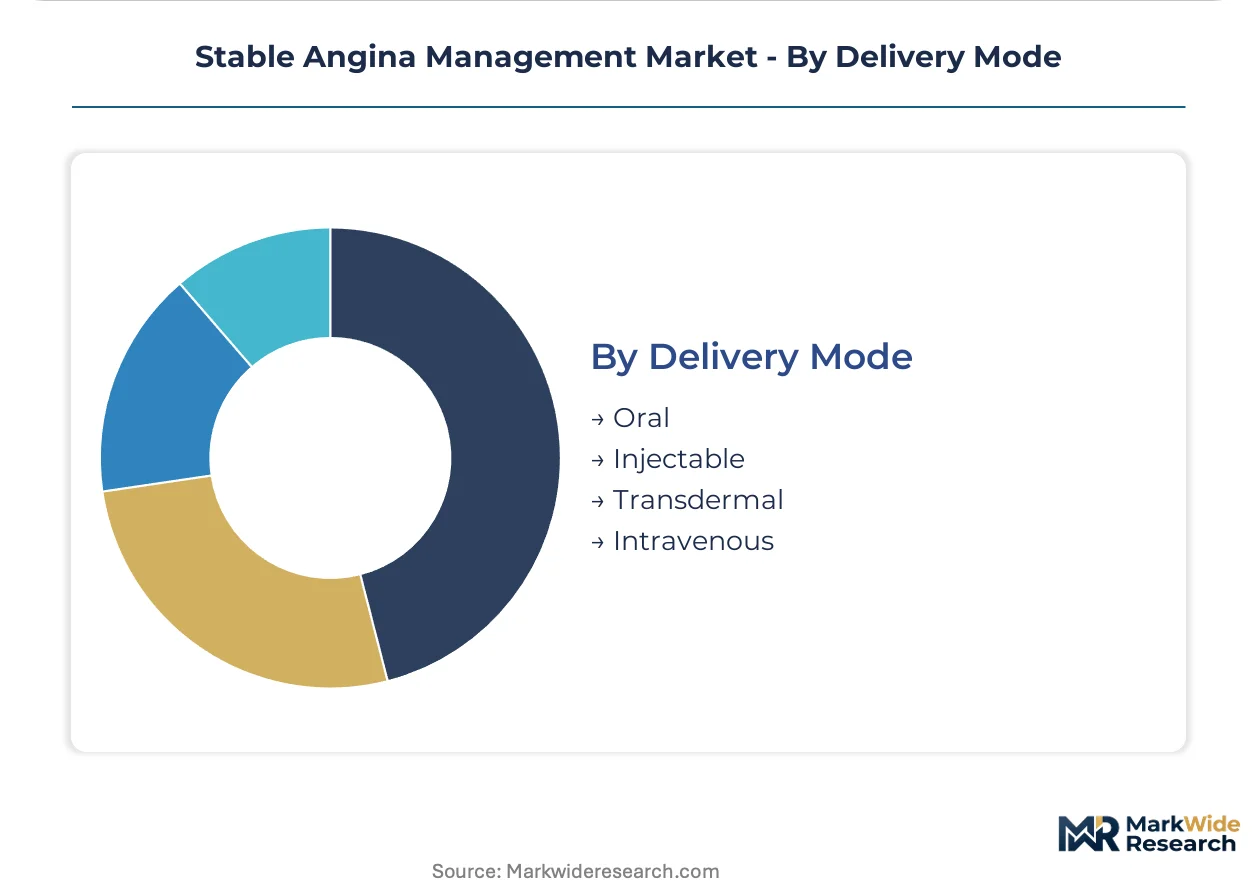
Delivery Mode:
Volume concentration reflects chronic maintenance patterns versus acute rescue requirements, with patient adherence and pharmacokinetic profiles driving route selection.
- Oral:Tablets and capsules dominate chronic maintenance regimens for beta-blockers, calcium channel antagonists, and long-acting nitrates. Fixed-dose combination formulations are reducing pill burden and improving adherence metrics in cardiology clinic populations.
- Injectable:Subcutaneous and intramuscular routes enable rapid onset for acute symptom breakthrough. Antianginal agent development programs are incorporating Japan's PMDA distinct pharmacovigilance requirements into multinational trial designs.
- Transdermal:Nitroglycerin patches provide sustained vasodilation with reduced first-pass metabolism.
- Intravenous:Hospital-based infusion enables precise titration during unstable presentations or peri-procedural management.
Oral delivery leads volumes today; transdermal systems are expanding most quickly as patient convenience preferences reshape chronic dispensing patterns.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting production investment toward jurisdictions where cardiovascular device approval costs diverge sharply. European manufacturers exploit EMA clinical evidence standards to command premium positioning, while Japanese and American firms leverage pharmacovigilance protocol harmonization to compress trial timelines.
United States
Medicare Advantage networks are consolidating site-of-care authority into integrated clinic-hospital systems. FDA premarket approval requirements for coronary revascularization devices demand extensive clinical infrastructure that favors large-cap developers. The Minneapolis-Cleveland cardiac device corridor concentrates stent manufacturing and catheter-based delivery system assembly.
Germany
Statutory insurers are deepening investment in ambulatory preventive cardiac care infrastructure. EMA Medical Device Regulation post-market surveillance obligations extend liability exposure across entire product lifecycles. The Rhine-Ruhr industrial cluster hosts specialized contract manufacturers of antianginal active pharmaceutical ingredients serving North American demand.
Japan
PMDA pharmacovigilance protocols for antianginal agents are accelerating multinational trial investments that expand approved therapy populations. Distinct safety monitoring requirements influence global labeling negotiations and trial design. The Kanto region around Tokyo anchors domestic pharmaceutical formulation and cardiovascular device distribution.
United Kingdom
National Health Service reimbursement consolidation is reshaping prescribing incentives toward optimized medical therapy documentation. MHRA post-Brexit regulatory autonomy is diverging from EMA timelines for coronary intervention devices. The Cambridge-Oxford-London life sciences triangle concentrates hybrid protocol research and digital therapeutics development.
Switzerland
Swissmedic maintains stringent device approval standards that reinforce premium positioning for cardiovascular manufacturers. The country's statutory health insurance framework favors evidence-based hybrid treatment protocols. Basel and Zurich host headquarters operations for major beta-blocker and calcium channel blocker portfolio holders.
Stable Angina Management Market Competitive Landscape
United States producers anchor one tier; European specialists hold another through regulatory expertise and API manufacturing scale. The vendor base stratifies across three tiers: integrated pharmaceutical-device conglomerates, pure-play cardiovascular device manufacturers, and contract service providers. Two dominant competitive moves are reshaping positioning: backward integration into coronary stent supply chains and strategic partnerships to bundle diagnostic software with interventional hardware.
Within the respiratory-cardiovascular crossover tier, AstraZeneca exemplifies fixed-dose combination therapy development. Among diversified medical technology conglomerates, Abbott Laboratories anchors upstream control over catheter-based delivery systems. Novartis occupies a position exemplifying established beta-blocker and calcium channel blocker portfolio strength across mature markets. These three represent distinct archetypes: therapeutic class consolidation, device supply chain captivity, and legacy cardiovascular pharmaceutical maintenance.
| Leading Market Players |
|---|
| Bayer AG |
| Johnson & Johnson |
| AstraZeneca |
| Bristol-Myers Squibb |
| Abbott Laboratories |
| Novartis AG |
| Gilead Sciences |
| Sanofi |
| Pfizer Inc. |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up cardiology device specialists now control catheter-based delivery system manufacturing, concentrating procurement leverage among three platform owners who impose strict pricing discipline on downstream stent assemblers while extracting per-procedure service premiums from Medicare Advantage networks.
Pricing Analysis
Distributor margins on antianginal medications compress branded pricing power as generic substitution dynamics in Germany and the United States accelerate chronic dispensing shifts toward unbranded nitrates and antiplatelet agents. Three-tier pricing structure across premium drug-device combinations, standard pharmacological regimens, and economy generic portfolios reflects FDA certification tiers and volume scale. Pricing pressure stems from statutory insurer demands for documented optimized medical therapy failure before procedural authorization. Hospital purchasing committees exhibit highest price sensitivity; integrated clinic-hospital networks command lowest due to episode-based reimbursement bundling.
Supply Chain Analysis
Domestic-content mandates in Japan's PMDA pharmacovigilance protocols are reshaping multinational trial sourcing toward local clinical research organizations and domestic formulation facilities. Active pharmaceutical ingredient production concentrates in India, China, and Germany's Rhine-Ruhr cluster, drawing from specialized chemical precursors, sterile manufacturing equipment, and cold-chain logistics infrastructure. Single-source vulnerability in coronary stent supply chains creates procurement risk as upstream catheter component production rests with limited qualified suppliers. Distribution runs through cardiology clinic networks with direct-to-hospital bypass for emergency revascularization devices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The stable angina management market functions as a stable compounder anchored by irreversible demographic shifts toward aging populations with chronic ischemic burden, ensuring sustained demand for maintenance therapies and selective procedural interventions.
For Market Incumbents: To counter generic substitution erosion in nitrates and antiplatelet agents, pharmaceutical incumbents should deepen backward integration into antianginal active pharmaceutical ingredient manufacturing and secure captive supply of fixed-dose combination precursors. Device manufacturers must consolidate coronary stent supply chains through exclusive catheter-based delivery system partnerships that lock in cardiology clinic procurement committees. For New Entrants and Emerging Players: Contract manufacturing organizations represent the most accessible channel partner type for mid-cap entrants seeking white-space positioning in lifestyle program delivery and remote hemodynamic monitoring services. Preventive cardiac care infrastructure in Germany's statutory insurer networks offers the most penetrable geography, with digital therapeutics convergence providing the clearest go-to-market angle through algorithmic risk stratification software licensing. For Investors and Strategic Acquirers: Valuations sit cheapest among pure-play cardiovascular device manufacturers lacking integrated pharmaceutical portfolios, presenting acquisition targets with embedded regulatory affairs infrastructure for EMA Medical Device Regulation compliance. Long-term viability favors hybrid protocol enablers that bridge diagnostic software with interventional hardware. The signal to watch is Medicare reimbursement authority consolidation accelerating site-of-care migration toward bundled service networks.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Premarket Approval Pathway | Extensive clinical trial infrastructure demands favor large-cap developers with dedicated regulatory affairs teams. |
| EMA CE Marking Pathway | Enhanced clinical evidence standards lengthen commercialization timelines and compress effective patent life for coronary revascularization devices. |
| Hospital System Partnership | Integrated clinic-hospital networks bundle diagnostic and interventional services under episode-based reimbursement frameworks. |
| Software Companion Development | Machine-interpreted coronary angiography platforms reduce unnecessary catheterization and elevate contrast agent demand. |
| Reimbursement Strategy | Medicare Advantage site-of-care migration incentives favor networks documenting optimized medical therapy failure before procedural escalation. |
Research Methodology
Coverage spans the United States, Germany, Japan, the United Kingdom, and Switzerland, with primary inputs from each market through structured interviews with cardiology clinic directors, hospital purchasing committee members, regulatory affairs leads at cardiovascular device manufacturers, and formulary directors at statutory insurers. Secondary validation draws from FDA premarket approval filings, EMA Medical Device Regulation submission databases, Japan PMDA pharmacovigilance protocols, CMS Medicare reimbursement data, and GPO contract repositories. Bottom-up patient population modeling triangulates against top-down pharmaceutical dispensing and device shipment data.
Granularity-level modeling operates at the treatment approach dimension (pharmacological, non-pharmacological, hybrid, preventive care) crossed with end-user facility type (hospital, cardiology clinic, home healthcare, rehabilitation center) and regional regulatory cluster (FDA, EMA, PMDA, MHRA, Swissmedic jurisdictions). CAGRs derive from log-linear trend fitting across the projection horizon, incorporating antianginal agent patent expiry schedules, coronary stent innovation cycles, and ambulatory monitoring technology adoption curves as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA premarket approval evidentiary requirement shifts, EMA post-market surveillance obligation expansions, and statutory insurer hybrid protocol reimbursement consolidation. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular
High-Sensitivity Cardiac Biomarker Market
Cardiovascular
Heart Block Therapeutics Market
Cardiovascular
Coronary Artery Disease Therapeutics Market
Cardiovascular
Antihypertensive Market
Cardiovascular
Cardiac Troponin Market
Cardiovascular
Global Hypotension Treatment Market
Cardiovascular
Myocarditis Disease Market
Cardiovascular
Middle East and Africa Acute Coronary Syndrome Market
Cardiovascular
Global Deep Vein Thrombosis Market
Cardiovascular
Brugada Syndrome Treatment Market
Cardiovascular
Cardiac Arrhythmia Therapeutics Market
Cardiovascular
Bifurcation Lesions Market
Cardiovascular
Cardiac Safety Services Market
Cardiovascular
Acute Coronary Syndrome (ACS) Market
Cardiovascular
Angina Market
Cardiovascular
Myocardial Infarction Market