
 Positive Displacement Blowers Market | 2026-2036
Positive Displacement Blowers Market Size, Share, and Industry Trends Forecast 2026-2036
Positive Displacement Blowers Market Analysis
Wastewater treatment is shifting toward higher-capacity aeration systems as municipalities upgrade aging infrastructure. Aerzen dominates European blower supply through its specialized rotary lobe engineering. Ingersoll Rand leverages its compressor distribution network to cross-sell positive displacement units into North American industrial accounts. Gardner Denver sustains aftermarket revenue through extensive service contracts on installed vacuum generation equipment.
Positive displacement blowers are volumetric machines that trap and displace fixed air pockets through rotating lobes, vanes, or diaphragms, typically delivering pressures up to 15 psig and flow rates suited to continuous-duty industrial processes. Their primary purpose is to provide oil-free, pulsation-controlled air or gas movement for aeration, material transport, and vacuum duties. Roots blowers occupy the largest installed base due to decades of proven performance in municipal water plants, while sliding vane blowers capture margin pools in chemical processing where pulsation sensitivity demands smoother discharge profiles. Diaphragm blowers are gaining traction in pharmaceutical cleanrooms where oil contamination risks override efficiency considerations.
EPA effluent limitations and EU Urban Wastewater Treatment Directive revisions are forcing utilities toward energy-efficient aeration retrofits, directly shaping blower procurement specifications. OSHA noise exposure standards and EU machinery safety directives constrain equipment design, pushing manufacturers toward acoustic enclosure integration and variable-speed electric drives. Stakeholders must weigh total lifecycle costs against capital outlays as energy efficiency regulations tighten and electric technology displaces legacy mechanical drives across installed fleets.
Market Dynamics
Energy-efficiency mandates from the EPA and EU Urban Wastewater Treatment Directive are forcing utilities toward aeration retrofits. Variable-speed electric drives and acoustic enclosures now dominate procurement specifications as lifecycle cost calculations displace simple capital outlay decisions.
Growth Catalysts
- EU effluent standards:The Urban Wastewater Treatment Directive revisions compel German and French utilities to expand blower fleets for enhanced biological nutrient removal.
- Pneumatic conveying systems:Food processing capacity expansion across China's coastal industrial zones concentrates demand for oil-free rotary lobe units.
- India's chemical manufacturing:Cluster development in Gujarat and Maharashtra drives procurement of sliding vane blowers for pulsation-sensitive discharge applications.
Market Restraints
- Permanent magnet motor costs:Rare earth price volatility from Chinese supply concentration inflates variable-speed drive premiums by double-digit percentages.
- Roots blower technical ceiling:Fixed displacement geometry limits pressure rise efficiency above 10 psig, ceding high-pressure applications to screw compressors.
- CE marking machinery safety:Acoustic enclosure and guarding requirements extend European certification timelines by four to six months.
Strategic Opportunities
- Saudi wastewater infrastructure:NEOM and Red Sea Project developments create greenfield demand for modular aeration packages.
- Pharmaceutical cleanrooms:Oil-free diaphragm blowers capture specification share as FDA sterile manufacturing guidelines tighten contamination protocols.
- IoT-enabled predictive maintenance:Vibration and temperature sensor convergence with cloud analytics opens aftermarket service revenue streams.
Industry Challenges
- Rotordynamics specialization:Declining numbers of engineers trained in lobe profile optimization and bearing load analysis constrain R&D throughput.
- Legacy control system integration:SCADA retrofits for variable-frequency drives demand custom programming across decades-old municipal installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Positive Displacement Blowers Market |
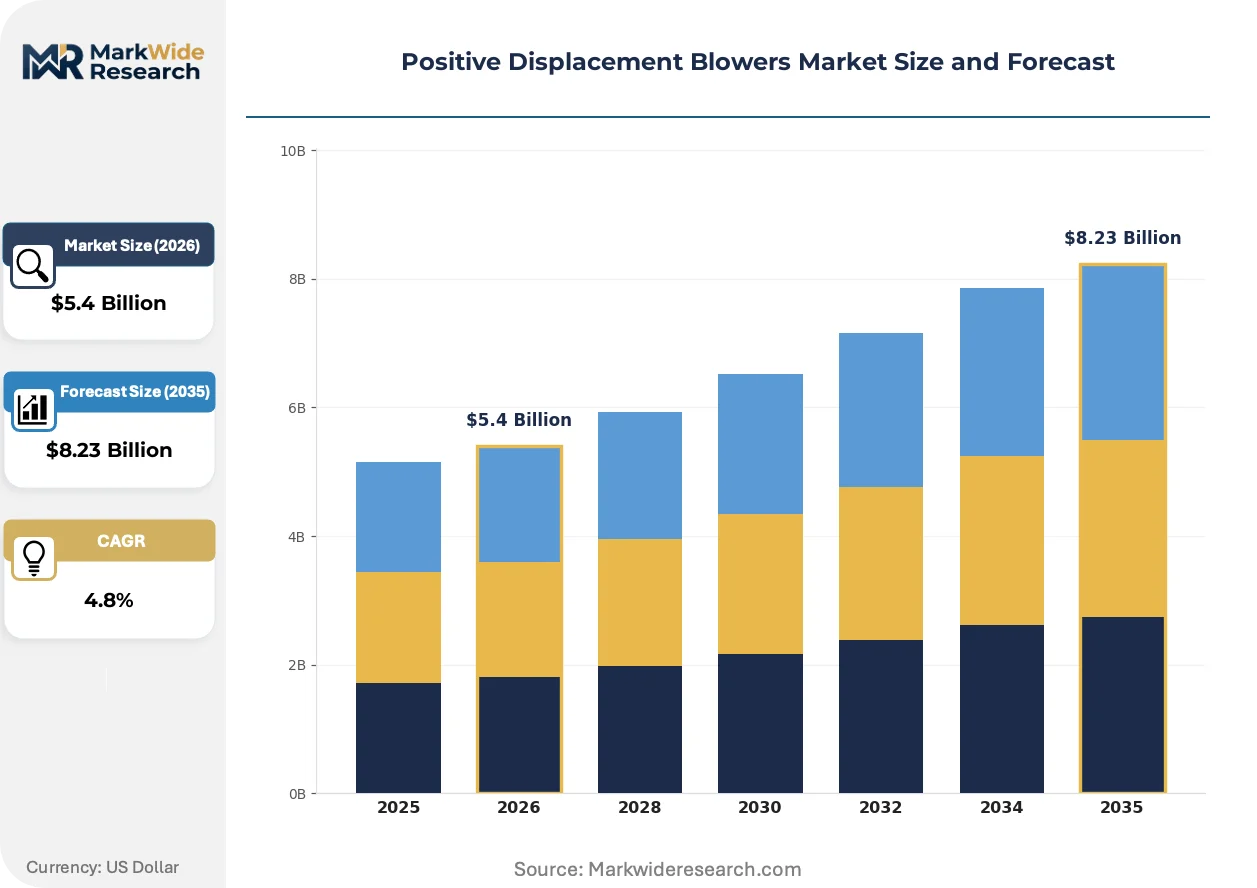
| Market Size in 2026 | $5.4 Billion |
| Market Size in 2035 | $8.23 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Roots Blowers, Sliding Vane Blowers, Mobeal Blowers, Diaphragm Blowers End User: Wastewater Treatment, Chemical Processing, Food & Beverage, Pharmaceuticals Application: Aeration, Pneumatic Conveying, Gas Handling, Vacuum Generation Technology: Mechanical, Electric, Hydraulic, Hybrid |
| Companies Covered | Eurus Blowers, Aerzen, Hitachi Ltd., Tuthill Corporation, Ingersoll Rand, Busch SE, Howden Group, Aerzener Maschinenfabrik GmbH, Gardner Denver, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Positive Displacement Blowers Market Emerging Trajectories
Digitalization and electrification are compressing equipment lifecycles while expanding performance monitoring capabilities. Manufacturers now compete on total cost of ownership rather than unit price alone.
Magnetically levitated turbo blowers are decentralizing aeration system architecture in large-scale wastewater plants. Dutch and Danish utilities operating above 100,000 population-equivalent capacity are adopting these units for their 15-20% energy savings over rotary lobe alternatives. The technology is decentralizing blower station design by enabling distributed aeration zones without header pressure losses.
EPA effluent limitation guidelines are tightening phosphorus and nitrogen discharge thresholds for municipal treatment works. These rules force aeration capacity upgrades across 16,000 US publicly owned treatment facilities. Package plant OEMs in the Ohio River Valley and Great Lakes regions are responding with pre-engineered blower skids that compress installation timelines.
Service contract unbundling is fragmenting traditional aftermarket relationships. Industrial buyers in chemical processing now procure spare rotors and bearings through independent distributors rather than captive OEM channels. This pattern is most visible in Germany's Ruhr industrial cluster, where maintenance departments maintain multi-brand spare inventories to minimize downtime exposure.
Positive Displacement Blowers Market Segmentation
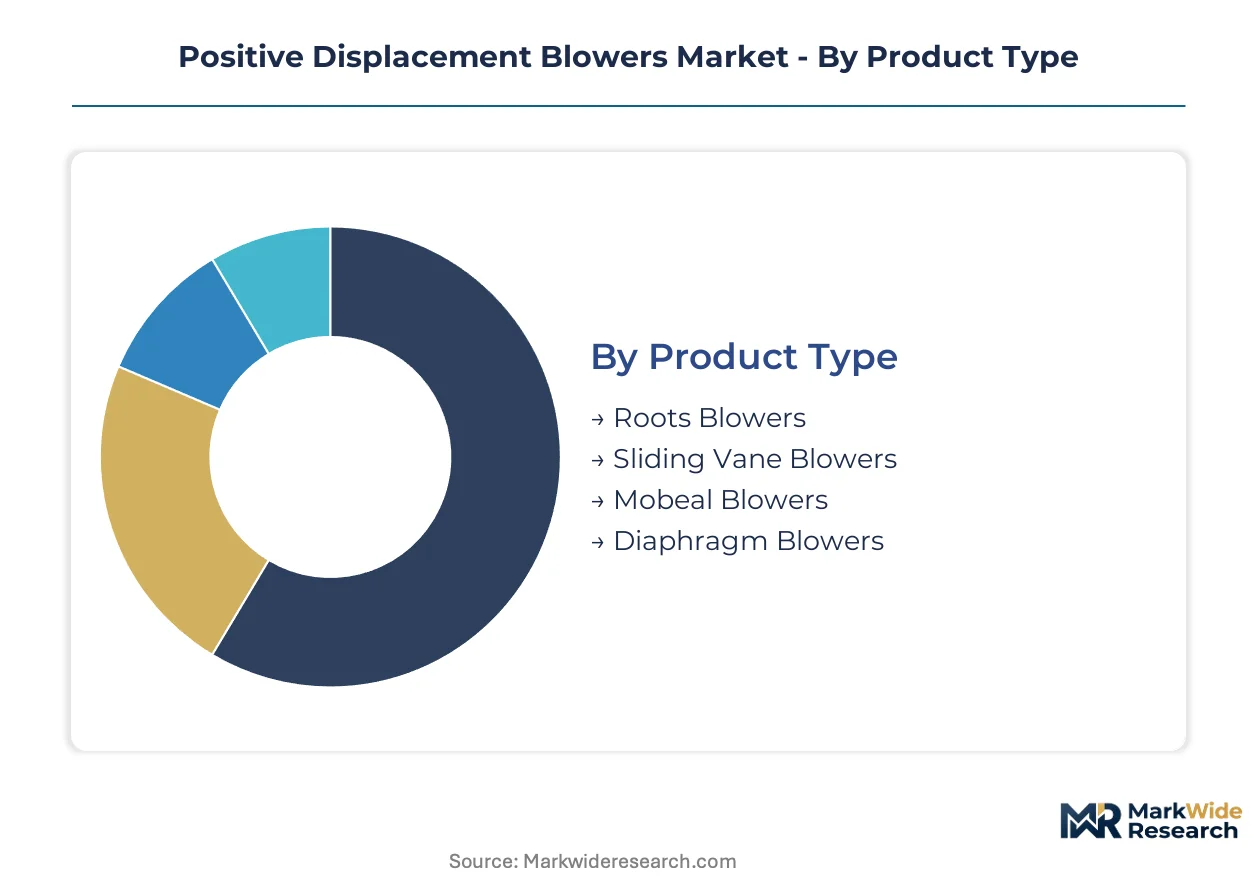
Positive displacement blower procurement varies sharply by duty cycle, contamination tolerance, and energy efficiency requirements. Understanding segment boundaries clarifies why wastewater utilities favor rotary lobe architectures while pharmaceutical cleanrooms specify diaphragm technologies despite higher capital outlays.
Product Type:
Capital intensity escalates with precision manufacturing requirements and specialized sealing systems.
- Roots Blowers:Twin-lobe rotors trap and displace air through meshing impellers without internal compression, delivering oil-free flow at moderate pressures. German and US wastewater treatment utilities specify these units for biological aeration basins under EPA and EU Urban Wastewater Treatment Directive mandates. Fixed displacement geometry limits efficiency above 10 psig, creating a technical ceiling that shapes retrofit decisions.
- Sliding Vane Blowers:Eccentric rotors with self-compensating vanes maintain tighter clearances than lobe designs, producing smoother discharge profiles with reduced pulsation. Chemical processing clusters in Gujarat and Maharashtra deploy these units where pressure-sensitive reactions demand steady airflow. Higher precision machining requirements elevate upfront costs 15-25% above comparable rotary lobe capacities.
- Mobeal Blowers:Compact rotary designs integrate motor and blower housings for space-constrained installations.
- Diaphragm Blowers:Reciprocating elastomer membranes eliminate all oil contact with process air, satisfying FDA sterile manufacturing guidelines in pharmaceutical cleanrooms.
Roots blowers absorb the bulk of installed capacity; diaphragm blowers are expanding most quickly.
End User:
Regulatory stringency and contamination protocols segment buyers by lifecycle cost tolerance rather than unit price sensitivity.
- Wastewater Treatment:Municipal utilities operate continuous-duty aeration systems requiring 20-year equipment lifespans. US publicly owned treatment facilities face EPA phosphorus and nitrogen discharge thresholds forcing capacity upgrades across 16,000 sites. Energy consumption dominates total cost of ownership calculations, driving variable-speed electric retrofits.
- Chemical Processing:Batch and continuous reactors demand pulsation-controlled gas movement for catalyst fluidization and vapor recovery. China's coastal industrial zones concentrate demand for oil-free pneumatic conveying as food-adjacent chemical capacity expands. Process safety requirements mandate redundant blower configurations unavailable in standard municipal specifications.
- Food & Beverage:Pneumatic conveying of powders and granules requires oil-free compression to prevent product contamination.
- Pharmaceuticals:Sterile manufacturing protocols under FDA and EMA guidelines specify zero oil carryover, overriding efficiency considerations.
Wastewater treatment commands the largest equipment base; pharmaceuticals posts the steepest expansion trajectory.
Application:
Duty cycle characteristics determine maintenance intervals and drive configuration requirements.
- Aeration:Continuous oxygen transfer for biological treatment consumes 50-70% of plant electrical load in activated sludge systems. Dutch and Danish utilities above 100,000 population-equivalent are decentralizing aeration architecture with magnetically levitated turbo alternatives. Blower selection directly determines compliance with effluent limitation guidelines.
- Pneumatic Conveying:Dilute and dense-phase transport of bulk solids requires pressure staging and filtration integration. China's food processing capacity expansion concentrates demand for rotary lobe units with integrated acoustic enclosures. Material abrasiveness dictates rotor coating specifications and replacement schedules.
- Gas Handling:Biogas and process gas compression demands corrosion-resistant materials and leak-tight sealing.
- Vacuum Generation:Industrial process vacuum requires dedicated lubrication systems and interstage cooling.
Aeration dominates operational hours across installed fleets; pneumatic conveying shows the fastest volume gains.
Technology:
Electrification trajectories and legacy infrastructure compatibility split procurement between established mechanical drives and emerging electric architectures.
- Mechanical:Belt and direct-coupled drives with fixed-speed motors dominate decades-old municipal installations. Legacy SCADA integration constraints complicate variable-frequency retrofits across aging US treatment infrastructure. Maintenance departments in Germany's Ruhr cluster stock multi-brand spare inventories to minimize downtime exposure.
- Electric:Permanent magnet motors with variable-speed drives deliver 15-30% energy savings over fixed-displacement alternatives. Rare earth price volatility from Chinese supply concentration inflates drive premiums, extending payback periods. EPA and EU efficiency mandates are accelerating displacement of mechanical drives in new procurement.
- Hydraulic:Fluid power transmission suits mobile and explosion-rated installations where electric motors face certification barriers.
- Hybrid:Combined mechanical-electric systems optimize partial-load efficiency in variable-demand applications.
Mechanical drives retain the largest installed base; electric systems are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany manufactures precision-engineered rotary lobe systems for export, while the United States and China absorb the majority of installed capacity through wastewater infrastructure and industrial expansion programs.
United States
Sixteen thousand publicly owned treatment facilities face EPA phosphorus and nitrogen discharge thresholds requiring aeration capacity upgrades. The EPA Clean Water Act enforcement tightens effluent limitations annually. Package plant OEMs in the Ohio River Valley and Great Lakes regions deliver pre-engineered blower skids that compress installation timelines for municipal utilities.
Germany
Ruhr industrial cluster maintenance departments stock multi-brand spare inventories to minimize downtime exposure across chemical processing sites. The EU Urban Wastewater Treatment Directive mandates enhanced biological nutrient removal. Aerzen anchors European blower supply through specialized rotary lobe engineering developed in Lower Saxony.
China
Coastal industrial zones concentrate demand for oil-free pneumatic conveying systems as food-adjacent chemical capacity expands. The MEE enforces dual carbon goals that accelerate electric drive retrofits in municipal wastewater plants. Yangtze River Delta manufacturing clusters source rotary lobe units for integrated conveying and aeration applications.
India
Gujarat and Maharashtra chemical manufacturing clusters drive procurement of sliding vane blowers for pulsation-sensitive discharge applications. The CEA efficiency regulations push variable-speed electric adoption in new industrial installations. Western India industrial corridors deploy redundant blower configurations for batch reactor catalyst fluidization.
Saudi Arabia
NEOM and Red Sea Project developments create greenfield demand for modular aeration packages in zero-carbon city infrastructure. The SFDA pharmaceutical manufacturing guidelines align with FDA sterile protocols for oil-free compression. Red Sea coastal development zones specify pre-integrated blower skids for decentralized wastewater treatment.
Positive Displacement Blowers Market Vendor Landscape
Top-tier vendors anchor European precision engineering, while mid-tier specialists and regional fabricators compete on customization speed and aftermarket proximity. The vendor base stratifies across three tiers: integrated compressor conglomerates with cross-selling distribution networks, dedicated blower engineering houses with century-long lobe optimization expertise, and emerging Asian manufacturers capturing standard-duty municipal specifications. Consolidation pressure operates through M&A activity among compressor OEMs and strategic partnerships for IoT-enabled predictive maintenance platforms.
Among European engineering houses, Aerzen and Aerzener Maschinenfabrik GmbH exemplify the dedicated blower archetype with deep lobe profile specialization. Ingersoll Rand occupies a position within the integrated conglomerate tier, leveraging compressor distribution infrastructure for cross-selling positive displacement units. Gardner Denver represents the aftermarket-focused archetype, sustaining revenue through extensive service contracts on installed vacuum generation equipment across North American industrial accounts.
| Leading Market Players |
|---|
| Eurus Blowers |
| Aerzen |
| Hitachi Ltd. |
| Tuthill Corporation |
| Ingersoll Rand |
| Busch SE |
| Howden Group |
| Aerzener Maschinenfabrik GmbH |
| Gardner Denver |
| Others |
Supply Flow & Price Mechanics
Certification-grade divergence between CE-marked European precision engineering and standard-duty Asian fabrication manifests in both procurement premiums and supplier qualification timelines. Municipal utilities in Germany and the United States absorb 15-25% price escalations for documented energy efficiency guarantees, while India's chemical clusters prioritize inventory availability over specification stringency.
Pricing Analysis
Lead-time compression commands measurable premiums in municipal procurement cycles, with pre-engineered blower skids from Ohio River Valley OEMs extracting margin advantages over standard catalog units. Three-tier pricing structure across premium, standard, and economy levels reflects certification burden, acoustic enclosure integration, and variable-speed drive inclusion. Cost compression in the economy tier intensifies because Chinese manufacturers are absorbing rare earth price volatility to maintain volume share. Wastewater utilities demonstrate highest price sensitivity due to municipal budget constraints, while pharmaceutical cleanrooms prioritize contamination protocol compliance over capital outlay.
Supply Chain Analysis
Refurbishment flows for rotary lobe rotors and bearing assemblies now constitute a parallel supply channel, with Germany's Ruhr industrial cluster maintaining multi-brand spare inventories to minimize downtime exposure. Manufacturing concentration centers on Germany for precision rotary lobe systems, China for standard-duty municipal specifications, and India for sliding vane chemical processing units. Rare earth magnet supply draws from Chinese processing dominance, while specialized bearing steel sources from Japanese and Swedish mills. Single-source vulnerability in permanent magnet motors threatens variable-speed drive availability. Distribution runs through captive OEM service networks in North America and independent industrial distributors in European chemical corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Permanent magnet motor electrification is displacing belt-driven mechanical architectures across municipal wastewater retrofits, compressing equipment replacement cycles while expanding aftermarket service contract attach rates.
For Market Incumbents: Anticipate margin compression in standard-duty rotary lobe specifications as Chinese manufacturers achieve CE marking parity, and respond by deepening captive aftermarket penetration through IoT-enabled predictive maintenance platforms. Backward integration into rare earth magnet sourcing or long-term offtake agreements with Japanese bearing suppliers defends position against supply disruption. Aerzen and Ingersoll Rand should prioritize lobe profile R&D to maintain efficiency advantages above 10 psig where Roots geometry cedes ground to screw compressors. For New Entrants and Emerging Players: Begin with modular aeration package supply for Saudi Arabia's NEOM and Red Sea Project developments, where greenfield infrastructure lacks incumbent service relationships. Pharmaceutical cleanroom diaphragm specifications offer penetrable white space given FDA sterile manufacturing guideline tightening and incumbent capacity constraints. Target aftermarket parts unbundling in Germany's chemical clusters through independent distributor partnerships rather than direct OEM confrontation. For Investors and Strategic Acquirers: Re-rating potential sits with IoT-enabled predictive maintenance platform operators given EPA effluent mandate acceleration and utility fleet digitalization requirements. Five-to-ten year viability favors vendors with installed base scale sufficient to convert service contracts into recurring revenue streams. The signal to watch is municipal procurement specification language shifting from capital expenditure limits to total cost of ownership scoring, indicating electric architecture preference lock-in.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare Earth Magnet Supply | Secures permanent motor cost stability against Chinese supply concentration volatility. |
| IoT-Enabled Predictive Maintenance Platform Launch | Captures vibration sensor convergence with cloud analytics for aftermarket revenue expansion. |
| CE Marking Acceleration for Acoustic Enclosure Lines | Compresses four-to-six month certification timelines constraining European market access. |
| Joint Venture for Modular Aeration Package Production | Addresses NEOM and Red Sea Project greenfield demand in Saudi zero-carbon zones. |
| Long-Term Service Contract Unbundling Response | Defends aftermarket share against independent distributor spare rotor procurement in Ruhr clusters. |
Methodological Framework
Document review covered customs and trade data, EPA effluent limitation filings, EU Urban Wastewater Treatment Directive implementation reports, and SEC 10-K disclosures from compressor OEMs, complemented by interviews with municipal wastewater plant engineers, chemical processing maintenance directors, blower OEM procurement teams, and aftermarket service heads. Primary fieldwork across Germany's Ruhr industrial cluster, the US Ohio River Valley, and India's Gujarat chemical corridor validated secondary estimates. Bottom-up unit shipment tallies triangulated against top-down energy consumption projections for aeration applications.
Historical capacity expansion patterns cross-referenced against utility capital improvement panel inputs anchored the projection framework across the analysis window. Segmentation modeling incorporated product type, end-use industry, application duty cycle, and technology architecture dimensions. CAGRs derived from regression analysis of installed base turnover rates and regulatory compliance deadline clustering. Forecast inputs included rare earth price trajectory assumptions and municipal bond issuance patterns for infrastructure retrofits.
Underlying measurement precision varies by segment; wastewater treatment and chemical processing carry tighter precision than pharmaceutical cleanroom specifications given disclosure transparency differences. Forecasts reflect assumptions around EPA and EU directive enforcement intensity, electric drive cost curves, and Chinese rare earth export policy continuity. Practitioners should monitor municipal procurement specification language evolution, permanent magnet motor spot pricing, and CE marking backlog durations for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
US HVAC Services Market
HVAC Equipment
Middle East and Africa Commercial HVAC Market
HVAC Equipment
HVAC Centrifugal Compressors Market
HVAC Equipment
Industrial Air Blower Market
HVAC Equipment
Global Air-To-Air Heat Pumps Market
HVAC Equipment
Heavy Duty Heat Pump Market
HVAC Equipment
Equipment Fan Filter Unit (EFU) Market
HVAC Equipment
Swing Compressor Market
HVAC Equipment
China Commercial HVAC Market
HVAC Equipment
Compressor Market
HVAC Equipment
Radiant Heating and Cooling Systems Market
HVAC Equipment
Canada HVAC Equipment Market
HVAC Equipment
Latin America Heat Exchanger Market
HVAC Equipment
Recirculating Chillers Market
HVAC Equipment
Global HVAC Linesets Market
HVAC Equipment
Thermocompressors Market