
 Secondary Water and Wastewater Treatment Equipment Market | 2026-2036
Secondary Water and Wastewater Treatment Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Secondary Water and Wastewater Treatment Equipment Market Intelligence
Aftermarket service revenue is tilting toward membrane bioreactor maintenance and biofilm media replacement as utilities stretch capital cycles. Xylem Inc. leverages its digital monitoring platforms to lock in long-term service contracts across North American municipal accounts. Evoqua Water Technologies anchors its position through captive supply of specialized membranes and chemical regeneration services. Pentair plc competes on compact skid-mounted systems that reduce installation labor for industrial end users.
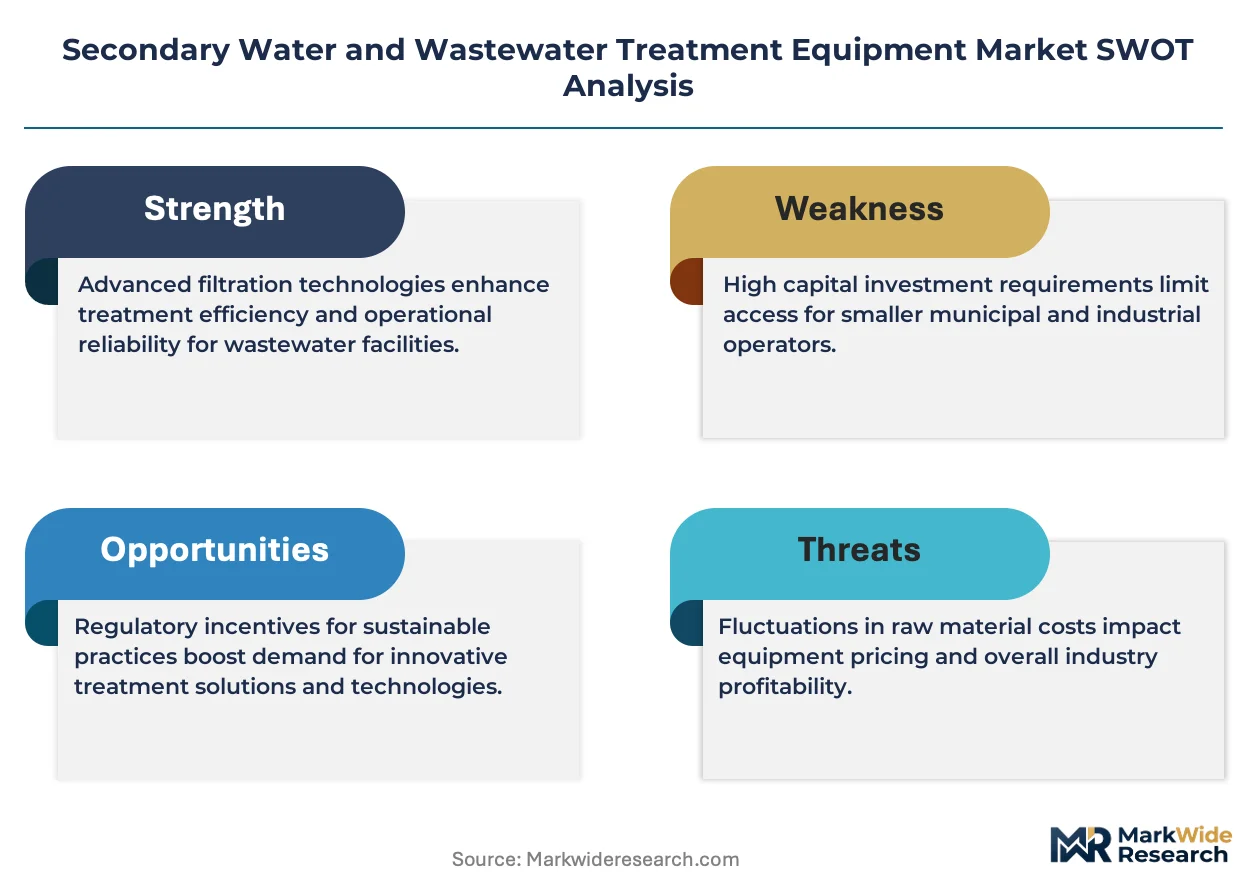
Secondary water and wastewater treatment equipment encompasses biological and physicochemical systems engineered to reduce biochemical oxygen demand, suspended solids, and nutrient loads below primary treatment levels, typically achieving 85-95% BOD removal through controlled microbial oxidation or advanced filtration. These installations serve the essential commercial purpose of rendering effluent safe for environmental discharge, agricultural reuse, or tertiary polishing. Membrane bioreactors command premium positioning due to their smaller footprint and superior effluent quality versus conventional activated sludge systems, though moving bed biofilm reactors are gaining traction in retrofit applications where tank volume is fixed. Trickling filters retain cost advantages in smaller municipal settings but face margin compression from more efficient biological alternatives.
The EPA enforces effluent limitation guidelines under the Clean Water Act that mandate nitrogen and phosphorus removal, directly stimulating demand for biological nutrient removal upgrades and advanced oxidation add-ons. China's MEE implements increasingly stringent GB standards for industrial wastewater discharge that force manufacturing facilities toward membrane-based secondary trains rather than conventional options. The EU Green Deal and associated Urban Wastewater Treatment Directive revisions push member states toward energy-neutral biological processes, reshaping technology selection criteria. Stakeholders must weigh capital intensity against operational resilience as regulatory thresholds tighten and energy costs reshape total cost of ownership calculations.
Market Dynamics
Membrane bioreactor technology is compressing conventional activated sludge economics as utilities face footprint constraints and tightening effluent standards simultaneously.
Growth Catalysts
- Urbanization Pressures:Southeast Asian municipalities are expanding biological treatment capacity to accommodate rapid population migration into metropolitan corridors. Indonesia's Ministry of Public Works has prioritized wastewater infrastructure in its national medium-term development plan.
- Zero-Liquid-Discharge Mandates:India's Central Pollution Control Board now enforces ZLD requirements across textile and pharmaceutical manufacturing clusters, forcing secondary treatment upgrades with membrane-based trains.
- Activated Sludge Infrastructure:The EPA's tightening effluent limitation guidelines under the Clean Water Act compel US utilities to retrofit aging biological nutrient removal systems.
Market Restraints
- Membrane Replacement Cycles:Specialized membrane elements require scheduled replacement every 5-7 years, creating recurring opex burdens that strain municipal operating budgets.
- Energy Input Volatility:Biological aeration systems consume 45-60% of total facility energy, making secondary treatment vulnerable to electricity price fluctuations.
- Skilled Technician Scarcity:Advanced biological systems demand operators trained in microbial process control, a capability concentrated in industrialized economies.
Strategic Opportunities
- Retrofit Applications:Moving bed biofilm reactor technology enables capacity expansion within existing tank volumes, opening upgrade paths for space-constrained facilities in Japan and South Korea.
- Energy-Neutral Biological Processes:The EU Green Deal's Urban Wastewater Treatment Directive revisions incentivize anaerobic membrane bioreactor adoption to achieve carbon-neutral operations.
- Digital Monitoring Convergence:Integration of dissolved oxygen sensors with predictive algorithms allows real-time process optimization, creating service revenue streams for equipment vendors.
Industry Challenges
- Legacy Control System Integration:Modern membrane bioreactors must interface with decades-old SCADA architectures common in North American municipal plants, complicating commissioning timelines.
- Biofilm Media Standardization:Proprietary carrier designs from competing suppliers create maintenance silos and limit second-source procurement flexibility for operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Secondary Water and Wastewater Treatment Equipment Market |
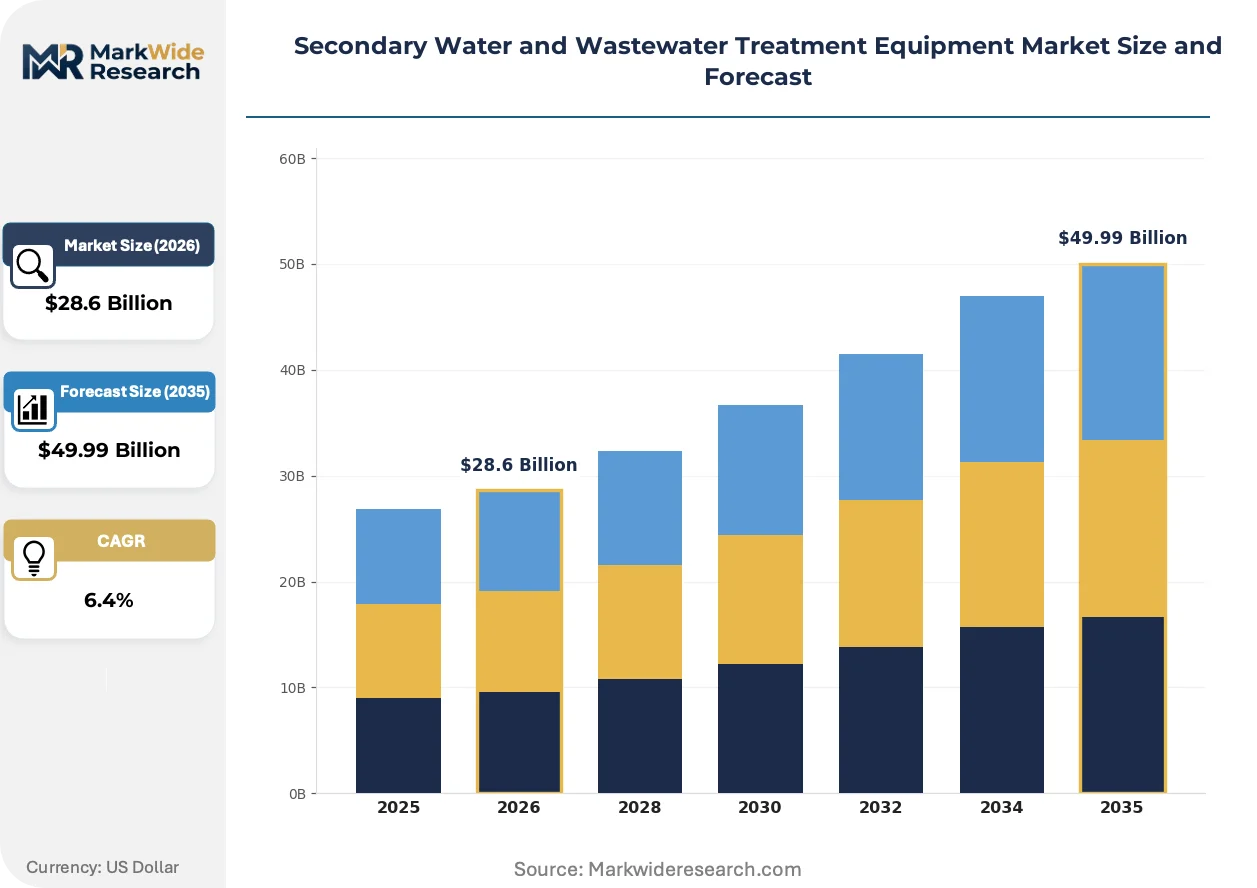
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $49.99 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Membrane Bioreactors, Activated Sludge Systems, Trickling Filters, Moving Bed Biofilm Reactors Application: Municipal Wastewater, Industrial Wastewater, Reuse & Recycling, Stormwater Management Technology: Biological Treatment, Chemical Treatment, Physical Treatment, Advanced Oxidation Processes End User: Municipalities, Manufacturing Facilities, Power Plants, Construction Sites |
| Companies Covered | Veolia Water Technologies, Xylem Inc., Suez Water Technologies Solutions, Evoqua Water Technologies, Pentair plc, Siemens AG, IDEX Corporation, Ecolab Inc., Aquatech International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Secondary Water and Wastewater Treatment Equipment Market Strategic Shifts & Innovations
Real-time process control is replacing scheduled maintenance paradigms as sensor costs decline and machine-learning platforms mature for biological treatment applications.
Smart dissolved oxygen and mixed liquor suspended solids instrumentation is digitizing operational decision-making across secondary treatment trains. Municipal utilities in Germany and the Netherlands are deploying these systems at pilot scale, with full-scale adoption accelerating where energy costs exceed regional averages. The technology is digitizing how operators manage aeration demand, compressing energy consumption by 15-25% compared to timer-based controls.
The EPA's effluent limitation guidelines now mandate nutrient removal thresholds that conventional activated sludge cannot achieve without supplemental processes. This regulatory pressure forces utilities toward biological nutrient removal retrofits or membrane bioreactor replacements. Industrial discharge permits in the Great Lakes region face the strictest phosphorus limits, driving demand for advanced oxidation add-ons.
Service unbundling is fragmenting traditional equipment procurement as utilities separate capital purchases from long-term performance guarantees. North American municipal buyers increasingly contract operations and membrane replacement through distinct vendors rather than single-source EPC arrangements. This pattern is most pronounced in California and Texas, where public-private partnership frameworks enable specialized service providers to compete for O&M contracts independent of original equipment suppliers.
Secondary Water and Wastewater Treatment Equipment Market Segmentation
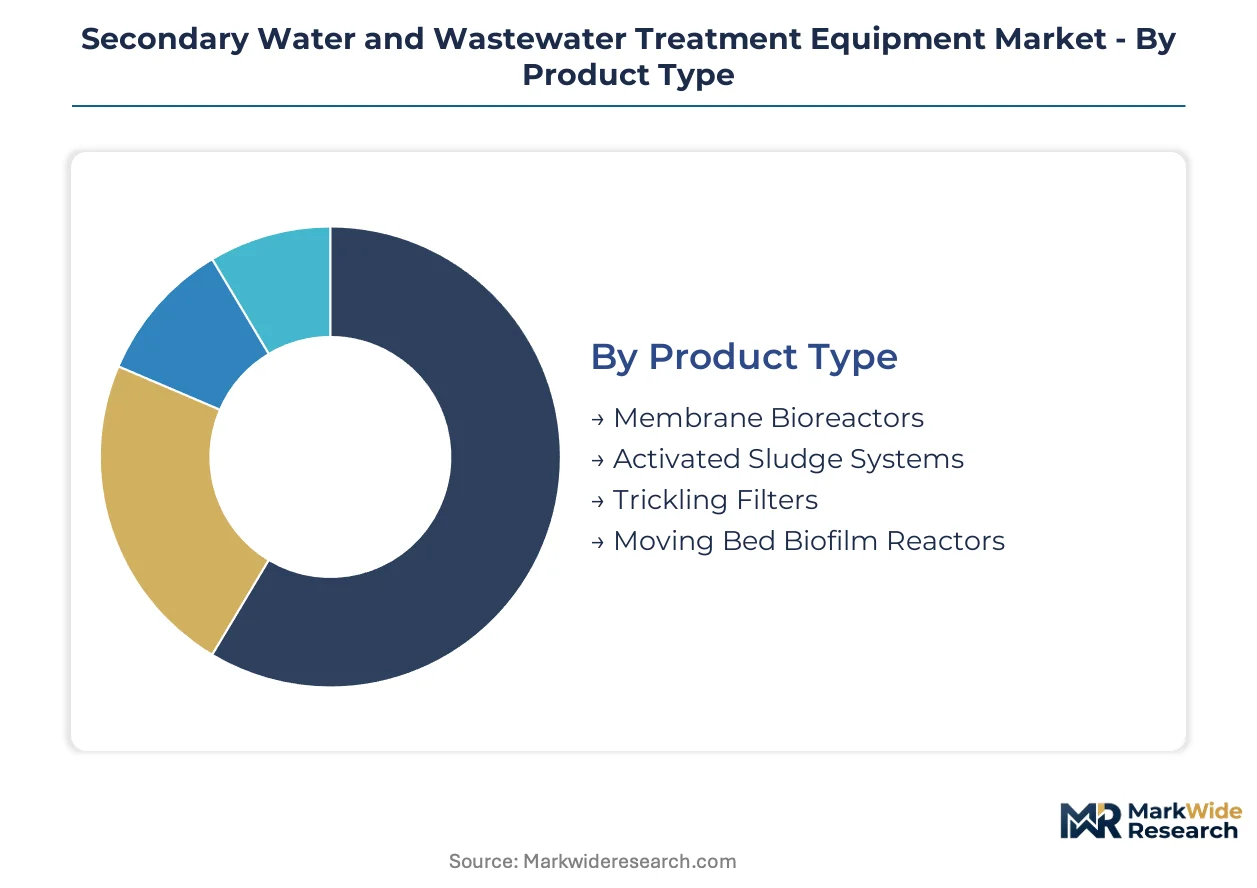
Technology selection in secondary treatment hinges on effluent targets, footprint constraints, and energy economics. Equipment vendors calibrate product portfolios across four intersecting dimensions: process technology, application environment, treatment mechanism, and operator sophistication.
Product Type:
Cost tier differentiation separates premium membrane-based systems from conventional biological alternatives with lower capital intensity but higher land requirements.
- Membrane Bioreactors:Combine suspended growth bioreactors with micro- or ultrafiltration membranes in a single integrated process, eliminating secondary clarifiers and achieving direct solids separation. Demand concentrates in Japan and South Korea where urban land scarcity commands 40-60% footprint reduction versus conventional trains, though membrane replacement cycles strain municipal operating budgets.
- Activated Sludge Systems:Employ aerated basins with microbial floc formation and gravity settling, representing the most widely deployed biological treatment architecture globally. Utilities across the US Great Lakes region are retrofitting these systems with biological nutrient removal zones to meet EPA phosphorus discharge limits, extending asset life rather than greenfield replacement.
- Trickling Filters:Fixed-film biological towers using rock or plastic media support heterotrophic biofilm growth with minimal mechanical complexity. Small municipalities in India and Indonesia favor these systems for operational simplicity where skilled technician availability is limited.
- Moving Bed Biofilm Reactors:Suspend engineered plastic carriers in aerated basins to combine biofilm stability with suspended growth flexibility, enabling capacity expansion within existing tank volumes. Retrofit applications in Japan and Germany are climbing fastest where space constraints preclude tank construction.
Activated sludge systems command the established base. The steepest expansion runs through membrane bioreactors.
Application:
Application context dictates equipment specification through influent variability, discharge standards, and reuse potential.
- Municipal Wastewater:Serves residential and commercial sewage streams with relatively consistent organic loading and stringent pathogen removal requirements. Southeast Asian metropolitan utilities in Jakarta and Bangkok are expanding biological capacity to accommodate urbanization pressures, prioritizing nutrient removal to protect receiving waters.
- Industrial Wastewater:Handles variable-strength effluent from manufacturing processes with specialized contaminants requiring customized pretreatment trains. India's textile and pharmaceutical clusters face Central Pollution Control Board zero-liquid-discharge mandates, forcing membrane-based secondary treatment with evaporative crystallization.
- Reuse & Recycling:Produces treated effluent suitable for agricultural irrigation, industrial cooling, or potable reuse augmentation. California's municipal utilities are deploying advanced oxidation add-ons to secondary effluent for groundwater replenishment, driven by state reuse regulations.
- Stormwater Management:Captures and treats urban runoff with high hydraulic variability and episodic pollutant loading. Construction sites in Germany integrate compact biological treatment with detention basins to meet EU Water Framework Directive requirements for receiving water protection.
Municipal wastewater retains the volume base. Reuse and recycling applications are gaining share fastest as water stress intensifies across arid regions.
Technology:
Treatment mechanism selection balances removal efficiency against energy input and chemical dependency.
- Biological Treatment:Harnesses microbial metabolism to oxidize organic matter and transform nutrients through controlled aeration and solids retention. The EU Green Deal's Urban Wastewater Treatment Directive revisions push member states toward energy-neutral anaerobic biological processes, reshaping technology procurement criteria.
- Chemical Treatment:Deploys coagulants, flocculants, and precipitants to enhance solids removal or supplement biological nutrient capture. Industrial facilities in China's Yangtze River Economic Belt combine chemical phosphorus precipitation with biological trains to meet MEE discharge standards.
- Physical Treatment:Employs sedimentation, filtration, and screening without biological or chemical transformation, typically as secondary clarification or tertiary polishing. Power plants in India use physical filtration downstream of biological treatment for cooling tower makeup water.
- Advanced Oxidation Processes:Generate hydroxyl radicals through ozone, UV, or peroxide combinations to mineralize recalcitrant organics and destroy emerging contaminants. US utilities in the Great Lakes region add these processes to meet EPA effluent limitation guidelines for pharmaceutical residuals.
Biological treatment anchors installed capacity. Advanced oxidation processes are expanding most quickly as micropollutant regulations tighten.
End User:
Customer type determines procurement approach, with municipalities favoring design-bid-build and industrial buyers seeking performance contracting.
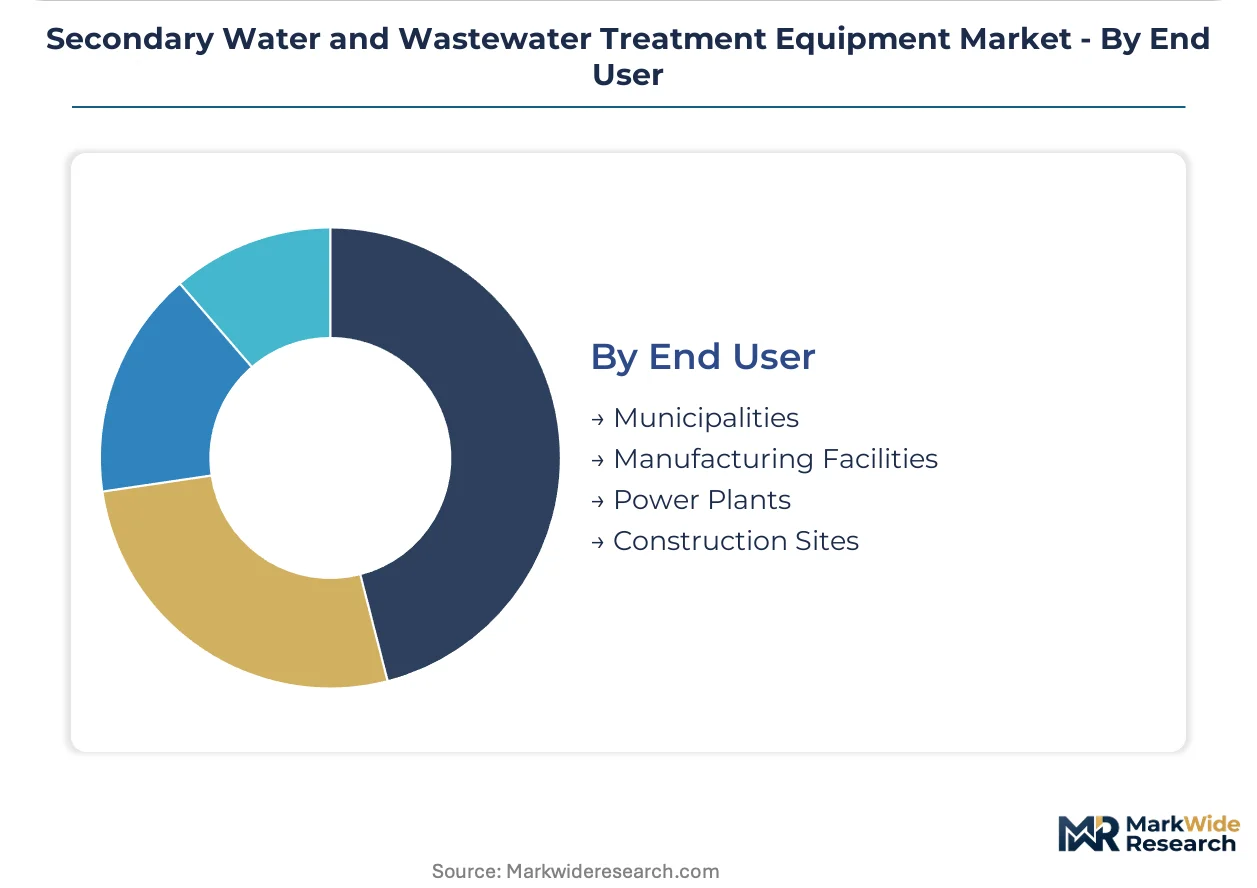
- Municipalities:Public water and sewer authorities with regulated rate structures, long asset horizons, and political accountability for service delivery. Indonesian Ministry of Public Works infrastructure programs are channeling national development funds toward biological treatment expansion in metropolitan corridors.
- Manufacturing Facilities:Private industrial operators with discharge permits, production-integrated water management, and cost-recovery pricing flexibility. Textile clusters in India's Tiruppur and Surat regions invest in zero-liquid-discharge secondary trains to maintain export market access.
- Power Plants:Thermal and renewable generation facilities with high-volume cooling water requirements and strict boiler feed specifications. Coal-fired stations in Germany retrofit biological treatment for flue gas desulfurization wastewater to comply with EU Industrial Emissions Directive.
- Construction Sites:Temporary dewatering and runoff treatment operations requiring mobile, rapidly deployable systems with minimal civil works. South Korean infrastructure projects specify containerized membrane bioreactors for tunnel construction wastewater.
Municipalities represent the established demand base. Manufacturing facilities are climbing fastest as industrial discharge standards proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between land-constrained East Asian metros favoring compact membrane systems and sprawling South Asian industrial zones deploying conventional activated sludge at scale.
United States
Utilities across the Great Lakes and Chesapeake Bay watersheds face EPA effluent limitation guidelines mandating phosphorus and nitrogen removal below 0.1 mg/L. The Clean Water Act enforcement is accelerating biological nutrient removal retrofits in legacy plants. Chicago and Milwaukee metropolitan districts are prioritizing anaerobic membrane bioreactor pilots to achieve carbon-neutral operations.
Germany
Municipal operators under the EU Green Deal's Urban Wastewater Treatment Directive revisions must achieve energy-neutral biological processes by 2035. The country's technical standards authority is channeling compliance investments toward anaerobic MBR adoption. The Ruhr industrial corridor and Bavarian cities are retrofitting conventional trains with moving bed biofilm reactors to expand capacity within fixed tank volumes.
China
Manufacturing facilities in the Yangtze River Economic Belt confront MEE enforcement of GB 8978 discharge standards tightening COD and ammonia limits. The ministry's dual carbon goals are reshaping technology procurement toward energy-efficient biological trains. Textile clusters in Zhejiang and pharmaceutical zones in Jiangsu are deploying membrane-based secondary treatment with evaporative crystallization for zero-liquid-discharge compliance.
India
Central Pollution Control Board zero-liquid-discharge mandates now cover textile and pharmaceutical manufacturing clusters in Gujarat and Tamil Nadu. The country's national infrastructure pipeline is directing development funds toward biological treatment expansion in metropolitan corridors. Tiruppur and Surat industrial zones are investing in membrane bioreactor trains to maintain export market access under tightening environmental compliance requirements.
Indonesia
Jakarta and Bandung metropolitan utilities are expanding biological capacity to accommodate rapid urbanization pressures under the Ministry of Public Works national medium-term development plan. The country's wastewater infrastructure deficit is driving demand for trickling filter systems in smaller municipalities where skilled technician availability remains limited. Java's northern coastal manufacturing zones are retrofitting secondary treatment to meet receiving water protection requirements.
Secondary Water and Wastewater Treatment Equipment Market Key Industry Players
Capability concentration sits with integrated technology providers commanding membrane chemistry and digital monitoring expertise; scale advantage sits with diversified industrial conglomerates leveraging cross-sector procurement relationships. The market structure exhibits tiered consolidation with premium membrane specialists, mid-scale system integrators, and regional fabrication shops occupying distinct competitive positions. Three archetypes dominate: captive membrane suppliers locking in long-term service contracts, compact skid-mounted system specialists targeting industrial retrofit applications, and digital platform operators monetizing predictive maintenance revenue streams. Dominant competitive moves include backward integration into specialized membrane manufacturing and strategic partnerships bundling equipment procurement with performance-based operations contracts.
Among diversified water technology groups, Veolia Water Technologies and Suez Water Technologies Solutions exemplify the integrated service archetype spanning design, build, and long-term operations. Xylem Inc. occupies a position within the digital convergence tier, anchoring its market presence through sensor-integrated monitoring platforms that generate recurring service revenue from municipal accounts.
| Leading Market Players |
|---|
| Veolia Water Technologies |
| Xylem Inc. |
| Suez Water Technologies Solutions |
| Evoqua Water Technologies |
| Pentair plc |
| Siemens AG |
| IDEX Corporation |
| Ecolab Inc. |
| Aquatech International |
| Others |
Cost & Logistics Intelligence
Shanghai-to-Rotterdam container freight corridors transmit cost volatility from membrane polymer supply clusters to European municipal utilities, compressing margins on skid-mounted systems while amplifying price spreads between premium membrane bioreactor suppliers and economy-tier activated sludge fabricators.
Pricing Analysis
Long-term performance-based O&M contracts dominate municipal procurement, locking in 10-15 year service revenue streams that equipment vendors monetize through bundled membrane replacement schedules. Three-tier pricing structure across premium, standard, and economy levels separates membrane bioreactor specialists with digital monitoring platforms from conventional activated sludge integrators and trickling filter fabricators. Cost compression in economy-tier biological systems is intensifying because Indonesian and Indian municipalities prioritize capital expenditure minimization over operational efficiency. Industrial end-users in pharmaceutical and textile clusters exhibit lowest price sensitivity due to zero-liquid-discharge compliance mandates that override capital cost considerations.
Supply Chain Analysis
Export control regimes on advanced ultrafiltration membrane manufacturing equipment limit technology transfer from Germany and Japan to emerging market fabricators, concentrating high-performance module production among incumbent suppliers. Polyvinylidene fluoride resin supply draws from Chinese and Belgian chemical complexes, while specialized aeration diffuser membranes source from German and Japanese precision extrusion facilities. Single-source vulnerability runs through ceramic membrane substrate production anchored in Japanese industrial ceramics corridors. Distribution runs through regional system integrators who bundle imported membrane elements with locally fabricated tankage and control skids.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital platform interoperability is reshaping this market toward ecosystem economics, as Xylem's sensor-integrated monitoring architectures create switching costs that lock municipal utilities into proprietary service orbits and fragment procurement between equipment and O&M vendors.
For Market Incumbents: Harden defensive moats by deepening backward integration into hollow-fiber membrane extrusion capacity in Germany and Japan, insulating against supply disruption while capturing margin from replacement cycles. Lock in long-term performance contracts with North American municipal accounts before service unbundling fragments traditional EPC relationships. Prioritize API-enabled platform integration that embeds predictive algorithms into legacy SCADA architectures common in aging US treatment plants.
For New Entrants and Emerging Players: Build out compact moving bed biofilm reactor offerings targeting Japan and South Korea retrofit applications where footprint constraints preclude greenfield construction and incumbent membrane suppliers face margin compression. Target India's textile and pharmaceutical clusters with containerized zero-liquid-discharge secondary trains that bypass established channel relationships through direct industrial sales. Lead with energy-neutral anaerobic biological process designs that align with EU Green Deal procurement criteria reshaping European municipal specifications.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with captive water technology divisions lacking standalone scale; mid-sized membrane specialists with proprietary biofilm media formulations present attractive consolidation candidates. Long-term viability hinges on recurring service revenue attachment rates rather than equipment shipment volumes. Monitor EPA effluent limitation guideline enforcement intensity across US watersheds as the signal indicating upgrade cycle acceleration or deferral.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Membrane Manufacturing | Captive PVDF resin processing secures margin capture from replacement cycles in municipal accounts. |
| Digital Platform Integration with Legacy SCADA | API-enabled sensor convergence locks utilities into proprietary monitoring orbits and recurring service streams. |
| Energy-Neutral Biological Process Development | Anaerobic MBR designs align with EU Green Deal mandates reshaping European procurement specifications. |
| Containerized System Packaging for Industrial Retrofit | Skid-mounted delivery reduces installation labor and bypasses established EPC channel relationships. |
| Long-Term Performance-Based O&M Contracting | Service unbundling from equipment procurement creates recurring revenue independent of capital cycles. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with municipal utility operations directors, industrial plant engineers overseeing zero-liquid-discharge compliance, membrane module procurement managers at system integrators, and aftermarket service heads at equipment vendors. Secondary validation drew from EPA effluent limitation guideline enforcement databases, EU Urban Wastewater Treatment Directive implementation reports, Central Pollution Control Board discharge compliance records, and customs trade data on membrane module imports. Bottom-up equipment shipment tallies were triangulated against top-down infrastructure investment flows from national development plans.
Calibration across the analysis window employed a segmented growth model treating technology type, application environment, treatment mechanism, and end-user sophistication as independent demand drivers. CAGRs were derived from elasticity-adjusted projections of regulatory enforcement intensity, urbanization-driven capacity expansion, and industrial discharge standard proliferation. Forecast inputs incorporated membrane replacement cycle timing, energy cost trajectories affecting biological aeration economics, and skilled technician availability constraints limiting technology adoption in emerging markets.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese membrane fabricators or digital platform entrants would shift outcomes beyond modeled ranges. Material shifts in EPA enforcement posture, EU Green Deal timeline acceleration, or breakthrough anaerobic process economics would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environmental Engineering
Septic Tanks Market
Environmental Engineering
North America Rainwater Harvesting Market
Environmental Engineering
Aerobic Treatment Units Market
Environmental Engineering
Outdoor Sound Barrier Market
Environmental Engineering
Rainwater Harvesting Market
Environmental Engineering
Dust Control Systems Market
Environmental Engineering
Fume Hoods Market
Environmental Engineering
Silt Curtain Market
Environmental Engineering
Global Built and Natural Environment Consulting Market
Environmental Engineering
Wet Scrubber Market
Environmental Engineering
Gas Scrubber Market
Environmental Engineering
Tunnel Ventilation and Environmental Monitoring Systems Market
Environmental Engineering
Global Rainwater Harvesting System Market
Environmental Engineering
Outdoor Noise Barrier Market