
 Industrial Blowers Market | 2026-2036
Industrial Blowers Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Blowers Market Outlook
Aftermarket service revenue is narrowing as a margin pool migration between activities as OEMs claw back refurbishment and spare parts streams from independent service networks. Atlas Copco leverages its compressor service infrastructure to cross-sell blower maintenance contracts across European process industries. Kaeser Kompressoren anchors its position through captive distribution and direct field technician deployment. Greenheck Fan competes on specification-grade ventilation systems where engineering relationships override price sensitivity.
Industrial blowers are turbomachines engineered to move air or gases at pressures between 0.5 and 2.5 psig, employing impeller geometries ranging from radial to mixed-flow designs forged from aluminum alloys or coated carbon steel. These devices serve as the pneumatic backbone of dust collection networks, biological aeration basins, and bulk material transport lines where continuous airflow reliability determines operational uptime. Centrifugal blowers occupy the mature core of the product mix, while regenerative blowers capture the fastest growth in precision pneumatic conveying for food and pharmaceutical applications. Electric power source configurations dominate procurement specifications as facility operators retire gas-driven units to satisfy Scope 1 emissions accounting.
EPA Clean Air Act enforcement and EU F-Gas Regulation phase-down schedules are reshaping blower specification requirements across North American and European process plants. China's MEE ambient air quality standards and dual carbon policy framework are forcing domestic manufacturers toward high-efficiency motorized designs with permanent magnet synchronous drives. Stakeholders must monitor how IEC motor efficiency class upgrades and emerging ISO energy management certifications will redefine equipment qualification criteria for large capital projects.
Market Dynamics
Permanent magnet synchronous motor architectures are compressing energy consumption benchmarks across installed blower bases, forcing incumbent equipment owners into accelerated replacement cycles under tightening carbon accounting rules.
Growth Catalysts
- EU F-Gas Regulation phase-down:Refrigerant containment mandates in process cooling circuits are expanding demand for hermetic blower designs in German chemical corridors.
- Wastewater infrastructure:Biological nutrient removal upgrades across Japanese municipal treatment networks are specifying high-pressure aeration blowers with variable frequency drives.
- Food-grade pneumatic conveying:Regenerative blower adoption is accelerating in Brazilian protein processing plants handling fragile granular materials.
Market Restraints
- Rare earth magnet supply concentration:Permanent magnet motor production depends on Chinese neodymium processing, exposing cost volatility to downstream OEMs.
- High-efficiency IEC motor cost premiums:IE4 and IE5 class motors carry 35-50% price deltas over IE3 equivalents, stretching municipal procurement budgets.
- Compressed air substitution:Oil-free compressor technologies are capturing low-pressure pneumatic applications previously served by regenerative blowers.
Strategic Opportunities
- India PLI scheme for capital goods:Domestic manufacturing incentives are attracting blower assembly investments serving subcontinent process industries.
- Carbon capture solvent regeneration:Amine stripping operations require corrosion-resistant blower trains handling acid gas mixtures at elevated temperatures.
- Direct-to-plant digital distribution:Configurator platforms are bypassing traditional distribution layers for standardized centrifugal units in North American light manufacturing.
Industry Challenges
- Rotordynamics specialization shortage:Field service networks lack technicians trained in magnetic bearing commissioning for high-speed turbo blowers.
- Legacy control system integration:Variable frequency drive retrofits face communication protocol mismatches with aging SCADA architectures in brownfield facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Blowers Market |
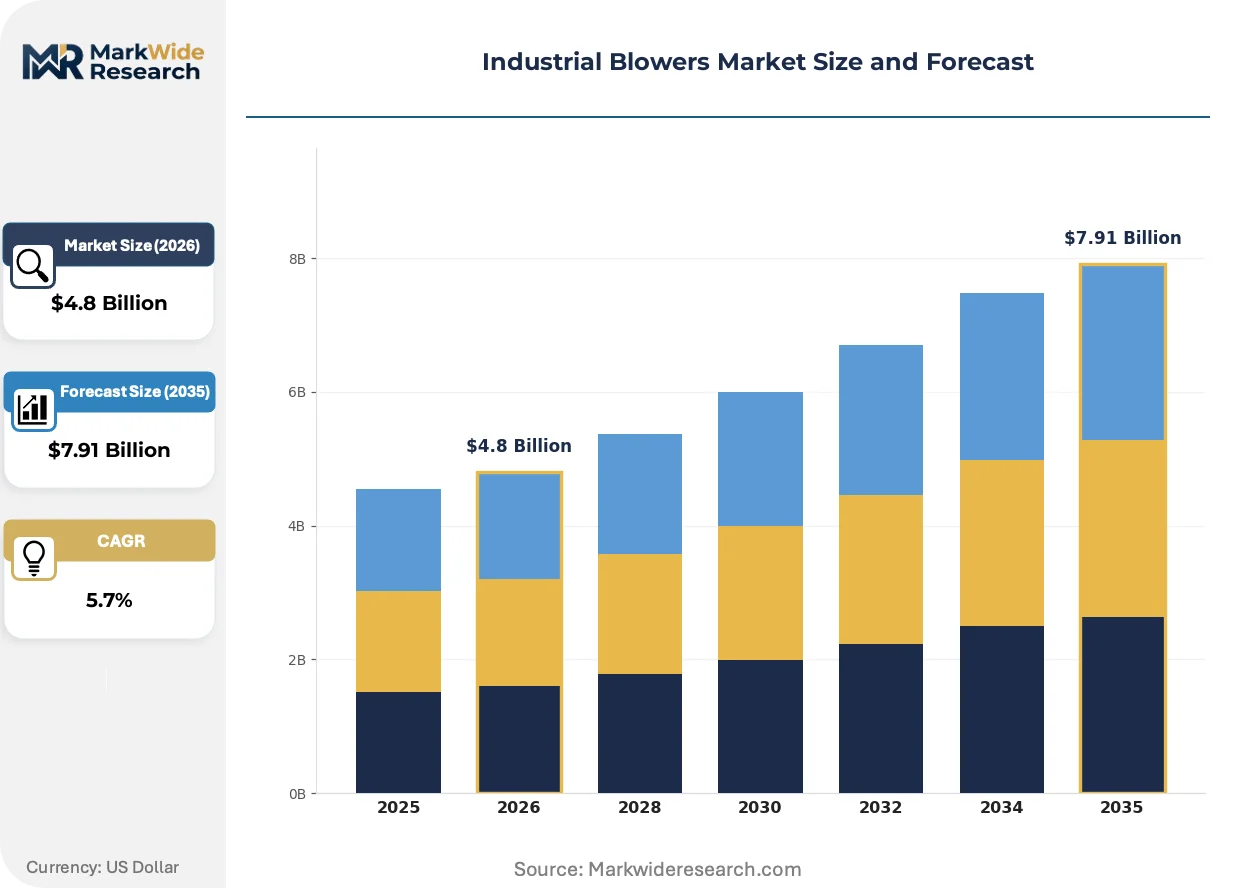
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Centrifugal Blowers, Positive Displacement Blowers, Regenerative Blowers, Mixed Flow Blowers Application: Dust Control, Wastewater Treatment, Pneumatic Conveying, Ventilation End User: Manufacturing, Chemical Processing, Food & Beverage, Mining Power Source: Electric, Gas, Diesel, Hybrid |
| Companies Covered | Atlas Copco, Ingersoll Rand, Aerzen, Howden Group, Continental Blower, Kaeser Kompressoren, Xylem, Loren Cook Company, Greenheck Fan, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Blowers Market Strategic Shifts
Active magnetic bearing technology is eliminating mechanical contact in high-speed turbomachinery, collapsing maintenance intervals while enabling operating speeds impossible with conventional rolling element bearings.
Magnetic bearing blower platforms are rendering obsolete oil-lubricated gearbox architectures in large aeration applications. German and Dutch wastewater utilities are specifying these units for continuous-duty biological treatment trains. The elimination of lubricant systems is compressing total cost of ownership calculations and shortening payback periods against conventional multistage centrifugal alternatives.
China's MEE ambient air quality standards are mandating continuous emissions monitoring at stack discharge points. Process plants must install dedicated sampling blower systems maintaining constant velocity through heated probe lines. Steel and cement producers in Hebei and Shandong provinces are retrofitting existing stacks with these pneumatic sampling trains to maintain operating permits.
Service contract unbundling is fragmenting aftermarket revenue streams. End-users in North American food processing are separating preventive maintenance from parts supply, awarding these scopes to different vendors. This disintermediation is compressing margins for traditional full-service providers while creating openings for specialized predictive analytics firms monitoring vibration and thermal signatures remotely.
Industrial Blowers Market Segmentation
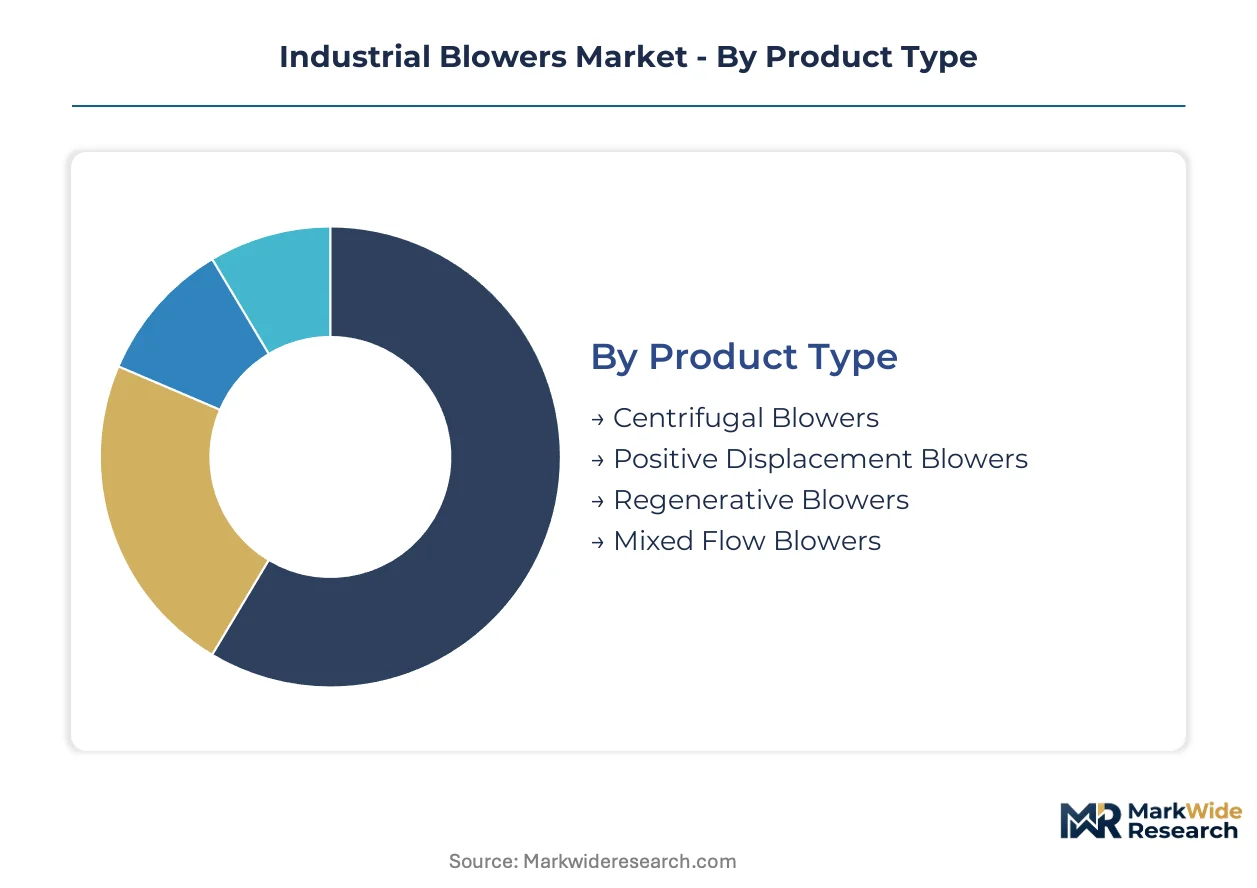
Equipment segmentation in the industrial blowers market determines service contract structures and spare parts forecasting accuracy. Distinct product architectures create divergent aftermarket revenue profiles that OEMs must navigate through specialized field technician networks.
Product Type:
After-sales-service intensity varies sharply across blower architectures, with high-speed designs demanding magnetic bearing specialists and conventional units requiring routine impeller balancing.
- Centrifugal Blowers:Radial impeller designs forged from aluminum alloys or coated carbon steel handle continuous-duty airflow at 0.5 to 2.5 psig. Demand concentrates in German and Dutch wastewater utilities specifying magnetic bearing platforms for biological aeration trains under tightening EU discharge mandates. Service contracts here span bearing commissioning, rotor dynamics calibration, and predictive vibration monitoring.
- Regenerative Blowers:Side-channel compression stages generate higher pressure ratios through multiple impeller passes, suited for precision pneumatic conveying. Brazilian protein processing plants and Chinese pharmaceutical corridors are scaling deployments for fragile granular material handling where oil-free operation is mandatory. These units require less intensive field service but demand frequent seal replacement programs.
- Positive Displacement Blowers:Lobe or screw rotor architectures deliver pulsation-free flow for bulk material transport lines.
- Mixed Flow Blowers:Intermediate impeller geometries blending radial and axial characteristics serve specialized ventilation applications.
By volume, Centrifugal Blowers leads. By growth pace, Regenerative Blowers is ahead.
Application:
Cost tier differentiation separates specification-grade engineered systems from standardized commodity units across deployment contexts.
- Wastewater Treatment:High-pressure aeration blowers with variable frequency drives serve biological nutrient removal basins. Japanese municipal networks are upgrading installed bases under METI efficiency directives, while German facilities deploy hermetic designs for refrigerant containment circuits. These projects carry extended warranty terms and captive service agreements.
- Pneumatic Conveying:Regenerative and positive displacement configurations transport powders, granules, and fragile solids through enclosed pipeline networks. Food-grade specifications in North American processing plants require stainless steel construction, FDA-compliant seals, and documented cleaning protocols that elevate procurement costs substantially above industrial-grade alternatives.
- Dust Control:Centrifugal designs maintain negative pressure in collection hoods and baghouse systems.
- Ventilation:General-purpose airflow management for industrial facilities and commercial infrastructure.
Wastewater Treatment commands the highest average selling prices. Pneumatic Conveying is climbing the fastest.
End User:
Customer type determines procurement sophistication, with multinational chemical operators imposing energy efficiency certification requirements that municipal utilities often bypass.
- Chemical Processing:Corrosion-resistant blower trains handle acid gas mixtures, solvent vapors, and amine stripping operations in carbon capture configurations. Chinese state-owned enterprises in Shandong and Hebei provinces are retrofitting stacks with continuous emissions monitoring systems under MEE ambient air quality standards, driving specification-grade demand for heated probe line sampling blowers.
- Food & Beverage:Oil-free compressed air alternatives and regenerative blower platforms serve packaging, conveying, and processing lines where contamination risks are unacceptable. Brazilian meat processing corridors and Indian dairy cooperatives are expanding pneumatic infrastructure under tightening FSSAI and ANVISA hygiene mandates.
- Manufacturing:General industrial applications span dust collection, drying, and process cooling across diverse production environments.
- Mining:Heavy-duty ventilation and material handling in underground and surface extraction operations.
Chemical Processing generates the largest project scale. Food & Beverage is gaining share fastest.
Power Source:
Supply concentration in permanent magnet materials is reshaping procurement strategies for electrified equipment.
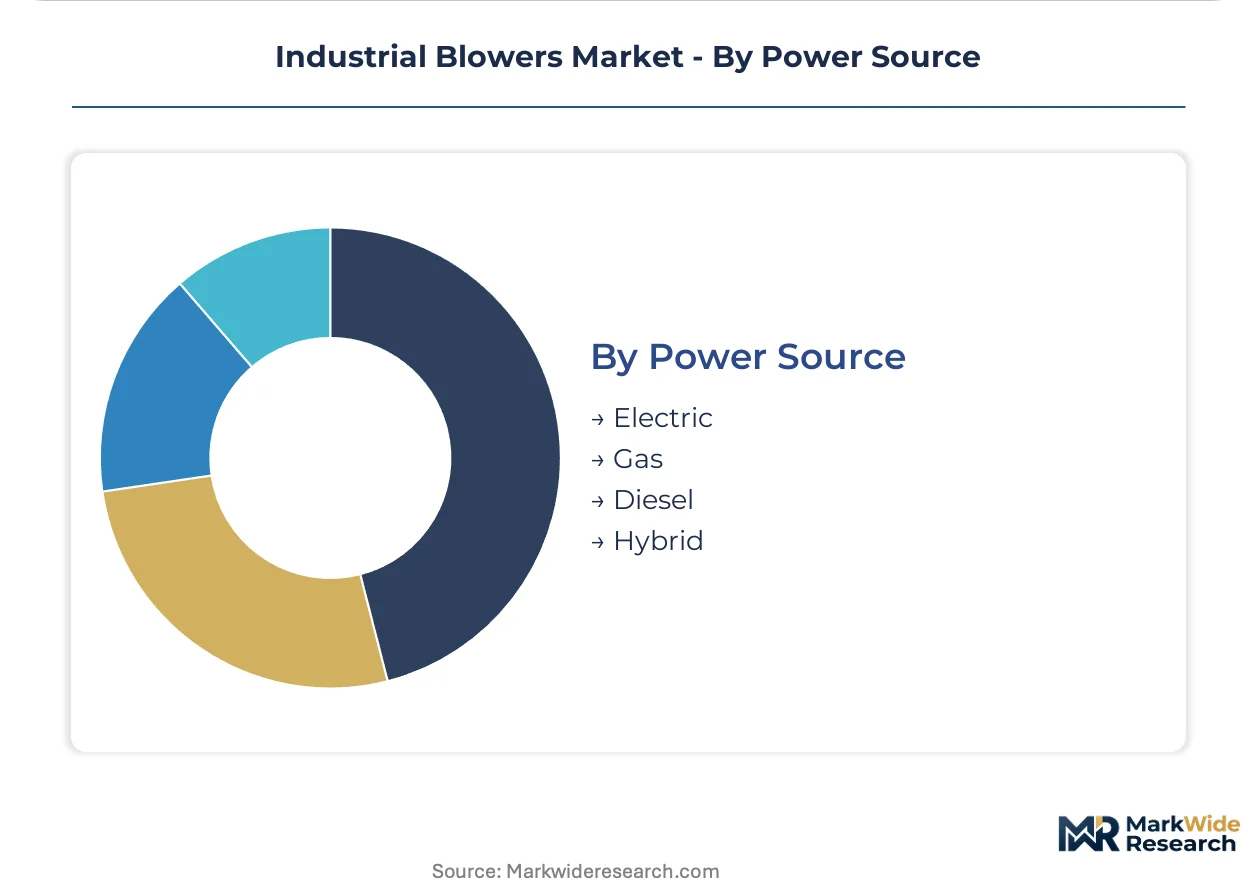
- Electric:Permanent magnet synchronous motor architectures with IE4 and IE5 efficiency ratings are displacing gas-driven units as facility operators retire equipment to satisfy Scope 1 emissions accounting. Chinese neodymium processing concentration exposes OEMs to raw material volatility, while IEC motor efficiency class upgrades redefine qualification criteria for large capital projects.
- Gas:Natural gas and biogas engines serve remote installations and peak-shaving applications where grid connectivity is unreliable.
- Diesel:Mobile and emergency backup configurations for construction sites and temporary industrial installations.
- Hybrid:Dual-fuel or battery-assisted designs emerging in decarbonization-focused pilot deployments.
Electric dominates current procurement specifications. Hybrid is expanding most quickly in pilot phases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in municipal wastewater sectors exhibit acute price sensitivity to IE4 and IE5 motor premiums, while chemical processors absorb higher specification costs under carbon accounting mandates. This elasticity divergence fragments procurement patterns across national markets.
China
State-owned enterprises in Shandong and Hebei provinces drive specification-grade demand for corrosion-resistant blower trains handling acid gas mixtures. MEE ambient air quality standards mandate continuous emissions monitoring retrofits at steel and cement stacks. The Yangtze River Delta chemical processing corridor forces wholesale equipment upgrades under dual carbon policy deadlines.
Germany
Dutch and German wastewater utilities specify magnetic bearing platforms for biological aeration trains under tightening EU discharge mandates. EU F-Gas Regulation phase-down schedules expand hermetic blower procurement for refrigerant containment circuits. The Rhine-Ruhr chemical corridor anchors continental demand for high-efficiency motorized designs.
United States
EPA Clean Air Act enforcement reshapes blower specifications across process plants in the Gulf Coast petrochemical cluster. North American food processing facilities unbundle service contracts, separating preventive maintenance from parts supply. Configurator platforms bypass traditional distribution layers for standardized centrifugal units in light manufacturing.
Japan
METI efficiency directives accelerate biological nutrient removal upgrades across municipal treatment networks. Japanese utilities specify high-pressure aeration blowers with variable frequency drives for continuous-duty applications. The Kanto region concentrates precision pneumatic conveying demand for pharmaceutical and electronics manufacturing.
Brazil
ANVISA hygiene mandates expand pneumatic infrastructure in meat processing corridors. Protein plants deploy regenerative blowers for fragile granular material handling where oil-free operation is mandatory. The São Paulo state industrial cluster absorbs growing volumes of food-grade specification equipment.
Industrial Blowers Market Competitive Environment
Capability concentration sits with specialized turbomachinery houses; scale advantage sits with diversified compressor and ventilation conglomerates. The vendor base stratifies across three tiers: integrated air technology platforms, standalone blower specialists, and specification-grade ventilation engineers. Dominant competitive moves include cross-selling maintenance contracts through captive service networks and direct field technician deployment bypassing distribution layers.
Within the integrated platform tier, Atlas Copco leverages compressor service infrastructure to anchor aftermarket revenue streams, while Kaeser Kompressoren exemplifies captive distribution models with direct technical deployment. Greenheck Fan occupies a position in specification-grade ventilation where engineering relationships override procurement price sensitivity. These three archetypes represent divergent strategic postures: technology bundling, channel control, and application engineering depth.
| Leading Market Players |
|---|
| Atlas Copco |
| Ingersoll Rand |
| Aerzen |
| Howden Group |
| Continental Blower |
| Kaeser Kompressoren |
| Xylem |
| Loren Cook Company |
| Greenheck Fan |
| Others |
Value Chain & Pricing Dynamics
Rare earth magnet supply concentration in Chinese neodymium processing determines both pricing tier spreads across IE4 and IE5 motor classes and supply chain shape through captive sourcing requirements. Municipal wastewater buyers face acute budget compression from permanent magnet motor premiums while chemical processors absorb specification-grade costs under carbon accounting mandates.
Pricing Analysis
Aftermarket service revenue tiers—spanning preventive maintenance contracts, spare parts programs, and extended warranty bundles—drive lifetime value capture across blower installations. Three-tier pricing structure across premium magnetic bearing platforms, standard centrifugal units, and economy positive displacement models reflects efficiency certification levels and after-sales bundling intensity. Pricing pressure stems from IE4 and IE5 motor cost premiums stretching municipal procurement budgets. Food and beverage processors demonstrate lowest price sensitivity where contamination risks override procurement cost concerns.
Supply Chain Analysis
Upstream permanent magnet feedstock draws from Chinese rare earth processing concentration, South Korean motor component fabrication, and German precision bearing manufacturing. Aluminum alloy castings, coated carbon steel impeller forgings, and neodymium-dysprosium magnet assemblies constitute critical input dependencies. Single-source vulnerability in Chinese rare earth refining exposes OEMs to raw material volatility and tariff exposure. Distribution runs through captive field technician networks for specification-grade units and configurator platforms for standardized centrifugal blowers in light manufacturing.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Permanent magnet synchronous motor disruption is reshaping competitive positioning as efficiency mandates force accelerated replacement cycles across installed bases. EU F-Gas Regulation phase-down and China's dual carbon policy framework create simultaneous regulatory inflections across major demand corridors.
For Market Incumbents: Build captive service infrastructure moats through direct field technician deployment and magnetic bearing commissioning specialization. Atlas Copco's cross-selling of blower maintenance through compressor service networks exemplifies channel control leverage. Incumbents must accelerate backward integration into permanent magnet motor production to offset Chinese rare earth supply concentration risks.
For New Entrants and Emerging Players: Establish a beachhead in Indian process industries under PLI scheme manufacturing incentives where domestic assembly investments face limited entrenched competition. Carbon capture solvent regeneration applications for corrosion-resistant blower trains represent underdeveloped specification-grade demand. Direct-to-plant digital distribution platforms bypass traditional channel layers for standardized centrifugal units.
For Investors and Strategic Acquirers: EU F-Gas Regulation phase-down reshapes the acquisition landscape toward hermetic blower design capabilities and refrigerant containment expertise. Five-to-ten year viability favors targets with magnetic bearing technology depth and municipal wastewater utility relationships. Signal to monitor: IEC motor efficiency class upgrade timelines and their acceleration effects on replacement cycle velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Permanent Magnet Motors | Captive neodymium supply hedges Chinese processing concentration for IE4 and IE5 class production. |
| Magnetic Bearing Technology Licensing | Eliminates mechanical contact maintenance intervals for German and Dutch wastewater utility specifications. |
| Direct-to-Plant Digital Distribution | Configurator platforms bypass traditional layers for North American light manufacturing centrifugal procurement. |
| Carbon Capture Application Development | Amine stripping corrosion resistance opens specification-grade demand in steel and cement retrofit markets. |
| India PLI Scheme Manufacturing Footprint | Domestic assembly incentives attract subcontinent process industry demand under localized procurement preferences. |
Study Parameters
Cross-validation between OEM aftermarket service heads and municipal utility maintenance directors anchors the qualitative findings on procurement behavior and contract unbundling trends. Primary interviews with plant engineers at chemical processing facilities, food-grade pneumatic conveying operators, and wastewater treatment technical staff combined with secondary validation from customs trade data, SEC equipment manufacturer filings, and EU ETS carbon accounting disclosures. Bottom-up unit shipment estimates and top-down energy efficiency mandate impact modeling provide triangulation across the analysis window.
Calibration against historical replacement cycle velocities and regulatory compliance deadline clustering shaped the projection framework. Segmentation dimensions modeled include blower architecture type, application intensity tier, end-user industry vertical, power source efficiency class, and regional regulatory cluster. CAGRs derived from equipment retirement curves under tightening carbon accounting rules and efficiency mandate phase-in schedules. Permanent magnet motor cost trajectories and rare earth supply elasticity constitute industry-specific forecast inputs.
Stress conditions across neodymium price volatility bands, IEC motor efficiency class acceleration scenarios, and municipal budget constraint severities were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on regulatory enforcement consistency and technology substitution rates. Cross-checking against EPA Clean Air Act enforcement patterns and EU F-Gas Regulation implementation benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Global Air Conditioner Market
HVAC Equipment
Commercial Air Conditioner (AC) Market
HVAC Equipment
North America Air to Water Heat Pump Market
HVAC Equipment
Europe Ventilation Equipment Market
HVAC Equipment
Europe Air Conditioning Equipment Market
HVAC Equipment
United States Heat Exchanger Market
HVAC Equipment
Germany Heat Pump Market
HVAC Equipment
Duct Fans Market
HVAC Equipment
Canada Commercial HVAC Market
HVAC Equipment
Desert Air Cooler Market
HVAC Equipment
Commercial Water Heater Market
HVAC Equipment
North America Air Conditioning Equipment Market
HVAC Equipment
Industrial Insulation Testers Market
HVAC Equipment
GCC Portable Air Conditioners Market
HVAC Equipment
Chilled Beams Market
HVAC Equipment
Europe Heat Exchanger Market