
 Global HVAC Linesets Market | 2026-2036
Global HVAC Linesets Market Size, Share, and Industry Trends Forecast 2026-2036
Global HVAC Linesets Market Outlook
Asian copper tube producers is shifting capacity toward thinner-walled, high-efficiency linesets for inverter-driven heat pumps. Mueller Streamline Co. leverages vertical integration from copper rod to finished coil to control cost volatility across North American distribution. Zhejiang Hailiang Co., Ltd. anchors its position through captive refining and seamless tube capacity that dominates exports to Southeast Asian OEMs. Hydro competes on low-carbon primary metal certification, differentiating its offering for European projects bound by CSRD supply-chain disclosure rules.
HVAC linesets are paired insulated refrigerant tubing assemblies, typically comprising copper or aluminum conductors sheathed in UV-resistant polyethylene foam, engineered to transport compressed refrigerant between outdoor condensing units and indoor evaporators. The tubing wall thickness, insulation thermal conductivity, and flare joint geometry determine system energy efficiency and leak resistance under cyclic pressure loads. Cu Linesets retain the dominant share in premium installations where thermal conductivity and braze reliability justify material cost, while Al Linesets gain ground in price-sensitive residential markets where installation labor rather than material performance drives contractor preference. Heat Pumps represent the fastest-expanding application segment as electrification policies displace fossil-fired heating across temperate climates.
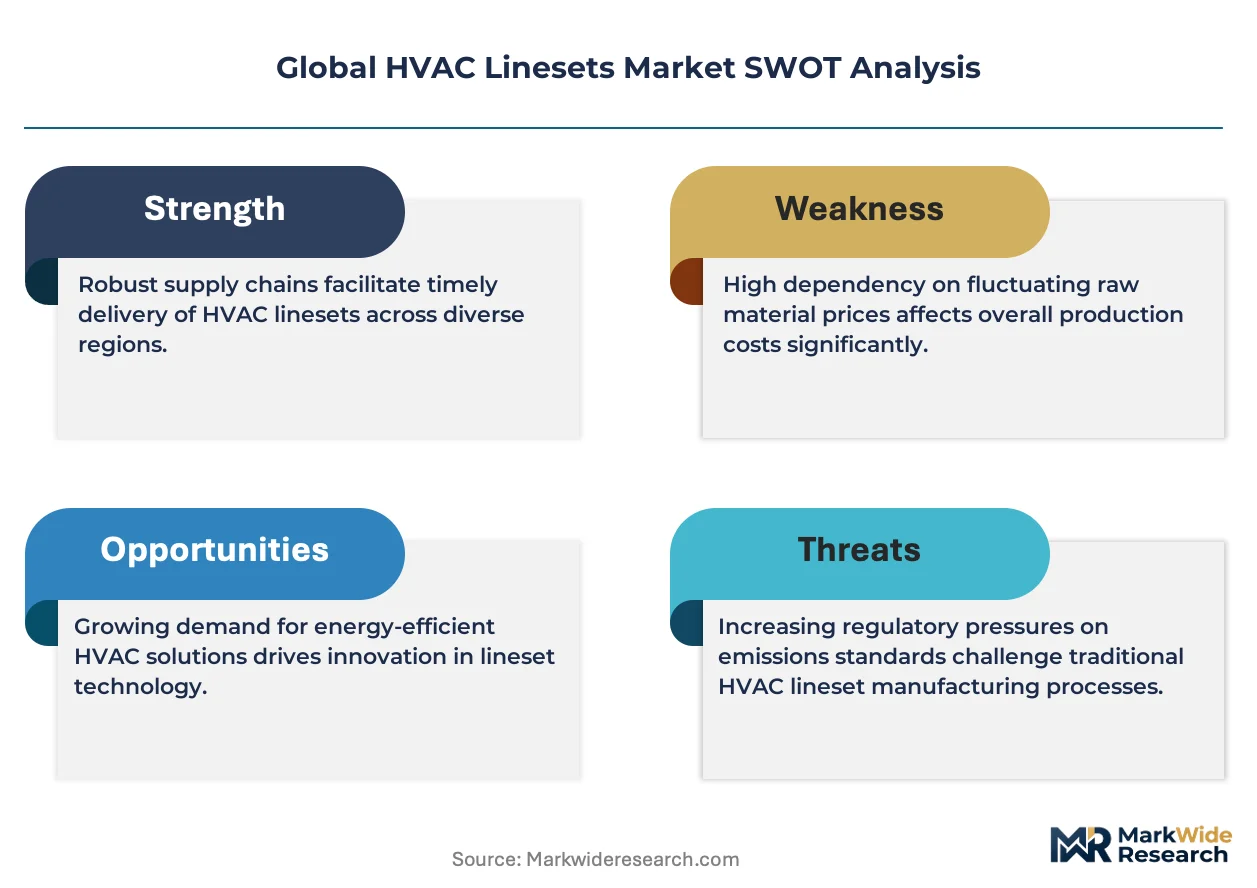
The EPA regulates refrigerant handling and lineset evacuation standards under Section 608 of the Clean Air Act, compelling technicians toward certified low-loss installation practices. Ecodesign requirements under the EU F-Gas Regulation mandate minimum insulation values for split-system interconnects, effectively filtering non-compliant imports from third-country suppliers. China's GB standards specify copper purity grades and pressure-test protocols that OEMs must verify for domestic certification. Stakeholders must track how refrigerant transitions from R-410A to lower-GWP alternatives reshape flare geometry and pressure-class specifications across their product portfolios.
Market Dynamics
Building electrification mandates across temperate zones are compressing installation timelines and forcing refrigerant line specifications toward higher pressure classes and thinner wall geometries. This structural pull is reconfiguring supplier qualification requirements and OEM sourcing footprints simultaneously.
Growth Catalysts
- EU F-Gas Regulation phase-down:The refrigerant quota system accelerates heat pump retrofits across Germany, Poland, and France, generating wholesale replacement demand for legacy split-system interconnects.
- Inverter-driven compressor technology:Variable-speed heat pumps require linesets rated for higher cyclic pressure loads, pushing specification upgrades across residential and light-commercial installations.
- China's MIIT efficiency standards:Domestic OEMs must source GB-certified copper tubing with verified purity grades, filtering out non-compliant imports and consolidating procurement toward certified suppliers.
Market Restraints
- Copper price volatility:LME copper futures swings above 15% annually compress fabricator margins and destabilize contractor bidding for fixed-price installation contracts.
- Concentrated primary metal supply:Chilean and Peruvian mine output disruptions transmit directly to tube mill feedstock costs, exposing downstream lineset assemblers to input scarcity.
- Aluminum substitution ceiling:Thermal conductivity gaps and flare joint reliability concerns limit aluminum lineset penetration in commercial applications above 5-ton cooling capacity.
Strategic Opportunities
- US Inflation Reduction Act heat pump incentives:The 30% tax credit for qualifying equipment extends through 2032, creating sustained demand pull for residential lineset pairs across the Southeast and Midwest.
- Pre-insulated modular linesets:Factory-sealed assemblies with integrated flare nuts and UV-resistant cladding reduce field installation labor by 40%, appealing to contractor shortages in Australia and Canada.
- Refrigerant transition services:R-410A to R-32/R-454B conversions require pressure-class upgrades and flare geometry changes, opening retrofit specification windows for qualified suppliers.
Industry Challenges
- EPA Section 608 certification bottlenecks:Technician shortage for low-loss evacuation and refrigerant handling compliance extends project timelines and inflates labor rates in US metropolitan markets.
- CSRD supply-chain disclosure complexity:European OEMs now require embodied carbon documentation and smelter traceability, forcing tier-2 tube mills to implement audit-ready data systems.
- Legacy flare joint incompatibility:Existing installation tool inventories and technician muscle memory create friction against 45-degree flare adoption for A2L refrigerant systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global HVAC Linesets Market |
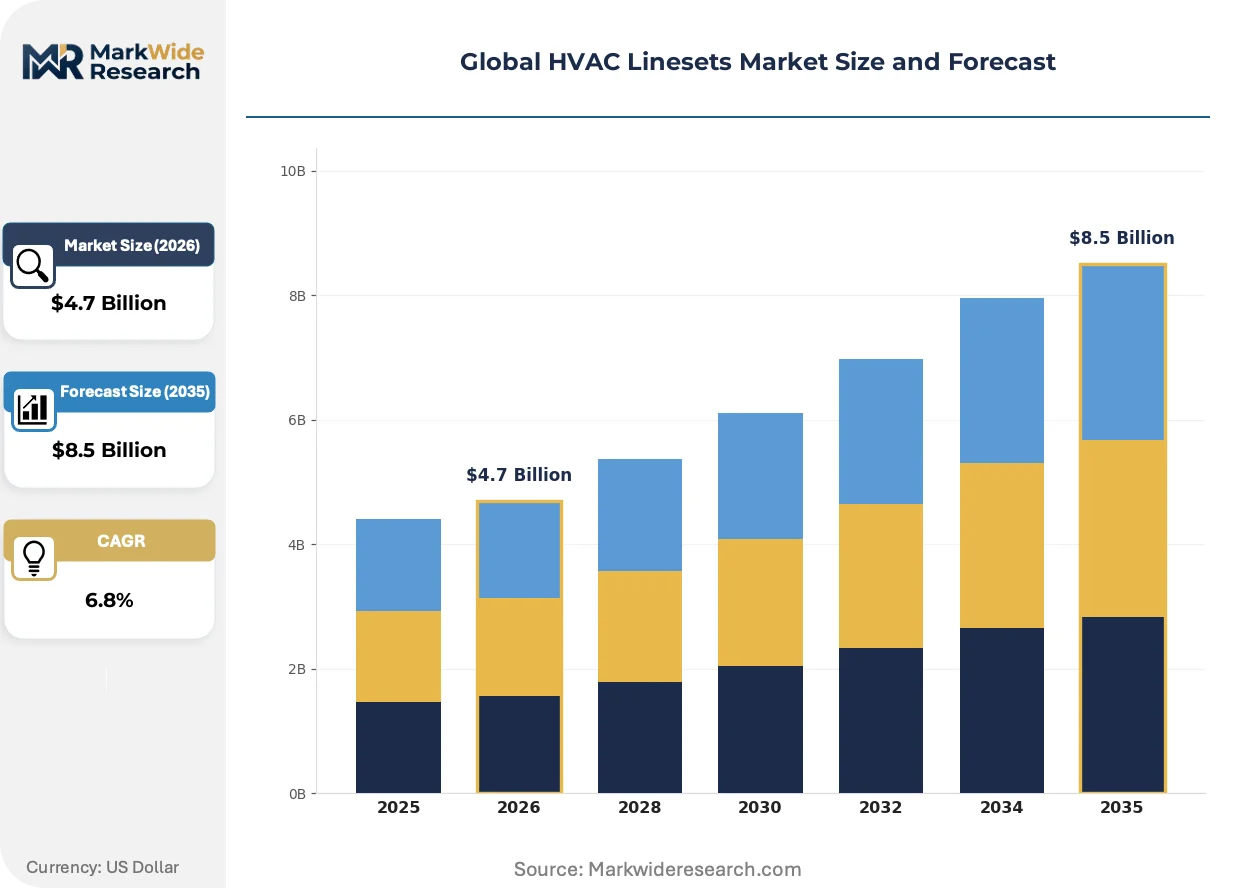
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $8.5 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cu Linesets, Al Linesets, PVC Linesets, Other Materials Installation Type: Residential, Commercial, Industrial, Renovation Application: Air Conditioning, Refrigeration, Heat Pumps, Ventilation End User: Installers, Contractors, Distributors, OEMs |
| Companies Covered | Mueller Streamline Co., Cerro Flow Products LLC, JMF Company, Halcor, Zhejiang Hailiang Co., Ltd., Feinrohren S.p.A, Hydro, KME SE, Diversitech Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global HVAC Linesets Market Strategic Shifts
Refrigerant chemistry transitions and installation labor scarcity are jointly forcing product architecture toward pre-engineered, higher-pressure-rated assemblies that reduce field complexity.
Microchannel aluminum tubing is expanding into residential heat pump linesets as a weight-reduction strategy. Japanese and Korean OEMs specify this material for wall-mounted inverter units under 3 tons, where thermal performance tradeoffs are acceptable. The technology is expanding into European renovation markets where crane access limitations favor lighter outdoor condensing units.
The EU F-Gas Regulation's 2027 quota cuts are mandating lower-GWP refrigerant adoption across split-system supply chains. A2L-class mildly flammable refrigerants require linesets with thicker insulation barriers and revised flare geometries. German and Italian HVAC distributors are pre-staging compliant inventory ahead of the enforcement window to avoid installation delays.
Direct-to-contractor digital procurement platforms are compressing traditional two-step distribution through HVAC wholesalers. Independent installers in the US and Australia now specify lineset SKUs through mobile apps with same-day fulfillment from regional fulfillment centers. This channel shift is most visible in residential replacement markets where project timelines measure in days rather than weeks.
Global HVAC Linesets Market Segmentation
HVAC lineset specifications diverge sharply across installation contexts, with material chemistry, pressure ratings, and insulation standards calibrated to end-use thermal loads and regulatory exposure. Segment boundaries are hardening as refrigerant transitions and electrification mandates force incompatible technical requirements across product tiers.
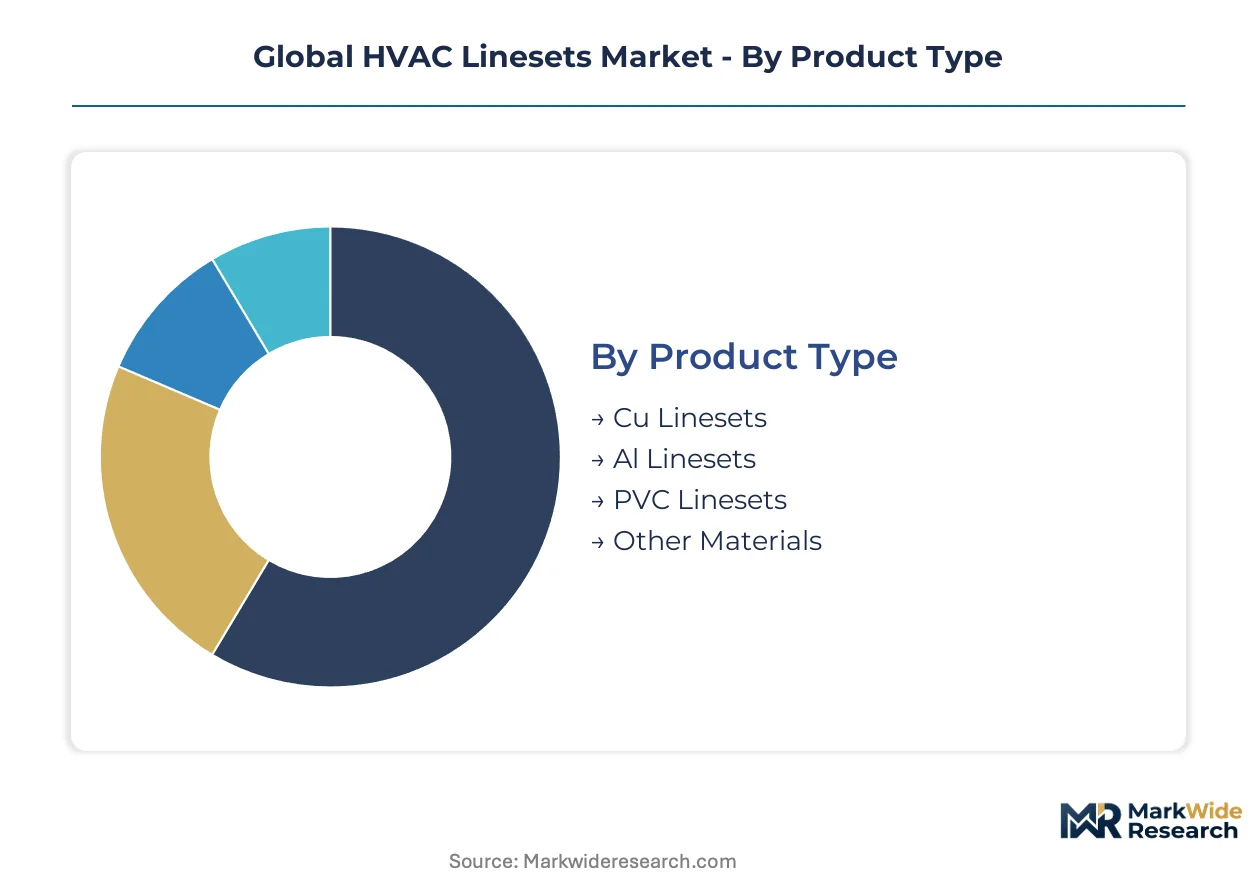
Product Type:
Tube mill capacity concentrates in East Asian copper refining corridors and Gulf Coast aluminum extrusion clusters, creating divergent feedstock security profiles for each material class.
- Cu Linesets:Oxygen-free copper tubing with 0.8-1.2mm wall thickness delivers superior thermal conductivity and braze joint integrity for high-pressure R-32 systems. Demand clusters in German renovation markets where F-Gas Regulation compliance mandates leak-resistant interconnects for heat pump retrofits.
- Al Linesets:Microchannel aluminum extrusions with polymer barrier coatings reduce weight by 60% versus copper equivalents. Southeast Asian OEMs specify these for residential inverter units under 3 tons, though flare reliability concerns limit penetration in commercial applications above 5-ton capacity.
- PVC Linesets:Reinforced polymer tubing with embedded wire braid serves drainage and low-pressure vapor lines in cost-optimized split systems.
- Other Materials:Composite hybrid constructions and stainless steel variants address corrosive coastal environments and specialized industrial process cooling.
Today's leader: Cu Linesets. Tomorrow's challenger: Al Linesets.
Installation Type:
Project scale and labor availability determine whether specifications prioritize field flexibility or factory precision.
- Residential:Pre-insulated coil pairs with integrated flare nuts dominate replacement markets where technician shortages in Australia and Canada favor 40% labor reduction. Volume concentrates in US Southeast and Midwest corridors where IRA heat pump incentives sustain demand.
- Commercial:Custom-fabricated hard-drawn copper assemblies with brazed joints serve rooftop units and VRF distribution networks. Procurement shifts toward qualified fabricators capable of pressure testing and refrigerant evacuation certification.
- Industrial:Heavy-wall seamless tubing with welded joints addresses ammonia and process cooling loads in food processing and data center applications.
- Renovation:Flexible mini-split interconnects with kink-resistant armor replace legacy R-410A linesets during refrigerant transition projects across Poland and France.
Renovation climbs fastest as building electrification mandates compress retrofit timelines across temperate European markets.
Application:
Refrigerant chemistry and thermodynamic cycle requirements fragment specifications across cooling, heating, and ventilation functions.
- Heat Pumps:Bidirectional linesets rated for higher cyclic pressure loads and enhanced insulation thermal resistance serve variable-speed compressors. EU Green Deal building electrification mandates accelerate specification upgrades across Germany, Poland, and France.
- Air Conditioning:Standard split-system pairs with UV-resistant polyethylene foam cladding address peak cooling demand in Southeast Asian and US Sun Belt markets.
- Refrigeration:Low-temperature-rated assemblies with vapor-proof insulation barriers serve supermarket display cases and cold storage distribution.
- Ventilation:Flexible ducting and low-pressure tubing links energy recovery ventilators to central air handlers in tight-building envelopes.
Heat Pumps gain share fastest as fossil-fired heating displacement policies reconfigure equipment mix across OECD temperate zones.
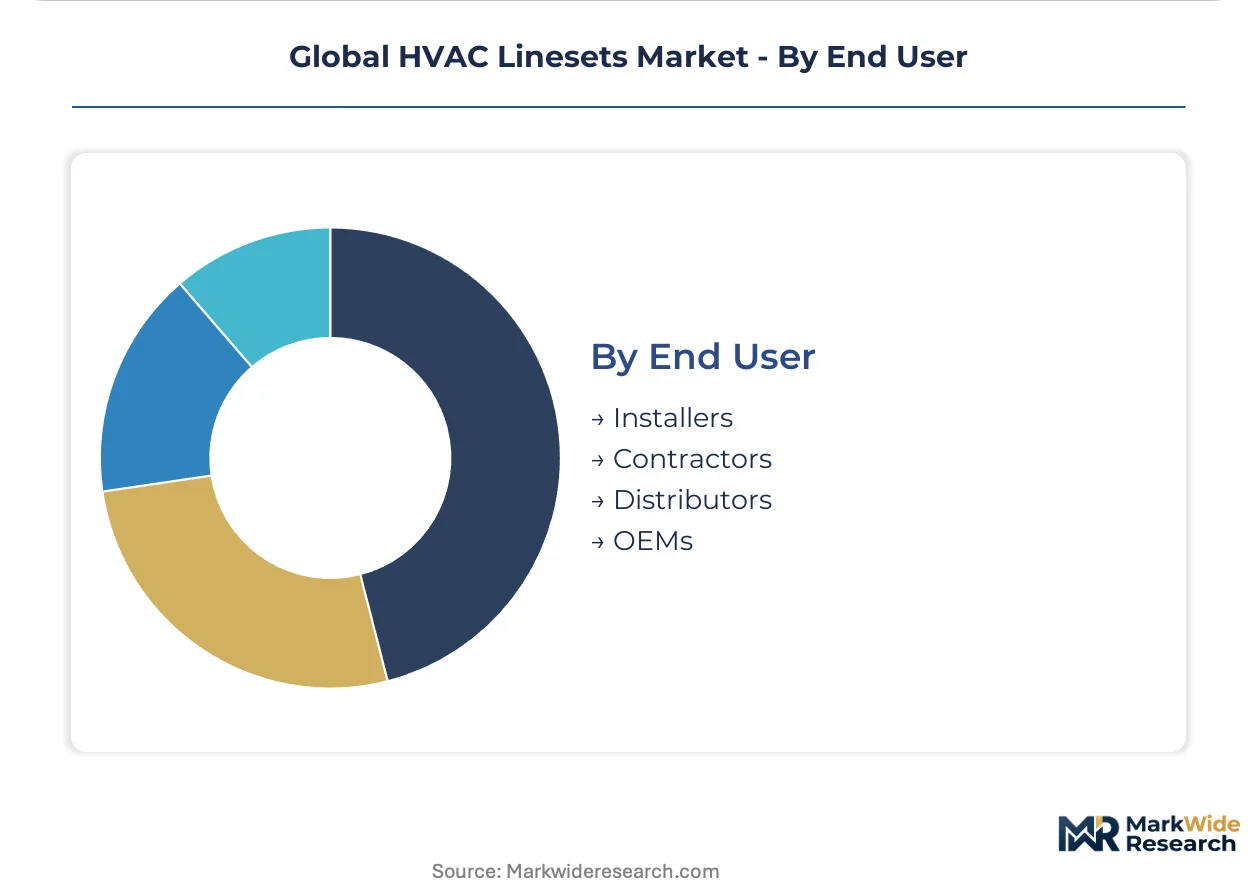
End User:
Channel structure and technical capability determine whether procurement emphasizes price, availability, or specification compliance.
- Installers:Mobile-app procurement from regional fulfillment centers compresses traditional wholesaler intermediation for residential replacement projects with day-scale timelines.
- Contractors:Fixed-price bidding exposure to copper volatility drives preference for pre-negotiated annual supply agreements with tube mill direct sources.
- Distributors:Inventory pre-positioning of A2L-compliant linesets ahead of EU F-Gas quota cuts distinguishes German and Italian HVAC supply houses.
- OEMs:Captive tubing specifications with verified purity grades and pressure-test protocols filter procurement toward GB-certified Chinese suppliers and vertically integrated North American producers.
OEMs command specification authority today. Installers are capturing channel power through digital disintermediation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redrawing production maps as tube mills migrate toward jurisdictions with lower carbon-accounting burdens and streamlined certification pathways. Cost-of-compliance gaps between the EU's CSRD disclosure regime and China's GB standards are accelerating capacity shifts across East Asian copper refining corridors.
United States
IRA heat pump tax credits are compressing residential installation timelines across the Southeast and Midwest. EPA Section 608 enforcement tightens technician certification requirements for low-loss evacuation practices. Gulf Coast aluminum extrusion clusters around Houston and New Orleans are scaling microchannel capacity for lightweight residential inverter units.
Germany
F-Gas Regulation phase-down mandates are driving wholesale replacement of legacy R-410A split-system interconnects in renovation markets. The EU Green Deal's building electrification targets tighten insulation performance standards for bidirectional heat pump linesets. Industrial fabricators in Bavaria and North Rhine-Westphalia are pre-staging A2L-compliant inventory ahead of 2027 quota cuts.
China
MIIT efficiency standards are filtering domestic OEM procurement toward GB-certified copper tubing with verified purity grades. Dual carbon goals are pressuring Yangtze River Delta smelters to document embodied carbon for export-bound tube mills. Captive refining operations in Zhejiang province dominate seamless tube exports to Southeast Asian OEM assembly plants.
Japan
METI-backed heat pump adoption targets are accelerating specification upgrades for variable-speed compressor interconnects. JIS pressure-test protocols differentiate domestic-certified suppliers from import competitors. Osaka-based fabricators are developing thinner-walled, high-efficiency linesets for wall-mounted inverter units under 3 tons.
Australia
Technician shortages in Sydney and Melbourne are pulling demand toward pre-insulated modular linesets with 40% field labor reduction. State-level building electrification mandates in New South Wales and Victoria are displacing fossil-fired heating in residential retrofits. Regional fulfillment centers in Brisbane are enabling same-day procurement through direct-to-contractor digital platforms.
Global HVAC Linesets Market Competitive Environment
East Asian producers anchor the scale-driven tier; European specialists hold premium positions through low-carbon certification. The vendor base stratifies across vertically integrated copper refiners, aluminum extrusion houses, and regional fabrication specialists. Three archetypes dominate: captive smelter-tube mills with backward integration into ore supply; modular assembly specialists serving contractor-direct channels; and carbon-certified European suppliers qualifying for CSRD-bound projects. Consolidation is accelerating through smelter acquisitions and regional distribution partnerships.
Among North American fabricators, Mueller Streamline Co. and Cerro Flow Products LLC exemplify the vertically integrated archetype, controlling cost volatility through captive copper rod production. Zhejiang Hailiang Co., Ltd. occupies a position within the East Asian export tier, leveraging seamless tube capacity for Southeast Asian OEM supply. These three represent the dominant competitive vectors: upstream integration, regional scale, and export specialization.
| Leading Market Players |
|---|
| Mueller Streamline Co. |
| Cerro Flow Products LLC |
| JMF Company |
| Halcor |
| Zhejiang Hailiang Co., Ltd. |
| Feinrohren S.p.A |
| Hydro |
| KME SE |
| Diversitech Corporation |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap fabricators in Germany's North Rhine-Westphalia cluster anchor premium pricing through CSRD-compliant carbon certification, while sovereign-backed Chinese producers in Zhejiang province undercut on spot markets by absorbing copper volatility through captive refining. This ownership divergence creates bifurcated supply behavior: European specialists withhold volume to defend margin, Asian scale players flood channels to capture OEM procurement share.
Pricing Analysis
Distributor margin compression in North American residential channels is forcing specification-grade suppliers toward direct-to-contractor digital platforms. Three-tier pricing structure across premium, standard, and economy levels separates A2L-certified assemblies with thickened insulation from legacy R-410A pairs and unbranded imports. Cost compression in the economy tier is intensifying because LME copper futures swings above 15% annually destabilize fixed-price bidding. Residential installers show highest price sensitivity, while German renovation contractors prioritize leak-resistant certification over unit cost.
Supply Chain Analysis
Freight cost spikes on Asia-Europe routes are accelerating regionalization of tube mill capacity toward Gulf Coast aluminum extrusion clusters and Yangtze River Delta copper refining corridors. Feedstock security draws from Chilean mine concentrate, Peruvian cathode, and domestic Chinese blister copper. Single-source vulnerability concentrates in Andean mine output disruptions that transmit directly to downstream fabricator input scarcity. Distribution runs through HVAC wholesalers in mature markets, direct-to-contractor fulfillment centers in technician-scarce geographies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Building electrification mandates across temperate zones create geographic-arbitrage opportunities: EU F-Gas Regulation compliance costs in Germany and France exceed China's MIIT certification burden by a factor that justifies Southeast Asian export capacity repositioning.
For Market Incumbents: Acquire seamless tube fabrication assets in Zhejiang province to lock in GB-certified copper supply for Southeast Asian OEM procurement. Defend margin position by pre-staging A2L-compliant inventory ahead of EU quota enforcement, filtering non-compliant imports from third-country competitors. Channel control through contractor-direct digital platforms reduces distributor margin leakage in technician-scarce Australia and Canada markets. For New Entrants and Emerging Players: Regional fulfillment centers represent the most penetrable infrastructure gap, particularly where same-day procurement apps compress traditional two-step distribution. Target residential replacement markets in the US Southeast where IRA heat pump incentives sustain demand pull with compressed project timelines. White-space exists in pre-insulated modular assemblies with integrated flare nuts that reduce field labor by 40%. For Investors and Strategic Acquirers: Copper tube mills with captive smelter integration are the most active acquirer in this space, consolidating ore supply security as LME volatility intensifies. Long-term viability hinges on carbon-accounting differentiation for CSRD-bound European projects. Acquisition target archetype: mid-cap fabricators with pressure-test certification and refrigerant transition service capability. Watch German distributor inventory pre-positioning rates as inflection indicator for A2L adoption velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Copper Refining | Zhejiang province smelters secure ore supply against Chilean mine disruption risk. |
| A2L Refrigerant Transition Service Launch | German fabricators capture retrofit specification windows ahead of F-Gas quota cuts. |
| Pre-Insulated Modular Assembly Scale-Up | Australian contractors reduce field labor 40% amid Sydney-Melbourne technician shortages. |
| Direct-to-Contractor Digital Platform Deployment | US Southeast installers bypass wholesaler markup through same-day regional fulfillment. |
| CSRD-Compliant Carbon Certification Investment | European OEM procurement filters toward audit-ready embodied carbon documentation. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary discussions with HVAC procurement managers at Southeast Asian OEMs, German renovation contractors, US residential installers, Chinese tube mill operations directors, and copper concentrate traders informed demand-side and supply-side dynamics. Secondary validation drew from EPA Section 608 enforcement data, EU F-Gas Regulation quota filings, China MIIT GB standard updates, LME copper futures archives, and customs trade flows. Bottom-up segment sizing and top-down macro constraint checks were cross-referenced for triangulation.
Historical reference periods anchored volume and value projections across the analysis window. The analytical framework modeled segmentation across material chemistry, installation type, application, and end-user channel structure. CAGRs were derived from install-base replacement cycles, refrigerant transition timelines, and electrification policy implementation curves. Forecast inputs included heat pump adoption rates under EU Green Deal mandates and IRA tax credit utilization patterns in US residential markets.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to copper price volatility, Andean mine supply disruptions, and technician certification bottlenecks under EPA Section 608. Forecasts reflect documented assumptions about refrigerant transition pace and regulatory enforcement timing. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
North America HVAC Equipment Market
HVAC Equipment
Global Air Conditioner Market
HVAC Equipment
Compact Fan Coils Market
HVAC Equipment
Dedicated Outdoor Air System Market
HVAC Equipment
Compressor Controllers Market
HVAC Equipment
Positive Displacement Blowers Market
HVAC Equipment
Warm Air Heater Market
HVAC Equipment
Air Conditioning Equipment Market
HVAC Equipment
Middle-East and Africa Compressor Market
HVAC Equipment
North America Commercial HVAC Market
HVAC Equipment
North America Gas Water Heater Market
HVAC Equipment
Wall Fan Coil Market
HVAC Equipment
GCC Kitchen Hood Market
HVAC Equipment
India Residential Heat Pump Market
HVAC Equipment
Utility and Industrial Boilers Market
HVAC Equipment
Welded Spiral Heat Exchangers Market