
 Middle East and Africa Commercial HVAC Market | 2026-2036
Middle East and Africa Commercial HVAC Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Commercial HVAC Market Insights
Project finance tied to energy performance contracts is reconfiguring competitive access across the Middle East and Africa Commercial HVAC landscape. Johnson Controls International Plc leverages its building automation integration to anchor large district cooling concessions in the Gulf. Carrier Global Corp sustains factory-level presence through captive component sourcing for screw chiller lines. Daikin Industries Ltd dominates variable refrigerant flow deployments across commercial office towers in Dubai and Riyadh.
Middle East and Africa Commercial HVAC encompasses engineered climate systems designed to maintain indoor air quality, temperature, and humidity across non-residential built environments, typically operating at capacities from 5 tons to over 2,000 tons with coefficient of performance ratings governing energy transfer efficiency. Centrifugal chillers occupy the premium tier in district cooling plants where scale economics justify first-cost outlays, while variable refrigerant flow systems extend fastest across retrofit-intensive commercial office segments seeking zoned control without structural overhaul. Smart HVAC platforms now capture margin pools through predictive maintenance subscriptions, shifting value from hardware-only transactions to recurring software revenue.
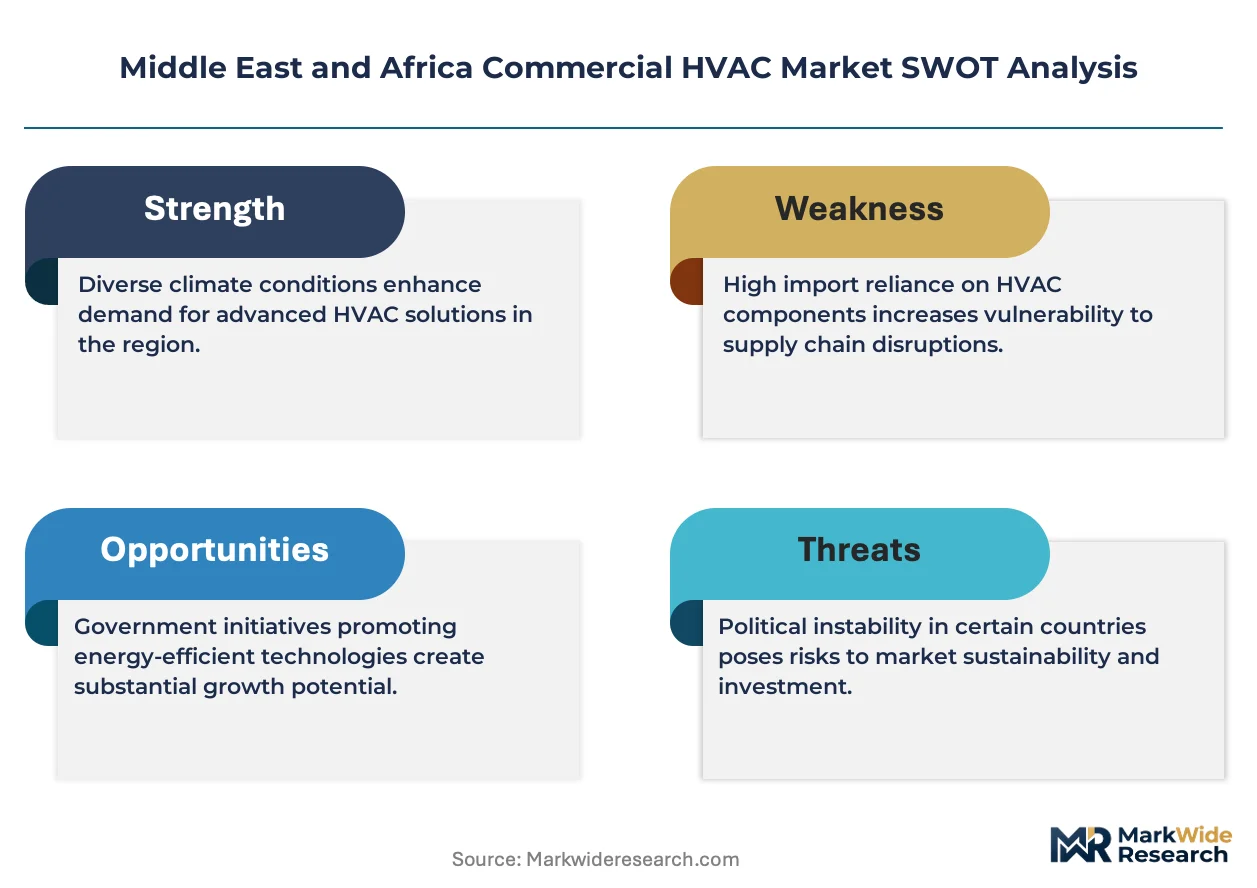
Saudi Arabia's SFDA and the UAE's MOHAP enforce indoor air quality standards that shape hospital and pharmaceutical facility specifications, while municipal green building codes across Dubai and Abu Dhabi mandate minimum efficiency indices for new commercial construction. The region's regulatory divergence between Gulf standardization and sub-Saharan alignment with ISO frameworks fragments certification requirements. Stakeholders must monitor which efficiency tier emerging African commercial hubs adopt, as this choice will determine whether low-cost absorption chiller imports or premium European VRF systems capture nascent institutional demand.
Market Dynamics
District cooling concessions across the Gulf Cooperation Council are redrawing competitive boundaries as energy performance contracts displace conventional equipment-only procurement. Sovereign wealth-backed infrastructure funds now bundle financing, construction, and long-term operation into single-tender packages that favor vertically integrated system providers.
Growth Catalysts
- SFDA Efficiency Mandates:Saudi Arabia's pharmaceutical and hospital construction pipeline now enforces seasonal coefficient of performance minimums, forcing mechanical cooling upgrades in Riyadh and Jeddah medical zones.
- Healthcare Expansion:MOHAP-licensed hospital projects across Abu Dhabi and Dubai absorb premium chiller volumes as bed capacity targets drive intensive care and operating theater climate specifications.
- Desalination Integration:Coastal district cooling plants in the UAE leverage waste heat from reverse osmosis facilities, cutting operational energy intensity for commercial district networks.
Market Restraints
- Copper and Aluminum Volatility:Heat exchanger and compressor housing costs fluctuate with London Metal Exchange pricing, compressing margin visibility for project bids with 18-24 month delivery horizons.
- European Component Concentration:Electronic expansion valves and advanced refrigerant sensors ship predominantly from German and Italian specialist manufacturers, creating single-source vulnerability for Gulf-based integrators.
- Water Scarcity Constraints:Cooling tower makeup requirements face municipal allocation caps in Doha and Kuwait City, limiting evaporative chiller deployment despite superior thermodynamic performance.
Strategic Opportunities
- Sub-Saharan Commercial Hubs:Lagos and Nairobi institutional construction lacks mature district cooling infrastructure, creating first-mover positioning for packaged chiller and VRF system providers.
- Refrigerant Transition:The phasedown of high-global-warming-potential hydrofluorocarbons under the Kigali Amendment opens retrofit demand for low-GWP alternatives across existing UAE office stock.
- Digital Twin Convergence:Building information modeling platforms merging with real-time sensor networks enable predictive maintenance subscriptions that extend contractor revenue beyond hardware installation.
Industry Challenges
- Commissioning Specialist Scarcity:Certified TAB (testing, adjusting, balancing) technicians for large-tonnage centrifugal installations remain concentrated in European and North American labor pools, delaying Gulf project handovers.
- Legacy BAS Integration:Proprietary communication protocols from 1990s-era building automation systems resist interoperability with modern IoT-enabled HVAC controllers, forcing expensive gateway middleware in Dubai retrofit projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Commercial HVAC Market |
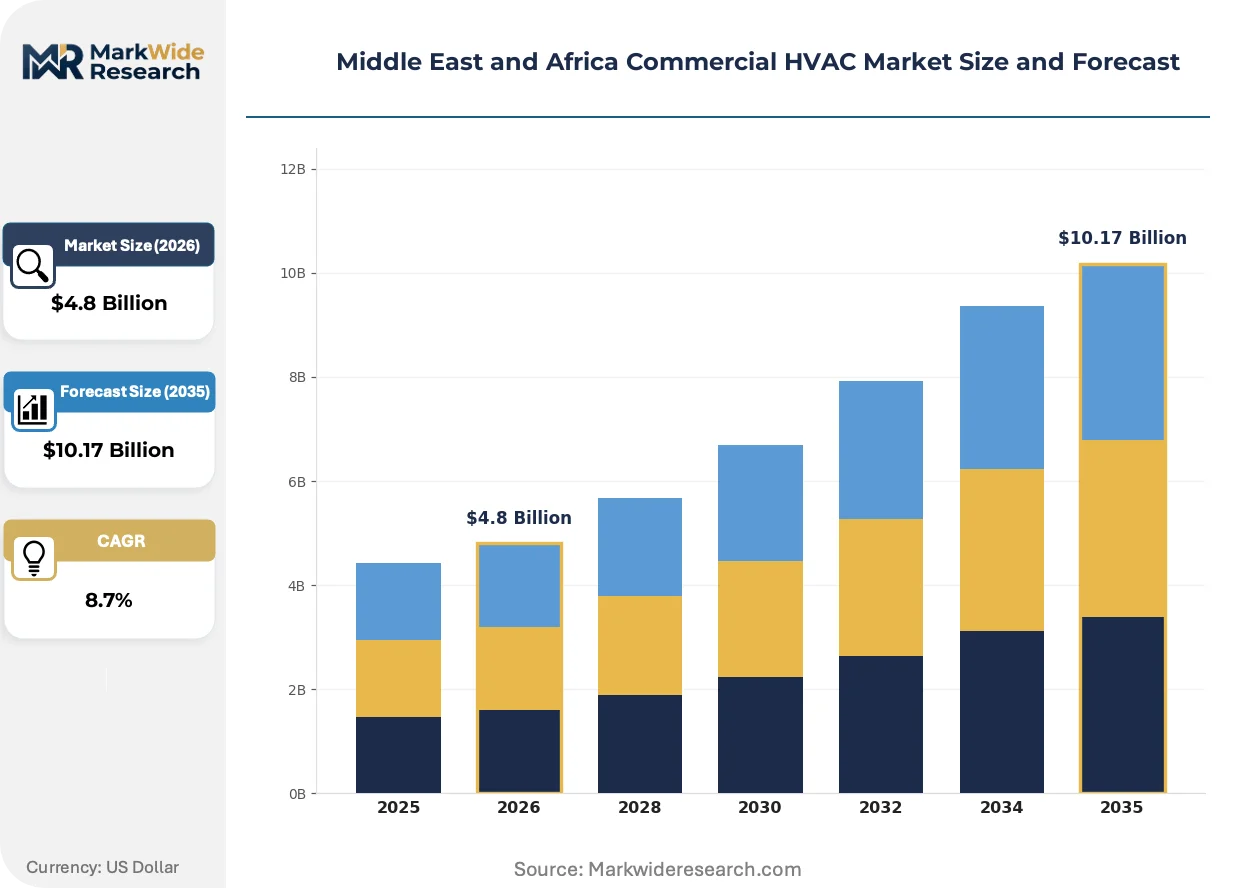
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Centrifugal Chillers, Screw Chillers, Absorption Chillers, Rooftop Units Technology: Variable Refrigerant Flow, Chilled Beam, Thermal Energy Storage, Smart HVAC End User: Commercial Offices, Shopping Malls, Hospitals, Educational Institutions Installation: New Installations, Retrofits, Overhauls, Maintenance Services |
| Companies Covered | Daikin Industries Ltd, Johnson Controls International Plc, Carrier Global Corp, Lennox International Inc, Trane Technologies Plc, Schneider Electric SE, Honeywell International Inc, Zamil Air Conditioners, Robert Bosch GmbH, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Commercial HVAC Market Trends and Innovations
Digital replication of physical cooling infrastructure is compressing commissioning cycles and enabling remote diagnostics across dispersed commercial portfolios. This virtualization layer is shifting value capture from hardware margins to software-enabled service contracts.
Artificial intelligence-driven fault detection and diagnostics is virtualizing the traditional maintenance dispatch model. Facility managers in Riyadh commercial towers now receive automated refrigerant leak alerts and compressor degradation forecasts before thermal comfort thresholds breach. This capability is compressing aftermarket service revenue into predictive subscription streams that displace break-fix contracts.
The UAE's MOHAP and Saudi SFDA have tightened indoor air quality enforcement for healthcare facilities, mandating continuous particle monitoring and pressure differential logging. These requirements are forcing HVAC specification upgrades in hospital new-builds and triggering retrofit demand in aging clinical infrastructure. Pharmaceutical manufacturing zones across Jeddah and Dubai Science Park face the strictest compliance timelines.
Energy-as-a-service contracting is displacing capital purchase models for large commercial cooling systems. Corporate real estate teams in Abu Dhabi and Doha now prefer operational expenditure structures that transfer efficiency risk to equipment providers. This preference shift concentrates procurement authority with finance and sustainability officers rather than traditional engineering departments, altering vendor sales cycle dynamics across Gulf commercial office segments.
Middle East and Africa Commercial HVAC Market Segmentation
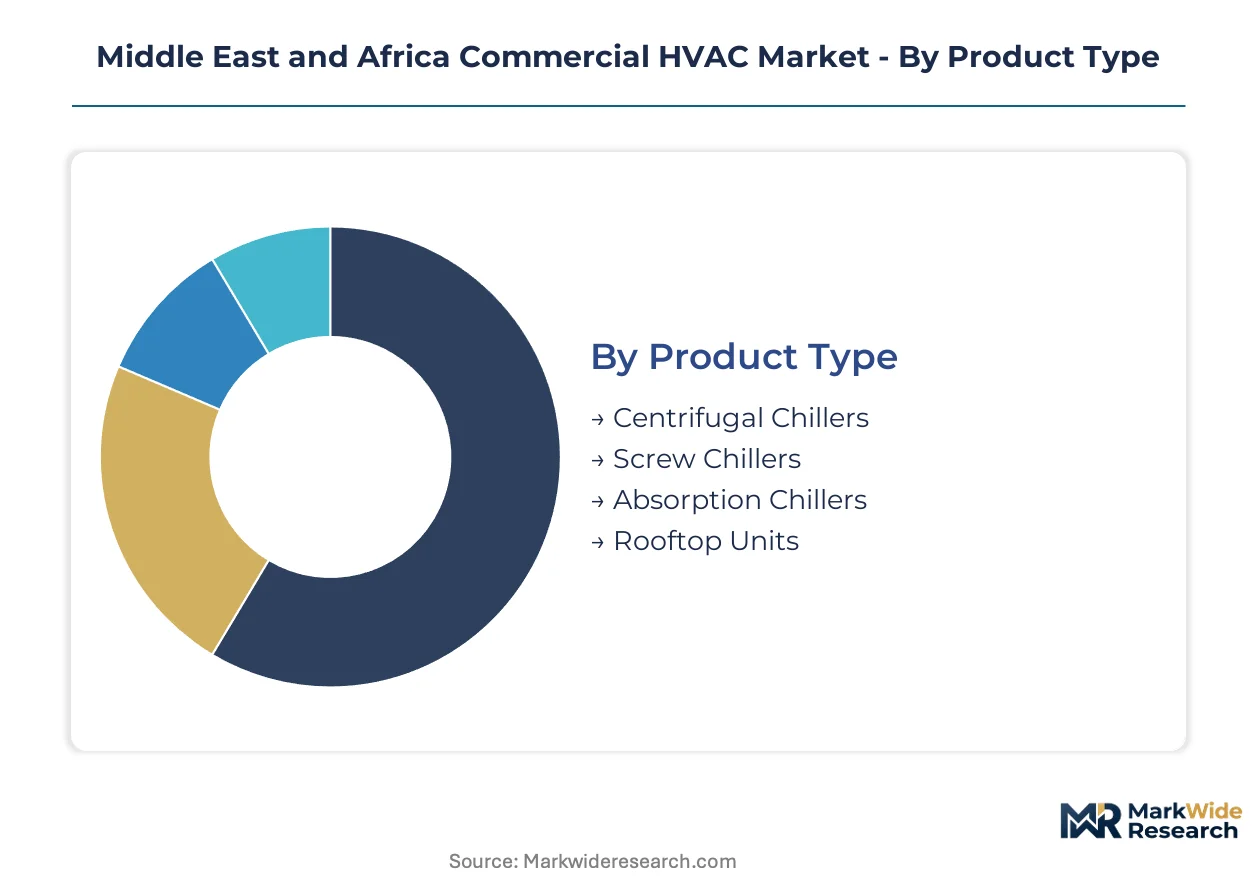
Segmentation in the Middle East and Africa Commercial HVAC market reveals how equipment specifications diverge between Gulf district cooling infrastructure and sub-Saharan packaged systems. Understanding these splits exposes where margin pools concentrate and which technology transitions will reshape procurement patterns.
Product Type:
Cost tier determines equipment selection across the region's divergent project scales.
- Centrifugal Chillers:High-capacity turbomachinery operating above 500 tons, optimized for district cooling plants where scale economics justify capital intensity. Demand concentrates in Dubai and Abu Dhabi district cooling concessions where sovereign wealth-backed operators seek 25-year operational lifespans.
- Screw Chillers:Positive displacement compressors spanning 30-500 tons, balancing part-load efficiency with first-cost accessibility. Saudi Arabia's SFDA-mandated hospital construction across Riyadh and Jeddah absorbs premium screw chiller volumes for clinical climate control.
- Absorption Chillers:Heat-activated cooling systems leveraging waste heat or solar thermal inputs.
- Rooftop Units:Packaged air handlers integrating compressors, coils, and controls in weatherized enclosures.
Centrifugal systems command the established base in Gulf district infrastructure. The steepest expansion runs through screw chillers as Saudi healthcare construction accelerates.
Technology:
Application requirements drive technology adoption across building types with distinct climate control needs.
- Variable Refrigerant Flow:Refrigerant-based zoned climate systems enabling individual temperature control without ductwork. Dubai and Riyadh commercial office towers deploy VRF for retrofit-intensive segments seeking operational flexibility without structural overhaul.
- Chilled Beam:Hydronic radiant cooling panels delivering silent thermal conditioning. UAE healthcare facilities under MOHAP air quality mandates specify active chilled beams for operating theaters requiring precise humidity control.
- Thermal Energy Storage:Ice or chilled water reservoirs shifting cooling load to off-peak hours.
- Smart HVAC:Sensor-integrated platforms with predictive analytics and automated fault detection.
Variable Refrigerant Flow dominates the installed base across commercial office retrofits. The steepest expansion trajectory belongs to Smart HVAC as energy performance contracts displace conventional procurement.
End User:
Customer type determines specification intensity and procurement authority structures.
- Commercial Offices:Tenant-driven climate systems prioritizing zoned control and operational expenditure flexibility. Abu Dhabi and Doha corporate real estate teams now prefer energy-as-a-service contracting that transfers efficiency risk to equipment providers.
- Hospitals:Critical-care infrastructure demanding continuous particle monitoring and pressure differential compliance. Saudi SFDA and UAE MOHAP enforcement of indoor air quality standards forces HVAC specification upgrades in new-build and retrofit clinical infrastructure.
- Shopping Malls:High-occupancy retail environments with variable load profiles.
- Educational Institutions:Campus-scale climate systems serving fragmented building ages and usage patterns.
Hospitals command the established base for premium equipment specifications. The steepest expansion runs through commercial offices as energy performance contracts reconfigure procurement dynamics.
Installation:
Maturity of building stock determines service mix across the region's divergent construction cycles.
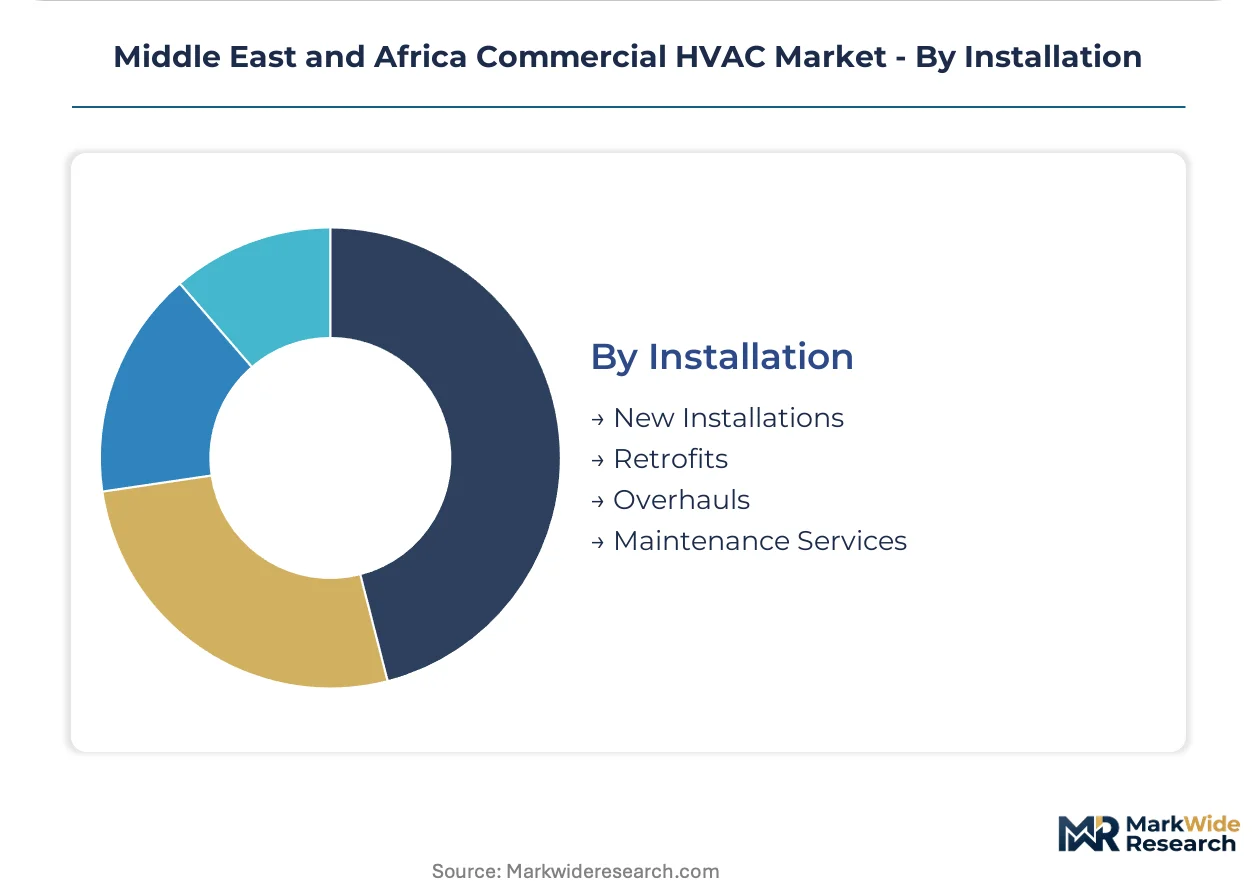
- New Installations:Greenfield equipment deployment in buildings under construction. Dubai's district cooling network expansion and Abu Dhabi's hospital construction pipeline absorb chiller and VRF volumes with integrated building automation specifications.
- Retrofits:System replacement in existing structures without structural modification. Existing UAE office stock faces refrigerant transition pressure under Kigali Amendment phasedown timelines for high-global-warming-potential hydrofluorocarbons.
- Overhauls:Major component replacement extending system operational lifespan.
- Maintenance Services:Recurring aftermarket revenue through preventive and predictive service contracts.
New installations command the established base across Gulf construction pipelines. The steepest expansion runs through maintenance services as digital twin convergence enables predictive subscription revenue streams.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SFDA efficiency mandates and MOHAP air quality enforcement are redirecting procurement flows across Gulf commercial construction. Sovereign wealth-backed infrastructure funds now bundle district cooling concessions with long-term operational contracts.
United Arab Emirates
Dubai's district cooling network expansion absorbs premium centrifugal chiller volumes as Emirates Central Cooling Systems Corporation scales pipeline capacity. MOHAP-licensed hospital projects across Abu Dhabi enforce continuous particle monitoring specifications in operating theaters. Dubai Science Park pharmaceutical manufacturing clusters face compressed compliance timelines for indoor air quality upgrades.
Saudi Arabia
Riyadh and Jeddah medical zones drive screw chiller demand as SFDA-mandated seasonal coefficient of performance minimums force mechanical cooling upgrades. The Saudi Vision 2030 healthcare privatization pipeline targets bed capacity expansion in tertiary care facilities. King Abdullah Financial District commercial towers specify VRF systems for zoned climate control without structural overhaul.
Qatar
Doha's commercial office stock shifts toward energy-as-a-service contracting as corporate real estate teams transfer efficiency risk to equipment providers. Municipal water allocation caps constrain cooling tower makeup for evaporative chiller deployment. Lusail City development absorbs packaged rooftop units for mid-rise commercial segments.
South Africa
Johannesburg and Cape Town institutional construction lacks mature district cooling infrastructure, creating positioning opportunities for packaged chiller providers. National energy regulator efficiency guidelines shape commercial building specifications without mandatory enforcement. Gauteng province healthcare facility upgrades trigger retrofit demand for aging clinical HVAC systems.
Egypt
New Administrative Capital commercial construction absorbs premium equipment volumes as government relocation programs drive office tower development. General Authority for Healthcare Accreditation and Regulation standards influence hospital climate specifications in Cairo medical zones. Alexandria coastal humidity challenges accelerate corrosion-resistant equipment specifications for seaside commercial properties.
Middle East and Africa Commercial HVAC Market Competitive Landscape
On the supply side, the industry is consolidating around vertically integrated system providers capable of anchoring bundled energy performance contracts. Three strategic archetypes dominate: building automation integrators securing district cooling concessions, component-captive manufacturers defending factory-level presence, and VRF specialists capturing retrofit-intensive commercial office segments. Competitive moves concentrate on strategic partnerships with sovereign wealth infrastructure funds and technology licensing for low-GWP refrigerant transitions.
Within the building automation integration tier, Johnson Controls International Plc exemplifies the concession-anchoring archetype through its control system bundling capabilities. Daikin Industries Ltd occupies a position representing VRF deployment dominance across Gulf commercial retrofits. Carrier Global Corp sits within the component-captive manufacturer archetype, sustaining factory-level supply chain positioning for chiller production.
| Leading Market Players |
|---|
| Daikin Industries Ltd |
| Johnson Controls International Plc |
| Carrier Global Corp |
| Lennox International Inc |
| Trane Technologies Plc |
| Schneider Electric SE |
| Honeywell International Inc |
| Zamil Air Conditioners |
| Robert Bosch GmbH |
| Others |
Pricing and Supply Chain Analysis
Jeddah's industrial corridor anchors Gulf chiller manufacturing capacity, concentrating compressor assembly and coil fabrication for downstream pricing power across Saudi and UAE project bids. This geographic clustering enables tiered quoting structures that reflect logistics proximity to district cooling concessions.
Pricing Analysis
Certification level under SFDA and MOHAP air quality mandates creates the primary spread between premium clinical-grade systems and standard commercial office equipment. Project-based pricing dominates large hospital and district cooling tenders, with differentiation driven by seasonal efficiency thresholds and after-sales service bundling. Cost compression in mid-tier screw chillers is intensifying because Saudi healthcare construction absorbs volumes faster than certified commissioning capacity expands. Public hospital procurement committees exhibit highest price sensitivity, while sovereign wealth-backed district cooling operators prioritize lifecycle efficiency over first cost.
Supply Chain Analysis
Export controls on advanced refrigerant sensors and electronic expansion valves from German and Italian specialists limit component flows to Gulf integrators, forcing inventory buffers. Manufacturing concentrates in China, South Korea, and Japan for compressor housings, with copper and aluminum heat exchanger materials drawing from London Metal Exchange pricing. Single-source vulnerability runs through European sensor suppliers. Distribution runs through EPC contractors and building automation integrators anchoring energy performance contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East and Africa Commercial HVAC market sits at a platform-economics inflection where building information modeling interoperability determines contractor margin capture. Smart HVAC subscription revenue now hinges on seamless sensor-to-software integration.
For Market Incumbents: Entrench control system bundling capabilities to anchor district cooling concessions before sovereign wealth funds consolidate procurement authority. Deepen backward integration into compressor manufacturing to defend margin position against copper volatility. Lock in exclusive partnerships with MOHAP-licensed hospital developers to preempt retrofit competitors.
For New Entrants and Emerging Players: Nairobi and Lagos commercial construction corridors offer first-mover positioning where packaged chiller demand outruns local assembly capacity. Target healthcare facility upgrades in Johannesburg and Cape Town where aging clinical HVAC systems face efficiency compliance pressure. Pursue refrigerant transition retrofit contracts in existing UAE office stock as Kigali Amendment deadlines compress decision windows.
For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue infrastructure play because energy-as-a-service contracting displaces capital purchase models across Gulf commercial real estate. Acquire building automation integrators with established district cooling concession relationships rather than pure equipment manufacturers. Monitor sovereign wealth fund tender bundling patterns as the signal for when vertical integration premiums compress.
| Strategic Initiative | Industry Significance |
|---|---|
| Energy Performance Contracting | Bundles financing and operation, transferring efficiency risk to providers under SFDA mandates. |
| Low-GWP Refrigerant Transition | Opens retrofit demand across UAE office stock as Kigali Amendment phasedown accelerates. |
| Predictive Maintenance Platform | Converts hardware margins into recurring software revenue through digital twin convergence. |
| Sub-Saharan Geographic Expansion | Positions packaged chiller providers in Lagos and Nairobi ahead of district cooling maturity. |
| Healthcare Certification Investment | Captures MOHAP and SFDA-mandated hospital construction pipelines with compliant specifications. |
Research Methodology
Operator-level perspectives from district cooling plant managers, hospital facilities directors, EPC contractor procurement leads, and building automation system integrators anchored the qualitative base. Secondary validation drew from SFDA regulatory filings, MOHAP licensing databases, Emirates Central Cooling Systems Corporation concession disclosures, and London Metal Exchange pricing archives. Bottom-up equipment shipment tracking and top-down construction pipeline valuation were triangulated to cross-check volume estimates.
Scenario-bracketing around copper price volatility bands and healthcare construction acceleration cases framed the analytical approach across the projection horizon. Segmentation dimensions modeled include product type, technology tier, end-user vertical, and installation maturity. CAGRs were derived from equipment replacement cycles and regulatory compliance timelines. Forecast inputs incorporated sovereign wealth fund tender pipelines and refrigerant phasedown schedules.
Practitioners should monitor SFDA efficiency threshold revisions and MOHAP indoor air quality enforcement intensity for early signals. Forecasts reflect assumptions about district cooling concession award pacing and European component supply continuity. Material shifts in Gulf sovereign wealth procurement bundling or Kigali Amendment acceleration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
HVAC Systems Market
HVAC Equipment
Fabric Air Ducts Market
HVAC Equipment
US Compressed Air Treatment Equipment Market
HVAC Equipment
Heating Equipment Market
HVAC Equipment
Europe HVAC Field Device Market
HVAC Equipment
Wall Fan Coil Market
HVAC Equipment
Europe Ventilation Equipment Market
HVAC Equipment
Field-Erected Cooling Tower Market
HVAC Equipment
Global HVAC Filter Market
HVAC Equipment
Fabric Ducting Market
HVAC Equipment
Automatic Ducting Machine Market
HVAC Equipment
India Residential Heat Pump Market
HVAC Equipment
Underfloor Air Distribution Systems Market
HVAC Equipment
HVAC Pumps Market
HVAC Equipment
HVAC Services Market
HVAC Equipment
Refrigerant Compressors Market