
 Industrial Air Blower Market | 2026-2036
Industrial Air Blower Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Air Blower Market Intelligence
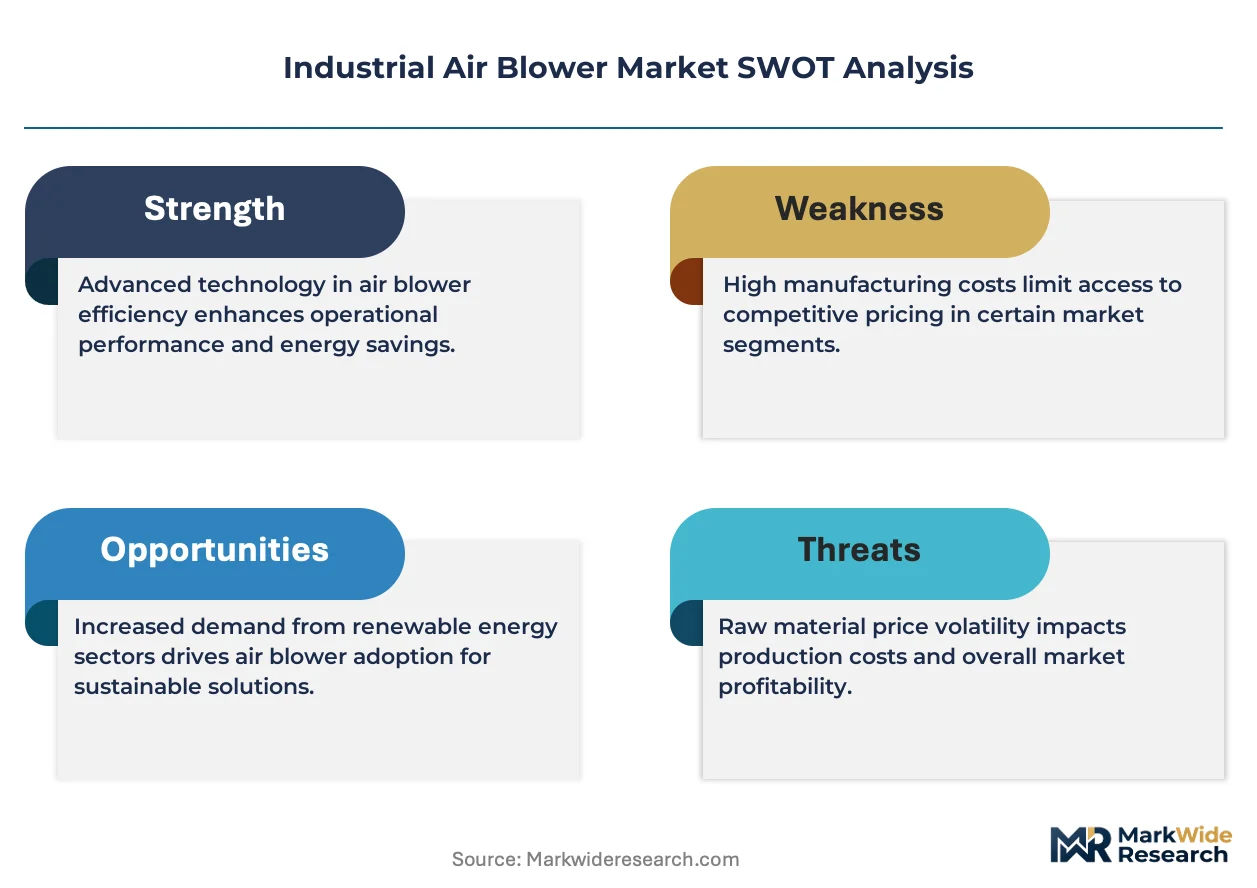
Multi-source procurement for high-performance impellers and motor assemblies is recalibrating how OEMs manage cost volatility and lead times. Atlas Copco leverages its captive foundry network across Sweden and China to secure cast component supply. Kaeser Kompressoren anchors its position through dense German service infrastructure that locks in aftermarket revenue. Gardner Denver competes by specializing in oil-free blower architectures for food-grade pneumatic conveying.
An industrial air blower is a mechanical device that generates airflow through rotating impellers, lobes, or blades to achieve specified pressure ratios typically between 1.1 and 2.5 bar, serving applications from aeration to material transport. Centrifugal blowers dominate volume due to mature supply chains and broad pressure-flow adaptability across wastewater and chemical processing. Positive displacement blowers sustain premium positioning in pneumatic conveying where precise, pulsation-free delivery protects fragile food and mineral particulates. Electric-drive technology leads new installations as plant operators retire mechanical drive trains to cut energy intensity.
EPA efficiency standards under the Clean Air Act and OSHA noise exposure limits shape blower specification across U.S. manufacturing and mining installations. The EU Ecodesign Directive and REACH compliance for lubricant chemistry constrain product architecture for equipment sold into European food processing and chemical end uses. Stakeholders must monitor how regional energy-efficiency thresholds reshape motor and drive supplier qualification criteria without warning.
Market Dynamics
EPA mandates for aeration efficiency upgrades at wastewater treatment facilities are forcing wholesale replacement cycles across installed blower bases, compressing replacement timelines from fifteen years to under eight.
Growth Catalysts
- EPA Clean Air Act efficiency mandates:Wastewater treatment operators in the United States must retrofit aging aeration systems to meet tightened energy intensity thresholds, triggering systematic equipment replacement.
- Pneumatic conveying retrofit waves:Steel and cement producers across China's industrial corridor cities are modernizing material handling infrastructure to reduce particulate emissions and energy waste.
- Electrification of mechanical drive trains:Plant operators are retiring belt-and-pulley systems in favor of direct-drive electric motors to satisfy corporate carbon reduction commitments and utility rebate programs.
Market Restraints
- Foundry capacity concentration:High-performance impeller castings depend on a narrow supplier base concentrated in Sweden and eastern China, exposing OEMs to lead time volatility.
- Rare-earth magnet cost exposure:Permanent magnet motors for premium efficiency blowers rely on neodymium supply chains subject to export quota fluctuations.
- REACH lubricant chemistry constraints:European food processing buyers face restricted formulation options that extend product development cycles and limit aftermarket fluid interchangeability.
Strategic Opportunities
- EU Ecodesign Directive tier upgrades:Anticipated 2027 efficiency thresholds will disqualify current motor classes, creating replacement demand before compliance deadlines.
- Hydrogen electrolyzer aeration:Green hydrogen production facilities require high-purity oil-free blower systems for electrolyte circulation, opening a nascent application vertical.
- Digital twin integration:Predictive maintenance platforms that combine vibration sensing with AI-driven failure modeling are enabling performance-based service contracts.
Industry Challenges
- Rotordynamics specialist scarcity:Design and field service of high-speed turbo blowers requires expertise in fluid-bearing interfaces that outpaces vocational training pipeline output.
- Legacy control system integration:Brownfield installations must bridge proprietary protocols from 1990s-era SCADA architectures to modern IoT-enabled drive platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Air Blower Market |
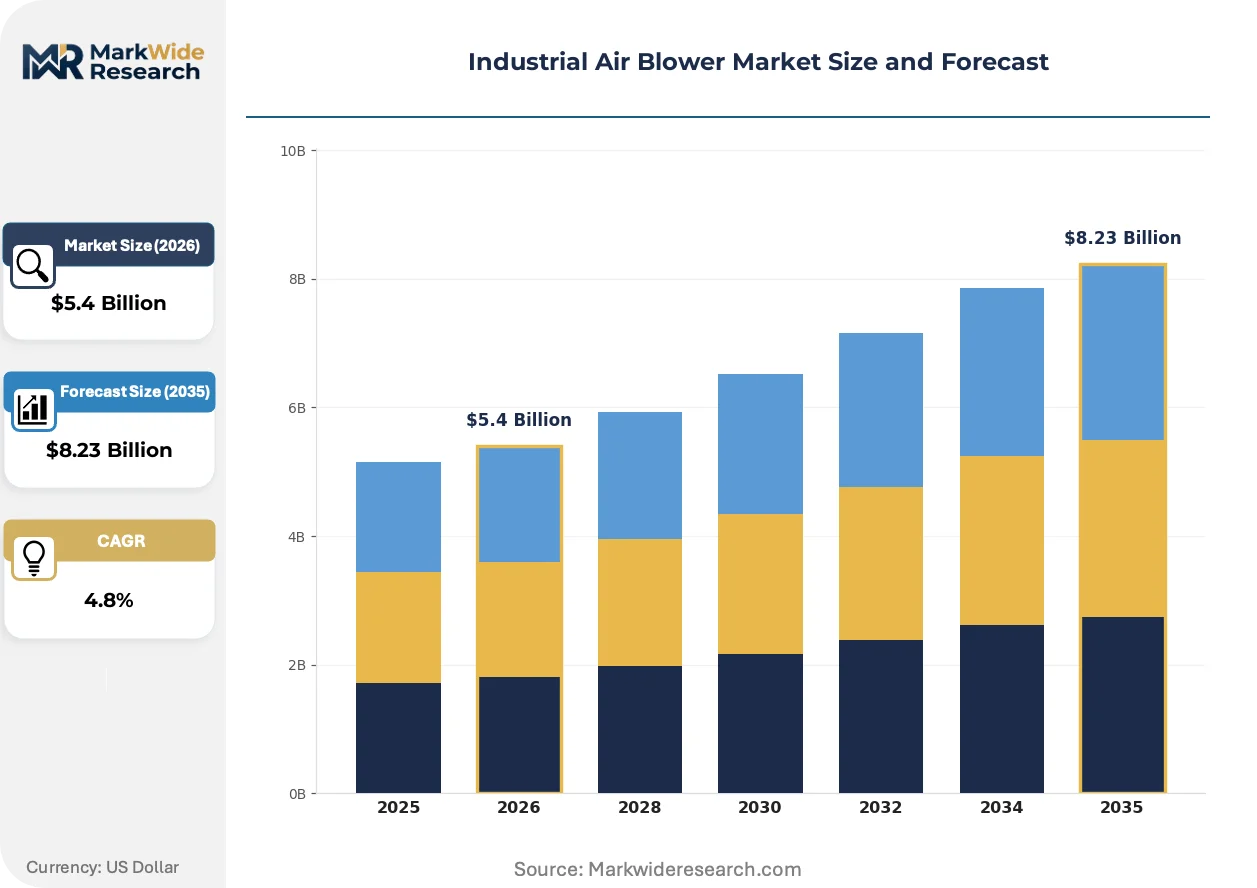
| Market Size in 2026 | $5.4 Billion |
| Market Size in 2035 | $8.23 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
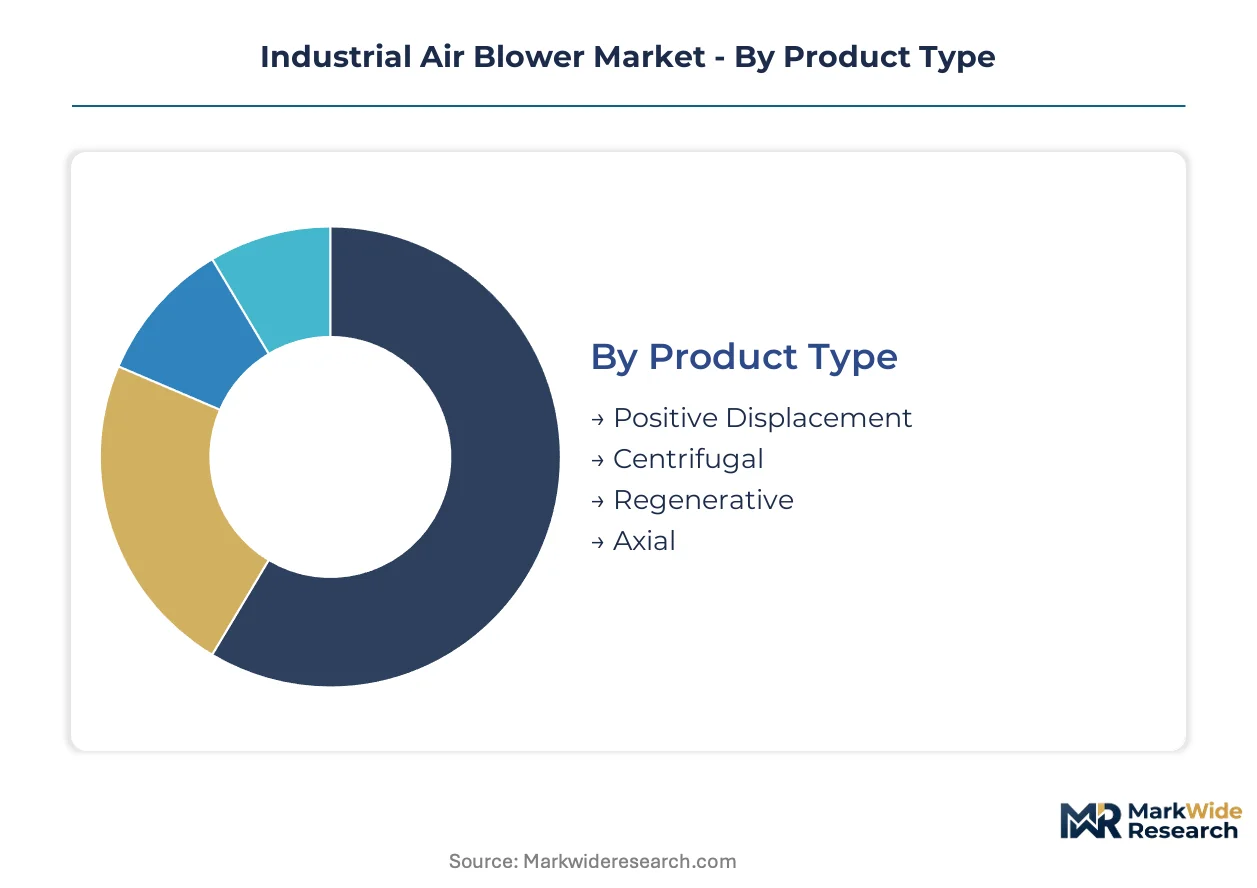
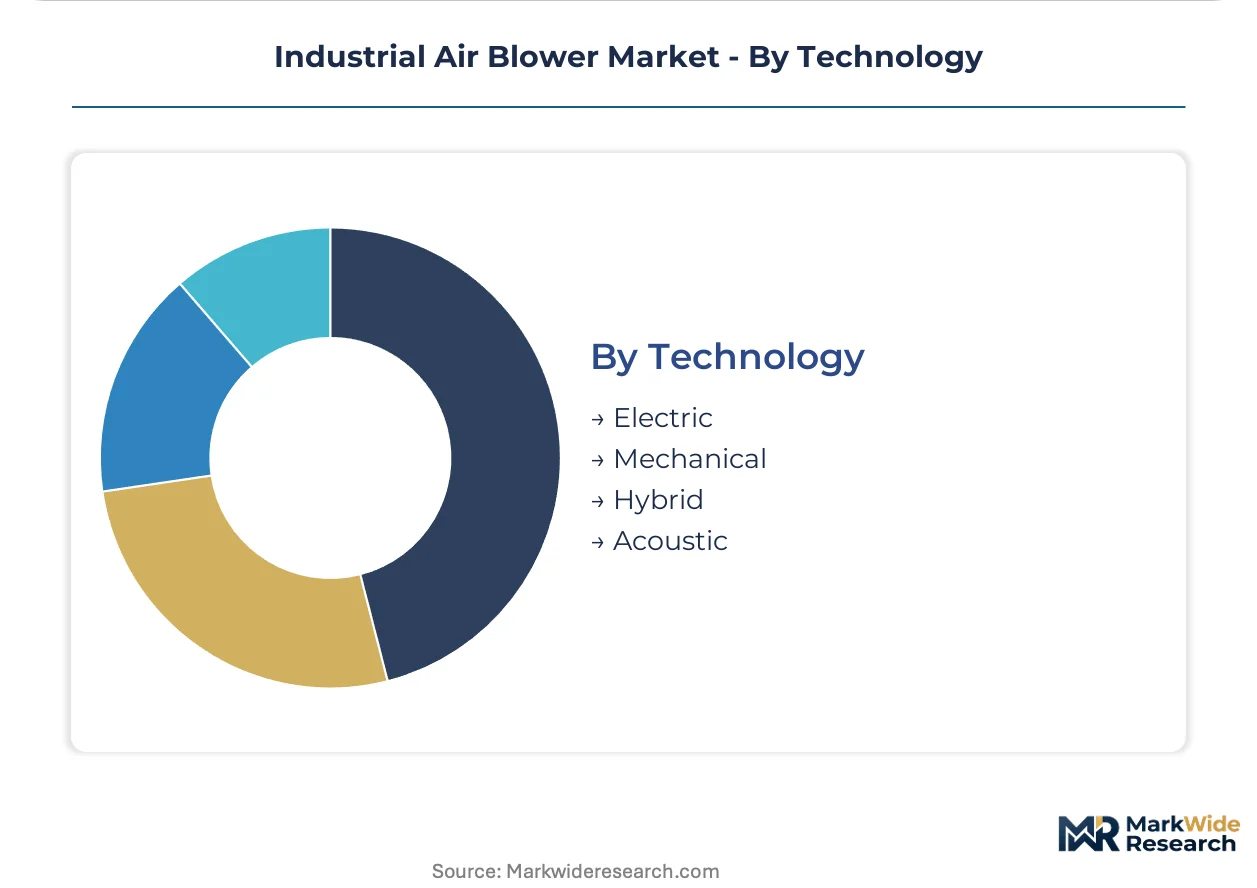
| Segmentation | Product Type: Positive Displacement, Centrifugal, Regenerative, Axial Application: Compressor Systems, Ventilation, Pneumatic Conveying, Dust Collection End User: Manufacturing, Mining, Food Processing, Chemical Technology: Electric, Mechanical, Hybrid, Acoustic |
| Companies Covered | Atlas Copco, Ingersoll Rand, Gardner Denver, Kaeser Kompressoren, Aerzen, Howden Group, Greenheck Fan, Twin City Fan & Blower, Chicago Blower, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Air Blower Market Strategic Shifts & Innovations
Magnetic bearing turbo blower technology is compressing the performance gap between centrifugal and positive displacement architectures while slashing maintenance intervals.
Active magnetic bearing systems eliminate mechanical contact between rotating and stationary components, enabling rotational speeds above 50,000 RPM in compact single-stage configurations. Food-grade pneumatic conveying operators in Germany and the Netherlands are adopting these systems to eliminate oil contamination risk while cutting energy draw by one-third versus traditional lobe designs. This convergence of aerodynamic efficiency with zero-wear mechanical architecture is rewriting competitive segmentation between premium turbo and mid-range rotary blower categories.
The EU F-Gas Regulation phase-down is restricting refrigerant options for blower motor cooling systems in heat pump-integrated configurations. Equipment suppliers must now qualify alternative dielectric fluids or redesign thermal management for air-cooled architectures. Chemical processing installations in Belgium and France face compressed certification timelines as they validate substitute cooling chemistries ahead of 2027 quota reductions.
Asset-as-a-service contracting is displacing capital purchase models among municipal wastewater authorities with constrained infrastructure budgets. Danish and Swedish utilities now lease blower capacity with guaranteed uptime and energy performance, transferring operational risk to OEM service divisions. This shift concentrates most visible in Nordic markets where public procurement rules favor operational expenditure treatment over balance sheet expansion.
Industrial Air Blower Market Segmentation
Industrial air blower procurement hinges on pressure-flow specifications, energy intensity thresholds, and contamination risk profiles that vary sharply across aeration, material transport, and process gas duties. Understanding how these technical requirements map to product architectures enables buyers to navigate trade-offs between capital cost, operating efficiency, and compliance burden.
Product Type:
Buyers select blower architecture based on pressure ratio requirements and pulsation tolerance in their specific application.
- Positive Displacement:Lobed or screw mechanisms deliver precise, pulsation-free airflow at fixed displacement ratios essential for fragile particulate handling. Food processing installations across Germany and the Netherlands specify oil-free rotary lobe designs to eliminate contamination risk in pneumatic conveying of flour and mineral additives.
- Centrifugal:Radial impellers generate continuous flow across broad pressure ranges with mature supply chains supporting rapid replacement part availability. Wastewater treatment operators in the United States favor these systems for aeration basins where EPA energy efficiency mandates drive retrofit cycles.
- Regenerative:Side-channel compressors achieve higher pressure ratios than centrifugal designs in compact footprints for vacuum and pressure duties. Semiconductor fabrication facilities specify these for cleanroom air handling where space constraints dominate.
- Axial:Propeller-style configurations move large air volumes at minimal pressure differential for ventilation and cooling applications. Steel mills in China's industrial corridor cities deploy axial blowers for furnace cooling and fume extraction.
Centrifugal designs lead on installed scale; positive displacement configurations lead on specification precision in contamination-sensitive environments.
Application:
Application selection follows the physical state of the medium being moved and the energy transfer mechanism required.
- Compressor Systems:Blower stages feed compressed air networks for tooling, instrumentation, and process actuation. Chemical processing plants in Belgium integrate these with instrument air systems requiring oil-free delivery under REACH lubricant constraints.
- Ventilation:Continuous air exchange maintains atmospheric quality in confined industrial spaces. Underground mining operations in Australia specify explosion-proof ventilation blowers to manage methane accumulation and thermal loading.
- Pneumatic Conveying:Controlled airflow transports dry bulk materials through pipeline networks without mechanical handling. Cement producers retrofit these systems to reduce particulate emissions and energy waste.
- Dust Collection:Negative pressure systems capture fugitive particulates at source to maintain occupational exposure limits. Wood processing facilities deploy cartridge collectors with dedicated blower packages.
Pneumatic conveying is expanding most quickly on retrofit investment; compressor systems retain the largest installed base.
End User:
End-user segmentation reflects divergent operating environments from corrosive chemical exposure to sanitary food-grade requirements.
- Manufacturing:General industrial applications span machining coolant mist extraction to drying operations. Automotive assembly plants specify energy-efficient regenerative blowers for parts drying stations.
- Mining:Harsh duty cycles demand abrasion-resistant materials and explosion-proof electrical enclosures. Surface and underground operations require ventilation and dust suppression blower capacity.
- Food Processing:Sanitary design standards mandate stainless steel construction and oil-free compression. EU Ecodesign Directive efficiency tiers increasingly influence motor selection for these installations.
- Chemical:Corrosive gas handling requires specialty alloys and sealed bearing configurations. Process safety management protocols dictate redundant blower capacity for critical reactor aeration.
Manufacturing dominates volume; food processing shows the steepest specification upgrade trajectory on regulatory compliance.
Technology:
Technology choice determines energy intensity, maintenance burden, and integration complexity with existing plant infrastructure.
- Electric:Direct-drive permanent magnet motors eliminate mechanical transmission losses and enable variable speed control. Plant operators retire belt-and-pulley systems to satisfy corporate carbon reduction commitments.
- Mechanical:Belt, gear, or chain drives persist in legacy installations where capital constraints delay electrification. These systems require periodic tensioning and coupling alignment maintenance.
- Hybrid:Configurations combine electric prime movers with mechanical energy recovery or storage elements. Emerging designs target peak shaving in cyclical aeration duty.
- Acoustic:Specialized architectures attenuate noise generation for OSHA compliance in occupied work areas. Mining and manufacturing applications specify these where hearing conservation programs mandate exposure limits.
Electric technology leads on new installation share; hybrid configurations are gaining momentum in energy-intensive cyclic duties.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's industrial corridor cities anchor the strongest demand concentration for pneumatic conveying retrofits, while EPA mandates in the United States compress replacement cycles for wastewater aeration systems. European food processing clusters drive specification upgrades on oil-free architectures. Mining ventilation requirements in Australia and steel modernization in India complete the geographic demand map.
United States
Wastewater treatment operators face compressed replacement timelines under EPA Clean Air Act efficiency mandates, with aeration system retrofits accelerating from fifteen-year cycles to under eight years. Municipal utilities in the Great Lakes region and California's Central Valley lead systematic equipment replacement. Chicago and Milwaukee industrial corridors concentrate demand for food-grade pneumatic conveying upgrades.
China
Steel and cement producers across the Yangtze River Delta and Pearl River Delta are modernizing material handling infrastructure to reduce particulate emissions and energy waste. MIIT efficiency standards and dual carbon goals drive retrofit investment timelines. Shenyang and Tangshan steel clusters deploy axial blowers for furnace cooling and fume extraction at scale.
Germany
Food processing installations specify oil-free rotary lobe designs under EU Ecodesign Directive efficiency tiers and REACH lubricant chemistry constraints. The Ecodesign Directive's anticipated 2027 thresholds disqualify current motor classes, creating pre-deadline replacement demand. Bavaria and Baden-Württemberg automotive suppliers specify energy-efficient regenerative blowers for parts drying stations.
India
Cement producers in Gujarat and Maharashtra retrofit pneumatic conveying systems to cut energy waste and particulate emissions. BIS efficiency standards and state-level pollution control mandates accelerate equipment replacement. The Delhi-Mumbai Industrial Corridor concentrates demand for dust collection blower packages in bulk material handling.
Australia
Underground mining operations in Queensland and Western Australia specify explosion-proof ventilation blowers to manage methane accumulation and thermal loading. State occupational health regulations mandate hearing conservation programs that drive acoustic blower specification. The Pilbara iron ore region deploys abrasion-resistant blower capacity for dust suppression at scale.
Industrial Air Blower Market Key Industry Players
Global majors compete with regional champions across technology licensing and aftermarket service density. The vendor base stratifies into three tiers: integrated compressor houses with captive foundry networks, specialized blower fabricators with dense service footprints, and regional equipment assemblers competing on delivered cost. Strategic moves concentrate on M&A for technology access and geographic expansion through distribution partnerships.
Among European-integrated compressor houses, Atlas Copco AB and Kaeser Kompressoren GmbH exemplify archetypes built on captive component supply and service infrastructure density. Gardner Denver Holdings Inc. occupies a position within the oil-free specialization tier. Howden Group Ltd. and Aerzen GmbH sit within the engineered-to-order segment for process-critical duties. Chicago-based Twin City Fan & Blower represents North American regional fabrication capability.
| Leading Market Players |
|---|
| Atlas Copco |
| Ingersoll Rand |
| Gardner Denver |
| Kaeser Kompressoren |
| Aerzen |
| Howden Group |
| Greenheck Fan |
| Twin City Fan & Blower |
| Chicago Blower |
| Others |
Cost & Logistics Intelligence
Neodymium magnet costs flow from Chinese export quotas through permanent-motor blower tiers into municipal wastewater procurement budgets, compressing margins at the premium efficiency tier while standard centrifugal designs absorb volatility through broader supplier bases.
Pricing Analysis
Input-cost pass-through from rare-earth magnet pricing and foundry casting premiums shapes three-tier pricing structure across premium, standard, and economy levels. Permanent-magnet turbo blowers command premium positioning on energy efficiency certifications under EU Ecodesign tiers, while belt-drive centrifugal units compete on delivered cost for budget-constrained municipal utilities. Pricing pressure stems from foundry capacity bottlenecks in Sweden and eastern China extending lead times for high-performance impellers. Municipal wastewater authorities in the United States exhibit highest price sensitivity due to constrained infrastructure budgets, whereas semiconductor fabrication facilities prioritize contamination-risk mitigation over capital cost.
Supply Chain Analysis
High-performance impeller castings rest on a narrow supplier base concentrated in Sweden, eastern China, and Germany, with specialty alloy sourcing extending to Austria and Japan. Critical dependencies include neodymium-iron-boron magnets, nickel-based superalloys for high-temperature applications, and precision-machined bearing assemblies. Single-source vulnerability concentrates in magnetic bearing control systems and specialized rotordynamics engineering talent. Distribution runs through OEM direct sales for large project installations, regional distributor networks for replacement parts, and integrated service contracts capturing aftermarket revenue.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between EPA-mandated U.S. replacement cycles and MIIT-driven Chinese retrofit timelines, with European Ecodesign compliance costs creating margin expansion opportunities for pre-certified suppliers.
For Market Incumbents: Anticipate rotordynamics specialist scarcity by captive training programs and university partnerships in Germany and Sweden. Consolidate aftermarket service density through acquisition of regional distributors in China's Yangtze River Delta. Magnetic bearing technology licensing from aerospace suppliers represents a priority capability gap to close before 2027 EU efficiency tier upgrades.
For New Entrants and Emerging Players: Enter via oil-free turbo blower specialization for hydrogen electrolyzer aeration, a nascent vertical with limited incumbent positioning. Target Australian mining ventilation retrofits where explosion-proof certification requirements create qualification barriers for established compressor houses. Partner with Nordic municipal utilities on asset-as-a-service contracting models to bypass capital-sale competition.
For Investors and Strategic Acquirers: Roll-up economics work for regional service specialists with dense installed-base coverage because aftermarket revenue concentration exceeds equipment margins by factor of three. Five-to-ten year viability hinges on electrification retrofit penetration rates. Watch EPA enforcement intensity on aeration efficiency mandates as demand inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Foundry Capacity | Atlas Copco's Swedish-Chinese foundry network insulates against impeller casting lead time volatility. |
| Magnetic Bearing Technology Licensing | Aerospace-derived active bearing systems enable 50,000 RPM turbo blower speeds with zero mechanical wear. |
| Asset-as-a-Service Contracting | Danish and Swedish municipal utilities now lease blower capacity with guaranteed uptime performance. |
| Hydrogen Electrolyzer Application Development | Green hydrogen facilities require oil-free blower systems for electrolyte circulation at high purity. |
| Digital Twin Platform Integration | Predictive maintenance combining vibration sensing with AI failure modeling enables performance-based service contracts. |
Research Approach
Bottom-up wastewater treatment and pneumatic conveying modeling reconciled against top-down OEM production tracking forms the analytical core. Primary interviews with maintenance directors at U.S. municipal utilities, plant engineers at Chinese steel producers, OEM procurement teams in Germany, aftermarket service heads, and food processing facility managers combined with secondary validation from EPA enforcement databases, MIIT efficiency standard filings, EU Ecodesign directive documentation, and customs trade data on impeller casting imports. Triangulation across supply-side capacity surveys and demand-side procurement pipeline tracking ensures cross-verification.
Input-output matrix framing connects end-use application demand to component-level supply constraints across the projection horizon. Segmentation dimensions modeled include blower architecture type, pressure-flow specification tier, drive technology category, end-use industry vertical, and regional regulatory cluster. CAGRs derive from installed base replacement cycle analysis and new capacity addition tracking. Industry-specific forecast inputs incorporate EPA mandate compliance timelines and MIIT dual carbon retrofit schedules.
Inputs from OEM production disclosures and utility procurement databases were available through the study window; gaps in private aftermarket service contract terms introduce uncertainty bands around recurring revenue projections. Forecasts reflect documented assumptions on regulatory enforcement intensity and rare-earth magnet quota stability. Supply chain disruption scenarios and technology substitution curves represent primary revision triggers. A small set of named triggers—EPA civil penalty actions, EU Ecodesign tier acceleration, Chinese export quota reductions—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Global Modular Chillers Market
HVAC Equipment
Screw Compressor Market
HVAC Equipment
Asia-Pacific Compressor Market
HVAC Equipment
GCC Portable Air Conditioners Market
HVAC Equipment
Global Heat Exchangers Market
HVAC Equipment
Equipment for HVAC Market
HVAC Equipment
North America Residential Heat Pump Market
HVAC Equipment
Utility and Industrial Boilers Market
HVAC Equipment
Industrial Boiler Market
HVAC Equipment
Heating Radiator Market
HVAC Equipment
Centrifugal Fan Wheels Market
HVAC Equipment
HVAC Air Duct Market
HVAC Equipment
Asia-Pacific Industrial Heat Pump Market
HVAC Equipment
Global Industrial Fans and Blowers Market
HVAC Equipment
Global Air Curtain Market
HVAC Equipment
Europe HVAC Field Device Market