
 Thermocompressors Market | 2026-2036
Thermocompressors Market Size, Share, and Industry Trends Forecast 2026-2036
Thermocompressors Market Analytics
The capability gap between custom-engineered and standardized thermocompressor portfolios is collapsing as modular platforms erode premium positioning. SPX Flow leverages its vertical integration in steam ejector systems to sustain margin structures in food processing applications. KSB anchors its European installed base with aftermarket service contracts, while GEA Group competes through specialization in hygienic designs for dairy and pharmaceutical heating circuits.
A thermocompressor is a jet-type compression device that uses high-pressure motive fluid—typically steam, air, or gas—to entrain and compress a lower-pressure suction stream, achieving discharge pressures up to 10 bar in industrial configurations. Its primary purpose is to recover and recompress waste vapor or low-grade steam, converting discarded thermal energy into reusable process heat or motive power. Steam thermocompressors occupy the dominant revenue position due to entrenched deployment in pulp drying and refinery vacuum distillation, while electric thermocompressors represent the fastest-expanding category as chemical manufacturers retrofit plants to reduce boiler dependency. Hybrid thermocompressors command concentrated margin pools where facilities require load-following capability across variable steam and electricity inputs.
The US EPA enforces emissions thresholds that compel refiners and chemical plants to recover vented steam rather than flare it, directly expanding thermocompressor specification in retrofit engineering. China's MEE implements dual carbon targets that penalize coal-fired boiler output, redirecting capital toward electric and hybrid thermocompressor architectures in Shandong and Jiangsu provinces. ISO 5167 nozzle measurement standards govern performance verification across export markets, creating compliance barriers for uncertified suppliers. Stakeholders must monitor how carbon border adjustment mechanisms in Europe and North America reshape the total cost justification for energy recovery equipment against competing heat pump technologies.
Market Dynamics
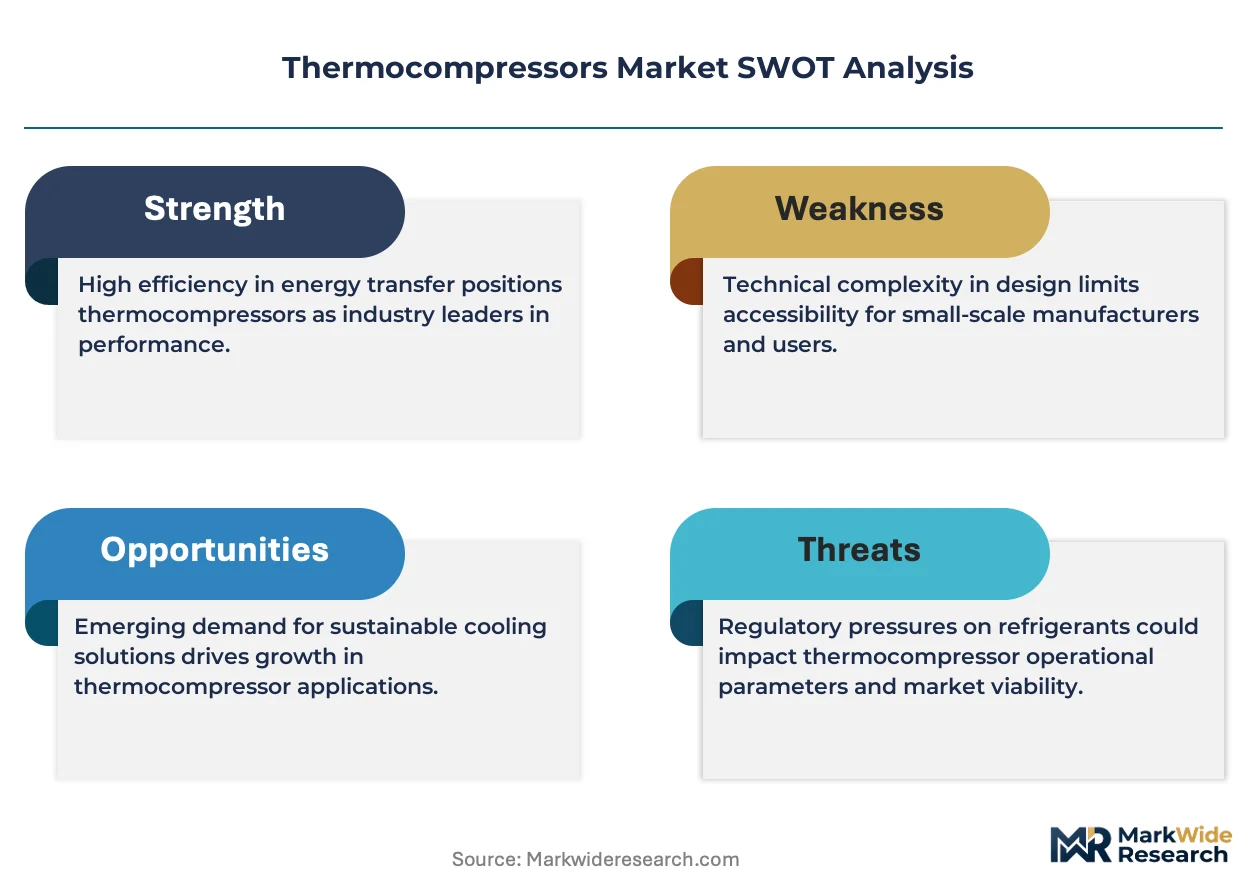
Modular thermocompressor platforms are collapsing the historical premium commanded by custom-engineered systems, forcing incumbents to defend margin structures through aftermarket capture and application-specific specialization rather than proprietary hardware alone.
Growth Catalysts
- EU Green Deal efficiency mandates:Germany's Rhine-Ruhr industrial belt faces accelerated replacement cycles as existing steam systems fail to meet revised emissions thresholds, redirecting capital toward electric and hybrid architectures.
- China's dual carbon enforcement:MEE penalties on coal-fired boiler output in Shandong and Jiangsu provinces are redirecting chemical manufacturer investment toward electric thermocompressor retrofits that reduce steam dependency.
- US Gulf Coast petrochemical expansion:EPA emissions thresholds compel refiners to recover vented steam rather than flare it, embedding thermocompressor specification into engineering standards across Texas and Louisiana process facilities.
Market Restraints
- Stainless steel input volatility:Pressure vessel fabrication depends on nickel-alloy pricing swings that compress project margins for equipment fabricators during tender cycles.
- ISO 5167 certification concentration:Nozzle measurement verification capacity clusters among accredited European laboratories, creating compliance bottlenecks for Asian suppliers seeking export market entry.
- Heat pump substitution threat:Industrial heat pump efficiency gains above 35°C temperature lift are capturing feasibility studies previously reserved for thermocompressor energy recovery schemes.
Strategic Opportunities
- India's Gujarat chemical cluster:Underpenetrated installation base among specialty chemical producers creates first-mover positioning for hybrid systems capable of load-following across variable steam and electricity inputs.
- Pharmaceutical heating circuit specialization:Hygienic design requirements for dairy and pharmaceutical applications reward dedicated engineering capabilities that generalist compressor manufacturers cannot replicate.
- Carbon border adjustment mechanisms:European CBAM implementation creates total cost justification advantages for energy recovery equipment against conventional boiler alternatives in export-exposed process industries.
Industry Challenges
- Computational fluid dynamics expertise scarcity:Jet ejector design optimization requires specialized simulation talent that equipment manufacturers struggle to retain against software sector compensation benchmarks.
- Legacy distributed control system integration:Retrofit installations face commissioning delays when existing plant automation architectures lack native compatibility with modern thermocompressor variable-speed drives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thermocompressors Market |
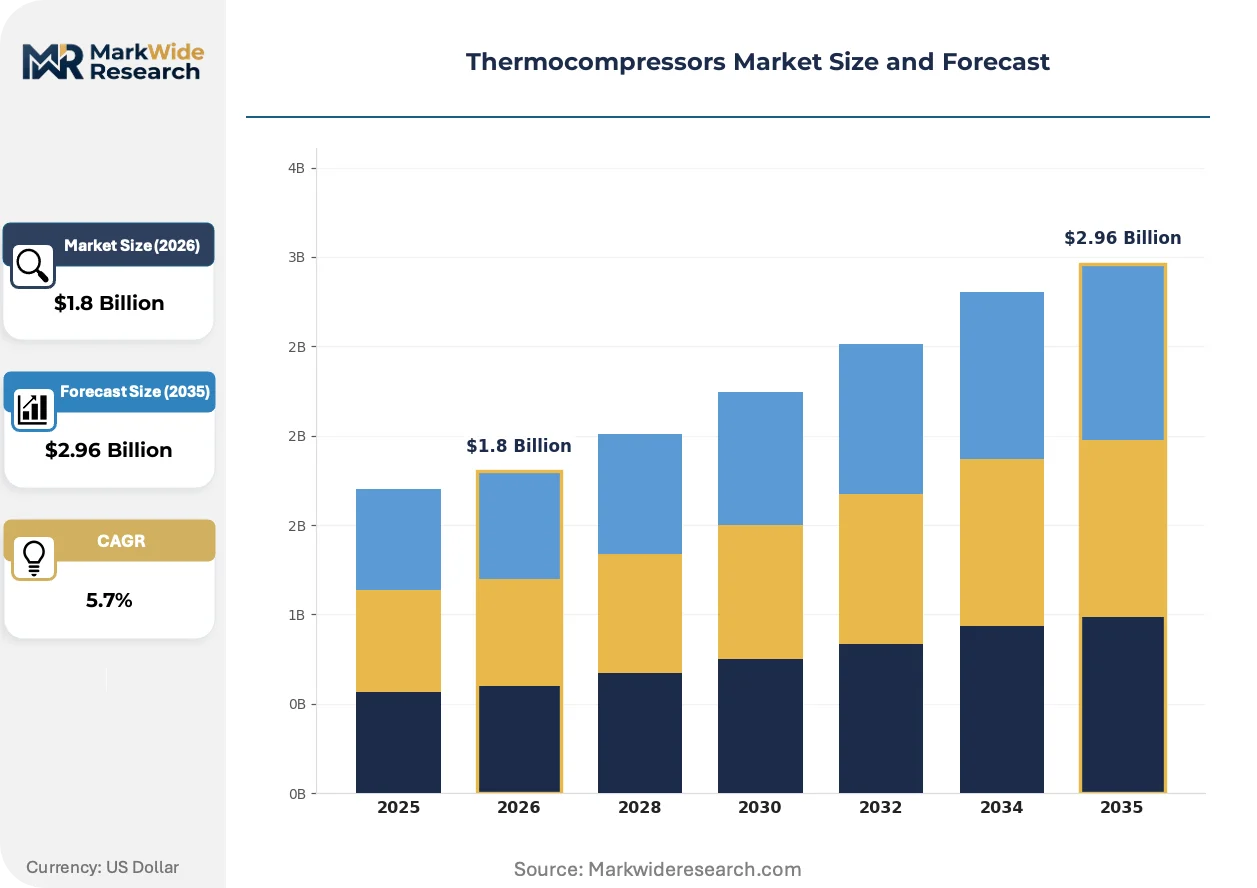
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Steam Thermocompressors, Electric Thermocompressors, Gas Thermocompressors, Hybrid Thermocompressors End User: Food Processing, Chemical Manufacturing, Oil & Gas, Power Generation Application: Pressure Boosting, Energy Recovery, Refrigeration, Heating Technology: High-Pressure Systems, Low-Pressure Systems, Cascading Systems, Variable Speed Systems |
| Companies Covered | SPX Flow, KSB, GEA Group, Altec, Andritz, Atlas Copco, JBT Corporation, Rietschle, Siemens, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thermocompressors Market Evolving Landscape
Digital twin deployment and additive manufacturing are reshaping how thermocompressor performance is validated and how critical flow components are produced, compressing development cycles while raising reliability expectations.
Additive manufacturing of complex nozzle geometries is decomposing the traditional machining bottleneck that constrained custom ejector design economics. Chemical processors in Germany's industrial belt are adopting topology-optimized motive nozzles for pilot-scale validation within six-month procurement windows. This capability is decomposing the volume threshold that previously separated viable custom projects from standardized catalog selections.
China's MEE enforcement of dual carbon targets is accelerating electric thermocompressor specification in provinces previously dependent on coal-fired steam infrastructure. Shandong chemical manufacturers face output penalties that redirect capital toward grid-powered compression architectures with lower Scope 2 emissions profiles. Electric thermocompressors are capturing retrofit engineering studies that steam-based systems dominated five years prior.
Aftermarket service unbundling is fragmenting traditional bundled maintenance contracts across India's process industries. Gujarat chemical operators are separating spare parts procurement from technical service agreements, forcing OEMs to defend component margins through inventory localization rather than captive service lock-in. This pattern is most pronounced among mid-scale specialty chemical producers with in-house mechanical maintenance capabilities.
Thermocompressors Market Segmentation
Thermocompressor procurement patterns diverge sharply between retrofit installations and greenfield projects, with each segment demanding distinct performance specifications and integration architectures. Understanding these fault lines reveals where engineering margins concentrate and which technology configurations command premium positioning.
Product Type:
Margin pools cluster where motive fluid flexibility intersects with regulatory pressure on emissions profiles, rewarding architectures that decouple from single-source energy dependency.
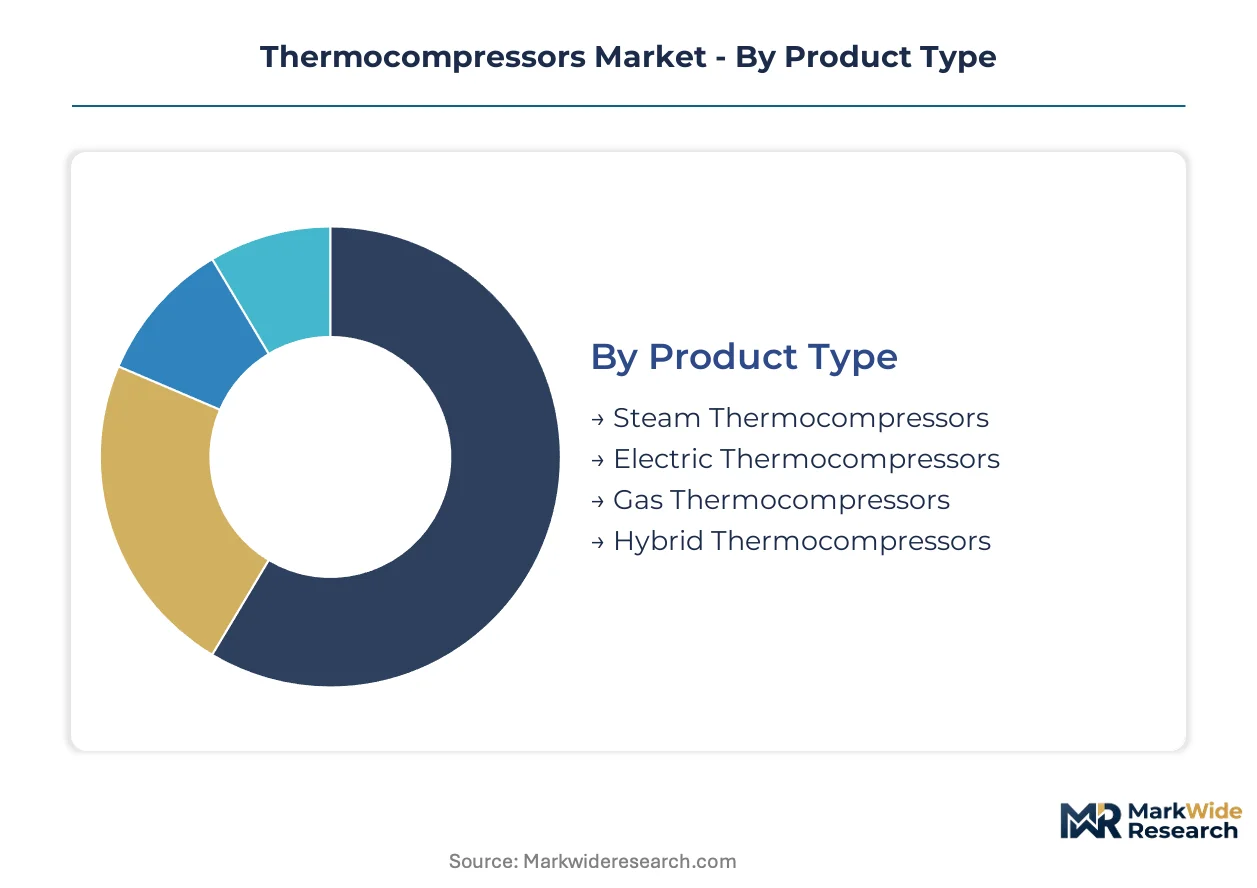
- Steam Thermocompressors:These systems deploy high-pressure steam as motive fluid to entrain and compress lower-pressure vapor streams, achieving discharge pressures up to 10 bar in standard industrial configurations. Demand concentrates across the US Gulf Coast petrochemical corridor where EPA emissions thresholds compel refiners to recover vented steam rather than flare it, embedding thermocompressor specification into engineering standards across Texas and Louisiana process facilities.
- Electric Thermocompressors:Grid-powered compression architectures eliminate boiler dependency entirely, converting electrical energy directly into motive power for vapor entrainment. China's MEE enforcement of dual carbon targets in Shandong and Jiangsu provinces is redirecting chemical manufacturer investment toward these systems as coal-fired boiler output faces escalating penalties.
- Gas Thermocompressors:Natural gas or process gas serves as motive fluid in applications where steam infrastructure is absent or uneconomical.
- Hybrid Thermocompressors:Load-following capability across variable steam and electricity inputs commands concentrated margin pools where facilities require operational flexibility.
Steam thermocompressors hold installed capacity. Electric thermocompressors are rotating up the share rankings.
End User:
Application-specific certification requirements and hygiene protocols create defensive moats that generalist compressor manufacturers cannot replicate.
- Chemical Manufacturing:Process plants in India's Gujarat cluster and Germany's Rhine-Ruhr belt deploy thermocompressors for vacuum distillation and solvent recovery, with EU Green Deal efficiency mandates accelerating replacement cycles as existing steam systems fail revised emissions thresholds.
- Food Processing:Steam ejector systems dominate evaporation and drying operations where SPX Flow leverages vertical integration to sustain margin structures through captive component supply and aftermarket service capture.
- Oil & Gas:Refinery vacuum distillation and vapor recovery applications specify thermocompressors for pressure boosting across low-pressure process streams.
- Power Generation:Combined cycle plants and geothermal facilities employ thermocompressors for bottoming cycle optimization and working fluid management.
Chemical manufacturing anchors procurement volume. Food processing is climbing the fastest on margin contribution.
Application:
Functional purpose determines nozzle geometry complexity and control system sophistication, with energy recovery applications demanding the most intensive computational fluid dynamics validation.
- Energy Recovery:Waste vapor recompression converts discarded thermal energy into reusable process heat, with feasibility studies increasingly contested by industrial heat pump alternatives achieving above 35°C temperature lift.
- Pressure Boosting:Low-pressure suction streams require compression to intermediate discharge pressures for downstream process integration.
- Refrigeration:Thermocompressor-driven absorption cycles serve niche cooling applications in chemical and food processing plants.
- Heating:Process heat delivery through recompressed vapor distribution dominates dairy and pharmaceutical hygienic design requirements.
Pressure boosting holds installed base. Energy recovery is gaining share fastest on carbon accounting integration.
Technology:
Control architecture sophistication separates premium positioning from commodity procurement, with variable-speed integration commanding engineering premiums in retrofit contexts.
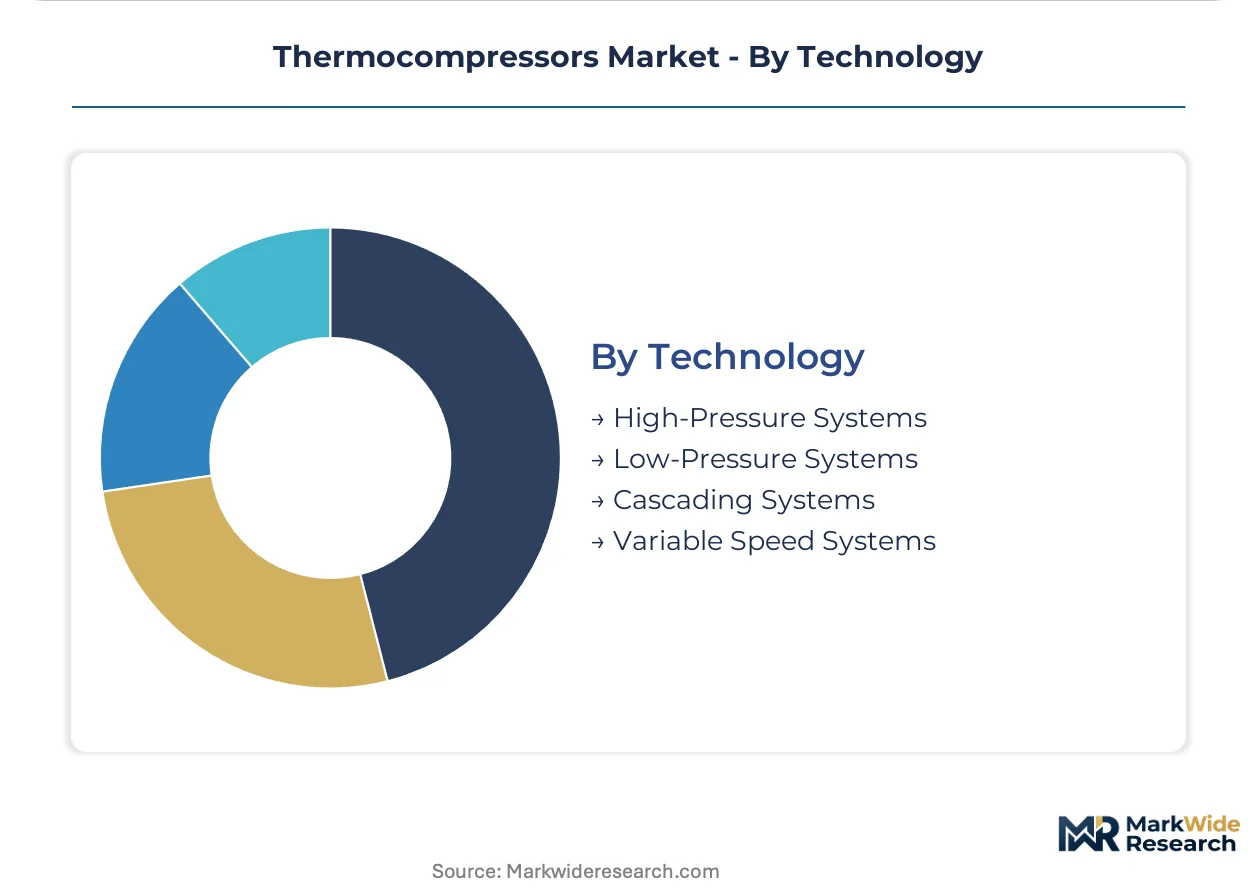
- High-Pressure Systems:Motive pressures above 15 bar enable compression ratios exceeding 10:1 for demanding process applications.
- Low-Pressure Systems:Reduced motive pressure requirements suit facilities with limited steam header capacity or lower compression ratio needs.
- Cascading Systems:Multiple ejector stages in series achieve higher overall compression ratios for deep vacuum applications.
- Variable Speed Systems:Variable-speed drives enable load-following across fluctuating process conditions, though legacy distributed control system integration creates commissioning delays when existing plant automation architectures lack native compatibility.
High-pressure systems dominate current installations. Variable speed systems are expanding most quickly on retrofit demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German engineering exports while Indian fabricators compete on tender cost. This asymmetry shapes procurement patterns across chemical processing corridors. Regional specialization determines where thermocompressor margins accumulate versus where volume concentrates.
United States
Petrochemical expansion along the Texas and Louisiana Gulf Coast drives specification demand. EPA emissions thresholds compel refiners to recover vented steam rather than flare it, embedding thermocompressor procurement into engineering standards. Houston-Baytown process facilities anchor installation volume for energy recovery configurations.
Germany
Rhine-Ruhr industrial belt replacement cycles accelerate under EU Green Deal efficiency mandates. Existing steam systems fail revised emissions thresholds, redirecting capital toward electric and hybrid architectures. BASF-Ludwigshafen and Bayer-Leverkusen chemical complexes lead retrofit specification for load-following systems.
China
Shandong and Jiangsu province chemical manufacturers face MEE penalties on coal-fired boiler output. Dual carbon enforcement redirects investment toward electric thermocompressor retrofits that reduce steam dependency. Ningbo-Zhoushan petrochemical zone pilots grid-powered compression architectures for Scope 2 emissions reduction.
India
Gujarat chemical cluster presents underpenetrated installation base among specialty chemical producers. PLI scheme incentives for process equipment manufacturing attract domestic fabrication investment. Dahej and Vadodara industrial zones generate first-mover positioning opportunities for hybrid system suppliers.
Japan
Chubu-Nagoya manufacturing belt maintains precision engineering demand for high-reliability vacuum systems. METI energy efficiency standards drive replacement of aging steam ejector infrastructure. Yokkaichi chemical complex specifications emphasize integration compatibility with existing distributed control architectures.
Thermocompressors Market Competitive Landscape
Concentration sits with diversified industrial conglomerates possessing captive steam system expertise. Mid-scale specialists defend position through application-specific certification and regional aftermarket capture. Three archetypes dominate: integrated process equipment suppliers, dedicated compression technology firms, and diversified engineering conglomerates. Competitive moves center on modular platform standardization and service contract unbundling to capture recurring revenue streams.
Among diversified engineering groups, Siemens and Atlas Copco exemplify scale-driven positioning across multiple compression technologies. KSB and GEA Group occupy specialized tiers where aftermarket service contracts and hygienic design capabilities create defensive positioning. SPX Flow represents backward integration into steam ejector component supply. These named entities anchor archetype descriptions rather than exhaust competitive mapping.
| Leading Market Players |
|---|
| SPX Flow |
| KSB |
| GEA Group |
| Altec |
| Andritz |
| Atlas Copco |
| JBT Corporation |
| Rietschle |
| Siemens |
| Others |
Value Network & Pricing Analysis
Electric thermocompressor substitution for steam-based systems is redrawing procurement geography from coal-dependent Shandong toward grid-rich Jiangsu, compressing margins on legacy boiler-tied configurations while elevating premiums for load-following hybrid architectures that bridge both energy inputs.
Pricing Analysis
The customization-premium spread between configured-to-order and catalog-standard thermocompressors has narrowed to three-tier pricing structure across premium, standard, and economy levels as additive manufacturing collapses minimum viable order thresholds. Price differentiation hinges on ISO 5167 nozzle certification tier and motive fluid flexibility—hybrid systems command the widest spreads while single-fluid steam units face the steepest compression. Cost compression in standard steam thermocompressors is intensifying because modular platforms erode proprietary design premiums. Mid-scale specialty chemical producers in India's Gujarat cluster exhibit highest price sensitivity, whereas pharmaceutical heating circuit buyers prioritize hygienic certification over unit cost.
Supply Chain Analysis
Strait of Malacca transit underwrites nickel-alloy delivery schedules for pressure vessel fabricators serving Asian project markets, exposing tender-cycle margins to maritime congestion volatility. Component manufacturing concentrates in Germany, China, and India—German engineering exports anchor premium nozzle assemblies, Chinese fabricators dominate electric drive integration, and Indian suppliers capture PLI-scheme incentives for domestic process equipment. Raw material dependencies center on nickel-chrome alloys for corrosion-resistant vessels, precision-machined motive nozzles, and variable-frequency drive electronics. Single-source vulnerability concentrates in accredited European ISO 5167 verification laboratories that gate export market entry for uncertified Asian suppliers. Distribution runs through EPC contractors and direct OEM channels to plant engineering teams at major chemical complexes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Jet ejector computational fluid dynamics expertise scarcity—compounded by software-sector compensation benchmarks that drain talent from equipment manufacturers—concentrates design optimization capability among incumbents with captive simulation teams and fragments innovation velocity across the supplier base.
For Market Incumbents: Compound aftermarket service capture through localized spare parts inventory in India's Gujarat cluster and dedicated CFD talent retention programs that industrial heat pump substitution threats cannot replicate. Defend margin structures by anchoring European installed bases with unbundled technical service agreements rather than captive component lock-in, while accelerating hybrid platform standardization to outpace electric-only entrants in load-following applications. For New Entrants and Emerging Players: Differentiate on pharmaceutical hygienic design certification that GEA Group and SPX Flow dominate but generalist compressor manufacturers cannot replicate without dedicated clean-steam validation protocols. Target India's underpenetrated specialty chemical segment with pilot-scale hybrid systems capable of six-month procurement windows via topology-optimized additive manufacturing. Pursue direct sales to Dahej and Vadodara industrial zones with outcome-based energy recovery guarantees rather than EPC channel dependence. For Investors and Strategic Acquirers: The market sits at a technology-replacement phase that favors electric and hybrid architecture specialists over legacy steam-system incumbents with stranded boiler-tied revenue streams. Long-term viability across the next decade hinges on carbon border adjustment mechanism positioning and dual carbon enforcement durability in China. Acquisition targets should demonstrate ISO 5167 certification capacity and native distributed control system integration compatibility. Watch MEE penalty escalation rates in Shandong and Jiangsu provinces as the signal for electric thermocompressor retrofit inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nozzle Manufacturing | Additive manufacturing of topology-optimized geometries collapses custom project volume thresholds for German engineering exports. |
| Hybrid Platform Standardization | Load-following capability across variable steam and electricity inputs captures EU Green Deal replacement cycles in Rhine-Ruhr chemical complexes. |
| Aftermarket Service Unbundling | Inventory localization in Gujarat defends component margins as Indian chemical operators separate spare parts procurement from technical agreements. |
| ISO 5167 Certification Investment | Accredited nozzle measurement verification removes export market entry barriers for Asian suppliers seeking US Gulf Coast petrochemical specification. |
| Pharmaceutical Hygienic Design Specialization | Clean-steam validation protocols create defensive moats in dairy and pharmaceutical heating circuits that generalist manufacturers cannot replicate. |
Research Methodology
Operator-level perspectives from plant engineers, maintenance directors at US Gulf Coast refineries, procurement leads at German chemical complexes, and aftermarket service heads anchored the qualitative base for this thermocompressor market assessment. Primary fieldwork with EPC contractors and OEM technical sales teams combined with secondary validation from EPA emissions enforcement documentation, MEE dual carbon policy filings, EU Green Deal efficiency mandate texts, and SEC 10-K disclosures from listed process equipment manufacturers. Customs data on nickel-alloy pressure vessel trade flows and ISO 5167 accreditation registries furnished supply-side triangulation. Bottom-up project pipeline tracking across Texas-Louisiana, Rhine-Ruhr, Shandong-Jiangsu, and Gujarat chemical corridors converged with top-down energy recovery equipment spend estimates.
Sensitivity analysis around carbon border adjustment mechanism implementation timelines, MEE penalty escalation scenarios, and industrial heat pump efficiency gain trajectories stress-tested base-case assumptions across the projection horizon. Segmentation modeling spanned product type (steam, electric, gas, hybrid), end-use industry (chemical manufacturing, food processing, oil and gas, power generation), application purpose (energy recovery, pressure boosting, refrigeration, heating), and technology tier (high-pressure, low-pressure, cascading, variable-speed). CAGRs derived from installed base turnover rates, retrofit engineering study conversion ratios, and greenfield petrochemical capital commitment pipelines. Specific forecast inputs included EPA emissions threshold compliance deadlines and PLI scheme incentive disbursement schedules for Indian process equipment manufacturing.
Material uncertainties—regulatory enforcement intensity variations, nickel-alloy price volatility, and heat pump substitution feasibility threshold crossings—sit outside the modeled envelope and could accelerate or delay technology replacement cycles substantially. Forecasts reflect assumptions about dual carbon policy durability and carbon border adjustment geographic expansion that practitioners should keep alternative scenarios live as EU and North American trade policy frameworks evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Recirculating Chillers Market
HVAC Equipment
Strip Warmer Market
HVAC Equipment
HVAC Airflow and Blend Door Actuator Systems Market
HVAC Equipment
Shell and Tube Heat Exchangers Market
HVAC Equipment
South Korea HVAC Market
HVAC Equipment
Global Modular Chillers Market
HVAC Equipment
Blowers Market
HVAC Equipment
Global Portable Air Conditioner Market
HVAC Equipment
North America Commercial HVAC Market
HVAC Equipment
Combustion Controls, Equipments and Systems Market
HVAC Equipment
Ventilation Equipment Market
HVAC Equipment
Global Portable Evaporative Air Cooler Market
HVAC Equipment
Global Industrial Air Chiller Market
HVAC Equipment
Global Variable Refrigerant Flow (VRF) Market
HVAC Equipment
Italy HVAC Market
HVAC Equipment
Compressor Controllers Market