
 Global Air-To-Air Heat Pumps Market | 2026-2036
Global Air-To-Air Heat Pumps Market Size, Share, and Industry Trends Forecast 2026-2036
Global Air-To-Air Heat Pumps Market Analysis
Certified refrigeration technician availability is bifurcating market growth between regions with robust vocational pipelines and those facing labor shortfalls. Daikin Industries leverages its captive training networks to sustain installation quality across priority markets. Mitsubishi Electric anchors premium cold-climate positioning through deep inverter R&D specialization. Carrier competes on scale by controlling commercial channel access across North America and Western Europe.
Air-to-air heat pumps transfer thermal energy between indoor and outdoor air masses using vapor-compression refrigeration cycles, typically operating with coefficient of performance ratings between two and five depending on ambient temperature and system configuration. These systems serve primary heating and cooling functions in residential, commercial, and light industrial envelopes where direct combustion equipment faces regulatory phaseout. Split systems dominate unit volume due to retrofit compatibility and lower installed cost, while inverter technology captures expanding share as efficiency standards tighten and electricity rate structures reward variable-load operation. Multi-split systems occupy narrower but higher-margin niches in multi-zone commercial and dense residential applications where ductwork retrofit proves impractical.
EPA refrigerant phase-down rules under the AIM Act, EU F-Gas Regulation fluorinated gas restrictions, and Japan METI Top Runner efficiency standards collectively reshape product design cycles and refrigerant selection across all major manufacturing bases. Compliance with these frameworks now determines market access eligibility rather than merely influencing product positioning. Stakeholders must monitor refrigerant transition timelines and cold-climate performance certification thresholds to align R&D allocation with emerging procurement specifications.
Market Dynamics
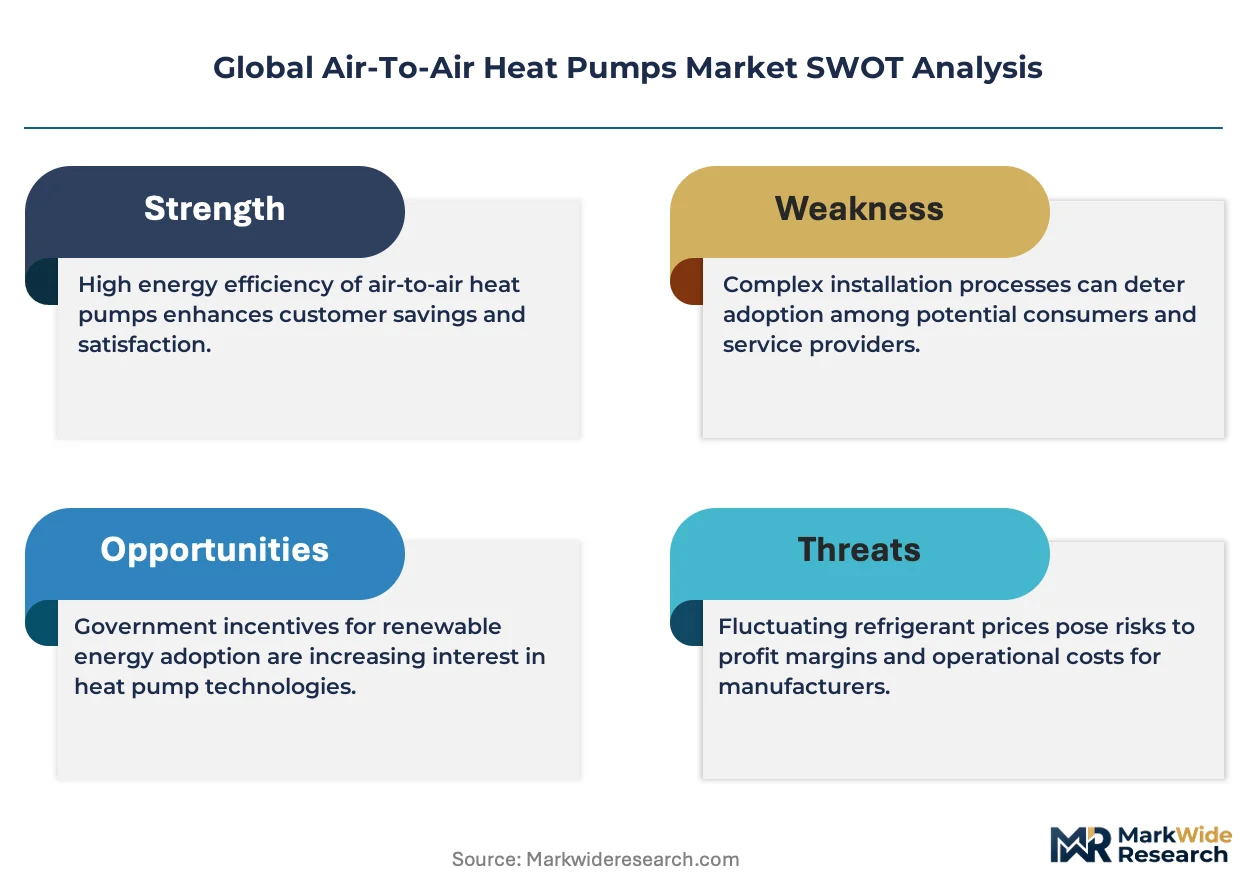
The refrigerant transition mandated by EPA AIM Act phase-down schedules and EU F-Gas Regulation is forcing simultaneous R&D redirection across all manufacturing bases, compressing product development cycles while cold-climate certification requirements intensify.
Growth Catalysts
- EU Green Deal implementation:National boiler bans across Germany, the United Kingdom, and France are accelerating residential retrofit decisions and reshaping heating infrastructure procurement timelines.
- Inverter technology maturation:Variable-speed compressors now achieve coefficient of performance ratings above three at ambient temperatures below minus fifteen degrees Celsius, expanding addressable markets in Nordic climates.
- Building energy code tightening:Japan METI Top Runner efficiency standards and comparable frameworks in South Korea are mandating performance thresholds that favor heat pump adoption over direct combustion equipment.
Market Restraints
- Copper and rare earth input volatility:Compressor motor magnets and refrigerant line materials face price swings that compress manufacturer margins and destabilize installed cost forecasting.
- Certified technician supply concentration:Vocational pipeline gaps in North American and Southern European markets limit installation capacity and elongate project timelines.
- Natural gas infrastructure lock-in:Existing distribution networks and sunk capital in residential heating oil systems create substitution friction in legacy building stock.
Strategic Opportunities
- Multi-split system penetration:Dense urban residential and commercial applications where ductwork retrofit proves impractical represent underexploited margin-rich segments.
- US Inflation Reduction Act incentives:Tax credits and rebate programs for high-efficiency heat pump installations are creating new demand pull in states with aggressive decarbonization targets.
- Refrigerant convergence with CO2 and propane:Low-global-warming-potential alternatives are opening certification pathways for manufacturers ahead of regulatory deadlines.
Industry Challenges
- Cold-climate performance certification complexity:Multiple testing protocols across AHRI, Eurovent, and JIS standards create compliance fragmentation and lengthen product validation cycles.
- Integration friction with legacy hydronic systems:Hybrid configurations requiring buffer tanks and control system upgrades increase project complexity and contractor training burdens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Air-To-Air Heat Pumps Market |
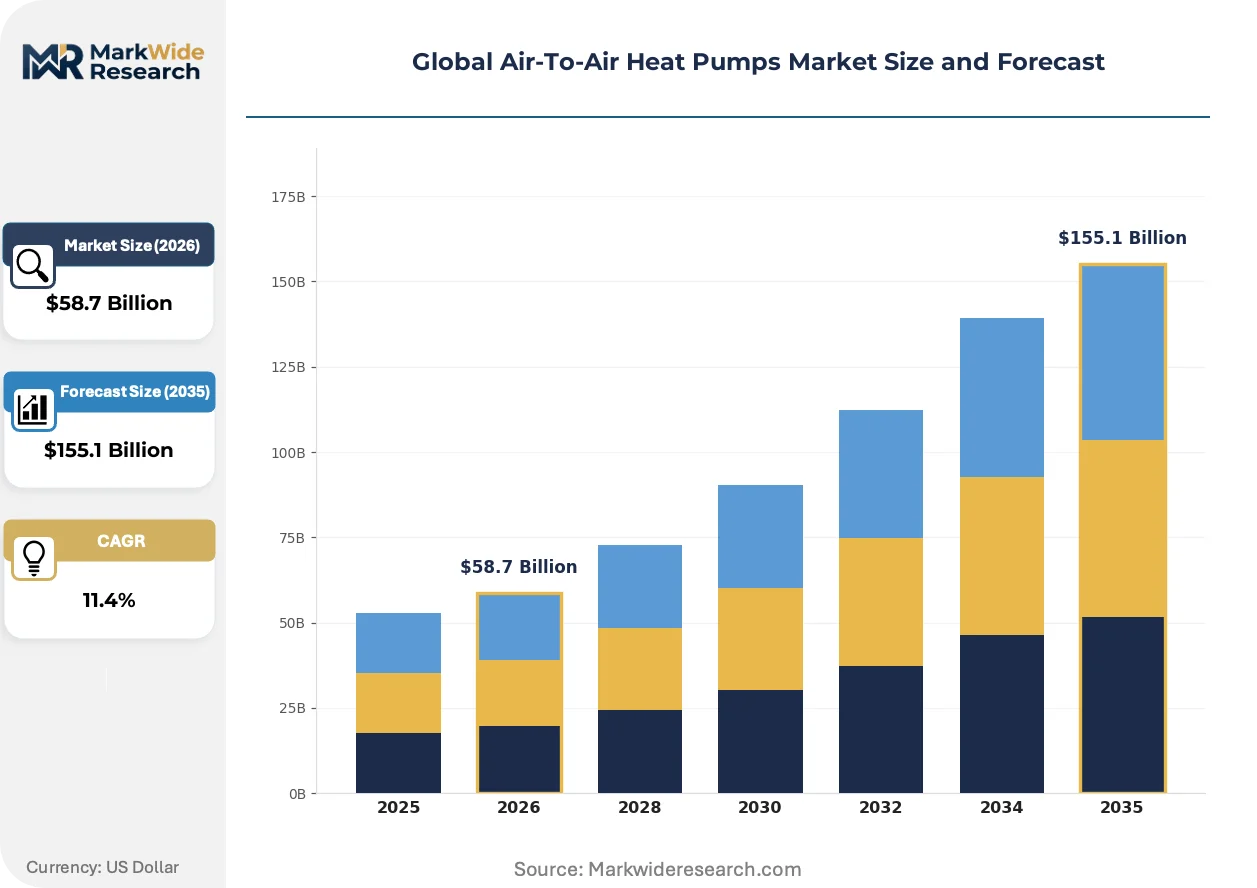
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $155.1 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Split Systems, Multi-Split Systems, Integrated Systems, Hybrid Systems Technology: Inverter Technology, Non-Inverter Technology, Geothermal Technology, Solar-Assisted Technology End User: Residential Buildings, Commercial Buildings, Industrial Facilities, Municipal Infrastructure Installation: New Construction, Retrofit, Replacement, Seasonal |
| Companies Covered | Daikin Industries, Carrier, LG Electronics, Panasonic, Mitsubishi Electric, Bosch Thermotechnology, Trane, Fujitsu General, Midea Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Air-To-Air Heat Pumps Market Emerging Trajectories
Refrigerant chemistry and system architecture are undergoing parallel transformation as regulatory phase-downs compress timelines and cold-climate performance demands intensify across high-latitude markets.
Low-global-warming-potential refrigerant adoption is bifurcating product portfolios between R-32 transitional solutions and propane/CO2 next-generation systems. European manufacturers are prioritizing R-32 platforms for immediate F-Gas compliance, while Japanese and Korean producers accelerate CO2 heat pump development for commercial scale. This technology split is creating divergent supply chains and certification requirements that will persist through the decade.
EPA refrigerant phase-down rules under the AIM Act are mandating cumulative production cuts that reshape import and manufacturing strategies. Domestic producers must retool assembly lines ahead of 2027 step-down milestones, while importers face quota allocation uncertainties. Residential split-system categories bear the greatest compliance burden due to volume exposure and refrigerant charge size.
Installer certification is becoming a decisive purchase criterion as quality failures in early deployments damage category reputation. Homeowners in Germany and the United Kingdom now prioritize contractor credentials over brand selection, fragmenting traditional manufacturer-distributor relationships. This behavior shift is most pronounced in retrofit markets where system sizing and commissioning errors carry high remediation costs.
Global Air-To-Air Heat Pumps Market Segmentation
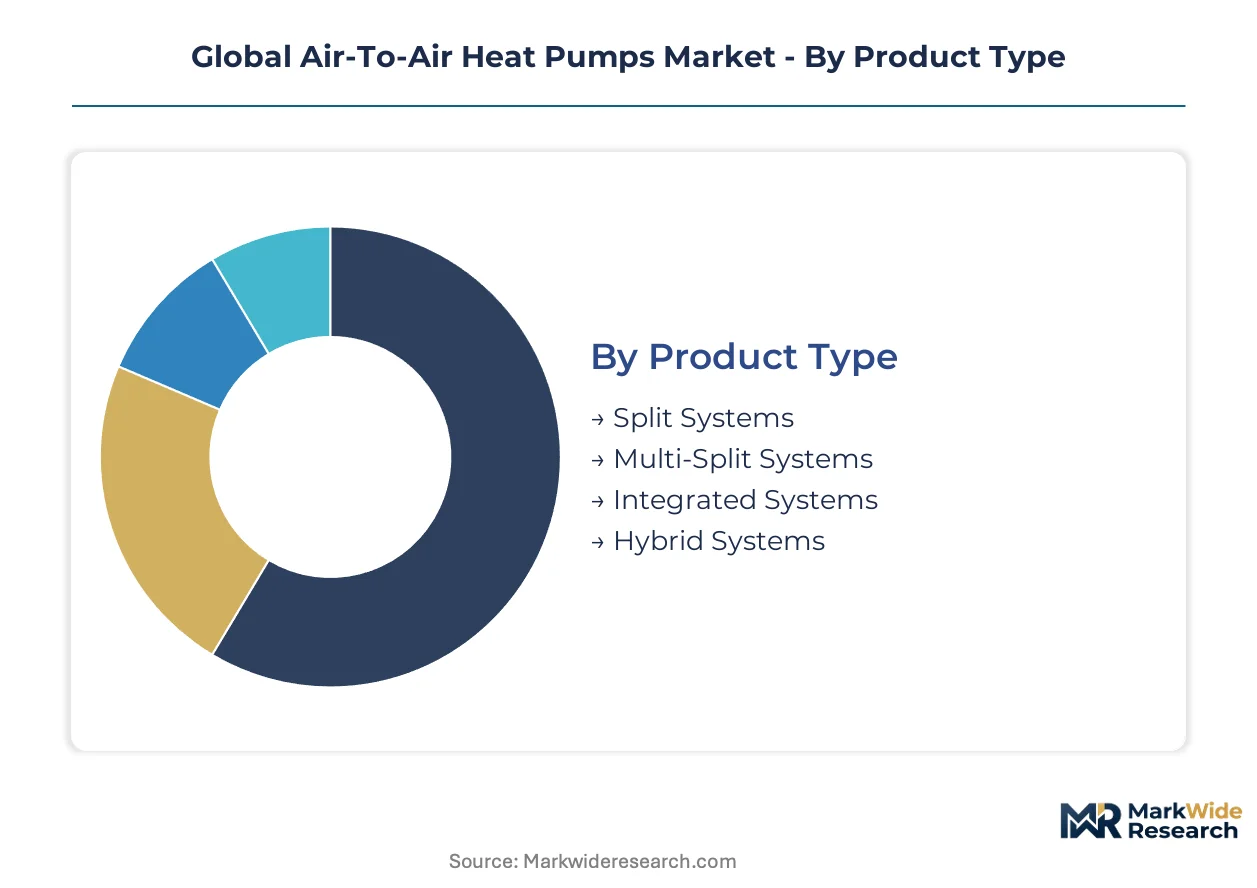
Segmentation in air-to-air heat pumps reveals how technology choices, building types, and installation contexts reshape procurement patterns across regulatory environments. Manufacturers align product portfolios with distinct performance thresholds and channel access requirements.
Product Type:
Split systems dominate domestic manufacturing bases in Japan and China, while multi-split platforms concentrate in European export channels serving dense urban retrofits.
- Split Systems:Single indoor unit paired with one outdoor compressor, optimized for residential envelope retrofits where ductwork installation proves cost-prohibitive. Demand clusters in German and UK residential replacements as boiler bans accelerate. Cold-climate inverter variants now achieve coefficient of performance above three at minus fifteen degrees Celsius ambient.
- Multi-Split Systems:Single outdoor unit serving multiple indoor zones through independent refrigerant lines, enabling individualized temperature control without ductwork. Commercial buildings and dense residential blocks in France and South Korea drive specification, with premium positioning reflecting installation complexity and commissioning requirements.
- Integrated Systems:Factory-sealed monobloc units with reduced on-site refrigerant handling, gaining traction in markets with strict F-Gas Regulation enforcement.
- Hybrid Systems:Dual-fuel configurations pairing heat pumps with auxiliary combustion equipment, addressing peak-load gaps in Nordic climates and legacy hydronic retrofits.
Split systems command the established base. The steepest expansion runs through multi-split configurations.
Technology:
Cost tiers separate premium inverter platforms from entry non-inverter alternatives, with emerging geothermal and solar-assisted categories occupying narrow high-margin niches.
- Inverter Technology:Variable-speed compressors modulate output to match thermal load, delivering part-load efficiency advantages under Japan METI Top Runner standards. European and Japanese manufacturers anchor R&D spending here, with cold-climate certification becoming the decisive competitive filter.
- Non-Inverter Technology:Fixed-speed compressors cycling between full output and off states, retaining volume in price-sensitive replacement markets and warm-climate applications where efficiency premiums fail to justify installed cost deltas.
- Geothermal Technology:Ground-source coupling for enhanced seasonal performance factors, limited by site-specific drilling requirements and concentrated in new construction with available land.
- Solar-Assisted Technology:Photovoltaic integration reducing grid electricity draw during peak cooling loads, emerging in Australian and California residential markets with favorable net-metering structures.
Inverter platforms absorb the majority of manufacturer R&D allocation. Solar-assisted configurations are climbing the fastest as distributed generation economics improve.
End User:
Application context determines performance certification requirements, with residential and commercial segments facing diverging procurement timelines and incentive eligibility.
- Residential Buildings:Single-family and multi-family dwellings where split and multi-split configurations displace direct combustion equipment. US Inflation Reduction Act tax credits and EU national boiler bans concentrate demand pull in Germany, France, and high-decarbonization US states.
- Commercial Buildings:Offices, retail, and hospitality envelopes where multi-split and VRF architectures dominate. Building energy code compliance and corporate sustainability procurement drive specification, with longer replacement cycles than residential counterparts.
- Industrial Facilities:Process heating and auxiliary space conditioning in light manufacturing, constrained by higher temperature requirements that limit pure heat pump applicability without hybrid configurations.
- Municipal Infrastructure:Schools, hospitals, and government buildings where public procurement rules and decarbonization mandates accelerate adoption, particularly in Scandinavian municipalities with district heating integration potential.
Residential buildings command the established base. Commercial buildings are gaining share fastest as corporate net-zero commitments harden into capital allocation priorities.
Installation:
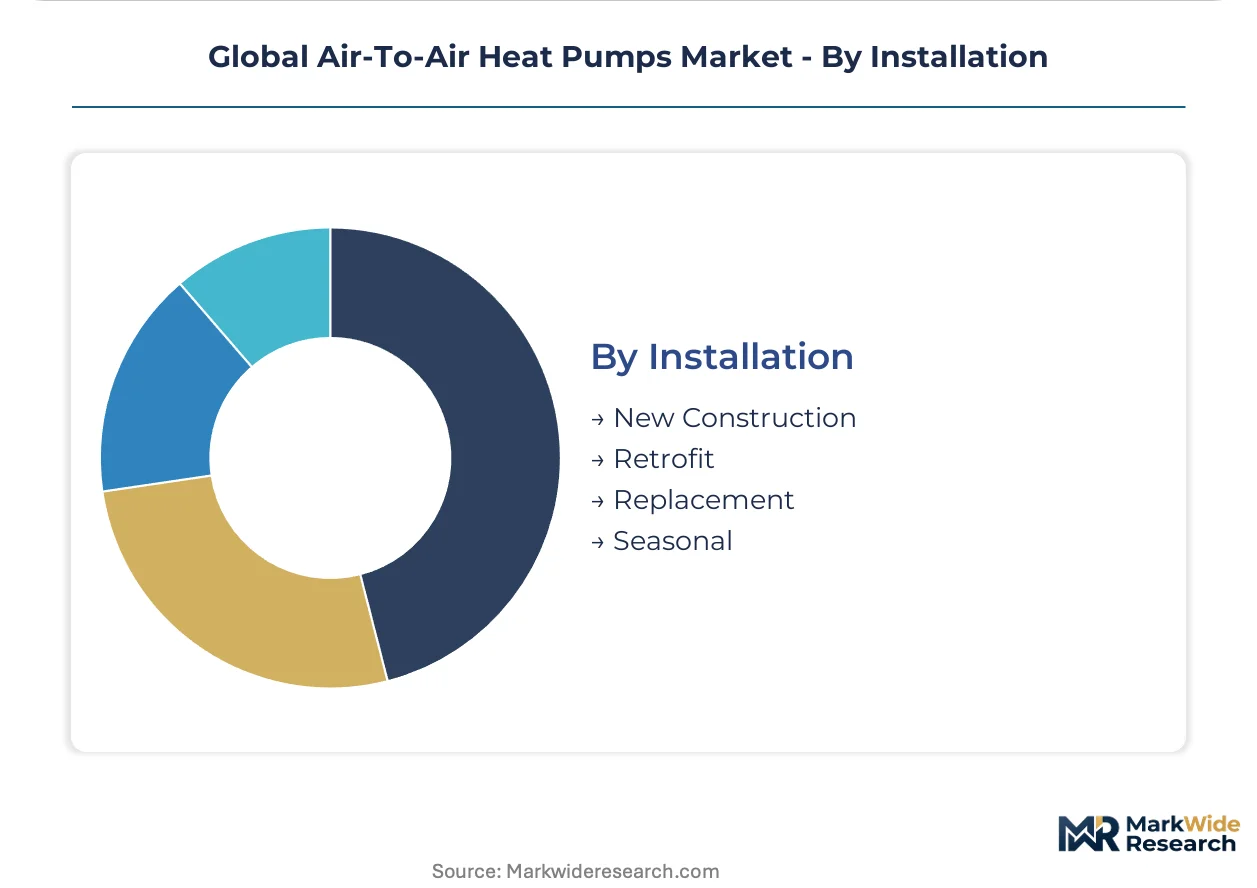
Volume concentrates in replacement and retrofit channels, with new construction penetration dependent on builder relationships and code adoption timing.
- New Construction:Heat pump-first designs integrated from architectural planning, prevalent in California and EU member states with near-zero-energy-building requirements. Lower installed cost per unit versus retrofit due to concurrent mechanical and envelope work.
- Retrofit:Replacement of existing combustion equipment in occupied buildings, dominating German and UK market volume. Project complexity and contractor availability constrain capacity, with quality failures in early deployments damaging category reputation.
- Replacement:Direct substitution of failed or end-of-life heat pump units, offering shortest sales cycles and lowest customer acquisition costs for established installers.
- Seasonal:Temporary or supplemental installations in recreational properties and construction site offices, limited volume but minimal regulatory exposure.
Retrofit commands the established base. New construction shows the steepest expansion trajectory as building codes tighten across high-income markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany deploys air-to-air heat pumps primarily for residential retrofits, whereas Japan concentrates volume in new construction with integrated inverter platforms. The United States splits demand between replacement cycles and IRA-driven upgrades. China manufactures at scale for export while domestic adoption lags in northern heating zones.
Germany
The Building Energy Act mandates heat pump readiness in all new heating installations from 2024, accelerating retrofit decisions in single-family housing stock. BAFA federal funding programs cover up to 40 percent of installed costs for systems meeting efficiency class A+++. Manufacturing and R&D clusters concentrate in Bavaria and Baden-Württemberg, where Bosch Thermotechnology and regional suppliers coordinate inverter cold-climate testing protocols.
United States
IRA tax credits of up to two thousand dollars per unit and state-level rebate stacking drive replacement demand in cold-climate zones previously dependent on fuel oil. EPA AIM Act refrigerant phase-down rules compress product development timelines for domestic assembly lines. Northeast corridor states from Massachusetts to New York enforce building performance standards that disqualify new fossil fuel heating in commercial envelopes.
Japan
METI Top Runner efficiency standards reset minimum performance thresholds every three years, forcing continuous inverter technology advancement. Residential new construction in the Kanto and Kansai regions specifies heat pump-first designs as standard practice. Osaka-based manufacturing clusters supply variable-speed compressor platforms to Southeast Asian export markets facing similar efficiency mandates.
China
Dual carbon goals target 2030 carbon peak and 2060 neutrality, with heat pumps designated as priority decarbonization technology in the 14th Five-Year Plan. NEVI-equivalent building efficiency standards in Yangtze River Delta cities mandate renewable heating in public construction. Guangdong Province export manufacturing bases supply inverter platforms to European markets facing F-Gas Regulation compliance deadlines.
United Kingdom
The Boiler Upgrade Scheme offers five-thousand-pound grants for air-source heat pump installations, targeting 600,000 annual deployments by 2028. Future Homes Standard bans fossil fuel heating in new construction from 2025. Installer certification concentration in Greater London and the Southeast contrasts with technician shortfalls in Northern England and Scotland, fragmenting service quality.
Global Air-To-Air Heat Pumps Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with scale advantages in compressor manufacturing and captive distribution networks determining tier boundaries. Japanese and Korean conglomerates anchor the upper tier through backward integration into inverter electronics and refrigerant chemistry. Mid-cap European specialists compete on cold-climate certification depth and hybrid system integration. Capacity expansion in Southeast Asian assembly plants and strategic partnerships for CO2 refrigerant development represent the dominant competitive moves across tiers.
Within the integrated conglomerate tier, Daikin Industries and Mitsubishi Electric exemplify vertical control over compressor manufacturing and captive training networks. Carrier occupies a position bridging North American commercial channel scale with European regulatory compliance capabilities. Among diversified electronics groups, LG Electronics and Panasonic sit within portfolios where heat pump divisions leverage shared inverter R&D with appliance and battery businesses.
| Leading Market Players |
|---|
| Daikin Industries |
| Carrier |
| LG Electronics |
| Panasonic |
| Mitsubishi Electric |
| Bosch Thermotechnology |
| Trane |
| Fujitsu General |
| Midea Group |
| Others |
Supply Flow & Price Mechanics
Compressor manufacturing scale economies in Japan and China anchor global production cost floors, concentrating inverter platform supply among vertically integrated conglomerates while compressing margins for second-tier assemblers dependent on merchant component sourcing. This scale concentration simultaneously elevates price floors for premium cold-climate certified systems and erodes pricing power in non-inverter segments facing commoditization.
Pricing Analysis
Long-term offtake contracts between European distributors and Japanese manufacturers dominate premium inverter procurement, insulating price stability against copper and rare earth volatility while spot-market exposure concentrates in non-inverter replacement channels. Price differentiation separates cold-climate AHRI-certified platforms from standard-efficiency alternatives, with installer bundling and extended warranty coverage widening spreads. Cost compression in entry-level split systems intensifies as Chinese export capacity expands, though residential retrofit buyers in Germany and the United Kingdom prioritize contractor certification over brand price points, muting pure price competition.
Supply Chain Analysis
Japan and China anchor variable-speed compressor fabrication, with South Korean producers expanding magnet motor capacity to feed European export demand. Rare earth permanent magnets and copper refrigerant tubing draw from concentrated mining and smelting networks, exposing manufacturers to commodity price swings and tariff exposure from trade policy shifts. Distribution runs through authorized dealer networks in developed markets and wholesale channels in price-sensitive regions, with captive training programs becoming decisive competitive infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense imperatives as district heating network expansions in Scandinavian municipalities and hydrogen-ready boiler retrofits in German residential stock threaten addressable market erosion. Navigating these parallel substitution threats demands preemptive positioning in hybrid system architectures and service-contract bundling.
For Market Incumbents: Shield core retrofit margins by deepening captive installer certification networks in technician-constrained UK and US Northeast markets, where quality failures in early deployments have fragmented brand loyalty. Accelerate backward integration into CO2 refrigerant compressor platforms ahead of EU F-Gas Regulation step-down milestones, converting compliance burden into sourcing advantage over import-dependent competitors.
For New Entrants and Emerging Players: Lead with multi-split system specialization targeting dense urban commercial retrofits in France and South Korea, where ductwork impracticality creates specification stickiness and commissioning complexity deters generalist competition. Emphasize project-based service bundling over equipment-only positioning, capturing lifecycle revenue streams that established manufacturers have left underdeveloped.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among manufacturers with captive service networks and refrigerant reclamation infrastructure, positioning these archetypes for sustained cash flow quality across regulatory transition cycles. Monitor US EPA AIM Act quota allocation rulings as inflection signals for import-dependent assembly strategies versus domestic retooling investments.
| Strategic Initiative | Industry Significance |
|---|---|
| CO2 Refrigerant Platform Development | Positions manufacturers ahead of EU F-Gas Regulation compliance deadlines in commercial segments. |
| Captive Installer Certification Expansion | Locks distribution access in Germany and UK markets where contractor credentials drive purchase decisions. |
| Multi-Split System Portfolio Deepening | Captures margin-rich urban retrofit demand in France and South Korea where ductwork is impractical. |
| Hybrid System Architecture Investment | Addresses peak-load gaps in Nordic climates and legacy hydronic integration requirements. |
| Refrigerant Reclamation Infrastructure Buildout | Creates regulatory-compliant service revenue streams under tightening EPA and EU recovery mandates. |
Methodological Framework
Two parallel data streams informed the analysis: primary interviews with heat pump product directors, certified installation contractors, and utility demand-side management officers, combined with secondary validation against EPA AIM Act filings, EU EEA F-Gas Regulation databases, and Japan METI efficiency standard disclosures. Bottom-up unit shipment estimates by product configuration and technology tier were triangulated against top-down manufacturer revenue disclosures and national incentive program disbursement records.
Across the analysis window, projections integrate segmented demand modeling across residential retrofit, commercial replacement, and new construction installation contexts, with technology adoption curves calibrated to building code adoption timelines and incentive program renewal cycles. CAGRs derive from unit volume trajectories weighted by efficiency-tier pricing differentials, incorporating cold-climate performance certification thresholds as demand filters.
Forecasts assume regulatory continuity in EPA refrigerant phase-down schedules and EU Green Deal implementation timelines; material policy shifts in national boiler ban enforcement or IRA incentive renewal would require re-modeling. Recalibration cycles align with material shifts in copper and rare earth input pricing, technician certification pipeline outputs, and major market incentive program revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Warming Cabinet Market
HVAC Equipment
GCC Kitchen Hood Market
HVAC Equipment
Global Portable Air Conditioner Market
HVAC Equipment
South America Screw Compressor Market
HVAC Equipment
GCC Portable Air Conditioners Market
HVAC Equipment
Water Softener Equipment Market
HVAC Equipment
HVAC Centrifugal Compressors Market
HVAC Equipment
Chilled Beams Market
HVAC Equipment
Industrial Exhaust System Market
HVAC Equipment
Wall Fan Coil Market
HVAC Equipment
Underfloor Heating Market
HVAC Equipment
India Chillers Market
HVAC Equipment
Steam Boiler Systems Market
HVAC Equipment
Industrial Ventilation Equipment Market
HVAC Equipment
Hybrid Air Conditioner Market
HVAC Equipment
Kitchen Hood System Market