
 Equipment Fan Filter Unit (EFU) Market | 2026-2036
Equipment Fan Filter Unit (EFU) Market Size, Share, and Industry Trends Forecast 2026-2036
Equipment Fan Filter Unit (EFU) Market Insights
The EU F-Gas Regulation is decoupling equipment fan filter unit procurement from conventional HVAC retrofit cycles, compelling facility managers to specify low-global-warming-potential refrigerant compatibility in new EFU installations. Camfil leverages its Nordic filtration R&D base to supply HEPA-integrated modules for pharmaceutical clean rooms across Northern Europe. AAF International anchors North American demand through its ISO 14644-certified production lines serving biotechnology clusters. Nicotra Gebhardt competes on fan efficiency ratings, sustaining margin pools in modular retrofit applications for existing semiconductor fabs.
An equipment fan filter unit combines a motorized fan assembly with a replaceable filter medium—typically fiberglass HEPA or ULPA media rated for 99.97% particle retention at 0.3 microns—to deliver laminar airflow and controlled particulate levels in enclosed environments. The integrated technology segment leads value capture, as OEMs bundle variable-frequency drive fans with differential-pressure monitoring to reduce energy draw in continuous-operation clean rooms. Pre-filter configurations represent the fastest-growing product category, since multi-stage filtration extends downstream HEPA element life and cuts maintenance downtime in electronics manufacturing facilities. Biotechnology end users concentrate demand for activated carbon variants, where volatile organic compound scrubbing protects cell culture viability in contract development labs.
The EPA enforces National Emission Standards for Hazardous Air Pollutants on semiconductor fabrication, mandating capture efficiency thresholds that filter-fan units must document through stack testing. ISO 14644-1 clean room classifications in Asia-Pacific electronics corridors require continuous airborne particle monitoring, which METI guidelines in Japan extend to nanomaterial handling facilities. Stakeholders must weigh refrigerant transition timelines against filter media supply constraints when specifying next-generation EFU architectures for greenfield fabs.
Market Dynamics
The EU F-Gas Regulation is forcing semiconductor fabs to accelerate refrigerant transitions in EFU cooling architectures, decoupling procurement cycles from conventional HVAC retrofit timelines and creating urgency around low-GWP compatibility specifications.
Growth Catalysts
- AI Chip Fabrication Expansion:Taiwan and South Korea fabs are scaling ISO Class 1-3 clean room capacity for sub-10 nanometer wafer production, driving concentrated demand for HEPA-integrated fan filter units with continuous laminar airflow.
- EU F-Gas Phase-Down:The regulation's hydrofluorocarbon reduction mandates are compelling facility managers to specify low-global-warming-potential refrigerant architectures in new EFU installations ahead of conventional replacement cycles.
- Multi-Stage Filtration Adoption:Pre-filter configurations are extending downstream HEPA element life in electronics manufacturing facilities, reducing maintenance downtime while meeting ISO 14644-1 particle monitoring requirements.
Market Restraints
- Filter Media Supply Concentration:Fiberglass HEPA and ULPA media production clusters in East Asia create vulnerability to regional logistics disruptions for OEMs dependent on 99.97% retention-rated materials.
- Refrigerant Transition Costs:Low-GWP alternative architectures require complete system redesigns rather than drop-in replacements, elevating capital intensity for fabs mid-upgrade cycle.
- Energy Draw Penalties:Continuous-operation clean rooms face escalating electricity costs that compress margins on standard-efficiency fan assemblies without variable-frequency drive integration.
Strategic Opportunities
- Biotechnology VOC Scrubbing:Activated carbon variants for volatile organic compound removal in contract development labs represent underpenetrated demand outside traditional electronics corridors.
- Modular Retrofit Applications:Existing semiconductor fabs require fan efficiency upgrades without full clean room reconstruction, creating serviceable white space for differential-pressure monitoring bundles.
- Pharmaceutical Clean Room Expansion:Northern Europe's pharmaceutical manufacturing clusters are specifying HEPA-integrated modules for ISO 14644-certified environments, diverging from East Asian electronics concentration.
Industry Challenges
- Stack Testing Documentation:EPA National Emission Standards for Hazardous Air Pollutants mandate capture efficiency thresholds that require specialized validation protocols, extending commissioning timelines for new installations.
- Cross-Regional Certification Alignment:Japan's METI nanomaterial handling guidelines diverge from ISO 14644-1 implementations elsewhere, forcing OEMs to maintain multiple compliance documentation sets.
- Legacy System Integration:Brownfield semiconductor facilities must reconcile variable-frequency drive fan controls with existing building management systems, complicating upgrade pathways.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Equipment Fan Filter Unit (EFU) Market |
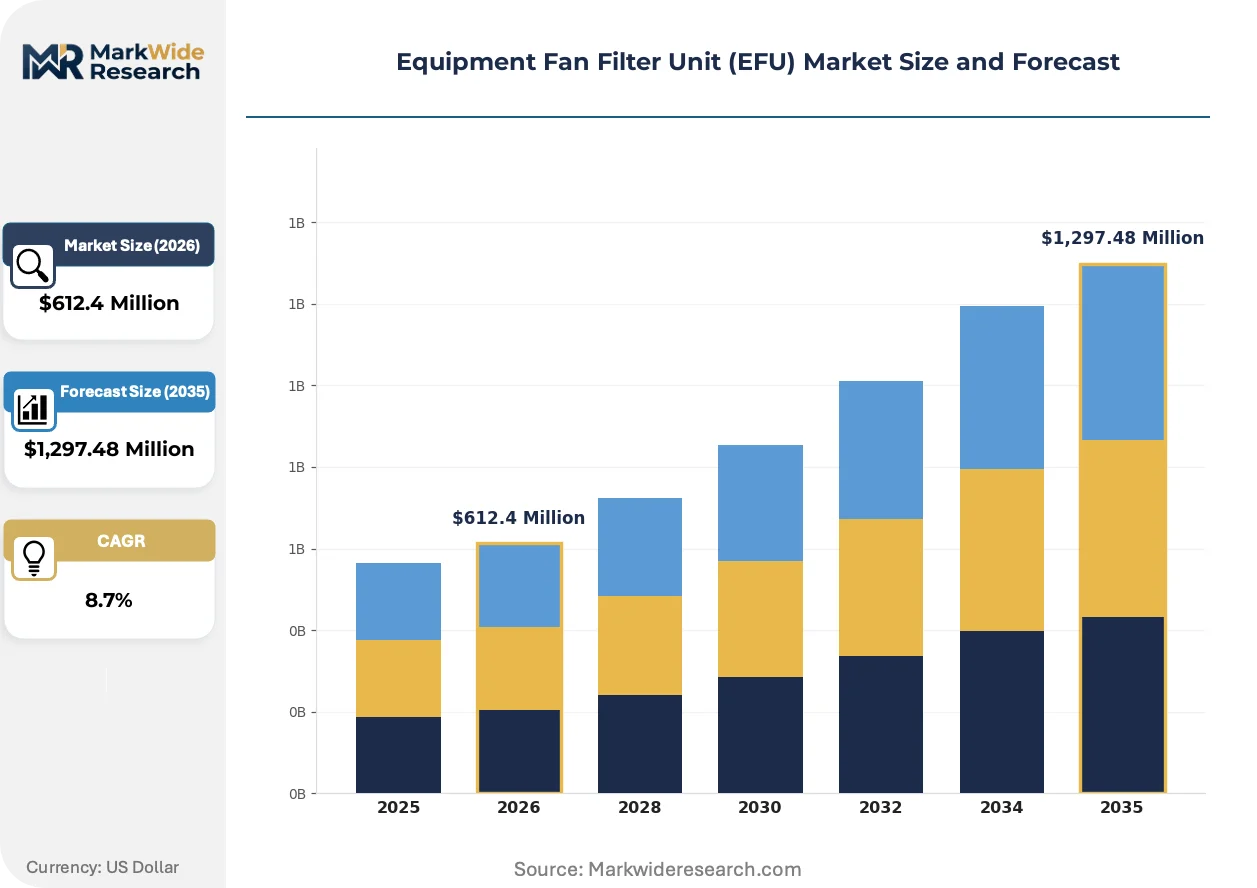
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $1,297.48 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: HEPA, ULPA, Pre-Filter, Activated Carbon Application: Clean Rooms, Laboratories, Pharmaceutical, Hospitals End User: Biotechnology, Electronics Manufacturing, Aerospace, Healthcare Technology: Modular, Integrated, Standalone, Enhanced Efficiency |
| Companies Covered | Camfil, AAF International, Nicotra Gebhardt, Fuji Electric, SHINSUNG E&G, Terra Universal, MANN+HUMMEL, American Air Filter Company, Bosch Rexroth, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Equipment Fan Filter Unit (EFU) Market Trends and Innovations
Equipment fan filter units are undergoing architectural transformation as refrigerant chemistry, filtration media, and procurement models converge to reshape how clean rooms specify, acquire, and operate air handling systems.
Variable-frequency drive integration with differential-pressure monitoring is rewriting energy economics for continuous-operation environments. Semiconductor fabs in Taiwan and South Korea are adopting these bundled configurations at accelerated pace. The technology is compressing operational expenditure gaps between premium and standard efficiency tiers, forcing OEMs to reposition base product lines.
The EU F-Gas Regulation's hydrofluorocarbon phase-down timeline is compressing cooling system replacement cycles across Northern European pharmaceutical and electronics facilities. Industrial consequence includes premature retirement of conventional refrigerant architectures still within technical service life. Modular EFU suppliers are responding with low-GWP-compatible heat exchanger designs sized for retrofit envelope constraints.
Service unbundling is fragmenting traditional bundled procurement in North American biotechnology clusters. Contract development labs are separating filter media supply from fan assembly maintenance, disintermediating single-source OEM relationships. Massachusetts and North Carolina research corridors exhibit the most visible shift toward third-party filter certification and independent fan efficiency auditing.
Equipment Fan Filter Unit (EFU) Market Segmentation
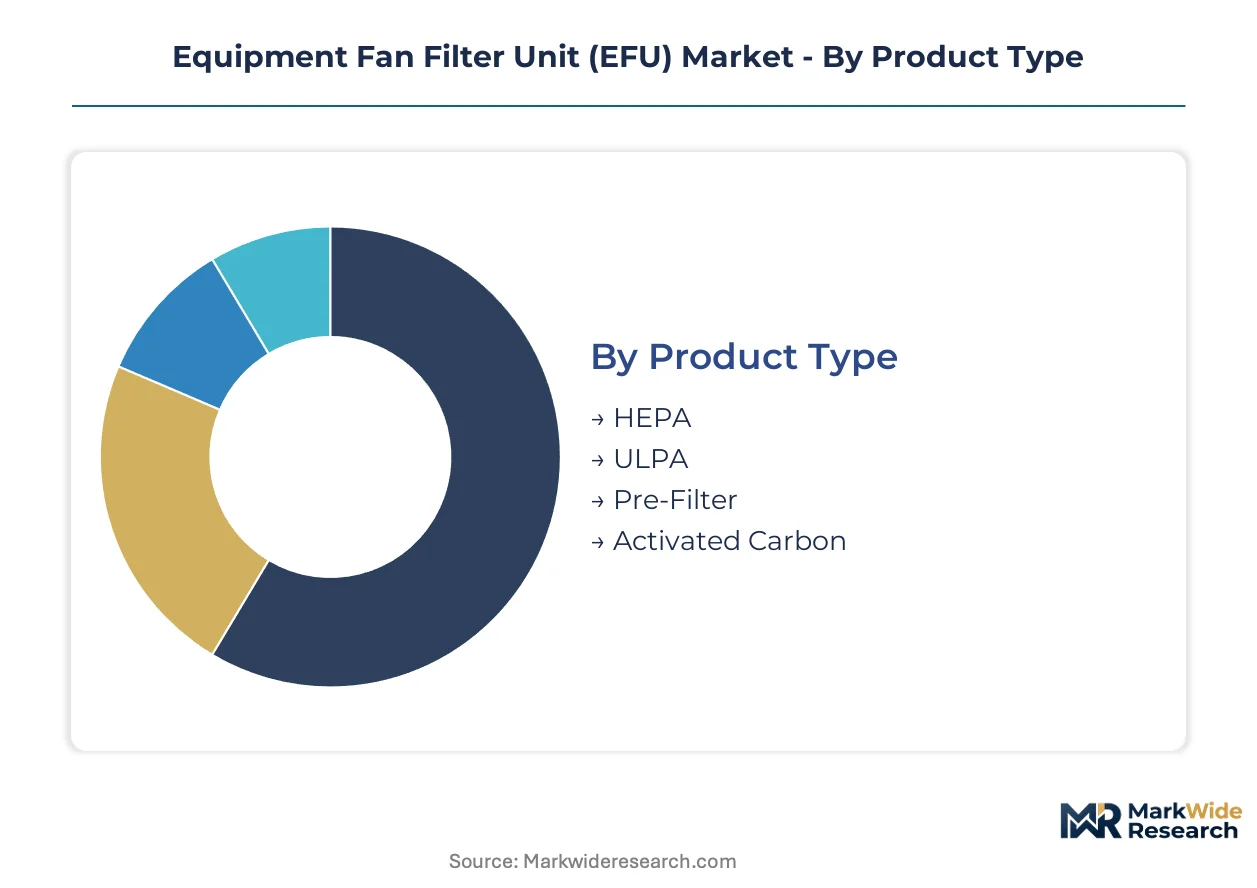
Equipment fan filter unit procurement decisions hinge on filtration grade, deployment architecture, and end-use contamination sensitivity. Segment boundaries are blurring as multi-stage configurations and variable-frequency drive integration reshape how facilities specify, upgrade, and replace air handling assets across upgrade cycles.
Product Type:
Replacement cycles for filter media are decoupling from fan assembly lifecycles, forcing facilities to stage capital expenditure across staggered procurement events.
- HEPA:Fiberglass media rated for 99.97% particle retention at 0.3 microns remains the baseline specification for ISO Class 5-8 environments. Taiwan and South Korea semiconductor fabs specify HEPA-integrated modules for sub-10 nanometer wafer production lines where laminar airflow continuity is non-negotiable.
- ULPA:Ultra-low penetration air filtration achieves 99.999% retention at 0.12 microns through denser glass fiber matrices. Biotechnology contract development labs in Massachusetts and North Carolina concentrate demand for ULPA configurations protecting cell culture viability against viral and nanoparticle contamination.
- Pre-Filter:Pleated synthetic or glass fiber media captures coarse particulates upstream of final filtration stages.
- Activated Carbon:Impregnated carbon beds adsorb volatile organic compounds and molecular contaminants.
Volume placements concentrate in HEPA configurations; the faster expansion belongs to pre-filter multi-stage architectures.
Application:
Cost tier stratification separates premium-specification environments from standard-grade deployments, with certification requirements driving specification divergence.
- Clean Rooms:ISO 14644-1 classified environments demand continuous particle monitoring and laminar airflow maintenance. Electronics manufacturing corridors in East Asia specify fan filter units with differential-pressure monitoring bundles for ISO Class 1-3 wafer fabrication bays.
- Laboratories:Research and analytical facilities balance contamination control against fume handling and personnel protection. Contract development labs are unbundling filter media supply from fan assembly maintenance, fragmenting traditional single-source procurement relationships.
- Pharmaceutical:Aseptic processing and sterile manufacturing operations require validated filtration performance with batch documentation.
- Hospitals:Operating theaters and isolation rooms specify medical-grade air changes per hour with pathogen capture assurance.
Revenue pools favor clean room deployments; the steepest expansion trajectory is appearing in pharmaceutical manufacturing clusters across Northern Europe.
End User:
Customer type determines whether procurement prioritizes energy efficiency metrics, regulatory documentation burden, or total cost of ownership over extended operational horizons.
- Biotechnology:Cell culture and bioprocessing operations require VOC scrubbing and biological containment capabilities. Activated carbon variants are gaining specification share in contract development labs where volatile organic compound removal protects therapeutic molecule stability.
- Electronics Manufacturing:Semiconductor and display panel fabrication demands sub-micron particle control with minimal electrostatic discharge. Taiwan and South Korea fabs are scaling ISO Class 1-3 capacity for AI chip production, concentrating demand for premium filtration configurations.
- Aerospace:Precision component manufacturing and satellite assembly facilities require cleanliness control with vibration isolation.
- Healthcare:Hospital infrastructure and diagnostic equipment manufacturing balance infection control against operational uptime requirements.
Electronics manufacturing commands the dominant placement volume; biotechnology is climbing the fastest on activated carbon and ULPA specification growth.
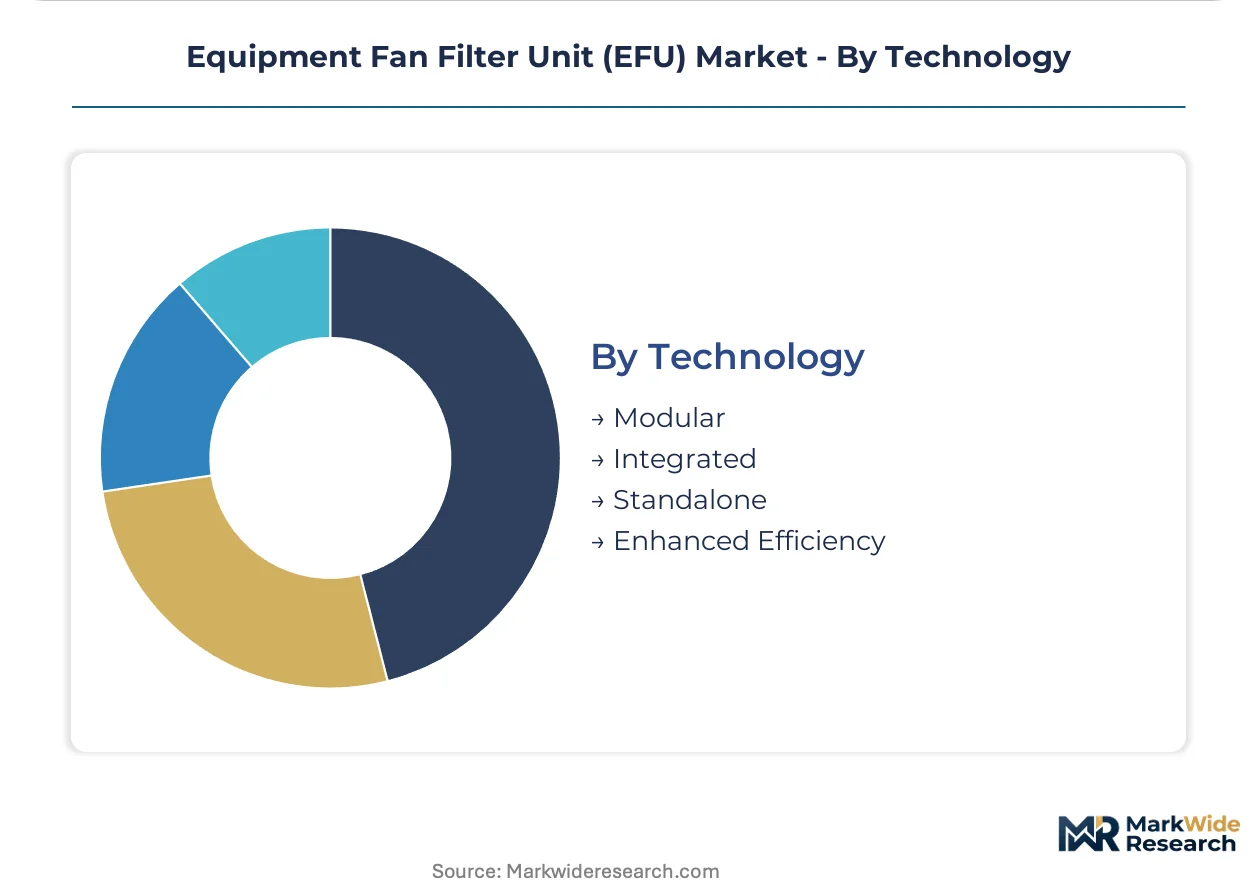
Technology:
Maturity gradients separate established modular architectures from emerging integrated platforms, with retrofit constraints favoring backward-compatible designs.
- Modular:Field-replaceable fan and filter components enable staged upgrades without full system reconstruction. Existing semiconductor fabs in brownfield sites are specifying modular configurations to reconcile variable-frequency drive controls with legacy building management systems.
- Integrated:Bundled fan, filter, monitoring, and control systems reduce commissioning complexity in greenfield deployments. OEMs are bundling variable-frequency drive fans with differential-pressure monitoring to compress energy draw penalties in continuous-operation clean rooms.
- Standalone:Self-contained units with independent power and control for localized deployment flexibility.
- Enhanced Efficiency:Advanced motor designs and aerodynamic optimizations targeting electricity cost reduction in 24/7 operation.
Integrated systems capture the largest revenue share; modular retrofit applications are gaining share fastest among facilities mid-upgrade cycle.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in East Asian electronics manufacturing corridors while consumption spreads across pharmaceutical clusters in Northern Europe and biotechnology hubs in North America. Taiwan and South Korea fabs drive premium EFU specifications for sub-10 nanometer wafer production. The EU F-Gas Regulation and EPA emission standards create divergent compliance timelines across major demand centers.
Taiwan
Semiconductor foundries in Hsinchu and Tainan Science Parks are scaling ISO Class 1-3 clean room capacity for AI chip fabrication. The country's national semiconductor regulator enforces facility emission documentation aligned with international standards. TSMC and United Microelectronics anchor concentrated demand for HEPA-integrated fan filter units with continuous laminar airflow systems.
South Korea
Samsung Electronics and SK Hynix are expanding Pyeongtaek and Yongin fab complexes requiring premium filtration configurations. The MFDS extends pharmaceutical clean room standards to biologics manufacturing, creating secondary demand pools. Seoul Capital Area biotechnology clusters are specifying activated carbon variants for VOC scrubbing in contract development labs.
United States
The EPA enforces National Emission Standards for Hazardous Air Pollutants mandating capture efficiency documentation through stack testing. Massachusetts and North Carolina research corridors exhibit accelerating service unbundling, with labs separating filter media supply from fan assembly maintenance. Boston-Cambridge biotechnology density drives ULPA specification growth for cell culture protection.
Germany
The EU F-Gas Regulation's hydrofluorocarbon phase-down compels pharmaceutical facilities in Baden-Württemberg and Bavaria to specify low-GWP refrigerant compatibility ahead of conventional replacement cycles. Bosch and Siemens Healthineers anchor clean room demand in precision manufacturing corridors. Mannheim and Stuttgart industrial clusters prioritize modular retrofit configurations for brownfield fab upgrades.
Japan
METI guidelines extend ISO 14644-1 implementations to nanomaterial handling facilities, broadening EFU compliance scope beyond traditional electronics. Tokyo Electron and Shin-Etsu Chemical drive demand in Nagoya and Kyoto manufacturing belts. Osaka pharmaceutical clusters are specifying differential-pressure monitoring bundles for continuous particle surveillance in aseptic processing environments.
Equipment Fan Filter Unit (EFU) Market Competitive Landscape
The competitive structure tilts toward diversified filtration conglomerates with cross-sector clean air expertise. Market concentration remains moderate, with no single entity commanding dominant share across all end-use verticals. Three archetypes define positioning: integrated HVAC-filtration specialists, pure-play clean room component suppliers, and diversified industrial conglomerates with air quality divisions. Capacity expansion and strategic technology licensing represent the dominant competitive moves, as players seek refrigerant-transition-ready architectures and multi-stage filtration bundles.
Among filtration-specialist incumbents, Camfil, AAF International, and Nicotra Gebhardt exemplify contrasting geographic anchoring strategies. Camfil leverages its Nordic R&D base for pharmaceutical clean room penetration across Northern Europe. AAF International occupies a position in North American biotechnology clusters through ISO 14644-certified production infrastructure. Nicotra Gebhardt represents the fan-efficiency-focused archetype, sustaining margin pools in modular retrofit applications for existing semiconductor fabs. Fuji Electric and SHINSUNG E&G sit within the East Asian electronics corridor concentration, while Terra Universal anchors North American laboratory demand. Bosch Rexroth exemplifies the industrial conglomerate model, applying automation expertise to clean room air handling integration.
| Leading Market Players |
|---|
| Camfil |
| AAF International |
| Nicotra Gebhardt |
| Fuji Electric |
| SHINSUNG E&G |
| Terra Universal |
| MANN+HUMMEL |
| American Air Filter Company |
| Bosch Rexroth |
| Others |
Pricing and Supply Chain Analysis
The EU F-Gas Regulation gates both qualified supply and premium-tier pricing access by mandating low-global-warming-potential refrigerant compatibility in new EFU installations, compressing procurement timelines and elevating specification costs for semiconductor fabs and pharmaceutical facilities across Northern Europe.
Pricing Analysis
Yield-guarantee pricing anchors the market, with OEMs bundling variable-frequency drive fans and differential-pressure monitoring to command premiums based on documented energy reduction and uptime assurance. Pricing stratifies across ISO 14644 certification tiers, with ULPA-configured units for biotechnology labs carrying material premiums over standard HEPA modules for electronics manufacturing. Cost compression in standard-efficiency tiers is intensifying because buyers in mass-market clean room deployments prioritize capital expenditure minimization over operational expenditure optimization. Contract development labs exhibit the highest price sensitivity due to unbundled procurement models, while Taiwan semiconductor fabs show lowest sensitivity given non-negotiable laminar airflow requirements for sub-10 nanometer production.
Supply Chain Analysis
Fiberglass HEPA and ULPA media supply rests on Japanese and Taiwanese specialty fiber producers, with downstream filter element fabrication concentrating in South Korea and China. Borosilicate glass microfiber, aluminum frame extrusions, and variable-frequency drive controllers constitute critical input dependencies. Single-source vulnerability in 99.97% retention-rated media creates exposure to regional logistics disruptions, particularly for OEMs without captive filtration R&D capabilities. Distribution runs through direct OEM-fab relationships for integrated systems, while modular retrofit components move through regional HVAC distributors serving brownfield upgrade projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
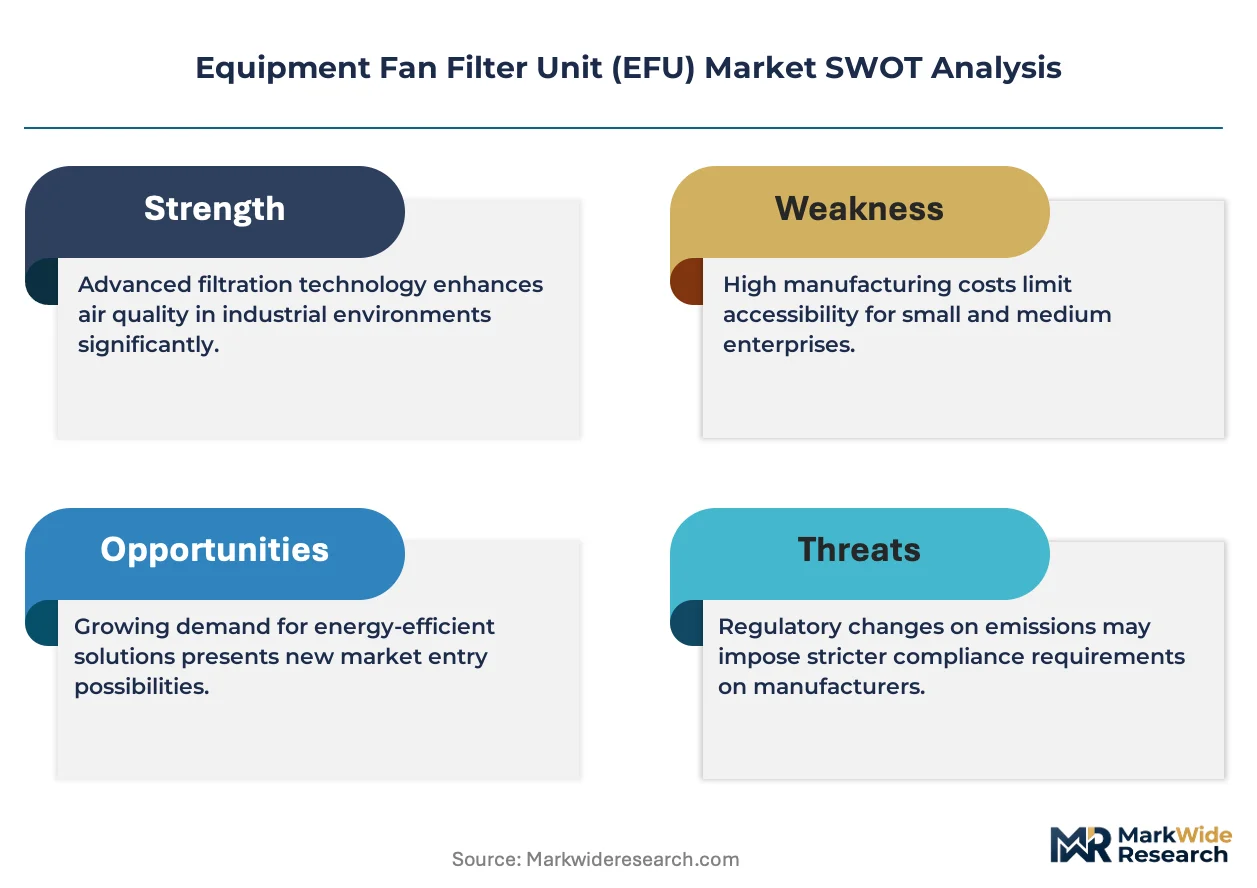
The EFU market functions as a vertical-integration race, with refrigerant-transition-ready architectures and multi-stage filtration bundles representing the decisive downstream levers players are pursuing to capture margin pools in accelerated replacement cycles.
For Market Incumbents: Acquire differential-pressure monitoring technology capabilities to defend against fan-efficiency specialists disintermediating traditional bundled offerings. Secure captive supply of low-GWP-compatible heat exchanger designs ahead of EU F-Gas enforcement timelines. Deepen backward integration into fiberglass media production to mitigate East Asian supply concentration risks. For New Entrants and Emerging Players: The mid-tier pricing gap between premium integrated systems and economy modular units creates entry space for hybrid configurations targeting pharmaceutical clean room expansion in Germany and Switzerland. Biotechnology VOC scrubbing applications in North American contract development labs represent the most penetrable segment given service unbundling trends. Pursue third-party filter certification partnerships to bypass established OEM channel control. For Investors and Strategic Acquirers: Accelerated refrigerant transition announcements by major semiconductor fabs are the leading indicator that low-GWP-compatible EFU architectures will command sustained premium positioning. Target acquisition candidates with ISO 14644-certified production infrastructure and established pharmaceutical sector relationships. Watch for EPA stack testing documentation bottlenecks extending commissioning timelines as a signal of validation-capability scarcity.| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerant Architecture Transition | Low-GWP heat exchanger designs capture premium pricing in EU F-Gas regulated facilities. |
| Multi-Stage Filtration Bundling | Pre-filter configurations extend HEPA element life, reducing maintenance downtime for TSMC and Samsung fabs. |
| Modular Retrofit Positioning | Field-replaceable components address brownfield semiconductor fab upgrades without full reconstruction. |
| Biotechnology VOC Scrubbing Expansion | Activated carbon variants penetrate contract development labs in Massachusetts and North Carolina corridors. |
| Energy Efficiency Integration | Variable-frequency drive bundles compress electricity penalties in continuous-operation clean rooms. |
Research Methodology
Multi-period observation of clean room capacity expansion, refrigerant transition timelines, and filter media procurement patterns anchored the trend analysis, supplemented by interviews with fab facility managers, HVAC procurement leads, filtration R&D directors, and aftermarket service heads. Secondary validation drew from EPA National Emission Standards documentation, EU F-Gas Regulation implementation reports, ISO 14644 certification databases, and semiconductor industry capex disclosures. Bottom-up unit economics triangulated against top-down sector spend estimates to constrain forecast variance.
Input-output matrices mapped EFU deployment volumes against wafer fabrication capacity, pharmaceutical manufacturing output, and biotechnology research facility expansion across the projection horizon. Segmentation dimensions included filtration grade, deployment architecture, end-use contamination sensitivity, and regional regulatory framework. CAGRs were derived from installed base turnover rates and greenfield build-out schedules, with energy cost trajectories and refrigerant phase-down timelines incorporated as scenario-weighted inputs.
Underlying measurement precision varies by segment; integrated systems with bundled monitoring carry tighter precision than standalone modular configurations due to documented procurement patterns. Forecasts reflect assumptions regarding EU F-Gas enforcement consistency, East Asian logistics stability, and semiconductor capital expenditure continuity. EPA documentation bottlenecks, filter media supply disruptions, and refrigerant technology transition delays warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
HVAC Air Duct Market
HVAC Equipment
Global VRF System Market
HVAC Equipment
Europe Heat Exchanger Market
HVAC Equipment
Europe Residential Fan Coil Convectors Market
HVAC Equipment
Positive Displacement Blowers Market
HVAC Equipment
Desert Air Cooler Market
HVAC Equipment
Field-Erected Cooling Tower Market
HVAC Equipment
Linear Slot Diffuser Market
HVAC Equipment
North America Industrial Air Chiller Market
HVAC Equipment
US Commercial Water Heater Market
HVAC Equipment
Commercial HVAC Market
HVAC Equipment
Brazed Plate Heat Exchangers Market
HVAC Equipment
Europe Air to Water Heat Pump Market
HVAC Equipment
Europe HVAC Market
HVAC Equipment
Foamer Pump Market
HVAC Equipment
South America Screw Compressor Market