
 Heavy Duty Heat Pump Market | 2026-2036
Heavy Duty Heat Pump Market Size, Share, and Industry Trends Forecast 2026-2036
Heavy Duty Heat Pump Market Outlook
The capital-intensity divergence between integrated compressor manufacturers and assembly-focused system integrators is collapsing as OEMs internalize heat exchanger production and refrigerant circuit design. Siemens Energy leverages its turbomachinery heritage to dominate centrifugal technology for district heating retrofits. Trane Technologies sustains broad geographic coverage through modular platform architectures. MAN Energy Solutions anchors its position in marine and industrial process heat with screw compressor expertise.
Heavy duty heat pumps are thermodynamic systems that transfer thermal energy from low-temperature sources to high-temperature sinks using vapor-compression cycles, typically achieving output temperatures above 80°C through multi-stage compression and optimized refrigerant selection. These units serve industrial decarbonization by displacing fossil fuel boilers in process heat applications ranging from food pasteurization to chemical distillation. Air source configurations lead volume due to lower installation complexity, though water source designs capture premium margin pools where river, lake, or wastewater access exists. Scroll technology occupies the sub-500 kW commercial segment, while centrifugal compressors command the multi-megawatt industrial and district heating space where efficiency thresholds justify capital outlay.
The EU F-Gas Regulation and Ecodesign Directive are tightening refrigerant restrictions and minimum performance standards, forcing OEMs to redesign around CO2, ammonia, or hydrocarbon working fluids. The EPA in the United States is phasing down HFC production under the AIM Act, creating parallel compliance burdens for suppliers serving North American industrial facilities. Stakeholders must monitor refrigerant supply chain constraints and certification timelines as these rules cascade through procurement specifications.
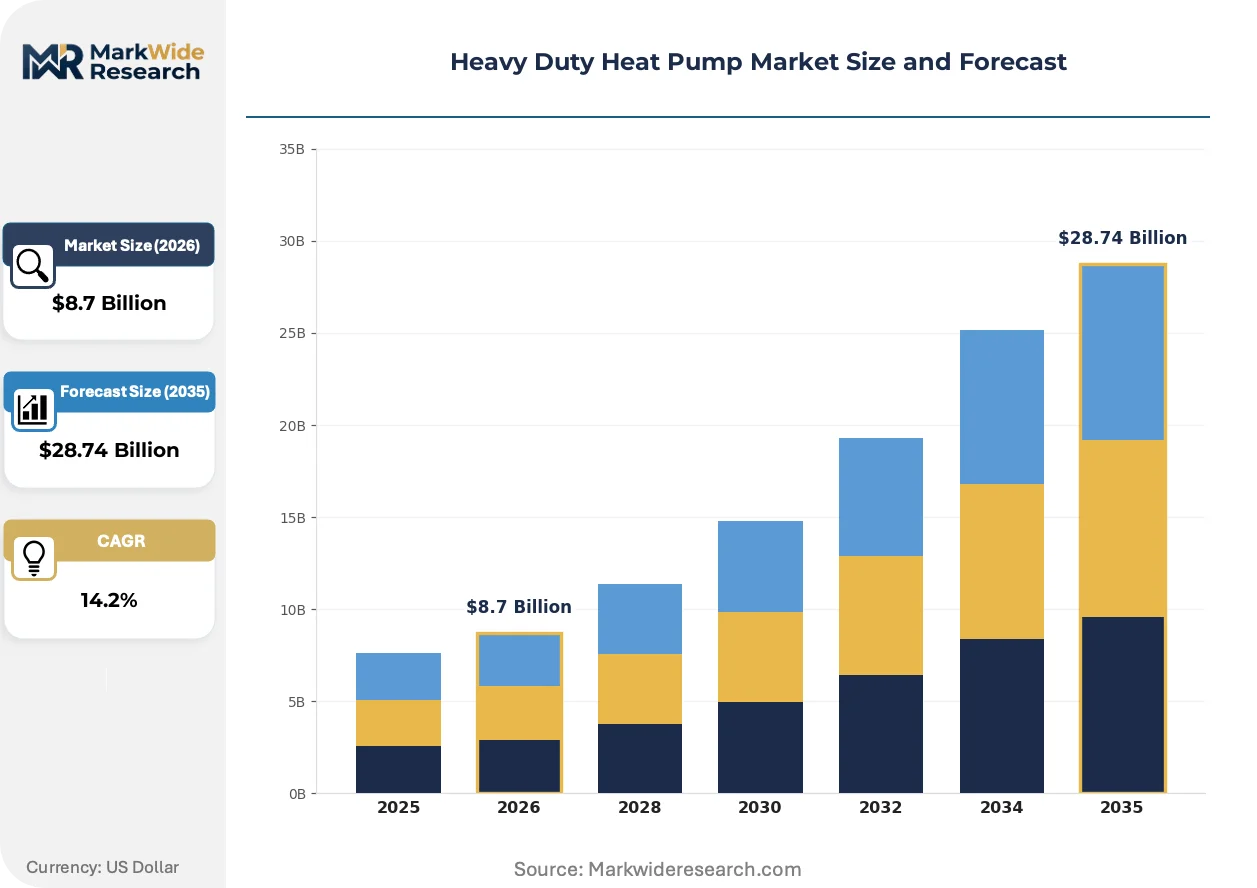
Market Dynamics
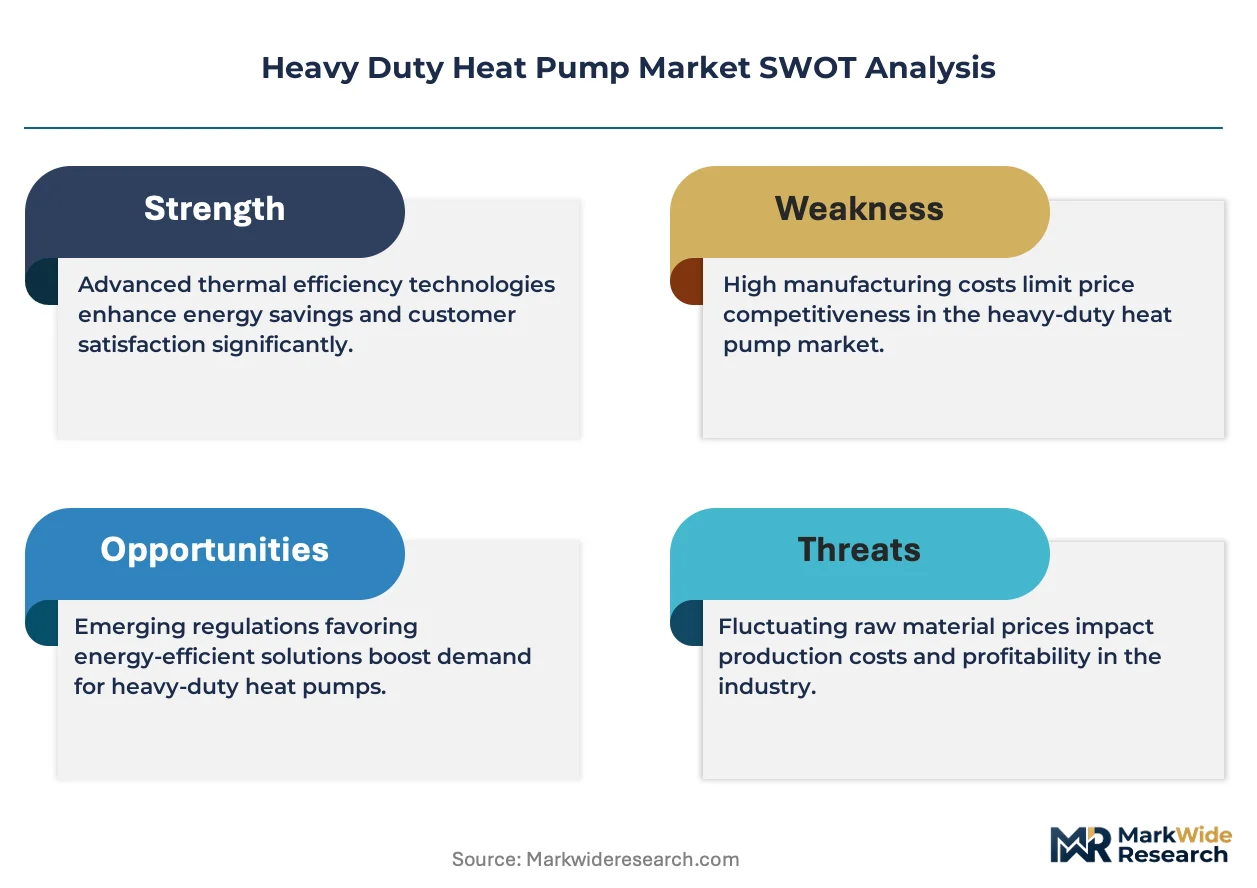
The EU F-Gas Regulation is compressing refrigerant availability timelines and forcing OEMs to requalify entire product lines around CO2 and ammonia architectures before 2030 phase-down deadlines.
Growth Catalysts
- Industrial Decarbonization Mandates:Germany's chemical sector faces binding emissions reduction targets under the EU Green Deal, retrofitting steam boilers with megawatt-scale heat pumps for process temperatures above 100°C.
- F-Gas Phase-Down Schedules:The regulation accelerates R&D investment in transcritical CO2 systems and ammonia circuits, creating first-mover advantages for OEMs with certified natural refrigerant platforms.
- District Heating Retrofits:Copenhagen, Stockholm, and Helsinki operators are procuring centrifugal units to replace coal and biomass plants, concentrating demand in Northern European urban clusters.
Market Restraints
- Copper and Rare Earth Input Volatility:Permanent magnet supply from Chinese processors faces export licensing uncertainty, compressing margins on high-efficiency compressor motors.
- Refrigerant Certification Bottlenecks:EU notified bodies lack capacity to process ammonia safety certifications at the pace required by 2027 equipment deployment schedules.
- Gas Boiler Substitution Economics:Pipeline natural gas in the Netherlands and Belgium retains cost advantages below 80°C applications, limiting heat pump penetration in moderate-temperature food processing.
Strategic Opportunities
- Marine Propulsion Waste Heat Recovery:Ship operators under IMO decarbonization rules are piloting seawater-source heat pumps to capture engine exhaust thermal energy for onboard heating.
- Data Center Cooling-to-Heating Reversal:Hyperscale facilities in Ireland and Denmark are installing heat pumps to export server waste heat into municipal district networks, creating new revenue streams.
- France's Renovergy Subsidy Expansion:The program now covers industrial heat pump capex above 1 MW, opening public funding for chemical and pharmaceutical retrofits in the Rhône-Alpes cluster.
Industry Challenges
- Refrigeration-Ammonia Safety Specialist Shortage:Qualified technicians for high-pressure NH3 systems are concentrated in Scandinavian markets, creating deployment bottlenecks in Southern European installations.
- Legacy Control System Integration:Chemical plants running 1990s-era SCADA architectures require costly middleware development to interface with modern heat pump variable-speed drives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heavy Duty Heat Pump Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Air Source, Water Source, Ground Source, Hybrid Technology: Scroll, Screw, Centrifugal, Reciprocating End User: Industrial Facilities, Commercial Buildings, Agricultural Applications, Residential Spaces Installation: On-site, Prefabricated, Modular, Centralized |
| Companies Covered | Atlas Copco AB, GEA Group Aktiengesellschaft, Johnson Controls, MAN Energy Solutions, Siemens Energy, Trane Technologies, OCHSNER, Oilon Group Oy, Piller Blowers & Compressors GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heavy Duty Heat Pump Market Strategic Shifts
Refrigerant chemistry and compressor architecture are converging to unlock temperature lifts previously unreachable with single-stage vapor compression, opening process heat applications above 120°C.
Transcritical CO2 compressor technology is miniaturizing. These systems achieve 90°C output through multi-stage intercooling and gas cooler optimization. Food pasteurization plants in Bavaria and Baden-Württemberg are piloting 500 kW skid-mounted units to replace gas-fired boilers. The footprint reduction is enabling rooftop installations where machinery hall space constraints previously blocked adoption.
The EPA's phasedown of HFC production under the AIM Act is compressing availability of R-134a and R-410A for servicing existing industrial equipment. North American chemical processors face parallel compliance burdens to their European counterparts, with some facilities accelerating full system replacement rather than attempting refrigerant reclamation. The uncertainty is pushing procurement committees toward ammonia and CO2 platforms despite higher upfront engineering costs.
Energy-as-a-service contracting is displacing traditional equipment purchase models. District heating operators in Denmark and the Netherlands now procure guaranteed heat output measured in MWh rather than compressor capacity in kW. Siemens Energy and MAN Energy Solutions have restructured sales organizations around performance guarantees, absorbing operational risk in exchange for 15-20 year service contracts. This transfer of balance-sheet exposure is most advanced in municipal utilities with constrained capex flexibility.
Heavy Duty Heat Pump Market Segmentation
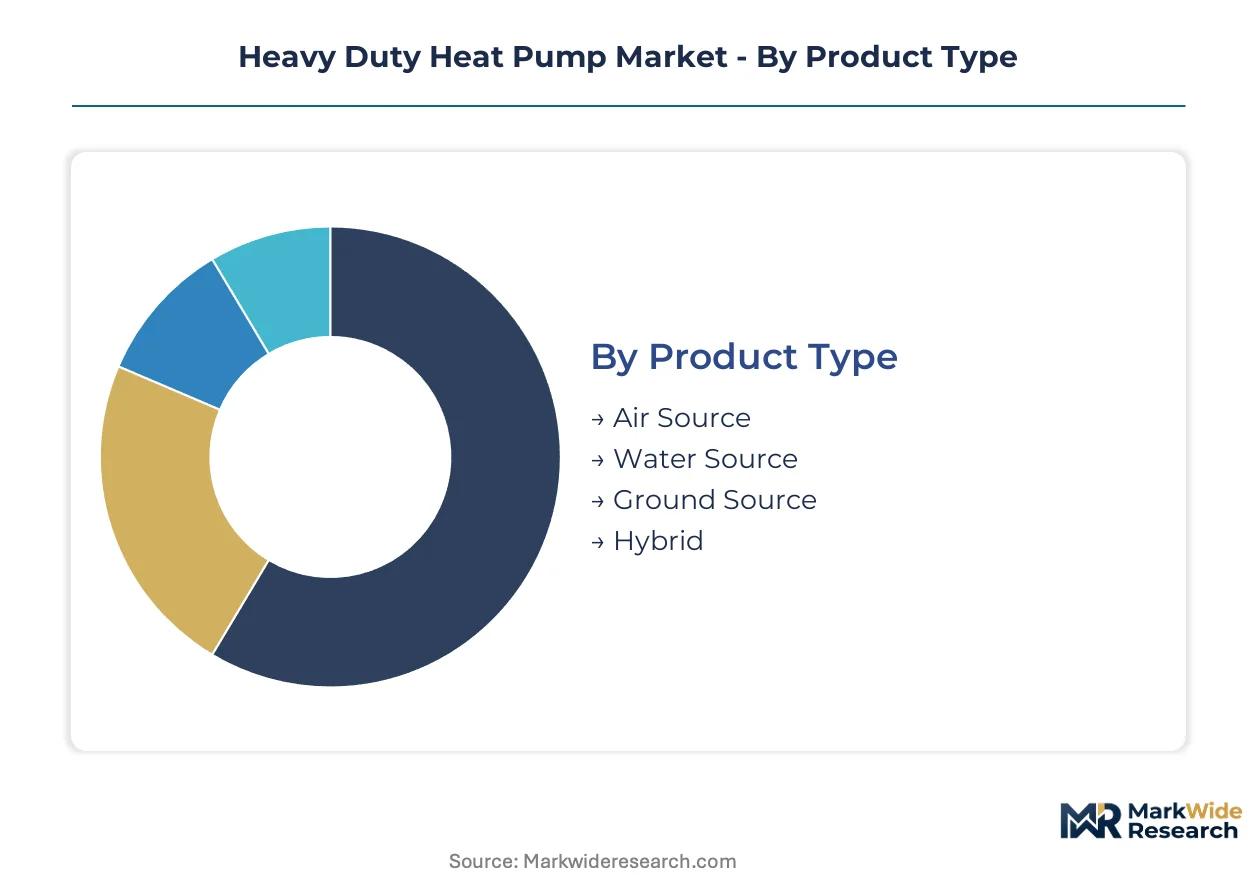
Segmentation in heavy duty heat pumps reveals distinct technology-to-application pairings where refrigerant chemistry, compressor architecture, and installation constraints intersect. Procurement committees weight capex flexibility against thermal output requirements differently across district heating, industrial process heat, and commercial building markets.
Product Type:
Substitution pressure from gas boilers and biomass systems varies sharply by source configuration, with air source designs facing the steepest efficiency skepticism in high-temperature applications.
- Air Source:These systems extract thermal energy from ambient air through large-format evaporator coils and variable-speed fans, achieving output temperatures up to 85°C in single-stage configurations. Demand concentrates in Germany's chemical corridor where retrofit timelines compress installation windows and outdoor space abounds. The F-Gas Regulation accelerates refrigerant transitions toward CO2 transcritical cycles in this segment.
- Water Source:River, lake, and wastewater-fed installations deliver coefficient of performance advantages of 40-60% over air source equivalents through stable inlet temperatures. Copenhagen's district heating operator anchors procurement volumes for 5-20 MW centrifugal units replacing coal infrastructure. Permitting complexity for surface water abstraction limits deployment velocity.
- Ground Source:Borehole or horizontal loop configurations exploit geothermal stability for baseload industrial applications requiring 24/7 thermal output. Baden-Württemberg food processors pilot closed-loop systems for pasteurization lines.
- Hybrid:Dual-source architectures combine air and water inlets with intelligent switching logic to optimize seasonal performance factors. Dutch greenhouse operators deploy these for horticultural heating with fluctuating ambient conditions.
Air source anchors the volume base while water source gains share at the steepest rate.
Technology:
Cost tier stratification separates commodity scroll platforms from engineered centrifugal systems where efficiency premiums justify 3-5x capital multiples.
- Centrifugal:Multi-stage turbocompressors achieve pressure ratios exceeding 8:1 for district heating temperatures above 100°C, with magnetic bearing systems eliminating lubrication maintenance. Siemens Energy dominates retrofit procurement across Stockholm, Helsinki, and Copenhagen municipal networks. The technology commands premium positioning where thermal output exceeds 5 MW.
- Screw:Twin-rotor positive displacement compressors handle oil-free ammonia circuits for industrial process heat in marine and chemical applications. MAN Energy Solutions anchors position in IMO-compliant waste heat recovery systems for container shipping.
- Scroll:Orbiting spiral plate configurations occupy sub-500 kW commercial and light industrial niches with standardized refrigerant charges. Bavarian food processors specify these for rooftop installations with space constraints.
- Reciprocating:Piston-driven compressors persist in legacy ammonia systems and high-pressure CO2 applications requiring exact pressure staging. Maintenance intensity limits new deployment.
Scroll technology retains the broadest installed base while centrifugal climbs the fastest on megawatt-scale district heating momentum.
End User:
Customer type determines specification rigor, with industrial facilities demanding certified performance guarantees unavailable in commercial procurement.
- Industrial Facilities:Chemical distillation, food pasteurization, and pharmaceutical drying require precise temperature control above 100°C with redundancy protocols. Germany's Rhine-Ruhr chemical cluster drives specification for ammonia-based systems with safety engineering.
- Commercial Buildings:Hotels, hospitals, and office complexes prioritize acoustic attenuation and footprint minimization over peak thermal efficiency. Danish district heating exports serve this segment through energy-as-a-service contracting.
- Agricultural Applications:Greenhouse heating and grain drying demand seasonal flexibility with rapid ramp rates. Netherlands horticultural cooperatives procure hybrid source systems.
- Residential Spaces:Multi-family district connections and large single-family estates represent marginal volume in heavy duty classifications, typically served by downsized commercial platforms.
Industrial facilities anchor the revenue base while commercial buildings expand most quickly on energy-as-a-service model adoption.
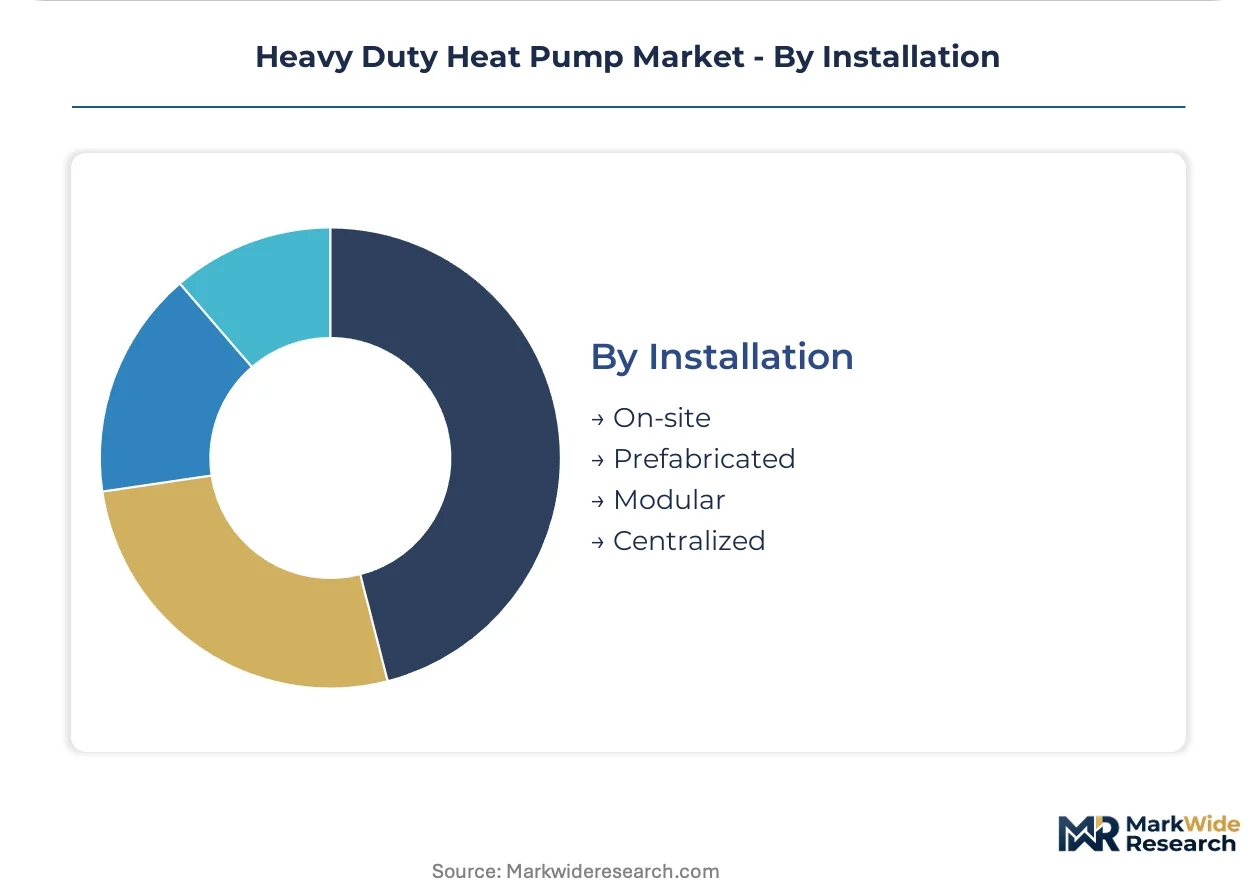
Installation:
Supply concentration in prefabrication capabilities is compressing field installation timelines and reshaping contractor relationships across Northern Europe.
- Modular:Skid-mounted compressor, heat exchanger, and control packages enable parallel manufacturing with 60-70% reduction in site labor. Trane Technologies' platform architecture dominates specification for repeatable commercial deployments.
- Prefabricated:Factory-integrated systems with pre-charged refrigerant circuits and tested safety interlocks accelerate commissioning in ammonia applications. Scandinavian contractors prefer these for technician scarcity mitigation.
- On-site:Traditional stick-built installations persist for non-standard footprints and heritage building constraints. Cost and schedule overruns disadvantage this approach.
- Centralized:Single large-format plant serving multiple buildings or district network nodes requires custom engineering and extended permitting. Copenhagen's Amager Bakker retrofit exemplifies this configuration.
Modular platforms anchor new procurement volumes while prefabricated systems gain share fastest on refrigerant safety certification bottlenecks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in the Netherlands and Belgium exhibit acute price sensitivity where pipeline natural gas undercuts heat pump economics below 80°C applications, while German chemical processors absorb premium capex to meet binding decarbonization mandates. This demand-elasticity divergence concentrates procurement momentum in high-regulation jurisdictions.
Germany
The Rhine-Ruhr chemical cluster drives megawatt-scale ammonia system procurement for distillation and drying processes above 100°C. The EU F-Gas Regulation accelerates retrofit timelines for BASF and Evonik facilities. Bavarian food processors in the Munich-Stuttgart corridor pilot transcritical CO2 units for pasteurization lines.
Denmark
Copenhagen's district heating operator procures 5-20 MW centrifugal replacements for coal infrastructure at Amager Bakker. The national energy-as-a-service contracting model transfers balance-sheet risk to OEMs through 15-20 year performance guarantees. Aarhus and Odense municipal utilities replicate this procurement structure.
Sweden
Stockholm Exergi anchors Nordic demand for magnetic-bearing centrifugal systems in fourth-generation district heating networks. The EU Ecodesign Directive tightens minimum performance standards for new installations. Gothenburg's river-source configurations exploit stable inlet temperatures for 40-60% efficiency premiums over air-source alternatives.
Netherlands
Greenhouse operators in Westland deploy hybrid-source architectures for horticultural heating with fluctuating ambient conditions. Pipeline natural gas retains cost advantages in moderate-temperature food processing, compressing heat pump penetration. Rotterdam's port industrial cluster pilots marine waste heat recovery under IMO decarbonization pressure.
United States
The EPA's AIM Act phases down HFC production, forcing chemical processors to choose between refrigerant reclamation and full system replacement. Gulf Coast petrochemical facilities face parallel compliance burdens to European counterparts. Data centers in Northern Virginia explore cooling-to-heating reversal for district network export.
Heavy Duty Heat Pump Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, with turbomachinery specialists commanding premium positioning in multi-megawatt district heating while modular platform builders capture repeatable commercial volumes. The market exhibits tiered concentration where centrifugal compressor expertise separates engineered-system vendors from assembly-focused integrators. Two strategic archetypes dominate: integrated OEMs with in-house heat exchanger production, and performance-contracting specialists absorbing operational risk through energy-as-a-service structures. Competitive moves center on refrigerant circuit requalification for natural working fluids and prefabrication capabilities compressing field installation timelines.
Within the integrated turbomachinery tier, Siemens Energy and MAN Energy Solutions exemplify divergent specialization vectors—Siemens Energy anchoring district heating retrofits through magnetic-bearing centrifugal platforms, MAN Energy Solutions occupying marine and industrial process heat with screw compressor architectures. Trane Technologies represents the modular platform archetype, sustaining broad geographic coverage through standardized skid-mounted configurations. These three entities illustrate how heritage technology bases translate into distinct market positions without overlapping core application domains.
| Leading Market Players |
|---|
| Atlas Copco AB |
| GEA Group Aktiengesellschaft |
| Johnson Controls |
| MAN Energy Solutions |
| Siemens Energy |
| Trane Technologies |
| OCHSNER |
| Oilon Group Oy |
| Piller Blowers & Compressors GmbH |
| Others |
Value Chain & Pricing Dynamics
Long-term performance contracting locks in supply access and price visibility for district heating operators across Denmark and Germany, binding OEMs to 15-20 year service obligations while insulating municipal buyers from copper and rare earth volatility. This structure transfers balance-sheet exposure to manufacturers and compresses spot-market participation for critical compressor components.
Pricing Analysis
After-sales service revenue from magnetic bearing maintenance and refrigerant circuit requalification drives lifetime value for centrifugal system OEMs. Three-tier pricing structure across premium, standard, and economy levels segments buyers by thermal output scale and certification requirements. Cost compression in scroll compressor tiers is intensifying because Chinese motor suppliers are absorbing margin to secure European OEM relationships. District heating operators exhibit lowest price sensitivity due to decarbonization mandate compliance deadlines, while Dutch greenhouse cooperatives negotiate aggressively on hybrid-source configurations.
Supply Chain Analysis
Strategic stockpiling of permanent magnet rare earths dominates inventory strategy among German and Danish OEMs facing Chinese export licensing uncertainty. Component sourcing concentrates in China for rare earth processing, Germany for precision heat exchanger fabrication, and Italy for electronic control modules. Copper tube and aluminum finstock dependencies expose manufacturers to commodity price swings. Single-source vulnerability from Chinese magnet processors threatens production continuity. Distribution runs through authorized service networks rather than open distribution channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Procurement concentration among Northern European district heating operators is shifting buyer power toward municipal utilities with 15-20 year contracting authority, fragmenting price-setting leverage across legacy industrial equipment vendors.
For Market Incumbents: Compound centrifugal platform dominance through captive heat exchanger production and ammonia safety certification expansion. Defend against modular scroll entrants by embedding magnetic bearing expertise into district heating retrofits. Prioritize prefabrication capabilities to compress field installation timelines where Scandinavian technician scarcity creates bottlenecks. For New Entrants and Emerging Players: Differentiate on transcritical CO2 miniaturization for rooftop-constrained food processors in Bavaria and Baden-Württemberg. Target France's Renovergy-subsidized chemical corridor for first commercial deployments. Pursue energy-as-a-service partnerships with constrained-capex municipal utilities as the primary go-to-market channel. For Investors and Strategic Acquirers: Capital is best deployed toward integrated turbomachinery specialists with in-house refrigerant circuit design and established natural refrigerant certifications. Long-term viability hinges on OEMs capturing district heating retrofit momentum before 2030 F-Gas deadlines crystallize market positions. Watch ammonia safety certification bottlenecks at EU notified bodies as the inflection signal for deployment velocity constraints.| Strategic Initiative | Industry Significance |
|---|---|
| Natural Refrigerant Platform Certification | EU F-Gas Regulation deadlines force CO2 and ammonia circuit requalification before 2030 phase-down. |
| Prefabricated System Manufacturing | Factory-integrated compressor packages reduce Scandinavian field labor dependence amid technician shortages. |
| Magnetic Bearing Technology Expansion | Elimination of lubrication maintenance commands premium positioning in Stockholm and Copenhagen district networks. |
| Energy-as-a-Service Contracting | Danish municipal utilities transfer operational risk to OEMs through guaranteed heat output procurement. |
| Waste Heat Recovery Integration | IMO decarbonization rules drive marine engine exhaust capture pilots for container shipping operators. |
Study Parameters
A spread of perspectives from district heating procurement officers, industrial plant engineers, OEM product development directors, and refrigerant safety certification specialists converged on the working assumptions underlying this analysis. Primary field engagement combined with secondary validation from EU F-Gas regulatory filings, Ecodesign Directive implementation reports, EPA AIM Act phase-down schedules, and customs data on compressor component trade flows. Bottom-up unit deployment tracking and top-down energy transition investment sizing were triangulated to anchor volume estimates.
Segmentation dimensions modeled span source configuration, compressor technology architecture, end-use application intensity, and installation format preference across the analysis window. CAGRs were derived from deployment trajectory analysis against decarbonization mandate timelines. Forecast inputs incorporated district heating retrofit pipeline visibility from Copenhagen, Stockholm, and Helsinki operators alongside industrial facility energy audits from Germany's Rhine-Ruhr chemical cluster.
Material uncertainties — refrigerant certification processing delays, rare earth export licensing disruptions, and natural gas price volatility affecting substitution economics — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory deadline adherence and OEM capacity expansion execution. Revision becomes warranted when ammonia safety certification backlogs at EU notified bodies exceed 18-month processing thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
North America Industrial Air Chiller Market
HVAC Equipment
Strip Warmer Market
HVAC Equipment
Refrigerant Compressors Market
HVAC Equipment
North America HVAC Equipment Market
HVAC Equipment
Heating and Cooling Market
HVAC Equipment
HVAC Louvers Market
HVAC Equipment
Global Industrial Fans and Blowers Market
HVAC Equipment
Compressor Controllers Market
HVAC Equipment
North America Heat Exchanger Market
HVAC Equipment
United States Heat Exchanger Market
HVAC Equipment
Global HVAC Filter Market
HVAC Equipment
Electric Underfloor Heating Market
HVAC Equipment
Global Air Duct Market
HVAC Equipment
Asia-Pacific Industrial Heat Pump Market
HVAC Equipment
Hot Water Circulator Pump Market
HVAC Equipment
Modular Refrigeration Unit Market