
 Reciprocating Chiller Market | 2026-2036
Reciprocating Chiller Market Size, Share, and Industry Trends Forecast 2026-2036
Reciprocating Chiller Market Analytics
China is rewriting reciprocating chiller supply dynamics through expanded compressor manufacturing corridors in Jiangsu and Zhejiang provinces. Carrier Global Corporation leverages backward integration into compressor assembly to sustain margin control across Asian project deployments. Bitzer Kühlmaschinenbau GmbH anchors European demand with specialized semi-hermetic reciprocating units engineered for industrial process loads. Daikin Industries, Ltd. competes through variable refrigerant flow integration with reciprocating compressor cores.
A reciprocating chiller employs piston-driven compression cycles to transfer thermal energy between refrigerant and process fluids, typically achieving coefficient of performance ratings between 2.8 and 4.2 depending on condenser configuration and part-load optimization. These systems serve precision cooling requirements in pharmaceutical synthesis, food processing, and district chilled water networks where temperature stability carries operational priority. Water-cooled configurations dominate installed base value due to higher efficiency thresholds in large-tonnage applications, while modular product architectures represent the fastest-expanding segment as facility managers prioritize scalable redundancy over monolithic central plants. Electric drive technology retains overwhelming share though variable speed drive penetration accelerates in markets with aggressive utility demand-response programs.
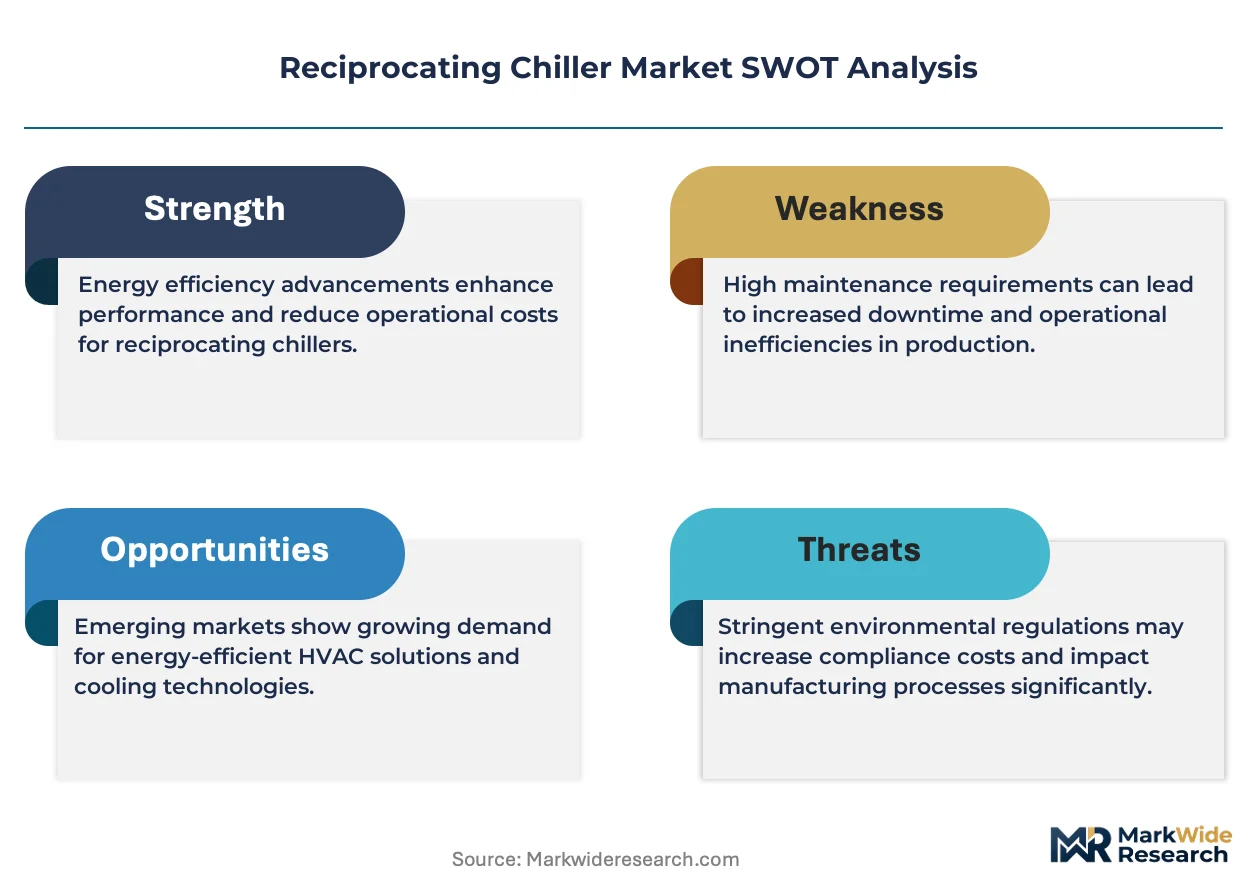
The EPA SNAP program and EU F-Gas Regulation jointly constrain refrigerant selection, compelling OEMs to validate alternative working fluids across reciprocating compressor architectures. China's GB standards and NMPA pharmaceutical facility codes shape product certification requirements for domestic and export-bound equipment. Stakeholders must monitor refrigerant transition timelines and compressor redesign cycles to align procurement decisions with evolving compliance thresholds.
Market Dynamics
The EU F-Gas Regulation and EPA SNAP program are jointly compressing refrigerant choice sets, forcing OEMs to revalidate compressor architectures around lower-GWP working fluids while buyers delay procurement cycles.
Growth Catalysts
- Pharmaceutical cleanroom expansion:Germany's synthetic drug manufacturing corridors are scaling precision-cooled reciprocating capacity to meet sterility-grade temperature stability requirements.
- Refrigerant transition mandates:The EU F-Gas Regulation is accelerating equipment replacement timelines as facility operators face phasedown quotas on high-GWP legacy fluids.
- Industrial process intensification:China's eastern manufacturing belt is adding chiller capacity to support chemical synthesis and food processing lines requiring sub-ambient cooling.
Market Restraints
- Copper and rare earth input volatility:Compressor motor windings and heat exchanger tubing face raw material price swings that compress OEM margin structures.
- Semi-hermetic compressor supply concentration:European specialist manufacturers control critical component availability for industrial-tonnage units.
- Screw chiller substitution:Rotary compressor technology captures large-tonnage applications where part-load efficiency thresholds favor continuous compression cycles.
Strategic Opportunities
- Modular plant architecture:Scalable chiller arrays allow pharmaceutical and data center operators to stage capacity additions without central plant redundancy.
- Variable speed drive convergence:Integration of VFD controls with reciprocating compressor cores opens demand-response revenue streams in utility territories with aggressive load-shaping programs.
- Refrigerant reclamation infrastructure:The EU F-Gas Regulation's service ban deadlines create aftermarket service and fluid recovery business models.
Industry Challenges
- Alternative refrigerant thermodynamic validation:OEMs must recalibrate compressor displacement ratios and lubricant compatibility for each new working fluid chemistry.
- Legacy control system integration:Building management system protocols from prior chiller generations resist seamless communication with digital-native monitoring platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Reciprocating Chiller Market |
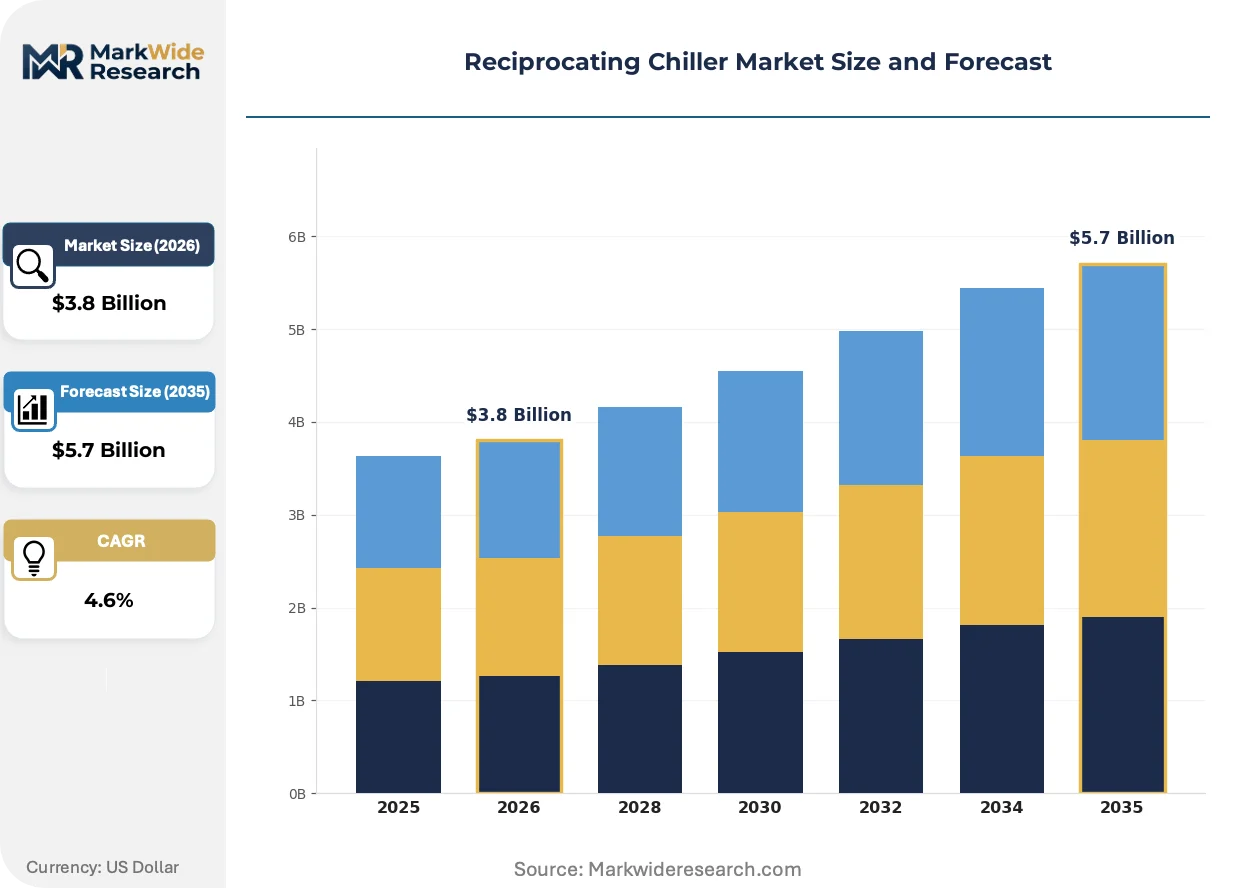
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Air-Cooled, Water-Cooled, Modular, Portable Application: Commercial Buildings, Industrial Processing, HVAC Systems, Laboratories End User: Manufacturing, Hospitality, Healthcare, Educational Institutions Technology: Electric, Variable Speed Drive, Reciprocating, Scroll |
| Companies Covered | Aermec S.p.A., Bitzer Kühlmaschinenbau GmbH, Blue Star Limited, Carrier Global Corporation, Daikin Industries, Ltd., Danfoss A/S, Dunham-Bush, Emerson Electric Co., Thermax Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Reciprocating Chiller Market Evolving Landscape
Digital compressor controls and refrigerant chemistry shifts are restructuring how buyers evaluate lifecycle cost against first cost. Equipment specification criteria now weight service accessibility and fluid transition pathways alongside nominal efficiency ratings.
Magnetic bearing centrifugal technology is rendering obsolete conventional reciprocating units in large-tonnage district cooling applications. District energy operators in Singapore and the UAE are specifying oil-free compression for maintenance interval extension. The technology is compressing addressable market scope for piston-driven systems above 500-ton capacity thresholds.
The EPA SNAP program's listing withdrawals are constraining R-134a and R-410A availability for new equipment. Industrial facility operators face accelerated obsolescence timelines for installed reciprocating chillers using delisted refrigerants. The pharmaceutical sector in the United States is responding with earlier-than-planned replacement cycles to preempt service fluid access constraints.
Buyers are unbundling aftermarket service contracts from initial equipment procurement. Facility managers in China's Jiangsu province are contracting independent service providers for compressor overhauls rather than accepting OEM captive service terms. This pattern compresses OEM service revenue attachment rates while expanding third-party parts markets.
Reciprocating Chiller Market Segmentation
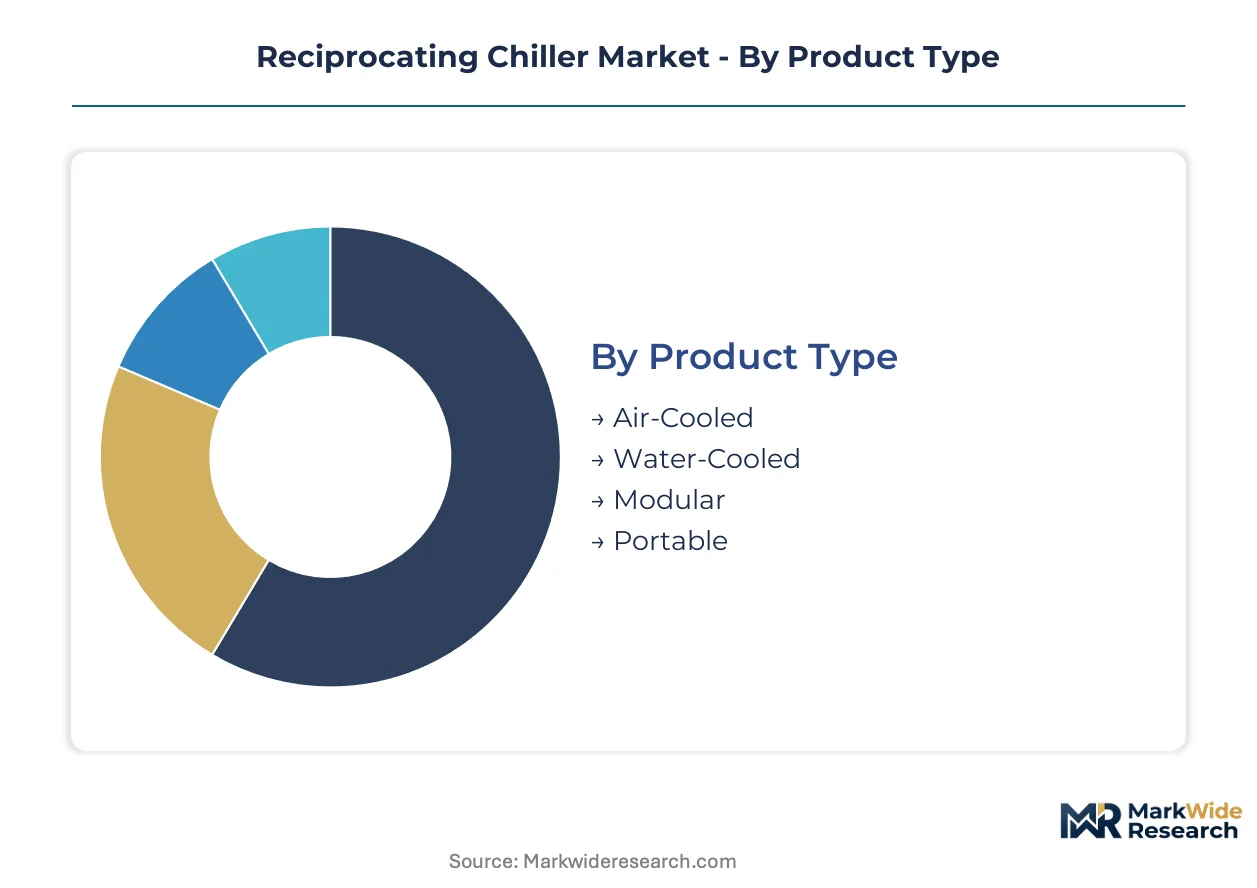
Reciprocating chiller procurement decisions hinge on thermal load profile, refrigerant compatibility, and facility redundancy requirements. Distinct specification criteria govern each segment, from part-load optimization in modular arrays to continuous-duty ratings in industrial process cooling.
Product Type:
Cost tier differentiation separates entry-level portable units from capital-intensive water-cooled installations serving permanent thermal infrastructure.
- Air-Cooled:Condenser coils reject heat directly to ambient air, eliminating cooling tower infrastructure and reducing first cost for facilities below 200-ton loads. Demand concentrates in Germany's pharmaceutical corridor where the EU F-Gas Regulation accelerates replacement of legacy R-407C systems with lower-GWP alternatives.
- Water-Cooled:Shell-and-tube condensers achieve coefficient of performance ratings exceeding 4.0 through evaporative cooling tower integration. China's Jiangsu province manufacturing belt specifies these configurations for chemical synthesis lines requiring sub-ambient process temperatures.
- Modular:Scalable arrays of 20-80 ton modules enable staged capacity deployment with N+1 redundancy.
- Portable:Trailer-mounted units serve temporary cooling for construction sites and emergency thermal backup.
Water-cooled configurations command the established base. The steepest expansion runs through modular architectures as facility managers prioritize scalable redundancy.
Application:
Application scope spans comfort cooling through precision thermal control, with specification rigor escalating alongside temperature stability requirements.
- Commercial Buildings:Office towers and retail complexes specify air-cooled reciprocating systems for 100-400 ton base loads. Germany's F-Gas Regulation phasedown quotas compel early replacement of R-134a equipment in Frankfurt and Munich commercial portfolios.
- Industrial Processing:Chemical synthesis, food pasteurization, and plastics extrusion demand continuous-duty compressors with ±0.5°C temperature stability. China's eastern manufacturing corridor adds capacity to support polymer processing lines.
- HVAC Systems:District chilled water networks and central plant retrofits.
- Laboratories:Research facilities requiring precision environmental control.
Industrial processing anchors revenue concentration. Commercial buildings deliver volume scale through replacement cycles.
End User:
Customer type shapes procurement authority, with centralized engineering teams in manufacturing contrasting against distributed decision-making in hospitality.
- Manufacturing:Automotive stamping plants and semiconductor fabs specify industrial-tonnage water-cooled systems with 15-20 year depreciation horizons. China's NMPA pharmaceutical facility codes mandate redundant cooling for active ingredient synthesis suites.
- Hospitality:Hotels and resorts prioritize acoustic attenuation and part-load efficiency for variable occupancy patterns.
- Healthcare:Hospital central plants require 24/7 reliability with emergency generator compatibility.
- Educational Institutions:University campuses balance first cost constraints against lifecycle efficiency in state-funded capital programs.
Manufacturing dominates capital deployment. Healthcare exhibits the most demanding specification criteria.
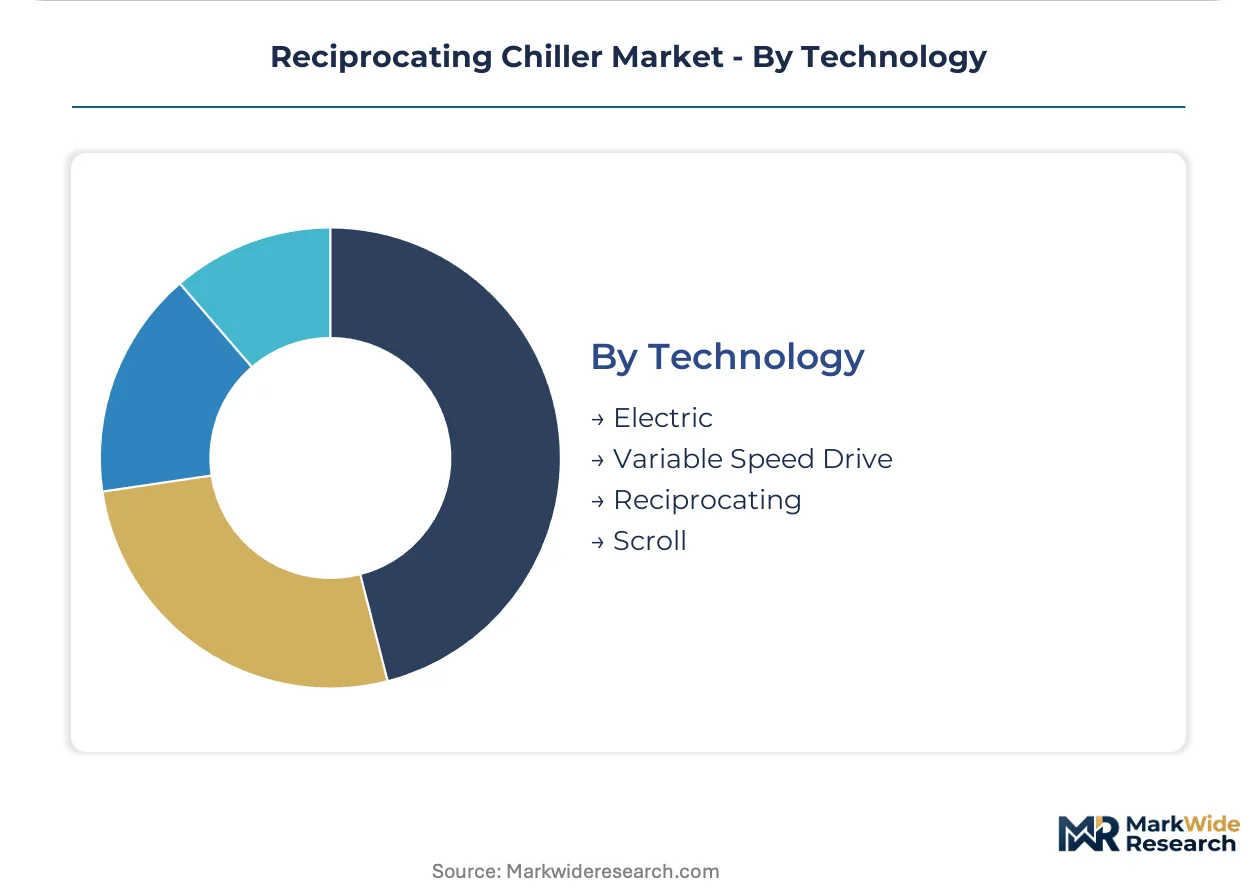
Technology:
Drive architecture and compression mechanism define efficiency thresholds and maintenance intervals across the installed base.
- Electric:Fixed-speed induction motors retain majority share through proven reliability and service infrastructure density. Germany's utility demand-response programs accelerate VFD retrofits on existing electric-drive installations.
- Variable Speed Drive:Inverter-controlled compressors modulate capacity from 25-100% without slide valve or cylinder unloading losses. China's Jiangsu province industrial parks specify VFD-equipped units to qualify for peak-shaving tariff incentives.
- Reciprocating:Piston-driven compression cycles serve applications requiring high pressure ratios and oil management flexibility.
- Scroll:Orbiting scroll technology competes in 5-30 ton segments where hermetic sealing and reduced moving parts lower maintenance burden.
Electric drive retains the broadest installed base. Variable speed drive gains share fastest in markets with aggressive load-shaping programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU F-Gas Regulation anchors European compliance pressure, while China's GB standards and NMPA pharmaceutical codes reshape procurement specifications across Asia. Facility operators in Germany, China, the United States, Japan, and India face distinct refrigerant transition timelines and industrial cooling demand profiles.
United States
Pharmaceutical synthesis facilities in New Jersey and Massachusetts are accelerating chiller replacement cycles to preempt EPA SNAP program refrigerant access constraints. The EPA's listing withdrawals for R-134a and R-410A compress equipment obsolescence timelines. Data center operators in Northern Virginia's Loudoun County corridor specify modular reciprocating arrays for staged capacity deployment.
Germany
Synthetic drug manufacturing corridors in Saxony and North Rhine-Westphalia scale precision-cooled reciprocating capacity for sterility-grade temperature stability. The EU F-Gas Regulation's phasedown quotas compel early replacement of legacy R-134a equipment in Frankfurt and Munich commercial portfolios. Bitzer Kühlmaschinenbau GmbH anchors industrial demand from its Sindelfingen base with specialized semi-hermetic units.
China
Chemical synthesis and polymer processing lines in Jiangsu and Zhejiang provinces drive sub-ambient cooling demand across the eastern manufacturing belt. NMPA pharmaceutical facility codes mandate redundant cooling for active ingredient synthesis suites in Shanghai and Suzhou. Carrier Global Corporation leverages backward integration into compressor assembly to sustain margin control across Asian project deployments.
Japan
Semiconductor fabrication facilities in Kyushu's Kumamoto region specify industrial-tonnage water-cooled systems with ±0.5°C temperature stability. METI efficiency standards accelerate variable speed drive adoption in utility territories with aggressive load-shaping programs. Daikin Industries, Ltd. competes through variable refrigerant flow integration with reciprocating compressor cores.
India
Automotive stamping plants in Tamil Nadu and pharmaceutical API manufacturers in Telangana specify 15-20 year depreciation horizons for capital-intensive cooling infrastructure. BIS certification requirements and state-level peak-shaving incentives shape procurement criteria. Blue Star Limited and Thermax Limited anchor domestic supply for industrial process cooling applications.
Reciprocating Chiller Market Competitive Landscape
Vertically integrated multinationals and specialized compressor fabricators split the market across distinct capability tiers. European specialists control critical semi-hermetic component availability for industrial-tonnage units, while Asian conglomerates leverage captive compressor production for project margin defense. The competitive terrain rewards refrigerant chemistry validation speed and modular plant architecture expertise. Dominant moves include backward integration into compressor assembly and geographic expansion through localized manufacturing corridors.
Within the integrated-systems tier, Carrier Global Corporation and Daikin Industries, Ltd. exemplify conglomerate-scale positioning with captive supply chain control over compressor cores. Bitzer Kühlmaschinenbau GmbH anchors the European specialist archetype from its German manufacturing base. Among diversified industrial groups, Emerson Electric Co. and Danfoss A/S occupy positions spanning component supply through system integration. These named entities represent strategic archetypes rather than exhaustive market coverage, with each exemplifying distinct approaches to refrigerant transition compliance and regional project execution.
| Leading Market Players |
|---|
| Aermec S.p.A. |
| Bitzer Kühlmaschinenbau GmbH |
| Blue Star Limited |
| Carrier Global Corporation |
| Daikin Industries, Ltd. |
| Danfoss A/S |
| Dunham-Bush |
| Emerson Electric Co. |
| Thermax Limited |
| Others |
Value Network & Pricing Analysis
The Shanghai-Rotterdam maritime corridor's freight cost volatility feeds directly into landed price spreads between Asian-manufactured compressor cores and European-assembled systems, concentrating margin pressure on OEMs without backward integration while enabling price differentiation based on regional service proximity.
Pricing Analysis
Price spreads between German-engineered semi-hermetic units and Chinese-assembled alternatives span 40-60% at equivalent tonnage ratings. Three-tier pricing structure across premium, standard, and economy levels segments buyers by certification tier and aftermarket bundling intensity. Cost compression in economy-tier portable units is intensifying because Jiangsu province manufacturers are absorbing copper price swings to defend export share. Pharmaceutical cleanroom operators in Saxony exhibit the lowest price sensitivity, while Indian automotive stamping plants negotiate hardest on depreciation-schedule alignment.
Supply Chain Analysis
Copper cathode and rare earth magnet feedstocks draw from Chilean mining concessions and Chinese refining complexes, tethering compressor motor winding costs to commodity exchange volatility. Component fabrication concentrates in Germany for semi-hermetic castings, China for scroll compressor cores, and Japan for precision electronic controls. Single-source vulnerability runs through European semi-hermetic compressor availability for industrial-tonnage units. Distribution runs through OEM-direct project sales for large installations and regional HVAC distributors for sub-200-ton replacements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Refrigerant transition timelines are fragmenting procurement authority across facility engineering, sustainability compliance, and finance functions—creating specialist niches for OEMs with validated alternative-fluid architectures and third-party service platforms.
For Market Incumbents: Pre-empt screw chiller substitution above 500-ton thresholds by accelerating magnetic bearing centrifugal partnerships or acquiring modular array expertise. Defend European margin structures through captive semi-hermetic compressor allocation to pharmaceutical cleanroom projects. Prioritize refrigerant chemistry validation speed over first-cost reduction.
For New Entrants and Emerging Players: Establish a beachhead in India's pharmaceutical API manufacturing corridor where BIS certification gaps create incumbent service dissatisfaction. Target independent aftermarket compressor overhaul contracts in China's Jiangsu province unbundled from OEM captive terms. Lead with refrigerant reclamation service bundling rather than equipment-first positioning.
For Investors and Strategic Acquirers: Specialist compressor fabricators with validated lower-GWP fluid architectures represent the most defensible acquisition profile. Long-term viability hinges on 5-10 year refrigerant transition completion rates and modular plant architecture adoption curves. Watch EPA SNAP listing withdrawal acceleration and EU F-Gas Regulation phasedown quota tightening as inflection indicators.
| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerant Chemistry Validation | EPA SNAP and EU F-Gas Regulation compliance timelines compress competitive windows for alternative-fluid architectures. |
| Modular Plant Architecture Development | Pharmaceutical and data center operators in Northern Virginia and Shanghai prioritize scalable N+1 redundancy over central plants. |
| Backward Integration into Compressor Assembly | Carrier's Jiangsu province manufacturing corridor demonstrates margin defense against copper price volatility. |
| Aftermarket Service Unbundling | Independent overhaul providers in China's eastern manufacturing belt capture revenue OEMs lose from captive service contracts. |
| Variable Speed Drive Convergence | Jiangsu province peak-shaving tariff incentives accelerate VFD-equipped unit specification for demand-response revenue streams. |
Research Methodology
Operator-level perspectives from plant engineers, HVAC procurement managers, aftermarket service heads, and refrigerant reclamation specialists anchored the qualitative base. Primary interview data combined with secondary validation from customs trade records, EPA SNAP program filings, EU F-Gas Regulation implementation reports, and SEC 10-K equipment disclosure segments. Bottom-up project pipeline tracking across Germany's pharmaceutical corridor and China's Jiangsu province manufacturing belt triangulated against top-down OEM revenue segmentation.
Scenario-bracketing framed low, baseline, and high refrigerant transition compliance trajectories across the projection horizon. Segmentation dimensions modeled include condenser configuration, application thermal stability requirement, end-user depreciation horizon, and regional regulatory framework cluster. CAGRs derived from equipment replacement cycle analysis, industrial capacity addition announcements, and utility demand-response program enrollment curves. Compressor manufacturing capacity utilization and copper price trajectory sensitivity informed tonnage deployment assumptions.
Stress conditions across refrigerant phasedown acceleration, rare earth export restriction severity, and maritime freight rate volatility were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding EU F-Gas Regulation enforcement consistency and NMPA pharmaceutical facility code revision timing. Cross-checking against IEA industrial cooling energy demand projections and national customs chiller import statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
South America Compressor Market
HVAC Equipment
Equipment Fan Filter Unit (EFU) Market
HVAC Equipment
Commercial Air Conditioner (AC) Market
HVAC Equipment
HVAC Actuators Market
HVAC Equipment
Industrial Exhaust System Market
HVAC Equipment
Commercial RAC PD Compressor Market
HVAC Equipment
Ventilation Fan Market
HVAC Equipment
Hydro Chillers Market
HVAC Equipment
Japan HVAC Market
HVAC Equipment
North America Residential Heat Pump Market
HVAC Equipment
North America Air to Water Heat Pump Market
HVAC Equipment
Centrifugal Blower Market
HVAC Equipment
India Chillers Market
HVAC Equipment
Kitchen Hood Market
HVAC Equipment
Warm Air Furnaces Market
HVAC Equipment
Centrifugal Chillers Market