
 Compressor Market | 2026-2036
Compressor Market Size, Share, and Industry Trends Forecast 2026-2036
Compressor Market Analysis
China is fragmenting compressor manufacturing capacity across provincial industrial zones, drawing investment from both domestic and multinational producers. Atlas Copco leverages its rotary screw technology leadership to sustain premium positioning in energy-efficient systems. Ingersoll Rand anchors North American service networks through extensive distributor control. Kaeser Kompressoren differentiates via German-engineered reliability standards and captive component production.
A compressor is a mechanical device that increases gas pressure by reducing volume through piston displacement, rotary screw meshing, or centrifugal impeller acceleration, typically achieving discharge pressures from 100 to 6,000 psi for industrial process use. Rotary screw compressors lead installed base value due to continuous-duty efficiency in manufacturing plants, while centrifugal systems dominate margin pools in large-scale oil and gas processing where uptime premiums command service contracts. Electric power source configurations capture the fastest replacement cycle as facility operators retire diesel units under carbon compliance timelines.
EPA refrigerant phase-down rules under the AIM Act reshape HVAC compressor specifications, while ISO 8573 air quality classes dictate filtration and oil-free design requirements for pharmaceutical and food processing buyers. Ecodesign regulations in Europe enforce minimum efficiency thresholds that disqualify legacy reciprocating models from new installations. Stakeholders must monitor refrigerant chemistry transitions and efficiency standard convergence to align R&D pipelines with compliance windows.
Market Dynamics
Refrigerant chemistry transitions under the EPA AIM Act and parallel F-Gas Regulation in Europe are forcing compressor OEMs to redesign displacement chambers, sealing systems, and lubrication circuits around lower-GWP alternatives. This regulatory compression is accelerating R&D spend and disqualifying legacy platforms from new commercial HVAC installations.
Growth Catalysts
- Data center cooling expansion:Hyperscale facilities in the US and Germany are deploying high-capacity centrifugal compressors for chilled water plants, with operators specifying oil-free designs to meet ISO 8573 Class 0 air quality for semiconductor manufacturing environments.
- Carbon compliance timelines:Industrial facility operators in China are retiring diesel-powered portable compressors under MIIT dual carbon goals, creating replacement demand for electric rotary screw units with variable speed drives.
- Process intensification in chemicals:Polymer and petrochemical plants are specifying integrally geared centrifugal compressors for ethylene cracking, leveraging higher pressure ratios to consolidate multi-stage train footprints.
Market Restraints
- Permanent magnet motor cost volatility:Neodymium and dysprosium price swings from Chinese rare earth processing concentration are compressing margins on premium efficiency compressor lines.
- Refrigerant supply fragmentation:R-454B and R-1234yf production capacity concentrates with Chemours and Honeywell, creating input bottlenecks for HVAC compressor assembly lines.
- Reciprocating platform obsolescence:Ecodesign thresholds in Europe and minimum efficiency standards in California are rendering single-acting piston designs economically unviable for new installations.
Strategic Opportunities
- Hydrogen compression infrastructure:Electrolyzer and fuel cell manufacturing in Germany and Japan is creating demand for diaphragm and ionic liquid compressors capable of 350-700 bar discharge pressures.
- Service contract digitization:Predictive maintenance platforms using vibration and temperature telemetry are enabling OEMs to capture recurring revenue streams from installed base monitoring.
- Food processing air quality mandates:FDA Food Safety Modernization Act requirements for compressed air in packaging lines are expanding addressable market for oil-free scroll and centrifugal technologies.
Industry Challenges
- Refrigerant handling certification gaps:EPA Section 608 technician shortages are slowing HVAC compressor replacement cycles as qualified installers become rate-limiting.
- Legacy control system integration:Brownfield manufacturing plants require protocol translation between modern compressor PLCs and existing SCADA architectures, extending commissioning timelines.
- Pressure vessel code compliance:ASME Section VIII and PED 2014/68/EU certification cycles for high-pressure designs are extending product development schedules by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Compressor Market |
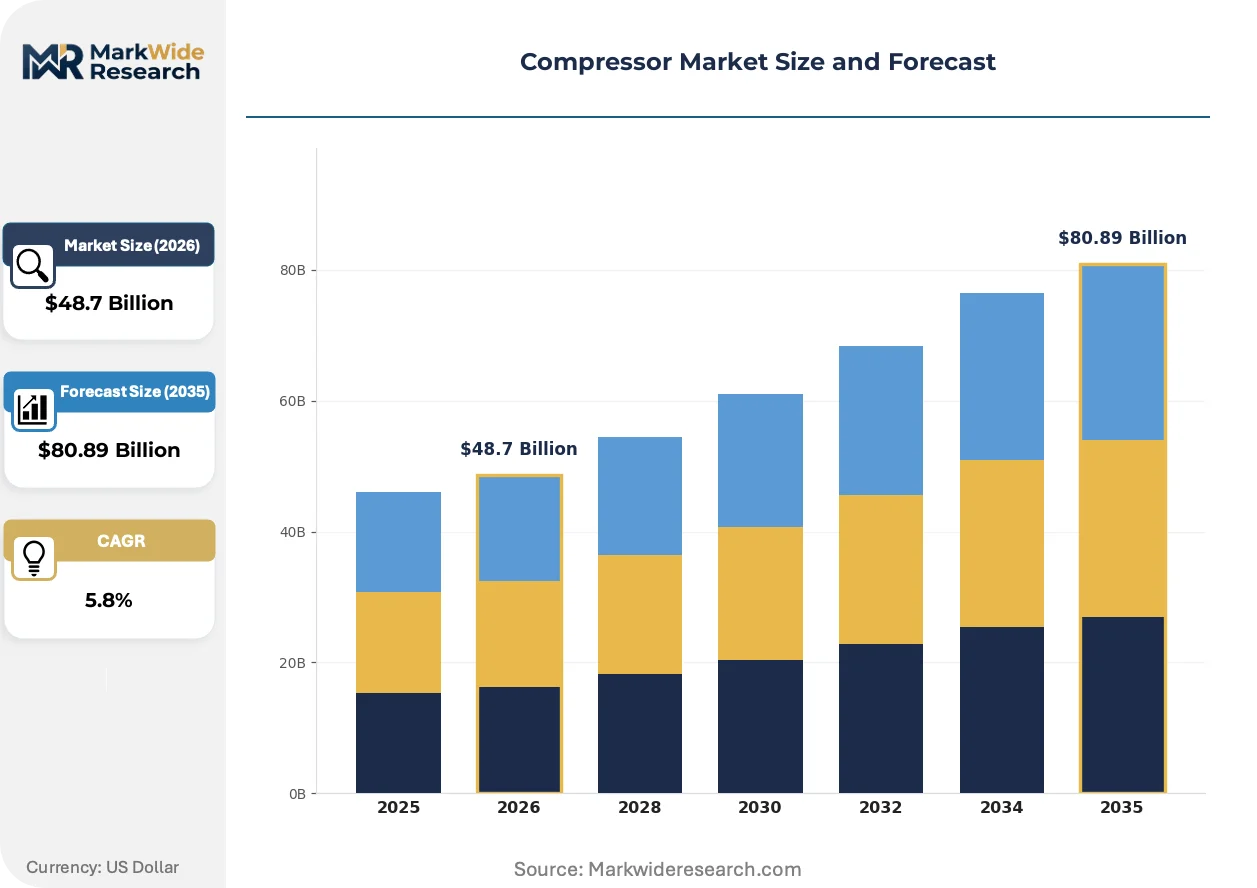
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $80.89 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reciprocating, Rotary Screw, Centrifugal, Scroll Application: Manufacturing, HVAC, Food Processing, Automotive End User: Oil & Gas, Construction, Marine, Pharmaceutical Power Source: Electric, Diesel, Gas, Hybrid |
| Companies Covered | Atlas Copco, Ingersoll Rand, Hitachi, ELGi Equipments, Sullair, Kaeser Kompressoren, Gardner Denver, Danfoss, Siemens Energy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Compressor Market Emerging Trajectories
Digital twin deployment and refrigerant transition chemistry are compressing product development cycles while fragmenting supplier qualification requirements across end-use verticals.
Magnetic bearing centrifugal compressor technology is collapsing mechanical seal maintenance intervals and enabling oil-free operation at capacities previously reserved for geared designs. Pharmaceutical and electronics manufacturing facilities in Singapore and Ireland are specifying these units for continuous-duty cleanroom applications. The elimination of lubricant contamination risk is collapsing the total cost of ownership gap between centrifugal and rotary screw alternatives in 200-500 kW duty ranges.
The EPA AIM Act hydrofluorocarbon phase-down mandates are forcing compressor OEMs to validate new refrigerant chemistries against redesigned pressure-enthalpy envelopes. R-454B and R-32 compatibility testing is consuming engineering resources while disqualifying legacy valve plate and gasket materials. North American rooftop HVAC manufacturers are accelerating platform transitions to maintain eligibility for federal commercial building efficiency incentives under the Inflation Reduction Act.
Compressed air as-a-service contracting is displacing capital purchase models among mid-size manufacturing operations in the US Midwest and German industrial corridors. Kaeser and Atlas Copco are deploying metered airflow arrangements where customers pay per cubic meter delivered, transferring compressor maintenance and efficiency risk to OEM balance sheets. This procurement evolution is most visible in automotive tier-1 supplier plants where working capital constraints favor operational expenditure treatment.
Compressor Market Segmentation
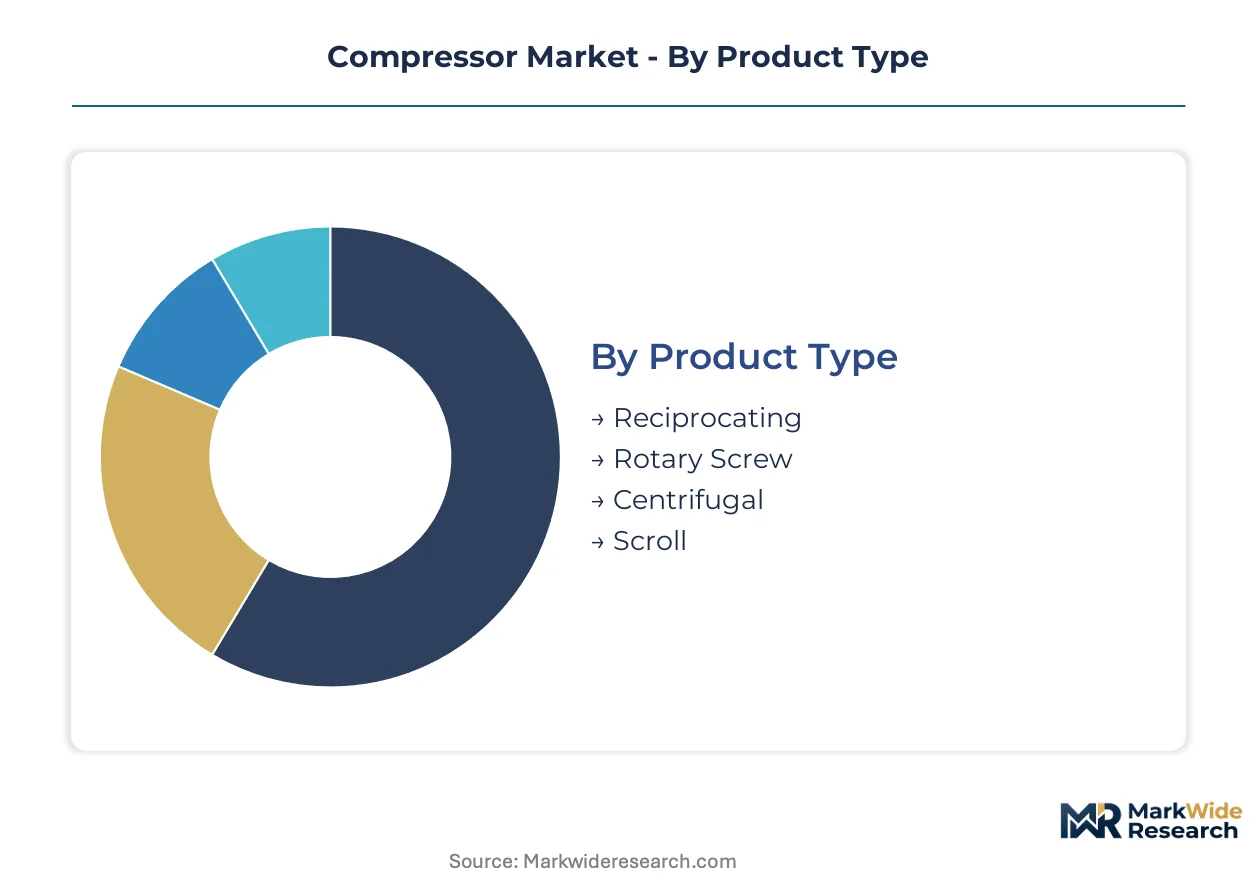
Compressor demand fragments across four distinct dimensions, each governing procurement logic and margin capture. Product type determines technical specification intensity, while application and end-user verticals dictate regulatory compliance burdens. Power source selection increasingly reflects carbon accounting rather than pure economics.
Product Type:
Cost tier differentiation separates intermittent-duty budget systems from continuous-operation premium platforms requiring lifecycle cost validation.
- Rotary Screw:Meshing helical rotors deliver pulsation-free airflow across 5-500 kW ranges with minimal maintenance intervals. Manufacturing plants in China's Guangdong and Jiangsu provinces specify oil-injected and oil-free variants under MIIT efficiency mandates, displacing legacy piston units. Variable speed drives from ABB and Siemens integrate with these compressors to match output to fluctuating demand curves.
- Centrifugal:Integrally geared impeller stages achieve pressure ratios exceeding 10:1 for ethylene cracking and LNG liquefaction trains. Oil and gas processing complexes along the US Gulf Coast and Middle Eastern coastlines specify these for 5,000+ hour annual duty cycles where unplanned shutdowns cost millions per day. Magnetic bearing variants eliminate lubricant contamination risks for semiconductor cleanrooms.
- Reciprocating:Single-acting and double-acting piston designs serve intermittent-duty applications in small machine shops and vehicle service bays. EPA refrigerant phase-down rules and European Ecodesign thresholds are disqualifying these from new commercial HVAC installations.
- Scroll:Orbiting spiral geometry produces oil-free compression for medical and laboratory air systems. Food packaging lines under FDA Food Safety Modernization Act mandates specify these for direct product contact applications.
Rotary screw commands the established base. The steepest expansion runs through centrifugal systems in process industries.
Application:
Volume concentration varies sharply across end-use environments, with uptime premiums and air quality specifications fragmenting procurement criteria.
- HVAC:Chiller and rooftop unit compressors operate under EPA AIM Act refrigerant constraints, forcing R-454B and R-32 compatibility redesigns. Commercial building efficiency incentives under the US Inflation Reduction Act accelerate electric heat pump compressor deployment.
- Manufacturing:Assembly plants and metal fabrication facilities consume compressed air for pneumatic tools, paint spraying, and automated handling systems. ISO 8573 air quality classes dictate filtration investment levels.
- Food Processing:Packaging and bottling lines require oil-free compression meeting FDA and EU food contact material regulations. Microbiological testing protocols for compressed air are tightening under FSMA preventive controls.
- Automotive:Tier-1 supplier plants specify metered airflow contracts to convert capital expenditure to operational expenditure treatment. Electric vehicle battery manufacturing creates demand for ultra-dry air in electrode coating processes.
Manufacturing retains the largest installed footprint. HVAC demonstrates the most rapid specification change velocity.
End User:
Customer type determines service intensity and contract structure, with asset-critical industries accepting premium pricing for guaranteed availability.
- Oil & Gas:Upstream production, midstream transport, and downstream refining specify API 618 and API 672 compliant machines for hydrogen, natural gas, and process gas duties. Service contracts with OEMs cover 10-15 year lifecycles.
- Pharmaceutical:FDA-regulated facilities mandate oil-free, contamination-proof systems with full batch traceability. Validation documentation burdens extend procurement cycles.
- Construction:Portable diesel units face retirement pressure under China's dual carbon goals and European urban emissions zones. Electric and battery-hybrid alternatives gain share in tunneling and indoor demolition.
- Marine:Shipboard compressed air systems serve starting air, control air, and cargo handling. IMO 2020 sulfur regulations indirectly affect auxiliary power availability for electric compressor drives.
Oil and gas anchors service contract value pools. Pharmaceutical requirements are climbing fastest on compliance intensity.
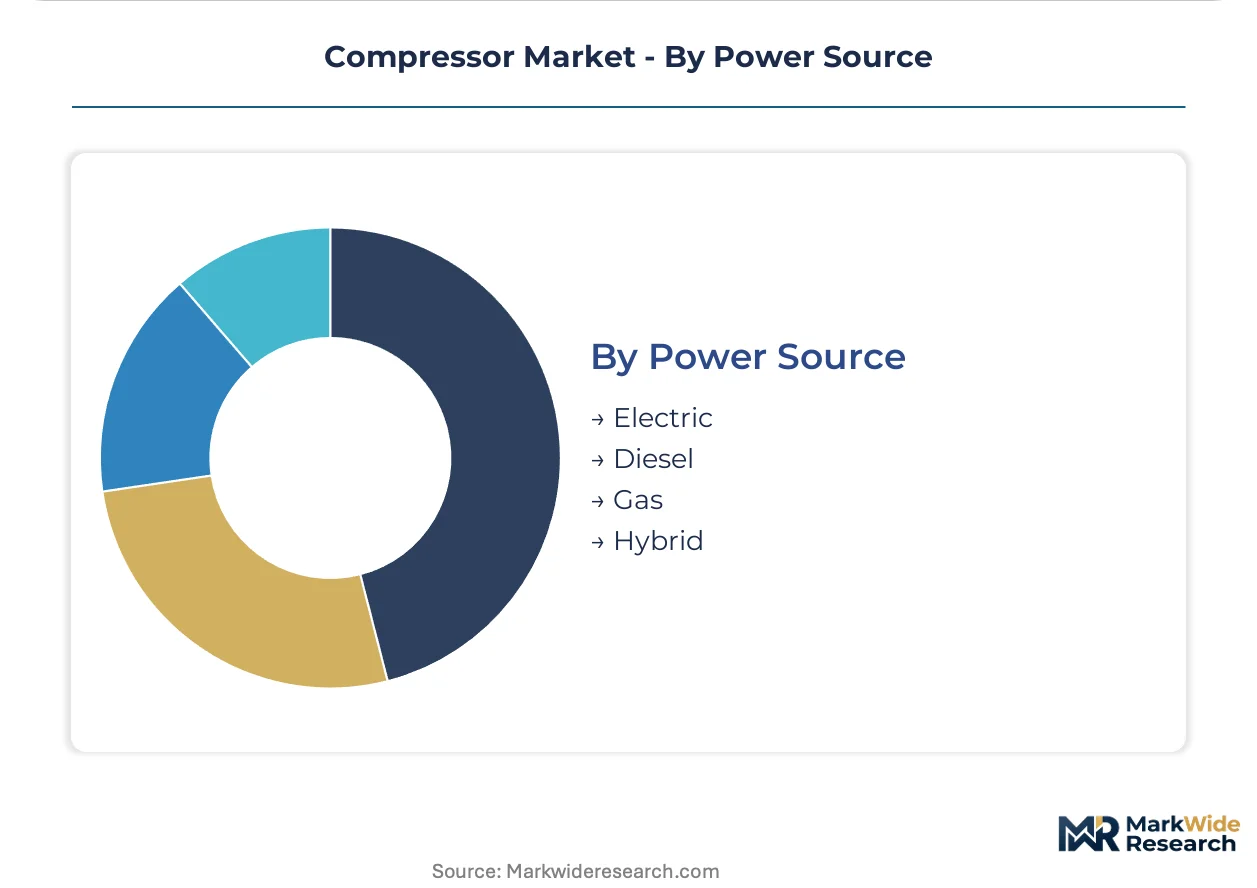
Power Source:
Maturity curves separate legacy fuel-based mobility from grid-connected and hybrid architectures responding to carbon compliance timelines.
- Electric:Fixed industrial installations specify high-efficiency motors with IE4 and IE5 classifications. Permanent magnet synchronous motor cost volatility from Chinese rare earth concentration compresses margins on premium lines.
- Diesel:Portable construction and mining applications face regulatory phase-out in European urban centers and Chinese industrial zones. Residual demand concentrates in remote extraction sites lacking grid infrastructure.
- Gas:Natural gas and biogas engines serve continuous-duty applications where pipeline access eliminates fuel logistics costs. Cogeneration configurations recover waste heat for drying processes.
- Hybrid:Battery-electric with range extender architectures bridge grid-dependent and fully mobile use cases. Underground mining operators in Australia and Canada specify these for ventilation-limited environments.
Electric systems dominate stationary installations. Hybrid architectures are gaining share fastest in regulated mobility applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Compressor manufacturing capacity clusters in Chinese industrial zones and German engineering corridors, with regulatory divergence across EPA, Ecodesign, and MIIT jurisdictions fragmenting product specifications.
United States
Data center cooling expansion in Northern Virginia and Texas drives demand for high-capacity centrifugal systems. EPA AIM Act refrigerant phase-down rules force HVAC compressor redesigns around R-454B chemistry. Gulf Coast petrochemical complexes specify API-compliant machines for ethylene cracking duty.
Germany
Electrolyzer manufacturing for hydrogen infrastructure creates demand for diaphragm compressors rated to 700 bar. EU F-Gas Regulation and Ecodesign thresholds disqualify legacy reciprocating platforms from new installations. Industrial clusters in North Rhine-Westphalia anchor oil-free compressed air contracting models.
China
MIIT dual carbon goals accelerate retirement of diesel portable compressors in construction and mining. Guangdong and Jiangsu provinces fragment manufacturing capacity across state-owned and multinational joint ventures. Yangtze River Delta facilities specify variable speed rotary screw units under efficiency mandates.
Japan
Fuel cell vehicle component manufacturing drives precision hydrogen compression demand. METI industrial efficiency standards favor permanent magnet motor integration in stationary systems. Nagoya-area automotive tier-1 suppliers adopt metered airflow service contracts.
India
Pharmaceutical manufacturing expansion in Maharashtra and Gujarat requires ISO 8573 Class 0 oil-free systems. BIS energy efficiency labeling creates compliance tiers for imported and domestic compressor lines. Tamil Nadu automotive clusters specify electric rotary screw units for paint shop applications.
Compressor Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in motors, bearings, and control electronics. Market structure consolidates around multinational OEMs with captive service networks, while regional fabricators compete on price for intermittent-duty applications. Strategic archetypes separate energy-efficiency technology leaders, reliability-focused premium brands, and scale-driven volume producers. Dominant competitive moves include predictive maintenance platform deployment and backward integration into permanent magnet motor production.
Among European engineering specialists, Atlas Copco and Kaeser Kompressoren exemplify premium-tier positioning through technology leadership and captive manufacturing depth. Ingersoll Rand occupies a position bridging North American service network scale with diversified industrial portfolio breadth.
| Leading Market Players |
|---|
| Atlas Copco |
| Ingersoll Rand |
| Hitachi |
| ELGi Equipments |
| Sullair |
| Kaeser Kompressoren |
| Gardner Denver |
| Danfoss |
| Siemens Energy |
| Others |
Supply Flow & Price Mechanics
Guangdong Province's fragmented manufacturing base concentrates rotary screw compressor capacity among state-owned and multinational joint ventures, feeding pricing power downstream to OEMs with captive component production. The Yangtze River Delta's efficiency mandates under MIIT dual carbon goals compress margins on legacy diesel units while elevating premium electric variable-speed drives.
Pricing Analysis
EPA AIM Act refrigerant phase-down rules dictate the pricing tier structure across HVAC compressor lines, with R-454B compatibility validation costs separating premium OEM platforms from economy fabricators. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 8573 air quality certification grade and after-sales service bundling intensity. Price erosion runs through reciprocating platforms as Ecodesign thresholds disqualify single-acting piston designs. Tier-1 automotive suppliers exhibit lowest price sensitivity due to metered airflow contracting models, while small machine shops remain most cost-conscious.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculus for permanent magnet motor sourcing. Manufacturing concentration spans China, Germany, and Japan for precision-machined rotors and impeller castings. Neodymium and dysprosium rare earth processing draws from Chinese refining capacity, while lubricant formulations and electronic control modules rest on German and Japanese specialty chemical suppliers. Single-source vulnerability concentrates in R-454B and R-1234yf refrigerant supply from Chemours and Honeywell. Distribution runs through OEM captive service networks for premium lines and independent distributors for intermittent-duty equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating among hyperscale data center operators and automotive tier-1 suppliers, compressing OEM margins and elevating service contract terms as the primary differentiation lever.
For Market Incumbents: Harden predictive maintenance platform deployment to capture recurring revenue from installed base telemetry before emerging IoT-native entrants displace legacy service relationships. Deepen backward integration into permanent magnet motor production to offset Chinese rare earth price volatility. Anchor capacity expansion in India's Tamil Nadu and Maharashtra pharmaceutical corridors where ISO 8573 Class 0 demand outstrips qualified supply. For New Entrants and Emerging Players: Establish a beachhead in India's pharmaceutical manufacturing expansion where FDA Food Safety Modernization Act mandates create urgent demand for oil-free scroll and centrifugal technologies underserved by incumbent service networks. Target hydrogen electrolyzer supply chains in Germany and Japan where diaphragm compressor qualification gaps persist. Lead with metered airflow contracting to bypass capital expenditure barriers among working-capital-constrained automotive suppliers. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among OEMs with captive predictive maintenance platforms and long-term service contracts in oil and gas processing. Long-term viability favors asset-light technology licensors over capital-intensive fabricators exposed to rare earth cost volatility. Monitor EPA Section 608 technician certification bottlenecks as an inflection indicator for HVAC replacement cycle velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Platform Deployment | Atlas Copco and Kaeser capture telemetry-driven recurring revenue from vibration monitoring contracts. |
| Backward Integration into Permanent Magnet Motors | OEMs reduce neodymium cost exposure through in-house motor production under IE4 and IE5 classifications. |
| Hydrogen Compression Infrastructure Buildout | Diaphragm and ionic liquid technologies address 700-bar electrolyzer demand in German industrial clusters. |
| Refrigerant Chemistry Validation Acceleration | R-454B and R-32 compatibility testing maintains eligibility for Inflation Reduction Act efficiency incentives. |
| Oil-Free Compressed Air Contracting Expansion | Metered airflow arrangements convert capital expenditure to operational expenditure for Midwest automotive tier-1 plants. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with plant engineers, maintenance directors, OEM procurement teams, and aftermarket service heads. Secondary validation drew from EPA AIM Act regulatory filings, MIIT efficiency mandate documentation, SEC 10-K equipment disclosures, and customs trade data on compressor unit imports. Bottom-up unit economics triangulated against top-down industry absorption rates.
Calibration against historical replacement cycles and regulatory compliance windows anchored projections across the analysis window. Segmentation dimensions modeled include product type, application vertical, end-user industry, and power source architecture. CAGRs derived from installed base turnover velocity and efficiency standard phase-in schedules. Forecast inputs incorporated refrigerant transition timelines and rare earth price elasticity assumptions.
Stress conditions across neodymium supply disruption, EPA technician shortage severity, and HVAC retrofit incentive duration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on regulatory enforcement intensity and carbon compliance adoption curves. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Commercial Refrigeration Compressor Market
HVAC Equipment
Steam Operated Condensate Pump Market
HVAC Equipment
Europe Air Conditioning Equipment Market
HVAC Equipment
Global Portable Evaporative Air Cooler Market
HVAC Equipment
Germany HVAC Market
HVAC Equipment
Water Softener Equipment Market
HVAC Equipment
Japan HVAC Market
HVAC Equipment
Asia-Pacific Heat Exchanger Market
HVAC Equipment
HVAC System Analyzer Market
HVAC Equipment
South America Screw Compressor Market
HVAC Equipment
North America Industrial Air Chiller Market
HVAC Equipment
Global Submerged Coil Heat Exchanger Market
HVAC Equipment
North America Gas Water Heater Market
HVAC Equipment
Linear Slot Diffuser Market
HVAC Equipment
US HVAC Services Market
HVAC Equipment
Europe Hydronic Radiators Market