
 Recirculating Chillers Market | 2026-2036
Recirculating Chillers Market Size, Share, and Industry Trends Forecast 2026-2036
Recirculating Chillers Market Intelligence
Demand from semiconductor manufacturing is consolidating its position as the primary driver, overtaking traditional applications in plastics processing. Thermo Fisher Scientific Inc. leverages its extensive distribution network to serve research labs and pharmaceutical clients. Concurrently, LAUDA Dr. R. Wobser GmbH & Co. KG specializes in high-precision thermal control systems for demanding industrial processes. Peter Huber Kältemaschinenbau SE differentiates through its focus on high-performance units utilizing environmentally friendly refrigerants.
A recirculating chiller is a closed-loop system designed to remove heat from a liquid coolant, typically maintaining temperature stability within ±0.1°C. These systems are essential for ensuring the operational integrity and longevity of heat-sensitive equipment in scientific and industrial settings. Vapor compression remains the dominant technology, while the choice between air-cooled and water-cooled units depends on facility infrastructure and heat load. Applications like laser cooling and semiconductor manufacturing command the highest performance specifications and, consequently, premium pricing.
Regulatory frameworks like the EU's F-Gas Regulation and the US EPA's SNAP program mandate the phase-down of high global warming potential (GWP) refrigerants. This directly influences chiller design, compelling manufacturers to innovate with alternatives such as hydrofluoroolefins (HFOs) or natural refrigerants. The key strategic decision for end-users will revolve around selecting either centralized plant-wide cooling or decentralized, point-of-use chiller systems for their facilities.
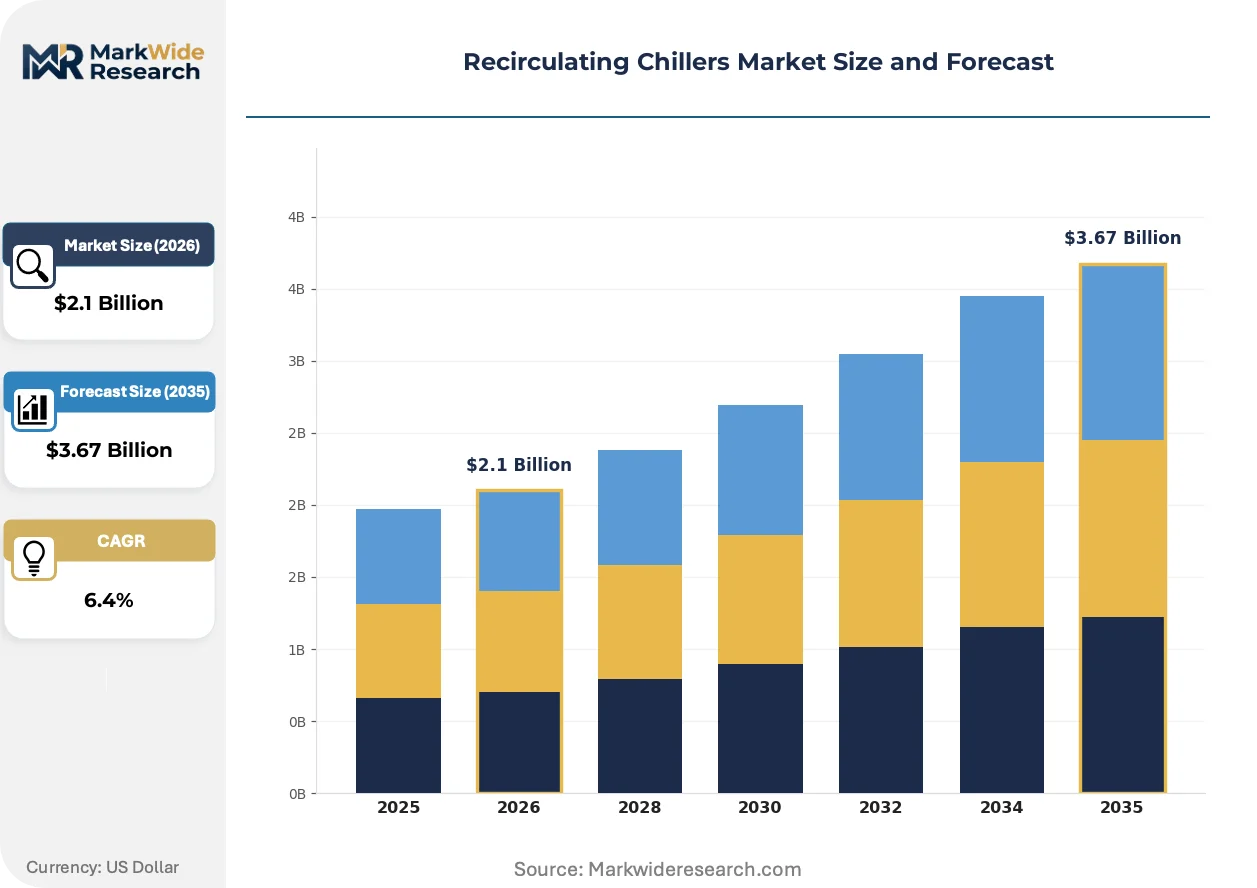
Market Dynamics
The recirculating chillers market is defined by the need to balance high-precision thermal management with escalating environmental regulations. This dynamic forces manufacturers to innovate with alternative refrigerants while meeting the sub-degree temperature stability demands of advanced industrial and scientific processes.
Growth Catalysts
- Semiconductor Fabrication:The demand for extreme precision cooling in photolithography and etching processes within semiconductor manufacturing facilities provides a primary catalyst for high-performance chiller adoption.
- Battery Manufacturing Expansion:China's aggressive expansion in electric vehicle battery production requires extensive thermal management systems to control heat during slurry mixing, coating, and cell testing, creating significant demand.
- Regulatory Mandates:The EU's F-Gas Regulation acts as a powerful demand driver by compelling end-users to replace older chillers using high-GWP refrigerants with new, compliant systems.
Market Restraints
- High Capital Expenditure:The significant upfront investment required for high-precision chillers, particularly those offering stability better than ±0.1°C, can be a barrier for academic institutions and smaller industrial operators.
- Natural Refrigerant Limitations:While eco-friendly, some natural refrigerants like CO2 require higher operating pressures and more complex system designs, which can increase equipment cost and limit serviceability.
- Component Supply Chain:The supply of specialized components, such as variable-speed compressors and high-efficiency microchannel heat exchangers, is concentrated among a few suppliers, creating potential price volatility and lead-time risks.
Strategic Opportunities
- Data Center Liquid Cooling:The rising thermal density of server racks presents an opportunity for direct-to-chip or immersion cooling systems that rely on high-capacity recirculating chillers for heat rejection.
- Smart Control Integration:There is a significant opportunity to embed IoT connectivity and AI-driven predictive analytics into chillers, offering end-users enhanced energy efficiency and predictive maintenance capabilities.
- Bio-Pharma Process Scaling:The expansion of biologics manufacturing and cell therapy production creates demand for GMP-compliant, reliable chillers to ensure temperature integrity for bioreactors and critical storage applications.
Industry Challenges
- Technician Skill Gaps:A shortage of service technicians trained to handle flammable or high-pressure natural refrigerants and complex electronic controls presents a challenge to widespread adoption and maintenance.
- System Integration Complexity:Integrating new, decentralized point-of-use chillers with a facility's existing centralized plant-wide cooling loops requires careful engineering to ensure hydraulic balance and optimal performance.
- Navigating Regulatory Fragmentation:Manufacturers face the complexity of designing and certifying products that comply with differing regional refrigerant regulations, such as the EU F-Gas Regulation versus the US EPA SNAP program.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Recirculating Chillers Market |
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.67 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Air-Cooled, Water-Cooled, Portable, Industrial, Compact Technology: Thermoelectric, Vapor Compression, Absorption, Magnetic, Ultrasound Application: Laser Cooling, Plastics Processing, Food Processing, Chemical Reactions, Semiconductor Manufacturing End User: Pharmaceutical Manufacturers, Universities, Research Labs, Food & Beverage Processors, Semiconductor Foundries |
| Companies Covered | LAUDA Dr. R. Wobser GmbH & Co. KG, Cole-Parmer Instrument Company LLC, Thermo Fisher Scientific Inc., SMC Corporation, Dimplex Thermal Solutions Inc., Peter Huber Kältemaschinenbau SE, BÜCHI Labortechnik GmbH, Agilent Technologies, Inc., JULABO GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Recirculating Chillers Market Strategic Shifts & Innovations
Product development is increasingly focused on the dual objectives of enhancing energy efficiency and complying with global refrigerant phase-down mandates. This shift drives innovation in compressor technology, control software, and system architecture, pushing the market toward more sustainable and intelligent cooling solutions.
Variable-speed drive (VSD) technology allows a chiller's compressor to precisely modulate its output to match the immediate thermal load. This capability is being adopted by end-users in medical diagnostics and laser systems who require both tight temperature control and lower energy consumption. VSD technology is integrating superior part-load efficiency with reduced operational noise, fundamentally improving the total cost of ownership for high-utilization applications.
The US EPA's Significant New Alternatives Policy (SNAP) program continues to restrict the use of certain high-GWP HFC refrigerants in new chiller equipment. This regulatory action directly influences design choices, pushing manufacturers toward approved low-GWP alternatives like HFOs and natural refrigerants. The scientific instruments segment is particularly affected, responding by qualifying new equipment designs that ensure performance is not compromised by the refrigerant transition.
A notable behavioral change is the move toward modular and scalable cooling architectures, especially in research and development environments. Instead of a single, large central chiller, users are opting for multiple smaller, dedicated units that can be added or reconfigured as process needs evolve. This trend is most prominent in university laboratories and biotech startups in North America, which prioritize flexibility over the economy of scale of a monolithic system.
Recirculating Chillers Market Segmentation
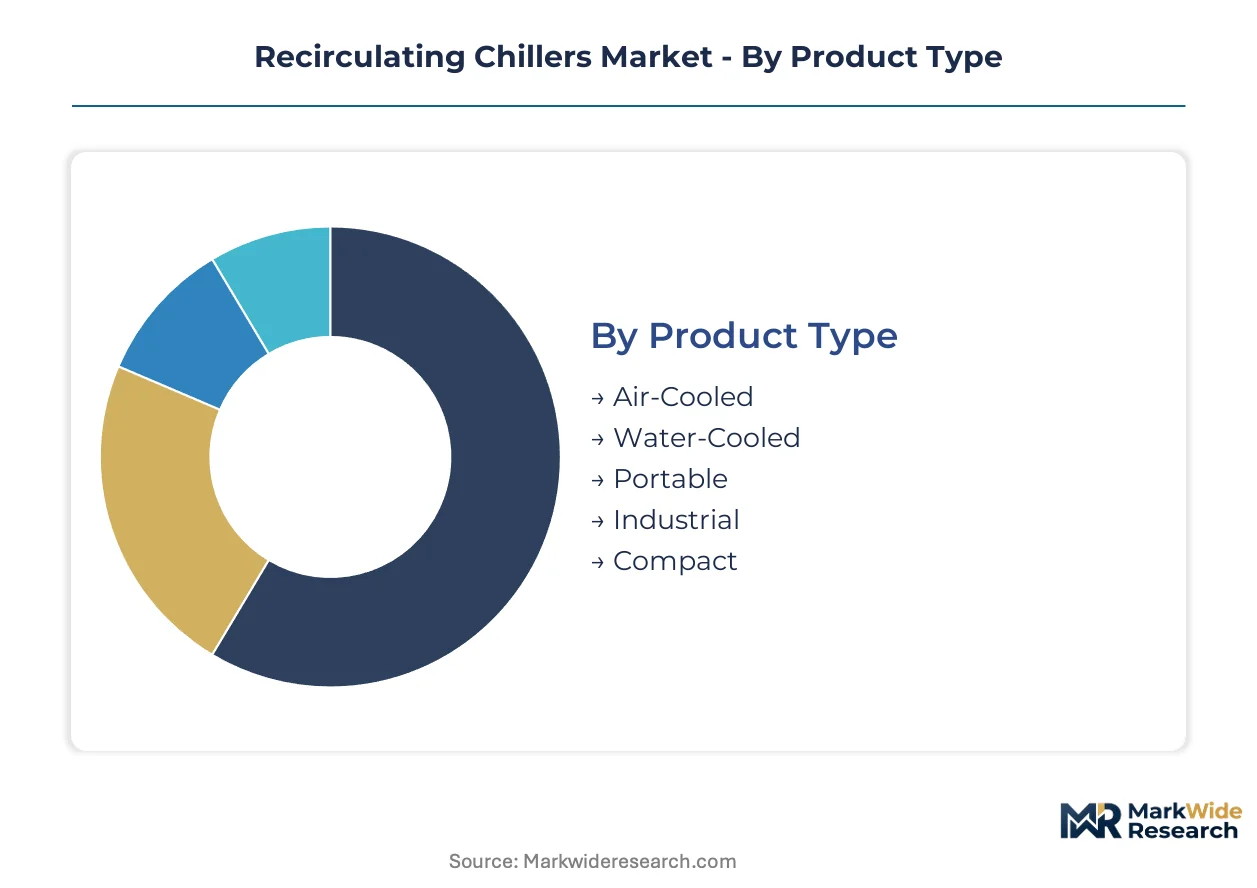
The recirculating chillers market is highly diversified, reflecting the varied thermal management needs across industrial and scientific applications. Understanding these distinct segments is crucial for manufacturers to tailor solutions and for end-users to optimize system selection for specific operational demands.
Product Type:
The recirculating chillers market differentiates product offerings based on their cooling mechanism and deployment flexibility.
- Air-Cooled:These systems utilize ambient air to dissipate process heat, eliminating the need for an external water supply or cooling tower infrastructure. Air-cooled chillers are frequently deployed in facilities with limited water resources or where portability is a primary consideration, such as remote industrial installations.
- Water-Cooled:Connecting to a facility's central water supply or dedicated cooling tower, these units offer superior efficiency for managing large heat loads and maintaining tighter temperature tolerances. Water-cooled systems are essential for high-performance computing centers and advanced semiconductor fabrication plants in highly industrialized regions.
- Portable:These compact units offer flexibility for temporary setups or mobile diagnostic equipment in research and development environments.
- Industrial:Designed for robust, continuous operation, these chillers withstand demanding conditions in heavy manufacturing and processing plants.
- Compact:Optimized for space-constrained laboratory and medical imaging applications, providing precise temperature control in limited footprints.
Water-Cooled units lead on scale; Portable chillers lead on momentum.
Technology:
Chiller technology choices are often dictated by the specific thermal management requirements of diverse industrial and scientific applications.
- Vapor Compression:This dominant technology employs a refrigerant cycle involving compression, condensation, expansion, and evaporation for highly efficient heat transfer. Vapor compression chillers are indispensable for high-performance applications like laser cooling and semiconductor manufacturing due to their superior temperature stability.
- Absorption:These systems utilize a heat source and two fluids—refrigerant and absorbent—to create a cooling effect without mechanical compression, offering a quieter operation. Absorption chillers are increasingly used in waste heat recovery systems and large industrial processes where energy efficiency from waste heat is paramount.
- Thermoelectric:This technology relies on the Peltier effect for precise, small-scale temperature control in analytical instruments and medical devices.
- Magnetic:Exploring magnetocaloric effects, this emerging technology offers potential for highly efficient, environmentally friendly cooling systems with reduced refrigerant use.
- Ultrasound:An innovative technology leveraging acoustic waves for non-contact thermal management in microfluidics and sensitive biological applications.
Vapor Compression technology retains market dominance, while Magnetic cooling is climbing the fastest.
Application:
The diverse operational needs of various end-user industries drive the segmentation of recirculating chillers by application.
- Semiconductor Manufacturing:This sector requires ultra-precise temperature control for photolithography, etching, and deposition processes to ensure product yield and quality. China's aggressive expansion in electronics production and advanced chip foundries drives significant demand for these critical systems.
- Laser Cooling:Maintaining stable operating temperatures for high-power lasers is crucial in industrial cutting, welding, and medical procedures to preserve beam quality and equipment longevity. Increasing adoption in material processing and scientific research facilities across Europe necessitates reliable thermal management.
- Plastics Processing:Chillers manage mold temperatures to ensure consistent product quality, reduce cycle times, and prevent warping in plastic injection molding.
- Food Processing:Essential for maintaining specific temperatures during mixing, cooking, and packaging, chillers preserve food safety and extend shelf life.
- Chemical Reactions:Provides precise temperature stability for exothermic or endothermic processes in pharmaceutical synthesis and specialty chemical production.
Semiconductor Manufacturing represents significant volume, with Laser Cooling showing robust expansion.
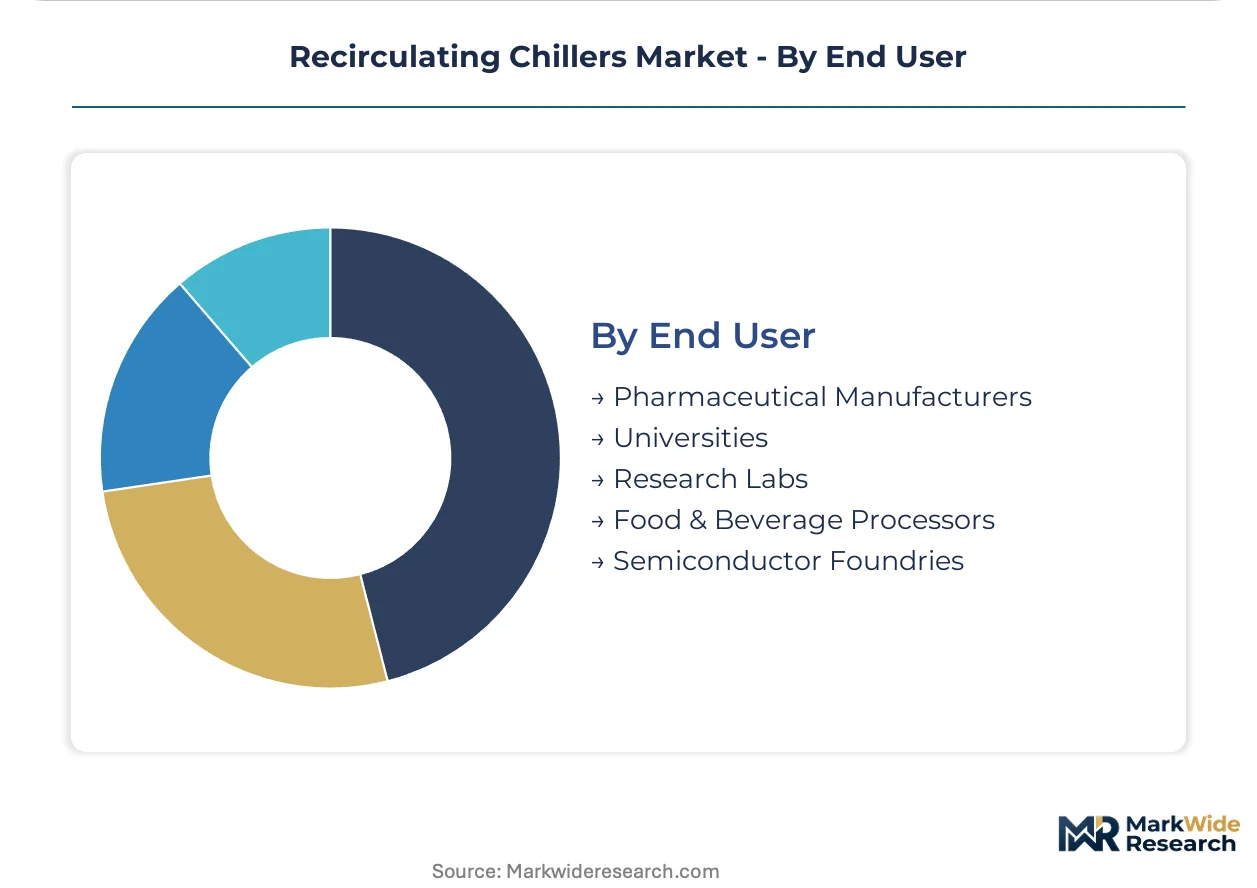
End User:
The varied operational scales and precision requirements across different end-user sectors necessitate specialized recirculating chiller solutions.
- Semiconductor Foundries:These facilities require highly reliable and precise chillers for critical process tools such as steppers, etchers, and deposition systems to prevent thermal drift. Demand is driven by global chip shortages and investments in new fabrication plants in regions like Arizona and Germany.
- Research Labs:Universities and private research institutions utilize chillers for a wide array of scientific instruments, including electron microscopes, mass spectrometers, and NMR machines. Universities and biotech startups in North America frequently seek flexible, modular cooling solutions for evolving experimental setups.
- Pharmaceutical Manufacturers:These companies ensure temperature integrity for bioreactors, fermenters, and storage of sensitive compounds, adhering to strict Good Manufacturing Practice (GMP) guidelines.
- Universities:Support diverse academic research projects requiring stable temperature environments for experimental apparatus in physics, chemistry, and biology departments.
- Food & Beverage Processors:Maintain hygiene and product quality through controlled cooling of production lines, mixing tanks, and storage facilities in large-scale food production.
Semiconductor Foundries remain the largest consumer, and Research Labs are rapidly expanding their footprint.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's robust electronics and battery manufacturing sector drives significant demand for recirculating chillers. This market exhibits distinct regional dynamics, influenced by local industrial concentrations and specific regulatory environments. Precise thermal management solutions are critical for advanced processes.
China
Demand for extreme precision cooling in semiconductor manufacturing and electric vehicle battery production remains strong in China. The country's dual carbon goals compel industries to adopt more energy-efficient, compliant cooling systems. Advanced chip foundries in the Yangtze River Delta continue to invest heavily in high-performance chiller technology.
United States
Investments in new semiconductor foundries and expanding biotech research facilities propel chiller demand across the United States. The US EPA's SNAP program influences refrigerant choices, pushing manufacturers towards low-GWP alternatives. Arizona's burgeoning semiconductor fabrication plants require advanced thermal control for critical process tools.
Germany
Germany's strong industrial base, particularly in high-precision manufacturing and pharmaceutical production, creates consistent demand for reliable chillers. The EU's F-Gas Regulation accelerates the transition to eco-friendly refrigerants in new equipment. Bavaria's advanced manufacturing and scientific research facilities frequently adopt specialized thermal control solutions.
Japan
High-tech manufacturing, including advanced materials processing and scientific instruments, requires stable temperature control in Japan. METI initiatives encourage energy efficiency and technological innovation in industrial equipment. The Kansai region, known for its optics and laser technology companies, relies on precise cooling for specialized applications.
India
Expanding pharmaceutical manufacturing and a growing research infrastructure contribute to chiller demand in India. The PLI scheme supporting domestic manufacturing stimulates investment in various industrial sectors requiring thermal management. Hyderabad's thriving pharmaceutical and biotech hub consistently seeks reliable cooling for bioreactors and laboratory equipment.
Recirculating Chillers Market Key Industry Players
Strategic partnerships dominate the current landscape, as manufacturers seek to combine expertise and broaden their market reach. The market structure is tiered, featuring global industrial giants alongside specialized high-precision manufacturers and regional providers. Strategic archetypes include innovation-driven specialists, volume-focused integrators, and service-oriented regional players. Competitive moves include technology licensing agreements to integrate advanced components and geographic expansion into high-growth regions.
Within the high-precision segment, Germany-based LAUDA Dr. R. Wobser GmbH & Co. KG exemplifies manufacturers focusing on demanding industrial processes, offering specialized thermal control systems. Peter Huber Kältemaschinenbau SE, also based in Germany, anchors the segment for high-performance units utilizing environmentally friendly refrigerants, catering to clients with stringent environmental requirements. US-based Thermo Fisher Scientific Inc. represents a broader market approach, leveraging its extensive distribution network to serve a wide array of research labs and pharmaceutical clients globally, emphasizing comprehensive solution provision.
| Leading Market Players |
|---|
| LAUDA Dr. R. Wobser GmbH & Co. KG |
| Cole-Parmer Instrument Company LLC |
| Thermo Fisher Scientific Inc. |
| SMC Corporation |
| Dimplex Thermal Solutions Inc. |
| Peter Huber Kältemaschinenbau SE |
| BÜCHI Labortechnik GmbH |
| Agilent Technologies, Inc. |
| JULABO GmbH |
Cost & Logistics Intelligence
Copper futures prices directly influence the manufacturing cost of recirculating chillers, cascading through component suppliers and impacting final product pricing across various performance tiers. This market balances the need for high-precision thermal management with escalating environmental regulations.
Pricing Analysis
Input-cost pass-through dynamics significantly shape pricing for recirculating chillers. Value-based pricing dominates for high-precision units, where performance directly impacts critical processes. Price differentiation stems from factors like temperature stability specifications and energy efficiency certifications. Upward pricing pressure stems from the rising cost of low-GWP HFO refrigerants mandated by regulations like the EU F-Gas Regulation. Academic institutions and smaller industrial operators exhibit the highest price sensitivity, whereas semiconductor foundries prioritize performance over cost.
Supply Chain Analysis
Regional distribution centers facilitate the timely delivery of recirculating chillers and critical spare parts to end-users globally. Manufacturing of specialized components concentrates in China, Germany, and Japan. The supply chain relies heavily on specialized compressors and high-efficiency microchannel heat exchangers. Component supply chain concentration among a few global suppliers creates lead-time risks and potential price volatility. Distribution runs through a mix of direct sales channels and extensive regional distributor networks, particularly for research labs and pharmaceutical clients.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Recirculating chillers market operates as a stable compounder. The ongoing industrialization and scientific advancement across semiconductor manufacturing and biopharmaceutical sectors drive steady, predictable growth.
For Market Incumbents: Deepen strategic partnerships with key component suppliers to mitigate supply chain risks and ensure access to specialized components. Invest in R&D for new low-GWP refrigerants and advanced control software to stay ahead of regulatory fragmentation, such as that between the EU F-Gas Regulation and the US EPA SNAP program. Expand global service networks and invest in technician training to support complex systems. Certification investment for new HFO-based systems will reinforce market leadership against emerging competitors.
For New Entrants and Emerging Players: Begin with niche applications requiring specialized thermal control, such as microfluidics or specific biotech processes, to establish a performance reputation. Target the growing demand for modular and scalable cooling architectures in university laboratories and biotech startups across North America. Focus on smart control integration, embedding IoT connectivity and AI-driven predictive analytics as a key differentiator. A go-to-market strategy emphasizing superior energy efficiency and predictive maintenance offers a compelling value proposition.
For Investors and Strategic Acquirers: Consolidation pressure builds where specialized high-precision thermal management expertise is scarce and critical to advanced industrial processes. The recirculating chillers market offers consistent, long-term viability over the next decade, driven by sustained demand from semiconductor and pharmaceutical sectors. Target acquisition archetypes include niche specialists in natural refrigerant technologies or advanced control software providers. Increased M&A activity among specialized component suppliers will signal further market maturation and potential for consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand HFO/Natural Refrigerant Portfolio | Addresses EU F-Gas Regulation compliance, securing market access for new equipment in Europe. |
| Develop AI-Driven Predictive Maintenance | Enhances energy efficiency and operational uptime for critical semiconductor manufacturing facilities. |
| Strengthen Global Service Network | Supports complex installations and ensures reliability for pharmaceutical manufacturers worldwide. |
| Invest in Modular Chiller Designs | Catters to the flexibility needs of North American university laboratories and biotech startups. |
| Form Joint Ventures for Microchannel Heat Exchangers | Mitigates component supply chain risks and optimizes cost structures for industrial chillers. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, providing a comprehensive view of the recirculating chillers market. Primary interviews with plant managers, R&D directors, and procurement officers informed the analysis. Secondary validation involved extensive review of patent filings, regulatory documents, and industry association publications. Bottom-up analysis of installed base and top-down validation of market sizing ensured data integrity through triangulation.
Historical market data from comparable periods anchored the forecast window, establishing a baseline for future projections. The analytical framework integrated regression analysis and scenario planning across the modeling period, segmenting by product type, technology, application, end-user, and refrigerant type. Compound annual growth rates were derived from volume and value growth, factoring in semiconductor fab expansions and EV battery production targets.
Caveats apply where unforeseen regulatory shifts or technological breakthroughs could materially shift the outlook. Forecasts reflect documented assumptions regarding global economic stability and geopolitical conditions affecting critical supply chains. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
US HVAC Services Market
HVAC Equipment
United States Heat Exchanger Market
HVAC Equipment
Europe HVAC Market
HVAC Equipment
Hydro Chillers Market
HVAC Equipment
Europe HVAC Equipment Market
HVAC Equipment
Air Conditioner Quilt Market
HVAC Equipment
North America Commercial Heating, Ventilation, and Air Conditioning (HVAC) Equipment Market
HVAC Equipment
HVAC Systems Market
HVAC Equipment
Residential Heat Pump Market
HVAC Equipment
HVAC Air Quality Monitoring Market
HVAC Equipment
Global Air Conditioner Market
HVAC Equipment
Germany Heat Pump Market
HVAC Equipment
Italy Commercial HVAC Market
HVAC Equipment
Steam Humidifiers Market
HVAC Equipment
Global Air Handling Units (AHU) Market
HVAC Equipment
Linear Slot Diffuser Market