
 HVAC Centrifugal Compressors Market | 2026-2036
HVAC Centrifugal Compressors Market Size, Share, and Industry Trends Forecast 2026-2036
HVAC Centrifugal Compressors Market Intelligence
The performance gap between premium magnetic bearing systems and commodity fixed-speed units is hardening as data center operators demand sub-1% energy degradation over ten-year cycles. Atlas Copco leverages its oil-free compressor platform to anchor high-reliability contracts with hyperscale cloud providers. Ingersoll Rand competes through integrated building automation bundles that extend its reach beyond hardware into lifecycle service contracts.
HVAC centrifugal compressors are dynamic turbomachines that accelerate refrigerant vapor through an impeller wheel to achieve pressure ratios typically ranging from 2:1 to 8:1, with capacities spanning 100 to 10,000+ tons of refrigeration for large-scale climate control. Their primary purpose centers on delivering efficient, continuous cooling for centralized building systems where screw or reciprocating technologies face capacity or efficiency ceilings. Oil-free product types command premium positioning due to elimination of lubricant contamination risk in sensitive environments like pharmaceutical cleanrooms and semiconductor fabrication. Variable speed drive technology leads volume growth as part-load efficiency regulations tighten across major economies, while magnetic bearing systems capture the fastest expansion rate despite higher first cost. Multi-stage configurations occupy the mature core of the installed base, particularly in legacy district cooling networks across the Middle East and Southeast Asia.
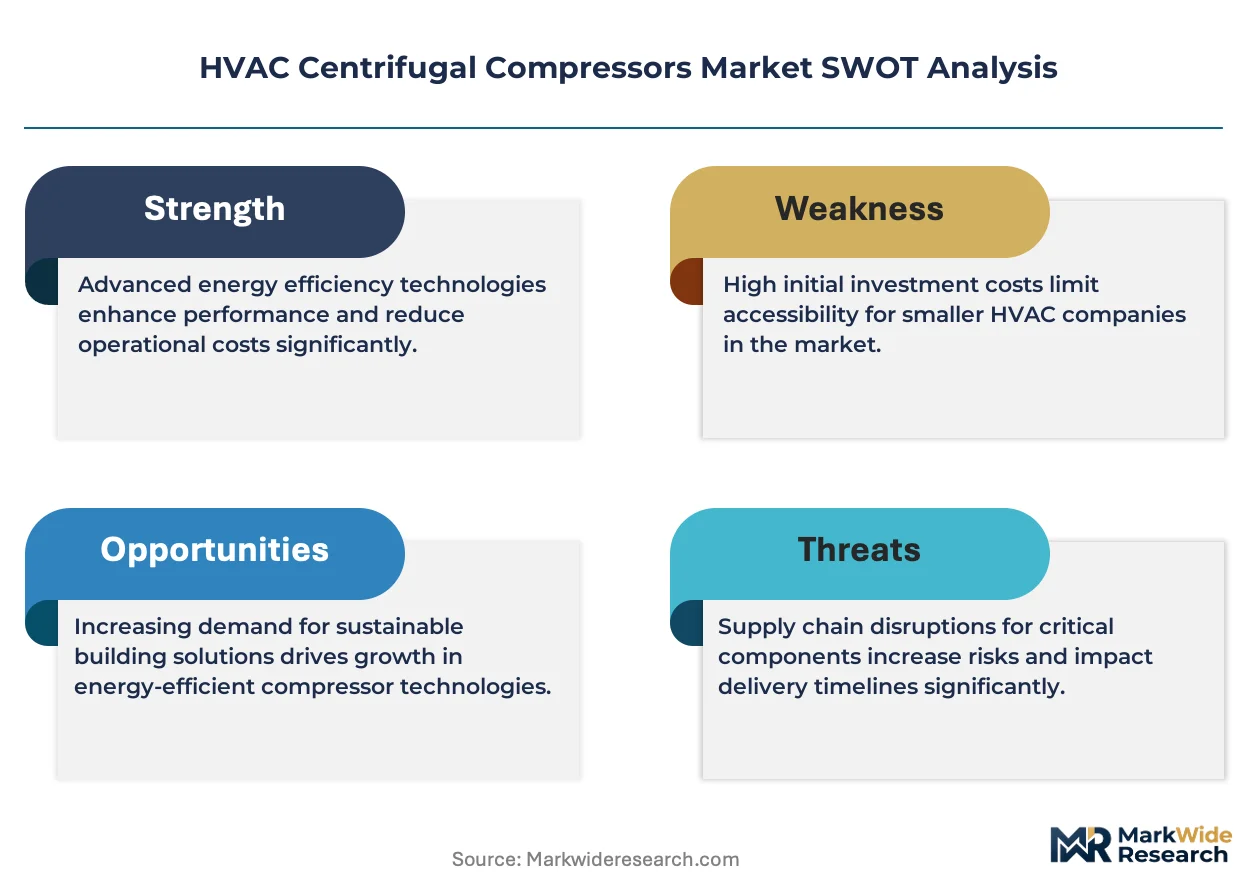
The U.S. Department of Energy mandates minimum full-load and part-load efficiency metrics under 10 CFR 431, while the EPA's AIM Act enforces phased reductions in HFC refrigerant global warming potential, forcing compressor redesigns for lower-GWP alternatives. The EU F-Gas Regulation and CE marking requirements under the Machinery Directive create parallel compliance burdens for equipment sold into European commercial building and cold storage applications. Stakeholders must monitor refrigerant transition timelines and efficiency standard convergence between North American and European frameworks to avoid stranded product development investments.
Market Dynamics
The EPA's phasedown of hydrofluorocarbon refrigerants under the AIM Act is compressing product development cycles and forcing compressor OEMs to validate lower-GWP chemistries against legacy performance benchmarks.
Growth Catalysts
- Data center precision cooling mandates:Hyperscale operators in Northern Virginia and Singapore require sub-1% energy degradation over ten-year cycles, pulling magnetic bearing technology into standard specifications.
- 10 CFR 431 efficiency standards:The U.S. Department of Energy's part-load metrics are disqualifying fixed-speed units from federal procurement and large commercial tenders.
- Asia-Pacific commercial construction:New district cooling networks in Vietnam and Indonesia specify multi-stage centrifugal systems for 10,000+ ton capacity requirements.
Market Restraints
- Copper and rare earth price volatility:Magnetic bearing stator assemblies depend on neodymium supply concentrated in Chinese processing facilities.
- Refrigerant transition friction:The EPA's GWP phasedown timeline forces simultaneous R-134a and R-513A validation, doubling certification costs.
- Screw compressor substitution:Oil-injected screw systems below 500 tons capture projects where first-cost sensitivity overrides lifecycle efficiency.
Strategic Opportunities
- India cold chain expansion:The country's PLI scheme for food processing infrastructure creates demand for oil-free compressors in pharmaceutical and dairy applications.
- AI-driven predictive maintenance:Vibration sensor integration with cloud analytics platforms enables compressor-as-a-service revenue models.
- EU F-Gas Regulation alignment:CE marking requirements for lower-GWP refrigerants position early-compliant OEMs for Middle East re-export markets.
Industry Challenges
- Magnetic bearing field service scarcity:Technician certification for active magnetic bearing calibration remains limited to OEM-captive networks.
- Legacy control system integration:BACnet and Modbus protocol mismatches delay retrofit projects in 1990s-era district cooling plants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | HVAC Centrifugal Compressors Market |
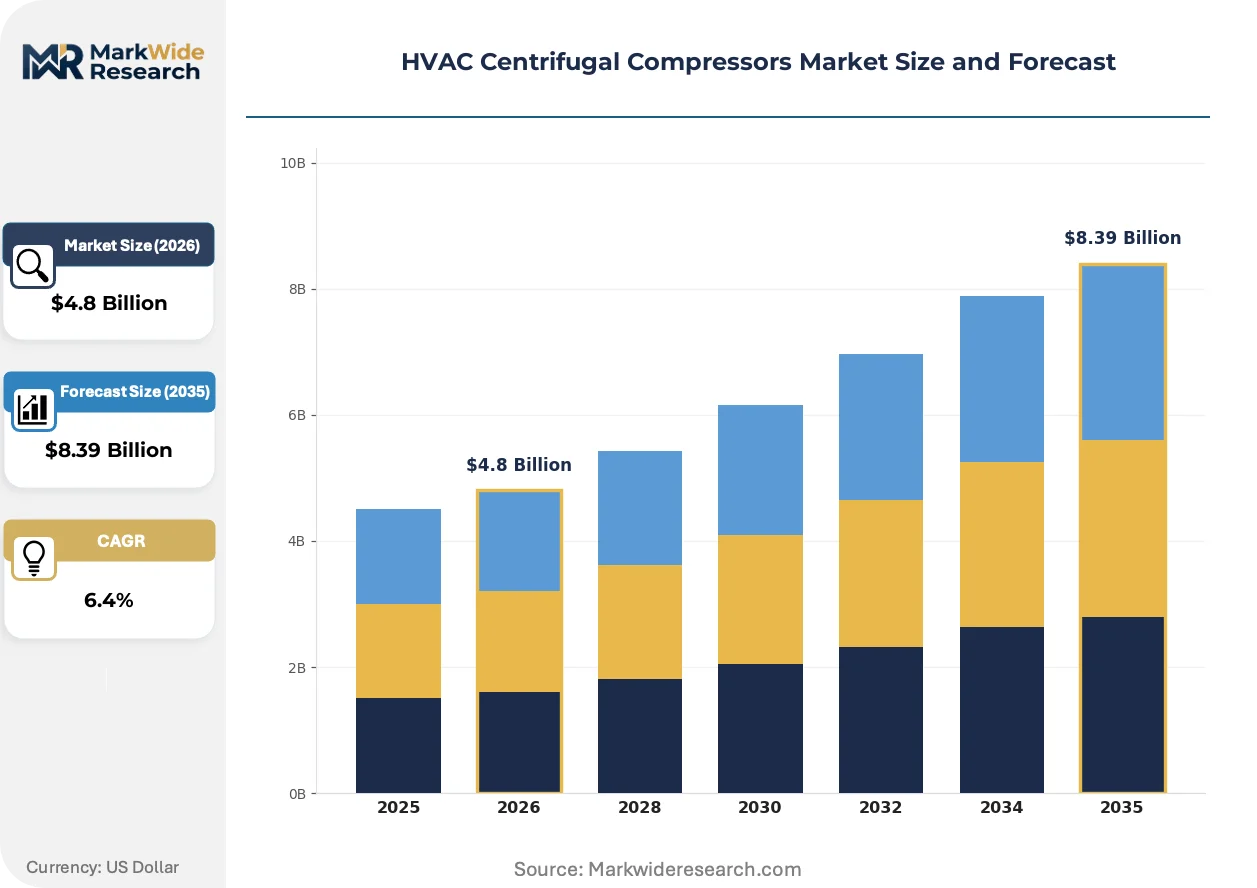
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Stage, Two-Stage, Multi-Stage, Oil-Free, Hermetic Technology: Variable Speed Drive, Magnetic Bearing, Air-Cooled, Water-Cooled, Direct Drive Application: Commercial Buildings, Data Centers, Cold Storage, Educational Complexes, Hospitality Facilities End User: Facility Management Companies, Industrial Plants, Government Buildings, Retail Chains, Warehousing Services |
| Companies Covered | Atlas Copco, Ingersoll Rand, Hitachi, Danfoss, Mitsubishi Heavy Industries, SKF, Howden Group, Elliott Group, Celeroton, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
HVAC Centrifugal Compressors Market Strategic Shifts & Innovations
Digital twin technology and refrigerant chemistry advances are compressing the gap between design-phase simulation and field performance, reducing warranty exposure for high-speed turbomachinery deployments.
Permanent magnet motor technology is converging with aerodynamic impeller redesigns to eliminate gearbox losses in variable-speed applications. Data center operators in Ashburn and Frankfurt specify these integrated drivetrains for part-load efficiency above 85%. The convergence is compressing market share for traditional induction motor configurations.
The EU F-Gas Regulation mandates 79% HFC reduction by 2030, forcing compressor OEMs to validate A2L mildly flammable refrigerants. Equipment redesigns for R-454B and R-455A are consuming 18-24 month certification cycles. European cold storage operators are front-loading replacement schedules to avoid 2027 supply bottlenecks.
Lifecycle service contracts are displacing equipment-only procurement in hyperscale data center tenders. Colocation providers in Singapore and Sydney now require ten-year performance guarantees with penalty clauses for energy degradation. This shifts vendor selection criteria from first cost to validated mean-time-between-failure data.
HVAC Centrifugal Compressors Market Segmentation
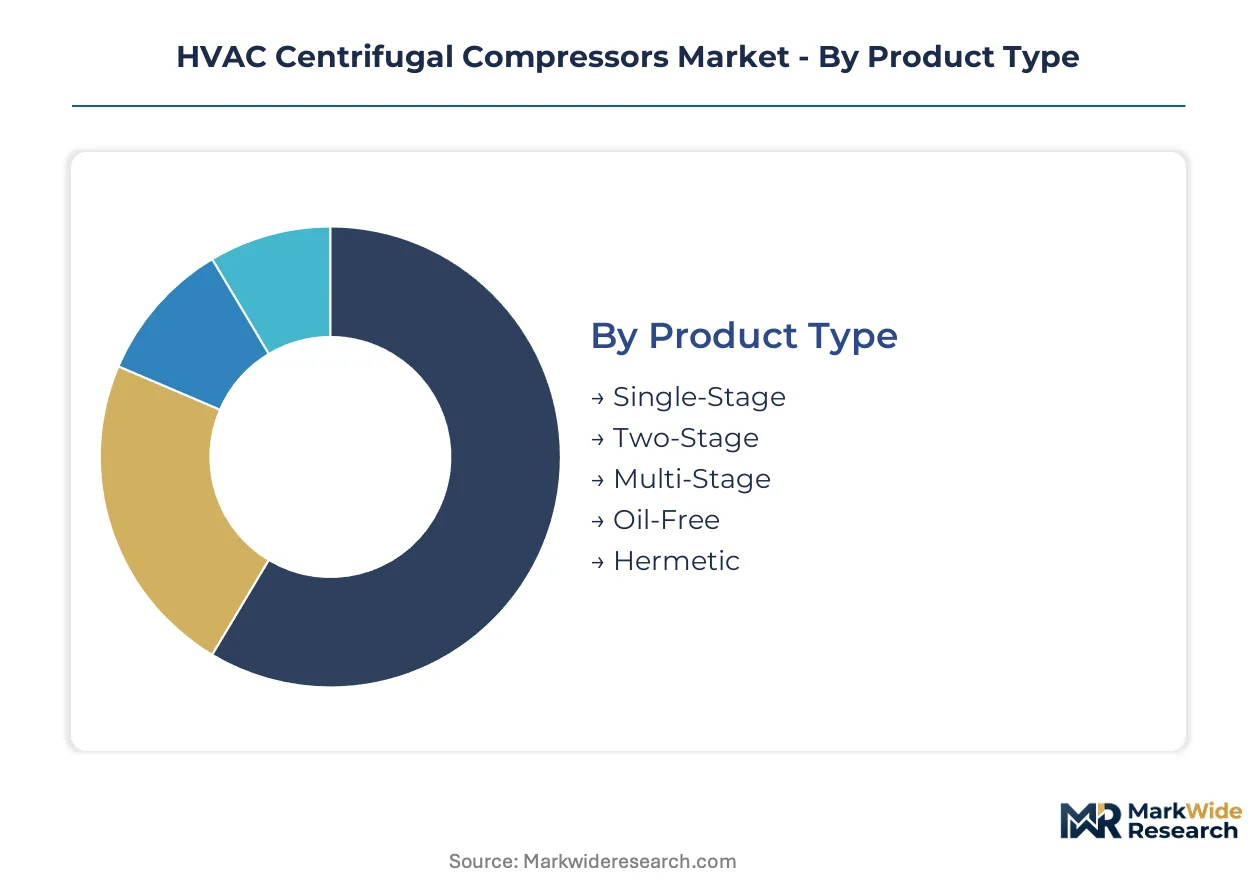
Centrifugal compressor procurement decisions split sharply between upfront capital constraints and lifecycle efficiency mandates. The segmentation below maps how technology choices, application requirements, and end-user procurement power reshape competitive positioning across product tiers.
Product Type:
Capital intensity varies dramatically across configurations, with magnetic bearing and oil-free systems demanding 40-60% higher first cost than fixed-speed alternatives.
- Single-Stage:Compact impeller designs achieve pressure ratios up to 3:1 for mid-rise commercial buildings. Demand concentrates in retrofit projects across Germany and Japan where footprint constraints override efficiency premiums.
- Two-Stage:Intercooling between impeller wheels lifts pressure ratios to 5:1 while trimming power consumption. Cold storage operators in India and Brazil specify these units for ammonia conversion projects under national refrigerant transition timelines.
- Multi-Stage:Three or more impeller stages deliver 8:1 pressure ratios for district cooling networks. Legacy installations across Saudi Arabia and the UAE dominate the installed base.
- Oil-Free:Elimination of lubricant contamination risk commands 25-35% price premiums. Semiconductor fabrication and pharmaceutical cleanrooms in South Korea and Switzerland drive specification.
- Hermetic:Sealed motor-compressor integration reduces refrigerant leakage risk. Small-scale commercial applications in Australia and Canada favor this configuration for simplified maintenance.
Multi-stage systems absorb the bulk of installed capacity; oil-free configurations are expanding most quickly.
Technology:
Technology selection tracks regulatory pressure on part-load efficiency, with variable speed and magnetic bearing systems capturing specification share as fixed-speed units face procurement disqualification.
- Variable Speed Drive:Inverter-controlled motor speed matches capacity to real-time cooling loads. Data center operators in Virginia and Singapore mandate VSD integration for ten-year energy performance guarantees.
- Magnetic Bearing:Active magnetic levitation eliminates mechanical contact and oil systems. Hyperscale cloud providers in Frankfurt and Sydney specify these for sub-1% degradation targets.
- Air-Cooled:Finned heat exchanger configurations eliminate cooling tower infrastructure. Water-scarce regions across Spain and Arizona default to this technology despite 15-20% efficiency penalties.
- Water-Cooled:Shell-and-tube condensers leverage evaporative cooling for peak efficiency. Coastal district cooling plants in Vietnam and Indonesia specify water-cooled systems for 10,000+ ton capacities.
- Direct Drive:Permanent magnet motor integration removes gearbox losses and maintenance points. New construction projects across Denmark and the Netherlands favor this simplified drivetrain architecture.
Variable speed drive technology anchors current volume; magnetic bearing systems command the steepest expansion trajectory.
Application:
Application segmentation reflects divergent reliability requirements, with data center and cold storage operators willing to absorb premium pricing for validated uptime performance.
- Commercial Buildings:Office towers and mixed-use developments specify 500-2,000 ton systems. Procurement in France and Italy emphasizes EU F-Gas compliance over efficiency optimization.
- Data Centers:Hyperscale facilities demand 99.999% cooling availability with real-time redundancy. Northern Virginia, Singapore, and Frankfurt clusters drive magnetic bearing adoption.
- Cold Storage:Temperature stability requirements span -30°C to +15°C zones. India's PLI scheme for food processing infrastructure is accelerating oil-free compressor deployment.
- Educational Complexes:K-12 and university campuses favor standardized maintenance protocols. Public procurement across Texas and Ontario prioritizes first-cost minimization.
- Hospitality Facilities:Hotels and resorts require acoustic attenuation for guest comfort. Coastal resorts in Thailand and Mexico specify hermetic configurations for corrosion resistance.
Commercial buildings retain the largest installed base; data center applications are climbing the fastest.
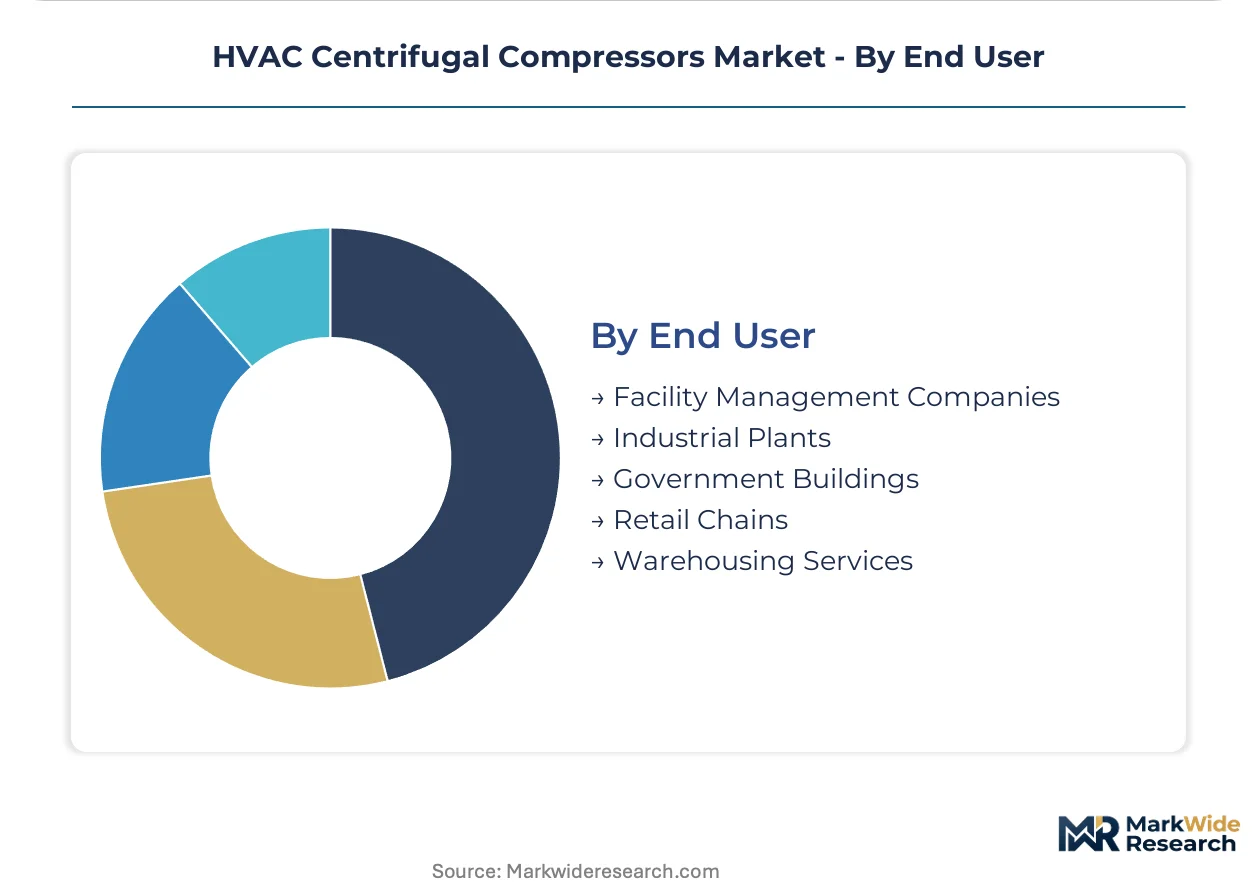
End User:
Procurement sophistication varies sharply across end-user categories, with facility management companies and industrial plants leveraging scale for lifecycle service contracts while retail chains prioritize first-cost minimization.
- Facility Management Companies:Integrated service providers bundle HVAC with electrical and security systems. Jones Lang LaSalle and CBRE specifications across the UK and Australia favor predictive maintenance integration.
- Industrial Plants:Petrochemical and automotive manufacturing demand 24/7 cooling continuity. BASF and Toyota facilities in Germany and Japan specify magnetic bearing systems for ten-year mean-time-between-failure guarantees.
- Government Buildings:Federal and municipal procurement faces 10 CFR 431 efficiency mandates. US General Services Administration tenders disqualify fixed-speed units from awards above $10 million.
- Retail Chains:Big-box and grocery networks prioritize standardized equipment for national maintenance contracts. Walmart and Carrefour procurement across the US and France emphasizes part commonality.
- Warehousing Services:Third-party logistics providers face seasonal load volatility. Prologis and GLP facilities in China and the Netherlands specify variable speed systems for demand-responsive capacity.
Industrial plants anchor premium technology demand; facility management companies are gaining share fastest through bundled service contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Northern Virginia's data center corridor drives magnetic bearing compressor specification as hyperscale operators demand ten-year energy performance guarantees. Frankfurt and Singapore clusters enforce identical reliability standards. China's manufacturing scale for magnetic bearing stator assemblies supplies global OEM requirements.
United States
The DOE's 10 CFR 431 efficiency mandates disqualify fixed-speed units from federal procurement above ten million dollars. Northern Virginia's Ashburn data center cluster specifies magnetic bearing systems for sub-1% degradation targets. EPA's AIM Act refrigerant phasedown compresses R-513A validation timelines.
China
Magnetic bearing compressor manufacturing concentrates in Jiangsu and Zhejiang provinces for neodymium processing integration. The country's dual carbon goals accelerate variable speed drive adoption in district cooling networks. Shanghai's commercial construction pipeline specifies multi-stage systems for 10,000+ ton capacities.
Germany
EU F-Gas Regulation mandates 79% HFC reduction by 2030, forcing A2L refrigerant validation cycles. BASF facilities in Ludwigshafen specify magnetic bearing compressors for ten-year mean-time-between-failure guarantees. Frankfurt's data center cluster matches Northern Virginia's reliability specifications.
India
The PLI scheme for food processing infrastructure accelerates oil-free compressor deployment in pharmaceutical and dairy cold chains. Cold storage operators in Maharashtra and Gujarat specify two-stage systems for ammonia conversion projects. BIS efficiency standards tighten part-load performance requirements.
Singapore
Colocation providers mandate ten-year performance guarantees with penalty clauses for energy degradation. The tropical climate drives water-cooled system specification for 10,000+ ton district cooling networks. Jurong Island's industrial complex anchors premium technology demand from petrochemical operators.
HVAC Centrifugal Compressors Market Key Industry Players
Premium-margin players sit above commodity-margin players across technology tiers, with magnetic bearing specialists commanding 40-60% first-cost premiums over fixed-speed alternatives. The vendor base consolidates around three strategic archetypes: integrated building automation providers, oil-free compressor specialists, and magnetic bearing technology leaders. Capacity expansion in Chinese neodymium processing facilities and strategic partnerships for lifecycle service contracts represent the dominant competitive moves.
Among diversified industrial conglomerates, Atlas Copco and Ingersoll Rand occupy positions spanning multiple technology tiers, while Hitachi represents the integrated electronics-to-HVAC vertical. These three companies exemplify contrasting strategic postures: Atlas Copco anchors oil-free reliability contracts, Ingersoll Rand bundles building automation with hardware, and Hitachi leverages permanent magnet motor integration across variable-speed applications.
| Leading Market Players |
|---|
| Atlas Copco |
| Ingersoll Rand |
| Hitachi |
| Danfoss |
| Mitsubishi Heavy Industries |
| SKF |
| Howden Group |
| Elliott Group |
| Celeroton |
| Others |
Cost & Logistics Intelligence
The EPA's AIM Act refrigerant phasedown gates qualified supply and premium-tier pricing access, as compressor OEMs must validate lower-GWP chemistries before bidding on federal and hyperscale data center tenders. This regulatory filter separates certified suppliers from commodity players while concentrating pricing power among early-compliant manufacturers.
Pricing Analysis
Ten-year energy performance guarantees anchor value-based pricing for magnetic bearing systems, with hyperscale operators in Northern Virginia and Singapore accepting 40-60% first-cost premiums for sub-1% degradation commitments. Price differentiation rests on certification grade for A2L refrigerant compatibility and magnetic bearing field service coverage. Cost compression in fixed-speed tiers is intensifying because DOE efficiency mandates disqualify these units from federal procurement above ten million dollars. Retail chains and educational complexes exhibit highest price sensitivity, while data center operators prioritize lifecycle efficiency over acquisition cost.
Supply Chain Analysis
Regional distribution centers in Rotterdam and Singapore coordinate hub-and-spoke patterns for magnetic bearing stator assemblies and variable speed drive components. Manufacturing gravity centers on China for neodymium processing integration, Germany for precision impeller machining, and the United States for final assembly serving federal procurement. Raw material dependencies include rare earth elements for magnetic bearings, copper for motor windings, and specialized steel alloys for impeller castings. Single-source vulnerability in Chinese neodymium supply chains poses structural risk amid export licensing uncertainties. Distribution runs through OEM-captive service networks for magnetic bearing calibration and aftermarket parts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EPA's AIM Act creates a barrier-to-entry moat for compliant players, as refrigerant validation cycles and efficiency certification investments strain undercapitalized competitors. This cost-of-compliance dynamic rewards early movers with pricing power in restricted procurement channels.
For Market Incumbents: Deepen captive service network coverage for magnetic bearing field calibration, as technician scarcity locks out independent competitors from hyperscale maintenance contracts. Expand in-house production of neodymium-bearing stator assemblies to offset Chinese supply concentration risk. Oil-injected screw compressor substitution below 500 tons threatens volume in first-cost-sensitive segments; defend through lifecycle service bundling that extends contract duration. For New Entrants and Emerging Players: Facility management companies present the most penetrable channel partner type, as their integrated service contracts bundle HVAC with electrical and security systems and prioritize predictive maintenance integration. Target India's PLI scheme for food processing infrastructure, where oil-free compressor demand outpaces established supplier capacity. Cold storage operators in Maharashtra and Gujarat offer white-space entry through ammonia conversion project specifications. Lead with AI-driven predictive maintenance platforms that enable compressor-as-a-service revenue models without requiring full manufacturing scale. For Investors and Strategic Acquirers: Ten-year performance guarantee penetration in Singapore colocation tenders is the leading indicator that lifecycle service contracting has crossed from premium niche to procurement standard. The long-term viability window favors vertically integrated players controlling magnetic bearing technology and refrigerant validation capabilities. Acquisition target archetype: mid-cap specialists with A2L refrigerant certification and established hyperscale customer relationships. Monitor BIS efficiency standard tightening in India as inflection signal for regional supply consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Magnetic Bearing Technology Licensing | Enables OEMs to bypass 18-24 month R&D cycles for active levitation systems. |
| Backward Integration into Neodymium Processing | Reduces exposure to Chinese export licensing volatility for rare earth supply. |
| A2L Refrigerant Validation Partnership | Accelerates certification timelines for R-454B and R-455A compatibility testing. |
| Predictive Maintenance Platform Acquisition | Captures compressor-as-a-service revenue from facility management contracts. |
| District Cooling Network Joint Venture | Locks in multi-stage system demand for 10,000+ ton capacity requirements in Vietnam and Indonesia. |
Research Approach
Trade association filings, customs and import-export records, and DOE efficiency certification databases formed the secondary backbone for this analysis. Primary interviews with compressor OEM product managers, data center facility engineers, cold storage procurement leads, and magnetic bearing field service technicians combined with secondary validation to triangulate market sizing. Bottom-up unit deployment estimates across commercial buildings, data centers, and cold storage applications were cross-checked against top-down equipment manufacturer revenue analysis.
Bottom-up modeling segmented the market by product type, technology configuration, application vertical, and end-user procurement sophistication across the projection horizon. CAGRs were derived from regression analysis of historical efficiency standard adoption curves and refrigerant transition timelines. Industry-specific forecast inputs included hyperscale data center capex disclosures, district cooling network project pipelines, and national cold chain infrastructure investment schemes.
Several conditions sit outside the modeled scope, including unannounced refrigerant chemistry breakthroughs, abrupt rare earth export restrictions, and accelerated efficiency mandate timelines. Forecasts reflect stated assumptions around regulatory implementation schedules and technology adoption rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Equipment for HVAC Market
HVAC Equipment
Wall Hung Boilers Market
HVAC Equipment
Global Industrial Fans and Blowers Market
HVAC Equipment
Global Industrial Air Chiller Market
HVAC Equipment
Middle-East and Africa Compressor Market
HVAC Equipment
Industrial Chiller Market
HVAC Equipment
North America Residential Heat Pump Market
HVAC Equipment
Refrigeration and Air Conditioning Compressors Market
HVAC Equipment
Air-Conditioning Natural Convection Refrigerator Market
HVAC Equipment
Screw Compressor Market
HVAC Equipment
Refrigerant Compressors Market
HVAC Equipment
Air Handlers Market
HVAC Equipment
Europe HVAC Market
HVAC Equipment
Air Humidifier and Dehumidifier Market
HVAC Equipment
Ceiling Cassettes Market
HVAC Equipment
North America Heat Exchanger Market