
 Swing Compressor Market | 2026-2036
Swing Compressor Market Size, Share, and Industry Trends Forecast 2026-2036
Swing Compressor Market Analytics
Commercial facility managers is collapsing as a buyer archetype while residential HVAC contractors gain procurement share in the swing compressor channel. Daikin Industries leverages captive inverter technology to anchor premium residential demand across East Asian markets. Panasonic competes through deep manufacturing scale in rotary swing architectures for compact cooling systems. Hanbell Precise Machinery specializes in screw-type variants for industrial processing clients in China.
A swing compressor employs an orbiting scroll or piston mechanism driven by a crankshaft with minimal radial clearance, achieving volumetric efficiency above 90 percent through continuous gas compression without valve losses. Its primary purpose centers on refrigerant circulation in vapor-compression cycles for climate control and industrial cooling. Rotary swing configurations lead unit shipments in residential air conditioning, while screw-type systems command the margin pool in oil and gas processing applications. Variable-speed technology is gaining fastest in food and beverage refrigeration, where digital control systems reduce energy draw during partial-load operation.
Japan's METI enforces Top Runner standards that mandate minimum coefficient-of-performance thresholds for residential air conditioners, directly shaping compressor efficiency requirements. China's GB standards and NMPA-equivalent quality certifications govern manufacturing access for rotary units sold into domestic HVAC supply chains. The EU F-Gas Regulation and REACH compliance frameworks restrict refrigerant choices, forcing redesigns of compressor sealing and lubrication systems. Stakeholders must monitor how refrigerant-phase-down timelines will reshape compressor displacement specifications and material compatibility across major supply bases.
Market Dynamics
The residential HVAC contractor segment is consolidating procurement authority as India's BIS energy-efficiency mandates force rapid displacement of fixed-speed compressor inventories across South Asian supply chains.
Growth Catalysts
- Rotary swing architectures:Compact cooling systems in urban residential construction are absorbing precision-manufactured rotary units at accelerating rates, particularly in high-density East Asian housing developments.
- EU F-Gas Regulation:Refrigerant-phase-down timelines are compelling compressor redesigns that favor low-displacement, high-efficiency swing mechanisms compatible with next-generation synthetic refrigerants.
- Food and beverage cold chain expansion:Variable-speed digital control systems are penetrating industrial refrigeration as energy costs force partial-load optimization across processing and distribution facilities.
Market Restraints
- Copper and rare-earth magnet volatility:Permanent magnet materials for inverter-driven motors face price instability that compresses margin structures for variable-speed unit manufacturers.
- German and Japanese supply concentration:Precision scroll machining capabilities remain captive to a narrow supplier base, creating bottleneck risk for OEMs seeking dual-source qualification.
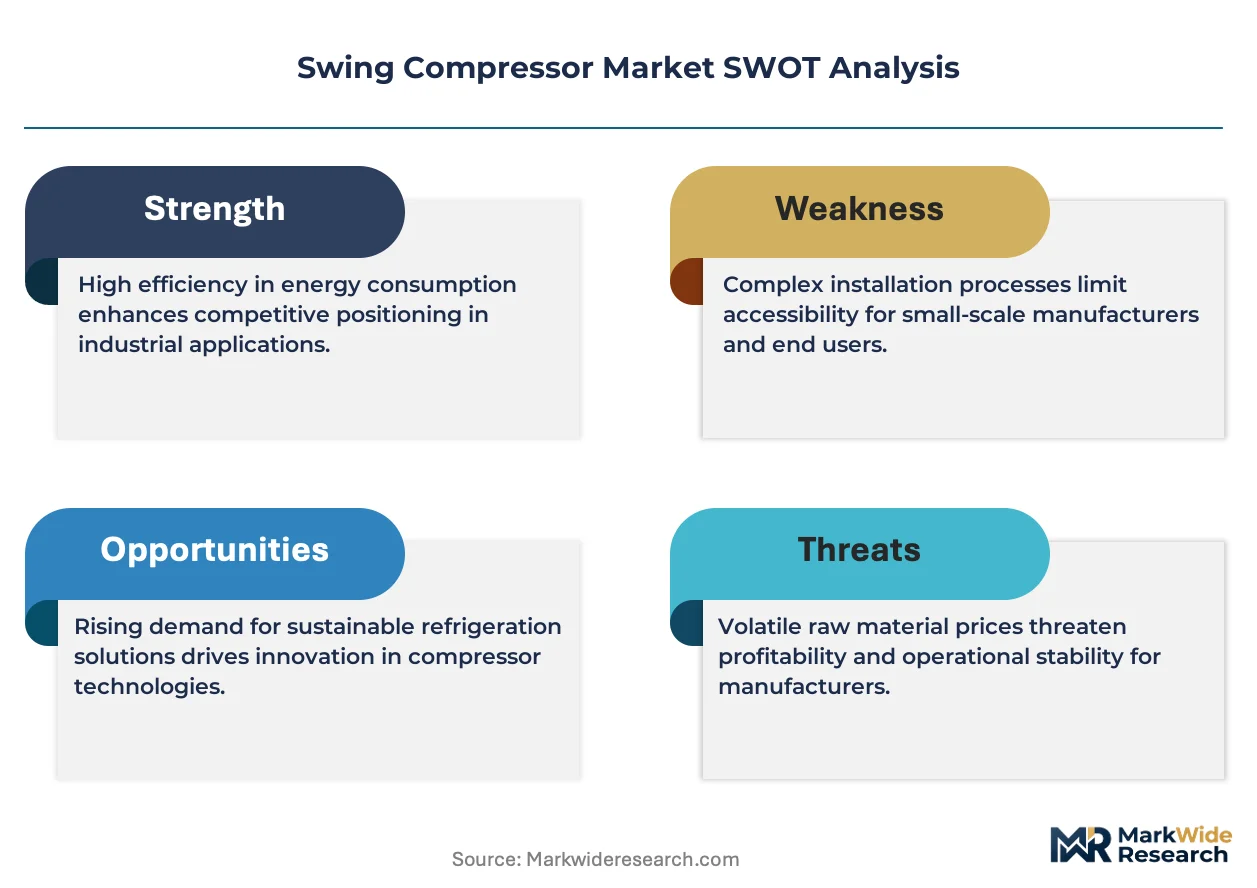
- Displacement ceiling in heavy industrial cooling:Swing mechanisms face technical boundaries above 50kW refrigeration load, ceding large-scale process cooling to centrifugal alternatives.
Strategic Opportunities
- India's BIS mandate enforcement:Tier-2 and Tier-3 city HVAC retrofits present untapped volume for inverter-compatible swing compressors as efficiency standards tighten beyond metropolitan enforcement zones.
- Heat pump convergence:Swing compressors optimized for reversible vapor-compression cycles are capturing share in residential heating applications as natural gas substitution accelerates.
- Direct contractor distribution:Bypassing traditional wholesaler networks through B2B platforms is unlocking margin recovery for manufacturers serving fragmented residential installation bases.
Industry Challenges
- Scroll profile grinding specialization:The precision machining workforce capable of sub-micron tolerance orbiting scroll production remains geographically concentrated and resistant to rapid scaling.
- Refrigerant compatibility certification:Compressor sealing and lubrication system validation for emerging low-GWP refrigerants extends product development timelines by 18-24 months.
- Legacy fixed-speed inventory absorption:Channel partners face working capital strain from stranded stock as regulatory deadlines accelerate obsolescence.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Swing Compressor Market |
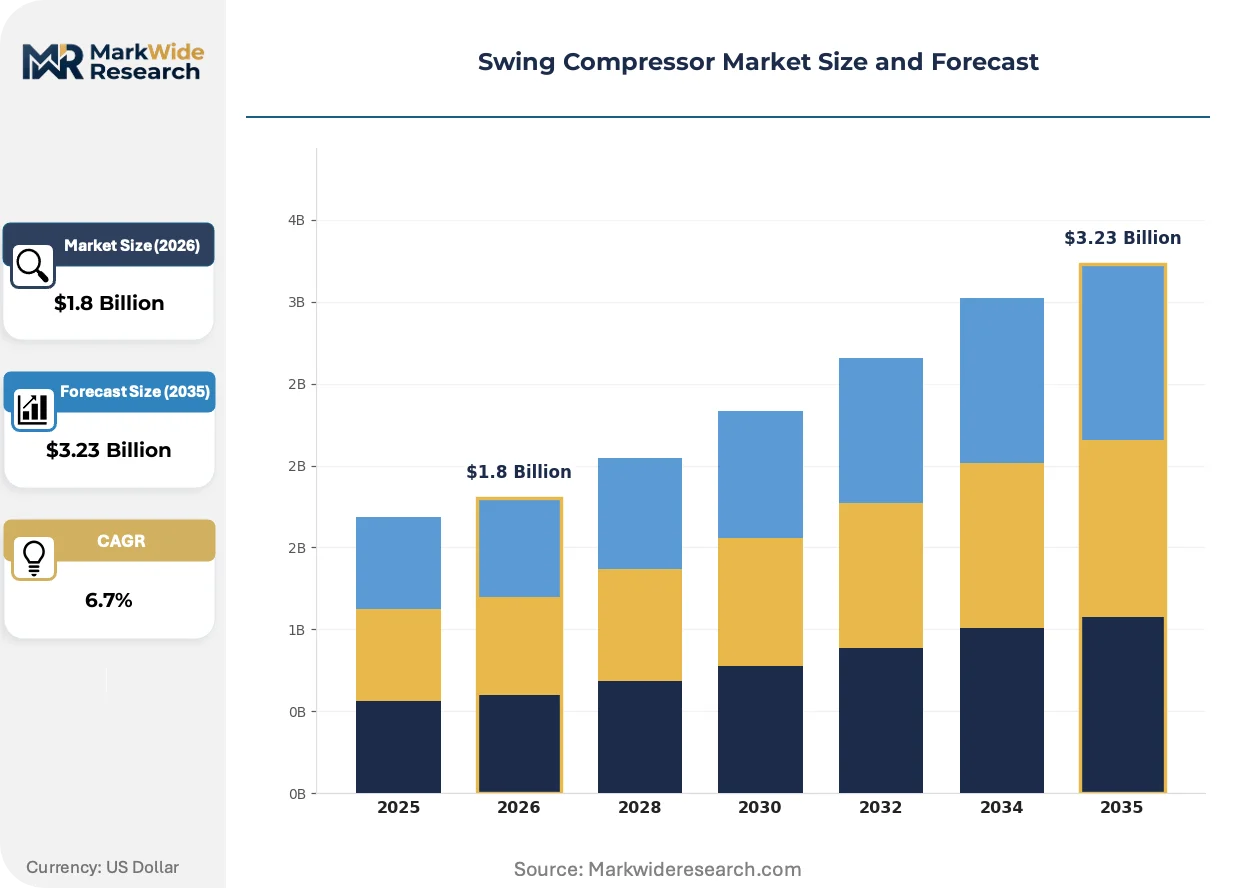
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reciprocating, Rotary, Screw, Centrifugal Application: Refrigeration, Air Conditioning, Automotive, Industrial Processing End User: Food & Beverage, Pharmaceuticals, Manufacturing, Oil & Gas Technology: Digital Control, Variable Speed, Compressors with IoT, Turbocharged |
| Companies Covered | Daikin Industries, Copeland, Hanbell Precise Machinery, Panasonic, Mitsubishi Electric, Danfoss, Bitzer, Emerson Electric, Johnson Controls, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Swing Compressor Market Evolving Landscape
Digital inverter control systems are fragmenting traditional compressor performance tiers as real-time modulation capabilities blur distinctions between residential and light-commercial product categories.
Permanent magnet synchronous motor technology is fragmenting efficiency benchmarks across the residential air conditioning segment. Japanese and South Korean OEMs are embedding magnet materials into compact rotor designs that enable 30-100Hz operating ranges without mechanical losses. This capability compression is collapsing the premium-mid-economy segmentation that historically organized compressor procurement.
China's GB standards for rotary compressor efficiency are tightening test-condition requirements that previously allowed laboratory-optimized ratings. The MIIT enforcement framework now mandates seasonal performance calculations that expose real-world degradation in fixed-speed units. Domestic HVAC manufacturers are responding by accelerating inverter platform commonization across product lines.
Residential contractors are consolidating specification authority previously dispersed among consulting engineers and facility managers. Direct manufacturer relationships are displacing traditional distribution tiers as digital quoting platforms enable real-time configuration and logistics transparency. This channel compression is most visible in China's Pearl River Delta and Japan's Kanto region, where contractor networks have achieved sufficient scale to negotiate captive supply arrangements.
Swing Compressor Market Segmentation
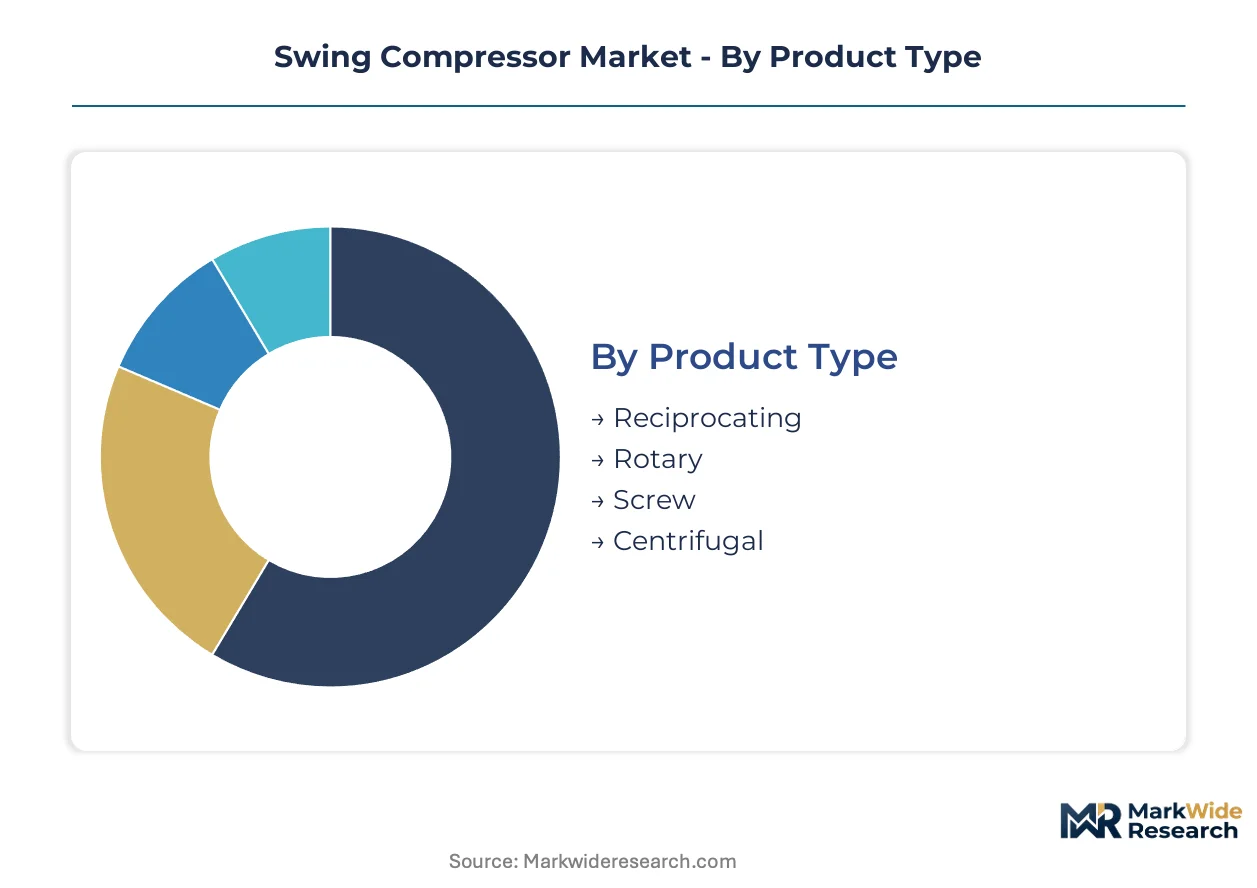
Swing compressor procurement patterns diverge sharply across product architectures and end-use applications. Each segment faces distinct substitution pressures from alternative compression technologies and regulatory compliance requirements.
Product Type:
Rotary mechanisms confront the most intense substitution threat from scroll compressors in residential cooling, while screw-type units defend niche positions in heavy industrial applications.
- Rotary:Orbiting piston designs achieve volumetric efficiency above 90 percent through continuous gas compression without valve losses. Demand concentrates in East Asian residential air conditioning where China's GB standards and Japan's METI Top Runner mandates force rapid displacement of fixed-speed alternatives.
- Screw:Twin-rotor positive displacement systems handle oil and gas processing loads above 50kW where swing mechanisms face technical boundaries. German and Japanese precision machining capabilities remain captive to a narrow supplier base, creating bottleneck risk for OEM qualification.
- Reciprocating:Piston-driven architectures with valve-actuated compression cycles dominate legacy commercial refrigeration retrofits.
- Centrifugal:Dynamic compression systems using impeller acceleration capture utility-scale process cooling above 500kW refrigeration load.
Rotary compressors anchor the volume base while screw-type configurations gain share at the steepest rate in industrial processing applications.
Application:
Cost tier stratification separates premium inverter-driven climate control from economy fixed-speed installations across residential and commercial building stock.
- Air Conditioning:Vapor-compression cycles for space cooling dominate unit shipments. India's BIS energy-efficiency mandates are forcing rapid displacement of fixed-speed inventories across Tier-2 and Tier-3 city HVAC retrofits.
- Refrigeration:Cold chain applications for food and beverage processing absorb variable-speed digital control systems as energy costs force partial-load optimization. EU F-Gas Regulation refrigerant-phase-down timelines compel compressor redesigns for low-GWP synthetic compatibility.
- Automotive:Electric vehicle thermal management systems require compact, high-reliability compression for battery and cabin conditioning.
- Industrial Processing:Manufacturing facility cooling and compressed air systems demand continuous-duty operation with minimal maintenance intervals.
Air conditioning commands the installed base while refrigeration applications expand most quickly as cold chain infrastructure proliferates.
End User:
Customer type determines specification authority consolidation patterns, with residential contractors displacing traditional engineering consultants.
- Food & Beverage:Cold chain operators from processing through distribution prioritize energy draw reduction during partial-load operation. Variable-speed penetration is accelerating fastest in this segment as digital control systems enable real-time modulation.
- Manufacturing:Facility managers in precision electronics and automotive component plants specify compressor reliability above efficiency metrics.
- Pharmaceuticals:GMP-validated temperature control systems require redundant compression with continuous monitoring documentation.
- Oil & Gas:Upstream processing and LNG liquefaction facilities specify heavy-duty screw and centrifugal alternatives above swing mechanism displacement ceilings.
Food and beverage end users anchor procurement volume while manufacturing specifications climb the fastest as production facility HVAC retrofits accelerate.
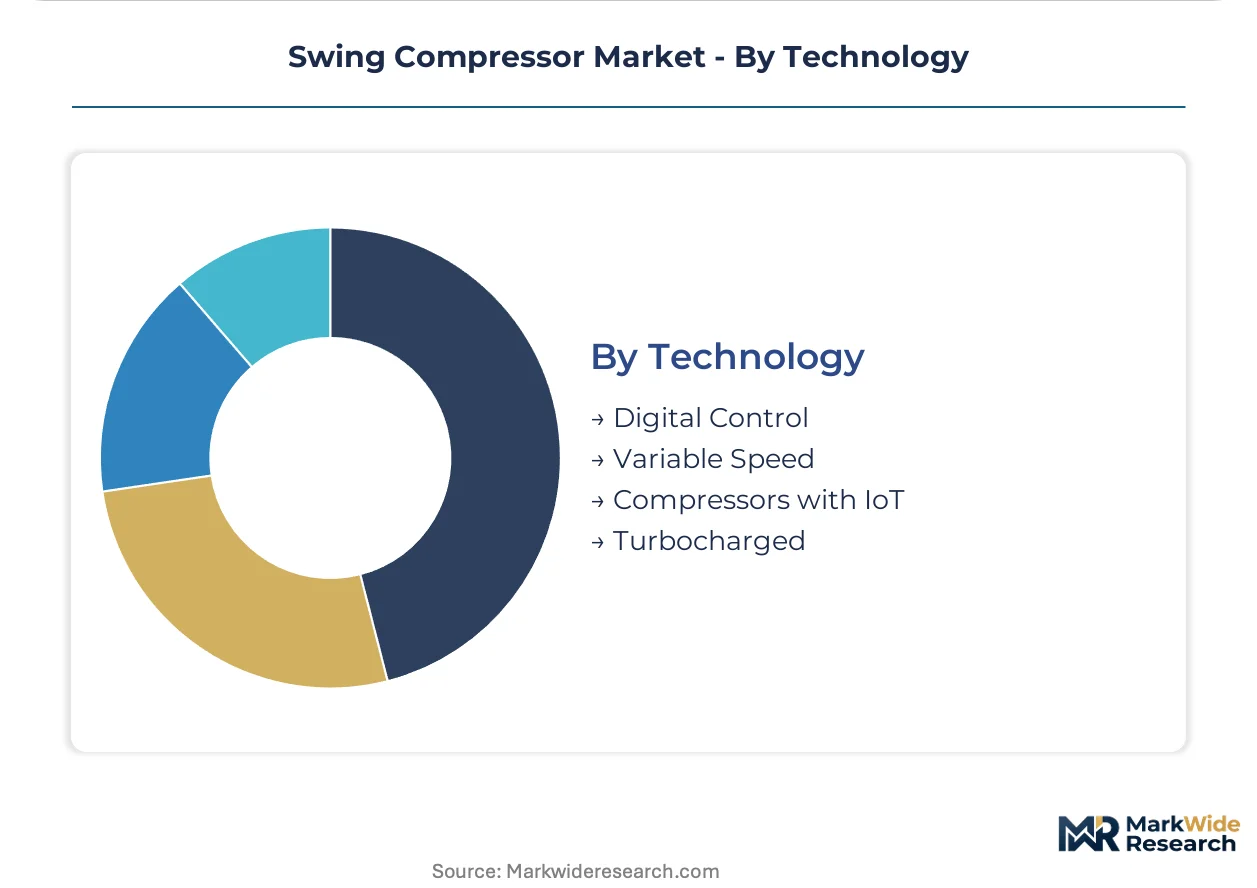
Technology:
Supply concentration in permanent magnet materials and precision inverter electronics shapes competitive positioning across technology tiers.
- Variable Speed:Inverter-driven motor control enables 30-100Hz operating ranges without mechanical losses. Residential HVAC contractors in China and Japan are consolidating procurement authority for these systems as digital quoting platforms displace traditional distribution tiers.
- Digital Control:Real-time modulation capabilities blur historical distinctions between residential and light-commercial product categories. Embedded sensor networks enable predictive maintenance and energy optimization algorithms.
- Compressors with IoT:Connected device architectures transmit operational data to cloud-based monitoring platforms for fleet management.
- Turbocharged:Forced induction compression enhancement improves mass flow rates in specialized industrial applications.
Variable speed technology anchors manufacturer revenue while digital control integration gains share at the steepest rate across premium product tiers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan exports precision-manufactured scroll components to German industrial compressor assemblers, while China supplies rotary units across South Asian residential HVAC retrofit channels.
China
Urban residential construction in the Pearl River Delta absorbs precision-manufactured rotary swing units at accelerating rates. MIIT enforcement of GB standards mandates seasonal performance calculations that expose real-world degradation in fixed-speed units. Domestic HVAC manufacturers in Guangdong province are accelerating inverter platform commonization across product lines.
Japan
Residential contractors in the Kanto region consolidate procurement authority for variable-speed systems through direct manufacturer relationships. METI Top Runner standards enforce minimum coefficient-of-performance thresholds for residential air conditioners. Daikin Industries leverages captive inverter technology to anchor premium residential demand across East Asian markets.
Germany
Industrial processing facilities specify screw-type swing compressors for oil and gas applications above 50kW refrigeration load. EU F-Gas Regulation and REACH compliance frameworks restrict refrigerant choices, forcing redesigns of compressor sealing systems. Precision scroll machining capabilities remain concentrated in Baden-Württemberg industrial clusters.
India
Tier-2 and Tier-3 city HVAC retrofits present untapped volume for inverter-compatible swing compressors as efficiency standards tighten beyond metropolitan enforcement zones. BIS energy-efficiency mandates force rapid displacement of fixed-speed compressor inventories across South Asian supply chains. Residential HVAC contractors in Maharashtra and Gujarat are shifting procurement toward variable-speed units.
South Korea
Permanent magnet synchronous motor technology fragments efficiency benchmarks across residential air conditioning segments. MFDS-equivalent quality certifications govern manufacturing access for components sold into domestic HVAC supply chains. Seoul Capital Area contractors achieve sufficient scale to negotiate captive supply arrangements with compressor manufacturers.
Swing Compressor Market Competitive Landscape
Player mix skews toward diversified industrial conglomerates with captive compressor divisions and specialized precision-machining fabricators. Market structure consolidates around Japanese and German engineering groups with vertical control over scroll production. Two strategic archetypes dominate: integrated climate-control OEMs with in-house compressor manufacturing, and independent component specialists serving fragmented installation bases. Competitive moves center on inverter technology licensing partnerships and direct-to-contractor distribution platform investments.
Among Japanese industrial conglomerates, Daikin Industries and Mitsubishi Electric occupy positions within the integrated OEM archetype, exemplifying captive supply chain control over compressor and system manufacturing. Panasonic sits within the precision-component specialist tier, representing manufacturing scale in compact cooling architectures. These three companies anchor the competitive structure through differentiated approaches to technology control and channel access.
| Leading Market Players |
|---|
| Daikin Industries |
| Copeland |
| Hanbell Precise Machinery |
| Panasonic |
| Mitsubishi Electric |
| Danfoss |
| Bitzer |
| Emerson Electric |
| Johnson Controls |
| Others |
Value Network & Pricing Analysis
Ninety-day scroll machining lead times from Baden-Württemberg suppliers concentrate pricing power among German and Japanese incumbents, while copper and rare-earth magnet volatility compresses margin structures for variable-speed unit manufacturers seeking dual-source qualification.
Pricing Analysis
Fixed-speed versus variable-speed versus next-generation inverter-integrated compressors stratify across premium, standard, and economy tiers. Price differentiation hinges on GB standard certification grade and permanent magnet motor integration level. Cost compression in economy fixed-speed tiers is intensifying because India's BIS mandate deadlines accelerate obsolescence. Residential HVAC contractors exhibit highest price sensitivity, while oil and gas processing facilities prioritize reliability over unit economics.
Supply Chain Analysis
Container availability constraints on the Shanghai-Rotterdam trade lane amplify inbound logistics costs for precision-machined scroll components. Manufacturing gravity centers on China, Japan, and Germany for rotary and screw-type architectures. Supply chains draw from copper winding stock, neodymium permanent magnets, and synthetic refrigerant formulations. Single-source vulnerability in sub-micron tolerance scroll grinding creates bottleneck risk. Distribution runs through direct manufacturer-contractor platforms displacing traditional wholesale tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Swing compressor incumbents face substitution pressure from centrifugal systems above 50kW refrigeration load, requiring defensive positioning across technology tiers and channel structures.
For Market Incumbents: Consolidate captive inverter technology control through backward integration into permanent magnet motor production. Deepen scroll machining specialization in Baden-Württemberg clusters to defend against Japanese precision-component competition. Lock in direct distribution relationships with Pearl River Delta and Kanto region contractor networks before platform commoditization accelerates.
For New Entrants and Emerging Players: Anchor in Tier-2 and Tier-3 Indian city HVAC retrofits where BIS enforcement creates vacuum for inverter-compatible supply. Target food and beverage cold chain applications where variable-speed penetration lags behind air conditioning saturation. Pursue white-label manufacturing partnerships with domestic HVAC OEMs in Guangdong province lacking captive compressor capability.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underperforming climate-control divisions and stranded fixed-speed compressor inventories. Five-to-ten year viability rests on refrigerant compatibility certification pipelines and digital control system integration depth. Monitor EU F-Gas Regulation phase-down enforcement velocity as inflection indicator for displacement specification demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Inverter Platform Commonization | Accelerates GB standard compliance across Guangdong manufacturer product lines. |
| Direct-to-Contractor Distribution | Bypasses wholesale tiers for margin recovery in fragmented residential installation bases. |
| Refrigerant Compatibility Certification | Validates sealing and lubrication systems for EU F-Gas synthetic refrigerant mandates. |
| Permanent Magnet Supply Agreement | Secures neodymium access against rare-earth price volatility for variable-speed production. |
| Scroll Machining Capacity Expansion | Relieves bottleneck risk in sub-micron tolerance orbiting component supply. |
Research Methodology
Initial hypotheses were tested against primary input from HVAC contractor procurement heads, compressor OEM platform engineers, refrigeration system integrators, and BIS regulatory compliance officers and refined through secondary validation against MIIT enforcement bulletins, METI Top Runner standard filings, EU ECHA refrigerant registration databases, and customs trade flow records. Bottom-up shipment estimates triangulated against top-down manufacturer capacity disclosures.
Variance decomposition isolates technology substitution effects, regulatory compliance cost pass-through, and channel structure shifts across the projection horizon. Segmentation dimensions modeled include compressor architecture type, end-use application tier, control technology integration level, and regional regulatory cluster. CAGRs derive from unit shipment trajectories weighted by average selling price evolution and input cost indices.
Material uncertainties — refrigerant-phase-down timeline acceleration, rare-earth export restriction implementation, and contractor platform consolidation velocity — sit outside the modeled envelope. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
North America Residential Heat Pump Market
HVAC Equipment
Linear Slot Diffuser Market
HVAC Equipment
Shell and Tube Heat Exchangers Market
HVAC Equipment
Industrial Heating Equipment Market
HVAC Equipment
France HVAC Market
HVAC Equipment
Global Snow Making System Market
HVAC Equipment
Europe HVAC Market
HVAC Equipment
Compact Fan Coils Market
HVAC Equipment
Global HVAC Packaged Unit Market
HVAC Equipment
HVAC Louvers Market
HVAC Equipment
Mexico Compressed Air Treatment Equipment Market
HVAC Equipment
Global Large-Scale Natural Refrigerant Heat Pump Market
HVAC Equipment
Duct Fans Market
HVAC Equipment
Europe Residential Fan Coil Convectors Market
HVAC Equipment
Air Conditioner Quilt Market
HVAC Equipment
Europe Heat Exchanger Market