
 US HVAC Services Market | 2026-2036
US HVAC Services Market Size, Share, and Industry Trends Forecast 2026-2036
US HVAC Services Market Outlook
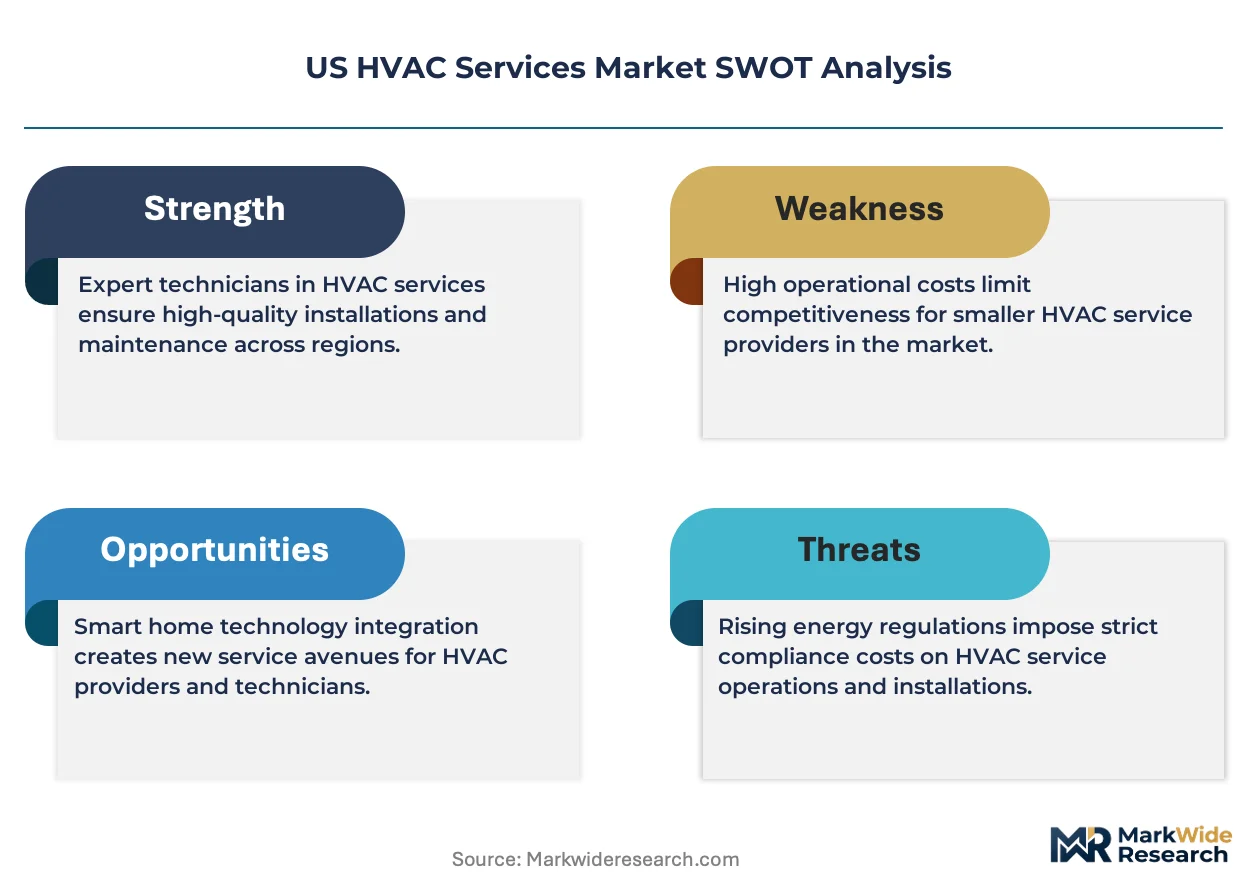
Commercial real estate ownership is consolidating among institutional investors and REITs, which is consolidating procurement power across multi-site portfolios. Carrier Global leverages national service networks to anchor long-term facilities management contracts. Trane Technologies competes on predictive maintenance platforms that reduce downtime for centralized cooling plants. Johnson Controls International specializes in building automation integration, extending its reach beyond equipment into energy-as-a-service models.
US HVAC services encompass the installation, maintenance, repair, and replacement of climate control systems operating on vapor-compression cycles, typically using R-410A or emerging A2L refrigerants with global warming potentials below 750. These systems maintain indoor air temperature, humidity, and ventilation rates within ASHRAE-specified ranges for occupant health and equipment protection. Maintenance and repair command recurring revenue streams with higher margin stability than installation, which fluctuates with construction cycles. Smart HVAC solutions are gaining traction as building operators deploy IoT sensors and cloud-based diagnostics to optimize energy consumption across distributed portfolios.
EPA regulations under the AIM Act mandate phased reductions of hydrofluorocarbon refrigerants, forcing service providers to certify technicians on alternative chemistries and recovery protocols. DOE appliance efficiency standards and state-level building codes, particularly California Title 24, ratchet minimum performance thresholds for replacement equipment. FERC demand-response rules also shape market access for providers offering grid-interactive thermal storage. Stakeholders must monitor refrigerant supply chain transitions and technician certification bottlenecks as compliance deadlines compress implementation timelines.
Market Dynamics
The AIM Act refrigerant phase-down is compressing service timelines and forcing wholesale technician retraining across the Sun Belt, where cooling-dominated load profiles amplify infrastructure strain.
Growth Catalysts
- EPA refrigerant mandates:The phased HFC reductions under AIM Act are accelerating equipment replacement cycles and expanding certified service demand.
- Institutional portfolio consolidation:REITs and private equity owners are bundling multi-site maintenance contracts, concentrating procurement power and favoring national service networks.
- Grid-interactive thermal storage:FERC demand-response rules are opening revenue streams for providers offering load-shifting capabilities to utilities.
Market Restraints
- Technician certification bottlenecks:EPA Section 608 and new A2L safety certifications are constraining qualified labor supply during peak demand windows.
- Refrigerant supply concentration:Domestic production capacity for low-GWP alternatives remains concentrated among limited chemical suppliers, creating price volatility risk.
- Legacy equipment interoperability:Building automation retrofits face technical friction when integrating with pneumatic control systems common in pre-2000 commercial stock.
Strategic Opportunities
- Texas and Florida sub-markets:Cooling-degree-day intensity and aging infrastructure in these states are expanding preventive maintenance contract penetration.
- Energy-as-a-service models:California Title 24 efficiency mandates are creating openings for providers to assume operational risk through performance-based contracts.
- IoT diagnostics convergence:Cloud-based fault detection combined with mobile workforce platforms is enabling predictive dispatch models that reduce truck rolls.
Industry Challenges
- A2L flammability protocols:New refrigerant safety classifications require field technician retraining and specialized recovery equipment deployment.
- Compliance timeline compression:Overlapping EPA, DOE, and state-level rulemakings are straining contractor administrative capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US HVAC Services Market |
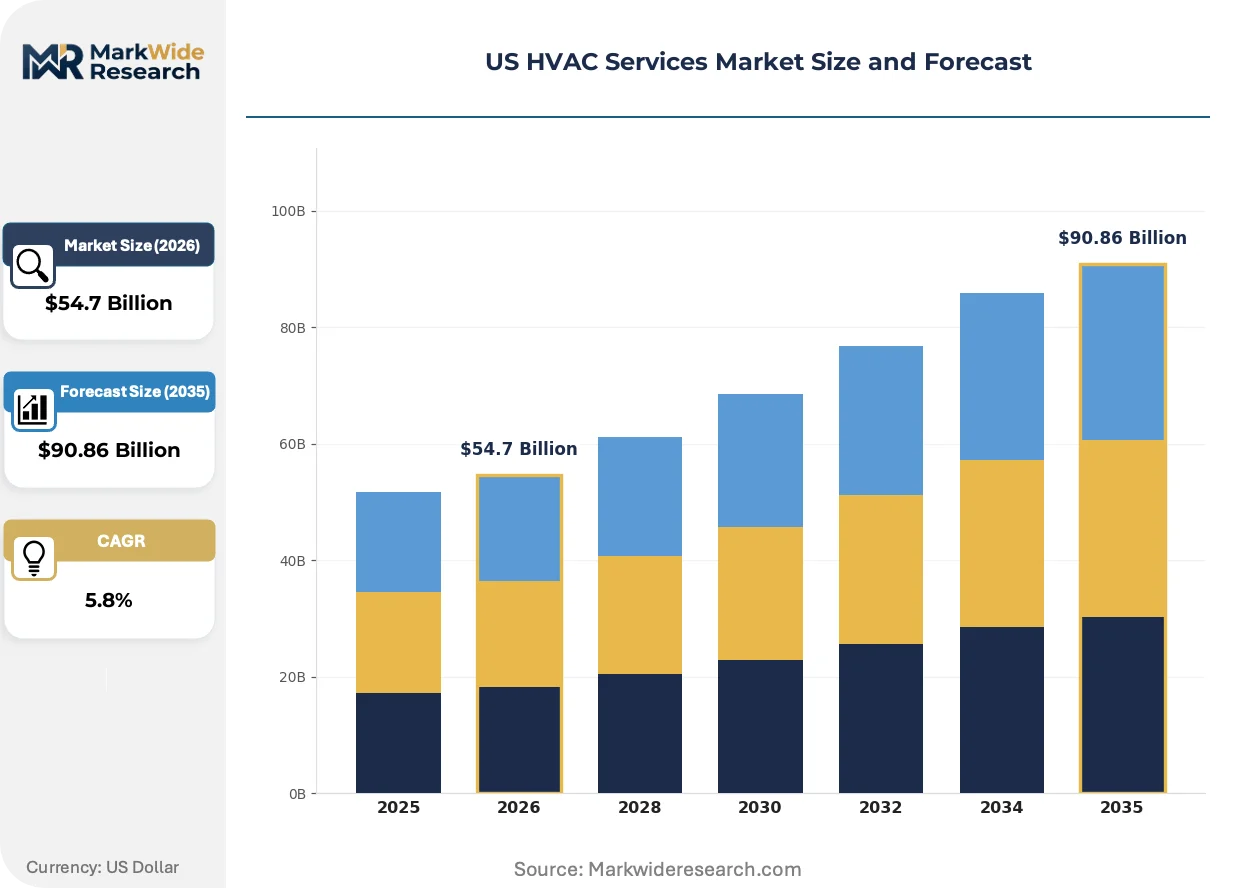
| Market Size in 2026 | $54.7 Billion |
| Market Size in 2035 | $90.86 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Maintenance, Repair, Installation, Replacement End User: Residential, Commercial, Industrial, Institutional Solution: Heating Systems, Cooling Systems, Ventilation Systems, Smart HVAC Technology: Geothermal, Ductless, Central Air, Hybrid Systems |
| Companies Covered | Daikin Industries, American Standard, Carrier Global, Amana, Bryant, Trane Technologies, Goodman Global, Johnson Controls International, Lennox International, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US HVAC Services Market Strategic Shifts
Service delivery models are pivoting from reactive break-fix to continuous monitoring architectures, compressing response times and shifting revenue toward subscription structures.
Smart HVAC platforms are integrating cloud-based diagnostics with mobile workforce management, compressing mean-time-to-repair metrics. Large commercial portfolios in Texas and Arizona are deploying these systems fastest, drawn by peak demand charge avoidance. The technology is integrating equipment health data directly into capital planning cycles, enabling just-in-time replacement scheduling.
EPA enforcement of refrigerant tracking and recovery protocols is tightening field documentation requirements. The industrial consequence is expanded investment in digital refrigerant logs and automated leak detection. Commercial property managers in California and Florida are responding earliest, driven by state-level audit exposure and insurance premium incentives.
Building operators are unbundling equipment procurement from long-term service agreements, compressing vendor selection cycles. National facility management firms are displacing regional contractors through standardized performance metrics. This pattern is most visible among institutional investors with multi-state office and industrial portfolios.
US HVAC Services Market Segmentation
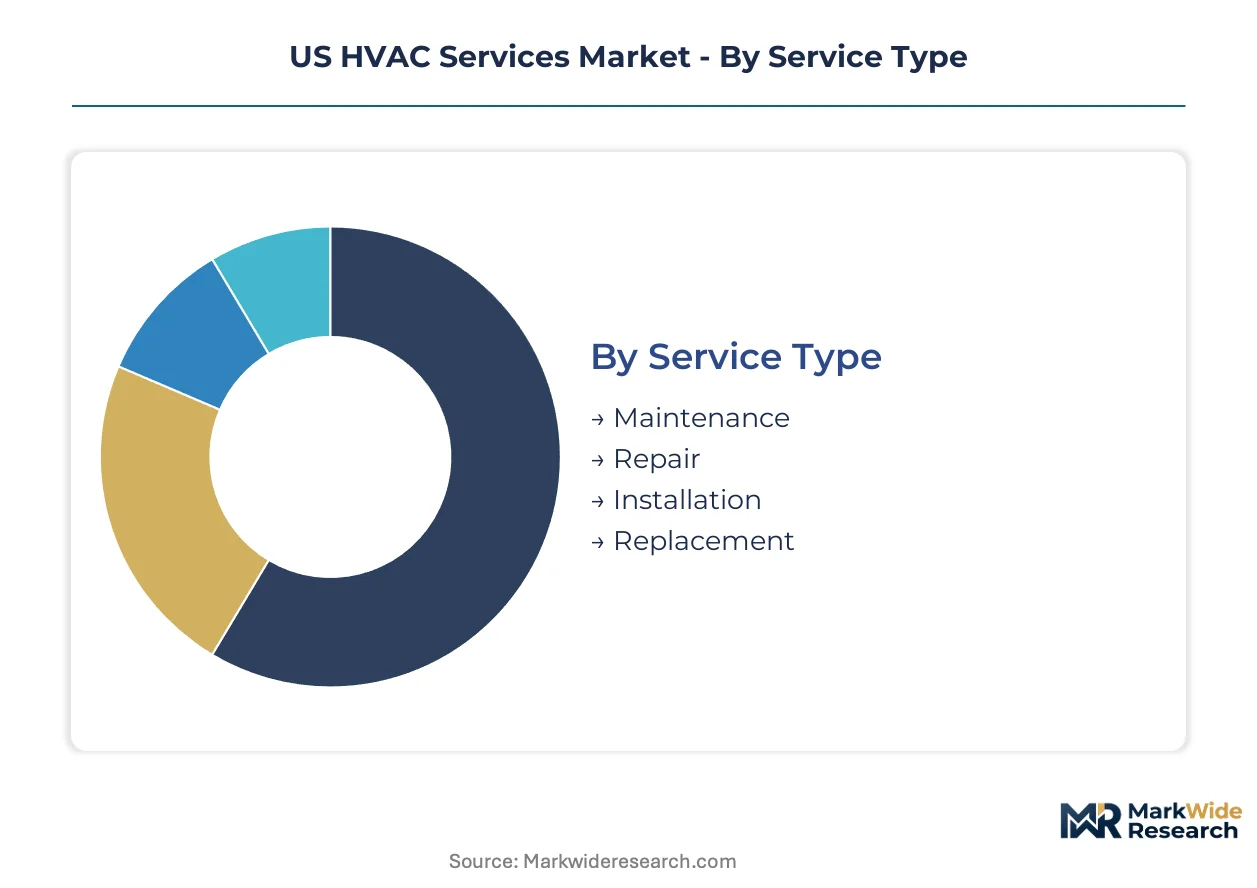
HVAC services fragment across equipment life-cycle stages, building types, and technology vintages. Each segment carries distinct margin profiles, technician skill requirements, and regulatory exposure that shape competitive positioning.
Service Type:
Customization intensity varies sharply across this spectrum, from standardized preventive maintenance protocols to highly bespoke replacement engineering.
- Maintenance:Recurring scheduled service contracts cover filter replacement, coil cleaning, and refrigerant level verification. Demand concentrates among commercial property managers in Texas and Florida seeking ASHRAE compliance and peak-load reliability during cooling-degree-day surges.
- Repair:Break-fix interventions address compressor failures, electrical faults, and refrigerant leaks. Aging R-22 and early R-410A systems in Sun Belt states drive emergency call volume during summer demand spikes.
- Installation:New construction and greenfield deployment tied to building permits and development cycles. Volume fluctuates with commercial real estate starts and residential housing permits.
- Replacement:End-of-life equipment swaps triggered by efficiency mandates or catastrophic failure. EPA AIM Act phase-down timelines are compressing decision windows for HFC-based system owners.
Most installed capacity flows through Maintenance. Expansion is steepest in Replacement.
End User:
Procurement sophistication and contract scale diverge across customer categories, from fragmented residential homeowners to consolidated institutional buyers.
- Commercial:Multi-site portfolios owned by REITs and private equity funds. These buyers bundle preventive maintenance across distributed assets, favoring national service networks with standardized KPIs and digital reporting platforms.
- Residential:Single-family homeowners and small multi-family properties. Decision-making is episodic and price-sensitive, with demand spiking during extreme weather events and equipment failures.
- Industrial:Manufacturing facilities, data centers, and cold storage operations requiring 24/7 uptime guarantees. Customized service level agreements with penalty clauses for downtime dominate this segment.
- Institutional:Schools, hospitals, and government buildings subject to public procurement rules and energy performance mandates. California Title 24 and similar state codes drive retrofit demand in this category.
Commercial commands the largest contract value per engagement. Industrial is gaining share fastest.
Solution:
Technology maturity and integration complexity separate legacy mechanical systems from digitally native platforms.
- Cooling Systems:Vapor-compression air conditioning and chillers serving cooling-dominated load profiles. Sun Belt infrastructure strain and A2L refrigerant transitions are reshaping service requirements.
- Smart HVAC:IoT-enabled platforms with cloud-based diagnostics, automated fault detection, and predictive dispatch. Large commercial portfolios in Texas and Arizona deploy these systems to avoid peak demand charges.
- Heating Systems:Furnaces, boilers, and heat pumps addressing heating-degree-day requirements. Northeast and Midwest markets concentrate seasonal demand for this equipment category.
- Ventilation Systems:Air handling units, exhaust systems, and indoor air quality infrastructure. Post-pandemic ASHRAE ventilation rate upgrades are driving retrofit demand in commercial and institutional buildings.
Cooling Systems anchor installed base. Smart HVAC is climbing the fastest.
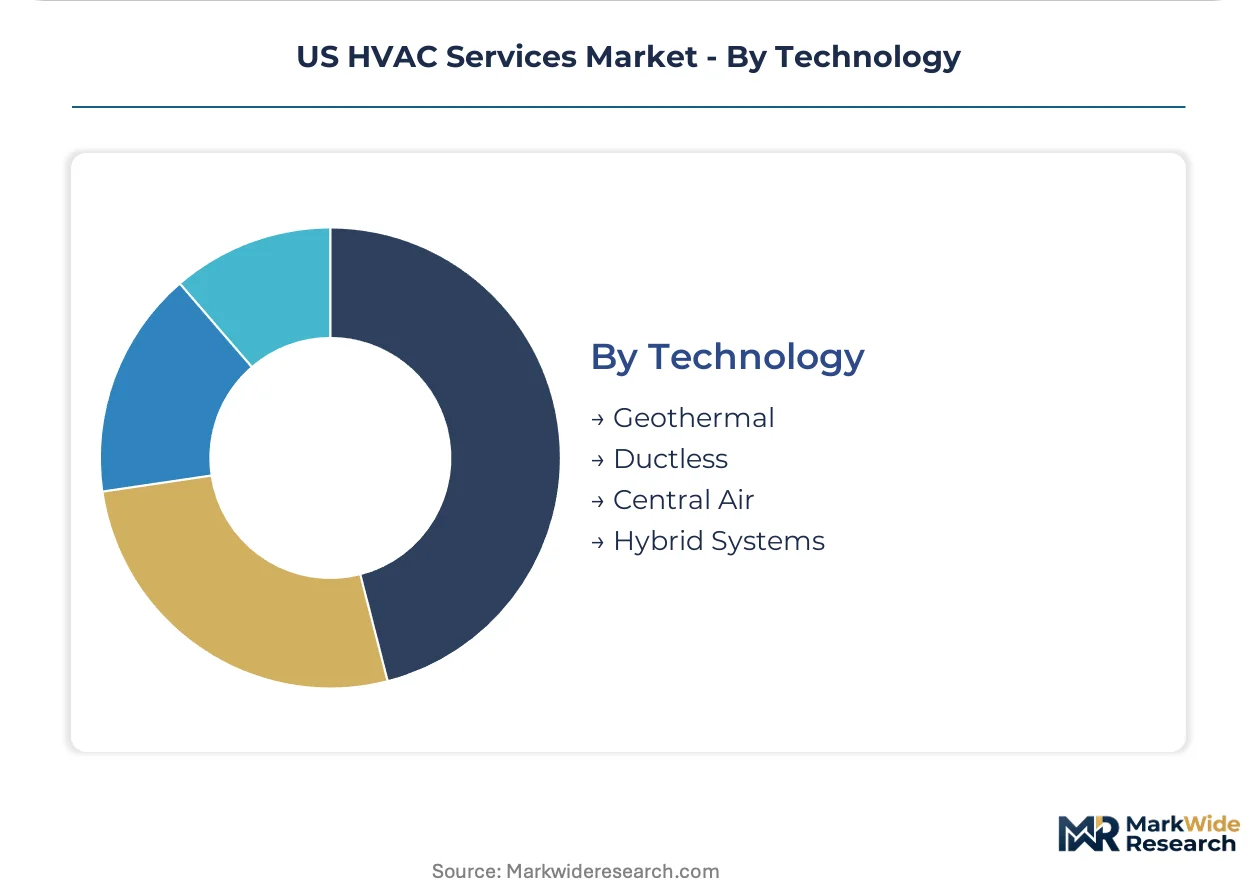
Technology:
Distribution infrastructure and technician certification requirements fragment this category between established central systems and emerging distributed architectures.
- Central Air:Ducted split systems and packaged units dominating commercial and large residential applications. Aging stock in pre-2000 buildings creates retrofit and replacement opportunity.
- Ductless:Mini-split and multi-zone systems enabling targeted conditioning without ductwork. Historic building renovations and residential additions in dense urban markets favor this technology.
- Geothermal:Ground-source heat pumps leveraging stable subsurface temperatures. High upfront capital requirements limit adoption to utility-incentivized projects and sustainability-focused institutional clients.
- Hybrid Systems:Dual-fuel configurations combining electric heat pumps with fossil fuel backup. Cold-climate variants are gaining traction in Midwest states with volatile electricity and natural gas pricing.
Central Air holds dominant share. Ductless is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Texas cooling-degree-day intensity outpaces national averages by a significant margin, while Florida's humidity-driven load profiles create distinct service demand patterns. These two states anchor Sun Belt infrastructure investment, though regulatory divergence and building stock age create heterogeneous sub-market dynamics across the country.
Texas
Commercial property managers in Dallas-Fort Worth and Houston are expanding preventive maintenance contracts as ASHRAE standards tighten. The Texas Commission on Environmental Quality enforces refrigerant handling protocols aligned with EPA AIM Act phase-down timelines. Austin's tech corridor drives smart HVAC deployment for data center cooling optimization.
Florida
Miami-Dade and Tampa Bay sub-markets concentrate demand for corrosion-resistant coastal equipment and hurricane-hardened infrastructure. The Florida Building Code mandates enhanced wind-load ratings for outdoor condensing units. Orlando's hospitality sector bundles multi-property service agreements with national facility management networks.
California
Title 24 efficiency standards accelerate replacement cycles for aging central air systems in Los Angeles and San Francisco commercial stock. The California Energy Commission ratchets minimum performance thresholds annually. San Diego's biotech cluster demands precision climate control with 24/7 uptime guarantees.
Arizona
Phoenix and Tucson metro areas exhibit the nation's highest cooling-degree-day density, straining aging vapor-compression infrastructure. The Arizona Corporation Commission oversees utility demand-response programs that incentivize grid-interactive thermal storage. Flagstaff's elevation creates hybrid heating-cooling demand profiles distinct from desert metros.
US HVAC Services Market Competitive Environment
US-based national service networks anchor one tier; regional specialists with deep local technician pools hold defensive positions in fragmented sub-markets. The vendor base concentrates around three strategic archetypes: diversified industrial conglomerates with building automation integration capabilities, pure-play HVAC OEMs with captive service arms, and independent contractors competing on emergency response speed. Dominant competitive moves include portfolio diversification into energy-as-a-service models and backward integration into refrigerant distribution.
Within the diversified industrial tier, Carrier Global and Johnson Controls International occupy positions emphasizing national facilities management contracts and building automation integration respectively. Trane Technologies exemplifies the predictive maintenance platform archetype, competing on cloud-based diagnostics that reduce downtime for centralized cooling plants. These three companies represent distinct strategic vectors—equipment-centric service anchoring, automation-led energy optimization, and data-driven uptime guarantees—rather than overlapping positioning.
| Leading Market Players |
|---|
| Daikin Industries |
| American Standard |
| Carrier Global |
| Amana |
| Bryant |
| Trane Technologies |
| Goodman Global |
| Johnson Controls International |
| Lennox International |
| Others |
Value Chain & Pricing Dynamics
Certification-tier divergence between EPA Section 608 universal technicians and emerging A2L-qualified specialists bifurcates both labor rates and inventory configurations across the US HVAC services landscape. Premium-tier providers command 40-60% rate spreads over commodity contractors by bundling refrigerant recovery documentation with predictive maintenance subscriptions, while supply chains for low-GWP alternatives concentrate among three domestic chemical distributors.
Pricing Analysis
Capacity additions in Gulf Coast chemical manufacturing are reshaping price floors for R-454B and other A2L alternatives, compressing margins on refrigerant resale. Three-tier pricing structure across premium, standard, and economy levels separates national facility management networks from regional independents and unlicensed gray-market operators. Pricing pressure stems from technician certification bottlenecks during peak cooling-degree-day windows. Residential homeowners exhibit highest price sensitivity; industrial data center clients prioritize uptime guarantees over unit economics.
Supply Chain Analysis
Regional distribution centers in Texas, Louisiana, and Georgia anchor hub-and-spoke patterns for refrigerant cylinders, recovery equipment, and replacement compressors. Domestic production of A2L refrigerants draws from fluorochemical plants in Texas and Louisiana, while specialized recovery machines source from Japanese and German OEMs. Single-source vulnerability concentrates in low-GWP refrigerant feedstocks subject to EPA allocation quotas. Distribution runs through authorized wholesaler networks requiring EPA Section 608 certification for purchase eligibility.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Texas and Florida operators capture geographic-arbitrage advantages from cooling-degree-day intensity that justifies premium preventive maintenance pricing unavailable in temperate Midwest markets. California Title 24 compliance costs create parallel arbitrage windows for energy-as-a-service providers assuming operational risk.
For Market Incumbents: Deepen technician certification pipelines in A2L handling and refrigerant recovery to defend against emerging platform-based competitors aggregating independent contractors. Anchor long-term contracts through building automation integration that raises switching costs. Prioritize backward integration into refrigerant distribution to secure allocation quotas during EPA phase-down compressions. For New Entrants and Emerging Players: EPA AIM Act refrigerant mandates in Sun Belt states open a window for specialized A2L service boutiques targeting mid-market commercial portfolios abandoned by national networks. Focus penetration on Orlando hospitality and Phoenix industrial sub-markets where aging R-410A stock faces compressed replacement timelines. Lead with mobile-first dispatch platforms that reduce mean-time-to-repair below incumbent benchmarks. For Investors and Strategic Acquirers: Consolidation pressure builds where multi-site commercial portfolios seek standardized KPI reporting across fragmented regional contractor bases. Long-term viability favors platforms integrating IoT diagnostics with captive technician networks over pure equipment distributors. Target acquisition archetype: regional specialists with EPA universal certification density and established relationships with REIT facility managers. Watch refrigerant allocation quota announcements as inflection indicators for distributor valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| Technician Certification Pipeline Investment | EPA A2L mandates create scarcity premium for qualified labor pools in Texas and Florida. |
| Building Automation Integration | Johnson Controls and Carrier anchor long-term contracts through energy-as-a-service bundling. |
| Refrigerant Distribution Backward Integration | Quota-controlled A2L supply chains reward captive sourcing from Gulf Coast chemical plants. |
| Predictive Maintenance Platform Deployment | Trane Technologies reduces truck rolls through cloud-based fault detection in Arizona data centers. |
| Multi-Site Portfolio Consolidation | REIT procurement bundling displaces regional contractors through standardized SLA metrics. |
Study Parameters
Direct dialogue with HVAC service contractors, commercial property managers, EPA compliance officers, and refrigerant distribution executives grounded qualitative findings in field operational realities. Secondary validation drew from EPA Section 608 certification databases, FERC demand-response filings, ASHRAE standard documentation, and state-level building code repositories. Bottom-up technician supply estimates triangulated against top-down service revenue projections across the analysis window.
Segment-level outputs spanning service type, end-user category, solution technology, and equipment vintage fed into analytical framework calculations over the projection horizon. CAGRs derived from equipment replacement cycle compression under AIM Act timelines and cooling-degree-day demand elasticity models. Key inputs included refrigerant phase-down allocation schedules and commercial real estate transaction velocity in Sun Belt metros.
Revisions become necessary when EPA rulemaking accelerates A2L transition timelines or refrigerant supply allocations diverge from baseline assumptions. Forecasts reflect documented assumptions around technician certification throughput and REIT portfolio consolidation rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Air Conditioning Equipment Market
HVAC Equipment
Europe HVAC Field Device Market
HVAC Equipment
Underfloor Heating Market
HVAC Equipment
Global HVAC Filter Market
HVAC Equipment
Asia-Pacific Heat Exchanger Market
HVAC Equipment
Compressed Air Treatment Equipment Market
HVAC Equipment
Europe Heating Radiator Market
HVAC Equipment
Canada Outdoor Air Source Heat Pump Market
HVAC Equipment
Underfloor Air Distribution Systems Market
HVAC Equipment
United States HVAC Equipment Market
HVAC Equipment
United Kingdom HVAC Market
HVAC Equipment
Blowers Market
HVAC Equipment
Steam Boiler Systems Market
HVAC Equipment
HVAC Pumps Market
HVAC Equipment
North America, Europe, and Asia Pacific Air Compressor Market
HVAC Equipment
Air-Cooled Heat Exchangers Market