
 Radiant Heating and Cooling Systems Market | 2026-2036
Radiant Heating and Cooling Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Radiant Heating and Cooling Systems Market Outlook
Aftermarket service revenue is rewriting how manufacturers capture lifetime value in this sector. Uponor Corporation leverages its installed base of cross-linked polyethylene piping to secure recurring maintenance contracts across Nordic utilities. REHAU anchors its position through backward integration into polymer compounding, controlling raw material quality for its TABS (thermally activated building systems) lines. Danfoss AS differentiates via its valve and control actuator portfolio, which sustains premium positioning in hydronic zoning applications.
Radiant heating and cooling systems distribute thermal energy through surfaces—floors, walls, or ceilings—rather than forced air, typically operating with fluid temperatures between 16°C and 35°C for cooling and 25°C to 40°C for heating, which enables heat pump integration and reduces energy consumption versus conventional HVAC. Hydronic systems dominate commercial specification due to their compatibility with low-carbon heat sources and capacity for zone-level control, while electric resistance floor heating occupies the residential retrofit segment where boiler replacement is impractical. Smart thermostat integration represents the fastest-growing technology dimension, as building operators prioritize demand response and occupancy-based conditioning.
The EU Green Deal and F-Gas Regulation are compressing conventional chiller markets and redirecting capital toward radiant cooling architectures that eliminate refrigerant distribution. Ecodesign requirements and CE marking under the Construction Products Regulation enforce minimum thermal output transparency, shaping how manufacturers test and label panel performance. Stakeholders must monitor how national building codes transpose these directives, since enforcement variance across member states determines project feasibility timelines.
Market Dynamics
The EU F-Gas Regulation is compressing conventional refrigerant-based cooling, redirecting capital toward hydronic radiant architectures that eliminate distributed refrigerant circuits entirely. This structural pivot reconfigures competitive positioning around low-temperature heat pump compatibility and polymer piping durability rather than compressor efficiency metrics.
Growth Catalysts
- EU Green Deal retrofit mandates:Germany's Building Energy Act (GEG) requires 65% renewable heating share in new construction, forcing specification of radiant floor systems compatible with district heating and ambient heat pumps.
- Commercial office densification:Scandinavian developers prioritize ceiling panel cooling to manage higher occupancy loads without ductwork bulk, accelerating specification in Copenhagen and Stockholm commercial towers.
- Cross-linked polyethylene maturation:PEX-a and PEX-c piping advances enable 50-year service life guarantees, reducing lifecycle cost calculations for institutional buyers in healthcare and education verticals.
Market Restraints
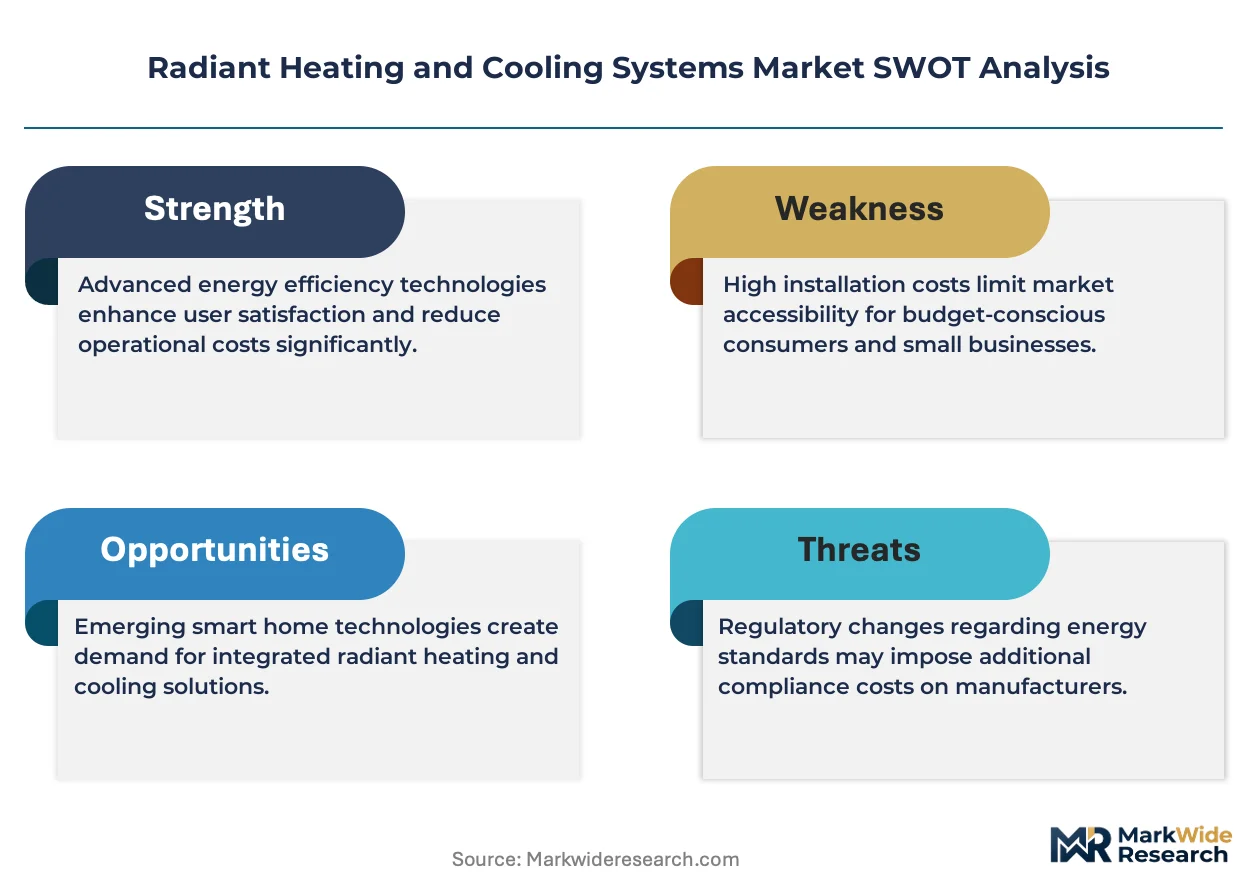
- Copper and polymer feedstock volatility:Hydronic system costs track ethylene and copper price swings, compressing installer margins when commodity spikes coincide with fixed-price construction contracts.
- Specialized contractor scarcity:Proper radiant installation demands certified hydronic technicians, and training pipeline gaps in Southern Europe limit market penetration outside Nordic and Germanic clusters.
- Electric resistance floor heating substitution:Residential retrofits with inaccessible boiler rooms default to electric mats despite higher operating costs, capping hydronic share in single-family renovation.
Strategic Opportunities
- Polish and Romanian new-build penetration:These markets lack legacy gas infrastructure density, creating clean-sheet specification opportunities for radiant networks paired with air-source heat pumps.
- Smart thermostat convergence:Integration with IoT-enabled demand response platforms allows radiant systems to monetize grid flexibility services, opening recurring revenue streams beyond equipment sale.
- French RE2020 environmental regulation:The biennial tightening of carbon performance thresholds advantages low-temperature radiant cooling over conventional VRF systems in commercial certification schemes.
Industry Challenges
- Commissioning complexity with legacy BMS:Radiant zone control integration with existing building management systems demands protocol translation expertise that mid-size contractors rarely possess.
- Moisture management liability:Ceiling cooling panels require precise dewpoint monitoring to prevent condensation damage, elevating insurance and warranty exposure for installers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Radiant Heating and Cooling Systems Market |
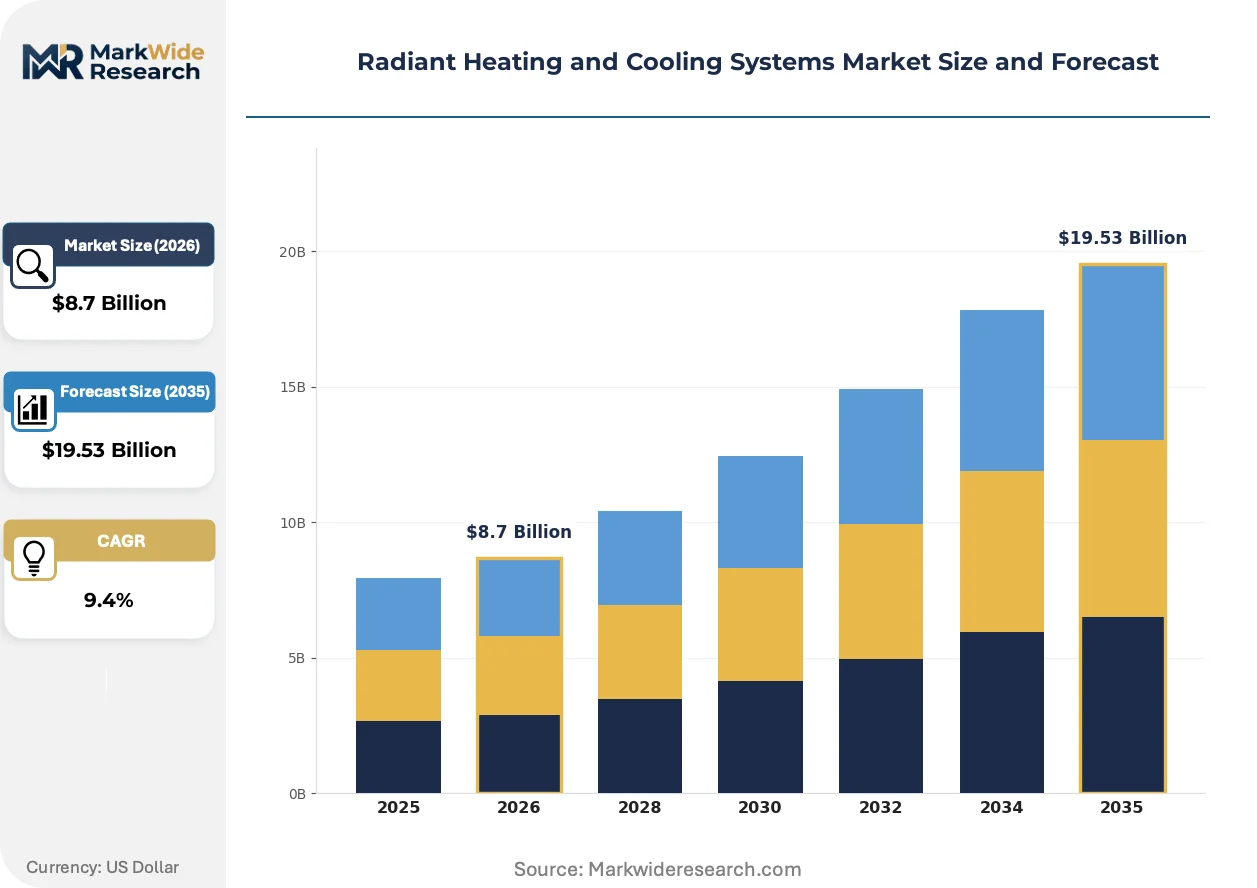
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
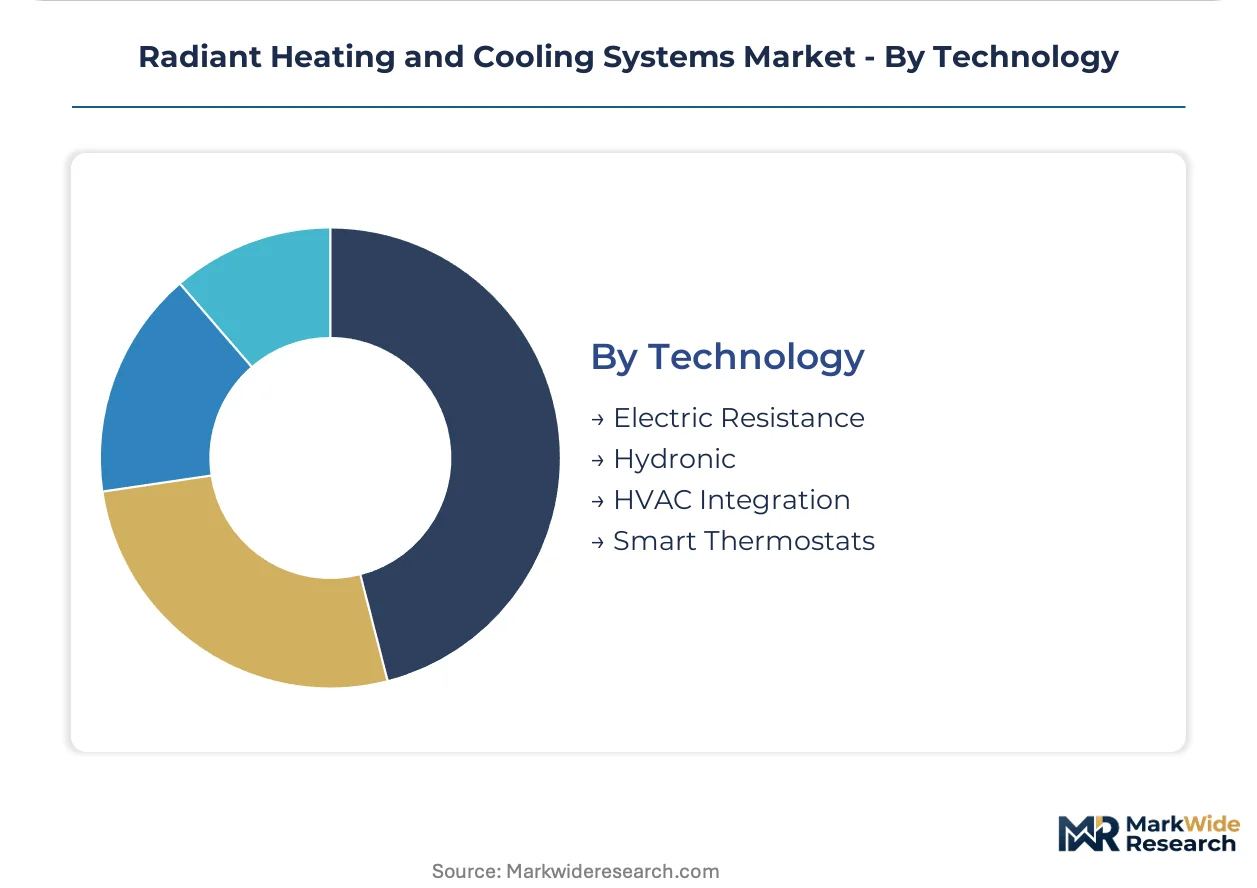
| Segmentation | Product Type: Hydronic Systems, Electric Systems, Radiant Ceiling Panels, Radiant Floor Heating Installation Type: Retrofit, New Construction, Modular, Standalone End User: Residential, Commercial, Industrial, Institutional Technology: Electric Resistance, Hydronic, HVAC Integration, Smart Thermostats |
| Companies Covered | Uponor Corporation, REHAU, Danfoss AS, Emerson Electric Co., BDR Thermea Group, Georg Fischer Ltd., Zehnder Group AG, Watts Water Technologies Inc., GIACOMINI Spa, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Radiant Heating and Cooling Systems Market Strategic Shifts
Active materials research and control system miniaturization are compressing the performance gap between radiant and forced-air responsiveness. Three convergent developments are restructuring how thermal comfort is engineered, procured, and monetized across building lifecycles.
Thermally activated building systems (TABS) using embedded polyethylene pipe networks in concrete slabs are collapsing the traditional separation between structural and mechanical engineering. German and Dutch commercial developers now specify TABS in core-and-shell contracts, compressing MEP coordination timelines by 20-30% while enabling thermal mass storage for peak load shifting. The technology is collapsing conventional chiller capacity requirements in net-zero office prototypes.
The EU F-Gas Regulation's phasedown schedule is accelerating refrigerant transition costs for conventional HVAC, compressing payback periods for radiant alternatives. Building operators in France and Belgium now face GWP-weighted refrigerant taxes that add 15-25% to VRF lifecycle costs, redirecting RFP evaluation criteria toward hydronic simplicity. The regulation is compressing specification timelines as procurement teams front-load compliance risk assessment.
Facility managers are unbundling long-term service contracts from equipment procurement, forcing manufacturers to compete on predictive maintenance algorithms rather than hardware durability alone. Nordic utilities now tender radiant network maintenance as standalone performance contracts, displacing traditional warranty-plus-breakfix arrangements. This shift concentrates in district heating-integrated developments where thermal output metering enables outcome-based billing.
Radiant Heating and Cooling Systems Market Segmentation
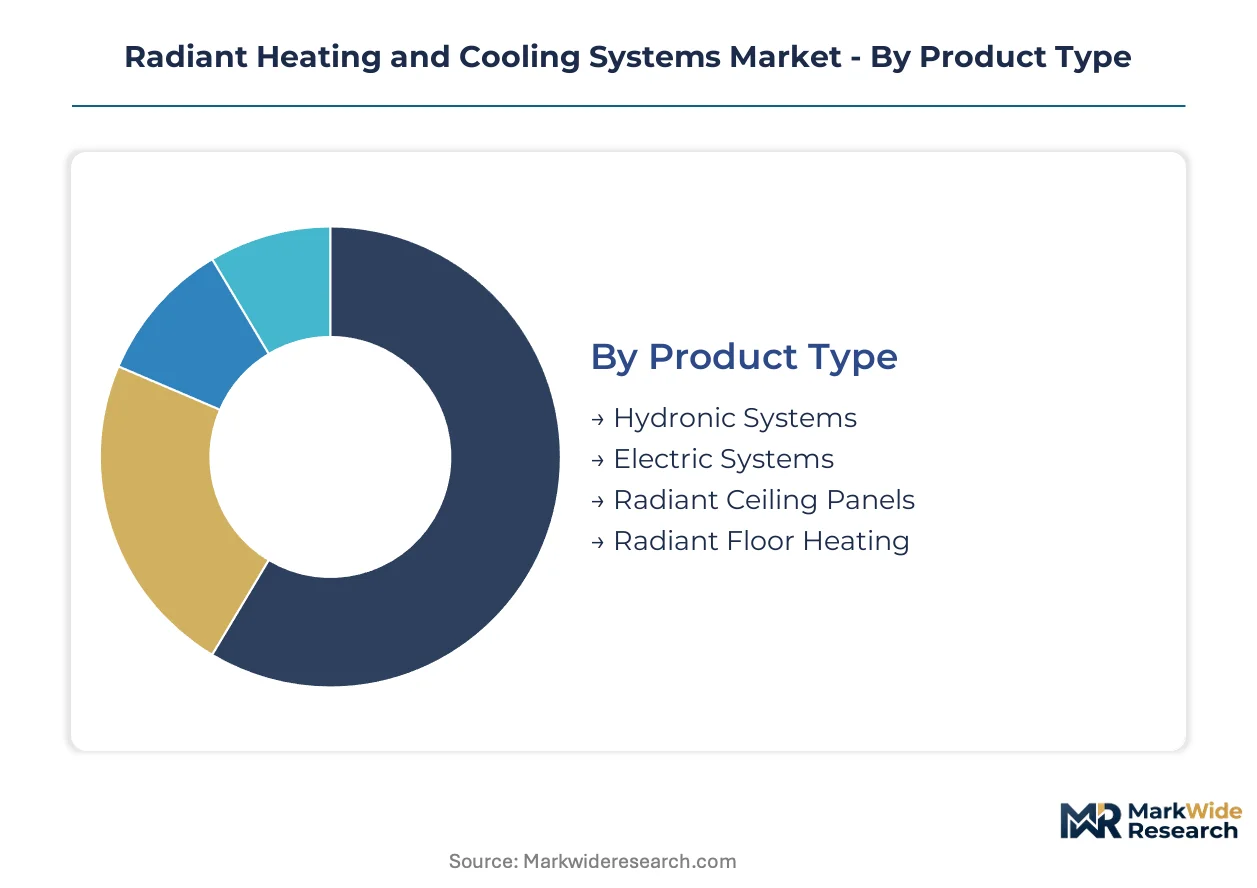
Radiant heating and cooling systems fragment across multiple technical and commercial dimensions that determine procurement patterns and lifecycle economics. Product type dictates thermal source compatibility and energy efficiency profiles. Installation type shapes project timelines and margin structures for contractors. End user classification drives specification standards and maintenance contract terms. Technology segmentation captures the control intelligence layer that increasingly determines system value.
Product Type:
Cost tier separates segments by capital intensity and operating expense structure, with hydronic architectures commanding premium upfront investment against lower lifetime energy costs.
- Hydronic Systems:Circulate heated or chilled water through embedded tubing networks, typically cross-linked polyethylene or composite piping. Demand concentrates in German and Scandinavian commercial construction where district heating integration and heat pump compatibility justify higher initial outlays. The EU Green Deal's renewable heating mandates accelerate specification in new office towers.
- Electric Systems:Deploy resistance cable or mat configurations beneath floor surfaces, eliminating boiler infrastructure. Residential retrofits across Southern Europe default to this segment where hydronic connection proves impractical, despite steeper operating costs from direct electricity conversion.
- Radiant Ceiling Panels:Aluminum or steel-faced hydronic modules suspend from structural decks. Copenhagen and Stockholm developers specify these for high-occupancy commercial spaces where floor-based distribution conflicts with raised access flooring.
- Radiant Floor Heating:Embedded tubing or electric elements within screed or slab constructions. Polish and Romanian new-build residential pipelines favor this format paired with air-source heat pumps in markets lacking legacy gas networks.
Hydronic systems hold installed capacity. Radiant ceiling panels are rotating up the share rankings.
Installation Type:
Application context determines project risk profiles and contractor specialization requirements, with new construction permitting integrated design against retrofit constraints.
- New Construction:Core-and-shell integration allows TABS specification and thermal mass optimization. German commercial developers leverage this segment to compress MEP coordination timelines and meet GEG renewable share mandates from project inception.
- Retrofit:Surface-mounted or thin-profile systems adapt existing structures with minimal structural intervention. French residential renovation programs under RE2020 environmental regulation channel subsidy flows toward this segment for energy performance upgrades.
- Modular:Prefabricated panel or mat configurations reduce on-site labor and commissioning duration. Healthcare and education verticals in the Netherlands adopt this format to minimize operational disruption during facility upgrades.
- Standalone:Single-zone electric mat systems for isolated room conditioning. Residential basement and bathroom renovations across Belgium and Luxembourg deploy this segment where whole-building system extension proves uneconomical.
New construction dominates project value. Retrofit is expanding most quickly as EU Green Deal renovation wave funding activates.
End User:
Customer type governs specification authority structures and procurement cycle lengths, with institutional buyers emphasizing lifecycle cost against residential sensitivity to upfront capital.
- Commercial:Office, retail, and hospitality facilities specifying zone-level climate control. Scandinavian developers prioritize ceiling panel cooling for densified floor plates in Copenhagen and Stockholm tower projects.
- Residential:Single-family and multi-family housing applications. German new-build mandates under the Building Energy Act drive hydronic floor system specification for heat pump pairing.
- Institutional:Healthcare, education, and government facilities with extended asset horizons. PEX-a piping guarantees attract procurement teams in Nordic hospital construction seeking 50-year service life commitments.
- Industrial:Manufacturing and warehouse environments with large conditioned volumes. Limited penetration due to air quality and process cooling requirements that favor conventional HVAC.
Commercial holds installed capacity. Institutional is rotating up the share rankings.
Technology:
Maturity stage differentiates segments by control sophistication and grid interaction capability, with smart integration representing the value migration frontier.
- Smart Thermostats:IoT-enabled demand response and occupancy-based conditioning. Nordic utilities now tender standalone performance contracts for network maintenance, enabling outcome-based billing through thermal output metering.
- Hydronic:Water-based distribution with zone valve actuation. Danfoss valve portfolios sustain premium positioning in this segment for commercial zoning applications.
- HVAC Integration:Hybrid configurations combining radiant surfaces with mechanical ventilation. Belgian and French procurement teams evaluate these against pure radiant alternatives under F-Gas Regulation compliance pressure.
- Electric Resistance:Simple on/off cable control without networked intelligence. Southern European residential retrofits default here where smart infrastructure investment remains uneconomical.
Hydronic holds installed capacity. Smart thermostats are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polish and Romanian buyers exhibit the highest price elasticity in new-build residential segments, while German and Scandinavian commercial developers prioritize lifecycle cost over capital outlay. Nordic utilities anchor premium hydronic specification through district heating integration. Southern European residential retrofits default to electric resistance systems where hydronic infrastructure proves inaccessible.
Germany
The Building Energy Act mandates 65% renewable heating share in new construction, forcing radiant floor pairing with heat pumps and district networks. Ecodesign requirements under the Construction Products Regulation enforce thermal output transparency for panel labeling. Berlin and Munich commercial towers concentrate specification activity as developers compress MEP coordination timelines through thermally activated building systems.
Poland
Absence of legacy gas infrastructure density creates clean-sheet specification opportunities for radiant networks with air-source heat pumps. National building codes transpose EU Green Deal directives with enforcement variance that accelerates project feasibility in Warsaw and Kraków corridors. The Silesian and Tri-City metropolitan clusters drive residential new-build penetration where developers specify embedded polyethylene piping for 50-year service horizons.
Sweden
Stockholm commercial densification prioritizes ceiling panel cooling to manage higher occupancy loads without ductwork bulk. The F-Gas Regulation redirects HVAC budgets toward hydronic architectures that eliminate refrigerant distribution entirely. Nordic utilities in the Mälardalen region tender standalone radiant network maintenance contracts, displacing traditional warranty arrangements with outcome-based billing models.
France
RE2020 environmental regulation tightens carbon performance thresholds biennially, advantaging low-temperature radiant cooling over conventional VRF in commercial certification. National renovation wave funding channels subsidy flows toward retrofit surface-mounted systems for energy performance upgrades. The Lyon and Lille metropolitan areas concentrate institutional procurement where healthcare facilities seek PEX-a piping guarantees for extended asset horizons.
Netherlands
Thermally activated building systems collapse structural-mechanical engineering separation in core-and-shell contracts across Rotterdam and Amsterdam commercial development. Dutch healthcare and education verticals adopt modular prefabricated configurations to minimize operational disruption during facility upgrades. CE marking requirements under the Construction Products Regulation shape how manufacturers test and label panel performance for institutional buyers.
Radiant Heating and Cooling Systems Market Competitive Environment
Capability concentration sits with polymer specialists commanding material science differentiation; scale advantage sits with diversified HVAC conglomerates leveraging distribution breadth. The market structures around three archetypes: piping system integrators with backward polymer compounding control, valve and actuator specialists capturing premium positioning in zoning applications, and diversified climate technology portfolios spanning multiple HVAC modalities. Dominant competitive moves include strategic partnerships with district heating utilities and technology licensing for smart thermostat convergence.
Among Nordic piping system integrators, Uponor Corporation and REHAU occupy positions defined by installed base leverage and captive polymer supply respectively. Danfoss AS anchors the control component tier through valve portfolio breadth. These three exemplify how competitive positioning fragments across material science, distribution architecture, and control intelligence rather than consolidating around unified system provision.
| Leading Market Players |
|---|
| Uponor Corporation |
| REHAU |
| Danfoss AS |
| Emerson Electric Co. |
| BDR Thermea Group |
| Georg Fischer Ltd. |
| Zehnder Group AG |
| Watts Water Technologies Inc. |
| GIACOMINI Spa |
| Others |
Value Chain & Pricing Dynamics
Copper and ethylene feedstock volatility compresses installer margins when commodity spikes coincide with fixed-price construction contracts, forcing three-tier pricing stratification across premium hydronic, standard electric, and economy standalone segments while reshaping procurement toward backward-integrated polymer compounders. This input-cost uncertainty accelerates long-term service contract bundling as manufacturers seek recurring revenue insulation from material price swings.
Pricing Analysis
Aftermarket service revenue drives lifetime value capture as Uponor Corporation leverages its installed base of cross-linked polyethylene piping to secure recurring maintenance contracts across Nordic utilities. Pricing stratifies across premium hydronic systems with 50-year PEX-a guarantees, standard electric mat configurations for residential retrofits, and economy standalone units for isolated room conditioning. Cost compression in the electric segment intensifies because residential buyers prioritize upfront capital minimization over operating efficiency. Institutional buyers in German healthcare and education verticals exhibit lowest price sensitivity due to lifecycle cost optimization mandates.
Supply Chain Analysis
Extended payment terms from German and Scandinavian commercial developers strain working capital for mid-size hydronic installers, accelerating supply-chain finance facility adoption among polymer piping distributors. Manufacturing concentrates in Germany, Austria, and Poland for PEX-a and PEX-c piping extrusion, with control component assembly anchored in Denmark and Switzerland. Raw material dependencies center on ethylene monomer, copper coil stock, and aluminum sheet for ceiling panel facings. Single-source vulnerability runs through specialized PEX-a peroxide cross-linking equipment. Distribution runs through district heating utility partnerships in Nordic markets and HVAC wholesaler networks in Southern Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market sits at a cyclical recovery phase driven by EU Green Deal retrofit mandate activation, with construction pipeline rebuilding favoring specification-heavy system integrators over commodity component suppliers.
For Market Incumbents: Entrench polymer compounding control through captive supply investments in ethylene cross-linking capacity, defending against emerging electric mat substitution in Southern European residential retrofits. Prioritize certification investment for CE marking under the Construction Products Regulation to maintain premium positioning as Ecodesign requirements tighten thermal output transparency standards.
For New Entrants and Emerging Players: Build out smart thermostat integration capabilities targeting Polish and Romanian new-build residential segments where clean-sheet specification opportunities bypass entrenched hydronic installer networks. Deploy direct-to-developer go-to-market angles in Warsaw and Kraków corridors, leveraging absence of legacy gas infrastructure density to specify air-source heat pump paired radiant floor systems.
For Investors and Strategic Acquirers: The market sits at a mid-cycle expansion phase that favors polymer specialists with installed base leverage over diversified HVAC conglomerates. Long-term viability across the analysis window rests on recurring service revenue monetization rather than equipment sale margins. Target acquisition archetypes include IoT-enabled control platform developers and district heating utility maintenance contractors. The signal to watch is F-Gas Regulation enforcement variance across member states as inflection indicator for hydronic specification velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | REHAU's captive ethylene supply secures PEX-a quality consistency for TABS specification in German commercial towers. |
| Smart Thermostat Platform Convergence | IoT-enabled demand response integration allows Nordic utilities to monetize grid flexibility services through radiant network control. |
| District Heating Utility Partnership | Uponor's installed base leverage converts to standalone performance contracts with outcome-based billing in Stockholm and Copenhagen. |
| Modular Prefabricated Panel Expansion | Dutch healthcare verticals adopt factory-assembled configurations to minimize operational disruption during facility upgrades. |
| CE Marking and Ecodesign Certification Investment | Thermal output transparency compliance under the Construction Products Regulation shapes procurement evaluation in French institutional tenders. |
Study Parameters
Initial hypotheses were tested against primary input from hydronic system installers, district heating utility planning officers, commercial developer MEP coordinators, and polymer piping procurement leads, then refined through secondary validation against EU F-Gas Regulation implementation reports, national building code transposition documents under the EU Green Deal, SEC filings from listed HVAC conglomerates, and customs data for ethylene and copper trade flows. Bottom-up project pipeline enumeration across German, Polish, and Scandinavian construction databases was triangulated with top-down energy efficiency spending forecasts.
Demand-supply balance modeling across the projection horizon segmented by product type, installation context, end-user category, and control technology sophistication, with CAGRs derived from weighted least-squares fitting to historical specification data and forward-adjusted for regulatory mandate acceleration. Industry-specific inputs included heat pump adoption curves, district heating network expansion plans, and F-Gas Regulation phasedown schedule impacts on conventional chiller displacement.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese polymer piping manufacturers or accelerated smart home platform entry by technology conglomerates would shift outcomes. Macroeconomic construction cycle downturn, regulatory enforcement variance across member states, or breakthrough advances in phase-change material thermal storage would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Foamer Pump Market
HVAC Equipment
Europe Residential Fan Coil Convectors Market
HVAC Equipment
North America HVAC Filter Change Service Market
HVAC Equipment
China Commercial HVAC Market
HVAC Equipment
Heating Radiator Market
HVAC Equipment
HVAC Chillers Market
HVAC Equipment
North America Commercial Heating, Ventilation, and Air Conditioning (HVAC) Equipment Market
HVAC Equipment
Brazed Plate Heat Exchangers Market
HVAC Equipment
Warm Air Furnaces Market
HVAC Equipment
Global Tubular Heating Elements Market
HVAC Equipment
Europe HVAC Market
HVAC Equipment
Air Volume Controllers Market
HVAC Equipment
Industrial Exhaust System Market
HVAC Equipment
Japan Commercial HVAC Market
HVAC Equipment
Centrifugal Blower Market
HVAC Equipment
Hydro Chillers Market