
 China Commercial HVAC Market | 2026-2036
China Commercial HVAC Market Size, Share, and Industry Trends Forecast 2026-2036
China Commercial HVAC Market Insights
Aftermarket service revenue is narrowing the margin gap between original equipment sales and long-term maintenance contracts in the China Commercial HVAC Market. Midea Group Co., Ltd. leverages its domestic manufacturing scale to control distribution networks across tier-one cities. Gree Electric Appliances Inc. of Zhuhai anchors its position through captive compressor production and vertical integration into core components. Carrier Global Corp. competes on premium system efficiency ratings for multinational-occupied office towers.
China Commercial HVAC encompasses centralized and distributed climate control systems engineered to regulate temperature, humidity, and air quality in non-residential buildings, with cooling capacities typically ranging from tens of kilowatts to multi-megawatt installations for large complexes. Chillers dominate installed base value in legacy commercial zones, while VRF Systems capture expanding share in mixed-use developments where zoned control and piping flexibility reduce retrofit disruption. Rooftop Units sustain steady replacement demand across aging shopping mall portfolios where full system overhaul remains cost-prohibitive.
MIIT efficiency labeling requirements and MEE refrigerant management protocols tighten product compliance thresholds for equipment sold in China. GB standards mandate minimum performance coefficients that escalate with each revision cycle, forcing manufacturers to redesign heat exchanger architectures and compressor mapping. SAMR market surveillance intensifies post-installation inspection protocols, elevating documentation burdens for imported systems. Stakeholders must weigh the capital allocation trade-off between incremental efficiency gains and the regulatory compliance timeline for next-generation refrigerant transitions.
Market Dynamics
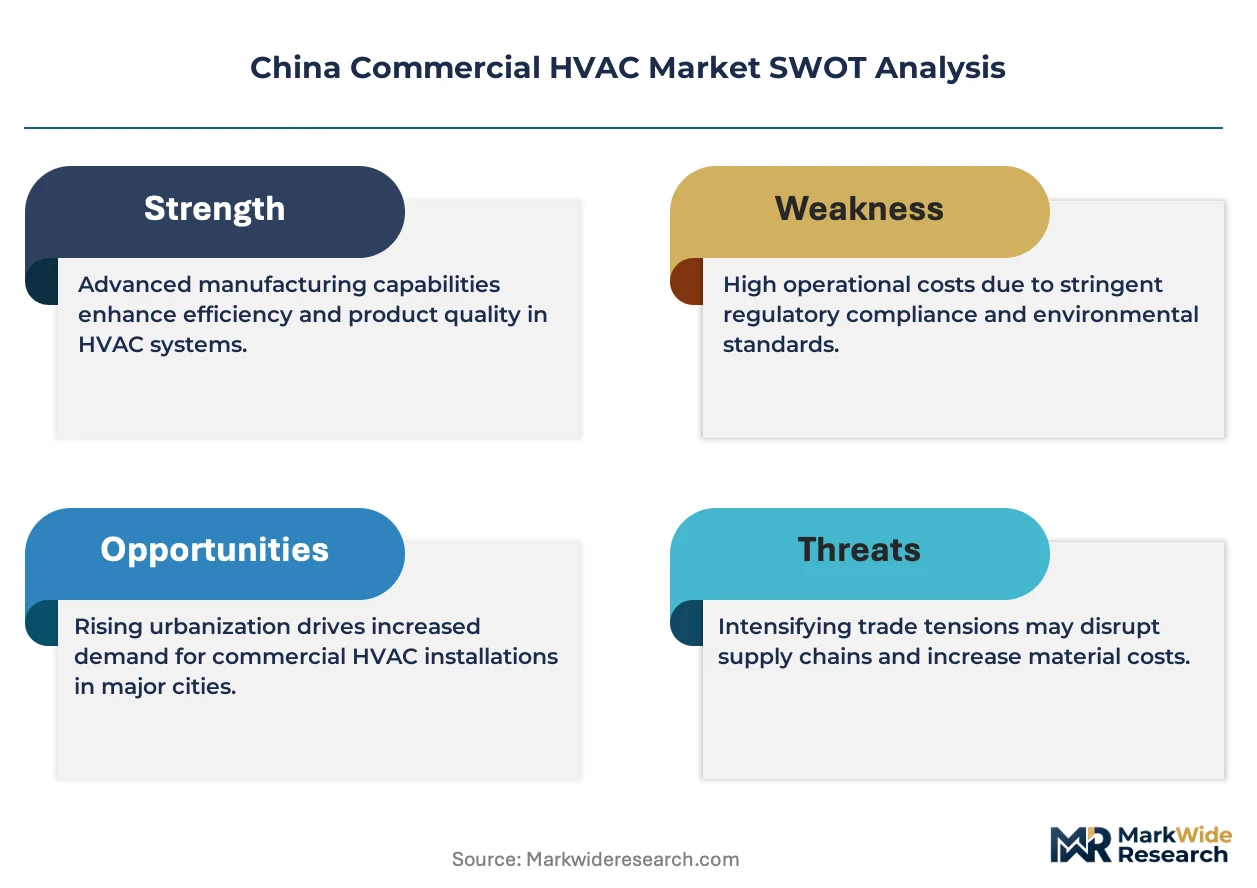
China Commercial HVAC faces a structural squeeze between escalating GB energy-efficiency mandates and the capital-intensive refrigerant transition timeline under MEE protocols, forcing manufacturers to redesign core architectures while absorbing compliance costs ahead of price recovery.
Growth Catalysts
- MEE Refrigerant Phase-Down Directives:Hydrofluorocarbon quotas under China's Kigali Amendment implementation timeline accelerate equipment replacement cycles in legacy office towers across Beijing and Shanghai.
- Yangtze River Delta Commercial Real Estate Corridor:Mixed-use development concentration in Suzhou, Hangzhou, and Nanjing sustains demand for variable refrigerant flow systems with zoned climate control.
- MIIT Efficiency Labeling Escalation:Minimum performance coefficient revisions force heat exchanger redesigns that create upgrade pull-through for premium chiller and rooftop unit categories.
Market Restraints
- Copper and Rare Earth Input Volatility:Compressor motor winding materials and permanent magnet supplies face price swings tied to concentrate processing capacity in Jiangxi and Inner Mongolia.
- SAMR Post-Installation Surveillance:Intensified documentation protocols for imported systems extend commissioning timelines and elevate compliance failure risk for non-domestic suppliers.
- Legacy Chiller Installed Base Persistence:Aging centrifugal and absorption systems in state-owned commercial portfolios resist full replacement due to SOE capital budget rigidities.
Strategic Opportunities
- Greater Bay Area Green Building Mandates:Shenzhen and Guangzhou local construction codes embed HVAC efficiency thresholds that outpace national baselines, creating premium product pull.
- Smart Building Convergence with IoT Sensors:Integration of occupancy detection and predictive maintenance algorithms enables outcome-based service contracting for facility managers.
- Tier-Two City Distribution Network Gaps:Chengdu, Xi'an, and Wuhan lack dense authorized service coverage, opening channel partnership entry points for systems specialists.
Industry Challenges
- Refrigerant Handling Certification Bottlenecks:MEE-licensed technician scarcity constrains installation capacity for next-generation low-global-warming-potential systems.
- Legacy Building Control Integration Friction:BACnet and Modbus protocol mismatches between new VRF controllers and existing building management systems extend commissioning cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Commercial HVAC Market |
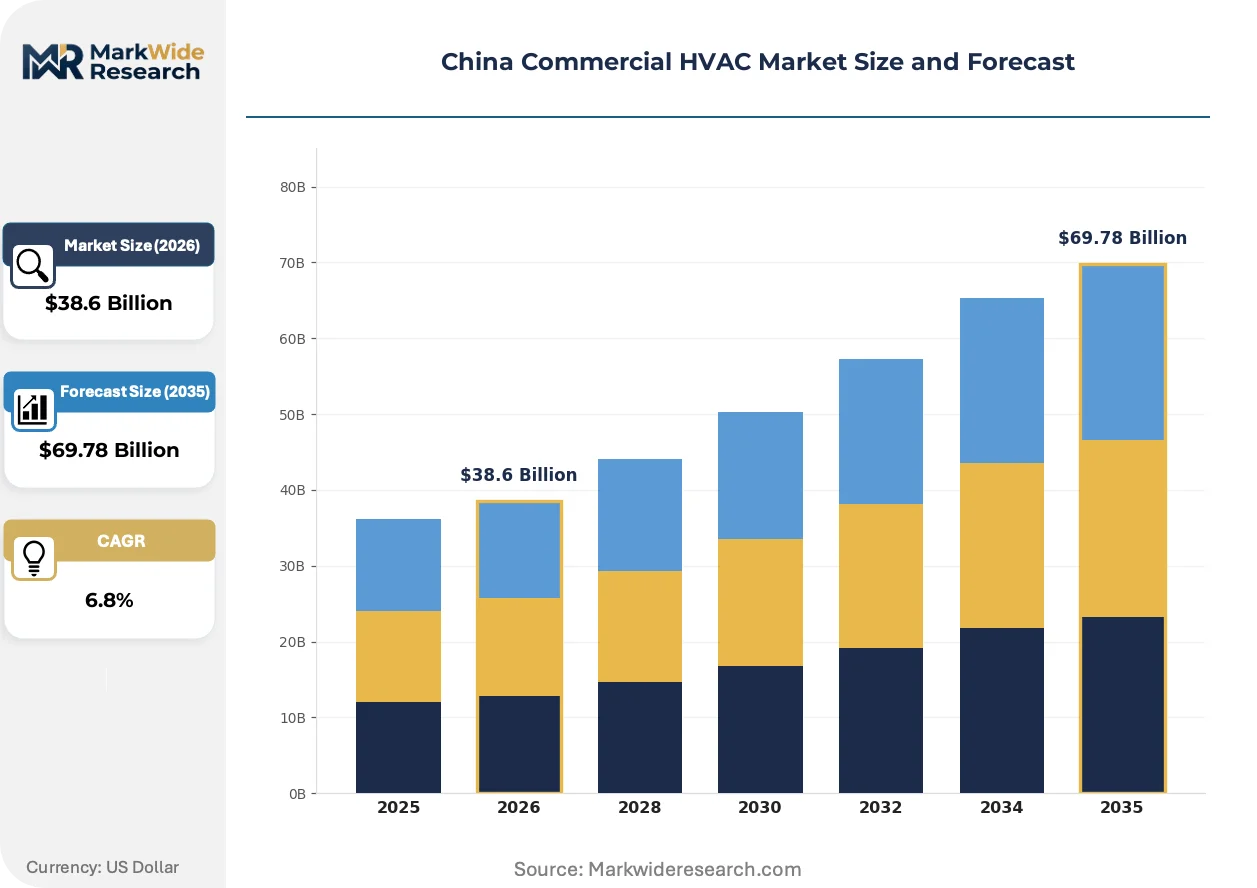
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $69.78 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chillers, Rooftop Units, VRF Systems, Ductless Systems Application: Office Buildings, Shopping Malls, Industrial Facilities, Educational Institutions Installation Type: New Construction, Replacement, Retrofit, Expansion End User: Commercial, Institutional, Government, Hospitality |
| Companies Covered | Midea Group Co., Ltd., Gree Electric Appliances Inc. of Zhuhai, Haier Smart Home Co. Ltd., Daikin Industries Ltd., Carrier Global Corp., Trane Technologies plc, Johnson Controls International Plc., Hisense Corporation, Shanghai Highly (Group) Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Commercial HVAC Market Trends and Innovations
Digital infrastructure is penetrating China Commercial HVAC at the equipment-control layer, compressing the gap between hardware performance and software-optimized operation while reshaping how facility managers procure climate systems.
Magnetic bearing centrifugal chiller technology is digitizing compressor operation through sensor-driven rotor levitation and real-time efficiency mapping. Multinational-occupied office towers in Shanghai Pudong and Beijing CBD are specifying these systems for load-matching precision. The technology is digitizing maintenance economics by enabling remote vibration monitoring that compresses unplanned downtime risk into predictable service intervals.
MIIT's escalating GB standards for seasonal energy efficiency ratios are mandating heat exchanger surface area expansion and enhanced vapor injection in scroll compressors. Manufacturers must redesign coil geometries and refrigerant circuiting to maintain market access. Rooftop unit suppliers serving aging shopping mall portfolios face the steepest redesign cost absorption as their price-sensitive buyer base resists specification premiums.
Facility managers in tier-one commercial towers are consolidating vendor relationships around full-lifecycle cost accountability rather than first-cost procurement. Single-source contracting for equipment, installation, and decade-long maintenance is displacing fragmented bid-and-spec purchasing. This concentration is most visible in Beijing's Guomao and Lujiazui districts where REIT-owned properties standardize on unified service platforms.
China Commercial HVAC Market Segmentation
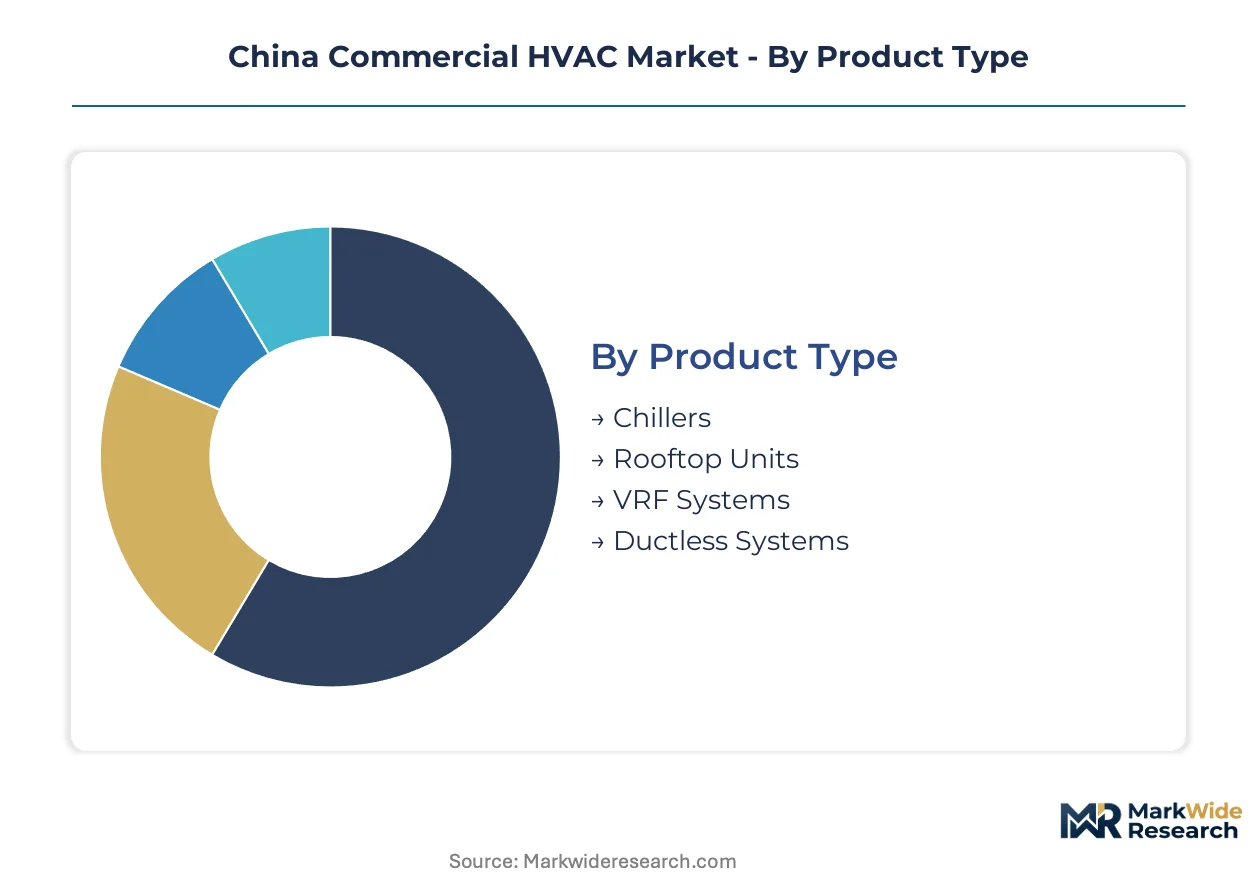
China Commercial HVAC segmentation reveals how regulatory pressure and building stock age split demand across equipment categories and customer types. Understanding these fault lines clarifies where GB efficiency mandates and refrigerant transitions concentrate commercial risk and opportunity.
Product Type:
Equipment differentiation tracks cooling capacity scale and architectural integration requirements across China's commercial building stock.
- Chillers:Centrifugal and absorption systems deliver multi-megawatt thermal output through centralized plant rooms. Beijing and Shanghai legacy office towers sustain replacement demand as MEE refrigerant quotas force equipment turnover. Absorption chillers in district cooling networks face the steepest efficiency compliance burden under escalating MIIT performance coefficients.
- VRF Systems:Variable refrigerant flow architectures enable zoned climate control with reduced piping disruption during retrofit. Mixed-use developments in Suzhou and Hangzhou specify these systems for tenant flexibility. Zoned control capabilities align with Shenzhen's local green building codes that exceed national baselines.
- Rooftop Units:Packaged systems serve aging shopping mall portfolios where full plant room overhaul remains capital-prohibitive.
- Ductless Systems:Split configurations address small-format commercial spaces and supplemental cooling in historic building conversions.
Chillers command the established base. The steepest expansion runs through VRF Systems.
Application:
Building use determines load profiles, operating hours, and procurement authority structures across China's commercial real estate.
- Office Buildings:High-rise towers in Beijing's Guomao and Shanghai's Lujiazui districts drive premium equipment specifications. Multinational-occupied properties demand magnetic bearing chillers for load-matching precision. REIT ownership structures are consolidating vendor relationships around full-lifecycle contracting.
- Shopping Malls:Aging retail portfolios across tier-two cities sustain steady rooftop unit replacement cycles. Price-sensitive procurement resists specification premiums despite MIIT efficiency labeling escalation.
- Industrial Facilities:Manufacturing plants require process cooling integration with plant HVAC systems.
- Educational Institutions:University campuses and K-12 facilities operate under government procurement protocols with extended tender timelines.
Office Buildings concentrate premium specification activity. Shopping Malls anchor volume replacement demand.
Installation Type:
Project origin shapes equipment selection constraints and margin structures across China's construction cycle.
- New Construction:Greenfield developments in the Yangtze River Delta corridor specify integrated building systems from foundation phase. Design-build contracts enable optimized chiller plant sizing and smart building sensor integration.
- Replacement:End-of-life equipment turnover accelerates under MEE refrigerant phase-down directives. Beijing and Shanghai legacy towers face compressed replacement windows as hydrofluorocarbon quotas tighten.
- Retrofit:Existing building system upgrades navigate BACnet and Modbus protocol friction between new controllers and legacy building management systems.
- Expansion:Additive capacity projects in growing commercial zones require thermal load matching with existing plant infrastructure.
New Construction captures specification influence. Replacement is climbing the fastest as regulatory deadlines compress decision timelines.
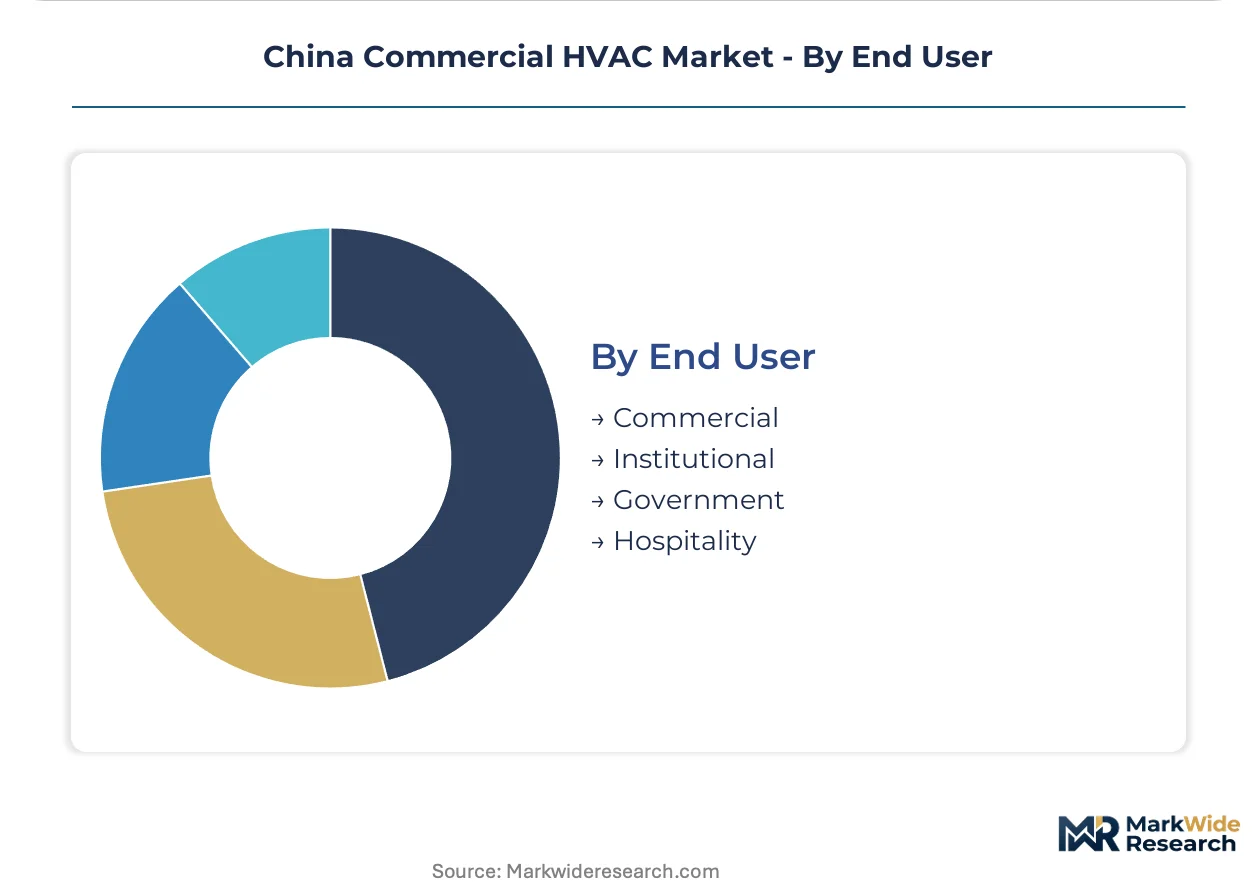
End User:
Ownership and operating models segment procurement behavior across China's commercial HVAC demand base.
- Commercial:Private-sector office towers and retail properties prioritize total cost of ownership calculations. Facility managers in tier-one cities are shifting from first-cost procurement to decade-long maintenance contracting.
- Institutional:Universities and healthcare systems operate under capital budget cycles with extended equipment depreciation schedules.
- Government:State-owned commercial portfolios resist full chiller replacement due to SOE capital budget rigidities. SAMR post-installation surveillance elevates documentation burdens for imported systems in government tenders.
- Hospitality:Hotels and conference facilities demand rapid recovery systems for guest comfort with minimal downtime tolerance.
Commercial end users drive specification innovation. Government procurement represents the most constrained expansion pathway.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's commercial HVAC consumption concentrates in coastal megacities where retrofit urgency outpaces greenfield specification, while interior provinces favor distributed systems over centralized plant infrastructure.
Yangtze River Delta
Suzhou and Hangzhou mixed-use developments specify VRF systems for tenant flexibility under local green building codes. MIIT efficiency labeling mandates accelerate equipment turnover in Shanghai's Lujiazui financial district. Nanjing's commercial corridor sustains replacement demand for aging chiller plants in state-owned office portfolios.
Pearl River Delta
Shenzhen's local construction codes embed HVAC efficiency thresholds exceeding national GB baselines. MEE refrigerant phase-down directives compress replacement windows for legacy systems in Guangzhou's aging commercial towers. Foshan manufacturing clusters supply heat exchanger components to regional equipment assemblers.
Beijing-Tianjin-Hebei
Beijing's Guomao district drives magnetic bearing chiller specifications for multinational-occupied properties. SAMR post-installation surveillance elevates documentation burdens for imported systems in government tenders. Tianjin port logistics facilities sustain steady rooftop unit replacement cycles.
Sichuan-Chongqing
Chengdu's tier-two commercial expansion lacks dense authorized service coverage for premium system maintenance. Western China development programs channel infrastructure investment into Chongqing's mixed-use construction pipeline. Local procurement patterns favor domestic equipment brands with established distribution networks.
Shandong Peninsula
Qingdao and Jinan industrial facilities integrate process cooling with plant HVAC systems under provincial energy efficiency targets. Shandong's manufacturing base produces compressor motors and coil assemblies for national supply chains. Port city commercial real estate sustains mid-market equipment specifications.
China Commercial HVAC Market Competitive Landscape
Capability concentration sits with domestic manufacturers commanding captive component production; scale advantage sits with multinational specialists targeting premium efficiency specifications. The vendor base organizes around three archetypes: integrated domestic conglomerates with backward control over compressors and heat exchangers, multinational system houses competing on efficiency ratings, and regional fabricators serving price-sensitive replacement cycles. Consolidation pressure runs through distribution network control in tier-one cities and M&A activity targeting IoT-enabled service platforms.
Among integrated domestic conglomerates, Midea Group Co., Ltd. and Gree Electric Appliances Inc. of Zhuhai exemplify the captive-manufacturing archetype through in-house production of core components. Carrier Global Corp. occupies a position on the premium-system vector. These three anchors illustrate how competitive positioning splits between scale-driven domestic coverage and efficiency-focused multinational specification.
| Leading Market Players |
|---|
| Midea Group Co., Ltd. |
| Gree Electric Appliances Inc. of Zhuhai |
| Haier Smart Home Co. Ltd. |
| Daikin Industries Ltd. |
| Carrier Global Corp. |
| Trane Technologies plc |
| Johnson Controls International Plc. |
| Hisense Corporation |
| Shanghai Highly (Group) Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Copper and rare earth input volatility determines both pricing tier spreads and supply chain shape in China Commercial HVAC. Compressor motor winding materials and permanent magnet supplies face price swings tied to concentrate processing capacity in Jiangxi and Inner Mongolia, forcing manufacturers to absorb cost fluctuations across premium and economy product lines.
Pricing Analysis
Long-term offtake contracts dominate procurement between tier-one property developers and domestic equipment manufacturers, insulating buyers from spot market commodity swings. Pricing stratifies across premium, standard, and economy tiers based on MIIT efficiency certification grade and after-sales service bundling. Cost compression in economy-tier rooftop units is intensifying because shopping mall operators resist specification premiums despite GB standard escalations. Government procurement represents the most price-sensitive buyer segment, while multinational-occupied office towers accept premium positioning for magnetic bearing chiller systems.
Supply Chain Analysis
Contract manufacturing concentration sits with Midea and Gree captive facilities controlling compressor and heat exchanger output. Geographic supply draws from Jiangxi rare earth processing, Inner Mongolia copper concentrate, and Guangdong coil assembly. Single-source vulnerability runs through permanent magnet supply for magnetic bearing systems. Distribution runs through authorized service networks in tier-one cities with coverage gaps in Chengdu, Xi'an, and Wuhan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China Commercial HVAC sits in early-cycle expansion as MEE refrigerant phase-down directives compress replacement windows and force equipment turnover across Beijing and Shanghai legacy towers.
For Market Incumbents: Pre-empt margin erosion in economy-tier rooftop units by accelerating backward integration into heat exchanger coil production. Lock in long-term rare earth supply agreements before Jiangxi concentrate processing capacity tightens. Channel control in tier-two cities represents the priority defensive lever against domestic competitors expanding authorized service networks. For New Entrants and Emerging Players: Establish a beachhead in Chengdu and Xi'an where authorized service coverage gaps create partnership entry points for systems specialists. Target smart building convergence opportunities by bundling IoT sensor platforms with predictive maintenance algorithms. White-space penetration runs through outcome-based service contracting for REIT-owned properties consolidating vendor relationships. For Investors and Strategic Acquirers: MEE refrigerant phase-down milestones reshape the acquisition landscape toward technicians with licensed handling certification for low-global-warming-potential systems. Long-term viability centers on service platform consolidation capturing decade-long maintenance contracts displacing fragmented procurement. Monitor SAMR post-installation surveillance intensity as the inflection signal for imported system compliance cost escalation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Compressor Manufacturing | Gree's captive production of core components insulates margin from copper winding price volatility. |
| IoT-Enabled Predictive Maintenance Platform | Magnetic bearing chiller remote vibration monitoring compresses unplanned downtime into scheduled intervals. |
| Channel Partnership Expansion in Tier-Two Cities | Chengdu and Wuhan service coverage gaps open entry points for systems specialists seeking geographic diversification. |
| MEE Refrigerant Handling Certification Investment | Licensed technician scarcity constrains installation capacity for next-generation low-GWP system rollout. |
| Full-Lifecycle Cost Accountability Contracting | REIT-owned properties in Beijing's Guomao standardize on unified single-source service platforms. |
Research Methodology
A standing panel of facility managers, OEM procurement directors, aftermarket service heads, and MEE regulatory compliance officers provided ongoing calibration across the research process. Primary interviews combined with secondary validation from MIIT efficiency labeling databases, SAMR market surveillance records, and commercial real estate development permits. Bottom-up equipment shipment tracking and top-down construction spend analysis triangulated market sizing.
Scenario-bracketing framed the analytical approach across the projection horizon. Segmentation dimensions modeled include product type, application, installation origin, and end-user ownership structure. CAGRs derived from equipment replacement cycle analysis against regulatory deadline compression. Forecast inputs incorporated Yangtze River Delta commercial construction pipeline data and MEE refrigerant quota allocation schedules.
Stress conditions across copper concentrate pricing, rare earth export quotas, and SAMR inspection protocol intensity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions around GB standard revision timing and Kigali Amendment implementation pace. Quarterly review of MEE technician certification issuance rates and tier-two city service network expansion is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Heating and Cooling Market
HVAC Equipment
North America Bus HVAC Market
HVAC Equipment
United States Air Conditioning Equipment Market
HVAC Equipment
Industrial Exhaust System Market
HVAC Equipment
Industrial Boiler Market
HVAC Equipment
High Pressure Heat Exchanger Market
HVAC Equipment
Heating Radiator Market
HVAC Equipment
China HVAC Field Device Market
HVAC Equipment
Shell and Tube Heat Exchangers Market
HVAC Equipment
Global Home Ventilation System Market
HVAC Equipment
Radiant Heating and Cooling Systems Market
HVAC Equipment
Variable Air Volume Box Market
HVAC Equipment
Steam Humidifiers Market
HVAC Equipment
HVAC Air Quality Monitoring Market
HVAC Equipment
HVAC Services Market
HVAC Equipment
Recirculating Chillers Market