
 Portable Projector Market | 2026-2036
Portable Projector Market Size, Share, and Industry Trends Forecast 2026-2036
Portable Projector Market Analysis
The capability gap between captive LED engine manufacturers and assembly-only brands is collapsing as XGIMI leverages in-house optical module production to control cost curves, while Nebula competes through Anker's battery supply chain dominance in compact form factors. Epson sustains its position via 3LCD patent architecture and cinema-grade color calibration, and Dangbei anchors volume in China's domestic smart projector segment through aggressive platform integration.
A portable projector is a self-contained display device integrating a light source, optical engine, and imaging chipset within a chassis typically weighing under five kilograms, designed to cast enlarged images onto arbitrary surfaces without permanent installation. Resolution tiers now stratify clearly: 4K models command premium positioning in home theater configurations, while Full HD units dominate business presentation procurement cycles due to cost-performance thresholds. Smart projectors with embedded Android TV or proprietary OS platforms represent the fastest-growing product type as streaming app integration eliminates external source dependency.
FCC certification governs wireless transmission modules and RF emissions for US-bound units, while CE marking and RoHS compliance dictate material composition and electrical safety for European market access. China's GB standards, administered by SAMR, now mandate stricter laser safety classifications for high-brightness models, directly affecting product design cycles and factory audit requirements. Stakeholders must monitor how evolving energy efficiency labeling regimes in multiple jurisdictions reshape component sourcing and factory qualification timelines.
Market Dynamics
The portable projector market is undergoing structural compression as laser phosphor technology collapses brightness-per-watt cost curves, forcing incumbents to reconfigure optical engine supply chains or surrender margin to vertically integrated competitors.
Growth Catalysts
- Outdoor Event Infrastructure:Festival organizers and pop-up cinema operators are replacing fixed LED walls with battery-powered projection rigs, creating pull-through demand for lumen-dense, weather-sealed chassis designs.
- China's GB 7247.1 Laser Safety Standards:SAMR's tightened classification protocols for Class 3R and 3B emitters are accelerating factory consolidation, privileging certified manufacturers with audit-ready quality systems.
- Android TV Platform Integration:Embedded streaming OS licenses are eliminating external source dependency, shortening purchase decision cycles for residential buyers seeking single-cable setups.
Market Restraints
- DMD Chip Supply Concentration:Texas Instruments maintains captive production of micromirror arrays for DLP architectures, exposing non-vertically integrated brands to allocation risk during foundry loading spikes.
- Optical Engine Cost Structure:Precision aspheric glass lenses and thermal-grade phosphor wheels constitute fixed cost anchors that resist scale economies below million-unit annual volumes.
- Large-Format Display Substitution:Direct-view LED tiles and falling OLED panel prices are compressing the addressable market for entry-lumen projectors in commercial signage applications.
Strategic Opportunities
- India's PLI Scheme for Electronics Manufacturing:Component-level incentives for display module assembly are attracting optical engine packagers to Noida and Sri City, creating alternative supply nodes outside East Asian clusters.
- Camping and Vanlife Recreation:Overlanding vehicle outfitters represent an underpenetrated channel where 12V DC-native projectors with integrated battery packs command pricing premiums over AC-adapted competitors.
- EU Ecodesign Requirements:Pending standby power regulations will mandate sub-0.5W idle consumption, rewarding firmware architectures with instant-on capabilities that bypass traditional warm-up cycles.
Industry Challenges
- Optical Calibration Talent Scarcity:Factory-floor engineers capable of aligning tri-color laser modules to sub-pixel tolerances are concentrated in Shenzhen and Taipei, constraining geographic diversification of final assembly.
- Multi-Jurisdiction Certification Overlap:Simultaneous FCC Part 15, CE RED, and GB 9254 electromagnetic compliance testing extends product launch timelines by 4-7 months for new chassis designs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Portable Projector Market |
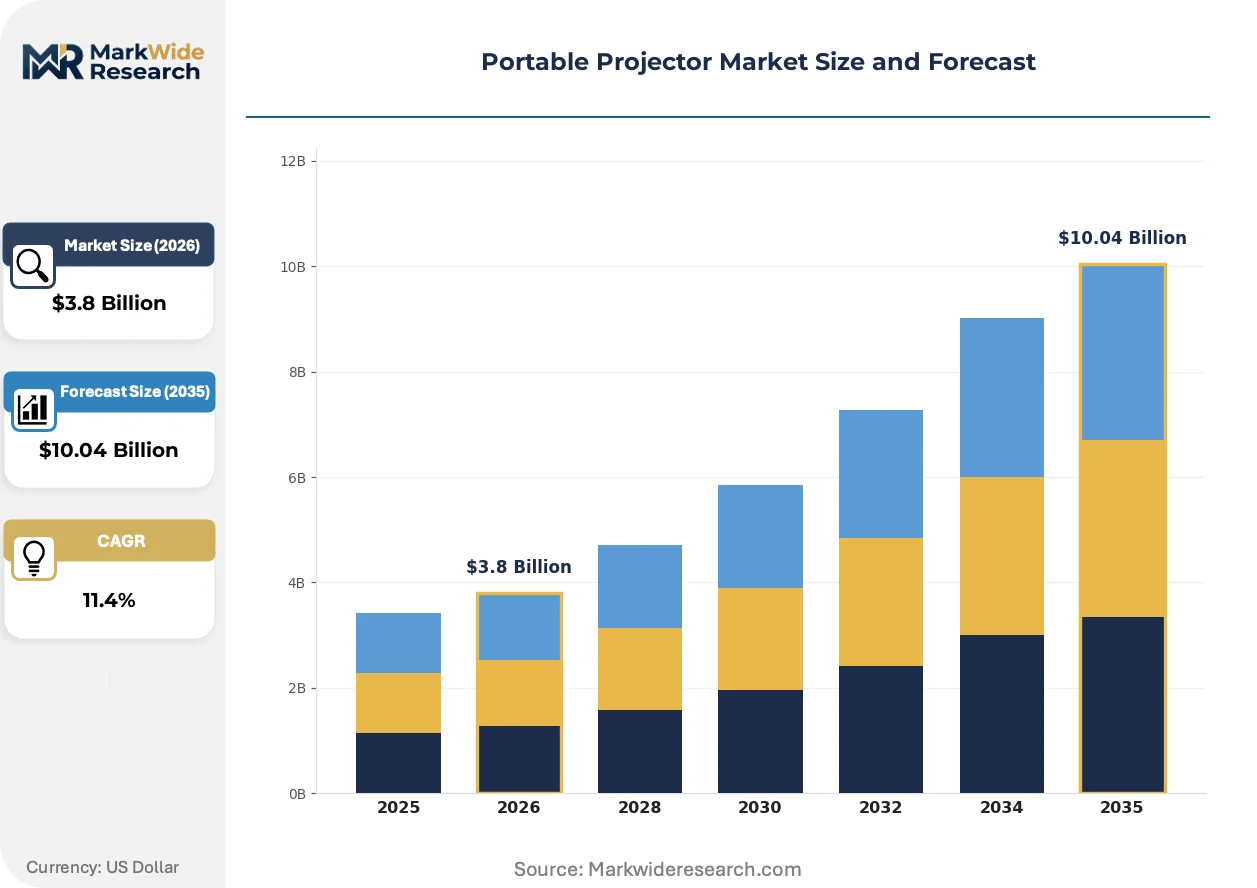
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mini Projector, Smart Projector, Business Projector, Home Theater Projector Resolution: HD, Full HD, 4K, Standard Definition Connectivity: HDMI, USB, Wi-Fi, Bluetooth Use Case: Home Entertainment, Business Presentations, Education, Outdoor Events |
| Companies Covered | BenQ, Optoma, XGIMI, Hisense, ASUS, JMGO, Nebula, Dangbei, Epson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Portable Projector Market Emerging Trajectories
Laser phosphor illumination is displacing legacy UHP lamp architectures across all but the most price-sensitive SKUs, compressing replacement cycle economics and reshaping aftermarket service revenue models for channel partners.
ALPD (Advanced Laser Phosphor Display) triple-laser engines are displacing hybrid LED-laser hybrids in 3000+ lumen segments by eliminating color wheel artifacts and extending operational lifespan beyond 20,000 hours. Corporate AV procurement teams are specifying pure laser architectures for installation projectors, while rental houses are retiring lamp-based inventory ahead of secondary market value collapse. This displacement is compressing residual value curves and accelerating write-down schedules for fleet operators.
China's GB standards for electromagnetic compatibility, administered by SAMR, are mandating stricter conducted emission limits above 1GHz for wireless-enabled projectors. Factory qualification timelines have extended by 30-45 days as testing laboratories clear backlogs for 5G WiFi module certification. High-brightness models with integrated streaming chipsets face the tightest compliance windows, pushing design teams toward modular RF architectures that isolate antenna subsystems.
Enterprise procurement teams are consolidating AV vendor relationships around outcome-based service contracts that bundle hardware, installation, and lamp-or-laser replacement coverage. Systems integrators are displacing traditional distributor markups by contracting directly with manufacturer service organizations for multi-site rollouts. This pattern is most visible in North American higher education and healthcare verticals where capital equipment budgets are merging with facilities operating expenditures.
Portable Projector Market Segmentation
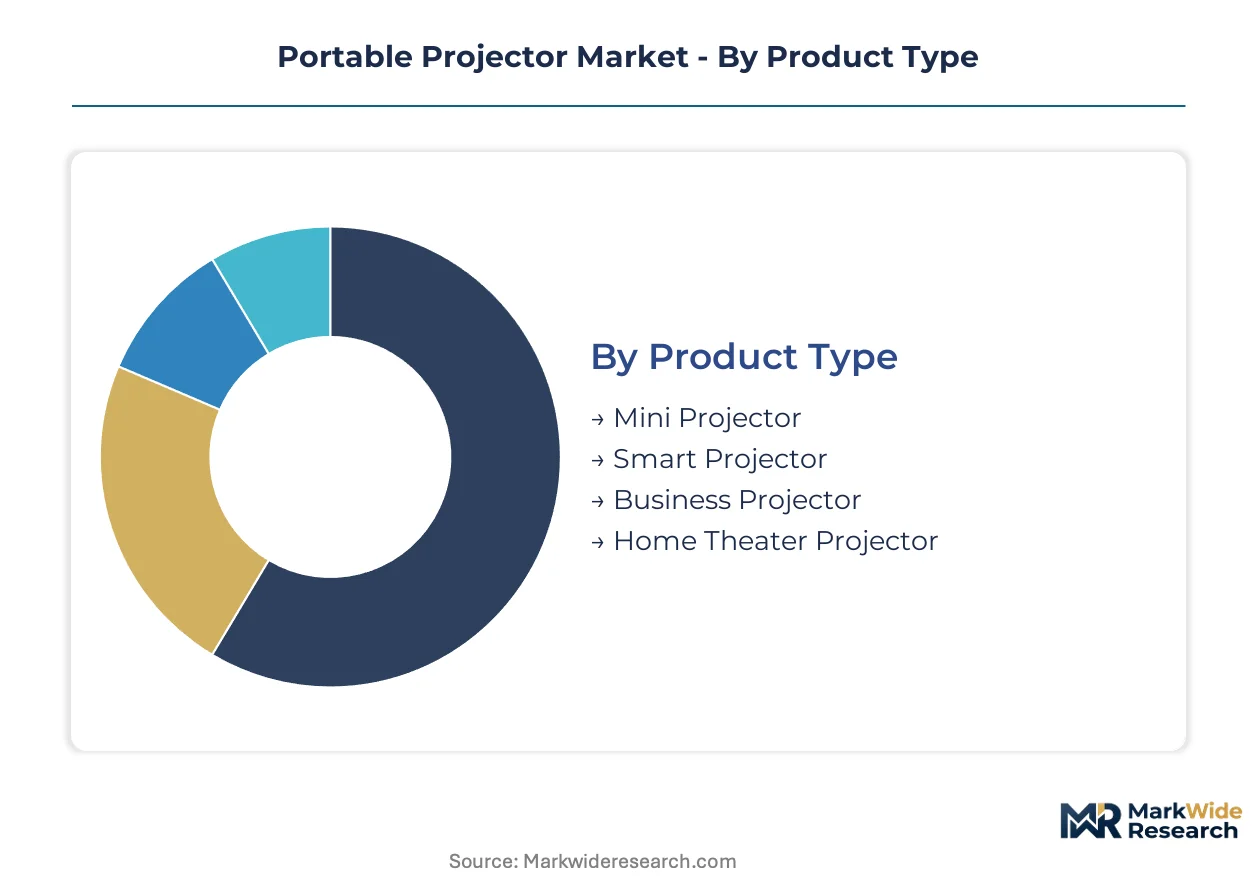
Segmentation in portable projectors reveals how technical specifications and connectivity architectures map to distinct margin architectures. Buyers sort into sharply different willingness-to-pay bands based on whether the unit serves occasional entertainment or mission-critical commercial deployment.
Product Type:
Mini Projector and Smart Projector segments capture the widest margin spreads, while Business and Home Theater variants anchor volume at opposing ends of the price-performance spectrum.
- Mini Projector:Ultra-compact chassis designs under one kilogram prioritize battery integration and LED illumination over raw lumen output. Demand concentrates in vanlife outfitters and camping retailers across the United States and Australia, where 12V DC-native power architectures command pricing premiums over AC-dependent alternatives.
- Smart Projector:Embedded Android TV or proprietary streaming OS platforms eliminate external source dependency through licensed app ecosystems. Residential buyers in China's tier-one cities and South Korean apartment complexes are shortening purchase cycles as single-cable setups displace multi-component home theater stacks.
- Business Projector:High-brightness laser phosphor engines prioritize instant-on reliability and network manageability for corporate AV fleets. Procurement teams specify these units for multi-site rollouts in North American healthcare and higher education verticals.
- Home Theater Projector:4K resolution tiers and cinema-grade color calibration target dedicated media room installations. Enthusiast buyers in Germany and Japan drive specification intensity for HDR tone mapping and lens shift flexibility.
Business Projector holds installed capacity. Smart Projector is rotating up the share rankings.
Resolution:
Resolution tiers stratify procurement behavior across fundamentally different customer types, with 4K and Full HD segments diverging on whether the buyer values specification leadership or procurement efficiency.
- 4K:Native 3840x2160 imaging chipsets paired with precision glass optics deliver pixel-dense canvases exceeding 120 inches. Home theater specialists in California and Bavaria specify these units for dedicated screening rooms where display replacement cycles stretch beyond seven years.
- Full HD:1920x1080 native resolution dominates commercial procurement cycles where cost-performance thresholds govern vendor selection. Corporate AV managers in Texas and Ontario standardize on this tier for conference room refreshes.
- HD:1280x720 imaging targets entry-level residential buyers and price-sensitive emerging market segments. Volume concentrates in Southeast Asian e-commerce channels.
- Standard Definition:Legacy 480p and 576p architectures persist in rental fleet inventories and developing market education deployments. Replacement demand is compressing as smartphone mirroring substitutes for dedicated projection.
Full HD holds installed capacity. 4K is rotating up the share rankings.
Connectivity:
Wireless transmission modules are reshaping margin structures as RF certification burdens concentrate in Wi-Fi and Bluetooth segments, while wired interfaces commoditize around universal standards.
- Wi-Fi:Integrated 802.11ac and emerging Wi-Fi 6E chipsets enable standalone streaming without tethered source devices. FCC Part 15 and China's GB 9254 electromagnetic compliance testing extends factory qualification timelines for these configurations.
- Bluetooth:Audio output and peripheral pairing capabilities support wireless soundbar integration and input device flexibility. European buyers prioritize this specification for minimalist living room aesthetics.
- HDMI:Universal wired interface standard ensures compatibility with legacy source equipment and gaming consoles. Procurement teams specify HDMI 2.1 for variable refresh rate support in residential segments.
- USB:Local media playback and firmware update capabilities through Type-A and Type-C ports. This interface anchors utility in education and signage applications where network connectivity is restricted.
HDMI holds installed capacity. Wi-Fi is rotating up the share rankings.
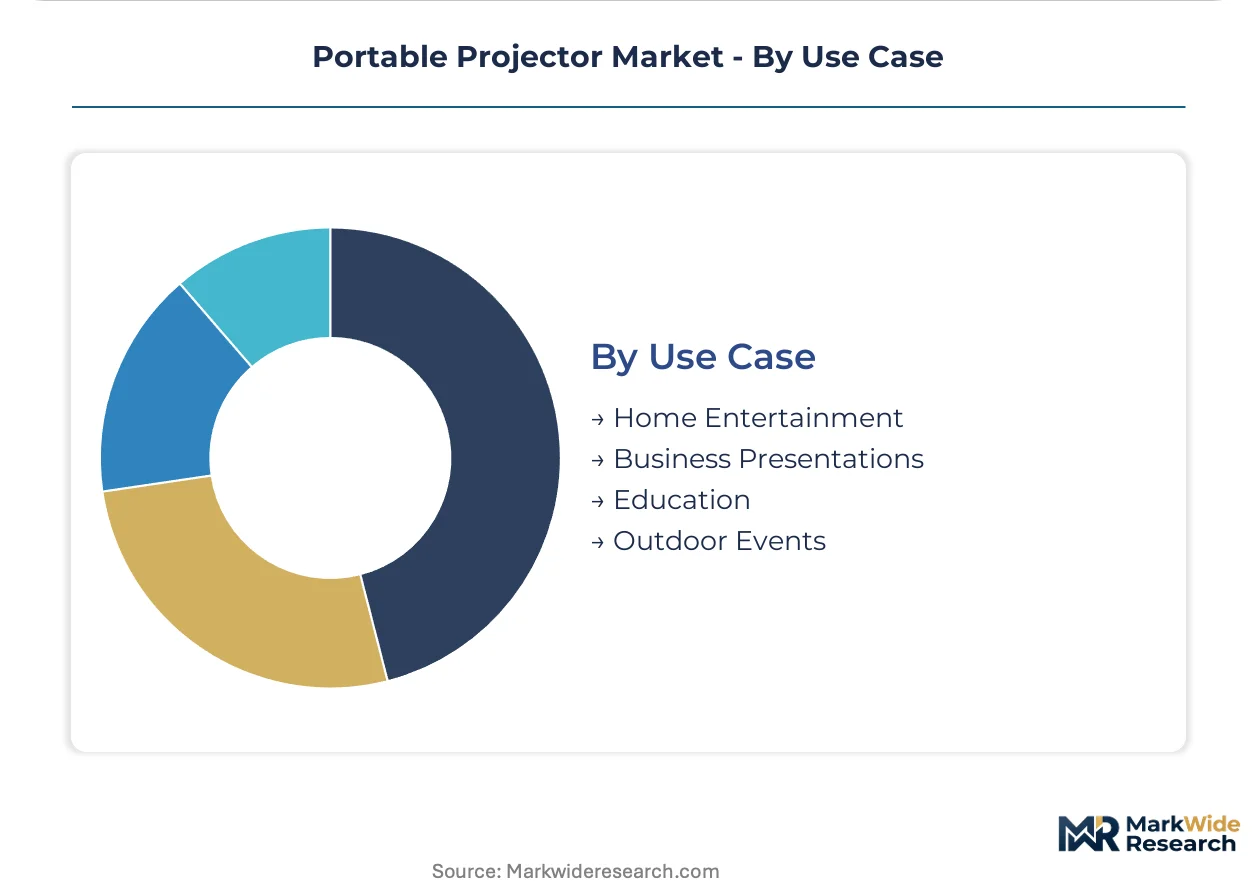
Use Case:
Application context determines chassis durability requirements and brightness specifications, with Outdoor Events and Education segments presenting the steepest divergence in environmental sealing and lumen density needs.
- Outdoor Events:Weather-sealed chassis designs with 3000+ lumen laser phosphor engines replace fixed LED walls at festivals and pop-up cinema operations. Rental houses in France and California are retiring lamp-based inventory ahead of secondary market value collapse.
- Education:Network-managed fleet deployments prioritize lamp-free laser architectures for reduced maintenance cycles in K-12 and university installations. School districts in Florida and Texas specify these units for bond-funded technology refreshes.
- Home Entertainment:Streaming-integrated smart platforms target residential buyers seeking television alternatives for flexible room placement. Demand concentrates in Japanese apartments and South Korean multi-generational households.
- Business Presentations:Portable form factors under two kilograms support mobile professional workflows and hoteling office configurations. Corporate procurement in Illinois and Ontario standardizes on this segment for sales team equipment.
Business Presentations holds installed capacity. Outdoor Events is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows concentrate optical engine sourcing in East Asian manufacturing clusters while end-market demand distributes across North American and European consumer channels. China's GB certification requirements now extend factory qualification timelines, compressing delivery windows for Western distributors.
China
Shenzhen and Taipei anchor captive production of DLP optical engines and laser phosphor modules for global brands. SAMR's tightened GB 7247.1 laser safety classifications privilege audit-ready manufacturers with certified quality systems. Dongguan assembly plants now handle final integration for 12V DC-native camping projectors targeting North American vanlife channels.
United States
Festival organizers in California and Texas are retiring lamp-based rental inventory ahead of secondary market value collapse. FCC Part 15 certification governs wireless transmission modules for streaming-integrated units, extending product launch timelines by 4-7 months for new chassis designs. Chicago corporate procurement teams standardize on portable laser projectors for hoteling office configurations.
Germany
Bavarian home theater enthusiasts drive specification intensity for 4K HDR tone mapping and lens shift flexibility. CE marking and RoHS compliance dictate material composition for European market access, with pending EU Ecodesign standby power regulations mandating sub-0.5W idle consumption. Frankfurt rental houses consolidate AV vendor relationships around outcome-based service contracts.
Japan
METI energy efficiency labeling reshapes component sourcing for compact residential units in Tokyo and Osaka apartment complexes. Japanese buyers prioritize minimalist living room aesthetics with Bluetooth audio integration and single-cable streaming setups. Nagoya-area distributors report shortening replacement cycles as smart projector platforms displace multi-component home theater stacks.
India
PLI scheme incentives for display module assembly attract optical engine packagers to Noida and Sri City, creating alternative supply nodes outside East Asian clusters. BIS certification requirements govern electromagnetic compatibility for wireless-enabled projectors. Mumbai and Bangalore education procurement teams specify lamp-free laser architectures for reduced maintenance cycles in K-12 bond-funded refreshes.
Portable Projector Market Vendor Landscape
Concentration sits with vertically integrated optical engine manufacturers who control cost curves through in-house DLP module production and captive laser phosphor supply. The vendor base stratifies across three tiers: global electronics conglomerates with cinema-grade color calibration heritage, China-based smart platform integrators with aggressive domestic market share capture, and compact lifestyle specialists leveraging battery supply chain dominance. Dominant competitive moves include backward integration into optical component manufacturing and strategic licensing of embedded Android TV platforms to eliminate external source dependency.
Within the premium-tier vector, Epson represents legacy 3LCD patent architecture holders, while XGIMI exemplifies vertically integrated challengers with in-house optical module production. Nebula occupies a position among compact lifestyle specialists leveraging parent-company battery supply chain scale. Dangbei anchors volume in China's domestic smart projector segment through platform integration density.
| Leading Market Players |
|---|
| BenQ |
| Optoma |
| XGIMI |
| Hisense |
| ASUS |
| JMGO |
| Nebula |
| Dangbei |
| Epson |
| Others |
Supply Flow & Price Mechanics
Ninety-day optical engine lead times from Shenzhen suppliers concentrate pricing power among captive manufacturers with in-house DLP module production, while assembly-only brands absorb margin compression from precision glass lens shortages and phosphor wheel allocation bottlenecks. This inventory dynamic rewards backward integration into laser phosphor supply chains and penalizes brands dependent on spot-market component procurement.
Pricing Analysis
Configured-to-order pricing for enterprise AV fleets with embedded Android TV licensing and extended warranty bundling commands spreads exceeding standard retail SKUs by margins reflecting certification investment recovery. Pricing stratifies across premium laser phosphor tiers with cinema-grade calibration, standard LED-illuminated business units, and economy mini-projector segments where battery integration drives cost. Cost compression in entry-lumen categories intensifies because direct-view LED substitution erodes residual value for lamp-based rental inventory. Education procurement teams in Texas and Florida exhibit highest price sensitivity, while home theater enthusiasts in Bavaria and California demonstrate lowest elasticity for 4K HDR specifications.
Supply Chain Analysis
Container availability constraints on the Shenzhen-Los Angeles trade lane extend inbound logistics costs for North American distributors, compressing working capital cycles and favoring regional fulfillment partnerships over direct factory shipments. Optical engine production concentrates in China, Taiwan, and South Korea, with DMD chip supply anchored in Texas Instruments' captive foundry operations. Manufacturing draws from precision aspheric glass, rare-earth phosphor substrates, and thermal-grade aluminum chassis as critical inputs. Single-source vulnerability sits with Texas Instruments' micromirror allocation protocols during foundry loading spikes. Distribution runs through Shenzhen ODMs for global brand sourcing, with final-mile fulfillment splitting between Amazon marketplace aggregators and specialized AV systems integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
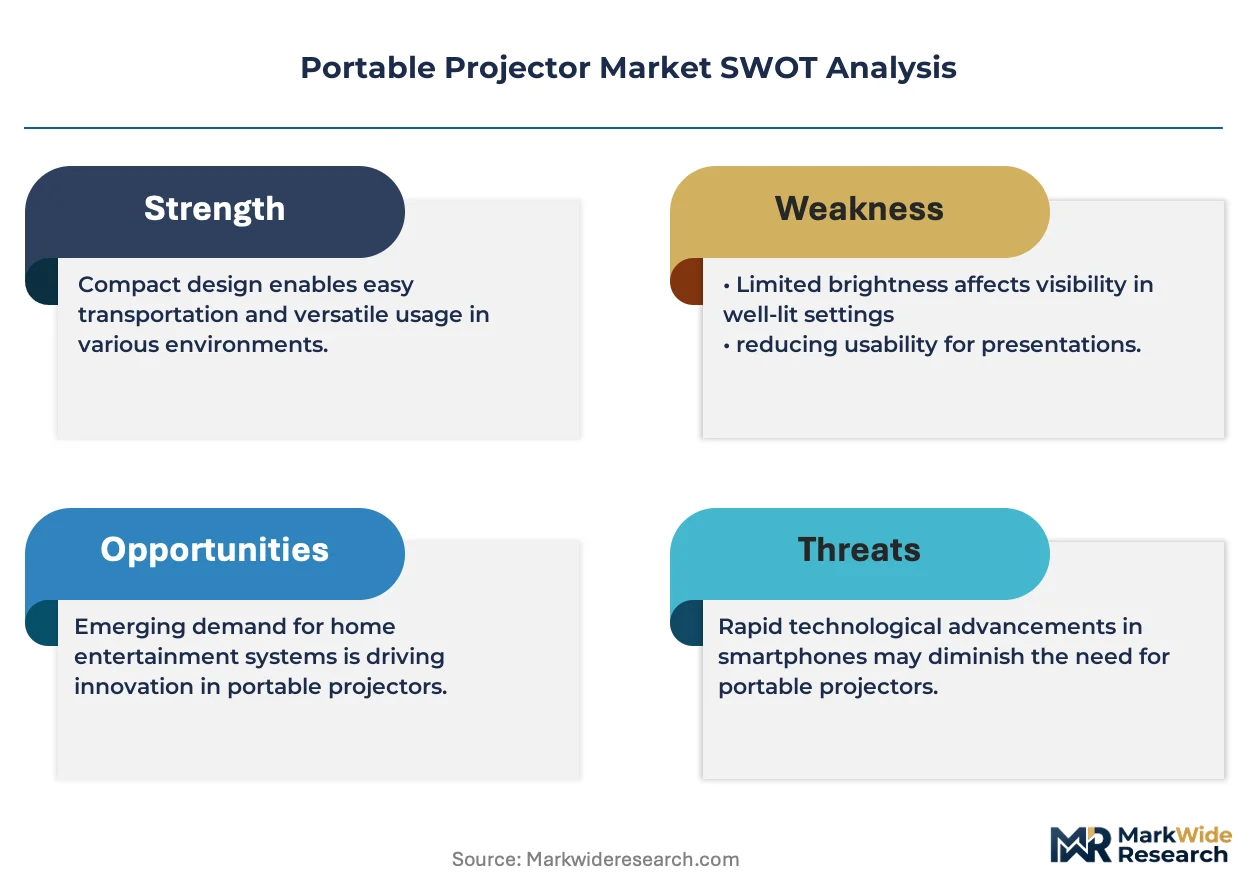
This market functions as a defensive-moat story where regulatory entrenchment through SAMR laser safety certification and FCC electromagnetic compliance creates switching costs that privilege audit-ready incumbents over speculative entrants.
For Market Incumbents: Shield market position by deepening backward integration into laser phosphor module production to escape Texas Instruments allocation risk, while accelerating GB 7247.1 factory certification investments to exploit SAMR's consolidation pressure on uncertified competitors. Channel control through direct service contracting with North American healthcare and education verticals reinforces margin protection against systems integrator disintermediation.
For New Entrants and Emerging Players: Lead with 12V DC-native camping projector architectures targeting vanlife outfitters in United States and Australian channels, where Anker's battery supply chain dominance has not yet saturated pricing premiums. India's PLI scheme for display module assembly presents the most penetrable geography for optical engine packagers seeking alternatives to Shenzhen-Taipei concentration. Go-to-market execution should prioritize direct partnerships with overlanding vehicle accessory distributors rather than consumer electronics retail.
For Investors and Strategic Acquirers: Long-term, this sits as a component-captive consolidation play because optical calibration talent scarcity in Shenzhen and Taipei constrains geographic diversification of final assembly, privileging acquirers with existing factory-floor engineering depth. Target acquisition archetypes include vertically integrated smart platform integrators with certified quality systems and embedded Android TV licensing relationships. The signal to watch as inflection indicator is factory qualification timeline compression versus extension under evolving GB electromagnetic compatibility standards.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Laser Phosphor Modules | Captive phosphor wheel supply escapes Texas Instruments DMD allocation bottlenecks during foundry loading spikes. |
| Embedded Android TV Platform Licensing | Streaming OS integration eliminates external source dependency and shortens residential purchase decision cycles. |
| GB 7247.1 Factory Certification Investment | SAMR audit-ready quality systems privilege certified manufacturers under tightened laser safety classifications. |
| Direct Service Contracting with Verticals | Outcome-based AV vendor relationships in North American healthcare displace traditional distributor markups. |
| 12V DC-Native Camping Product Development | Battery-integrated architectures command pricing premiums in United States vanlife and Australian outdoor channels. |
Methodological Framework
A spread of perspectives from optical engine procurement managers at Shenzhen ODMs, corporate AV fleet managers in Texas and Illinois education systems, rental house operators in California and France, and SAMR compliance auditors converged on the working assumptions shaping volume and value trajectories. Primary interview intelligence combined with secondary validation from FCC equipment authorization databases, China's GB standards disclosure filings, SEC 10-K component supplier disclosures, and IHS Markit display module production data. Bottom-up unit shipment modeling across resolution tiers and connectivity architectures triangulated against top-down addressable market sizing for outdoor event infrastructure and residential streaming substitution.
Segmentation dimensions modeled include product type stratification across mini, smart, business, and home theater variants; resolution tiers from standard definition through 4K; connectivity architectures spanning Wi-Fi, Bluetooth, HDMI, and USB; and use case applications in outdoor events, education, home entertainment, and business presentations. CAGRs derived from installed base replacement cycle analysis and penetration rate assumptions across the projection horizon. Industry-specific forecast inputs incorporated laser phosphor displacement curves for lamp-based inventory and PLI scheme incentive absorption rates for Indian manufacturing migration.
Forecasts assume regulatory continuity in SAMR laser safety classifications and FCC Part 15 electromagnetic compliance regimes; material policy shifts would require re-modeling factory qualification timelines and wireless module certification burdens. Scenario risks include Texas Instruments foundry allocation shocks, EU Ecodesign standby power mandate acceleration, and direct-view LED tile price compression in commercial signage applications. Practitioners should keep alternative scenarios live as outdoor event infrastructure investment cycles and vanlife recreation participation rates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
Asia-Pacific E-Paper Display Market
Display Technologies
Electronic Display Signs Market
Display Technologies
Plasma Display Module Market
Display Technologies
Flexible Display Market
Display Technologies
Light Field Display Market
Display Technologies
Europe E-Paper Display Market
Display Technologies
Flexible Screens Market
Display Technologies
Europe Transparent Conductive Films Market
Display Technologies
Privacy Screens Market
Display Technologies
Display Control and Management System Market
Display Technologies
Large Format Display (LFD) Market
Display Technologies
Display Material Market
Display Technologies
Low Power Next Generation Display Market
Display Technologies
Head Up Display Market
Display Technologies
North America Head-Up Display Market
Display Technologies
Global Display Controllers Market